
 Commercial Kitchen Appliances Market | 2026-2036
Commercial Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Kitchen Appliances Market Intelligence
Procurement power within the commercial kitchen appliance market is shifting as large, multinational food service chains consolidate their purchasing through centralized contracts. This trend favors suppliers with a global distribution network and a comprehensive product suite. The Middleby Corporation leverages its extensive brand portfolio to meet these diverse requirements. In contrast, Rational Group specializes in high-performance combi-ovens, targeting premium clients. Welbilt Inc. competes by offering integrated kitchen systems and digital connectivity solutions across its equipment lines.
Commercial kitchen appliances encompass a range of heavy-duty equipment engineered for high-volume food preparation, cooking, and storage in professional environments. These products, often constructed from 304-grade stainless steel for durability and sanitation, are designed for continuous operation. Their primary purpose is to ensure food safety, workflow efficiency, and consistent culinary output. The ovens category leads in value, driven by the versatility of convection models, while induction cooking technology is a fast-expanding segment due to its superior energy efficiency and heating speed.
The regulatory landscape imposes strict design and performance criteria on manufacturers. In the United States, equipment must often meet NSF International standards for sanitation, while in Europe, the CE marking is mandatory for safety compliance. China's GB standards dictate energy efficiency for many appliance categories. These regulations directly influence material selection, electrical safety, and market access. Equipment vendors must navigate the choice between embedding advanced IoT capabilities for data-driven kitchen management and engineering simpler, robust machines for cost-sensitive markets.
Market Dynamics
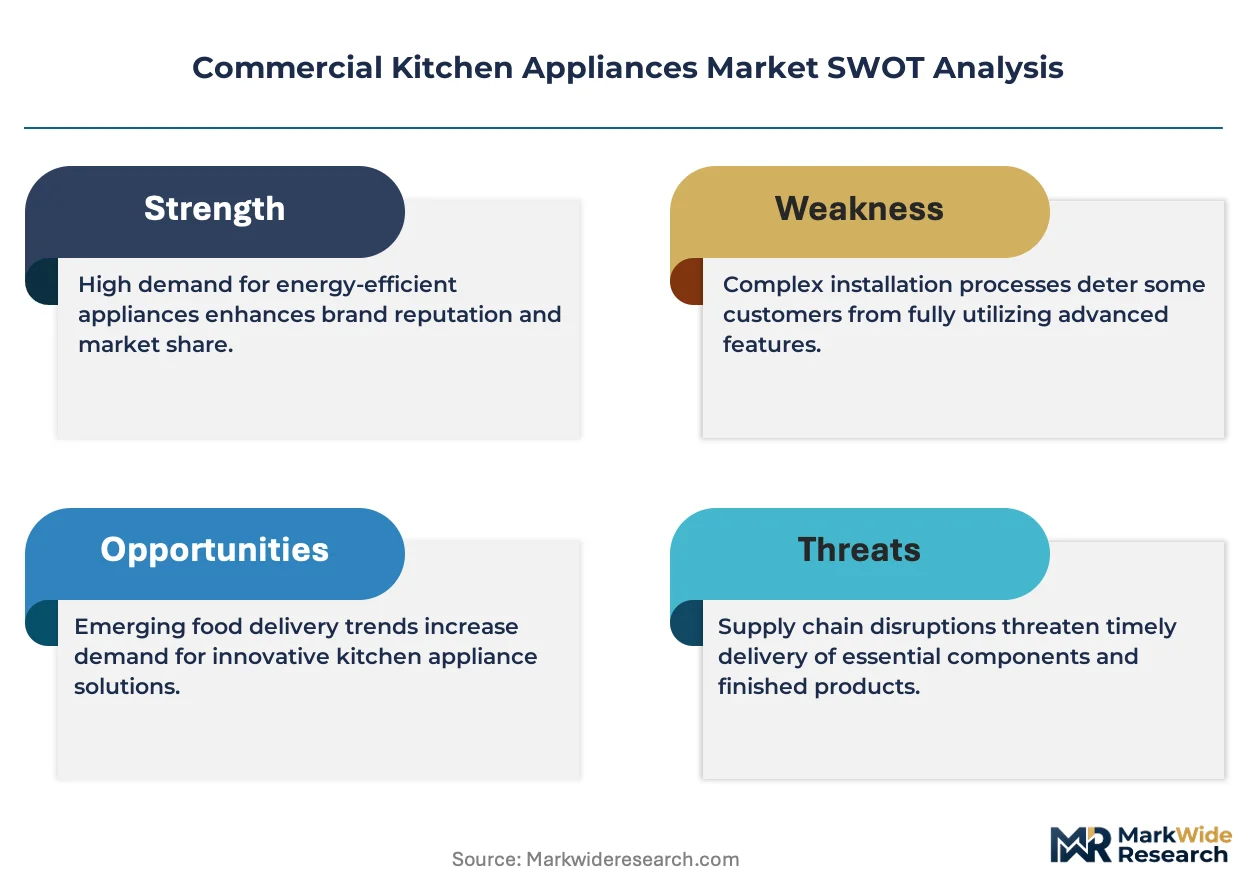
The central structural force shaping the market is the bifurcation of demand between highly efficient, connected appliances for new food service models like cloud kitchens, and simple, durable machines for cost-sensitive operators. This tension drives product development and supply chain strategies globally.
Growth Catalysts
- IoT Integration:The incorporation of Internet of Things connectivity allows for remote diagnostics, predictive maintenance, and energy consumption monitoring, which appeals to large chain operators seeking operational efficiency.
- Food Service Expansion:Rapid urbanization and the growth of quick-service restaurant chains in developing economies, particularly within India's metropolitan areas, create sustained demand for new equipment installations.
- Energy Efficiency Mandates:Government incentives and regulations, such as the ENERGY STAR program in the United States and the EU's Ecodesign Directive, push commercial kitchens to replace older equipment with certified, energy-saving models.
Market Restraints
- Input Material Volatility:The price and availability of high-grade 304 stainless steel, the primary material for durable and sanitary construction, are subject to global commodity market fluctuations, impacting manufacturer margins.
- High Capital Outlay:The significant upfront investment required for heavy-duty commercial appliances acts as a barrier to entry for independent restaurants and food startups, slowing replacement cycles.
- Regulatory Fragmentation:Manufacturers targeting a global footprint face high costs and long lead times to secure disparate certifications, including NSF in the US, CE marking in Europe, and GB standards in China.
Strategic Opportunities
- Modular Equipment Design:Developing smaller, modular, and multi-functional appliances can serve the specific spatial and operational needs of emerging ghost kitchens, food trucks, and pop-up dining concepts.
- Equipment-as-a-Service Models:Offering subscription or leasing-based financial models can lower the entry barrier for new businesses, creating a recurring revenue stream and fostering long-term customer relationships.
- Specialized Food Processing:There is a growing opportunity for equipment designed for niche but expanding food categories, such as plant-based meat alternatives or cold-brew coffee, which have unique preparation requirements.
Industry Challenges
- Service Technician Skill Gap:A shortage of technicians trained to repair and maintain modern, software-heavy, and IoT-connected kitchen equipment presents a significant operational challenge for both vendors and end-users.
- Legacy System Integration:Integrating new, smart appliances with existing, often analog, kitchen management systems and workflows creates interoperability conflicts and can limit the adoption of advanced features.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Kitchen Appliances Market |
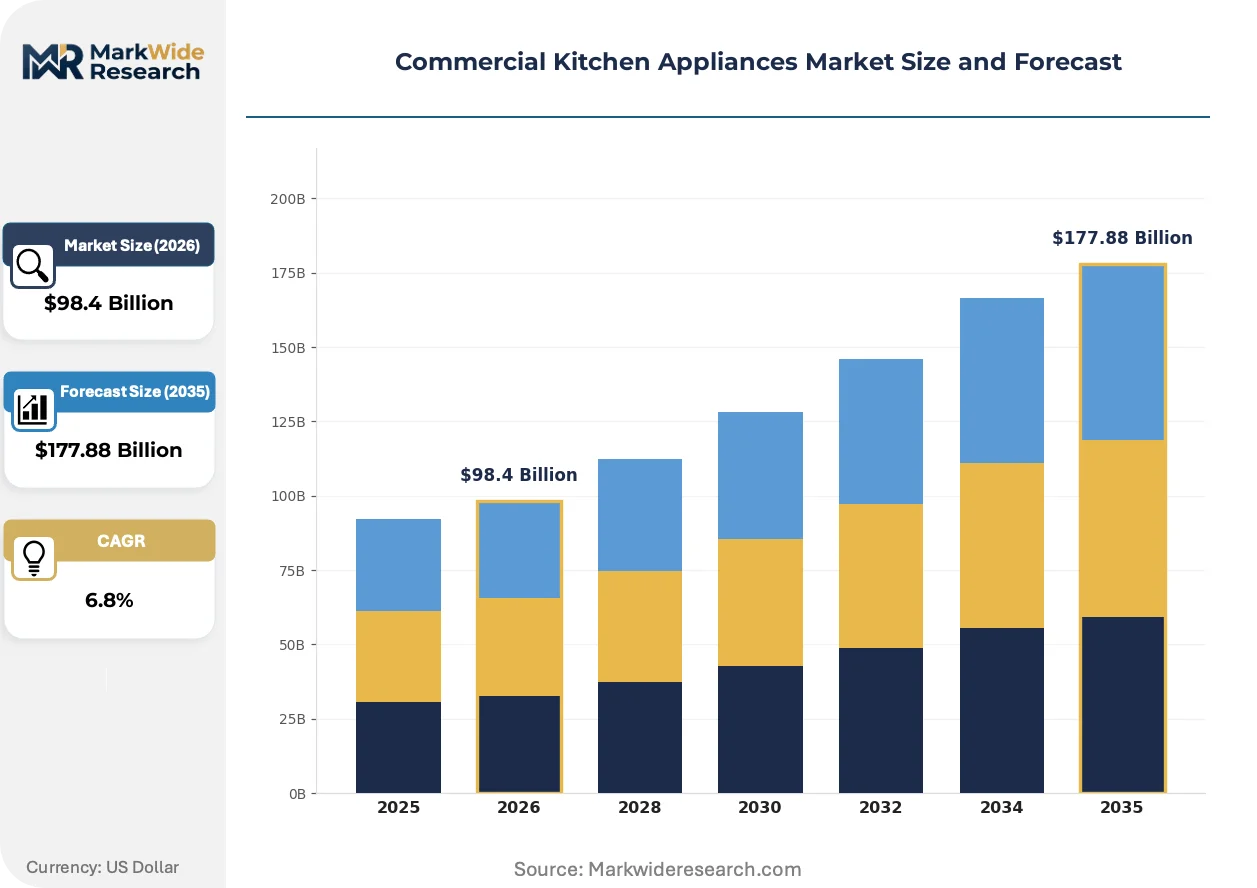
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $177.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ovens, Refrigerators, Dishwashers, Grills, Food Processors, Coffee Machines Technology: Induction Cooking, Convection Cooking, Steam Cooking, Deep Frying, Microwave Heating, Infrared Technology Application: Restaurants, Catering Services, Hotels, Food Trucks, Bakeries, Cafeterias End User: Hospitality, Food Service Chains, Institutional Kitchens, Event Management Companies |
| Companies Covered | Ali Group, Duke Manufacturing, Middleby Corporation, Vulcan, Hobart Corporation, Welbilt Inc., Rational Group, Blodgett, Electrolux Professional, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Kitchen Appliances Market Strategic Shifts & Innovations
The commercial kitchen is transforming from a collection of standalone, mechanical tools into an integrated, data-generating ecosystem. This evolution prioritizes digital connectivity, automation, and adherence to increasingly stringent environmental standards, which reshapes equipment design and function.
IoT sensors embedded in cooking and refrigeration equipment provide real-time data on performance, energy usage, and food safety parameters. Large-scale food service chains are the primary adopters, using the technology to enforce consistency and efficiency across geographically dispersed locations. This integration is automating critical operational tasks, including temperature logging for HACCP compliance and predictive maintenance alerts, thereby reducing manual labor and equipment downtime.
The European Union's F-Gas Regulation is compelling a significant technological shift in commercial refrigeration. This rule mandates the phase-down of high global warming potential hydrofluorocarbons (HFCs), forcing a transition to natural refrigerants like propane (R290) and CO2 (R744). The cold storage equipment segment, including refrigerators, freezers, and blast chillers, is most directly affected, requiring substantial R&D to maintain cooling performance and safety with these alternative substances.
A notable behavioral shift is occurring as buyers, especially in the fast-casual and cloud kitchen sectors, move from procuring individual appliances to sourcing complete, pre-configured kitchen stations. This trend favors manufacturers that can act as system integrators, offering a turnkey solution that bundles equipment, ventilation, and digital controls. The traditional dealer channel is disrupted by this model, which is most prominent in new build-outs across North American and European urban centers.
Commercial Kitchen Appliances Market Segmentation
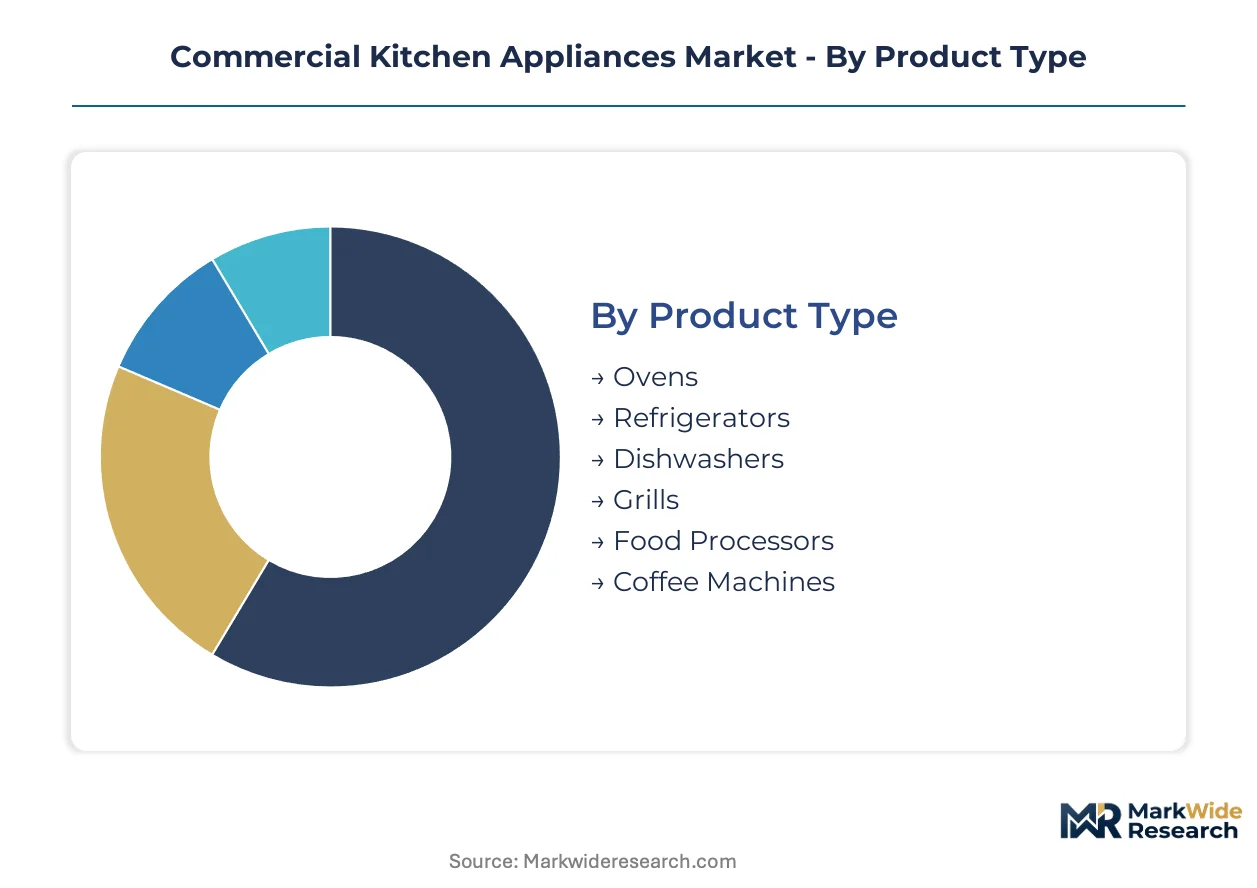
Market segmentation provides a critical lens for understanding the diverse operational needs and investment priorities within the commercial kitchen appliance sector. This granular analysis reveals how varying business models and culinary demands shape equipment procurement and technology adoption across the industry.
Product Type:
The lifecycle of commercial kitchen appliances significantly influences procurement decisions, with segmentation by product type reflecting varied replacement cycles and initial investment outlays.
- Ovens:Multi-functional cooking units, often incorporating convection or combi-steam capabilities for versatile preparation. Demand concentrates in large food service chains seeking consistent output and energy-efficient models.
- Refrigerators:Essential cold storage equipment designed for continuous operation and strict temperature control. Global demand focuses on models compliant with F-Gas Regulation and ENERGY STAR standards for sustainability.
- Dishwashers:Heavy-duty machines designed for high-volume warewashing in commercial settings, ensuring hygiene standards.
- Grills:High-temperature cooking surfaces used for searing and charring, prevalent in quick-service restaurants.
- Food Processors:Versatile machines for chopping, mixing, and pureeing ingredients, enhancing kitchen efficiency.
- Coffee Machines:Industrial-grade brewers and espresso machines, critical for cafes and hospitality venues.
Ovens sit at the top of the volume ranking, with Refrigerators climbing the fastest.
Technology:
Technological advancements define operational efficiency and culinary precision across commercial kitchens, influencing appliance selection for specialized preparation methods.
- Induction Cooking:Utilizes electromagnetic fields to directly heat cookware, offering superior energy efficiency and precise temperature control. Demand is strong in urban cloud kitchens prioritizing rapid cooking and reduced heat output.
- Convection Cooking:Incorporates fans to circulate hot air, ensuring even cooking and faster preparation times for a wide range of dishes. This technology is a staple in high-volume bakeries and institutional kitchens.
- Steam Cooking:Employs steam for gentle, healthy cooking, common in institutional kitchens and healthcare facilities.
- Deep Frying:Submerges food in hot oil for rapid cooking, a core technology for quick-service restaurants.
- Microwave Heating:Uses microwave radiation for quick reheating and defrosting, essential in convenience-focused operations.
- Infrared Technology:Utilizes infrared radiation for efficient heating and grilling, finding applications in specific oven types.
Adoption patterns are shifting towards Induction Cooking, driven by its energy efficiency, while Convection Cooking maintains broad utility.
Application:
The diverse operational environments within the food service industry dictate specific equipment configurations, from high-throughput restaurants to specialized bakeries.
- Restaurants:Primary end-users requiring a full suite of robust cooking, refrigeration, and warewashing equipment for varied menus. Demand is concentrated in metropolitan areas experiencing new establishment growth.
- Hotels:Demand comprehensive kitchen solutions for multiple dining outlets, banqueting, and room service. Procurement favors integrated systems that ensure consistent quality and operational efficiency across large-scale operations.
- Catering Services:Require portable and versatile equipment for off-site food preparation and serving, often focusing on modular designs.
- Food Trucks:Utilize compact, multi-functional appliances designed for limited space and mobile operation, with a focus on durability.
- Bakeries:Specialized kitchens demanding precise ovens, mixers, and proofers for high-volume production of baked goods.
- Cafeterias:Serve large volumes of food quickly, requiring efficient batch cooking and serving equipment, particularly in institutional settings.
This segment's growth is driven by the expansion of Restaurants and the increasing complexity of Hotel food service operations.
End User:
End-user segments reflect varying procurement power and operational scales, influencing demand for customized solutions versus standardized equipment.
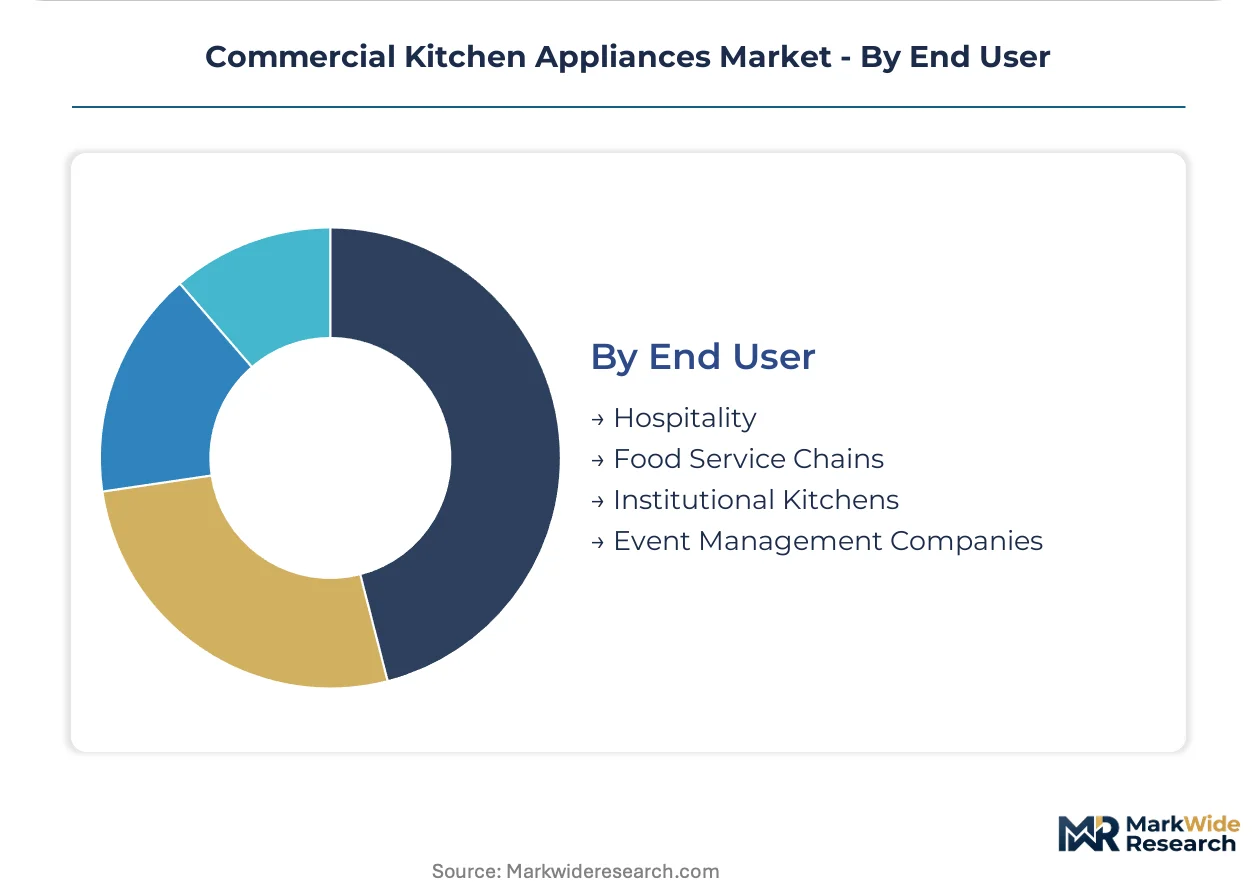
- Food Service Chains:Large, multinational operators with centralized procurement, demanding comprehensive product suites and IoT-integrated solutions for consistency across locations. These chains drive demand for advanced kitchen management systems.
- Hospitality:Encompasses hotels, resorts, and cruise lines, requiring diverse, high-performance equipment for varied culinary offerings and guest experiences. This segment prioritizes durability and aesthetic integration.
- Institutional Kitchens:Include schools, hospitals, and corporate canteens, focusing on robust, high-capacity equipment for batch cooking and strict hygiene.
- Event Management Companies:Require flexible, often mobile, kitchen setups for temporary events, valuing ease of transport and quick setup.
The segment shows a clear distinction between the large-scale, tech-driven needs of Food Service Chains and the varied requirements of the broader Hospitality sector.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled culinary professionals and engineering talent anchoring specific geographies drive innovation and market adoption within the commercial kitchen appliances sector. These concentrations influence regional product development and service infrastructure. Local regulatory frameworks and consumer preferences further shape demand for specific appliance types and technological features.
United States
Demand for commercial kitchen appliances in the United States stems from the expansion of quick-service restaurant chains and the adoption of ENERGY STAR certified equipment. NSF International standards dictate sanitation and design for most commercial food service equipment. Major metropolitan areas like New York City and Los Angeles show high demand for energy-efficient and IoT-integrated kitchen systems.
India
Rapid urbanization and the proliferation of cloud kitchens fuel the commercial kitchen appliance market across India. The country's FSSAI regulations ensure food safety and hygiene standards for all food service operations. India's metropolitan hospitality sector, particularly in cities like Mumbai and Bangalore, demonstrates strong demand for new equipment installations.
China
China's commercial kitchen appliance market is influenced by the growth of its domestic food service industry and stringent energy efficiency mandates. GB standards regulate electrical safety and performance for various appliance categories. Industrial clusters in the Yangtze River Delta region are key manufacturing hubs and also significant consumption centers for commercial kitchens.
Germany
The German market for commercial kitchen appliances emphasizes precision engineering and adherence to strict environmental regulations. The EU's Ecodesign Directive and F-Gas Regulation drive demand for energy-efficient and natural refrigerant-based equipment. Bavaria, with its strong manufacturing base, hosts several specialized commercial kitchen equipment producers and innovation centers.
United Kingdom
The United Kingdom's commercial kitchen appliance sector experiences demand from a vibrant restaurant scene and the expansion of fast-casual dining concepts. CE marking is mandatory for safety compliance for all equipment sold within the UK. London, as a global culinary hub, consistently requires advanced, high-performance kitchen technology for its diverse food establishments.
Commercial Kitchen Appliances Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a tiered market structure within the commercial kitchen appliance sector. This market exhibits both consolidation among established players and fragmentation among niche providers. Strategic archetypes include global brand portfolio holders and technology-centric innovators. Dominant competitive moves involve portfolio diversification and strategic acquisitions to expand market reach.
Specialists in integrated kitchen systems and high-performance ovens, such as Welbilt Inc. and Rational Group, represent technology-driven segments. Middleby Corporation, with its extensive brand portfolio, exemplifies a strategy of comprehensive product offerings across various kitchen needs. These companies anchor different competitive vectors, from premium, specialized solutions to broad, integrated system provision.
| Leading Market Players |
|---|
| Ali Group |
| Duke Manufacturing |
| Middleby Corporation |
| Vulcan |
| Hobart Corporation |
| Welbilt Inc. |
| Rational Group |
| Blodgett |
| Electrolux Professional |
| Others |
Cost & Logistics Intelligence
High-grade 304 stainless steel, a critical input for commercial kitchen appliances, drives pricing tiers from raw material cost through to finished product pricing. This material's global commodity market fluctuations directly impact manufacturer margins and influence end-user pricing across all segments.
Pricing Analysis
The bundled-vs-unbundled service split shapes pricing across the commercial kitchen appliance market. Transactional sales of individual units remain common, but integrated kitchen systems increasingly utilize project-based pricing. Price differentiation often stems from the inclusion of IoT capabilities and specific regulatory certifications like NSF International standards. Pricing softness reflects high upfront capital outlay for many operators, particularly independent restaurants. Food Service Chains, with their centralized procurement, typically exhibit the least price sensitivity due to volume discounts and long-term contracts.
Supply Chain Analysis
Single-source vulnerability sits with the global sourcing of specialized components and 304 stainless steel from countries like China. Key raw material dependencies include various metal alloys and advanced electronic controls. Commodity price volatility for stainless steel represents a significant structural risk for manufacturers. Distribution runs through a dual model, combining direct sales to large chains with a robust network of equipment dealers serving smaller operators and independent businesses across North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a geographic-arbitrage play, as manufacturing cost differentials between established regions like Germany and emerging production hubs in China create distinct competitive advantages.
For Market Incumbents: Anticipate continued pressure from modular equipment designs and the shift towards Equipment-as-a-Service models. Defend market share by deepening vertical integration into critical component manufacturing, especially for IoT-enabled systems. Invest in R&D for natural refrigerant technologies to comply with evolving EU F-Gas Regulation. Control distribution channels through exclusive partnerships with system integrators.
For New Entrants and Emerging Players: Begin with specialized offerings for niche but expanding segments like plant-based food preparation, which have unique equipment requirements. Target ghost kitchens and food trucks with compact, multi-functional appliances designed for limited space. A strong go-to-market angle involves offering Equipment-as-a-Service models to lower entry barriers for new businesses. Penetrate cost-sensitive markets by engineering simpler, robust machines adhering to local regulatory standards.
For Investors and Strategic Acquirers: Roll-up economics work for technology-driven manufacturers because fragmented innovation exists across specialized product categories. Focus on acquiring companies with strong intellectual property in IoT integration or advanced energy-efficient cooking technologies. A signal to watch is the increasing market penetration of subscription-based equipment models, indicating a shift in revenue streams. Long-term viability rests on manufacturers capable of delivering integrated, data-generating kitchen ecosystems.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in IoT Integration | Enhances operational efficiency and predictive maintenance for large food service chains. |
| Develop Modular Equipment | Addresses spatial and operational needs of emerging ghost kitchens and food trucks. |
| Expand Equipment-as-a-Service | Lowers capital outlay for new businesses, creating recurring revenue streams. |
| Focus on Natural Refrigerants | Ensures compliance with EU F-Gas Regulation and supports sustainability goals. |
| Acquire System Integrators | Captures demand for complete, pre-configured kitchen stations and turnkey solutions. |
Research Approach
Coverage spans the United States, India, China, Germany, and the United Kingdom, with primary inputs from each region. The analysis combines in-depth primary interviews with industry stakeholders, including procurement managers from multinational food service chains, R&D directors at equipment manufacturers, and facility managers within the hospitality sector. Secondary validation draws from government publications, regulatory body reports such as NSF International and FSSAI, and industry association data, all triangulated through bottom-up and top-down approaches.
Market dimensions, including product type, technology, application, and end-user, were modeled at a granular level across the analysis window. The analytical framework also incorporated specific regulatory compliance levels and material grade tiers as distinct variables. Compound annual growth rates were derived from historical data analysis and projected future market dynamics, with inputs from energy efficiency mandates and urbanization trends informing the forecast.
Caveats apply where unforeseen macroeconomic shifts or rapid technological disruptions could materially shift the outlook. Forecasts reflect assumptions regarding stable material supply chains and consistent regulatory enforcement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Commercial Tableware Services Market
Food Service
Global Cafe and Bars Market
Food Service
Restaurants and Mobile Food Services Market
Food Service
Food & Beverage in Asia Market
Food Service
Vacuum Flask Market
Food Service
Europe Food Away from Home Market
Food Service
Bahrain Food Service Market
Food Service
Commercial Pizza Oven Market
Food Service
Commercial Tandoor Oven Market
Food Service
Europe Vending Machine Market
Food Service
Europe Barbeque Grill Market
Food Service
Latin America Airport Quick Service Restaurant Market
Food Service
North America Online Grocery Delivery Market
Food Service
United Arab Emirates Quick Service Restaurant Market
Food Service
Airport Quick Service Restaurants Market
Food Service
Philippines Quick Service Restaurants Market