
 Europe Vending Machine Market | 2026-2036
Europe Vending Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Vending Machine Market Intelligence
Market Context
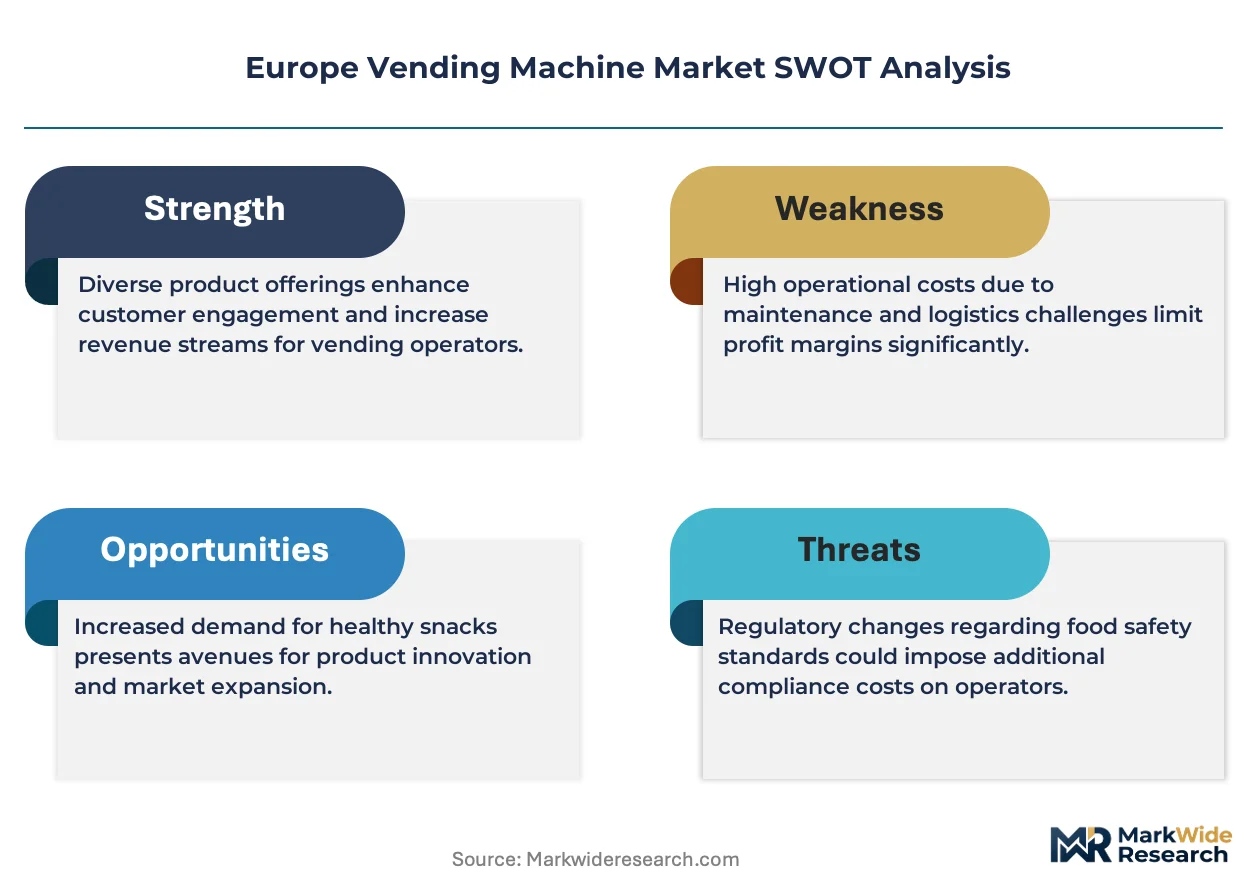
The EU F-Gas Regulation is expanding compliance costs for refrigerated vending equipment across member states. Azkoyen Group leverages its Spanish manufacturing base to control distribution networks throughout Iberia and southern France. Nayax Ltd. anchors the payment ecosystem with IoT-enabled transaction platforms that reduce cash-handling overhead for operators. Selecta sustains pan-European refreshment services through dense machine placement in transport hubs and corporate campuses.
Technical Definition and Segments
A vending machine is a self-service automated retail unit that stores, dispenses, and often refrigerates packaged goods through electromechanical or digital control systems, typically operating on 220-240V AC with integrated payment validation and inventory tracking modules. Beverage and healthy options categories are capturing margin pools as consumer preferences shift away from traditional sugary snacks toward fresh salads, protein boxes, and functional drinks. Smart and cashless technology segments are displacing legacy coin-operated units as contactless payment thresholds fall below one euro across Eurozone transit systems and office buildings.
Regulatory Frame
ECHA's REACH restrictions on hazardous substances and the EU Ecodesign Directive constrain material choices and energy consumption thresholds for new machine deployments. CE marking requirements under the EU Machinery Directive enforce safety protocols for electrical and mechanical systems in public access environments. Stakeholders must monitor how the EU AI Act's risk classification rules will apply to facial recognition age-verification and predictive restocking algorithms before committing R&D budgets to next-generation platforms.
Market Dynamics
Cashless payment infrastructure and EU energy mandates are compressing the installed base of legacy coin-operated machines while accelerating refresh cycles toward IoT-enabled, low-power units across German office parks and French transit hubs.
Growth Catalysts
- EU Green Deal efficiency mandates:Refrigerated vending equipment must meet stringent power consumption thresholds, forcing replacement of aging compressor systems with thermoelectric cooling across Benelux corridors.
- Contactless payment penetration:Eurozone transit authorities now process sub-one-euro transactions without PIN verification, eliminating friction for beverage purchases in Madrid and Milan metro networks.
- Corporate wellness programs:Fresh food machines dispensing protein boxes and functional drinks are capturing placement contracts in Parisian and Berlin office complexes seeking to reduce cafeteria operating costs.
Market Restraints
- F-Gas Regulation compliance costs:ECHA restrictions on hydrofluorocarbon refrigerants are elevating retrofit expenses for existing refrigerated units throughout Iberia and southern France.
- Component supply concentration:Compressor and payment module sourcing depends heavily on East Asian manufacturing clusters, exposing European operators to extended lead times and freight cost volatility.
- Real estate access friction:Municipal vending permits in Rome and Barcelona restrict machine density in historic centers, capping expansion potential in high-footfall tourist zones.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania maintain lower vending machine density per capita than Western European benchmarks, creating whitespace for fresh food and hot beverage formats in Warsaw and Bucharest office districts.
- Predictive restocking algorithms:Machine learning integration with inventory sensors enables dynamic route optimization, reducing service frequency costs for operators managing dispersed rural networks across France.
- EU AI Act risk classification clarity:Pending guidance on facial recognition age-verification systems will unlock R&D investment in automated compliance for tobacco and alcohol dispensing machines in German stations.
Industry Challenges
- Field service technician scarcity:Electromechanical repair skills are aging out of the workforce faster than training programs in Italy and Spain can replenish qualified maintenance personnel for legacy coin mechanisms.
- Legacy system integration complexity:Retrofitting cashless payment modules onto 15-20 year old machines requires custom firmware bridging that fragments software maintenance across heterogeneous installed bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Vending Machine Market |
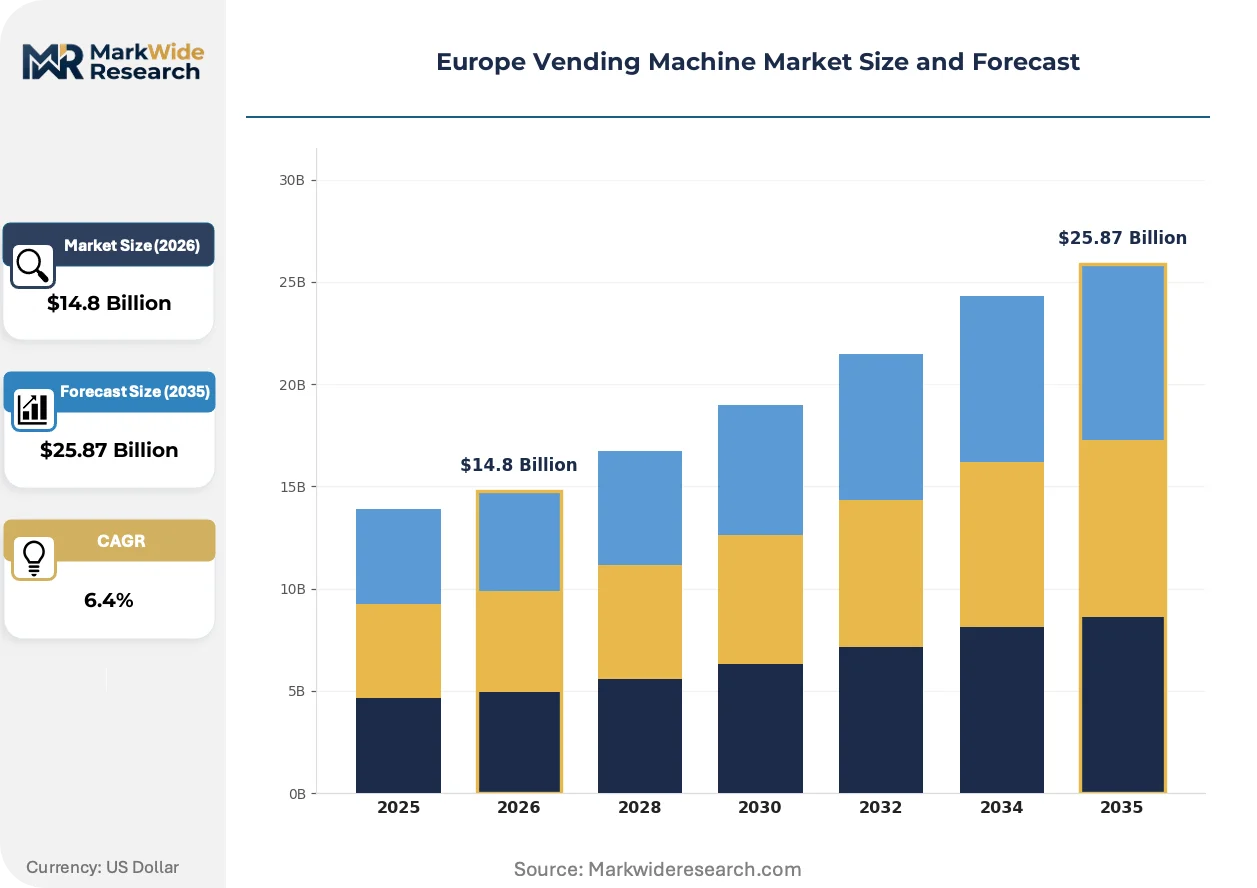
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
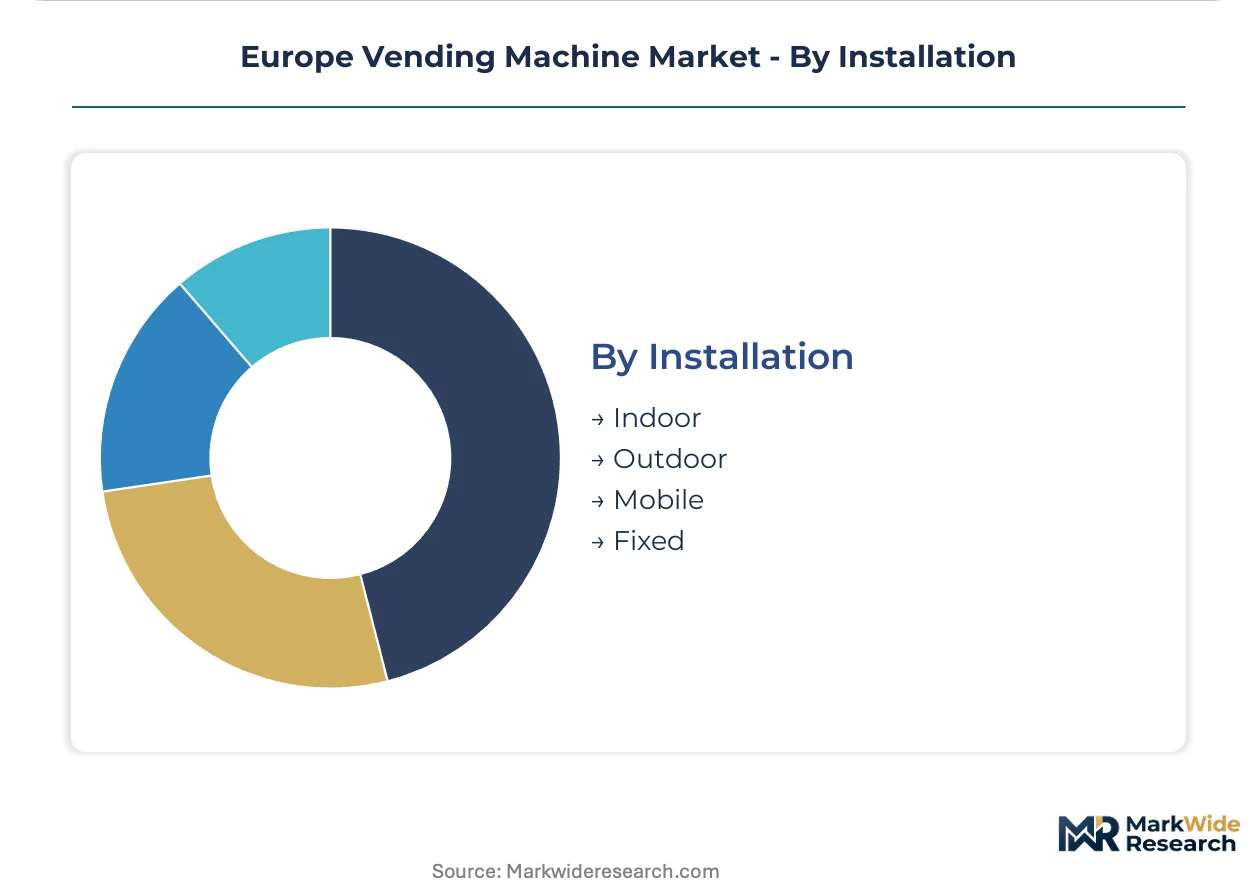
| Segmentation | Product Type: Snacks, Beverages, Healthy Options, Personal Care Technology: Traditional, Cashless, Smart, Hybrid End User: Offices, Educational Institutions, Hospitals, Public Spaces Installation: Indoor, Outdoor, Mobile, Fixed |
| Companies Covered | Nayax Ltd., ventopay GmbH, Selecta, Jofemar Corporation, IVS Iberica, Azkoyen Group, Worldline, Delikia Fresh, Aramark Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Vending Machine Market Strategic Shifts & Innovations
Electrification of vending infrastructure and algorithmic inventory management are converging to transform machine economics from passive retail to active data nodes within corporate and transit ecosystems.
IoT-enabled telemetry platforms are consolidating machine-level data streams into centralized fleet management dashboards. German vending operators are deploying these systems across Rhine-Ruhr industrial corridors to compress restocking cycles and reduce spoilage in fresh food units. The structural consequence is consolidating operational control with larger fleet managers capable of justifying platform licensing costs across thousand-plus machine estates.
REACH restrictions on hazardous substances are constraining material choices for internal machine components and food-contact surfaces. Manufacturers serving the French market are reformulating plastic formulations and coating chemistries to maintain CE marking eligibility under evolving ECHA substance blacklists. Fresh food refrigeration compartments face the most intensive reformulation pressure given direct food contact compliance requirements.
Corporate procurement departments are unbundling vending service contracts from integrated refreshment management, separating machine lease agreements from product supply and maintenance obligations. French and German facility managers are negotiating direct supplier relationships with healthy-options food producers, treating vending operators as pure hardware and payment processing vendors. This pattern is most visible in Paris La Défense and Frankfurt Bankenviertel financial districts where cost transparency pressures dominate sourcing decisions.
Europe Vending Machine Market Segmentation

Segmentation reveals how EU Green Deal mandates and cashless payment infrastructure are reshaping machine procurement priorities across European operators. Upgrade cycles now favor segments combining low-power refrigeration with IoT connectivity, compressing replacement timelines for legacy coin-operated estates.
Product Type:
Upgrade cycles favor machines capable of supporting fresh food refrigeration and telemetry integration, displacing legacy snack-only formats in German and French office corridors.
- Beverages:Refrigerated units dominate installed base economics, with thermoelectric cooling systems replacing compressor-based designs under F-Gas Regulation compliance pressure in Benelux markets. Cold coffee and functional drink formats are capturing placement contracts in Paris La Défense and Frankfurt Bankenviertel financial districts where corporate wellness budgets subsidize premium pricing.
- Healthy Options:Fresh salad, protein box, and chilled prepared meal machines require daily restocking protocols and HACCP-aligned temperature logging, elevating operational complexity for operators. Demand concentrates in Berlin and Munich corporate campuses seeking cafeteria cost reductions without sacrificing employee satisfaction metrics.
- Snacks:Traditional confectionery and packaged crisp formats face margin compression as procurement departments renegotiate vending contracts toward transparent cost-plus structures.
- Personal Care:Hygiene product and over-the-counter medicine dispensers occupy niche placement in transport hubs and hospital lobbies with limited SKU breadth.
Volume placements concentrate in Beverages; the faster expansion belongs to Healthy Options.
Technology:
Cost tier differentiation separates premium telemetry platforms from basic cashless retrofits, with mid-market operators gravitating toward hybrid configurations balancing capital outlay against data capture capabilities.
- Smart:Full-stack IoT platforms integrate inventory sensors, predictive algorithms, and remote diagnostics into centralized fleet management dashboards. Rhine-Ruhr industrial corridor operators deploy these systems across thousand-plus machine estates to compress restocking cycles and reduce fresh food spoilage.
- Cashless:Contactless payment modules with NFC and QR code acceptance eliminate coin-handling overhead while capturing transaction data for demand forecasting. Eurozone transit authorities in Madrid and Milan metro networks now process sub-one-euro purchases without PIN verification, accelerating adoption.
- Hybrid:Operators with heterogeneous installed bases combine legacy electromechanical reliability with modular payment upgrades to bridge technology generations.
- Traditional:Coin-only mechanisms persist in rural Iberia and Eastern European markets where cash penetration and technician scarcity delay replacement timelines.
Deployment density peaks with Cashless configurations; Smart platforms are climbing the fastest as fleet consolidation rewards scale.
End User:
Customer type segmentation tracks how procurement centralization and wellness mandates reshape contract structures across institutional buyers.
- Offices:Corporate facility managers unbundle vending contracts into separate hardware lease, product supply, and maintenance obligations, treating operators as pure payment processing vendors. Healthy options procurement now flows directly to food producers in French and German financial districts.
- Public Spaces:Municipal permits in Rome and Barcelona historic centers restrict machine density, capping expansion potential despite high tourist footfall.
- Hospitals:Healthcare procurement emphasizes 24-hour availability and infection-control surface materials under REACH substance restrictions.
- Educational Institutions:University campuses balance student convenience against sugar-content regulations and healthy eating campaigns.
Contract value aggregates in Offices; Public Spaces face the steepest regulatory barriers to expansion.
Installation:
Application context determines power supply requirements, weatherproofing specifications, and service accessibility constraints across deployment environments.
- Indoor:Climate-controlled environments support fresh food refrigeration with reduced energy consumption, concentrating healthy options placement in German and French office complexes with reliable HVAC infrastructure.
- Outdoor:Weather-hardened enclosures with vandal-resistant surfaces and extended temperature operating ranges serve transport hubs and street-level retail in Madrid and Milan.
- Fixed:Permanent electrical connections anchor high-volume beverage and snack installations with predictable maintenance scheduling.
- Mobile:Battery-powered or generator-dependent units serve temporary events and construction sites with limited SKU variety and higher per-transaction servicing costs.
Machine counts favor Indoor placement; Outdoor formats are gaining share fastest as transit authorities modernize station infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's Île-de-France region offers tax incentives for smart infrastructure deployment that concentrate vending modernization investments in Paris La Défense and surrounding office corridors.
Germany
Corporate wellness mandates and cafeteria cost reduction programs drive healthy options machine placement in Frankfurt Bankenviertel and Berlin corporate campuses. The EU F-Gas Regulation elevates retrofit costs for refrigerated units, pushing Rhine-Ruhr operators toward thermoelectric cooling systems. Bavarian industrial clusters anchor fleet consolidation as thousand-plus machine estates justify IoT platform licensing.
France
Facility managers unbundle vending contracts into separate hardware lease and product supply obligations in Paris financial districts. ECHA REACH restrictions on hazardous substances constrain plastic formulations for food-contact surfaces. Île-de-France office complexes lead fresh food machine adoption as procurement departments negotiate direct supplier relationships with healthy-options producers.
Spain
Municipal permit restrictions in Barcelona and Madrid historic centers cap machine density despite high tourist footfall. Azkoyen Group leverages its Spanish manufacturing base to control distribution networks throughout Iberia. Andalusian transit authorities deploy cashless payment modules as Eurozone sub-one-euro transaction thresholds eliminate purchase friction.
Italy
Field service technician scarcity delays legacy coin mechanism maintenance across Rome and Milan networks. CE marking requirements under the EU Machinery Directive enforce safety protocols for public access electromechanical systems. Northern Italian industrial corridors concentrate smart vending deployment as fleet managers compress restocking cycles through predictive algorithms.
Netherlands
Benelux markets lead thermoelectric cooling adoption under EU Green Deal power consumption thresholds. Amsterdam and Rotterdam transport hubs modernize station infrastructure with weather-hardened outdoor units. Dutch operators deploy IoT-enabled telemetry platforms across dense urban networks to reduce fresh food spoilage through dynamic route optimization.
Europe Vending Machine Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across payment systems, refrigeration hardware, and refreshment services. The vendor base organizes into three strategic archetypes: integrated refreshment service providers, component specialists in payment and telemetry modules, and regional manufacturing champions with captive distribution networks. Competitive moves center on fleet consolidation through operational scale and contract unbundling that separates hardware lease from product supply obligations.
Among payment ecosystem specialists, Nayax Ltd. and Worldline occupy positions anchoring IoT-enabled transaction platforms that reduce cash-handling overhead for operators. Azkoyen Group represents the regional manufacturing archetype with Spanish production bases controlling Iberian distribution networks. Selecta sits within the integrated service tier, sustaining pan-European refreshment operations through dense machine placement in transport hubs and corporate campuses.
| Leading Market Players |
|---|
| Nayax Ltd. |
| ventopay GmbH |
| Selecta |
| Jofemar Corporation |
| IVS Iberica |
| Azkoyen Group |
| Worldline |
| Delikia Fresh |
| Aramark Corporation |
| Others |
Cost & Logistics Intelligence
Copper price volatility cascades through compressor and payment module manufacturing, forcing European vending operators into three-tier pricing structures across premium telemetry platforms, standard cashless retrofits, and economy coin-mechanical units.
Pricing Analysis
Short-lead-time premiums of fifteen to twenty percent separate urgent compressor replacements from scheduled procurement cycles in German fleet operations. Price differentiation hinges on CE marking tier and IoT telemetry bundling, with unmarked refurbished units trading at steep discounts. Pricing pressure stems from F-Gas Regulation compliance retrofitting costs compressing margins on legacy refrigerated estates. Small rural operators in Iberia exhibit highest price sensitivity, while consolidated Rhine-Ruhr fleet managers absorb premium telemetry licensing with minimal negotiation.
Supply Chain Analysis
Reverse-logistics flows for compressor refurbishment and payment module remanufacturing concentrate in Poland and Romania, creating secondary supply channels for cost-conscious Eastern European operators. Compressor production draws from China, South Korea, and Germany, while NFC payment chip fabrication rests on Taiwanese and Malaysian capacity. Single-source vulnerability in thermoelectric cooling element supply exposes Benelux operators to extended lead times. Distribution runs through Azkoyen-controlled Iberian networks and Selecta-managed pan-European refreshment corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Component supply concentration in East Asian manufacturing clusters constrains European vending equipment availability, propping pricing power for domestic compressor assemblers with captive inventory positions.
For Market Incumbents: Anchor fleet consolidation advantages by acquiring distressed operator estates in Italy and Spain where technician scarcity accelerates exit pressures. Defend against payment ecosystem disintermediation by deepening backward integration into IoT telemetry software rather than licensing from Nayax-dependent platforms. Prioritize thermoelectric cooling capacity expansion in Poland to capture F-Gas retrofit demand.
For New Entrants and Emerging Players: Begin with fresh food machine placement in Warsaw and Bucharest office districts where vending density lags Western European benchmarks by sixty percent. Exploit contract unbundling trends by positioning as pure hardware vendors to French procurement departments already negotiating direct supplier relationships with healthy-options producers. Lead with HACCP-aligned temperature logging as differentiated service capability.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale fleet operators with dense Rhine-Ruhr or Île-de-France machine placement and aging coin-mechanical estates requiring capital-intensive refresh. Long-term viability hinges on telemetry platform ownership rather than operator scale alone. Monitor EU AI Act guidance on facial recognition age-verification as inflection signal for alcohol and tobacco dispensing machine R&D commitment.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Telemetry Platforms | Captures recurring SaaS revenue streams from fleet management dashboards across thousand-plus machine estates. |
| Thermoelectric Cooling Capacity Expansion | Positions manufacturers ahead of F-Gas Regulation compressor phase-out deadlines in Benelux and German markets. |
| Direct Supplier Relationships with Food Producers | Aligns with Paris La Défense procurement unbundling trends separating hardware lease from product supply. |
| Predictive Restocking Algorithm Development | Reduces service frequency costs for operators managing dispersed rural networks across France. |
| Eastern European Distribution Network Buildout | Captures whitespace in Warsaw and Bucharest office corridors with lower vending density per capita. |
Research Approach
Independent corroboration across vending fleet operators, component manufacturers, and facility management procurement leads underwrites the qualitative findings. Primary fieldwork encompassed interviews with Rhine-Ruhr fleet managers, Iberian maintenance technicians, Parisian procurement directors, and Dutch transport authority planners. Secondary validation drew from ECHA substance restriction databases, EU Machinery Directive CE marking registries, Eurozone transit authority payment disclosures, and Benelux customs import records. Bottom-up machine placement counts triangulated against top-down refreshment service revenue estimates.
Comparable-period anchoring tied projection assumptions to historical upgrade cycle patterns observed across German office park and French transit hub deployments. The analytical framework modeled value trajectories across product type, technology tier, end-user category, and installation environment throughout the forecast period. CAGRs were derived from segment-level replacement rate assumptions and penetration curve modeling. Forecast inputs included EU Green Deal power consumption threshold implementation schedules and contactless payment infrastructure rollout timelines.
Underlying measurement precision varies by segment; smart and cashless technology categories carry tighter precision than traditional coin-mechanical estates given concentrated vendor reporting. Forecasts reflect documented assumptions regarding F-Gas retrofit cost pass-through rates and technician training program expansion. Practitioners should monitor ECHA substance blacklist updates and Eurozone sub-one-euro transaction threshold adoptions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Global Food Retail Market
Food Service
Philippines Foodservice Market
Food Service
United States Quick Service Restaurants Market
Food Service
Food Service Utensils Market
Food Service
Europe Out of Home (OOH) Delivery Market
Food Service
Food Trays Market
Food Service
Chained Consumer Foodservice Market
Food Service
Egypt Food Service Market
Food Service
Global Virtual Restaurant and Ghost Kitchens Market
Food Service
Saudi Arabia Pizza Restaurants Market
Food Service
Commercial Ice Dispenser Market
Food Service
Europe Pizza Oven Market
Food Service
United States Foodservice Market
Food Service
North America Online Grocery Delivery Market
Food Service
UAE Food Service Market
Food Service
Germany Foodservice Market