
 Used Commercial Kitchen Equipment Market | 2026-2036
Used Commercial Kitchen Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Used Commercial Kitchen Equipment Market Analytics
Certified technician availability is bifurcating the used commercial kitchen equipment trade into dealer-networked refurbishment centers and informal resale channels. ACityDiscount Restaurant Equipment leverages its Southeast distribution footprint to sustain volume turnover in reconditioned refrigeration units. Texas Restaurant Supply anchors its competitive position through direct warehouse relationships with shuttered restaurant estates across Dallas and Houston. EquipNet operates a digital auction platform that extends geographic reach beyond traditional wholesale territories.
Used commercial kitchen equipment encompasses pre-owned stainless steel appliances rated for continuous foodservice operation, typically refurbished to NSF/ANSI sanitation and electrical safety standards before re-entry into commercial use. These assets retain thermal efficiency specifications within 85-95% of original manufacturer ratings after professional reconditioning, serving operators seeking capital expenditure reduction without sacrificing code compliance. Ovens and fryers command the largest residual value pools due to enduring structural demand from quick-service restaurants and institutional cafeterias. Refrigerators represent the fastest-turning segment as cold-chain integrity requirements accelerate replacement cycles even in secondary markets. Distribution through online retailers is reshaping price discovery, compressing regional arbitrage opportunities that wholesalers historically exploited.
NSF International standards, FDA Food Code provisions, and state health department inspection protocols collectively govern equipment eligibility for commercial kitchen redeployment in the United States. The EPA's energy efficiency guidelines and DOE commercial appliance standards further constrain which legacy units qualify for operational permits in foodservice establishments. Stakeholders must monitor evolving electrification mandates and refrigerant phase-down regulations that will progressively disqualify certain gas-fired and R-22-dependent equipment from lawful resale channels.
Market Dynamics
Certified refurbishment capacity is concentrating in dealer-networked hubs while informal resale channels lose access to NSF-compliant technician pools, bifurcating supply into code-compliant and gray-market tiers.
Growth Catalysts
- Electrification mandates:EPA and DOE efficiency standards are accelerating replacement of gas-fired equipment, expanding the residual pool of pre-owned electric units eligible for redeployment.
- Cloud kitchen proliferation:Ghost kitchen operators in Texas, Florida, and California prioritize capital-light equipment sourcing to compress payback periods on short-lease facilities.
- NSF certification traceability:State health department inspection protocols now require documented refurbishment chains, advantaging dealers with certified technician networks over informal sellers.
Market Restraints
- Refrigerant phase-down schedules:EPA regulations disqualifying R-22-dependent units from lawful resale are shrinking the addressable pool of legacy refrigeration assets.
- Technician scarcity:Certified NSF/ANSI reconditioning specialists concentrate in Dallas, Houston, and Atlanta, limiting refurbishment throughput in secondary markets.
- Energy code divergence:California Title 24 standards and Texas administrative codes create compliance fragmentation that raises cross-border equipment transfer costs.
Strategic Opportunities
- Digital auction platforms:Online marketplaces are compressing price discovery timelines and extending geographic reach beyond traditional wholesale territories.
- Institutional cafeteria contracts:K-12 and university foodservice operators represent underpenetrated buyers with standardized replacement cycles and bulk procurement authority.
- Refrigeration remanufacturing:Cold-chain integrity requirements accelerate replacement cycles, creating high-velocity turnover in reconditioned reach-in and walk-in units.
Industry Challenges
- Documentation authenticity:Provenance verification for shuttered restaurant estates requires forensic assessment of maintenance records and prior health inspection histories.
- Integration complexity:Legacy control systems in pre-owned cooking lines often conflict with modern kitchen automation platforms, demanding custom interface engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Used Commercial Kitchen Equipment Market |
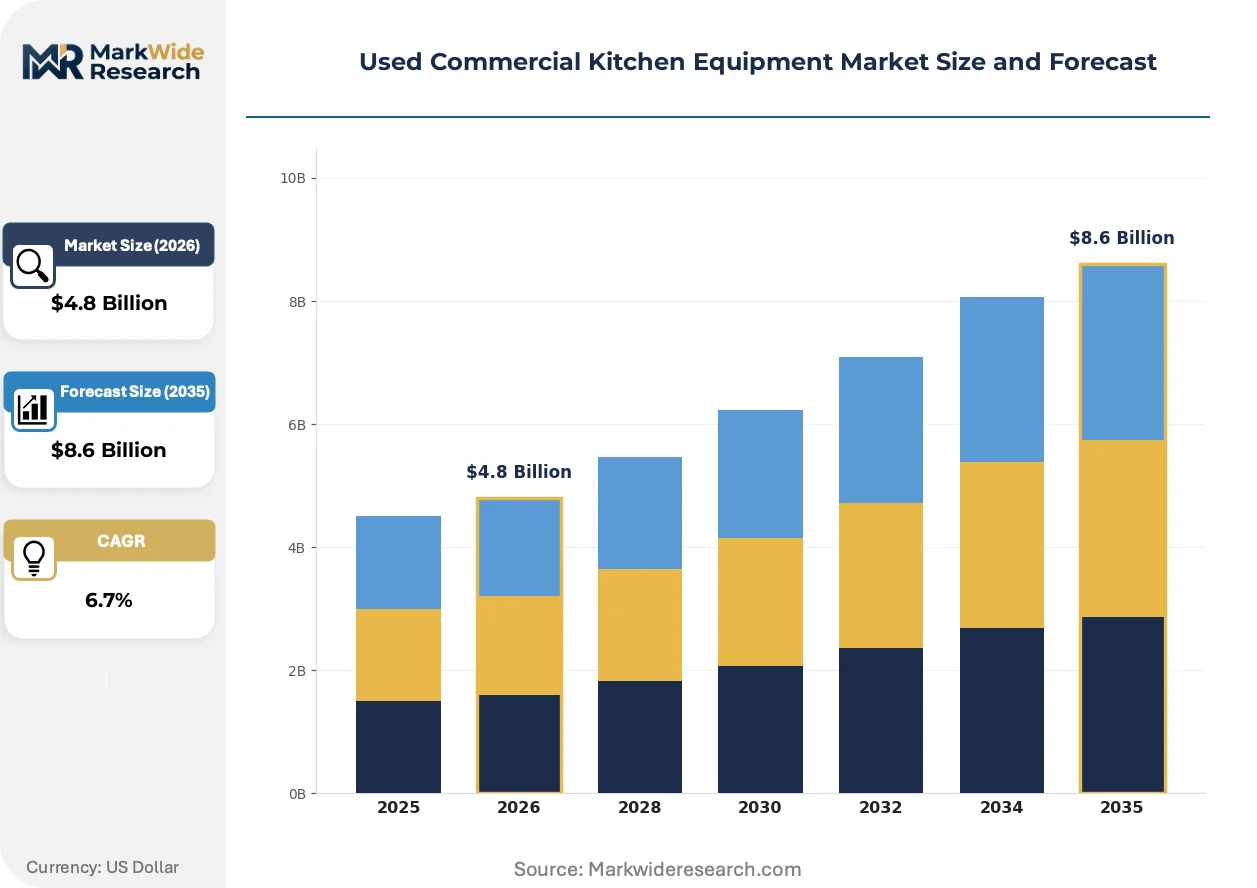
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ovens, Refrigerators, Fryers, Grills End User: Restaurants, Hotels, Catering Services, Cafes Distribution Channel: Online Retailers, Wholesalers, Auctions, Direct Sales Installation Type: Indoor, Outdoor, Mobile, Stationary |
| Companies Covered | ACityDiscount Restaurant Equipment, Federal Hospitality Equipment, Texas Restaurant Supply, Lauro Restaurant Equipment, EquipNet, Gillette Restaurant Equipment, Rose’s Equipment, Alternative Sales Corp., Machineseeker Group GmBH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Used Commercial Kitchen Equipment Market Evolving Landscape
Equipment intelligence and regulatory stringency are converging to reshape how secondary market assets are sourced, certified, and redeployed across foodservice operations.
Smart sensor retrofits are displacing manual temperature logging in reconditioned refrigeration units. Quick-service restaurant chains now mandate IoT-enabled cold-chain monitoring as a condition of equipment acceptance. This capability gap is compressing residual values for non-connected legacy assets while elevating premiums for sensor-integrated refurbished units.
California Title 24 building efficiency standards and EPA refrigerant management regulations are tightening equipment eligibility criteria. The industrial consequence is progressive disqualification of gas-fired and high-GWP refrigeration systems from permitted commercial use. Institutional cafeteria operators in the state are responding by accelerating procurement of electric-ready reconditioned lines ahead of compliance deadlines.
Buyer aggregation through group purchasing organizations is consolidating demand-side leverage in the secondary equipment channel. Independent restaurants historically sourced through fragmented dealer networks are now accessing volume-tier pricing through GPO intermediaries. This concentration is most visible in Florida and Texas, where multi-unit operators pool replacement cycles to extract refurbishment guarantees and extended warranty terms.
Used Commercial Kitchen Equipment Market Segmentation
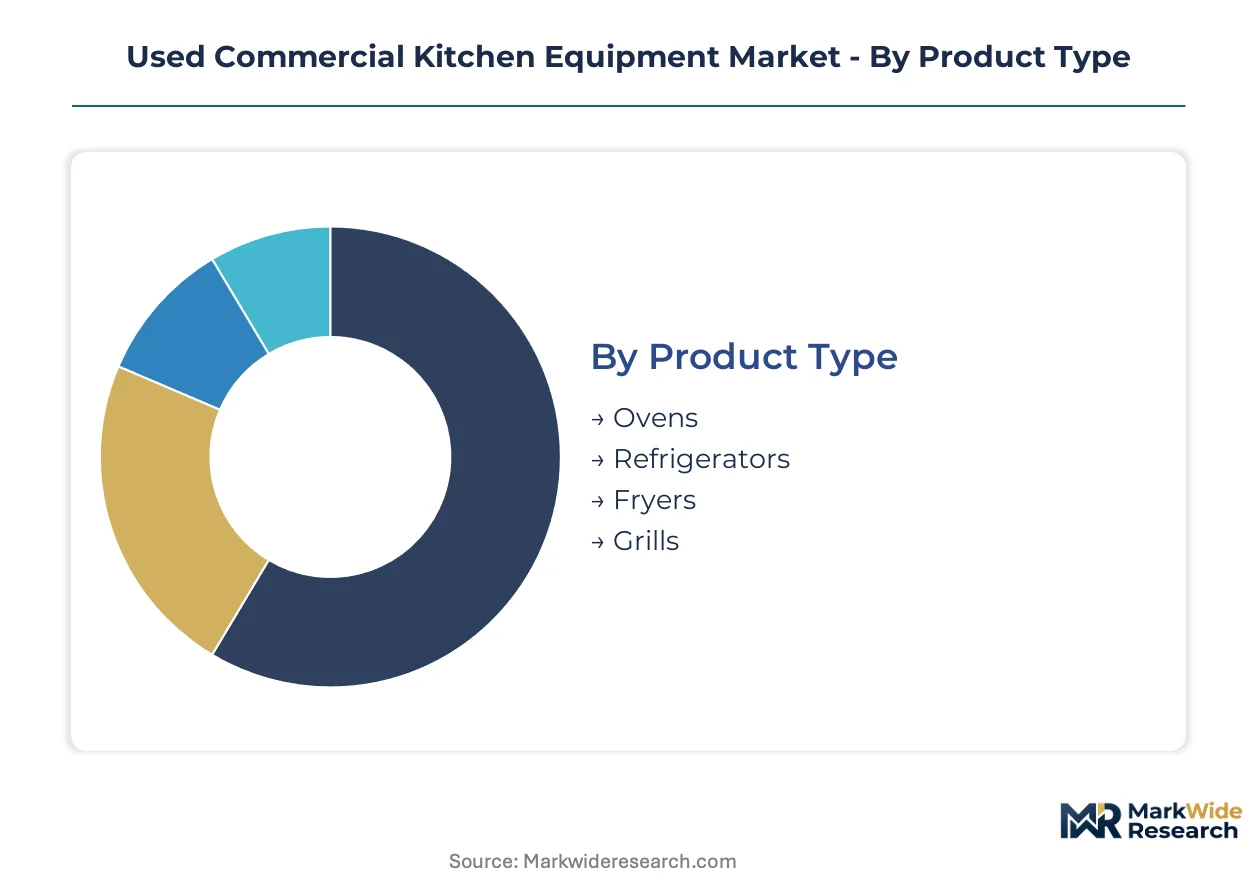
Segmentation in used commercial kitchen equipment reveals how capital constraints and code compliance reshape procurement patterns. Distinct buyer profiles prioritize different residual value pools and refurbishment guarantees.
Product Type:
Margin pools concentrate in thermally intensive assets where structural durability extends useful life beyond depreciation schedules.
- Ovens:Convection and deck-style units retain 85-95% thermal efficiency after professional reconditioning. Quick-service restaurant chains in Texas and Florida source these for standardized kitchen builds where NSF certification is non-negotiable.
- Refrigerators:Reach-in and walk-in cold storage units turn fastest in secondary markets due to accelerated replacement cycles driven by cold-chain integrity mandates. Cloud kitchen operators prioritize these for short-lease facilities where equipment mobility matters.
- Fryers:Gas and electric models command residual premiums in institutional cafeteria procurement.
- Grills:Flat-top and charbroiler configurations serve independent restaurants seeking line flexibility.
The dominant share belongs to Ovens, while Refrigerators is closing the gap fastest.
End User:
Volume concentration tracks lease cycle volatility and capital expenditure sensitivity across foodservice business models.
- Restaurants:Independent operators and small chains dominate refurbishment demand, sourcing reconditioned cooking lines to compress startup costs. Buyer aggregation through group purchasing organizations is consolidating demand-side leverage in Texas and Florida dealer networks.
- Hotels:Full-service properties with captive foodservice operations standardize replacement cycles across property portfolios, creating bulk procurement opportunities for certified refurbishment centers.
- Catering Services:Mobile and event-focused operators prioritize equipment portability and rapid deployment capability.
- Cafes:Limited-service beverage and light food concepts drive compact footprint equipment turnover.
Restaurants captures the largest volume share, with Hotels expanding most quickly through portfolio standardization.
Distribution Channel:
Price discovery mechanisms are fragmenting between digital platforms and relationship-based wholesale territories.
- Online Retailers:Digital marketplaces compress regional arbitrage timelines by extending geographic reach beyond traditional wholesale boundaries. Photographic documentation and remote condition assessment are displacing physical inspection requirements for standardized equipment categories.
- Wholesalers:Dealer-networked refurbishment centers in Dallas, Houston, and Atlanta anchor supply through certified technician pools and documented NSF compliance chains.
- Auctions:Estate liquidations from shuttered restaurant operations concentrate supply in distressed asset categories.
- Direct Sales:Manufacturer buyback programs and operator-to-operator transfers bypass intermediary markups.
Online Retailers is gaining share fastest, though Wholesalers retains the dominant position through certification credibility.
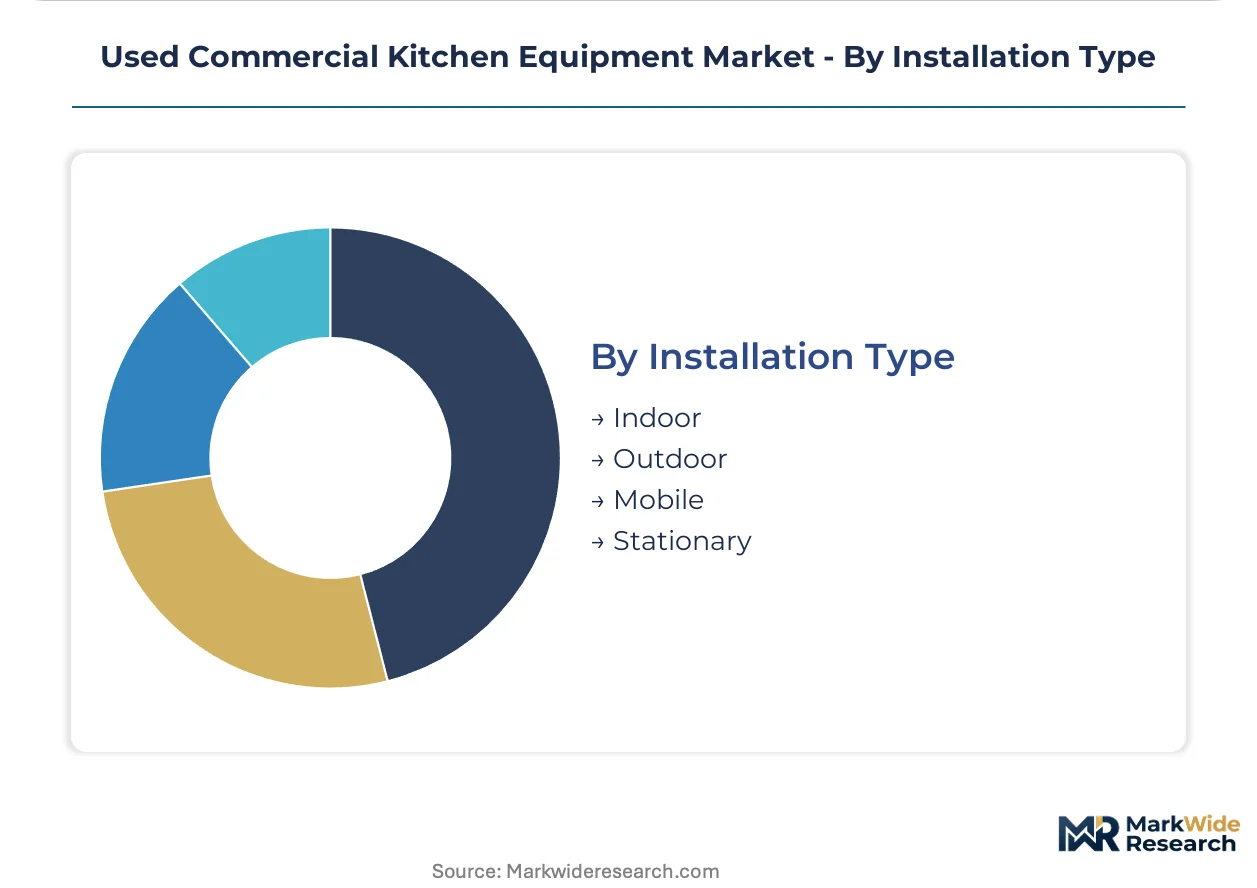
Installation Type:
Deployment flexibility is reshaping residual value calculations as operator mobility requirements intensify.
- Indoor:Fixed-location installations in permanent foodservice facilities represent the core refurbishment market, with code compliance documentation most mature for stationary assets.
- Outdoor:Weather-resistant configurations serve seasonal operations and entertainment venues with specialized ventilation and electrical requirements.
- Mobile:Trailer-mounted and cart-based systems enable rapid site deployment for catering operators and ghost kitchen concepts seeking lease flexibility.
- Stationary:Built-in equipment lines anchor institutional cafeteria and hotel kitchen configurations with extended depreciation horizons.
Indoor holds the dominant share, while Mobile is climbing the fastest on cloud kitchen proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NSF International certification requirements and state-level food safety codes in the United States establish the regulatory baseline that other jurisdictions reference when structuring their own secondary equipment frameworks.
United States
Independent restaurants and cloud kitchen operators in Texas, Florida, and California drive refurbishment demand through dense secondary dealer networks. The FDA Food Code provisions and EPA energy efficiency guidelines govern equipment eligibility for commercial redeployment. Dallas and Houston anchor certified technician concentration, while shuttered restaurant estates supply direct warehouse relationships.
Germany
Institutional cafeteria operators and hotel chains source reconditioned cooking lines to standardize replacement cycles across property portfolios. The ECHA REACH regulations and CE marking requirements constrain which legacy units qualify for operational permits. Industrial refurbishment hubs concentrate in North Rhine-Westphalia, where dealer-networked centers maintain documented compliance chains.
United Kingdom
Ghost kitchen concepts and quick-service restaurant chains prioritize capital-light equipment sourcing to compress payback periods. The Food Standards Agency codes and EU-legacy safety standards tighten traceability requirements for pre-owned assets. London and the Southeast corridor host the densest concentration of digital auction platforms extending geographic reach.
Canada
Full-service hotels with captive foodservice operations create bulk procurement opportunities for certified refurbishment centers. Health Canada and PMRA provisions align with FDA benchmarks while adding provincial inspection layers. Ontario and Quebec dealer networks leverage cross-border supply relationships with US refurbishment hubs.
Australia
Mobile catering operators and seasonal entertainment venues drive demand for weather-resistant outdoor configurations. The TGA and state health department protocols govern commercial kitchen equipment redeployment eligibility. New South Wales and Victoria concentrate certified technician pools, though scarcity limits refurbishment throughput relative to primary markets.
Used Commercial Kitchen Equipment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with geographic coverage and certification credibility separating the layers. The market structure bifurcates between dealer-networked refurbishment centers with documented NSF compliance chains and informal resale channels losing access to certified technician pools. Three archetypes dominate: Southeast-distributed volume specialists, Texas-anchored estate liquidators, and digital auction platforms compressing price discovery timelines. Competitive moves concentrate on geographic footprint expansion and technician certification pipeline development.
Among US-based refurbishment specialists, ACityDiscount Restaurant Equipment and Texas Restaurant Supply exemplify the dealer-networked archetype through regional density and direct warehouse relationships. EquipNet occupies a position on the digital platform vector, representing the auction-model alternative that extends reach beyond traditional wholesale territories. Machineseeker Group GmBH anchors the European specialist tier, with its German corporate structure signaling cross-border equipment sourcing capability.
| Leading Market Players |
|---|
| ACityDiscount Restaurant Equipment |
| Federal Hospitality Equipment |
| Texas Restaurant Supply |
| Lauro Restaurant Equipment |
| EquipNet |
| Gillette Restaurant Equipment |
| Rose's Equipment |
| Alternative Sales Corp. |
| Machineseeker Group GmBH |
| Others |
Value Network & Pricing Analysis
Long-term refurbishment contracts with certified dealer networks lock in supply access and price visibility for multi-unit restaurant operators across Texas and Florida. These agreements insulate buyers from spot-market volatility in NSF-compliant technician labor while compressing procurement timelines for critical kitchen line replacements.
Pricing Analysis
Geographic price spreads of 15-25% separate Dallas-Houston dealer hubs from secondary markets lacking certified technician density. Three-tier pricing structure across premium NSF-certified, standard reconditioned, and economy gray-market tiers reflects documentation authenticity and warranty coverage differentials. Cost compression in the economy tier is intensifying because informal sellers lose access to compliant technician pools. Independent restaurants exhibit highest price sensitivity, while institutional cafeteria operators prioritize certification credibility over unit cost.
Supply Chain Analysis
Strait of Hormuz transit risk is irrelevant here; instead, certified technician scarcity in secondary markets underwrites supply bottlenecks for NSF-compliant refurbishment. Equipment sourcing concentrates in the United States, Germany, and the United Kingdom where shuttered restaurant estates and institutional liquidation events feed secondary supply. Stainless steel fabrication, compressor assemblies, and control system components anchor raw material dependencies. Single-source vulnerability sits with EPA-certified refrigerant reclaim facilities. Distribution runs through dealer-networked refurbishment centers in Dallas, Houston, and Atlanta, with digital auction platforms compressing regional arbitrage timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against new equipment financing models and rental-as-a-service platforms that threaten refurbishment demand. Incumbents must navigate capital-light alternatives while preserving certification credibility.
For Market Incumbents: Shield refurbishment margins by deepening certified technician pipelines in Dallas and Houston, where scarcity concentrates pricing power. Secure exclusive estate liquidation relationships with shuttered restaurant chains to lock supply access. Vertical integration into refrigerant reclaim operations mitigates EPA regulatory exposure. For New Entrants and Emerging Players: Differentiate on IoT-enabled sensor retrofits for reconditioned refrigeration units, where quick-service chains now mandate connected cold-chain monitoring. Target institutional cafeteria procurement in Texas and Florida, where bulk replacement cycles and GPO aggregation create volume entry points. Lead with refurbishment guarantees and extended warranty terms. For Investors and Strategic Acquirers: Dealer-networked refurbishment centers with documented NSF compliance chains and direct warehouse relationships represent the priority acquisition archetype. Long-term viability hinges on electrification mandate tailwinds and cloud kitchen proliferation sustaining capital-light equipment demand. Watch EPA refrigerant phase-down enforcement velocity as the inflection signal for refrigeration asset stranding risk.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Technician Pipeline Expansion | NSF-compliant labor scarcity in secondary markets creates defensive moats for hub operators. |
| Digital Auction Platform Integration | EquipNet-style platforms compress price discovery timelines and extend geographic reach beyond wholesale territories. |
| IoT Sensor Retrofit Capability | Connected cold-chain monitoring mandates from quick-service chains elevate premiums for sensor-integrated refurbished units. |
| Estate Liquidation Relationship Lock | Direct warehouse relationships with shuttered restaurant chains in Dallas and Houston secure supply access. |
| Refrigerant Reclaim Vertical Integration | EPA phase-down regulations make certified reclaim operations critical for refrigeration asset eligibility. |
Research Methodology
Desk research of FDA Food Code provisions, EPA energy efficiency guidelines, and state health department inspection protocols preceded structured interviews with refurbishment center operators, certified NSF technicians, restaurant procurement directors, and group purchasing organization contract managers. Secondary validation drew from equipment auction transaction records, dealer network capacity disclosures, and regulatory filing databases. Bottom-up equipment flow modeling and top-down market sizing triangulated volume estimates across the analysis window.
Variance decomposition across product type, end user, distribution channel, and installation type segmentation dimensions shaped the analytical framework. CAGRs were derived from replacement cycle velocity, electrification mandate compliance deadlines, and cloud kitchen facility expansion trajectories. Refrigerant phase-down schedules and certified technician geographic concentration served as industry-specific forecast inputs throughout the modeling period.
The analysis sits within stated boundaries; outcomes outside sustained cloud kitchen proliferation or accelerated EPA enforcement would require recalibration. Forecasts reflect assumptions regarding refurbishment capacity expansion and state-level code harmonization. Practitioners should keep alternative scenarios live as electrification mandates and refrigerant regulations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Food Service Equipment Market
Food Service Equipment
Global Roti Maker Market
Food Service Equipment
900 Series Cooking Equipment Market
Food Service Equipment
Food Warmer Machines Market
Food Service Equipment
Global Glass Door Cooler Market
Food Service Equipment
Hospital Foodservice Equipment Market
Food Service Equipment
Slow Cooker and Sous Vide Market
Food Service Equipment
Commercial Hot Dog Cooker Market
Food Service Equipment
Cooking Hood Market
Food Service Equipment
Industrial Dishwasher Market
Food Service Equipment
Commercial Rotisserie Oven Market
Food Service Equipment
Commercial Rotisserie Equipment Market
Food Service Equipment
United States Commercial Dishwasher Market
Food Service Equipment
Commercial Foodservice Equipment Market
Food Service Equipment
Food Holding Equipment Market
Food Service Equipment
Portable Cooler Market