
 Cloud Kitchen Market | 2026-2036
Cloud Kitchen Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Kitchen Market Intelligence
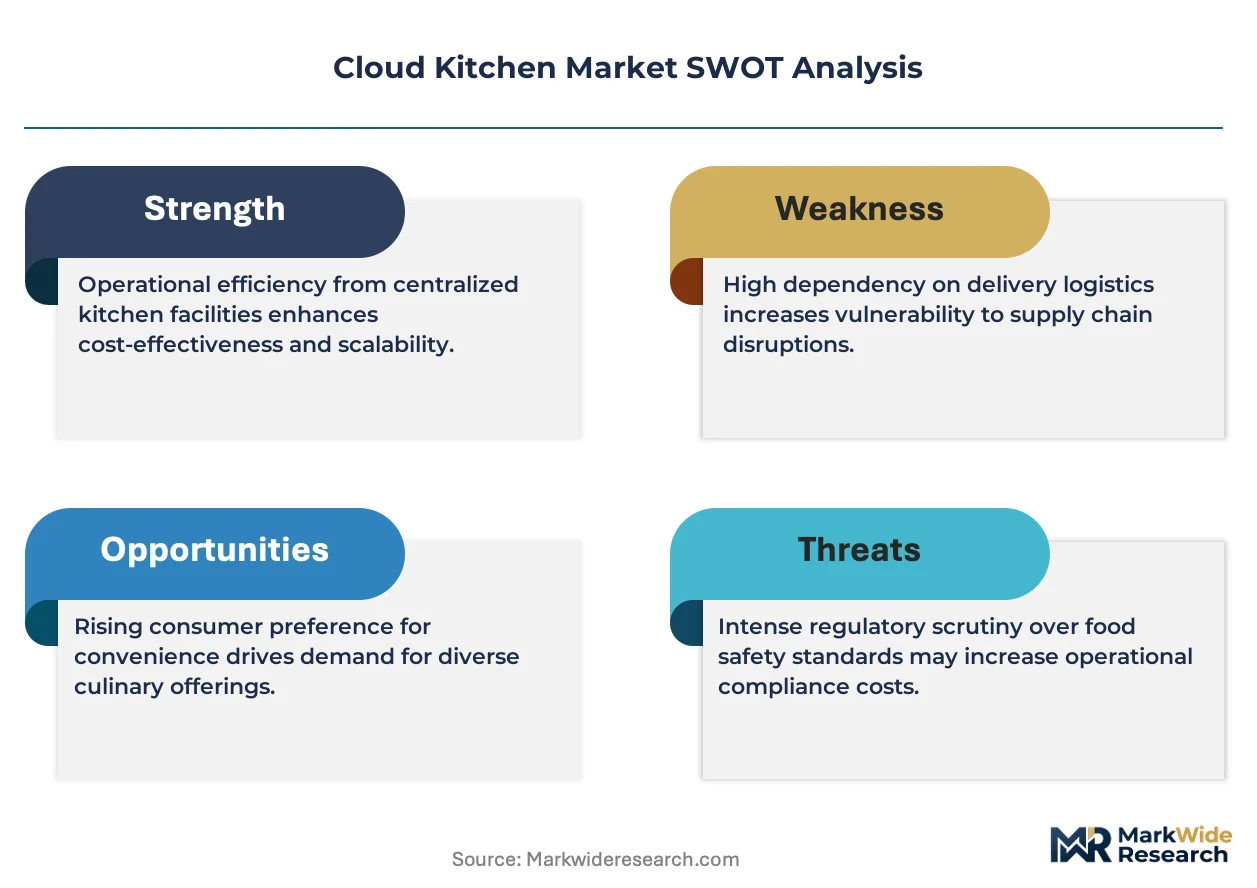
Delivery-first kitchen infrastructure is tilting margin pools away from traditional dine-in real estate toward asset-light fulfillment nodes. Rebel Foods operates India's largest multi-brand cloud kitchen network, leveraging proprietary technology to coordinate dozens of virtual restaurant brands from shared production sites. CloudKitchens sustains aggressive geographic expansion across North American and European metro corridors, anchoring its model on flexible lease terms and centralized logistics. Kitchen United differentiates through hybrid pickup-delivery hubs embedded in retail developments, competing for landlord partnerships in high-traffic suburban zones.
Cloud kitchens are commercial food production facilities purpose-built for off-premise consumption, equipped with modular cooking stations, temperature-controlled staging areas, and integrated exhaust and fire suppression systems rated for continuous high-volume output. Their primary purpose is to decouple food preparation from guest-facing service, enabling operators to optimize labor and real estate costs per order. Multi-brand kitchen configurations currently capture the dominant share of capital deployment, as operators maximize throughput across dayparts by housing several virtual brands under one roof. AI-powered analytics represents the fastest-growing technology integration segment, with operators deploying demand forecasting and dynamic menu pricing to reduce waste and improve kitchen utilization.
Food safety regulators including the FDA, EFSA, and local health departments impose stringent sanitation and traceability standards that shape kitchen design and operational protocols. The EU's General Food Law and emerging digital food safety mandates in US jurisdictions require cloud kitchen operators to maintain auditable temperature logs and allergen management systems. Stakeholders must monitor how evolving delivery platform commission structures and municipal zoning reforms for ghost kitchens will reshape unit economics and market access conditions.
Market Dynamics
Delivery-first infrastructure is tilting margin pools away from traditional dine-in real estate toward asset-light fulfillment nodes. Capital deployment now concentrates on modular cooking stations and integrated logistics rather than front-of-house buildouts.
Growth Catalysts
- Urban density premiums:Metropolitan India generates outsized order volumes per square kilometer, compressing last-mile costs below suburban benchmarks.
- FSSAI digitization mandates:India's food safety regulator requires real-time temperature logging and allergen traceability, accelerating operator investment in compliant kitchen infrastructure.
- Dark store convergence:Grocery and meal-kit operators are repurposing excess warehouse capacity into shared food production nodes, expanding addressable kitchen supply.
Market Restraints
- Platform commission compression:Aggregator take rates of 25-30% per order strip operating margins below sustainable thresholds for single-brand operators.
- Municipal zoning friction:Ghost kitchen permits face resistance from neighborhood associations and legacy restaurant lobbies in dense US and European jurisdictions.
- Input cost volatility:Commercial cooking equipment and cold-chain refrigeration components fluctuate with steel and copper commodity cycles.
Strategic Opportunities
- Suburban retail embedding:Hybrid pickup-delivery hubs anchored in grocery-anchored shopping centers capture underserved household clusters outside urban cores.
- AI-powered demand forecasting:Machine learning models predicting order timing and menu mix enable dynamic labor scheduling and waste reduction.
- EU digital food safety alignment:EFSA traceability standards create compliance arbitrage for operators building auditable systems ahead of enforcement deadlines.
Industry Challenges
- Certification timeline compression:Health department approvals for new kitchen sites stretch 4-8 months in major US metro corridors, delaying revenue ramp.
- Cross-brand contamination protocols:Multi-tenant facilities must engineer segregated airflow and sanitation workflows to satisfy allergen management requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Kitchen Market |
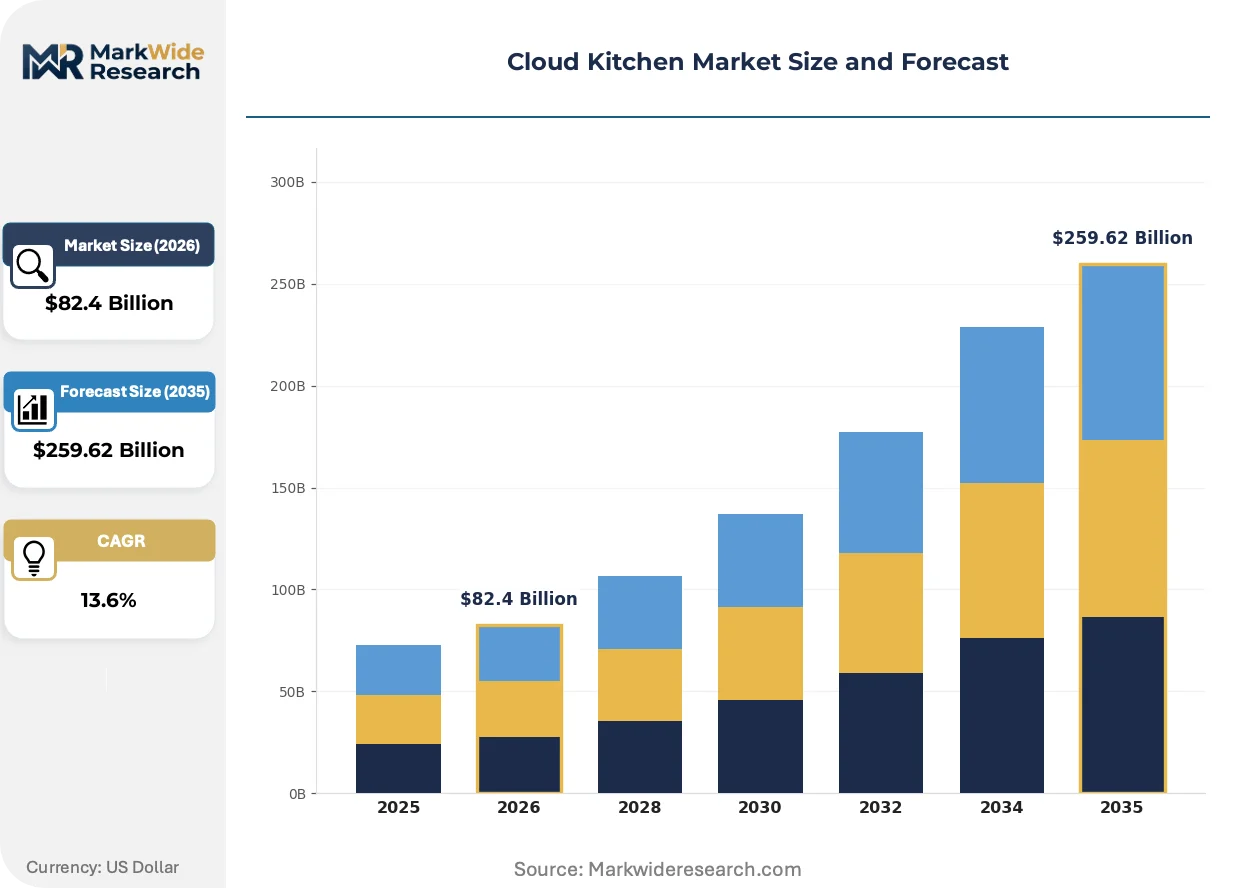
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $259.62 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Kitchen Type: Independent, Multi-Brand, Single-Brand, Commissary Service Mode: Delivery-Only, Pickup and Delivery, Catering, Subscription Meal Kits Customer Segment: Young Professionals, Families, Students, Working Executives Technology Integration: Order Management System, AI-Powered Analytics, Mobile App Ordering, Cloud POS |
| Companies Covered | Bigspoon, EatClub Brands, CloudKitchens, Franklin Junction, Zuul, Rebel Foods, Yummy Corp, The Food Lab, Kitchen United, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Kitchen Market Strategic Shifts & Innovations
Kitchen technology stacks are converging around predictive automation and modular hardware that adapts to shifting menu configurations. Three developments are restructuring competitive positioning.
Robotic cooking systems are migrating from experimental pilots to production-scale deployment. Mid-sized cloud kitchen operators in Singapore and Dubai are installing automated wok stations and fry lines to reduce labor dependency during peak hours. This technology is migrating from novelty demonstration to unit-economics necessity as wage floors rise across Asian logistics hubs.
REACH chemical safety protocols in Europe are restricting non-stick coatings and certain food-contact materials in commercial kitchen equipment. Manufacturers must reformulate surfaces and exhaust filtration to maintain CE marking eligibility. Equipment suppliers serving the EU market are accelerating R&D spend on ceramic and stainless-steel alternatives ahead of substance restriction deadlines.
Aggregator-dependent operators are diversifying toward direct-to-consumer channels and white-label delivery partnerships. Virtual brands that built exclusively on third-party platforms now face margin erosion and data opacity; subscription meal programs and proprietary apps are displacing pure-platform dependence in North American urban markets. This channel pivot is most visible among health-focused and ethnic cuisine concepts seeking customer relationship ownership.
Cloud Kitchen Market Segmentation
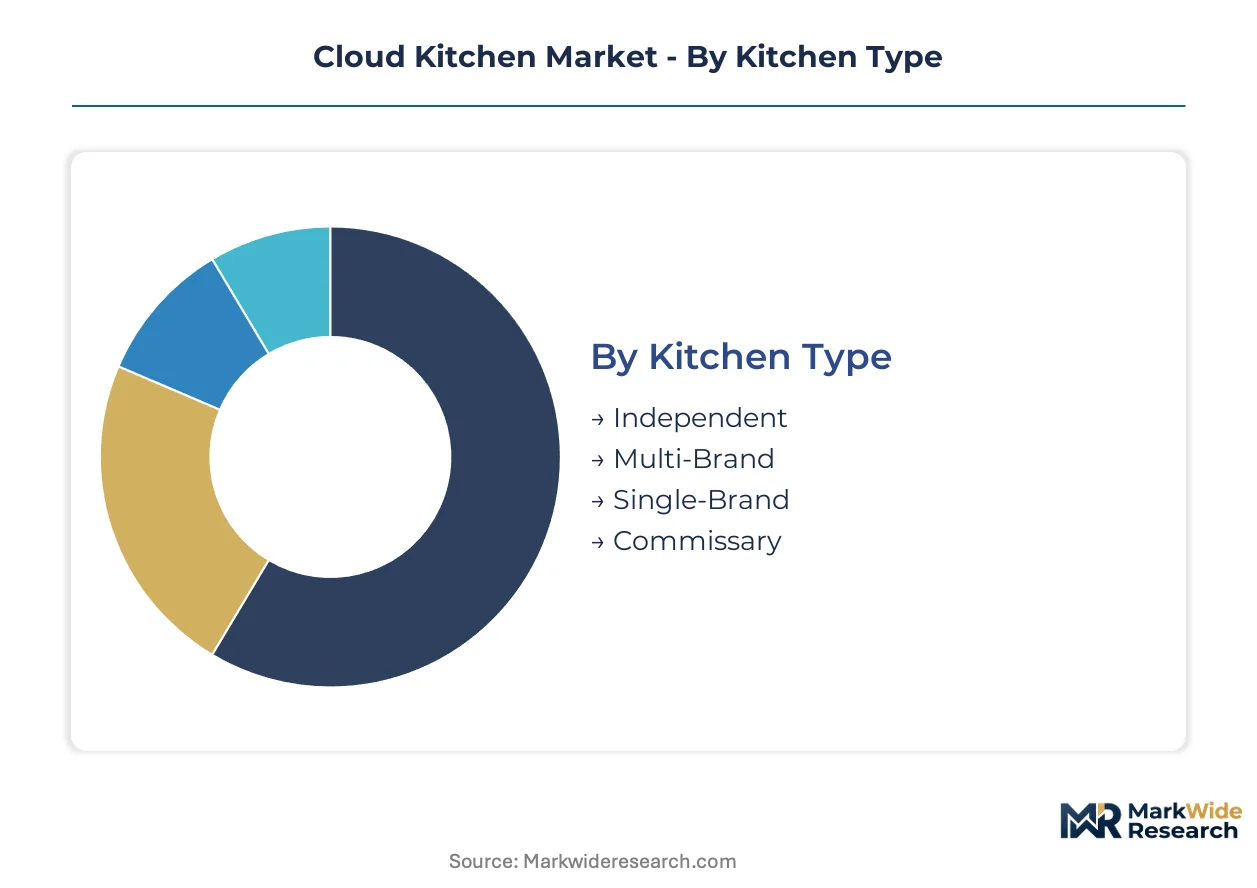
Cloud kitchen segmentation reveals how capital allocation and operational complexity vary dramatically across facility configurations and service models. Operators match kitchen type, technology stack, and customer targeting to local demand density and regulatory requirements.
Kitchen Type:
Facility ownership and brand tenancy arrangements determine capital intensity, revenue diversification, and compliance burden for operators entering specific metro corridors.
- Multi-Brand:Shared production facilities house multiple virtual restaurant concepts under one roof, maximizing equipment utilization across dayparts. Demand concentrates in Mumbai, Bangalore, and Delhi NCR where Rebel Foods and CloudKitchens anchor networks, driven by FSSAI digitization mandates requiring centralized temperature logging infrastructure.
- Independent:Standalone facilities operated by single entities without shared tenancy arrangements. These configurations dominate secondary Indian cities where multi-brand networks have not yet established presence, constrained by longer health department approval timelines.
- Single-Brand:Dedicated facilities serving one virtual restaurant concept exclusively. CloudKitchens deploys this model in North American suburban corridors for flagship concepts requiring specialized equipment.
- Commissary:Central production hubs supplying satellite finishing kitchens or external retail locations. Dark store convergence is accelerating commissary deployment as grocery operators repurpose warehouse capacity.
Multi-brand configurations command the established base. The steepest expansion runs through commissary facilities as retail-grocery convergence accelerates.
Service Mode:
Customer interface design shapes last-mile economics, labor scheduling, and real estate selection across urban and suburban deployment zones.
- Delivery-Only:Pure off-premise fulfillment with no customer-facing pickup infrastructure. Kitchen United and CloudKitchens dominate this segment in dense urban India, optimizing for aggregator platform integration and compressed delivery radius economics.
- Pickup and Delivery:Hybrid facilities combining courier handoff with direct customer collection. Kitchen United differentiates through retail-embedded hubs in US grocery-anchored centers, capturing suburban household clusters outside core delivery zones.
- Catering:Large-format production for corporate and event clients. Rebel Foods operates dedicated catering lines from select Mumbai facilities.
- Subscription Meal Kits:Pre-portioned ingredient assembly for home cooking. This mode is gaining traction among health-focused virtual brands seeking direct customer relationships.
Delivery-only operations command the established base. The steepest expansion runs through pickup-delivery hybrid models as suburban retail embedding accelerates.
Customer Segment:
Demographic targeting determines menu pricing, portion architecture, and platform marketing spend allocation.
- Young Professionals:Time-constrained urban workers aged 25-35 prioritizing convenience and variety. This segment drives order frequency in Bangalore's Whitefield and Koramangala corridors.
- Working Executives:Higher-income professionals seeking premium meal options with dietary customization. Demand concentrates in Mumbai's BKC and Delhi's Cyber Hub business districts.
- Families:Multi-person households ordering shared meals with child-friendly options. Cloud kitchens targeting this segment optimize for larger average order values and repeat subscription capture.
- Students:Price-sensitive cohorts in university-adjacent zones. Independent operators dominate this segment with economy-tier pricing.
Young professionals command the established base. The steepest expansion runs through working executives as premium virtual brands proliferate.
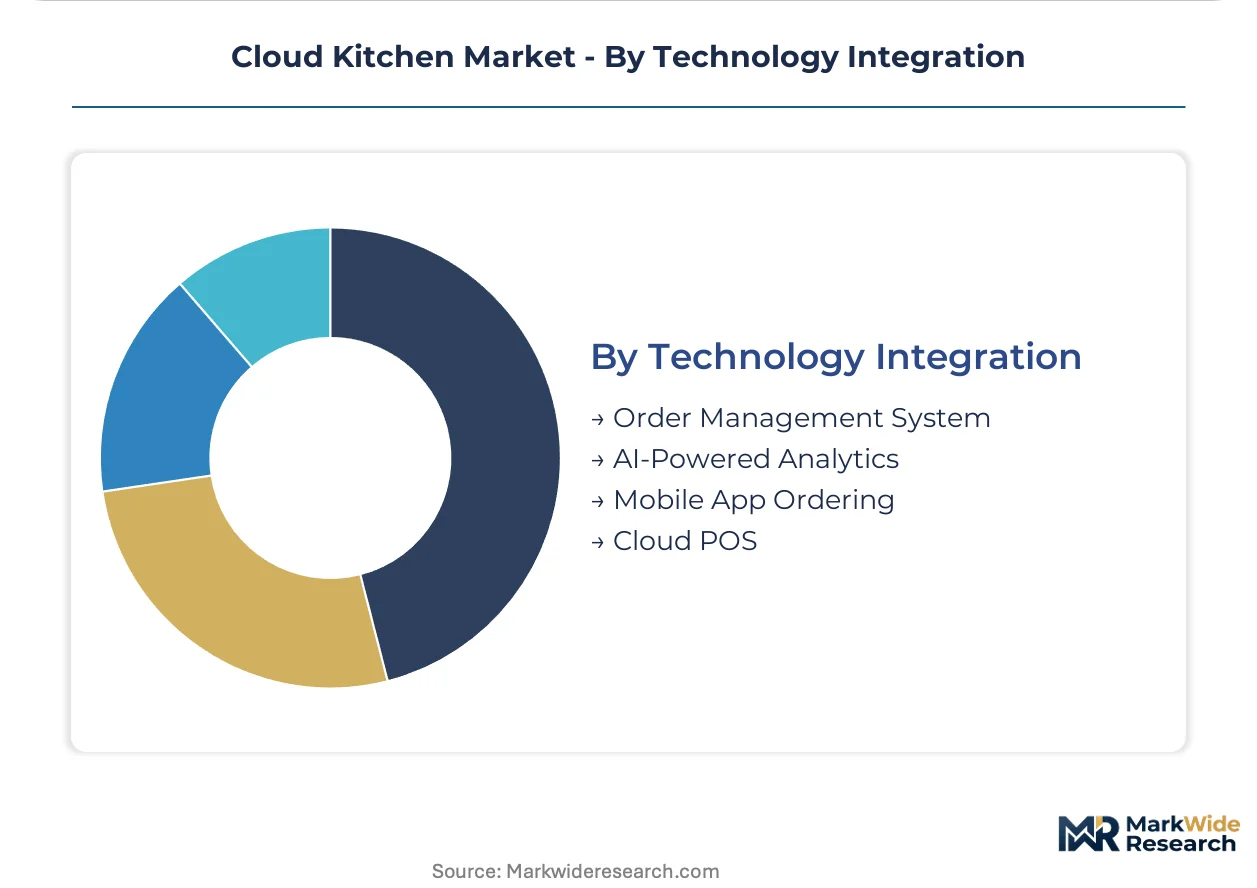
Technology Integration:
Software and automation deployment tiers separate margin-competitive operators from commodity kitchen providers.
- AI-Powered Analytics:Machine learning models predicting demand timing, menu mix, and dynamic pricing. Rebel Foods leverages proprietary algorithms across its Indian network to reduce waste and optimize labor scheduling.
- Order Management System:Centralized platforms aggregating inputs from multiple delivery aggregators and direct channels. This layer is becoming table stakes for multi-brand operators managing complexity.
- Cloud POS:Browser-based point-of-sale systems with real-time inventory synchronization. These systems enable rapid menu reconfiguration across virtual brands.
- Mobile App Ordering:Proprietary customer interfaces bypassing aggregator platforms. Operators are diversifying toward this channel to escape commission compression.
Order management systems command the established base. The steepest expansion runs through AI-powered analytics as predictive automation migrates from pilot to production scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Indian operators face acute price sensitivity among student and young professional segments, while US and European markets absorb premium positioning through working executive and family segments with higher disposable incomes and subscription meal preferences.
United States
Platform commission compression at 25-30% per order drives operator diversification toward direct-to-consumer channels. FDA digitization mandates for temperature logging and allergen traceability reshape kitchen design requirements. Kitchen United anchors hybrid pickup-delivery hubs in grocery-anchored suburban centers across California and Texas, capturing household clusters outside core urban delivery zones.
India
Urban density premiums in metropolitan corridors compress last-mile costs below suburban benchmarks, concentrating order volumes in Mumbai, Bangalore, and Delhi NCR. FSSAI digitization mandates require real-time temperature logging and allergen traceability, accelerating compliance investment in centralized kitchen infrastructure. Rebel Foods operates the largest multi-brand network across these three cities, leveraging proprietary technology to coordinate dozens of virtual brands from shared production sites.
Germany
REACH chemical safety protocols restrict non-stick coatings and certain food-contact materials in commercial kitchen equipment, forcing manufacturer reformulation. EFSA traceability standards create compliance arbitrage for operators building auditable systems ahead of enforcement deadlines. Berlin and Munich clusters see emerging deployment of modular cooking stations as dark store convergence accelerates shared food production nodes.
United Kingdom
Municipal zoning friction for ghost kitchen permits generates resistance from neighborhood associations and legacy restaurant lobbies in dense London jurisdictions. EU General Food Law alignment post-Brexit maintains stringent sanitation and traceability standards shaping operational protocols. Greater London and Birmingham corridors concentrate delivery-only infrastructure optimized for aggregator platform integration.
Singapore
Robotic cooking systems migrate from experimental pilots to production-scale deployment as wage floors rise across Asian logistics hubs. The national food regulator imposes strict hygiene and traceability standards for centralized food production facilities. Mid-sized operators install automated wok stations and fry lines to reduce labor dependency during peak hours in the city-state's dense urban core.
Cloud Kitchen Market Key Industry Players
Platform-dependent aggregators and asset-light kitchen infrastructure providers split the market between customer acquisition leverage and operational control. The vendor base concentrates around three strategic archetypes: multi-brand network operators maximizing equipment utilization across virtual concepts, hybrid pickup-delivery hub developers embedding in retail developments, and technology-integrated specialists deploying AI-powered demand forecasting. Dominant competitive moves include aggressive geographic expansion into secondary metro corridors and backward integration into proprietary delivery logistics to escape platform commission compression.
Within the multi-brand network tier, Rebel Foods and CloudKitchens exemplify contrasting geographic strategies. Rebel Foods anchors Indian metropolitan dominance through Mumbai, Bangalore, and Delhi NCR production clusters. CloudKitchens sustains North American and European metro corridor expansion through flexible lease terms and centralized logistics infrastructure. Kitchen United occupies a distinct position in the hybrid hub segment, competing for landlord partnerships in high-traffic suburban retail zones across the United States.
| Leading Market Players |
|---|
| Bigspoon |
| EatClub Brands |
| CloudKitchens |
| Franklin Junction |
| Zuul |
| Rebel Foods |
| Yummy Corp |
| The Food Lab |
| Kitchen United |
| Others |
Cost & Logistics Intelligence
Commodity volatility in steel and copper cooking equipment components determines both tiered pricing spreads across kitchen configurations and the geographic shape of equipment sourcing networks. Operators face compressed margins when input cost spikes coincide with aggregator commission pressure, forcing supply chain restructuring toward modular, replaceable hardware systems.
Pricing Analysis
After-sales service contracts and equipment maintenance subscriptions now drive lifetime value more than initial kitchen buildout costs. Three-tier pricing structure across premium, standard, and economy levels separates AI-integrated facilities from basic modular setups from bare-bones independent kitchens. Cost compression in the economy tier is intensifying because single-brand operators cannot absorb platform take rates above 25%. Young professionals and student segments exhibit acute price sensitivity, while working executives and corporate catering clients absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Export-control restrictions on advanced robotics and automated cooking systems limit technology flows into certain jurisdictions, forcing regional equipment sourcing patterns. Commercial kitchen equipment manufacturing concentrates in China, Germany, and Italy, with cold-chain refrigeration components drawing from South Korean and Japanese suppliers. Supply chains rest on stainless steel sheet, copper tubing, and semiconductor-based control systems as critical inputs. Single-source vulnerability runs through precision temperature control modules. Distribution runs through specialized foodservice equipment distributors and direct manufacturer relationships with large multi-brand network operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud kitchen infrastructure sits at an early-cycle expansion story where delivery-first adoption in secondary metro corridors and suburban retail zones provides substantial runway. FSSAI digitization mandates and equivalent food safety traceability requirements in North America and Europe accelerate compliant facility deployment.
For Market Incumbents: Pre-empt platform commission compression by accelerating proprietary direct-to-consumer channel development and subscription meal program infrastructure. Incumbents should consolidate landlord partnership positions in grocery-anchored suburban retail developments before competitors capture hybrid pickup-delivery hub locations. Vertical integration into last-mile logistics capabilities provides margin defense against aggregator dependency.
For New Entrants and Emerging Players: Secondary Indian cities and North American suburban corridors outside core urban delivery zones represent the most penetrable white-space opportunities. New entrants should target independent kitchen configurations in university-adjacent zones and emerging business districts where multi-brand networks have not established presence. A franchise-operated model with centralized technology licensing offers the strongest go-to-market angle for capital-constrained entrants.
For Investors and Strategic Acquirers: The market sits at a growth-phase inflection that favors technology-integrated operators with proprietary demand forecasting capabilities over pure real estate plays. Long-term viability over a multi-year horizon centers on AI-powered analytics deployment and direct customer relationship ownership rather than platform-dependent volume. Acquisition targets should demonstrate operational technology differentiation and multi-brand coordination capability. The signal to watch is aggregator commission rate negotiations and municipal zoning reform momentum as indicators of structural margin pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Technology Platform Development | Rebel Foods' AI-powered demand forecasting reduces waste and optimizes labor scheduling across shared production sites. |
| Suburban Retail Embedding Partnerships | Kitchen United's hybrid hub model captures household clusters in grocery-anchored centers outside core urban zones. |
| Direct-to-Consumer Channel Diversification | Virtual brands bypassing aggregator platforms escape 25-30% commission compression and capture customer data ownership. |
| Regulatory Compliance Infrastructure Investment | FDA and FSSAI digitization mandates require auditable temperature logging systems that reshape facility design requirements. |
| Robotic Cooking System Deployment | Automated wok stations and fry lines in Singapore and Dubai reduce labor dependency as wage floors rise across Asian logistics hubs. |
Research Approach
Two parallel data streams informed the analysis: primary intelligence gathering and secondary source validation. Primary interviews engaged cloud kitchen operators, foodservice equipment manufacturers, real estate developers specializing in retail-anchored properties, and regulatory compliance officers at FSSAI and FDA. Secondary sources included food safety regulatory filings, commercial kitchen equipment trade data, delivery platform commission structure disclosures, and municipal zoning records for ghost kitchen permits. Bottom-up facility deployment counts triangulated against top-down market sizing from aggregator order volume data.
Forecast inputs considered kitchen type segmentation, service mode configuration, technology integration tier, and customer demographic targeting across the projection horizon. Modeled dimensions spanned multi-brand versus independent versus commissary facility ownership, delivery-only versus hybrid pickup-delivery interface design, and AI-powered analytics penetration versus basic order management system deployment. CAGRs derived from historical facility buildout trajectories, order volume growth curves, and capital deployment patterns reported by leading operators. Industry-specific inputs incorporated FSSAI compliance timeline acceleration and REACH chemical safety protocol implementation schedules.
Practitioners should monitor municipal zoning reform momentum, aggregator commission rate negotiations, and commodity price volatility in steel and copper for early signals of forecast deviation. Forecasts reflect assumptions about continued urban density premiums in metropolitan India and sustained platform dependence among single-brand operators. Material shifts in food safety regulatory enforcement intensity or delivery platform market consolidation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
United States Online Food Delivery Market
Food Service
Beverage Napkins Market
Food Service
Cutting Boards Market
Food Service
China Retail Bubble Tea Kits Market
Food Service
Commercial Pizza Oven Market
Food Service
Stirrers Market
Food Service
Restaurants in Belgium Market
Food Service
Gourmet Street Food Market
Food Service
India Inflight Catering Market
Food Service
Nigeria Food Service Market
Food Service
Netherlands Food Service Market
Food Service
Popcorn Making Cart Market
Food Service
Shaker Bottles Market
Food Service
Air Fryer Meal Kits Market
Food Service
Hyperlocal Grocery Delivery Market
Food Service
US Food Service Market