
 United Kingdom Snack Bar Market | 2026-2036
United Kingdom Snack Bar Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Snack Bar Market Analytics
Food technologist talent is rotating toward plant-based protein formulation, tightening availability for conventional cereal bar development. Kind Snacks leverages its nut-dominant portfolio to anchor premium positioning in the UK free-from aisle. Mondelēz International sustains mass-market penetration through its established convenience store and supermarket relationships. Nakd competes on minimal ingredient lists, occupying the raw and cold-pressed niche that appeals to clean-label shoppers.
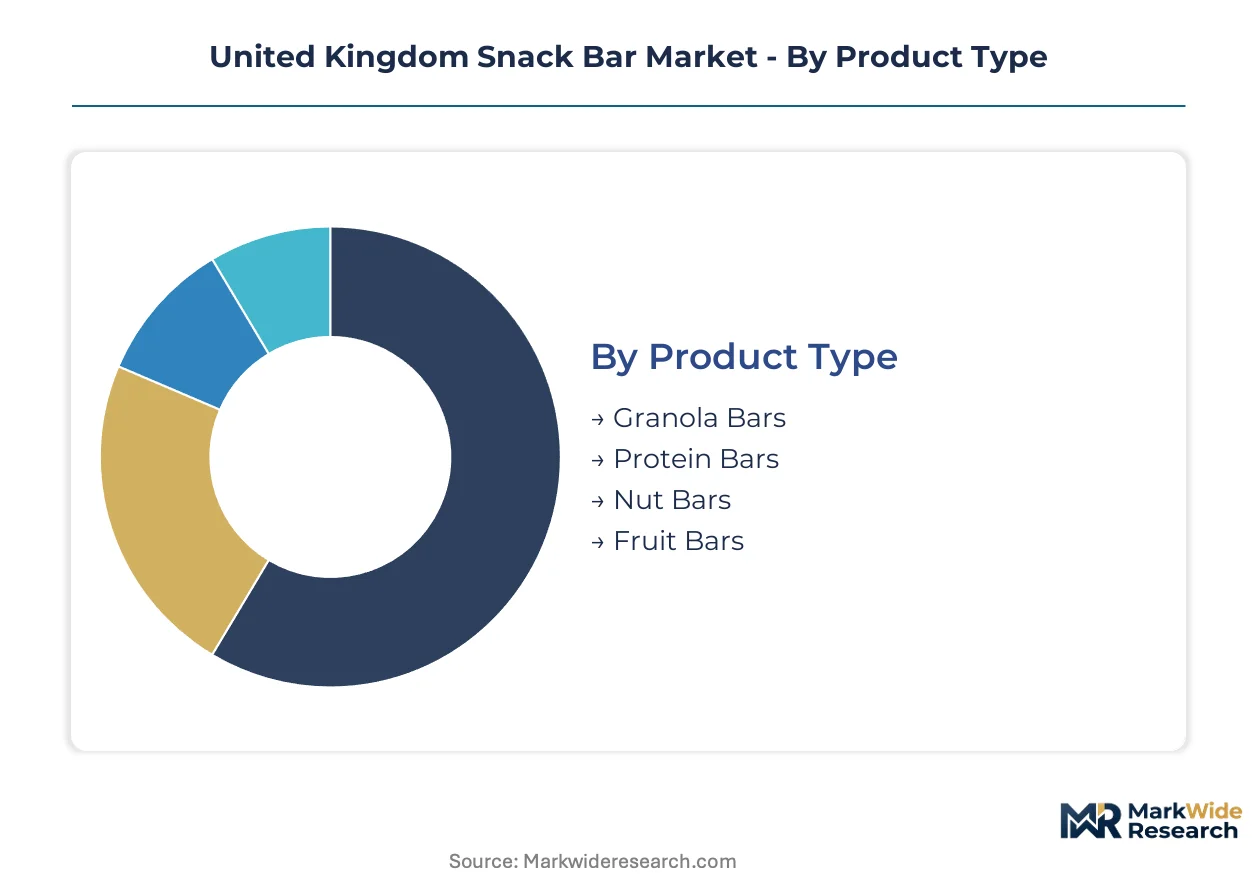
A snack bar denotes a compact, shelf-stable food item typically comprising cereals, nuts, dried fruits, protein isolates, or confectionery binders, extruded or cold-pressed into a handheld format with a moisture content below 15% to ensure ambient stability, designed for on-the-go consumption as a meal supplement or energy source. Protein bars lead value contribution due to higher per-unit pricing and gym-channel placement, while fruit bars remain the most mature segment with slower incremental growth. Granola bars dominate volume through family-pack formats in supermarket multiples, though single-serve protein bars capture disproportionate margin in health food shops and online retail.
The Food Standards Agency enforces strict nutritional claim thresholds that shape permissible front-of-pack messaging, while Advertising Standards Authority rules restrict child-targeted promotions for high-fat-salt-sugar products. UK Plastic Packaging Tax incentives are accelerating shifts toward recyclable or compostable flexible films across the supplier base. Stakeholders must monitor evolving HFSS display regulations and decide whether to reformulate core lines or redirect innovation spend toward exempt product architectures.
Market Dynamics
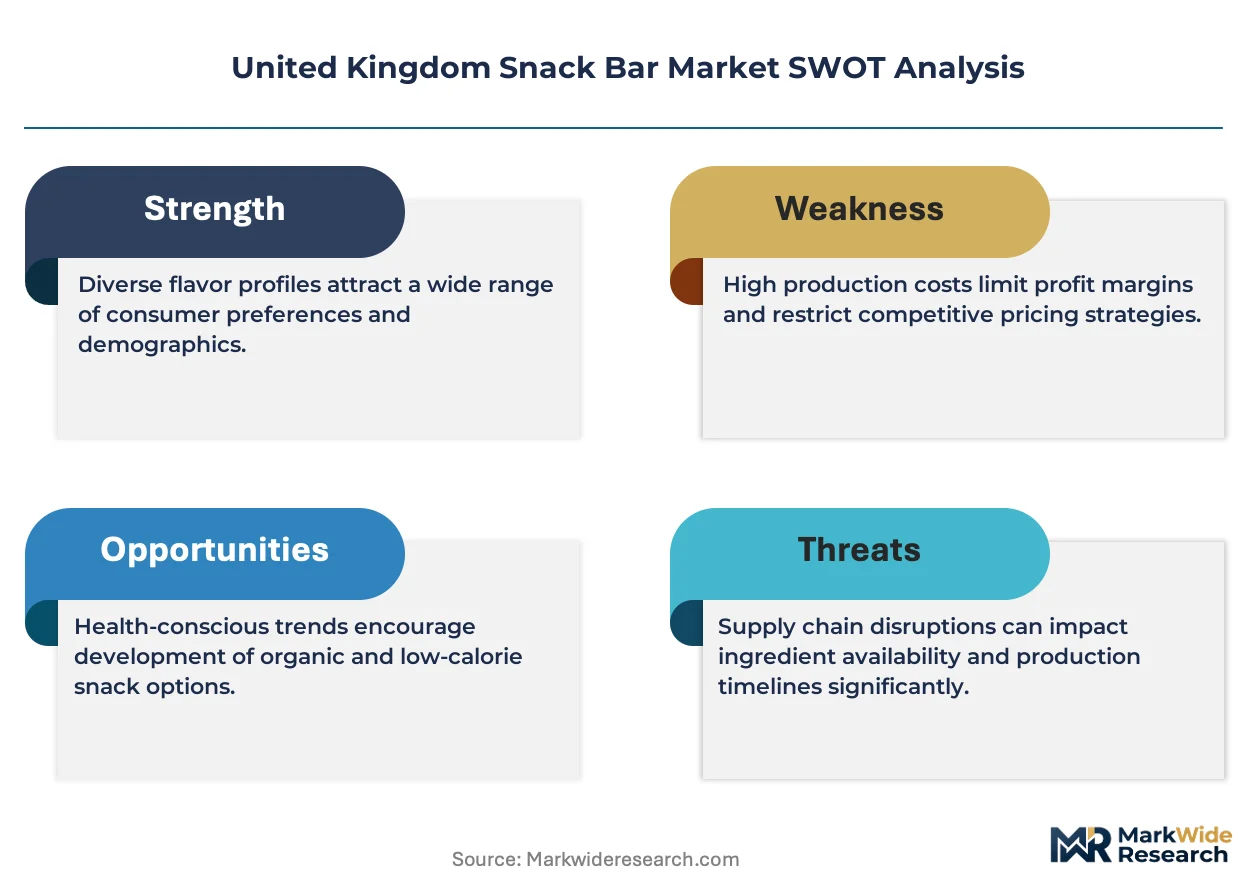
The UK Snack Bar Market is undergoing structural recalibration as the Food Standards Agency tightens enforcement of HFSS display regulations, forcing manufacturers to choose between expensive reformulation or channel redistribution toward exempt retail formats.
Growth Catalysts
- Clean-label protein innovation:Food technologists in Manchester and Bristol are developing cold-pressed formats using pea and fava isolates that meet the FSA's evolving nutritional claim thresholds without synthetic binders.
- Meal replacement convenience:Busy professionals across England's metropolitan corridors are substituting sit-down meals with shelf-stable bars, concentrating demand in London's financial districts and Manchester's media hubs.
- Plastic Packaging Tax incentives:The HM Treasury levy on virgin plastic is accelerating supplier migration toward compostable flexible films and paper-based barrier structures.
Market Restraints
- Protein input cost volatility:Global pea protein concentrate prices fluctuate with Canadian and Ukrainian harvest cycles, compressing margin on plant-based formulations.
- Regulatory friction:The Advertising Standards Authority's restrictions on child-targeted promotions for high-fat-salt-sugar products block legacy cereal bar brands from mainstream media channels.
- Substitution threat:Fresh prepared snacking from urban dark kitchens and refrigerated protein pots captures younger urban consumers seeking perceived freshness over ambient stability.
Strategic Opportunities
- Scotland and Northern England underpenetration:Health food shop density in Glasgow, Edinburgh, and Leeds remains below London levels, presenting whitespace for premium single-serve formats.
- Gym-channel expansion:Boutique fitness studios in Birmingham and Bristol are installing automated vending for post-workout protein bars, bypassing traditional retail markup structures.
- FSA exempt product architectures:Reformulating core lines to fall below HFSS nutrient profiling thresholds unlocks end-cap placement in supermarkets and impulse locations near checkout.
Industry Challenges
- Food technologist scarcity:Talent rotation toward plant-based protein formulation has tightened availability for conventional cereal bar development, extending NPD timelines.
- Certification timeline compression:Clean-label and organic accreditations from Soil Association and BRC require 12-18 month validation cycles that delay seasonal product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Snack Bar Market |
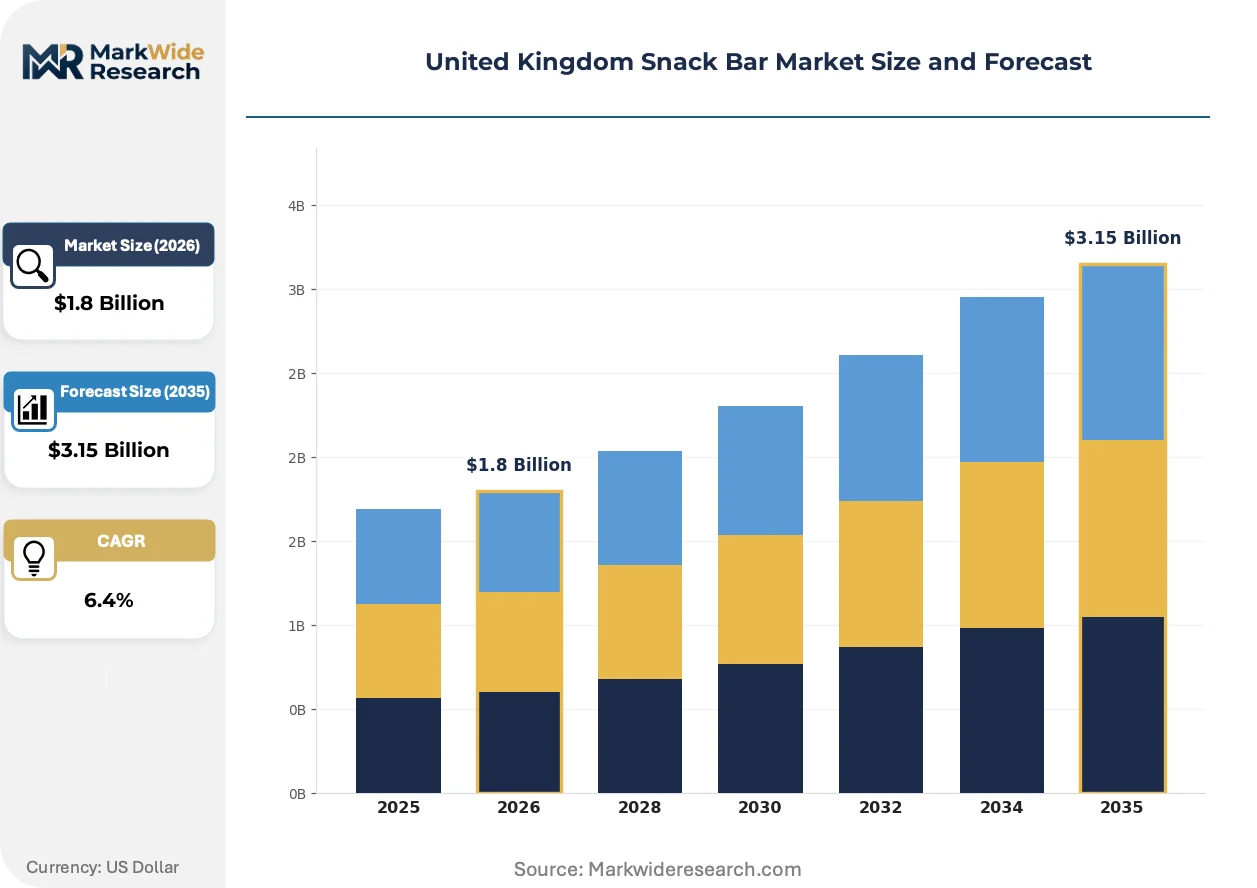
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola Bars, Protein Bars, Nut Bars, Fruit Bars Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Shops Customer Type: Health-conscious Consumers, Athletes, Busy Professionals, Students Packaging Type: Single-serve Packs, Family Packs, Bulk Packaging, Resealable Bags |
| Companies Covered | Graze (Thrive Snacks), Kind Snacks, Nakd (Natural Balance Foods), Trek Protein, Nature Valley (General Mills), Mondelēz International, Kellanov, Nestlé UK, PepsiCo UK, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Snack Bar Market Evolving Landscape
Reformulation pressures and channel fragmentation are reshaping how UK snack bar manufacturers allocate R&D spend and route products to market.
Cold-pressed bar technology is fragmenting the traditional extrusion-dominated manufacturing base. Small-batch producers in Brighton and Hackney are adopting low-temperature forming equipment that preserves heat-sensitive bioactive compounds in nut and seed matrices. Boutique brands serving the free-from aisle are capturing shelf space from multinational extruded lines by positioning minimal-processing credentials.
The UK Plastic Packaging Tax is accelerating migration toward mono-material flexible films and paper-based barrier laminates. Suppliers must validate new structures against 12-month shelf-life requirements for ambient distribution. Granola and fruit bar segments with lower moisture sensitivity are adapting faster than high-protein formats requiring oxygen barriers.
Urban professionals are compressing their snacking procurement cycles toward subscription replenishment and locker-based pickup points. Direct-to-consumer platforms in London and Manchester are displacing routine supermarket trips for core users. This channel shift concentrates lifetime value capture with brands owning customer data rather than retail intermediaries.
United Kingdom Snack Bar Market Segmentation
Snack bar manufacturers in the United Kingdom navigate divergent margin profiles and regulatory exposure across product architectures. Segmentation discipline determines where reformulation investments yield HFSS exemption and which channels escape display restrictions.
Product Type:
Protein bars face the most acute substitution pressure from fresh refrigerated alternatives in London's dark kitchen networks, while ambient fruit bars compete directly with whole fruit convenience pricing.
- Protein Bars:Formulations combine whey, pea, or fava isolates with binders to achieve 15-20g protein per 60g serving. Demand concentrates in Manchester's boutique fitness studios and Birmingham gym vending networks, where post-workout consumption drives premium single-serve purchases.
- Granola Bars:Baked oat matrices with honey or syrup binders dominate family-pack formats in Tesco and Sainsbury's multiples. England's suburban households sustain volume through breakfast replacement routines, though HFSS thresholds threaten end-cap placement for sugar-dense legacy recipes.
- Nut Bars:Almond and cashew-dominant formulations occupy the free-from aisle with minimal ingredient positioning. Bristol and Brighton clean-label shoppers drive trial through health food shop channels.
- Fruit Bars:Cold-pressed or extruded date and dried fruit matrices serve the raw snacking niche. Scottish metropolitan corridors show underpenetration relative to London baseline.
Granola bars retain volume leadership; protein bars hold the steepest expansion curve.
Distribution Channel:
Channel selection determines regulatory exposure, with supermarket multiples facing the strictest HFSS display enforcement while health food shops operate outside promotional restrictions.
- Supermarkets:Tesco, Sainsbury's, and Asda control mass-market throughput via central aisle and checkout placement. Reformulation to exempt status unlocks prime positioning for brands willing to absorb R&D costs.
- Online Retail:Direct-to-consumer platforms in London and Manchester bypass retail markup through subscription replenishment models. Data ownership enables lifetime value capture from busy professional cohorts.
- Convenience Stores:Impulse-oriented formats in transport hubs and petrol forecourts favor single-serve protein and nut bars. Shelf-space constraints disadvantage family-pack architectures.
- Health Food Shops:Holland & Barrett and independent Bristol retailers stock premium clean-label and organic certified lines. Soil Association accreditation serves as table stakes for shelf placement.
Supermarkets retain volume leadership; online retail holds the steepest expansion curve.
Customer Type:
Professional schedules and fitness routines segment demand intensity, with meal replacement behavior concentrating in England's financial districts while athletic consumption clusters around gym infrastructure.
- Busy Professionals:London's financial and Manchester's media sector workers compress procurement into subscription and locker-based pickup patterns. Shelf-stable convenience overrides freshness preferences for this cohort.
- Athletes:Post-workout protein consumption in Birmingham and Bristol boutique studios drives automated vending placement. Timing-sensitive demand favors ambient formats over refrigerated alternatives.
- Health-conscious Consumers:Clean-label scrutiny in Brighton and Hackney pushes ingredient list minimalism. Cold-pressed and raw positioning resonates with this segment's processing aversion.
- Students:Price-sensitive purchasing in university towns favors value-tier granola and fruit bar multipacks. Bulk formats align with constrained budgets and shared accommodation storage.
Busy professionals retain volume leadership; athletes hold the steepest expansion curve.
Packaging Type:
The UK Plastic Packaging Tax has reconfigured supplier economics, with mono-material films gaining cost advantage over multi-layer barrier structures that incur virgin plastic levies.
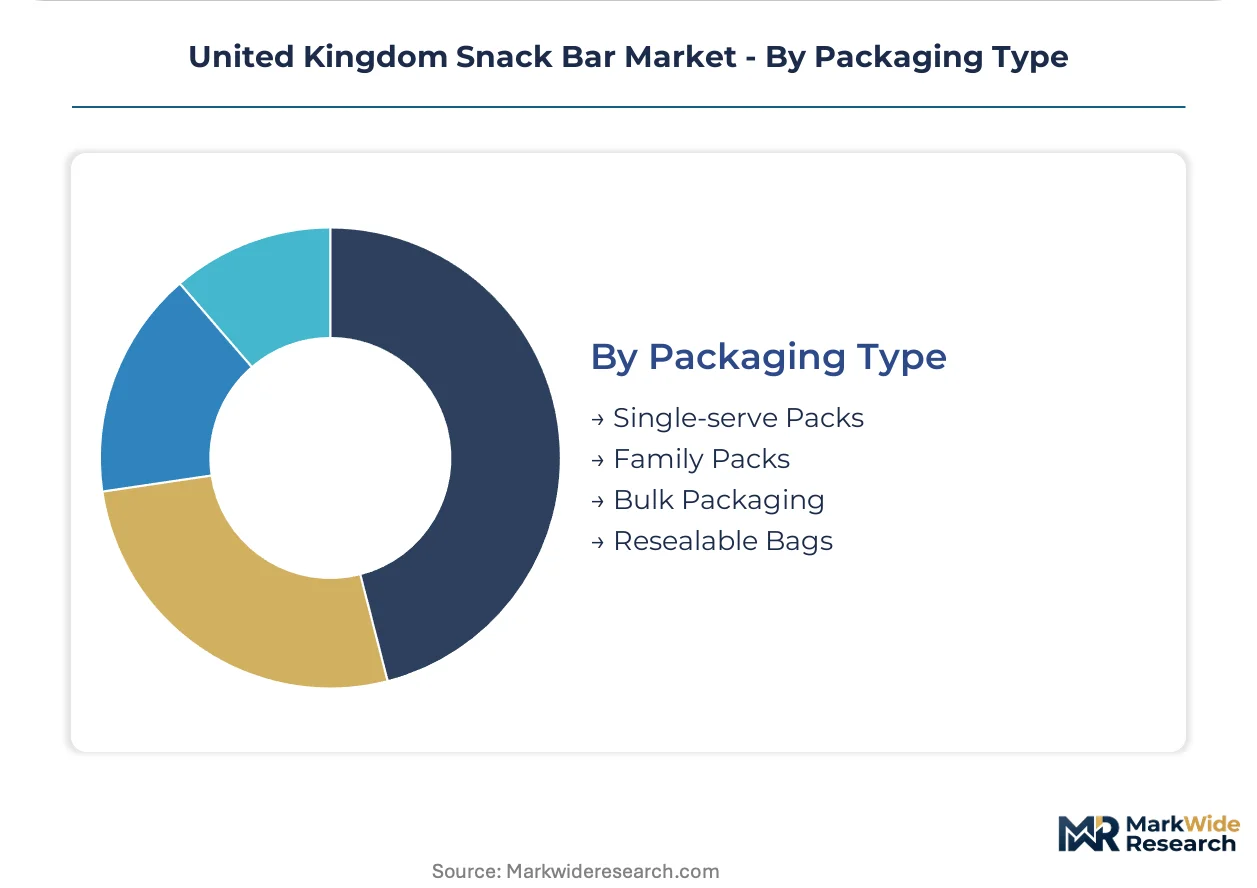
- Single-serve Packs:Individual wrappers dominate gym vending and convenience impulse channels. Oxygen barrier requirements for protein bars complicate compostable film migration versus granola and fruit alternatives.
- Family Packs:Multi-bar cartons serve suburban household replenishment through supermarket multiples. Secondary cardboard outer structures ease compliance with recyclable packaging mandates.
- Bulk Packaging:Foodservice and office pantry formats in London corporate towers reduce per-unit cost for high-volume procurement. Shelf-life validation extends to 18 months for ambient distribution.
- Resealable Bags:Zip-lock flexible films target health-conscious consumers seeking portion control. Paper-based barrier laminates are gaining share in Brighton and Hackney independent retail.
Family packs retain volume leadership; single-serve packs hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Food Standards Agency shapes formulation standards across England while devolved administrations in Scotland, Wales, and Northern Ireland apply localized enforcement of nutritional regulations.
London and the Southeast
Financial district professionals drive meal replacement demand through subscription platforms and locker-based pickup networks. The FSA's HFSS display restrictions force reformulation toward exempt nutrient profiles to secure supermarket end-cap placement. Clean-label startups cluster in Hackney and Brighton, developing cold-pressed formats for health food shop distribution.
Midlands
Birmingham's boutique fitness studios anchor automated vending networks for post-workout protein consumption. The Plastic Packaging Tax accelerates supplier migration toward mono-material films for granola and fruit bar formats. Manufacturing facilities in Nottingham and Leicester serve supermarket multiples with family-pack architectures.
North England
Manchester's media sector sustains busy professional demand for convenient shelf-stable nutrition. Health food shop density in Leeds remains below London baseline, presenting whitespace for premium single-serve expansion. Liverpool convenience stores favor impulse-oriented nut bar formats in transport hub locations.
Scotland
Glasgow and Edinburgh show underpenetration in protein bar distribution relative to English metropolitan corridors. Scottish Government procurement guidelines favor recyclable packaging for public sector catering contracts. Cold-pressed fruit bar adoption concentrates in Edinburgh's independent retail sector.
Wales and Northern Ireland
Cardiff's urban professionals mirror English snacking patterns with compressed procurement cycles. Northern Ireland's cross-border retail integration exposes manufacturers to dual jurisdiction compliance under UK and Irish nutritional frameworks. Belfast convenience channels favor value-tier granola multipacks for student demographics.
United Kingdom Snack Bar Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the UK snack bar market. Multinational confectionery conglomerates leverage established supermarket relationships and centralized manufacturing for mass-market penetration, while boutique cold-pressed specialists capture premium positioning through minimal processing credentials. Three archetypes dominate: multinational scale players with reformulation capabilities, plant-based protein innovators with clean-label positioning, and raw format specialists occupying the free-from aisle. Competitive moves concentrate on portfolio diversification toward exempt HFSS architectures and channel expansion into gym vending networks bypassing traditional retail markups.
Among UK-based and multinational operators, Kind Snacks, Nakd, and Mondelēz International exemplify contrasting strategic positions. Kind Snacks occupies the premium nut-dominant tier with minimal ingredient positioning in health food channels. Nakd anchors the raw and cold-pressed niche through Natural Balance Foods' distribution infrastructure. Mondelēz International represents scale-driven mass-market penetration through established convenience store and supermarket relationships.
| Leading Market Players |
|---|
| Graze (Thrive Snacks) |
| Kind Snacks |
| Nakd (Natural Balance Foods) |
| Trek Protein |
| Nature Valley (General Mills) |
| Mondelēz International |
| Kellanov |
| Nestlé UK |
| PepsiCo UK |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between pea protein concentrate suppliers and UK snack bar manufacturers lock in both supply access and price visibility across the forecast horizon, insulating formulation costs from Canadian and Ukrainian harvest volatility while committing buyers to minimum volume thresholds. These contracts concentrate purchasing power among scaled operators, squeezing boutique cold-pressed brands into spot-market exposure for fava and rice protein isolates.
Pricing Analysis
London health food shops command 15-25% premiums over Manchester supermarket multiples for identical clean-label SKUs, reflecting differential rent structures and shopper willingness-to-pay for Soil Association accreditation. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified nut bars in Brighton independents from value-tier granola multipacks in Tesco family formats, with certification grade and volume scale as the primary differentiation drivers. Cost compression in the standard tier is intensifying because Ukrainian sunflower protein supply disruptions have forced reformulation toward costlier fava isolates. Students in university towns exhibit highest price sensitivity, while busy professionals in London's financial districts show least sensitivity due to meal replacement convenience premiums.
Supply Chain Analysis
Inventory cycles for ambient-stable snack bars run 8-12 weeks from raw material procurement to finished goods dispatch, compressing further for cold-pressed formats with shorter best-before windows. Pea protein concentrate supply concentrates in Canada, Ukraine, and China, while flexible film packaging draws from German and Italian converter networks. Single-source vulnerability in Canadian pea protein extraction capacity threatens margin stability for plant-based formulations. Distribution runs through supermarket central distribution centres for mass-market penetration, with direct-to-consumer platforms bypassing retail markup for subscription-heavy professional cohorts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK Snack Bar Market is experiencing high-growth disruption as the Food Standards Agency's HFSS display regulations force immediate portfolio recalibration toward exempt nutrient architectures. This regulatory inflection compresses competitive advantage toward brands with existing clean-label R&D infrastructure and Soil Association certification pipelines.
For Market Incumbents: Compound defensive positioning through backward integration into pea protein toll processing in East Anglia, securing captive supply against Canadian harvest volatility. Accelerate reformulation of legacy cereal bar lines to fall below HFSS nutrient profiling thresholds, unlocking end-cap placement in Sainsbury's and Tesco multiples. Channel control through automated vending networks in Birmingham and Manchester boutique fitness studios bypasses retail markup compression from supermarket own-label expansion. For New Entrants and Emerging Players: Soil Association organic certification fast-track through Bristol and Brighton independent retail channels opens immediate shelf access before scaled competitors complete 18-month validation cycles. Scotland's underpenetrated protein bar distribution in Glasgow and Edinburgh presents whitespace for premium single-serve formats. Direct-to-consumer subscription models targeting London financial district professionals capture lifetime value through data ownership rather than retail intermediation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer platforms with subscription replenishment infrastructure in Manchester and London. Over the medium-term horizon, acquisition targets should demonstrate validated cold-pressed manufacturing capabilities and existing Soil Association accreditations. The signal to watch is FSA enforcement intensity on HFSS display restrictions, which would accelerate consolidation toward exempt-architecture portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Reformulation to HFSS-Exempt Architectures | Unlocks prime supermarket end-cap placement under FSA display regulations. |
| Backward Integration into Pea Protein Processing | Secures captive supply against Canadian and Ukrainian harvest volatility. |
| Gym-Channel Vending Network Expansion | Bypasses traditional retail markup structures in Birmingham boutique studios. |
| Soil Association Certification Investment | Establishes table stakes for health food shop distribution in Brighton and Hackney. |
| Direct-to-Consumer Platform Launch | Captures lifetime value through subscription data ownership in London corridors. |
Research Methodology
A standing panel of food technologists, supermarket category buyers, health food shop proprietors, and gym chain procurement managers provided ongoing calibration against shifting formulation standards and channel economics. Primary interviews with these stakeholders combined with secondary validation from FSA regulatory filings, Nielsen retail audit data, Soil Association certification databases, and HM Treasury Plastic Packaging Tax implementation records. Bottom-up volume builds across product type and distribution channel segments triangulated against top-down market sizing from trade association statistics.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation models incorporating product architecture, distribution channel, customer type, and regional regulatory cluster dimensions. CAGRs were derived from trend extrapolation adjusted for identified inflection points including HFSS enforcement timelines and packaging tax phase-ins. Industry-specific forecast inputs included pea protein concentrate price indices and health food shop density metrics by metropolitan area.
The analysis sits within stated boundaries; outcomes outside sustained FSA enforcement intensity or accelerated plant-protein cost declines would require recalibration. Forecasts reflect documented assumptions regarding regulatory trajectory and input cost stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Argentina Snack Bar Market
Snacks
Sweet Potato Chips Market
Snacks
Middle East and Africa Frozen Snacks Market
Snacks
Low Calorie Snack Foods Market
Snacks
Dairy Protein Crisps Market
Snacks
Asia-Pacific Snack Bar Market
Snacks
China Snack Bar Market
Snacks
Extruded Snacks Market
Snacks
Granola Market
Snacks
Savoury Biscuits Market
Snacks
Sweet Potato Fries Market
Snacks
No Fat Snacks Market
Snacks
North America Energy Bar Market
Snacks
Germany Energy Bar Market
Snacks
Roasted Snacks Market
Snacks
Low Calorie Biscuits Market