
 Europe Barbeque Grill Market | 2026-2036
Europe Barbeque Grill Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Barbeque Grill Market Insights
Premium-grade stainless steel construction is reorganizing competitive dynamics across the Europe barbeque grill landscape. Weber Inc. leverages its R&D intensity to dominate high-end gas grill categories. Napoleon anchors its position through manufacturing scale across North American and European production footprints. Landmann competes aggressively in the mid-range charcoal segment through specialized German engineering heritage.
Europe barbeque grills encompass fuel-fired or electrically heated cooking appliances designed for outdoor food preparation, typically constructed from grade 304 or 430 stainless steel with porcelain-enameled cast iron grates and BTU outputs ranging from 8,000 to 20,000 per burner. These units serve residential entertaining, commercial hospitality, and institutional catering applications requiring controlled high-temperature searing and indirect roasting capabilities. Gas grills occupy the largest value pool due to convenience-driven residential demand, while portable grills represent the fastest-expanding category as apartment dwellers and caravan owners seek compact solutions. Electric grills capture growing share in urban markets where open-flame restrictions limit combustion alternatives, with margin concentration strongest in premium and luxury price tiers where ceramic infrared burners and smart temperature controls differentiate offerings.
CE marking under the EU Gas Appliances Regulation and Ecodesign Directive framework governs product compliance, while REACH restricts hazardous substances in coatings and surface treatments. Germany's Federal Institute for Materials Research sets supplementary durability benchmarks that shape manufacturer quality investments. Stakeholders must monitor evolving carbon-border adjustment mechanisms and potential F-Gas Regulation extensions that could alter propane and natural gas grill economics.
Market Dynamics
The EU Ecodesign Directive is compressing margins across gas-fired grill portfolios while simultaneously accelerating R&D spending on ceramic infrared burner architectures. Manufacturers face simultaneous pressure from efficiency mandates and consumer preference for high-BTU searing performance.
Growth Catalysts
- CE marking expansion:The EU Gas Appliances Regulation is harmonizing safety standards across member states, reducing cross-border certification friction for German and Italian manufacturers exporting to Portugal and Spain.
- Covered terrace hospitality:Outdoor dining venues across Bavaria and Baden-Württemberg are installing permanent built-in grill stations, creating commercial-grade replacement cycles independent of residential weather sensitivity.
- Caravan and camping infrastructure:Portable grill demand is concentrating in coastal Portugal where seasonal tourism drives compact appliance turnover every 24-36 months.
Market Restraints
- Grade 304 stainless input costs:Nickel price volatility from Indonesian supply concentration is squeezing margin on premium construction tiers.
- F-Gas Regulation extension risk:Propane grill economics face structural uncertainty as Brussels evaluates refrigerant-phase-down precedents for liquefied petroleum gas appliances.
- Apartment fire-code restrictions:Open-flame prohibitions in Paris and Barcelona high-density housing limit addressable market for combustion-based units.
Strategic Opportunities
- Electric grill white space:Madrid and Milan urban cores present underpenetrated demand for balcony-compliant infrared electric units with 2,000-watt outputs.
- CSRD-aligned circular design:The EU Corporate Sustainability Reporting Directive creates procurement preference for manufacturers offering take-back programs and modular component replacement.
- Smart temperature control convergence:Bluetooth-enabled probe systems integrated with ceramic burner management are opening premium price tiers previously captured by indoor appliance brands.
Industry Challenges
- REACH compliance timeline compression:Coating reformulation for porcelain-enameled grates requires 18-24 month certification cycles that delay product launches.
- Cross-border spare parts logistics:Post-Brexit customs documentation is fragmenting pan-European after-sales service networks for UK-origin manufacturers serving continental markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Barbeque Grill Market |
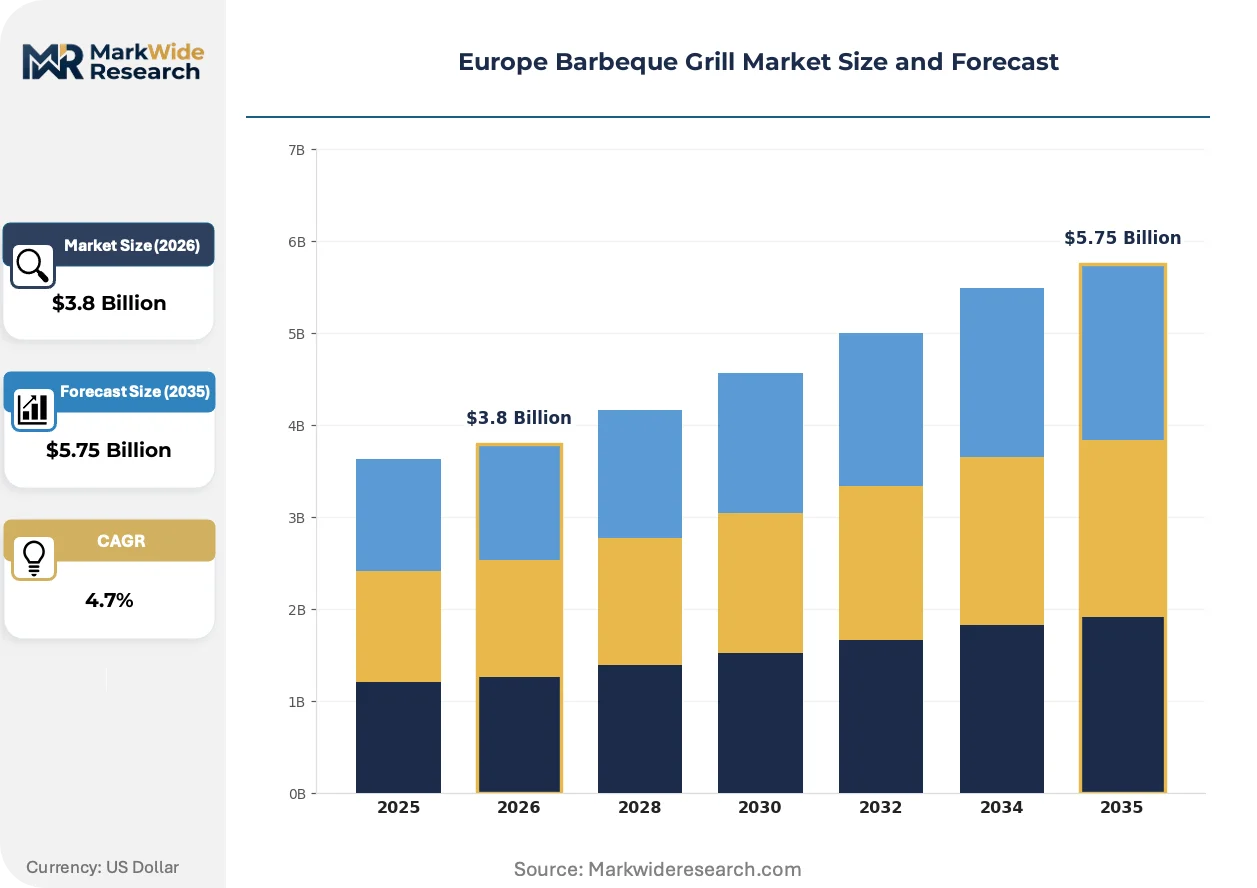
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Grills, Charcoal Grills, Electric Grills, Portable Grills End User: Residential Users, Restaurants, Catering Services, Outdoor Events Distribution Channel: Retail Stores, Online Platforms, Direct Sales, Specialty Shops Price Tier: Premium, Mid-Range, Budget, Luxury |
| Companies Covered | Weber Inc., Napoleon, Char-Broil, Landmann, Traeger Inc., Campingaz, Broil King, Boretti BV, Tefal, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Barbeque Grill Market Trends and Innovations
Ceramic infrared burner technology is compressing the performance gap between compact urban grills and full-size outdoor kitchens. Three distinct vectors are reshaping product architecture and go-to-market economics across the continent.
Infrared ceramic tile systems are replacing traditional stainless steel tube burners in premium compact units. Apartment dwellers in Barcelona and Lisbon are adopting these systems at twice the rate of conventional gas alternatives. The technology is miniaturizing searing performance into countertop footprints previously limited to electric contact grills.
REACH restrictions on hexavalent chromium in surface coatings are forcing coating suppliers to accelerate trivalent chromium and ceramic-based alternatives. Porcelain-enameled cast iron grate manufacturers face 12-18 month reformulation timelines. Southern European coastal markets with salt-air corrosion exposure are driving earliest adoption of new compliant formulations.
Specialty retailers are ceding share to direct-to-consumer channels as buyers research BTU outputs and burner configurations online before purchase. Independent garden centers in Germany and Austria are consolidating or launching private-label grill lines to retain margin. This channel rotation is most visible in the Benelux region where Amazon and manufacturer-direct platforms now capture over one-third of premium grill transactions.
Europe Barbeque Grill Market Segmentation
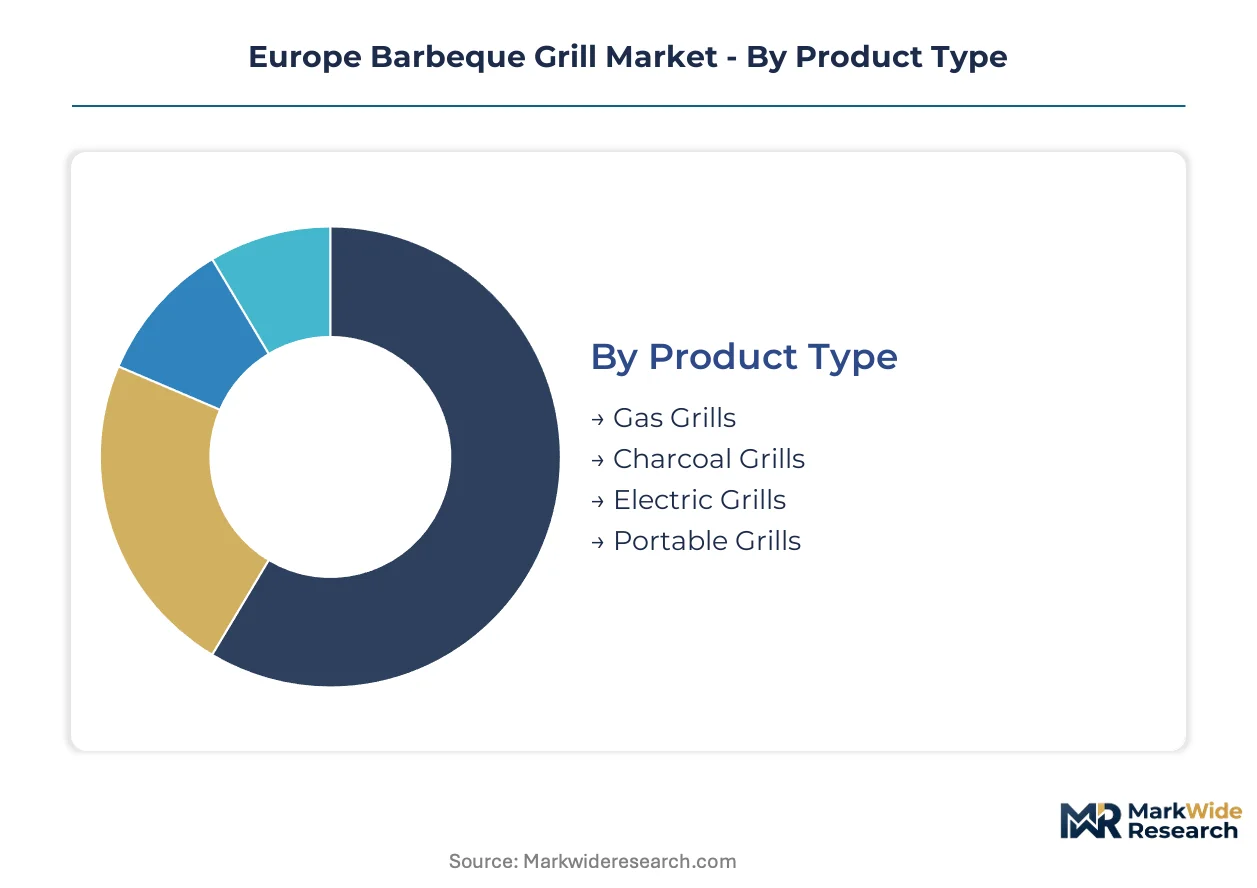
Segmentation in the Europe barbeque grill market reveals distinct procurement patterns between Southern European coastal hospitality and Northern European residential replacement cycles. Fuel type and distribution channel choices diverge sharply across Mediterranean terrace dining versus Alpine apartment balcony constraints.
Product Type:
Domestic manufacturing in Germany and Italy dominates gas grill output for intra-European trade, while portable grill sourcing concentrates in Portuguese coastal assembly for export to French and Spanish camping markets.
- Gas Grills:These units deploy propane or natural gas through brass valve manifolds with 8,000-20,000 BTU per burner ratings. German covered terrace installations in Bavaria and Baden-Württemberg drive commercial-grade replacement demand insulated from weather sensitivity. CE marking harmonization under the EU Gas Appliances Regulation reduces cross-border certification friction for manufacturers exporting from Stuttgart and Bologna to Lisbon and Madrid.
- Electric Grills:Infrared ceramic heating elements deliver 2,000-watt outputs in balcony-compliant footprints. Madrid and Milan urban cores present underpenetrated demand where open-flame restrictions limit combustion alternatives. REACH-compliant surface coatings accelerate product launch timelines for ceramic-based alternatives to hexavalent chromium finishes.
- Charcoal Grills:Porcelain-enameled steel construction with adjustable air dampers for temperature control. Landmann's German engineering heritage anchors mid-range competition through specialized kettle and barrel designs.
- Portable Grills:Compact foldable units with cast aluminum fireboxes for caravan and camping deployment. Coastal Portugal seasonal tourism drives 24-36 month replacement cycles in compact appliance turnover.
Gas grills hold the largest share; momentum sits with portable grills gaining share fastest among caravan owners and apartment dwellers.
End User:
Cost tier stratification separates premium ceramic infrared systems for restaurant chains from budget charcoal units for occasional residential entertaining.
- Residential Users:Backyard installations in German suburban markets favor built-in natural gas connections with 304 stainless steel construction. Nickel price volatility from Indonesian supply concentration squeezes margin on premium construction tiers for this segment.
- Restaurants:Covered terrace hospitality venues across Southern Spain and Portugal install permanent built-in grill stations with modular component replacement programs. CSRD-aligned circular design creates procurement preference for manufacturers offering take-back schemes.
- Catering Services:Mobile propane cart systems with quick-connect hose assemblies for event deployment. Post-Brexit customs documentation fragments after-sales service networks for UK-origin equipment serving continental European catering fleets.
- Outdoor Events:Rental-grade charcoal kettle grills with reinforced leg assemblies for festival and wedding deployment. Seasonal demand concentrates in French Provence and Italian Tuscany vineyard event circuits.
Residential users command volume leadership; restaurants are climbing the fastest on covered terrace expansion.
Distribution Channel:
Volume concentration tilts toward digital platforms in Benelux premium segments, while specialty retail retains hold in Austrian and German garden center networks.
- Retail Stores:Big-box home improvement chains in France and Germany stock seasonal grill assortments with assembly services. Independent garden centers consolidate or launch private-label lines to retain margin against platform competition.
- Online Platforms:Amazon and manufacturer-direct platforms capture over one-third of premium grill transactions in Belgium, Netherlands, and Luxembourg. Buyers research BTU outputs and burner configurations digitally before purchase completion.
- Direct Sales:Commercial hospitality procurement runs through manufacturer account teams for covered terrace specification. Direct channel margin concentration is strongest in ceramic infrared burner configurations.
- Specialty Shops:Independent outdoor living retailers in Austria and Switzerland provide consultation on natural gas line integration. These outlets emphasize grade 304 stainless durability benchmarks set by Germany's Federal Institute for Materials Research.
Retail stores maintain the largest share; online platforms show steepest expansion trajectory on research-driven purchase behavior.
Price Tier:
Application maturity separates established premium gas grill replacement cycles from emerging luxury smart-control segments.
- Premium:Grade 304 stainless construction with ceramic infrared burners and Bluetooth-enabled probe systems. Weber Inc. leverages R&D intensity to dominate this category through connected temperature management.
- Mid-Range:Grade 430 stainless or porcelain-enameled steel with conventional tube burners. Napoleon anchors position through manufacturing scale across European production footprints serving this tier.
- Budget:Painted carbon steel construction with basic charcoal or low-BTU gas configurations. Price-sensitive demand concentrates in Eastern European markets with shorter replacement horizons.
- Luxury:Outdoor kitchen island integration with multiple fuel types and smart home connectivity. Bluetooth-enabled probe systems integrated with ceramic burner management open price tiers previously captured by indoor appliance brands.
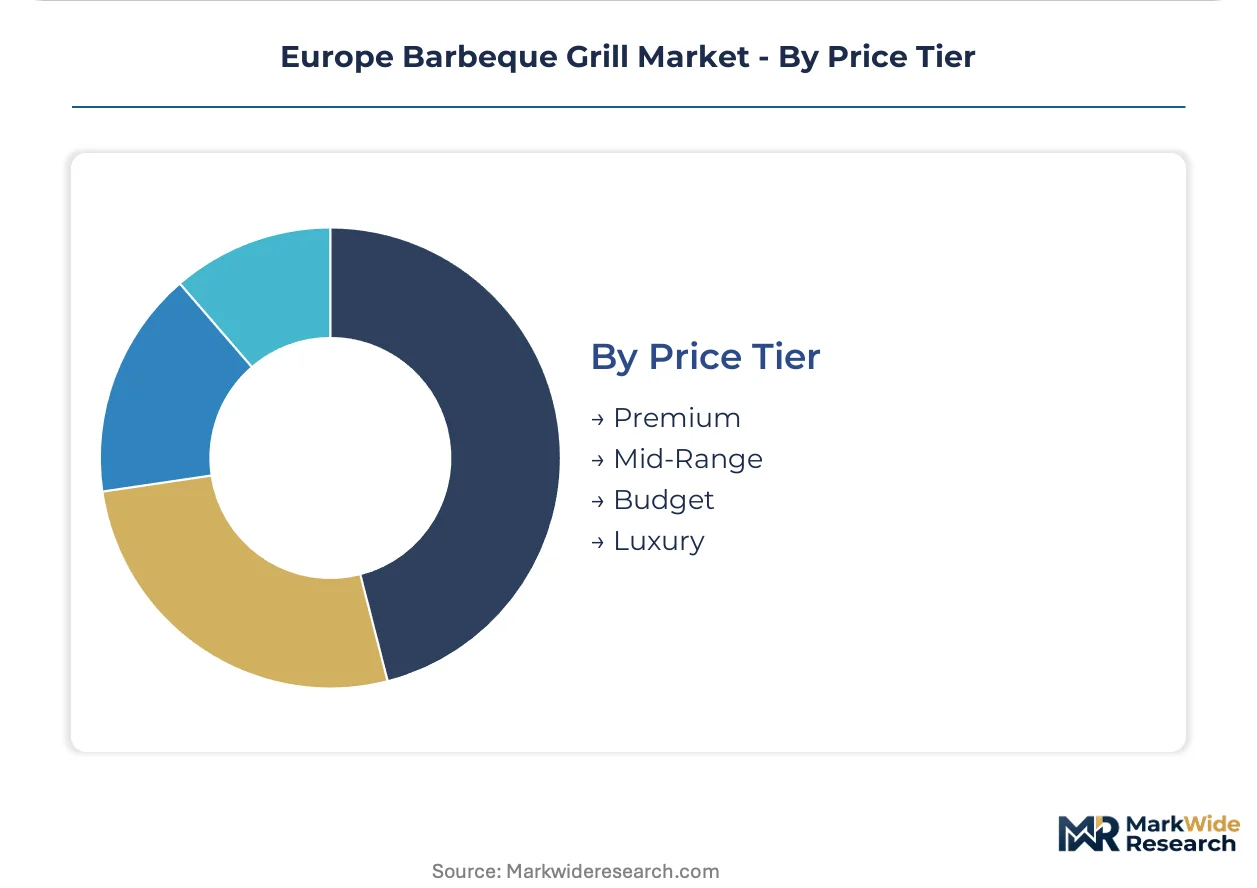
Premium tier holds the largest share; luxury segment is expanding most quickly on smart temperature control convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Europe, with German and Austrian buyers accepting premium construction costs while Spanish and Portuguese consumers prioritize seasonal value tiers. Southern coastal markets favor portable solutions with shorter replacement cycles, whereas Northern European suburban households invest in permanent built-in installations.
Germany
Covered terrace hospitality venues in Bavaria and Baden-Württemberg drive commercial-grade demand insulated from weather sensitivity. The Federal Institute for Materials Research sets supplementary durability benchmarks that shape manufacturer quality investments. Stuttgart anchors gas grill manufacturing for intra-European trade.
Spain
Coastal tourism concentrates portable grill turnover every 24-36 months in Algarve-adjacent regions. Open-flame restrictions in Barcelona and Madrid high-density housing limit combustion-based unit addressability. Valencia serves as the primary assembly hub for compact camping-oriented exports.
France
Provence and Tuscany vineyard event circuits sustain seasonal rental-grade charcoal demand. Big-box home improvement chains stock seasonal assortments with assembly services. The Auvergne-Rhône-Alpes cluster specializes in porcelain-enameled grate manufacturing under REACH-compliant coating timelines.
Italy
Milan urban cores present underpenetrated demand for balcony-compliant infrared electric units. CE marking harmonization under the EU Gas Appliances Regulation reduces certification friction for Bologna-based manufacturers exporting to Lisbon. Emilia-Romagna hosts specialized valve manifold production.
Portugal
Seasonal tourism drives compact appliance replacement concentration in coastal Alentejo and Algarve regions. Caravan and camping infrastructure expansion accelerates portable grill procurement cycles. Lisbon serves as the distribution gateway for French and Spanish camping market exports.
Europe Barbeque Grill Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Europe barbeque grill landscape. Premium ceramic infrared burner development concentrates in R&D-intensive specialists, while manufacturing scale advantages accrue to diversified outdoor appliance conglomerates. Three strategic archetypes dominate: engineering-heritage German specialists, North American scale players with European production footprints, and diversified home appliance multinationals. Competitive moves center on CSRD-aligned circular design programs and direct-to-consumer channel expansion.
Among German engineering-heritage specialists, Landmann exemplifies mid-range charcoal segment focus through specialized kettle and barrel designs. Weber Inc. and Napoleon occupy positions spanning premium gas grill categories and manufacturing scale across transatlantic production networks. These three anchors represent distinct strategic postures: heritage craftsmanship, R&D-intensive premium positioning, and operational scale efficiency.
| Leading Market Players |
|---|
| Weber Inc. |
| Napoleon |
| Char-Broil |
| Landmann |
| Traeger Inc. |
| Campingaz |
| Broil King |
| Boretti BV |
| Tefal |
| Others |
Pricing and Supply Chain Analysis
CE marking under the EU Gas Appliances Regulation gates both supplier qualification and price tier separation simultaneously. Manufacturers must absorb certification costs to access premium positioning, while uncertified competitors remain trapped in commodity charcoal segments with thinner returns.
Pricing Analysis
After-sales revenue from modular component replacement and burner refurbishment drives lifetime value across installed base portfolios. Three-tier pricing structure across premium ceramic infrared, standard tube burner, and economy charcoal configurations segments buyer willingness-to-pay by application intensity. Price differentiation rests on grade 304 stainless certification against Germany's Federal Institute for Materials Research benchmarks. Cost compression in mid-range gas portfolios is intensifying because nickel price volatility from Indonesian supply concentration squeezes margin on premium construction tiers. Budget-tier buyers in Eastern European markets exhibit highest price sensitivity, while covered terrace hospitality operators in Bavaria accept premium construction costs for weather-insulated replacement cycles.
Supply Chain Analysis
Inbound logistics costs from Asia-Pacific container lanes into Rotterdam and Hamburg shape working capital requirements for stainless steel coil importers. Manufacturing gravity centers on Germany and Italy for gas grill valve manifolds and burner assemblies, with Portuguese coastal facilities handling portable grill export assembly for French and Spanish camping markets. Raw material dependencies include Indonesian nickel for grade 304 stainless, Chinese porcelain enamel for grate coatings, and Italian brass for precision valve castings. Single-source vulnerability concentrates in hexavalent chromium coating suppliers facing REACH-mandated reformulation timelines. Distribution runs through big-box home improvement chains for residential volume, with direct manufacturer account teams capturing commercial hospitality specification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe barbeque grill demand sits in early-cycle expansion as urban balcony compliance requirements accelerate electric grill penetration beyond traditional combustion alternatives. Covered terrace hospitality investment across Southern Germany and coastal Portugal extends replacement cycles independent of residential weather sensitivity.
For Market Incumbents: Consolidate aftermarket service networks to capture recurring revenue from modular burner replacement programs. Deepen captive supply of grade 304 stainless through backward integration into European rolling mill partnerships to defend margin position against nickel price volatility. Lock in CSRD-aligned circular design certification ahead of procurement preference shifts in Spanish and Portuguese covered terrace hospitality.
For New Entrants and Emerging Players: Anchor in Madrid and Milan urban cores with balcony-compliant infrared electric units where open-flame restrictions eliminate incumbent gas grill competition. Target caravan and camping infrastructure expansion along Portugal's Alentejo coast with compact foldable designs optimized for 24-36 month seasonal replacement cycles. Pursue direct-to-consumer channel entry through Amazon and manufacturer-direct platforms where research-driven purchase behavior now captures over one-third of premium transactions in Benelux markets.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across ceramic infrared burner R&D programs as efficiency mandates from the EU Ecodesign Directive compress development timelines. Long-term viability over the next decade favors manufacturers with transatlantic production footprints capable of serving both European regulatory compliance and North American volume scale. Acquisition targets should demonstrate established CE marking pathways and REACH-compliant coating supplier relationships. The signal to watch is F-Gas Regulation extension proposals affecting propane grill economics, which would structurally favor electric and natural gas alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Infrared Burner R&D Scale-Up | EU Ecodesign Directive efficiency mandates compress development timelines for premium compact units. |
| REACH-Compliant Coating Supplier Partnership | Trivalent chromium and ceramic-based alternatives to hexavalent finishes accelerate product launch timelines. |
| Direct-to-Consumer Channel Expansion | Amazon and manufacturer-direct platforms capture research-driven purchase behavior in Benelux premium segments. |
| CSRD-Aligned Circular Design Program | Take-back schemes and modular component replacement create procurement preference in Southern European hospitality. |
| Portuguese Coastal Assembly Footprint | Valencia and Lisbon hubs serve French and Spanish camping market export demand with logistics cost advantages. |
Research Methodology
A spread of perspectives from product development directors at German engineering-heritage manufacturers, procurement managers at French big-box retail chains, regulatory affairs leads navigating REACH compliance timelines, and aftermarket service heads managing cross-border spare parts logistics converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through EU Gas Appliances Regulation filing databases, German Federal Institute for Materials Research durability benchmark publications, and customs records tracking stainless steel coil imports through Rotterdam and Hamburg. Bottom-up unit economics triangulated against top-down category spend estimates from retail audit data.
Segmentation dimensions modeled include fuel type architecture, price tier construction grade, end-user application intensity, and distribution channel format across the projection horizon. CAGRs were derived from installation base growth rates, replacement cycle compression in portable segments, and premium tier share expansion from smart temperature control adoption. Industry-specific forecast inputs incorporated nickel price volatility assumptions from Indonesian supply concentration and F-Gas Regulation extension risk scenarios affecting propane grill economics.
Decision-makers should treat outputs as directional under assumptions of continued EU Ecodesign Directive enforcement and stable REACH compliance timelines; material deviation would warrant model refresh. Specific risk factors that could revise forecasts include carbon-border adjustment mechanism implementation affecting stainless steel input costs and potential open-flame restriction expansion into additional high-density housing markets. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Europe Cloud Kitchen Market
Food Service
Commercial Deep Fryer Parts and Accessories Market
Food Service
Global Vending Machine Market
Food Service
Global Combi Ovens Market
Food Service
Europe Biodegradable Food Service Disposables Market
Food Service
United States Food Truck Market
Food Service
Global Online Food Delivery Services Market
Food Service
Switzerland Food Service Market
Food Service
China Inflight Catering Market
Food Service
Kamado Grill Market
Food Service
New Zealand Foodservice Market
Food Service
India Foodservice Market
Food Service
Light Meal Market
Food Service
India Quick Service Restaurant Market
Food Service
Cloud Kitchen Market
Food Service
Mobile Food Services Market