
 Airport Quick Service Restaurants Market | 2026-2036
Airport Quick Service Restaurants Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Quick Service Restaurants Market Outlook
The capital-intensity divergence between full-scale kitchen operators and kiosk-only formats is collapsing as lease costs and labor shortages compress margins across all formats. McDonald's Corporation leverages its supply chain scale to sustain unit economics in high-rent terminal locations. SSP Group plc anchors its portfolio through geographic dominance across European and Middle Eastern aviation hubs. Autogrill SpA differentiates via brand specialization in Italian and Mediterranean concepts that command premium positioning.
Airport quick service restaurants are foodservice outlets designed for rapid preparation and minimal dwell time, typically operating with streamlined menus, batch-cooking protocols, and throughput targets exceeding 100 transactions per hour during peak flight windows. Their primary commercial purpose is capturing discretionary passenger spending during constrained dwell periods while maximizing revenue per available square foot in terminal real estate. The self-service kiosk segment leads in capital deployment as operators seek labor arbitrage and order-accuracy gains, while mobile ordering represents the fastest-growing channel as airline app integrations and gate-area pickup locations proliferate. Healthy options command outsized margin pools relative to traditional fast food, reflecting traveler willingness to pay premium prices for perceived wellness benefits during stressful transit.
FDA food safety protocols, FAA terminal concession guidelines, and EU Green Deal packaging mandates collectively shape product standards, operational compliance costs, and market access conditions for operators across multiple jurisdictions. REACH chemical restrictions on food-contact materials and local health department inspection regimes further constrain supplier selection and equipment procurement decisions. Stakeholders must monitor evolving biometric payment integration and dynamic pricing algorithms as these technologies redefine competitive advantage in constrained airport environments.
Market Dynamics
Self-service kiosk deployment is compressing labor dependencies while biometric payment integration redefines throughput economics across terminal concessions. Operators now face simultaneous pressure to reduce dwell times and capture premium pricing during constrained passenger windows.
Growth Catalysts
- EU Green Deal packaging mandates:Sustainable packaging requirements are accelerating supplier consolidation toward compostable alternatives that command traveler willingness-to-pay premiums.
- Mobile ordering channel proliferation:Airline app integrations and gate-area pickup locations are expanding transaction capture beyond traditional concourse footprints.
- Passenger throughput expansion at Dubai International Airport:Infrastructure investments across United Arab Emirates aviation hubs are enlarging the addressable traveler base for expedited dining.
Market Restraints
- Terminal lease cost escalation:Revenue-sharing agreements with airport authorities now extract 15-25% of gross sales, compressing unit economics for all format sizes.
- Perishable supply concentration:Just-in-time fresh ingredient logistics depend on a narrow base of regional cold-chain distributors vulnerable to disruption.
- FDA food safety protocol complexity:Multi-jurisdictional compliance requirements impose redundant audit burdens and limit menu standardization across hub networks.
Strategic Opportunities
- Healthy option premiumization:Wellness-positioned menus capture outsized margin pools as travelers pay premiums for perceived nutritional benefits during stressful transit.
- Dynamic pricing algorithm deployment:Real-time demand-responsive pricing enables revenue optimization across flight schedule peaks and troughs.
- China aviation infrastructure expansion:Secondary city airport development creates first-mover positioning opportunities before concession saturation.
Industry Challenges
- Biometric payment system integration:Facial recognition and palm-scan transaction protocols require costly POS infrastructure upgrades and staff retraining.
- Cross-functional kitchen automation talent scarcity:Operators struggle to recruit technicians capable of maintaining robotic cooking equipment and IoT-enabled inventory systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Quick Service Restaurants Market |
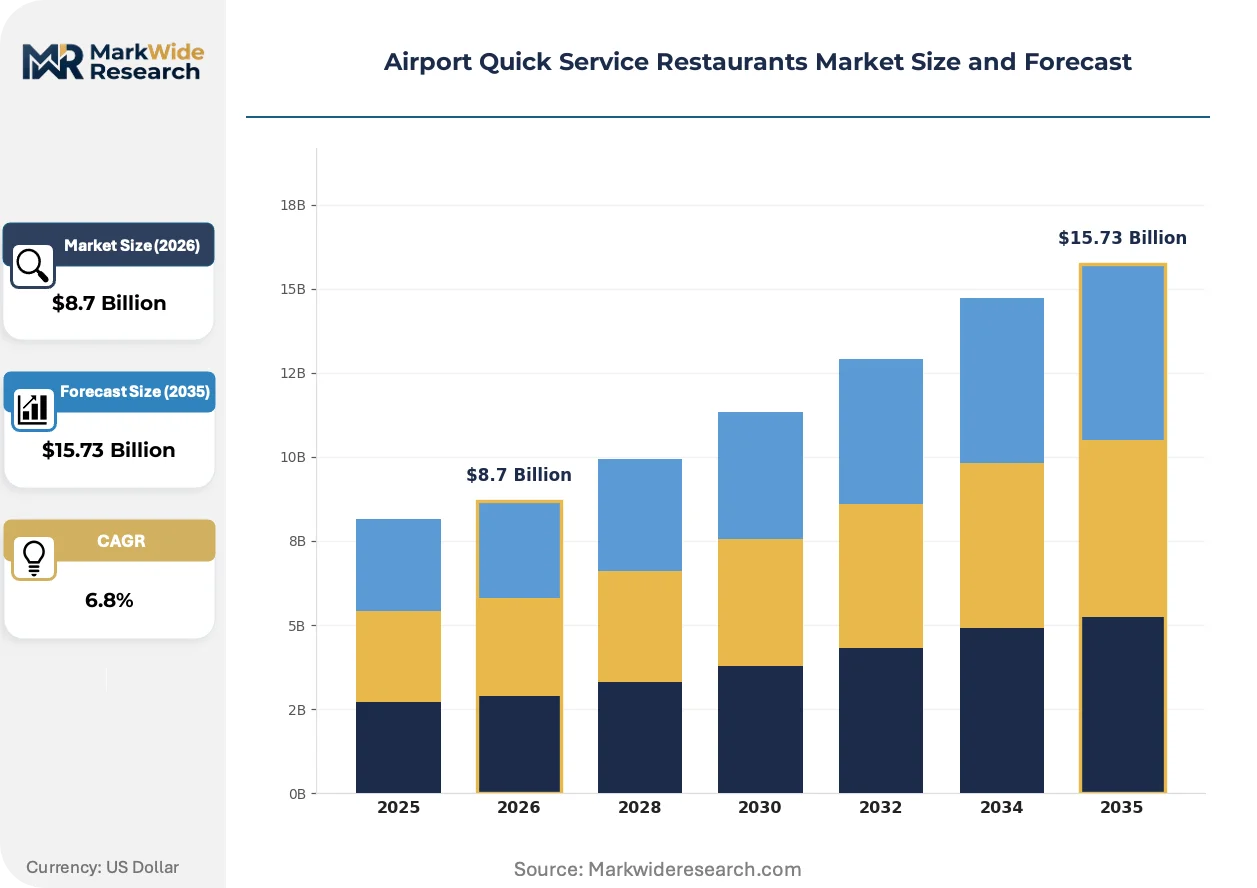
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Counter Service, Self-Service Kiosks, Drive-Thru, Mobile Ordering Menu Type: Fast Food, Coffee Beverages, Snacks, Healthy Options Customer Type: Travelers, Airport Staff, Airline Crew, Business Travelers Seating Arrangement: Indoor Seating, Outdoor Terrace, Grab-and-Go, Lounge Area |
| Companies Covered | Subway IP LLC, Chick-fil-A Inc., McDonald's Corporation, Autogrill SpA, SSP Group plc, Starbucks Corporation, Lagardère Travel Retail, Panda Restaurant Group Inc., Yum! Brands Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Quick Service Restaurants Market Strategic Shifts
Digital ordering architectures are fragmenting service delivery models while compressing the traditional distinction between full-kitchen and kiosk-only formats. Three concurrent developments are reshaping competitive positioning.
Kitchen automation robotics is decomposing the labor-intensive preparation layer that previously justified full-scale kitchen investments. Mid-sized operators at Hartsfield-Jackson Atlanta International Airport and Denver International Airport are deploying robotic fry stations and automated beverage systems to match throughput benchmarks of legacy full-service formats without proportional headcount expansion. This compression of the capital-labor tradeoff is enabling smaller footprint entrants to bid competitively for premium gate-adjacent real estate previously reserved for established chains.
REACH chemical restrictions on food-contact materials are constraining supplier selection across European aviation hubs. The ECHA framework limits certain per- and polyfluoroalkyl substances in disposable serviceware, forcing operators to source alternative coatings at 20-40% cost premiums. German and French terminal concessionaires are responding through consolidated procurement alliances that aggregate volume sufficient to secure compliant materials at negotiated rates unavailable to standalone operators.
Passenger dwell-time anxiety is compressing the acceptable service interval from order placement to handoff. Gate-proximate pickup locations and mobile order-ahead functionality are displacing traditional concourse queue-based models at United States hubs including Dallas-Fort Worth International Airport and Los Angeles International Airport. This behavioral shift concentrates demand spatially and temporally, rewarding operators with predictive preparation algorithms and dynamic staffing models over those dependent on walk-up traffic patterns.
Airport Quick Service Restaurants Market Segmentation
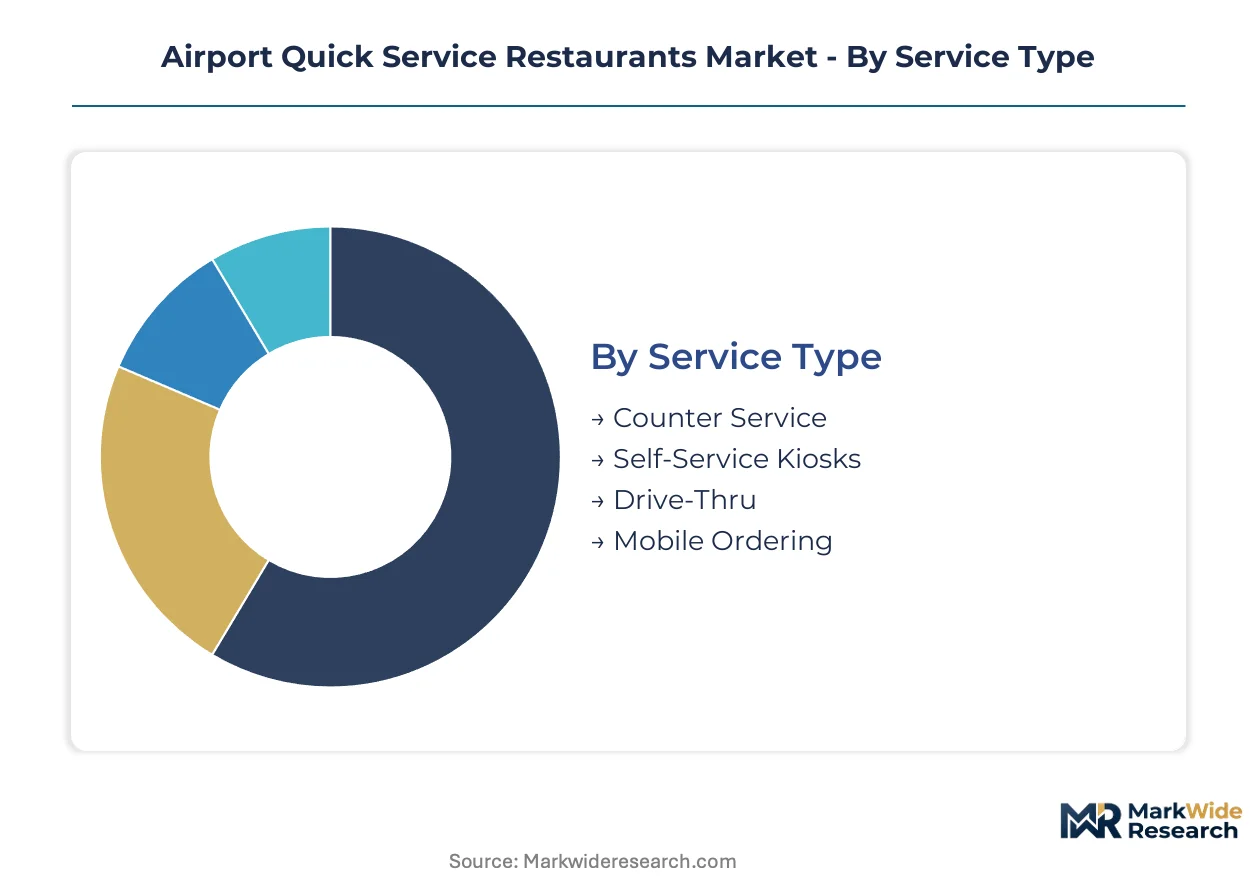
Segmentation in airport quick service restaurants determines real estate allocation, labor deployment, and technology investment across constrained terminal environments. Each dimension reflects distinct passenger dwell-time behaviors and spending propensities that operators must match to capture transaction volume during flight windows.
Service Type:
Channel-mix dynamics concentrate capital deployment toward formats that compress service intervals while expanding transaction capture beyond traditional concourse footprints.
- Counter Service:Traditional staffed ordering points with menu boards and cash handling, still dominant at older terminals and premium-positioned concepts. Demand concentrates at Dubai International Airport and Frankfurt Airport where legacy concession agreements preserve full-service formats despite labor cost pressures.
- Self-Service Kiosks:Touchscreen terminals enabling unassisted ordering and payment, now standard at Hartsfield-Jackson Atlanta and Denver International Airport. Operators deploy these to reduce headcount dependencies while maintaining throughput targets above 100 transactions hourly during peak windows.
- Drive-Thru:Vehicle-accessible service lanes at select ground-level terminals, limited to airports with adjacent parking or rental car facilities. Chicago O'Hare and Dallas-Fort Worth maintain these for staff and crew convenience rather than passenger volume.
- Mobile Ordering:Smartphone-based pre-ordering with designated pickup points, the channel expanding most quickly through airline app integrations and gate-proximate retrieval locations at Los Angeles International and Seattle-Tacoma International Airport.
By volume, Counter Service leads. By growth pace, Mobile Ordering is ahead.
Menu Type:
Cost-tier stratification separates commodity fast food from premium-positioned wellness concepts that command price elasticity advantages in stressed transit environments.
- Fast Food:Standardized burger, sandwich, and fried item portfolios with batch-cooking protocols and sub-three-minute service targets. McDonald's and similar chains dominate this tier through supply chain scale that offsets high terminal lease burdens.
- Coffee Beverages:Espresso-based drinks and ready-to-drink formats with morning demand concentration and premium pricing power. Starbucks and regional specialists anchor this segment at London Heathrow and Singapore Changi where dwell times accommodate beverage rituals.
- Snacks:Pre-packaged and quick-assembly items including pastries, chips, and confectionery for sub-60-second transactions. This segment captures impulse spending from passengers with under-15-minute connection windows at hub airports.
- Healthy Options:Salads, grain bowls, and protein-focused menus with fresh ingredient logistics and 40-60% gross margins. Travelers at San Francisco International and Amsterdam Schiphol demonstrate willingness-to-pay premiums for perceived nutritional benefits during long-haul connections.
By revenue concentration, Fast Food leads. By margin expansion, Healthy Options is climbing fastest.
Customer Type:
Application-based segmentation distinguishes discretionary leisure spending from contractually governed crew provisioning and recurring staff demand with divergent price sensitivity profiles.
- Travelers:General passenger base including leisure and infrequent flyers with variable dwell times and discretionary budgets. This group generates majority revenue but exhibits unpredictable traffic patterns tied to flight schedules and seasonal route variations.
- Airport Staff:Permanent and contract employees seeking value-priced meals during shift breaks, representing predictable daily volume with high price elasticity. Operators at Heathrow and Charles de Gaulle dedicate specific kiosks to this segment with subsidized pricing through employer partnerships.
- Airline Crew:Flight deck and cabin personnel with contracted meal allowances and time-constrained service requirements. Crew demand concentrates in early morning and late evening windows, requiring 24-hour operational capability at major crew bases.
- Business Travelers:Frequent flyers with expense account flexibility and preference for premium formats with seating and power access. This segment over-indexes on healthy options and coffee beverages at financial hub airports including London City and Frankfurt.
By transaction frequency, Travelers dominate. By per-capita spend, Business Travelers outpace all others.
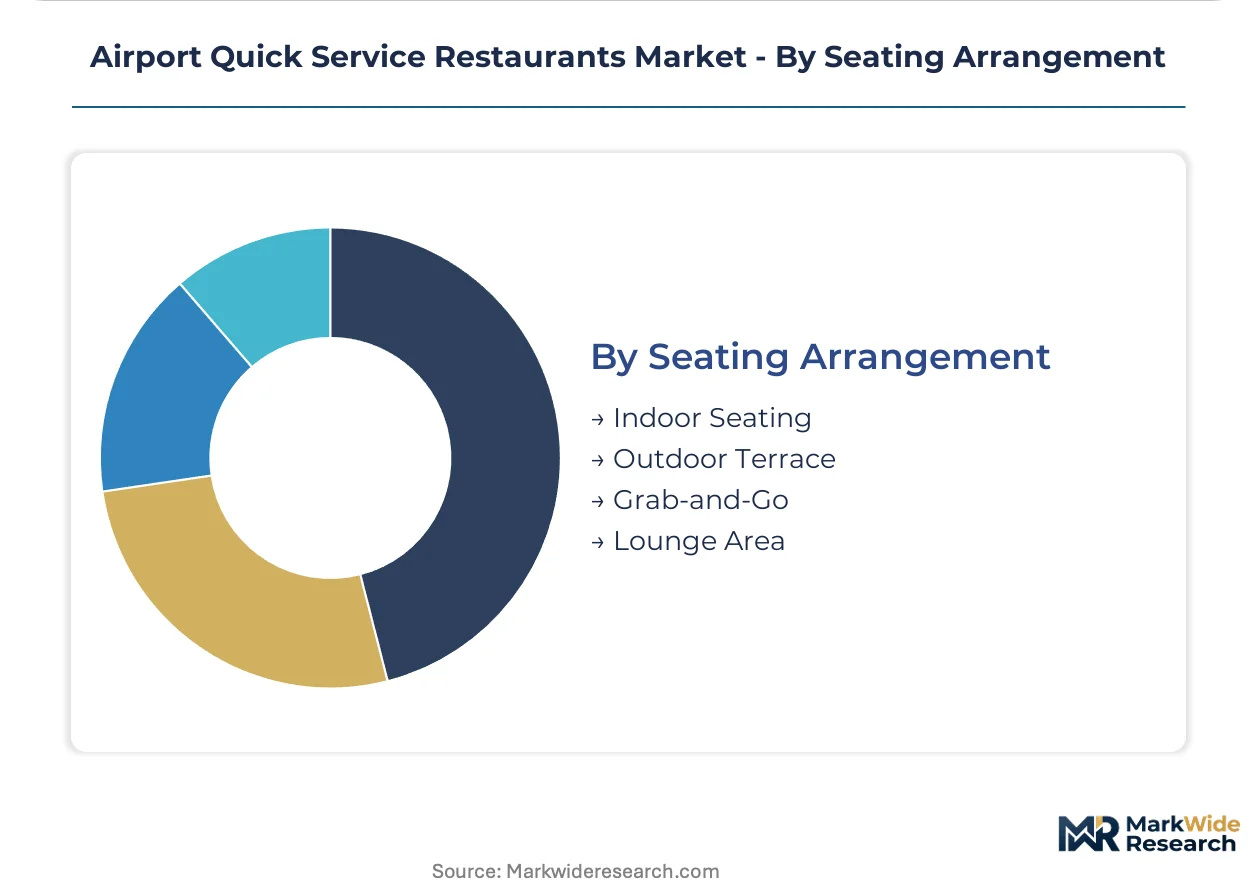
Seating Arrangement:
Volume-throughput tradeoffs differentiate formats optimized for dwell-time extension versus those maximizing passenger flow-through in gate-proximate real estate.
- Indoor Seating:Table and chair configurations accommodating 15-45 minute stays with full menu service. Legacy formats at Amsterdam Schiphol and Munich Airport retain these despite space efficiency pressures from airport authorities.
- Outdoor Terrace:Climate-dependent open-air seating with premium positioning at terminals with favorable weather and tarmac views. Dubai International and Singapore Changi leverage these for differentiation, though utilization fluctuates seasonally.
- Grab-and-Go:No-seating formats with refrigerated displays and rapid transaction design for sub-5-minute service. This configuration dominates new concession builds at Atlanta and Denver where square-foot revenue maximization drives planning decisions.
- Lounge Area:Premium paid or membership-access spaces with comfortable seating, power, and extended dwell tolerance. Priority Pass and airline-branded lounges at Heathrow Terminal 5 and Dallas-Fort Worth Terminal D capture high-margin captive audiences.
By unit count, Grab-and-Go leads. By revenue per square foot, Lounge Area formats outperform.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Passenger willingness-to-pay varies sharply across geographies, with Gulf and Asian travelers accepting premium pricing while European and North American buyers exhibit greater price elasticity. This demand-elasticity contrast shapes concession strategies and real estate bidding behavior.
United States
Hartsfield-Jackson Atlanta and Dallas-Fort Worth anchor domestic volume, with biometric payment pilots reducing transaction friction. FAA terminal concession guidelines govern revenue-sharing structures between operators and airport authorities. Denver International Airport is deploying kitchen automation robotics across mid-sized concessions to match throughput of legacy full-service formats.
United Arab Emirates
Dubai International Airport passenger throughput expansion is enlarging the addressable base for expedited dining concepts. MOHAP food safety protocols align with international standards while permitting operational flexibility. Abu Dhabi International Airport is attracting first-mover healthy-option concepts targeting premium-positioned wellness demand.
China
Secondary city airport development in Chengdu and Xi'an is creating concession opportunities before saturation sets in. SAMR food safety supervision and GB standards for food-contact materials shape supplier compliance requirements. Shanghai Pudong International Airport is integrating mobile ordering with airline apps for gate-proximate pickup deployment.
Germany
Frankfurt and Munich airports sustain demand for full-service formats despite labor cost pressures. REACH chemical restrictions on food-contact materials constrain disposable serviceware sourcing at 20-40% cost premiums. Berlin Brandenburg Airport concessionaires are forming procurement alliances to secure compliant packaging at negotiated volume rates.
United Kingdom
Heathrow Terminal 5 and London City Airport concentrate business traveler demand with expense account flexibility. EU Green Deal packaging mandates, retained in UK law post-Brexit, accelerate compostable alternative adoption. Gatwick Airport is expanding lounge-area formats to capture high-margin captive audiences during extended dwell periods.
Airport Quick Service Restaurants Market Competitive Environment
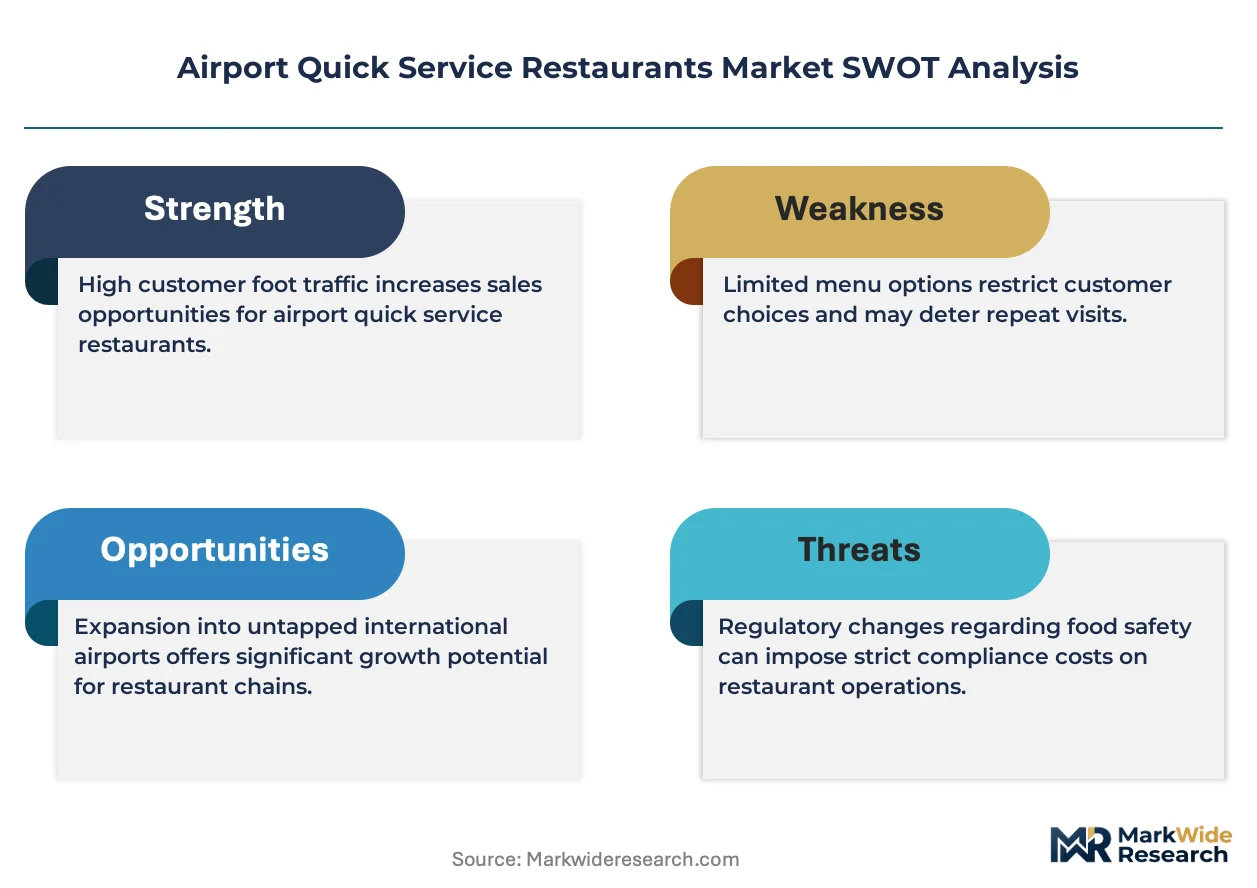
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Full-scale kitchen operators with supply chain scale anchor premium gate-adjacent real estate, while kiosk-only formats leverage labor arbitrage to bid competitively for mid-tier locations. Three archetypes dominate: global fast-food chains with terminal-specific operational adaptations, regional concessionaires with geographic hub concentration, and healthy-option specialists commanding wellness premiums. Competitive moves concentrate on M&A for hub portfolio expansion and strategic partnerships for airline app integration.
Within the global chain archetype, McDonald's Corporation and Subway IP LLC exemplify supply chain scale advantages that offset high terminal lease burdens. SSP Group plc occupies a position representing geographic dominance across European and Middle Eastern aviation hubs. Autogrill SpA exemplifies brand specialization in Mediterranean concepts that command premium positioning through differentiated menu architecture.
| Leading Market Players |
|---|
| Subway IP LLC |
| Chick-fil-A Inc. |
| McDonald's Corporation |
| Autogrill SpA |
| SSP Group plc |
| Starbucks Corporation |
| Lagardère Travel Retail |
| Panda Restaurant Group Inc. |
| Yum! Brands Inc. |
| Others |
Value Chain & Pricing Dynamics
Terminal lease cost escalation at Hartsfield-Jackson Atlanta and Dubai International compresses unit economics across all format sizes, forcing operators to consolidate procurement volumes and automate preparation layers to defend margin floors. This scale imperative concentrates supply relationships toward regional cold-chain distributors capable of just-in-time fresh ingredient logistics while pricing power concentrates with concepts commanding wellness premiums.
Pricing Analysis
After-sales revenue through loyalty program subscriptions and mobile app engagement drives lifetime value capture beyond transactional food sales. Three-tier pricing structure across premium healthy concepts, standard fast-food formats, and economy grab-and-go tiers reflects divergent passenger willingness-to-pay during stressful transit. Pricing pressure stems from revenue-sharing agreements extracting 15-25% of gross sales to airport authorities. Leisure travelers exhibit highest price sensitivity while business travelers with expense account flexibility accept premium positioning.
Supply Chain Analysis
Strait of Hormuz transit vulnerability underwrites energy cost volatility that feeds into cold-chain logistics pricing across Middle Eastern aviation hubs. Fresh produce sourcing concentrates in Spain, the Netherlands, and Morocco for European terminals while protein suppliers cluster in Brazil and the United States. Single-source vulnerability runs through regional cold-chain distributors serving just-in-time delivery windows. Distribution runs through consolidated procurement alliances at Berlin Brandenburg and Frankfurt to secure REACH-compliant packaging at negotiated volume rates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Airport quick service restaurants represent an early-cycle expansion story as biometric payment integration and kitchen automation robotics penetrate below the largest global chains, creating first-mover advantages for mid-sized operators before concession saturation accelerates.
For Market Incumbents: Fortify gate-adjacent real estate positions through lease renewal prioritization at Dubai International and Hartsfield-Jackson Atlanta before secondary city airports mature. Deploy kitchen automation robotics to match throughput benchmarks without proportional headcount expansion. Counter emerging healthy-option specialists by acquiring regional wellness-positioned concepts with established supplier relationships for fresh ingredient logistics.
For New Entrants and Emerging Players: Lead with mobile ordering channel development targeting airline app integrations at Los Angeles International and Seattle-Tacoma International where gate-proximate pickup infrastructure remains underdeveloped. White-space opportunities concentrate in secondary Chinese city airports at Chengdu and Xi'an before concession saturation. Capture crew demand through 24-hour operational capability with value-priced menus at major crew bases.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors operators with deployed biometric payment infrastructure and predictive preparation algorithms over legacy queue-dependent formats. Long-term viability rests on concession portfolio diversification across multiple aviation hubs to mitigate single-airport revenue concentration. Monitor biometric payment adoption velocity at Dallas-Fort Worth and Denver International as inflection indicator for technology leadership consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Airline App Integration Partnership | Mobile ordering channel expansion captures gate-proximate transactions beyond traditional concourse footprints at United States hubs. |
| Kitchen Automation Robotics Deployment | Automated fry stations and beverage systems match legacy full-service throughput without proportional labor cost expansion. |
| Healthy Option Menu Extension | Wellness-positioned concepts command 40-60% gross margins through traveler willingness-to-pay premiums during stressful transit. |
| Biometric Payment Infrastructure Upgrade | Facial recognition and palm-scan protocols reduce transaction friction and redefine throughput economics across terminal concessions. |
| Consolidated Procurement Alliance Formation | Volume aggregation secures REACH-compliant and EU Green Deal-aligned packaging at negotiated rates unavailable to standalone operators. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA food safety protocol filings, FAA terminal concession guidelines, EU Green Deal regulatory texts, and airport authority revenue-sharing disclosures. Interviews with concession operations directors, terminal real estate managers, cold-chain logistics coordinators, and quick-service franchise development executives informed demand-side and supply-side assessments. Customs and trade data, SEC 10-K filings for listed operators, and aviation authority passenger throughput statistics provided secondary validation. Bottom-up unit economics modeling and top-down market sizing triangulated volume and value estimates.
Segmentation dimensions modeled include service type, menu category, customer archetype, and seating configuration across the projection horizon. Service type captures counter service, self-service kiosk, mobile ordering, and drive-thru channels. Menu category stratifies fast food, coffee beverages, snacks, and healthy options. Customer archetype distinguishes travelers, airport staff, airline crew, and business travelers. CAGRs derive from passenger throughput projections, concession penetration assumptions, and technology adoption curves for digital ordering platforms.
The analysis sits within stated boundaries; outcomes outside sustained aviation infrastructure investment, regulatory stability for food-contact materials, and labor cost trajectories would require recalibration. Forecasts reflect assumptions regarding biometric payment adoption velocity, healthy option menu expansion, and mobile ordering channel proliferation. Practitioners should keep alternative scenarios live as EU Green Deal packaging mandates, REACH chemical restrictions, and FAA terminal concession guidelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Restaurants in Belgium Market
Food Service
South Africa Fast Food Market
Food Service
Lunch Takeout Market
Food Service
Turkey Retail Bubble Tea Kits Market
Food Service
India Foodservice Market
Food Service
One-Off Chopsticks Market
Food Service
United States Food Truck Market
Food Service
GCC Food Service Market
Food Service
Nigeria Food Service Market
Food Service
Asia-Pacific Cloud Kitchen Market
Food Service
Flat Top Grills Market
Food Service
Global Online Food Ordering Market
Food Service
Inflight Catering Market
Food Service
Europe Pizza Oven Market
Food Service
Supermarkets Market
Food Service
Food Away from Home Market