
 Commercial Pizza Oven Market | 2026-2036
Commercial Pizza Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Pizza Oven Market Outlook
Modular oven configurations is consolidating buyer preferences across the commercial pizza oven landscape. Wood Stone Corporation leverages its stone-hearth engineering heritage to anchor premium positioning in full-service installations. Middleby Corporation competes through manufacturing scale and broad foodservice equipment portfolios that extend across multiple buyer tiers. Marra Forni specializes in Italian-imported refractory materials to differentiate its artisan-focused product lines.
A commercial pizza oven is a thermally insulated chamber designed to maintain temperatures between 450°F and 900°F, using refractory stone decks, convection airflow, or radiant flame to bake dough-based products in commercial foodservice environments. Deck ovens and conveyor ovens represent the largest installed base, with conveyor systems capturing high-throughput quick-service demand where speed determines kitchen throughput. Wood-fired ovens command the highest margin pools among fuel-type segments, though electric and hybrid configurations are gaining traction where municipal emissions restrictions limit gas combustion.
The U.S. Department of Energy sets minimum efficiency standards for commercial cooking equipment, while the EPA regulates particulate emissions from wood-burning installations in urban airsheds. NSF International certification governs food-contact surface safety, creating a compliance threshold that shapes product development budgets and market access timelines. Stakeholders must monitor evolving municipal electrification mandates and their impact on gas infrastructure access for new restaurant construction.
Market Dynamics
Quick-service restaurant chains are consolidating procurement around modular electric deck systems as municipal electrification mandates in dense metropolitan markets accelerate the phase-out of gas-fired kitchen infrastructure.
Growth Catalysts
- DOE Commercial Kitchen Efficiency Standards:Federal minimum efficiency thresholds are forcing equipment replacement cycles in U.S. foodservice operations, pulling forward demand for electric and hybrid fuel configurations.
- Refractory stone deck technology:Advanced thermal mass engineering is shortening recovery times between bakes, enabling higher throughput in compact kitchen footprints.
- Metropolitan restaurant density:Urban foodservice clusters in New York, Chicago, and Los Angeles are driving concentrated equipment procurement from multi-unit operators.
Market Restraints
- Refractory material import concentration:Italian-sourced firebrick and ceramic fiber supply chains face extended lead times and freight cost volatility.
- Three-phase electrical infrastructure:High-voltage installation requirements in older commercial buildings create retrofit friction and landlord negotiation delays.
- EPA particulate emissions rules:Urban airshed restrictions on wood combustion are constraining authentic wood-fired oven deployment in core metropolitan markets.
Strategic Opportunities
- Cloud kitchen proliferation:Delivery-optimized ghost kitchen operators are creating demand for compact, high-output conveyor systems with minimal ventilation footprints.
- Hybrid fuel system convergence:Gas-electric combination ovens are capturing operators seeking operational flexibility against uncertain municipal fuel bans.
- NSF certification premium tier:Enhanced food-contact surface standards are enabling price differentiation for manufacturers with accelerated compliance pathways.
Industry Challenges
- Refractory mason skill scarcity:Specialized craft knowledge for field-assembled wood-fired dome construction is concentrating in regional installer networks, extending project timelines.
- Ventilation system integration:Type I hood requirements for solid-fuel and high-temperature electric units are creating coordination complexity with HVAC contractors and fire code officials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Pizza Oven Market |
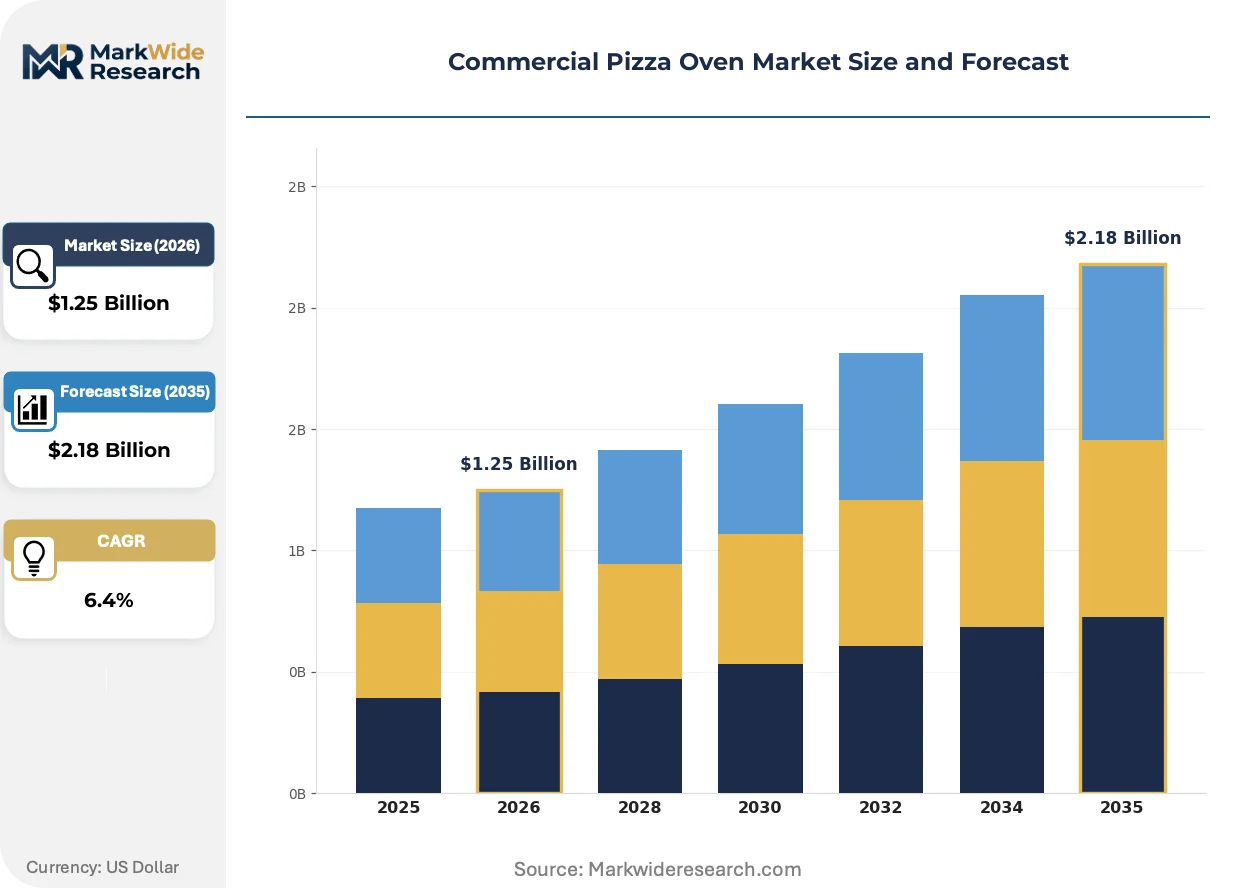
| Market Size in 2026 | $1.25 Billion |
| Market Size in 2035 | $2.18 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deck Ovens, Convection Ovens, Conveyor Ovens, Wood-Fired Ovens End User: Restaurants, Pizzerias, Food Trucks, Catering Services Fuel Type: Electric, Gas, Wood, Hybrid Size: Small, Medium, Large, Extra Large |
| Companies Covered | Wood Stone Corporation, Morello Forni, Fontana Forni, Gozney, Forno Bravo, Mugnaini Imports, Marra Forni, Middleby Corporation, Californo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Pizza Oven Market Strategic Shifts
Equipment manufacturers are compressing development cycles to align with accelerating municipal electrification timelines and evolving buyer specifications around energy intensity and kitchen footprint.
Smart temperature control systems with IoT-enabled remote monitoring are consolidating operational oversight for multi-unit pizza chains. These platforms transmit deck temperature, door-open frequency, and energy consumption data to central facilities management teams. The technology is consolidating maintenance scheduling and reducing unplanned downtime across distributed restaurant footprints.
The U.S. Department of Energy's amended commercial cooking equipment standards are mandating measurable efficiency gains in electric oven categories. Manufacturers are responding with enhanced insulation packages and regenerative heat recovery systems. Full-service independent operators face the steepest compliance cost absorption as they lack the procurement leverage of chain buyers.
Equipment-as-a-service financing models are displacing traditional capital purchase structures among emerging fast-casual concepts. Monthly payment arrangements bundle maintenance, certification renewal, and technology refresh cycles. This shift is most pronounced in Texas and Florida markets where franchise development velocity exceeds internal capital formation capacity.
Commercial Pizza Oven Market Segmentation
Equipment specification varies sharply across operator scale and throughput requirements. Capital allocation decisions hinge on fuel infrastructure access, kitchen footprint constraints, and menu positioning strategies.
Product Type:
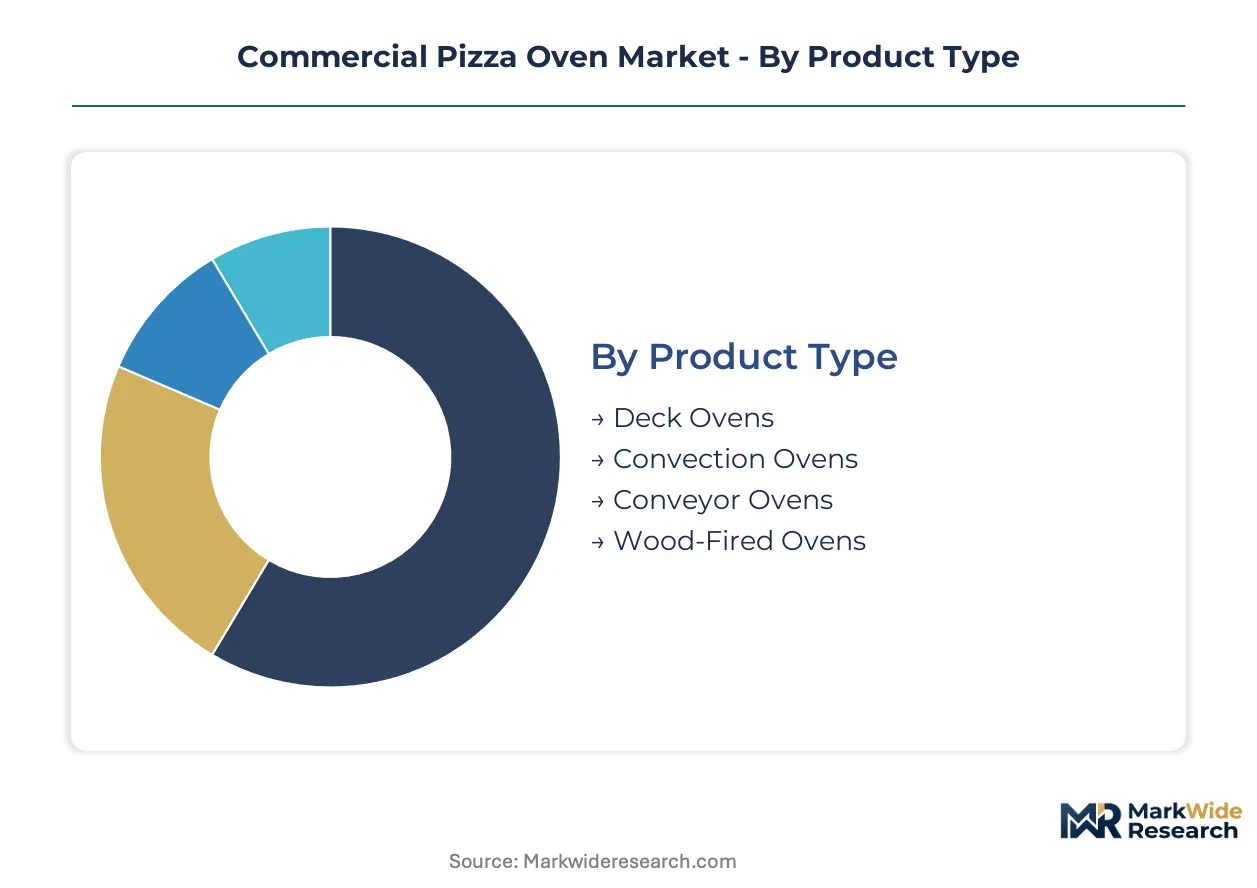
Deck ovens demand the highest upfront capital outlay due to refractory stone construction and multi-chamber configurations. Conveyor systems require substantial mechanical investment but lower per-unit labor costs.
- Deck Ovens:Refractory stone decks with independent temperature zones enable simultaneous baking of diverse products. Quick-service chains in Chicago and Los Angeles specify these for menu flexibility across thin-crust and deep-dish formats.
- Conveyor Ovens:Continuous belt systems with forced-air convection deliver 200+ pizzas hourly. High-volume airport concessions and stadium vendors prioritize these where labor minimization overrides energy costs.
- Convection Ovens:Fan-assisted heat circulation suits operators with space constraints and moderate throughput needs.
- Wood-Fired Ovens:Dome-shaped refractory chambers reach 900°F for 90-second Neapolitan bakes. Premium independent pizzerias absorb installation complexity for authenticity positioning.
Deck ovens absorb the bulk of installed capacity; conveyor ovens are expanding most quickly in high-throughput environments.
End User:
Volume concentration and replacement frequency diverge sharply across operator categories. Full-service establishments prioritize durability; mobile operators emphasize portability and ventilation flexibility.
- Restaurants:Multi-concept operators with pizza as a secondary menu category specify versatile deck or convection units. Casual dining chains in Texas and Florida are standardizing on electric configurations ahead of anticipated municipal fuel bans.
- Pizzerias:Single-purpose operators drive demand for authentic wood-fired and high-performance deck systems. Independent operators in New York City's outer boroughs sustain artisan equipment procurement despite regulatory pressure.
- Food Trucks:Compact convection and small-format deck ovens dominate this mobile segment where three-phase electrical access varies by municipality.
- Catering Services:Rental-oriented operators favor rapid-deployment conveyor and convection units with minimal site preparation requirements.
Restaurants command the largest equipment volume; food trucks are climbing the fastest as mobile foodservice permits proliferate.
Fuel Type:
Regulatory trajectory and infrastructure availability reshape total cost of ownership calculations. Electrification mandates in dense metropolitan markets are accelerating technology transitions.
- Electric:Resistance-element or infrared heating systems eliminate combustion ventilation requirements. Operators in California and New York municipalities are specifying these to preempt EPA particulate restrictions and local gas hookup moratoria.
- Gas:Natural gas and propane systems retain cost advantages in markets without carbon pricing. Independent pizzerias in Texas and Florida continue specifying gas deck ovens where infrastructure access remains unrestricted.
- Wood:Solid-fuel combustion with hardwood or compressed pellets delivers distinctive flavor profiles. Deployment concentrates in suburban and rural markets outside EPA non-attainment zones.
- Hybrid:Dual-fuel configurations combine gas or wood with electric backup elements. Multi-unit operators in transition markets specify these for operational flexibility against uncertain regulatory timelines.
Gas systems retain the majority of installed base; electric configurations are gaining share fastest as municipal mandates tighten.
Size:
Kitchen footprint constraints and peak-hour throughput requirements determine dimensional selection. Real estate costs in dense urban markets push toward compact configurations.
- Small:Single-deck or countertop units under 36 inches wide serve food trucks and ghost kitchen pods. Cloud kitchen operators in Dallas and Miami specify these for minimal ventilation footprint.
- Medium:Double-deck configurations balance throughput and space efficiency. Fast-casual chains with 1,500-2,500 square foot footprints standardize on this tier.
- Large:Triple-deck or extended conveyor systems serve high-volume quick-service locations. Airport and university dining contracts drive procurement of these units.
- Extra Large:Custom-configured multi-chamber installations accommodate 500+ hourly output. Stadium and entertainment venue operators specify these for event-driven demand spikes.
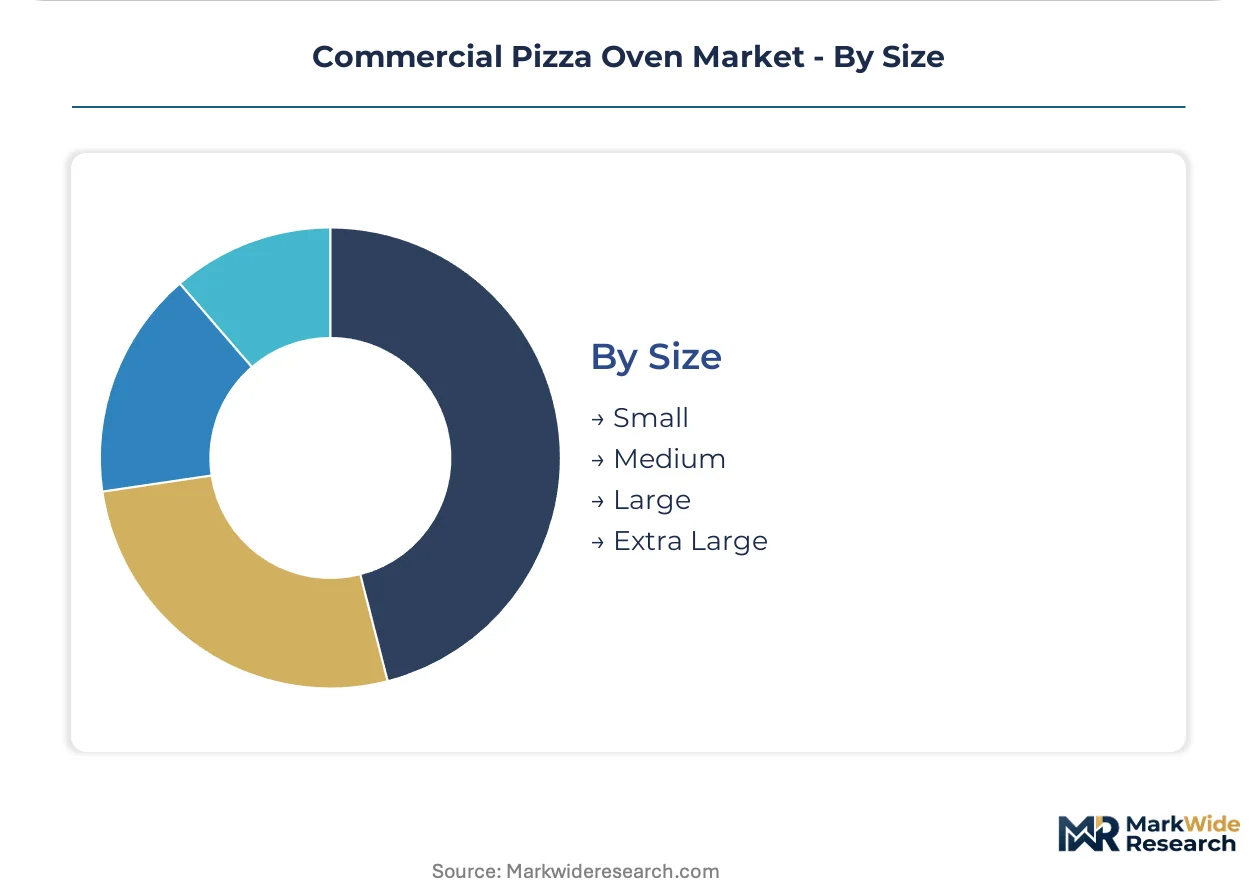
Medium-size equipment dominates current procurement; small-format systems are expanding most quickly in delivery-optimized kitchen formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones and federal tax incentives are concentrating commercial kitchen equipment procurement in designated urban redevelopment corridors across major metropolitan markets.
United States
Quick-service restaurant chains in Chicago and Los Angeles are accelerating electric oven deployments ahead of municipal gas hookup moratoria. The EPA's particulate emissions standards for urban airsheds are constraining wood-fired installations in dense metropolitan markets. Equipment procurement clusters most heavily in Opportunity Zone-designated districts of Houston and Phoenix where franchise development velocity exceeds national averages.
Italy
Artisan pizzeria exports and refractory material supply chains anchor demand in Emilia-Romagna and Campania manufacturing clusters. REACH compliance requirements for ceramic fiber insulation are extending product development timelines for EU-bound equipment. Naples and Modena industrial zones sustain specialized fabrication capacity for dome-construction components serving international markets.
Germany
Energy-intensive foodservice operators in Bavaria and North Rhine-Westphalia are retrofitting kitchens ahead of amended EU commercial cooking efficiency standards. The F-Gas Regulation is phasing down refrigerant-dependent technologies in hybrid oven cooling systems. Munich's equipment distributor networks are consolidating procurement for central European multi-unit operators.
United Kingdom
Ghost kitchen proliferation in Greater London is driving compact conveyor system demand for delivery-optimized footprints. The UK's net-zero building regulations are mandating electrification timelines for new commercial kitchen construction. Birmingham and Manchester logistics corridors are anchoring distribution hubs for European-manufactured oven imports.
Canada
Fast-casual expansion in Toronto and Vancouver is standardizing on medium-format electric deck configurations. Health Canada's commercial food equipment safety standards are creating certification bottlenecks for non-domestic manufacturers. Calgary and Edmonton energy-sector dining demand is sustaining high-throughput equipment procurement despite regional economic volatility.
Commercial Pizza Oven Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market segments. The vendor base organizes around three strategic archetypes: integrated foodservice equipment conglomerates with broad portfolio coverage, heritage stone-hearth specialists leveraging refractory engineering traditions, and regional fabricators serving price-sensitive installation markets. Competitive positioning consolidates through manufacturing scale advantages and certified compliance pathway acceleration.
Within the heritage specialist tier, Wood Stone Corporation and Marra Forni exemplify premium positioning through stone-hearth engineering lineage and Italian-imported refractory material sourcing respectively. Middleby Corporation occupies a position among diversified conglomerates with cross-category manufacturing scale. These three anchors represent distinct competitive vectors: authenticity-driven artisan positioning, imported material differentiation, and portfolio breadth across buyer tiers.
| Leading Market Players |
|---|
| Wood Stone Corporation |
| Morello Forni |
| Fontana Forni |
| Gozney |
| Forno Bravo |
| Mugnaini Imports |
| Marra Forni |
| Middleby Corporation |
| Californo |
| Others |
Value Chain & Pricing Dynamics
Refractory stone index volatility from Italian and Spanish quarries cascades through three-tier pricing across premium artisan installations, mid-market electric configurations, and economy-grade convection units. Procurement managers at multi-unit chains leverage volume commitments to compress landed costs while independent operators absorb full exposure to ceramic fiber freight surcharges.
Pricing Analysis
Margin tightening in mid-market electric tiers reflects municipal electrification mandates accelerating replacement cycles. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified stone-hearth systems from basic deck ovens and entry-level convection units. Price differentiation hinges on thermal mass engineering and ventilation integration complexity. Independent pizzerias exhibit highest price sensitivity; stadium concessionaires with captive volume demonstrate lowest.
Supply Chain Analysis
Direct-to-operator channels serve independent pizzerias and regional chains, while distributor networks handle multi-unit quick-service procurement. Manufacturing concentrates in Italy, the United States, and China. Production draws from Campania-sourced firebrick, Tennessee ceramic fiber, and Guangdong electronic controls. Single-source vulnerability in Italian refractory masonry creates project timeline risk. Distribution runs through foodservice equipment dealers and factory-direct specification teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial pizza oven sector is executing a technology-transition phase as electric and hybrid configurations displace gas-fired infrastructure under municipal decarbonization timelines.
For Market Incumbents: Anticipate accelerated electrification mandates by securing three-phase electrical certification pathways ahead of regulatory deadlines. Defensive consolidation through captive refractory supply agreements mitigates Italian import concentration risk. Channel control in Texas and Florida franchise corridors protects volume share against emerging equipment-as-a-service competitors. For New Entrants and Emerging Players: Begin with cloud kitchen conveyor deployments in Dallas and Miami where delivery-optimized footprints create specification whitespace. Ghost kitchen operators represent the most penetrable buyer archetype due to compressed decision cycles and minimal legacy equipment entrenchment. Go-to-market execution through bundled ventilation-oven packages accelerates landlord approval timelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional fabricators with established municipal certification relationships in California and New York. Long-term viability across the projection horizon rests on electrification-ready product portfolios and NSF compliance acceleration capabilities. Monitor municipal gas hookup moratoria announcements as inflection indicators for equipment replacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Fuel System Development | Gas-electric configurations capture operators facing uncertain municipal fuel bans. |
| Refractory Material Backward Integration | Captive Italian firebrick supply secures margin protection against freight volatility. |
| Equipment-as-a-Service Launch | Monthly payment models penetrate Texas and Florida franchise development corridors. |
| Smart Temperature Control Integration | IoT-enabled monitoring consolidates multi-unit operational oversight for chains. |
| NSF Certification Fast-Track Investment | Accelerated compliance pathways enable price differentiation in premium tiers. |
Study Parameters
Independent corroboration across foodservice equipment distributors, commercial kitchen contractors, and multi-unit restaurant operators underwrites the qualitative findings. Primary interviews engaged facilities management directors at quick-service chains, specification consultants for independent pizzerias, and HVAC integration specialists. Secondary validation drew from DOE efficiency standard filings, EPA airshed compliance databases, NSF certification registries, and trade customs data. Bottom-up equipment shipment analysis triangulates against top-down foodservice construction spending patterns.
Rate-of-change decomposition isolates volume drivers across product type, fuel configuration, end-user scale, and regional regulatory intensity. Segmentation modeling incorporates deck versus conveyor format, electric-gas-wood-hybrid fuel architecture, and metropolitan density tiers. CAGRs derive from fitted growth curves against historical replacement cycles and regulatory phase-in schedules. Forecast inputs include municipal electrification mandate calendars and cloud kitchen permit issuance velocity.
Underlying measurement precision varies by segment; electric configuration forecasts carry tighter precision than wood-fired artisan projections due to regulatory visibility. Forecasts reflect assumptions around municipal ban enforcement timing and refractory material supply continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Food & Beverage in Asia Market
Food Service
Meal Voucher Market
Food Service
Ship Catering Service Market
Food Service
Restaurant Takeout Market
Food Service
Peer-To-Peer Dining Market
Food Service
Pizza Oven Market
Food Service
United Kingdom Foodservice Market
Food Service
Gas Fryers Market
Food Service
Philippines Foodservice Market
Food Service
United Kingdom Full Service Restaurants Market
Food Service
Steam Tables and Food Well Market
Food Service
Plates Market
Food Service
New Zealand Foodservice Market
Food Service
Middle East and Africa Online Grocery Delivery Market
Food Service
Global Digital Grocery Market
Food Service
North America Online Grocery Delivery Market