
 Fast Food and Quick Service Restaurant Market | 2026-2036
Fast Food and Quick Service Restaurant Market Size, Share, and Industry Trends Forecast 2026-2036
Fast Food and Quick Service Restaurant Market Intelligence
A multi-sourcing approach for digital and delivery technology is shifting away from reliance on single, proprietary platforms, creating openings for specialized tech vendors. Major operators like McDonald's leverage global supply chain efficiencies to maintain cost leadership across its extensive network. Starbucks differentiates through its premium beverage offerings and strong brand loyalty programs. In contrast, Domino's Pizza competes on the strength of its vertically integrated digital ordering and delivery infrastructure.
Fast food and quick service restaurants (QSR) provide rapidly prepared meals served with minimal table service. Operations are defined by standardized menus, assembly-line production, and service times often under five minutes from order to fulfillment. The Drive-thru and Delivery service types represent the fastest-growing channels, overtaking traditional dine-in models in many markets. While Burgers and Sandwiches remain foundational product categories, demand from Professionals is driving innovation in healthier, convenient options.
Food safety and nutritional labeling standards, enforced by bodies like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA), govern menu composition. In India, regulations from the FSSAI impact ingredient sourcing and operational hygiene protocols. Navigating divergent regional consumer preferences for plant-based alternatives and sustainable packaging will be critical for future brand relevance and market share.
Market Dynamics
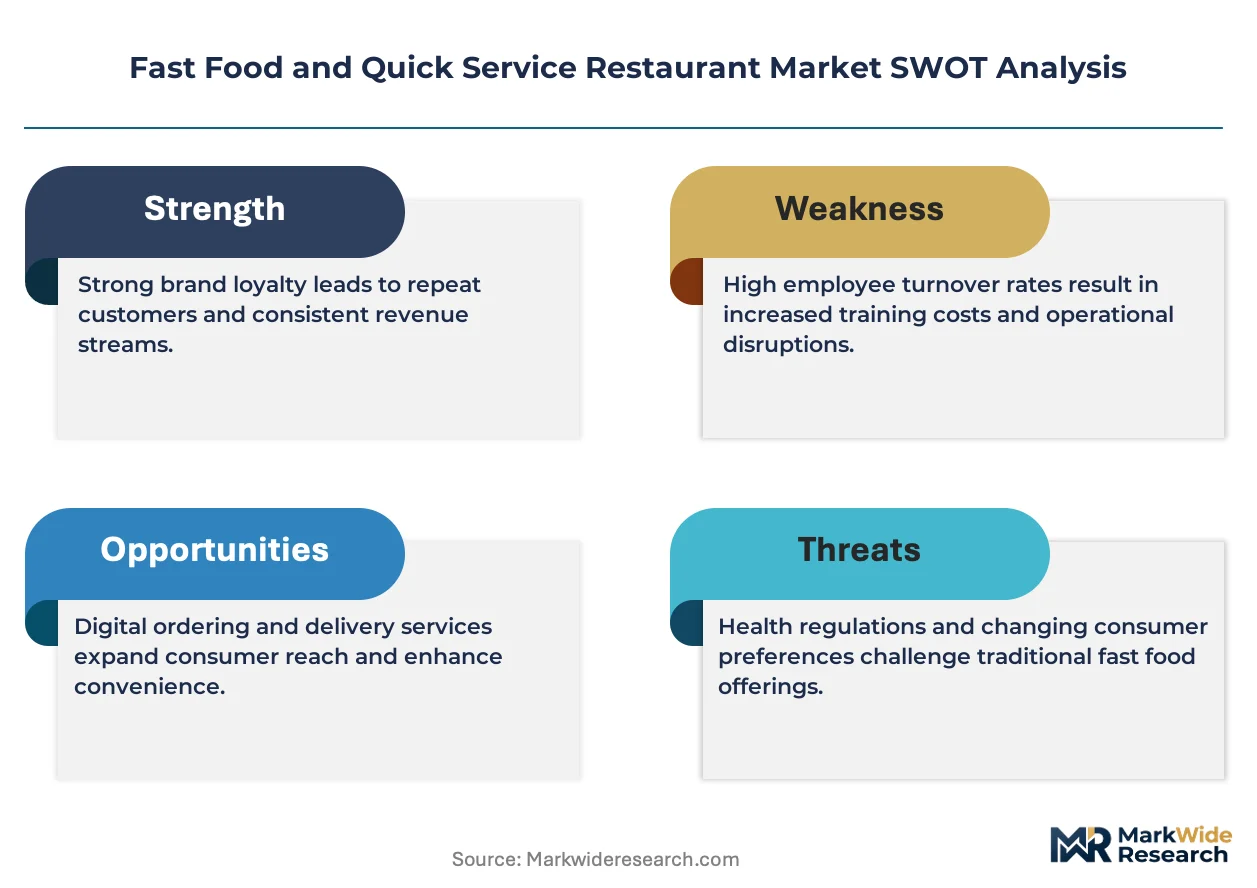
The central dynamic in the fast food and quick service restaurant market is the tension between the need for operational standardization to achieve cost leadership and the growing demand for menu localization and personalization driven by digital platforms.
Growth Catalysts
- Digital Platform Proliferation:The expansion of third-party delivery applications and proprietary digital ordering systems lowers the barrier to entry for consumers, increasing order frequency and reaching customers beyond the traditional walk-in and drive-thru channels.
- Urbanization in Emerging Economies:Rapid urbanization in countries like India creates a concentrated base of professionals and dual-income households who prioritize the convenience and speed offered by quick service restaurants for daily meals.
- Health and Wellness Demand:A growing focus on health is driving menu innovation, with operators introducing plant-based proteins, lower-calorie options, and transparent nutritional information to attract a wider, more health-conscious consumer segment.
Market Restraints
- Input Cost Volatility:Operators face significant margin pressure from unpredictable price fluctuations in core commodities, including poultry, beef, wheat, and cooking oils, which directly impact the cost of goods sold and menu pricing stability.
- Stringent Regulatory Scrutiny:Compliance with divergent and evolving food safety and labeling standards from bodies like the FSSAI in India and the FDA in the US creates operational complexity and increases costs for global brands.
- Intense Labor Market Competition:A persistent shortage of service-level staff, coupled with upward pressure on wages and benefits in major metropolitan areas, constrains store-level profitability and can impact service quality and speed.
Strategic Opportunities
- Plant-Based Menu Expansion:Developing and marketing dedicated plant-based product lines, beyond single burger offerings, presents an opportunity to capture a larger share of the mainstream flexitarian consumer market, not just vegans or vegetarians.
- Secondary City Penetration:Targeting expansion in less-saturated secondary and tertiary cities within high-growth regions like Southeast Asia offers access to new consumer bases with less direct competition compared to saturated metropolitan markets.
- Automation Technology Integration:Investing in AI-driven kitchen automation, predictive ordering systems, and robotic process automation for administrative tasks can significantly improve operational efficiency, reduce labor dependency, and enhance order accuracy over time.
Industry Challenges
- Supply Chain Consistency:Maintaining uniform ingredient quality, safety standards, and reliable supply across a geographically dispersed network of franchised and company-owned stores is a constant logistical challenge that directly impacts brand reputation.
- Legacy System Integration:The high capital cost and operational disruption associated with upgrading outdated point-of-sale and back-office systems to integrate with modern digital ordering and delivery platforms hinders technological agility for many operators.
- Sustainable Packaging Transition:Shifting to environmentally friendly packaging materials to meet consumer expectations and regulatory mandates presents significant sourcing, cost, and operational hurdles, particularly for maintaining food integrity during delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fast Food and Quick Service Restaurant Market |
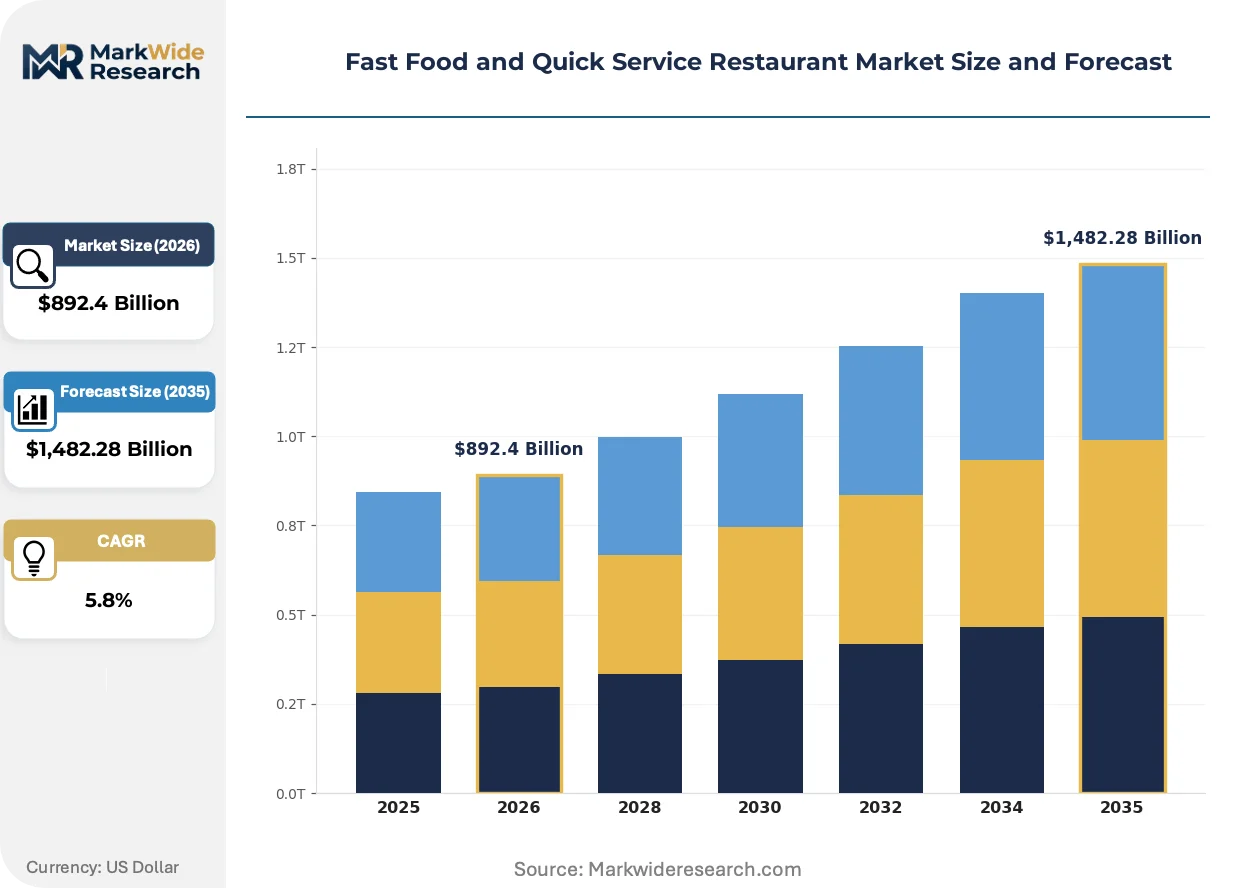
| Market Size in 2026 | $892.4 Billion |
| Market Size in 2035 | $1,482.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Burgers, Sandwiches, Salads, Beverages Service Type: Dine-in, Takeout, Drive-thru, Delivery Customer Type: Families, Students, Professionals, Tourists Price Tier: Premium, Mid-range, Budget, Value |
| Companies Covered | McDonald's, Starbucks, Subway, Taco Bell, Chick-fil-A, Burger King, KFC, Wendy's, Domino's Pizza, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fast Food and Quick Service Restaurant Market Strategic Shifts & Innovations
The market is defined by a dual pursuit of hyper-efficiency in operations and hyper-personalization in customer engagement. Technology is the primary enabler of both, allowing brands to optimize kitchen workflows while simultaneously tailoring marketing and loyalty programs.
Kitchen automation and cloud kitchen models are key technological advancements. These systems use software to manage order flow and optimize food preparation, often in off-site, delivery-focused facilities. Major chains and virtual-only brands are rapidly adopting this approach to expand their delivery footprint without the capital cost of traditional storefronts. This technology is decentralizing food production away from consumer-facing restaurants and toward distributed, logistics-optimized culinary hubs.
Regulations requiring menu calorie labeling and nutritional transparency, enforced by authorities like the US Food and Drug Administration (FDA) and advocated by the European Food Safety Authority (EFSA), are becoming a global standard. This forces operators to invest in supply chain traceability and product reformulation to meet disclosure requirements. The fast-casual segment is particularly affected, frequently leveraging its compliance with these health-focused mandates as a key point of brand differentiation.
Consumer ordering behavior is shifting away from loyalty to a single brand's app towards a more platform-agnostic approach that prioritizes convenience and value. This trend disrupts the direct-to-consumer model, forcing brands to compete for visibility and favorable placement on third-party delivery aggregators. This pattern is most pronounced among urban professional and Gen Z demographics in markets with a high density of competing delivery services.
Fast Food and Quick Service Restaurant Market Segmentation
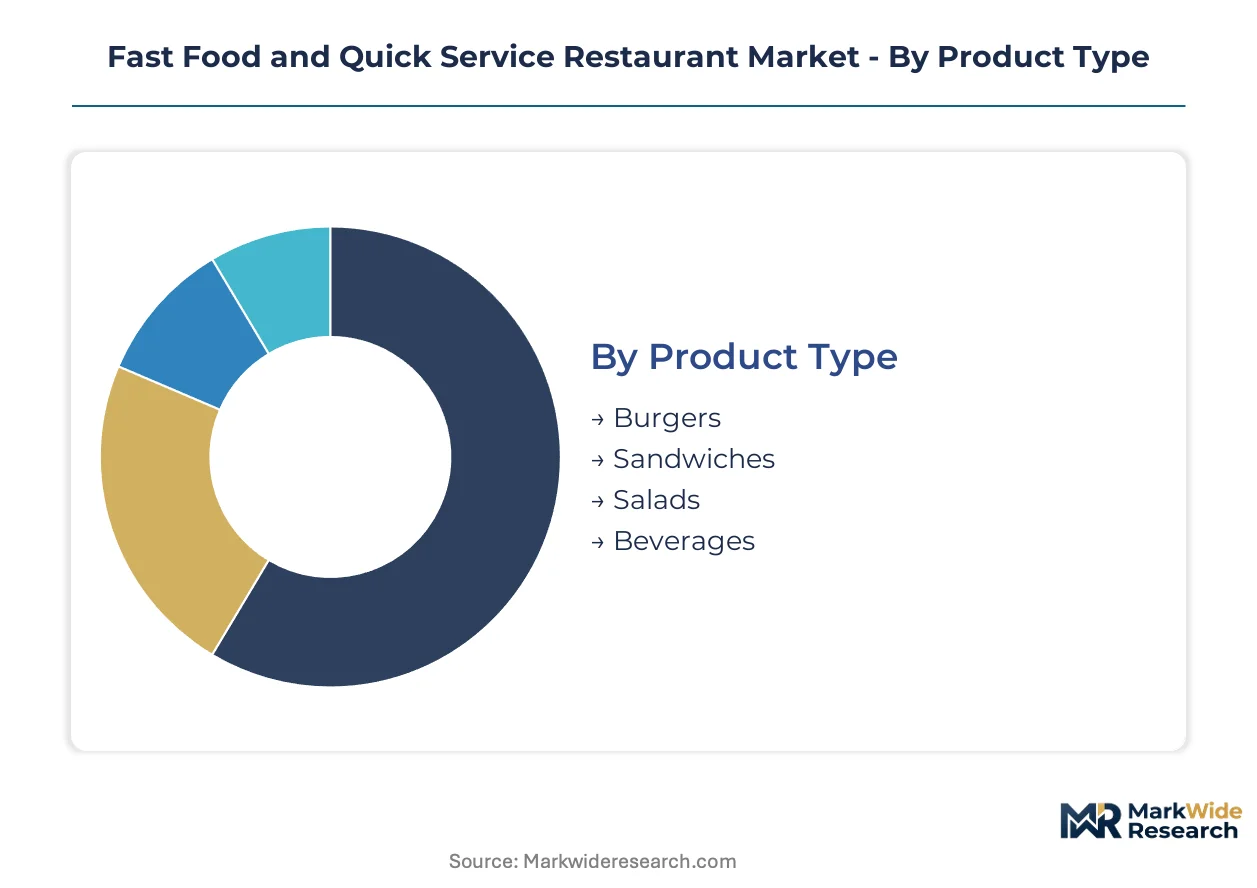
Understanding the Fast Food and Quick Service Restaurant market requires a detailed breakdown of its operational and consumer-facing dimensions. Segmentation provides clarity on the diverse offerings and service models that define competitive strategies. This analysis highlights key distinctions across product, service, customer, and price categories.
Product Type:
Consumer preference for core menu items versus supplementary offerings significantly differentiates purchasing behavior within the fast food and quick service restaurant sector.
- Burgers:Classic fast food staples, typically featuring ground meat patties, buns, and various toppings. Demand remains concentrated among a broad demographic seeking familiar, quick meal solutions, particularly in established markets like the US and Germany.
- Beverages:This category encompasses a wide array of drinks from carbonated soft drinks to specialty coffees and teas. Profitability is high, with operators leveraging these items to boost average transaction value and cater to diverse tastes across urban centers in India and Brazil.
- Sandwiches:Comprise various fillings between slices of bread or rolls, offering a versatile and often customizable meal.
- Salads:Feature fresh greens, vegetables, and proteins, appealing to health-conscious consumers seeking lighter options.
Volume sits with Burgers; growth tilts toward Beverages.
Service Type:
The operational model chosen by customers, driven by convenience and speed, dictates the primary service type utilized in quick service restaurants.
- Drive-thru:This channel allows customers to order and receive food from their vehicles, emphasizing speed and minimal interaction. It represents a significant portion of sales in suburban and commuter-heavy areas, with continued expansion in countries like Canada and Australia due to its efficiency.
- Delivery:Facilitated by third-party aggregators and proprietary apps, delivery brings food directly to the customer's location. This service type has experienced explosive growth in metropolitan areas such as London and Mumbai, driven by digital platform proliferation and urban density.
- Dine-in:Customers consume meals on-premises within the restaurant's seating area, offering a traditional social experience.
- Takeout:Orders are placed and picked up by customers for consumption elsewhere, prioritizing convenience for on-the-go meals.
Drive-thru and Delivery services are climbing the fastest, reflecting evolving consumer preferences for off-premise consumption.
Customer Type:
Demographic characteristics and lifestyle patterns define distinct customer segments, influencing menu choices and service expectations within the market.
- Professionals:This segment includes individuals working in urban and commercial centers, seeking quick, convenient, and often healthier meal options during work hours. Their demand for speed and digital ordering drives innovation in operational efficiency and menu development in cities like New York and Singapore.
- Students:Comprising university and school-aged individuals, this group prioritizes affordability, value, and social dining experiences. Their frequent patronage of quick service establishments near educational institutions contributes to consistent demand for budget-friendly meals in student hubs worldwide.
- Families:Represent households dining together, often seeking kid-friendly options, value meals, and comfortable dining environments.
- Tourists:Visitors to new locations, often looking for familiar brands, quick service, and convenient food options while exploring.
Professionals are gaining share fastest, driving demand for innovative and convenient meal solutions.
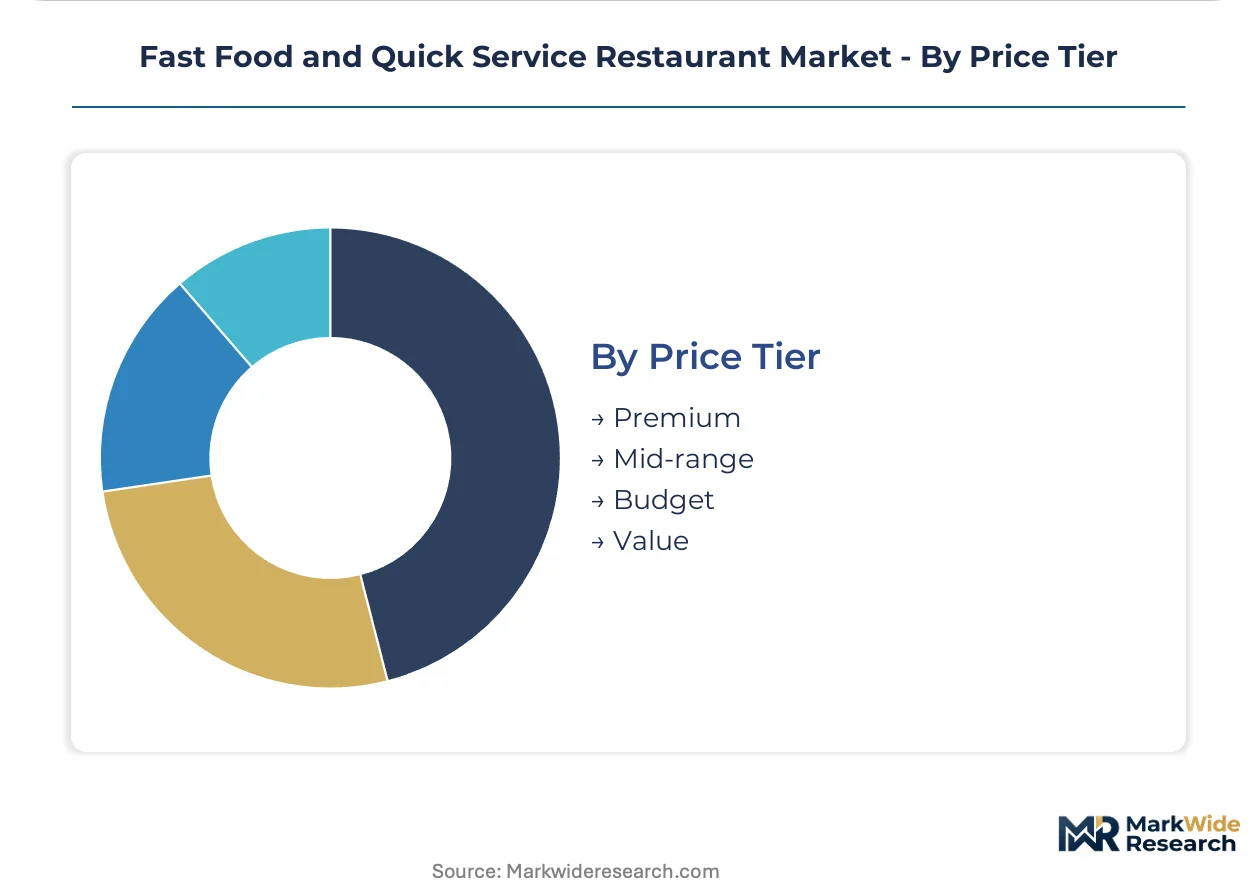
Price Tier:
Customer perceptions of affordability and perceived quality directly influence their selection across various price tiers offered by quick service restaurants.
- Mid-range:This tier balances affordability with perceived quality, offering a step up from basic budget options. It caters to a broad consumer base seeking good value without compromising on taste or variety, particularly prevalent in developed economies across Europe and North America.
- Value:Focused on providing the lowest possible price point, this tier emphasizes large portions or bundled offers for maximum cost-effectiveness. It appeals to price-sensitive consumers and is a key competitive battleground, especially in emerging markets and during economic downturns.
- Premium:Characterized by higher prices, this tier offers elevated ingredients, unique menu items, or enhanced dining experiences.
- Budget:Provides basic, inexpensive food options, often with limited customization, targeting highly price-conscious individuals.
The Value and Mid-range segments show the steepest expansion trajectory, reflecting diverse consumer spending habits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's substantial urban population anchors the fast food and quick service restaurant market, driving considerable demand. This demographic shift creates a concentrated base of professionals seeking convenient meal solutions. Regulatory frameworks and evolving consumer preferences shape market dynamics across diverse global regions.
India
India's rapid urbanization fuels a significant demand for quick service restaurants among professionals and dual-income households. FSSAI regulations impact ingredient sourcing and operational hygiene protocols across the country. Major metropolitan centers like Mumbai and Delhi witness high concentrations of digital ordering and delivery platform activity.
United States
The United States market demonstrates robust demand from urban professionals seeking both convenience and healthier options. The US Food and Drug Administration (FDA) enforces stringent food safety and nutritional labeling standards. Cities such as New York and Los Angeles are hubs for innovative plant-based menu expansions and digital ordering solutions.
Germany
German consumers show a steady preference for established fast food staples, particularly within the mid-range price tier. The European Food Safety Authority (EFSA) provides scientific advice on food safety, influencing menu composition. Urban areas like Berlin and Munich exhibit strong demand for both traditional and increasingly health-conscious quick service offerings.
Canada
Canadian market expansion is heavily driven by the efficiency of drive-thru channels, particularly in suburban and commuter-heavy regions. Health Canada provides guidelines for nutritional labeling and food safety, influencing menu development. Major cities such as Toronto and Vancouver are seeing increased adoption of digital delivery services.
Brazil
Brazil's growing middle class and urban centers contribute to significant demand for accessible and value-driven quick service meals. ANVISA, the country's health surveillance agency, regulates food safety and hygiene standards for restaurants. São Paulo and Rio de Janeiro serve as key markets for beverage sales and digital ordering platform growth.
Fast Food and Quick Service Restaurant Market Key Industry Players
Global majors compete with regional champions across operational efficiency and brand recognition in the fast food and quick service restaurant market. The market structure exhibits both consolidation among established players and fragmentation with numerous local brands. Three strategic archetypes include global scale operators, premium segment differentiators, and vertically integrated digital specialists. Dominant competitive moves involve extensive geographic expansion and continuous menu innovation.
Global scale operators like McDonald's and Burger King exemplify strategies focused on cost leadership and extensive network presence. These brands leverage global supply chain efficiencies to maintain competitive pricing across vast geographical footprints. Starbucks occupies a distinct position, anchoring the premium beverage segment through strong brand loyalty programs and unique product offerings. Domino's Pizza represents a vertically integrated digital specialist, competing on the strength of its proprietary ordering and delivery infrastructure that optimizes speed and customer convenience.
| Leading Market Players |
|---|
| McDonald's |
| Starbucks |
| Subway |
| Taco Bell |
| Chick-fil-A |
| Burger King |
| KFC |
| Wendy's |
| Domino's Pizza |
| Others |
Cost & Logistics Intelligence
Urban service-level staff concentration in metropolitan centers ties labor-cost differentials directly to fast food pricing-tier spreads. This dynamic forces operators to balance wage pressures with consumer expectations for value across diverse markets.
Pricing Analysis
Service bundling for combo meals and loyalty programs influences fast food pricing across tiers. The transactional pricing model dominates, with price differentiation driven by brand recognition and menu customization. Pricing softness stems from intense competition in the Value segment, exacerbated by input cost volatility. Professionals, seeking convenience and quality, exhibit the least price sensitivity, while the Value segment remains highly sensitive to minor price fluctuations.
Supply Chain Analysis
Single-source vulnerability sits with specific agricultural regions for key commodities like poultry, beef, and wheat. Raw material dependencies include cooking oils and various packaging materials, sourced globally but with significant processing in China and India. Commodity price volatility represents a primary structural risk, directly impacting operational margins. Distribution primarily runs through extensive franchised networks and third-party logistics providers, ensuring broad market reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fast food market operates as a cost-of-compliance story, where stringent FSSAI regulations in India create a barrier-to-entry moat for established, compliant players.
For Market Incumbents:Deploy global supply chain optimization to counter input cost volatility and maintain cost leadership against regional competitors. Consolidate digital ordering platforms to fend off fragmentation from third-party aggregators. Invest in kitchen automation to mitigate labor market competition, safeguarding service speed and operational efficiency against rising wage pressures.
For New Entrants and Emerging Players:Digital ordering platform integration offers new entrants a direct route to urban professionals seeking convenience. Target secondary cities in Southeast Asia with plant-based menus, leveraging a localized go-to-market strategy focusing on health. Penetrate underserved suburban markets by emphasizing drive-thru efficiency and family-friendly value propositions.
For Investors and Strategic Acquirers:Re-rating potential sits with tech-enabled QSR brands given the accelerating shift to off-premise consumption models. Acquisition targets include regional chains with strong digital infrastructure or specialized plant-based offerings. The long-term viability favors brands that effectively balance operational standardization with menu personalization. Watch for sustained growth in digital order frequency as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Ordering System Enhancement | Improving proprietary digital platforms strengthens direct customer relationships and loyalty programs. |
| Plant-Based Menu Diversification | Expanding plant-based offerings captures a broader flexitarian consumer base in urban markets. |
| Kitchen Automation Investment | Integrating AI-driven kitchen systems reduces labor dependency and enhances order accuracy. |
| Secondary City Expansion | Targeting less saturated markets in high-growth regions unlocks new customer segments. |
| Sustainable Packaging Adoption | Transitioning to eco-friendly packaging meets evolving consumer expectations and regulatory mandates. |
Research Approach
Independent corroboration across industry reports, company financial statements, and regulatory filings underwrites the qualitative findings. This study combined primary interviews with QSR executives, supply chain managers, and marketing directors, alongside secondary validation from trade associations and academic research. Bottom-up data aggregation and top-down market sizing provided comprehensive triangulation.
Rate-of-change decomposition modeled market evolution across the analysis window, projecting Compound Annual Growth Rates for each segment. Segmentation dimensions included product type, service type, customer type, price tier, and regional market penetration. Forecast inputs included urbanization rates, digital platform adoption, and commodity price trends, informing future demand scenarios.
Inputs from major QSR operators and food safety authorities were available through the study window; gaps in granular consumer spending data introduce uncertainty bands. Forecasts reflect underlying assumptions regarding economic stability and technological adoption, alongside regulatory shifts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Healthy Takeout Market
Food Service
Food Service Market
Food Service
Mexico Foodservice Market
Food Service
Gourmet Street Food Market
Food Service
Europe Online Grocery Market
Food Service
Europe Pizza Oven Market
Food Service
Restaurants in Belgium Market
Food Service
Switzerland Food Service Market
Food Service
China Food Service Market
Food Service
Electric Tiffin Market
Food Service
Commercial Steam Table Market
Food Service
Bar Refrigeration Market
Food Service
New Zealand Foodservice Market
Food Service
Germany Foodservice Market
Food Service
Cambodia Foodservice Market
Food Service
Food Away from Home Market