
 Vacuum Flask Market | 2026-2036
Vacuum Flask Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Flask Market Outlook
REACH compliance is shifting the cost-of-entry calculus for European vacuum flask manufacturers by mandating full material disclosure across stainless steel and silicone supply chains. Hydro Flask leverages its vertically integrated domestic manufacturing to absorb these certification costs without margin erosion. Zojirushi Corporation anchors its premium positioning through proprietary vacuum insulation technology developed at its Osaka R&D center. Haers Vacuum Containers Co., Ltd. competes on manufacturing scale from its Zhejiang production base, supplying private-label brands across Southeast Asia.
A vacuum flask is a double-walled vessel with an evacuated air gap between inner and outer chambers, typically constructed from 18/8 stainless steel with copper or aluminum reflective layers, designed to minimize conductive and radiative heat transfer for temperature retention exceeding 12 hours. Its primary commercial purpose spans portable beverage storage, food preservation for outdoor activities, and laboratory thermal management. Stainless steel material grades command the dominant margin pool due to durability premiums and recyclability credentials under EU circular economy frameworks. Insulated bottles lead volume across product types, while travel mugs represent the fastest-growing category as hybrid work patterns normalize commuter-oriented consumption. Online retail channels are displacing specialty stores in customer acquisition efficiency, though supermarkets retain impulse-purchase dominance for family-oriented SKUs.
The US FDA regulates food-contact surfaces for vacuum flasks sold with consumable storage claims, while China's SAMR enforces GB standards for stainless steel alloy composition in domestic manufacture. Japan's METI energy-efficiency labeling program extends to thermal retention performance claims, creating a three-jurisdiction compliance mosaic for multinational suppliers. Stakeholders must monitor evolving extended-producer-responsibility frameworks in Europe and North America, as these will determine whether refurbishment and recycling infrastructure becomes a competitive differentiator or a compliance burden.
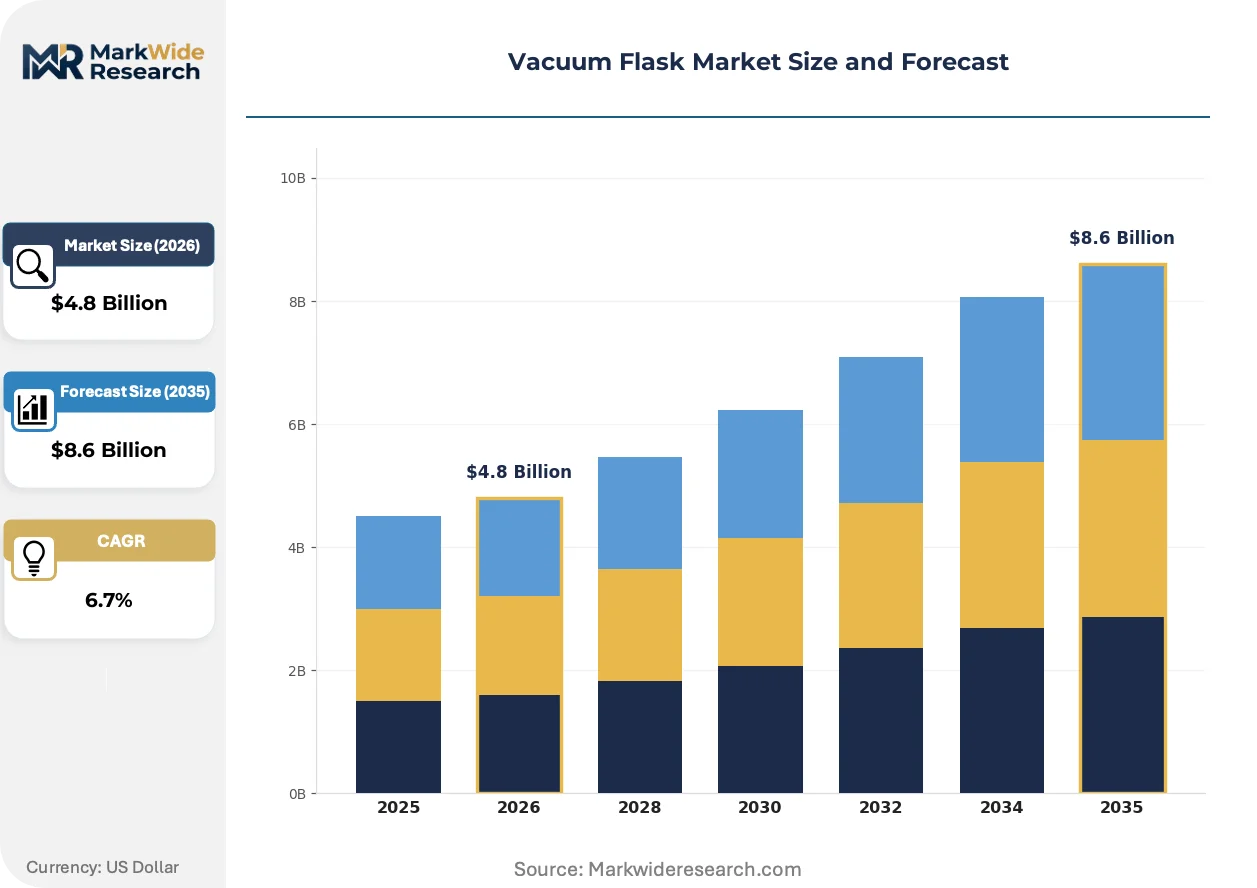
Market Dynamics
Stainless steel fabrication capacity in China's Yangtze River Delta is concentrating supply-side power, while REACH compliance in Europe and FDA food-contact regulations in the United States are fragmenting demand into jurisdiction-specific certification tiers.
Growth Catalysts
- Outdoor recreation procurement:North American national parks are expanding durable hydration gear acquisition programs, pulling vacuum flask volumes into institutional channels previously served by disposable alternatives.
- F-Gas Regulation tailwind:The EU's phase-out of hydrofluorocarbon-based insulation alternatives is redirecting specification engineers toward vacuum insulation technology for thermal management applications.
- 18/8 stainless steel recyclability:Circular economy frameworks under EU Green Deal implementation are embedding recyclability premiums into public procurement criteria, favoring double-walled steel construction over polymer alternatives.
Market Restraints
- Raw material concentration:Nickel and chromium supply volatility from Indonesian and South African mining corridors creates input cost instability for 18/8 stainless steel shell production.
- Regional manufacturing lock-in:Zhejiang province's dominance in vacuum chamber sealing equipment constrains geographic diversification of fabrication capacity.
- Copper reflective layer substitution:Aluminum deposition technology remains thermally inferior for radiative heat transfer suppression, limiting cost-down pathways in premium product tiers.
Strategic Opportunities
- Hybrid work commuter channels:Travel mug formats for rail and bus transit systems in Germany and Japan represent underpenetrated replacement cycles against disposable cup consumption.
- Laboratory thermal management:Biopharma cold-chain sample transport is converging with IoT temperature logging, creating specification openings for connected vacuum flask systems.
- Extended producer responsibility frameworks:France and California advance refurbishment infrastructure mandates that reward modular designs with replaceable seals and valves.
Industry Challenges
- Vacuum chamber sealing technician scarcity:Precision helium leak detection and electron beam welding skills concentrate in Osaka and Ningbo, constraining new facility ramp rates.
- Multi-jurisdiction certification parallelism:Simultaneous FDA, SAMR GB standard, and METI energy-efficiency labeling timelines extend product launch windows by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Flask Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Bottles, Food Containers, Drinkware, Travel Mugs Material: Stainless Steel, Glass, Plastic, Silicone End User: Outdoor Enthusiasts, Students, Professionals, Families Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Others |
| Companies Covered | Hydro Flask, Tiger Corporation, Thermos LLC, Contigo, YETI Coolers, LLC, Zojirushi Corporation, Haers Vacuum Containers Co., Ltd., Klean Kanteen, Stanley, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Flask Market Strategic Shifts
Copper-coated stainless steel inner chambers are consolidating thermal performance tiers, while regulatory disclosure requirements and direct-to-consumer channel migration are compressing traditional distribution hierarchies.
Electropolished 18/8 stainless steel with copper vacuum deposition is unifying previously separate premium and standard product tiers by delivering twelve-plus hour retention at mid-market price points. Outdoor equipment retailers in the United States and Japan are adopting this specification as a baseline, collapsing the historical three-tier performance segmentation into two practical categories.
REACH full material disclosure mandates are forcing silicone gasket and polypropylene lid suppliers to document supply chain provenance down to smelter level for European market access. Manufacturers with captive stainless steel rolling mills are absorbing documentation costs internally, while outsourced fabricators face margin compression from third-party certification fees.
Specialty outdoor retailers are losing share to brand-owned e-commerce storefronts and Amazon marketplace direct fulfillment, particularly for replacement lid and seal accessory sales. This channel rotation is most pronounced in the United States and United Kingdom, where commuter-oriented travel mug purchasers research thermal retention specifications through video review content before purchase.
Vacuum Flask Market Segmentation
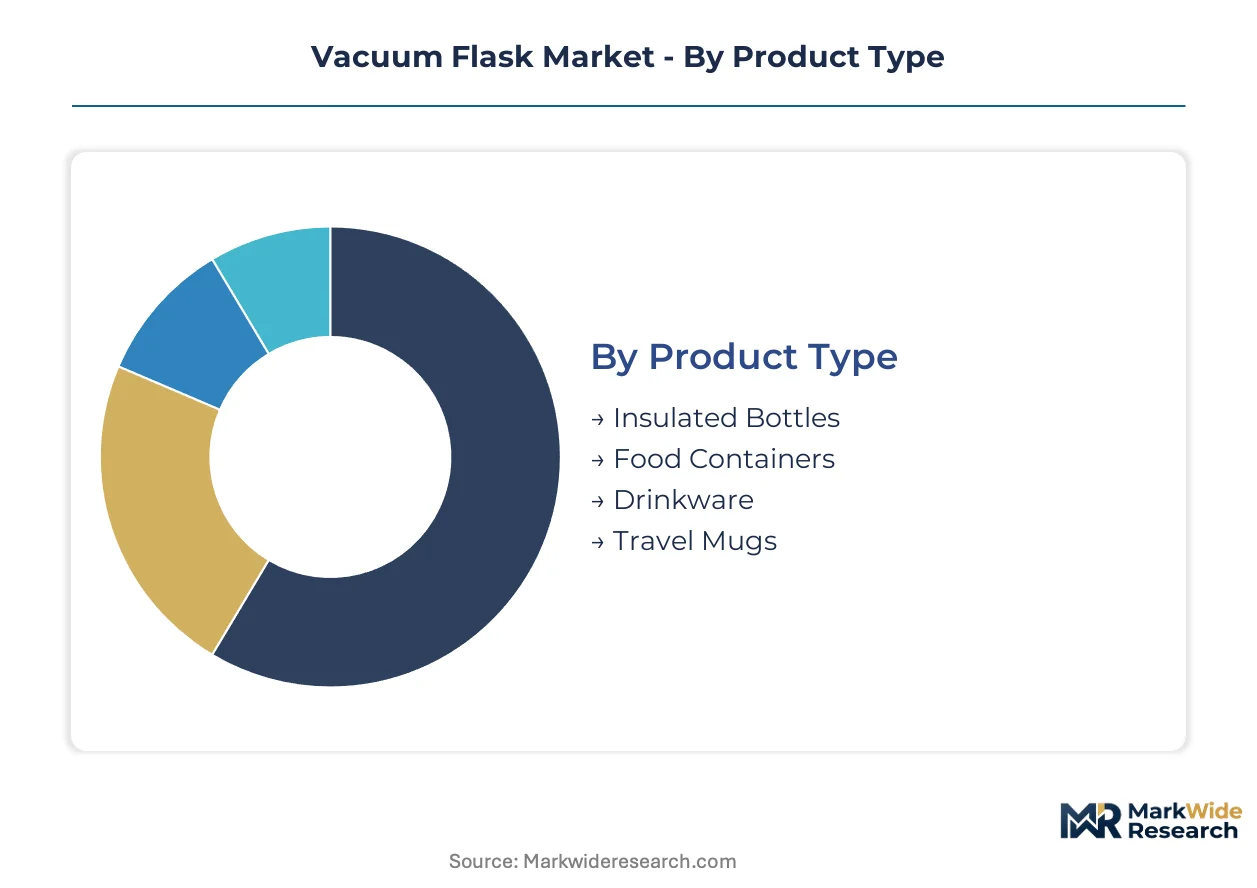
Vacuum flask segmentation reveals how material certification tiers and channel economics fragment addressable demand. Product architecture and procurement channel selection determine margin capture and compliance burden simultaneously.
Product Type:
Volume concentration sits with everyday hydration formats, while premium expansion concentrates in commuter-oriented designs.
- Insulated Bottles:Double-walled 18/8 stainless steel construction with copper vacuum deposition dominates institutional procurement from North American national parks. Outdoor recreation programs specify these for durability under extreme temperature cycling.
- Travel Mugs:Narrow-diameter designs with leak-proof sealing mechanisms are climbing the fastest as hybrid work patterns normalize rail and bus commuter consumption in Germany and Japan.
- Food Containers:Wide-mouth vacuum chambers with stackable nesting profiles target meal-prep users seeking thermal retention beyond six hours.
- Drinkware:Tumbler formats with splash-resistant lids capture impulse replacement cycles through supermarket checkout placement.
Today's leader: Insulated Bottles. Tomorrow's challenger: Travel Mugs.
Material:
Cost tier stratification separates certified recyclability premiums from disposable alternatives.
- Stainless Steel:18/8 grade with electropolished inner surfaces commands the dominant margin pool through EU circular economy procurement criteria. REACH full material disclosure mandates favor mills with captive smelter documentation.
- Glass:Borosilicate double-walled construction with silicone sleeve protection targets laboratory thermal management and premium home use where metal taste sensitivity matters.
- Silicone:Flexible, collapsible designs for ultralight backpacking sacrifice thermal retention for packability in weight-constrained applications.
- Plastic:Copolyester and Tritan variants occupy entry price points but face displacement from F-Gas Regulation tailwinds favoring vacuum insulation over polymer alternatives.
Stainless Steel captures margin. Glass gains specification in controlled environments.
End User:
Application context determines performance tier selection and replacement frequency.
- Outdoor Enthusiasts:Backpacking and climbing users prioritize weight-to-retention ratios, driving demand for titanium-laminated vacuum chambers and integrated carabiner attachment points.
- Professionals:Commuter rail users in metropolitan Japan and Germany specify travel mug formats with one-hand operation and thermal logging compatibility.
- Families:Multi-liter food containers with portion-divided interiors target school lunch and picnic applications through supermarket seasonal promotions.
- Students:Price-sensitive volume concentrated in private-label insulated bottles through campus bookstore and online retail channels.
Outdoor Enthusiasts anchor premium tier. Professionals drive connected-feature adoption.
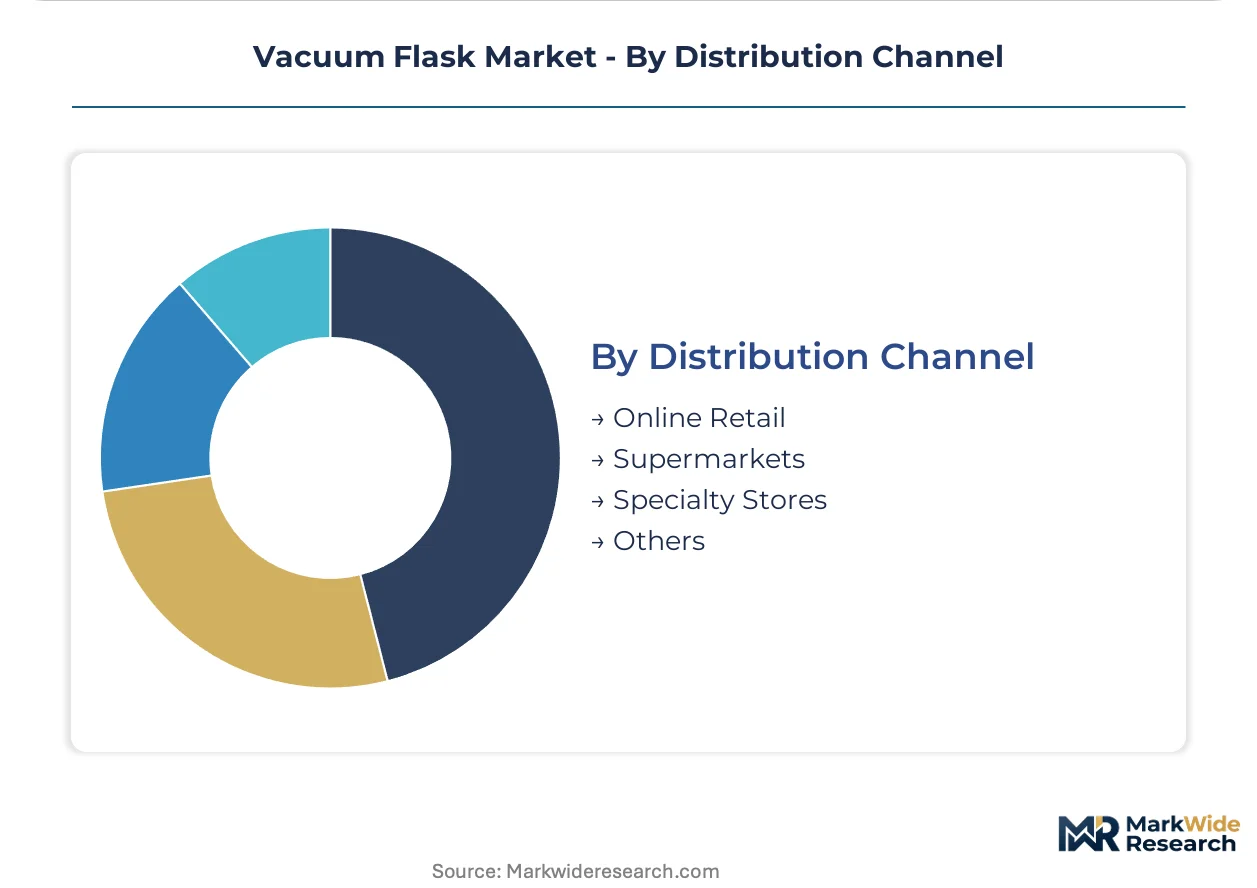
Distribution Channel:
Customer acquisition economics favor direct fulfillment for replacement parts while supermarkets retain family-SKU dominance.
- Online Retail:Amazon marketplace and brand-owned storefronts displace specialty retailers for replacement lid and seal accessory sales, particularly in the United States and United Kingdom.
- Supermarkets:Impulse-purchase placement for family-oriented SKUs retains volume concentration through seasonal back-to-school and holiday promotional windows.
- Specialty Stores:Outdoor equipment retailers in the United States and Japan consolidate around electropolished copper-coated specifications as baseline performance tiers.
- Others:Institutional procurement channels serving North American national parks and European public sector contracts operate on extended tender timelines with recyclability scoring.
Online Retail captures accessory margin. Supermarkets defend volume placement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision helium leak detection technicians cluster in Osaka and Ningbo, anchoring fabrication quality standards that diffuse through multinational supply chains. These workforce concentrations determine where vacuum chamber sealing capacity expands and where new facility ramp rates stall.
United States
National park outdoor recreation procurement programs specify durable hydration gear for institutional channels, pulling vacuum flask volumes away from disposable alternatives. The FDA enforces food-contact surface regulations for consumable storage claims, extending product launch timelines. Fabrication activity concentrates in Pacific Northwest manufacturing zones where vertically integrated producers absorb certification costs.
China
Stainless steel fabrication capacity dominates the Yangtze River Delta manufacturing cluster, supplying private-label brands across Southeast Asia. The SAMR enforces GB standards for stainless steel alloy composition in domestic manufacture. Zhejiang province houses vacuum chamber sealing equipment production that constrains geographic diversification of fabrication capacity.
Germany
Hybrid work patterns normalize commuter-oriented consumption for rail and bus transit systems, driving travel mug specification. The EU F-Gas Regulation phases out hydrofluorocarbon-based insulation alternatives, redirecting engineers toward vacuum insulation technology. Industrial procurement in Baden-Württemberg favors circular economy recyclability credentials under EU Green Deal implementation.
Japan
METI energy-efficiency labeling programs extend to thermal retention performance claims, creating compliance requirements for multinational suppliers. Osaka-based R&D centers develop proprietary vacuum insulation technology that anchors premium positioning. Kanto region commuter rail users specify travel mug formats with one-hand operation capabilities.
France
Extended producer responsibility frameworks advance refurbishment infrastructure mandates that reward modular designs with replaceable seals. ECHA REACH compliance mandates full material disclosure across stainless steel and silicone supply chains. Île-de-France procurement channels operate on extended tender timelines with recyclability scoring criteria.
Vacuum Flask Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across certification-tiered market segments. The vendor base separates into three strategic archetypes: vertically integrated domestic manufacturers absorbing regulatory documentation costs, scale-driven private-label suppliers from concentrated fabrication clusters, and premium-tier technology developers with captive R&D facilities. Dominant competitive moves include backward integration into stainless steel rolling capacity and strategic partnerships with national park procurement channels.
Among Osaka-based technology developers, Zojirushi Corporation exemplifies the premium-tier archetype through proprietary vacuum insulation development. Haers Vacuum Containers Co., Ltd. anchors the scale-driven private-label segment from its Zhejiang production base. Hydro Flask represents vertically integrated domestic manufacturing capacity that internalizes REACH certification costs without margin erosion.
| Leading Market Players |
|---|
| Hydro Flask |
| Tiger Corporation |
| Thermos LLC |
| Contigo |
| YETI Coolers, LLC |
| Zojirushi Corporation |
| Haers Vacuum Containers Co., Ltd. |
| Klean Kanteen |
| Stanley |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap fabricators in Zhejiang province anchor supply-side discipline through multi-generational control of vacuum chamber sealing equipment, translating captive production knowledge into pricing power that resists margin erosion from REACH documentation mandates and nickel price volatility.
Pricing Analysis
Accessory bundling versus unbundled hardware sales splits the market into two pricing logics. Premium brands command three-tier pricing structure across premium, standard, and economy levels through certification grade differentiation and after-sales service inclusion. Cost compression in private-label tiers intensifies because aluminum reflective layer substitution remains thermally inferior. Institutional procurement from North American national parks exhibits lowest price sensitivity; students through campus bookstore channels show highest.
Supply Chain Analysis
Hub-and-spoke distribution patterns radiate from Yangtze River Delta regional distribution centers into Southeast Asian retail networks. Manufacturing concentrates in China, Japan, and United States fabrication zones. Raw material flows draw from Indonesian nickel corridors and South African chromium deposits. Single-source vulnerability concentrates in Zhejiang vacuum chamber sealing equipment production. Distribution runs through brand-owned e-commerce storefronts and Amazon marketplace direct fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance costs in Europe diverge from SAMR GB standard enforcement in China, creating margin capture opportunities for manufacturers with dual-jurisdiction certification infrastructure.
For Market Incumbents: Hedge against aluminum reflective layer substitution limits by deepening captive R&D in copper vacuum deposition technology. Absorb REACH documentation costs through backward integration into stainless steel rolling capacity rather than outsourcing to third-party mills. Defend channel position against direct-to-consumer migration by controlling replacement lid and seal accessory supply. For New Entrants and Emerging Players: Launch via Amazon marketplace direct fulfillment targeting travel mug formats for German and Japanese commuter rail systems. White-space sits with connected-feature vacuum flasks for biopharma cold-chain sample transport converging with IoT temperature logging. Penetrate through modular designs with replaceable seals that satisfy France and California extended producer responsibility mandates. For Investors and Strategic Acquirers: Valuations sit cheapest among scale-driven private-label suppliers from Zhejiang production clusters lacking captive R&D facilities. Long-term viability favors vertically integrated domestic manufacturers with in-house stainless steel rolling and dual-jurisdiction certification timelines already compressed. Watch helium leak detection technician wage inflation in Osaka and Ningbo as inflection indicator for new facility ramp rate constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Rolling | Captive supply of 18/8 grade absorbs REACH documentation costs without margin erosion. |
| Modular Design with Replaceable Seals | France and California refurbishment infrastructure mandates reward component-level serviceability. |
| IoT Temperature Logging Integration | Biopharma cold-chain specifications open premium positioning beyond commodity hydration. |
| Dual-Jurisdiction Certification Parallelism | Simultaneous FDA and METI timelines compress product launch windows against competitors. |
| Direct-to-Consumer Channel Expansion | Brand-owned storefronts capture replacement accessory margin from specialty retailers. |
Study Parameters
Coverage spans United States, China, Germany, Japan, and France, with primary inputs from each market. The analysis combines primary interviews with supply chain directors, vacuum chamber sealing technicians, national park procurement officers, and e-commerce channel managers with secondary validation from SAMR GB standard filings, FDA food-contact surface registrations, METI energy-efficiency labeling databases, and EU F-Gas Regulation implementation reports. Bottom-up fabrication capacity estimates triangulate against top-down retail audit data.
Granularity-level modeling operates at product type, material grade, end-user archetype, and distribution channel dimensions. Volume and value outputs across the analysis window derive from segment-level CAGRs applied to base-year installed base estimates. Forecast inputs incorporate nickel and chromium price volatility assumptions, REACH disclosure timeline compression, and hybrid work commuter pattern normalization.
Forecast precision tightens around the base case; tail outcomes carry wider variance under raw material supply disruption or extended-producer-responsibility mandate acceleration. Outputs reflect documented assumptions regarding vacuum insulation technology substitution rates and channel migration velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Latin America Online Grocery Delivery Market
Food Service
Saudi Arabia Out of Home (OOH) Delivery Market
Food Service
Beverage Coaster Market
Food Service
Europe Inflight Catering Market
Food Service
Smoker Grill Market
Food Service
Clear Ice Maker Market
Food Service
India Quick Service Restaurant Market
Food Service
Countertop Pressure Fryer Market
Food Service
Cloud Kitchen Market
Food Service
Commercial Griddle Market
Food Service
Commercial Tableware Services Market
Food Service
Aquarium Protein Skimmers Market
Food Service
Africa Foodservice Market
Food Service
Rotisseries Market
Food Service
United States Food Truck Market
Food Service
United Kingdom Foodservice Market