
 Global Cafe and Bars Market | 2026-2036
Global Cafe and Bars Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cafe and Bars Market Foresight
The capability gap between asset-heavy real estate players and digitally native operators is rotating competitive dynamics across the industry. Starbucks Corporation sustains premium positioning through controlled lease portfolios in high-footfall districts. Luckin Coffee leverages algorithmic store placement and mini-format kitchens to dominate China's urban density. McDonald's Corporation anchors its McCafé extension within existing drive-thru infrastructure, competing on throughput rather than ambiance.
Cafes and bars constitute licensed foodservice establishments where beverage preparation combines controlled extraction parameters—water temperature, pressure profiles, and grind granularity for coffee; fermentation control and hop dosing for craft beer—with ambient hospitality design to create third-place social environments. Chain cafes capture economies in procurement and training, while microbreweries command local margin pools through batch-scale exclusivity and direct taproom distribution. The service model dimension shows online ordering and delivery-only formats displacing traditional table service as labor costs and real estate premiums reshape unit economics.
FDA food safety codes, EU F-Gas Regulation on refrigeration systems, and local alcohol licensing boards collectively shape operational compliance and capital requirements for new entrants. China's SAMR enforces foodservice labeling standards that affect menu transparency and ingredient sourcing disclosure across chain networks. Stakeholders must monitor how carbon accounting rules under CSRD and emerging packaging extended-producer-responsibility frameworks redefine cost structures before committing to multi-year store expansion programs.
Market Dynamics
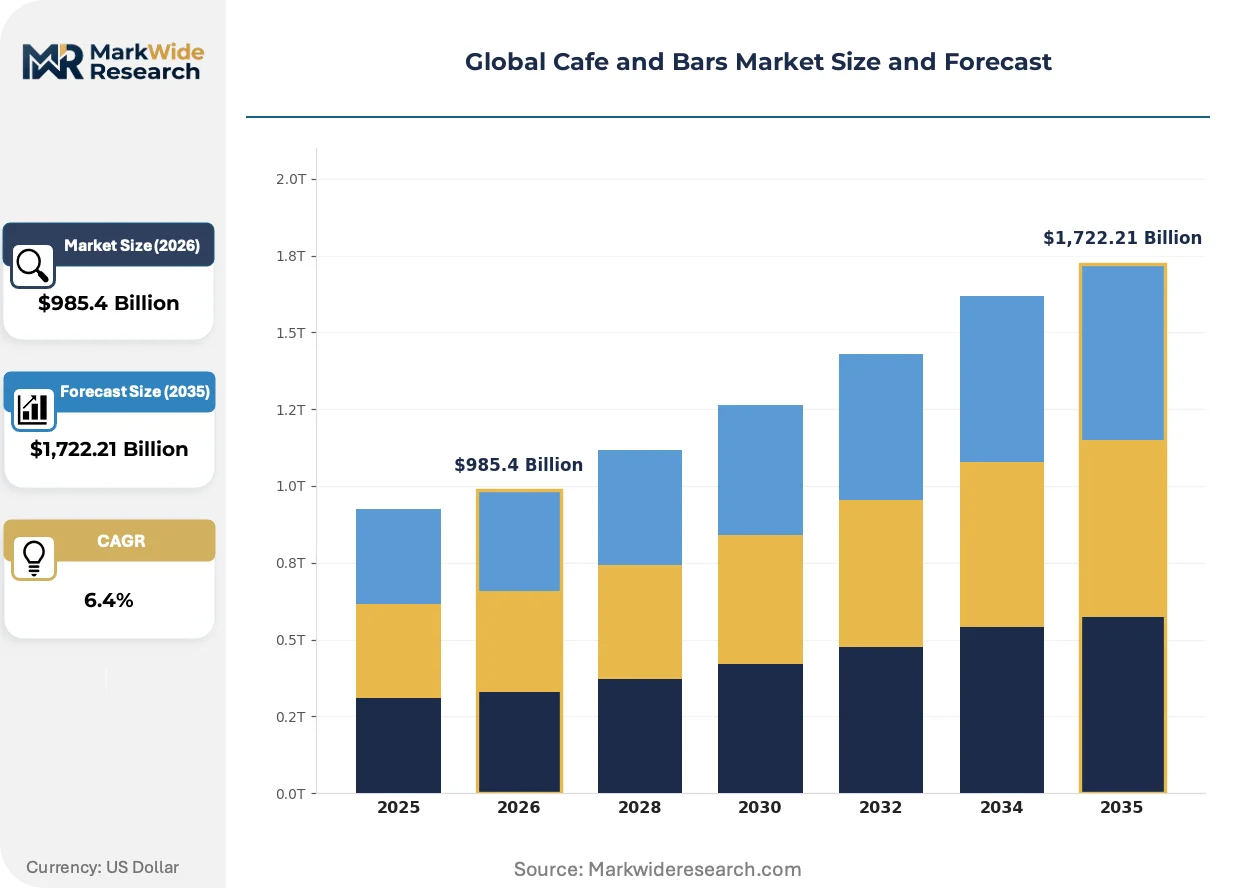
Algorithmic store placement and mini-format kitchens are compressing traditional real estate premiums across licensed beverage premises. The EU Green Deal's packaging mandates and China's SAMR labeling standards are simultaneously raising compliance thresholds while digital-native operators exploit lower fixed-cost structures.
Growth Catalysts
- EU F-Gas Regulation:Refrigeration retrofit mandates accelerate equipment replacement cycles across licensed premises in Germany, France, and Italy. Operators modernizing cooling systems unlock energy cost reductions that improve unit economics.
- Urban density clustering:Tier-one Chinese cities demonstrate how algorithmic site selection maximizes capture rates per square meter. Dense store networks reduce delivery radius costs and build brand recognition through physical presence.
- Controlled extraction automation:Precision brewing and espresso systems standardize beverage quality across distributed locations. Chain operators deploy these technologies to reduce training burdens and waste from inconsistent preparation.
Market Restraints
- Arabica price volatility:Climate-driven supply fluctuations in Brazil and Colombia transmit directly to cost-of-goods for coffee-focused operators. Hedging instruments remain underutilized among mid-scale chains.
- CSRD carbon accounting:Extended producer responsibility frameworks in the European Union require granular supply-chain disclosure. Compliance infrastructure demands capital that crowds out store expansion budgets.
- Non-alcoholic substitutes:Functional beverages and adaptogenic drinks capture occasions previously dominated by craft beer and cocktail consumption. Taproom operators face margin compression as consumption occasions fragment.
Strategic Opportunities
- India's FSSAI modernization:Simplified licensing pathways for organized foodservice create entry channels for international formats. Urban professionals in Mumbai and Bangalore demonstrate willingness-to-pay for third-place environments.
- Drive-thru beverage-only formats:Dedicated pickup lanes and mobile-order integration minimize labor per transaction. McDonald's McCafé extension demonstrates throughput economics that pure-play operators can replicate.
- Packaging innovation convergence:Biodegradable cup technologies and deposit-return schemes align with EU Green Deal targets. Early adopters capture regulatory goodwill and municipal procurement preferences.
Industry Challenges
- Barista certification pipelines:Specialty coffee associations train fewer practitioners than chain expansion plans require. Wage competition from adjacent hospitality segments intensifies retention costs.
- Legacy POS integration:Mobile-ordering platforms and kitchen display systems demand API compatibility with decade-old infrastructure. Fragmented vendor ecosystems prolong deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cafe and Bars Market |
| Market Size in 2026 | $985.4 Billion |
| Market Size in 2035 | $1,722.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Outlet Type: Independent Cafes, Chain Cafes, Cocktail Bars, Wine Bars, Microbreweries Service Model: Table Service, Counter Service, Drive-Thru, Online Ordering, Delivery Only Customer Demographic: Young Adults, Working Professionals, Tourists, Students, Retirees Beverage Offering: Espresso-Based Drinks, Craft Beers, Specialty Teas, Premium Wines, Non-Alcoholic Mocktails |
| Companies Covered | McDonald's Corporation, Luckin Coffee, Starbucks Corporation, Luigi Lavazza S.p.A., Costa Coffee, Nestlé S.A., Tim Hortons, Cotti Coffee, Dunkin' Brands Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cafe and Bars Market Shifts & Advancements
Digital ordering infrastructure and automation are compressing traditional service models while regulatory pressure on packaging and refrigeration accelerates capital rotation. These forces reshape how beverage operators configure physical space and labor deployment.
Cloud-based kitchen display systems and automated espresso workstations are displacing traditional counter-service labor models. Mid-market chains deploy these technologies to maintain throughput during peak hours without proportional staff increases. The structural consequence compresses break-even revenue thresholds for new store openings.
REACH and RoHS substance restrictions in the European Union are eliminating certain refrigerants and food-contact materials from licensed premises. Equipment suppliers must recertify product lines, extending procurement lead times. Operators in Germany and France front-load replacement cycles to avoid compliance deadlines.
Subscription-based beverage programs and app-locked loyalty tiers are capturing recurring revenue from urban professionals. Third-place social consumption migrates toward membership models that guarantee seating and skip-the-line privileges. This pattern concentrates in China's tier-one cities and spreads through Southeast Asian metropolitan clusters.
Global Cafe and Bars Market Segmentation
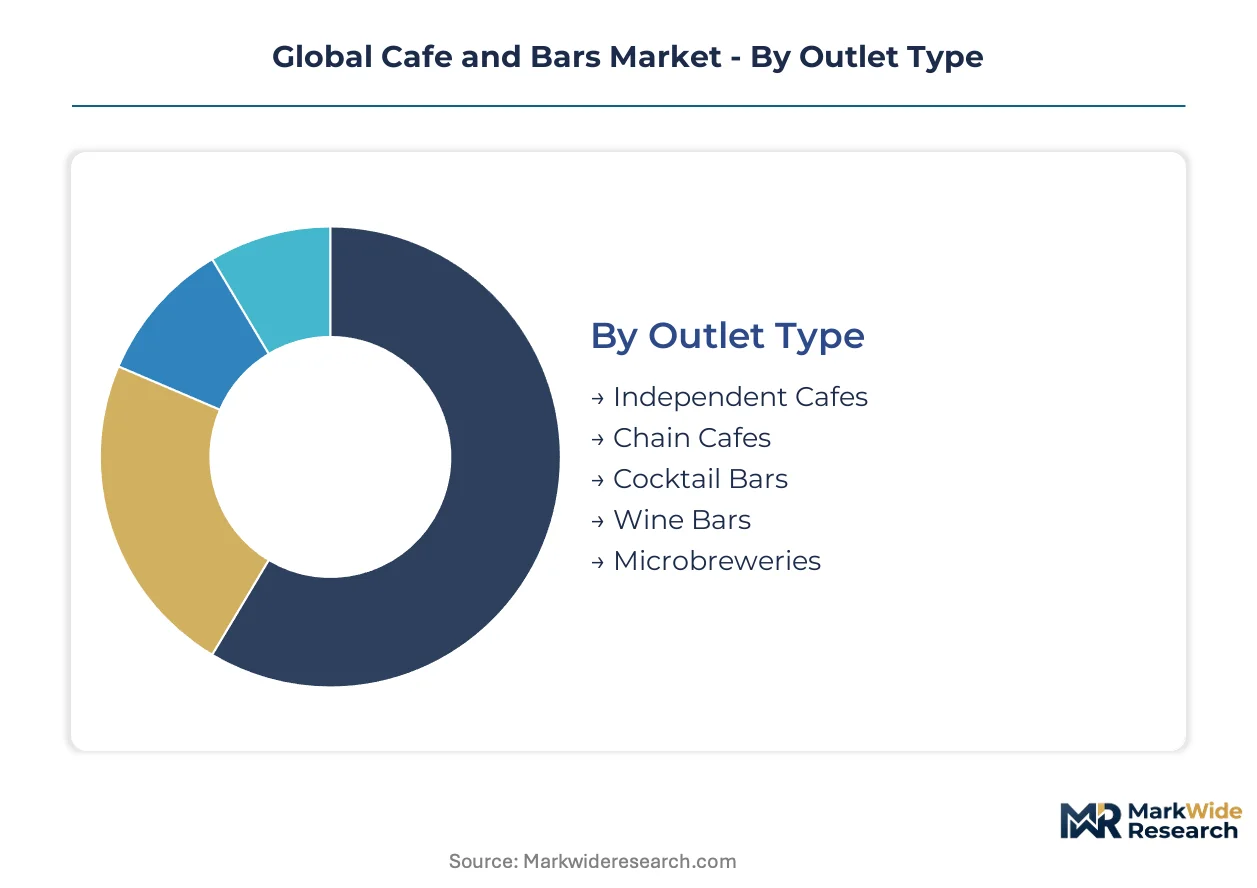
Segmentation reveals how regulatory frameworks and operational models fragment competitive positioning across licensed beverage premises. Different outlet configurations face distinct compliance thresholds from alcohol licensing boards, food safety codes, and extended producer responsibility mandates. Understanding these structural divisions clarifies where capital requirements concentrate and where digital-native operators can compress fixed-cost structures.
Outlet Type:
FDA food safety codes, EU F-Gas refrigeration mandates, and local alcohol licensing boards impose tiered compliance burdens that reshape capital allocation across physical formats.
- Independent Cafes:Single-location operators source arabica through regional importers and roast on-site or contract locally. These venues concentrate in European urban cores where EU Green Deal packaging rules elevate procurement costs. Labor intensity limits automation deployment.
- Chain Cafes:Controlled lease portfolios in high-footfall districts enable standardized extraction parameters across distributed locations. Procurement economies and training centralization dominate China's tier-one cities where SAMR labeling standards enforce menu transparency.
- Cocktail Bars:Spirit-forward operations require specialized licensing from municipal alcohol boards and face higher liability insurance thresholds. Demand clusters in metropolitan tourism corridors where third-place social consumption commands premium pricing.
- Wine Bars:Curated cellar inventories and sommelier certification requirements elevate operational complexity. These formats concentrate in mature European markets where REACH substance restrictions affect glassware and storage equipment specifications.
- Microbreweries:Batch-scale fermentation control and direct taproom distribution capture local margin pools. EPA and state-level environmental regulations govern wastewater discharge and grain handling across US production facilities.
Established volume favors chain cafes; emerging adoption favors microbreweries.
Service Model:
Cost tier differentiation separates labor-heavy table service from capital-light digital formats that minimize real estate exposure.
- Table Service:Traditional hospitality labor models dominate European licensed premises where minimum wage floors and tipping conventions structure cost bases. These formats retain ambient design investment as a competitive differentiator.
- Counter Service:Reduced labor per transaction enables throughput focus in high-density urban locations. China's Luckin Coffee and Cotti Coffee deploy this model with algorithmic queue management to maximize capture rates per square meter.
- Drive-Thru:Dedicated pickup lanes integrated with mobile-order infrastructure minimize labor per transaction. McDonald's McCafé extension demonstrates throughput economics that pure-play operators can replicate in suburban US markets.
- Online Ordering:App-locked loyalty tiers and subscription programs capture recurring revenue from urban professionals. Third-place consumption migrates toward membership models that guarantee seating privileges.
- Delivery Only:Ghost kitchen configurations eliminate front-of-house real estate entirely. These formats concentrate in Indian metropolitan clusters where FSSAI modernization simplifies licensing pathways for organized foodservice.
Labor intensity anchors table service; capital efficiency drives delivery-only expansion.
Customer Demographic:
Application-based segmentation tracks how consumption occasions fragment across life-stage and employment status.
- Young Adults:Social discovery and Instagram-native ambiance drive venue selection in Southeast Asian metropolitan clusters. These consumers demonstrate high price elasticity and rapid format switching.
- Working Professionals:Out-of-home beverage consumption expands fastest among this cohort, particularly in China's tier-one cities where dense store networks reduce delivery radius costs. Subscription loyalty programs capture recurring weekday occasions.
- Tourists:Seasonal demand concentration requires inventory flexibility and multilingual service capability. These consumers prioritize location convenience over brand loyalty in European heritage city centers.
- Students:Price sensitivity and extended dwell times characterize consumption patterns. Campus-adjacent locations in Indian cities face distinct FSSAI compliance requirements for educational institution proximity.
- Retirees:Daypart concentration in morning hours and preference for seated service reshape staffing schedules. This segment concentrates in Japanese and European markets with aging demographic profiles.
Volume concentration sits with working professionals; steepest expansion trajectory appears among young adults.
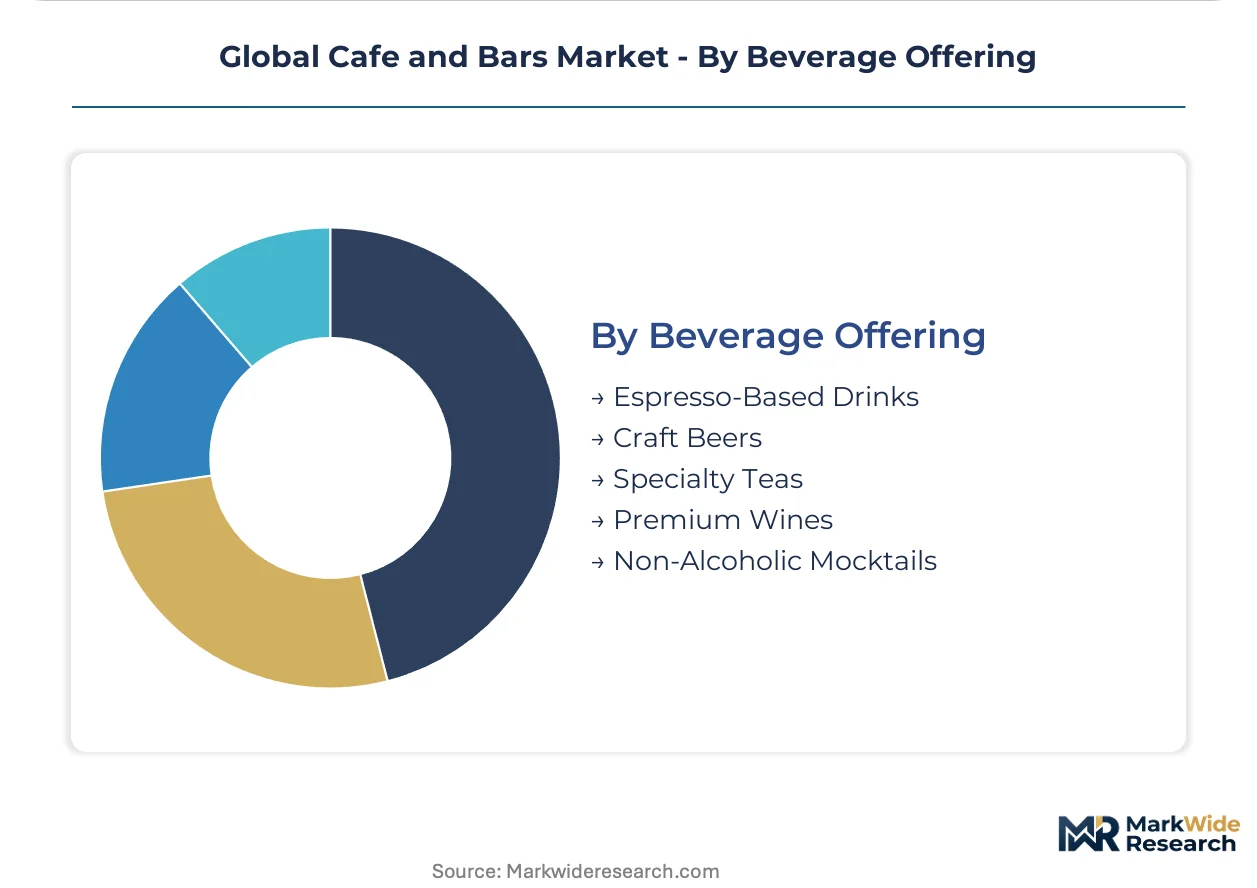
Beverage Offering:
Margin structure and supply chain configuration differentiate extraction-based, fermentation-based, and mixology-forward categories.
- Espresso-Based Drinks:Controlled extraction parameters—water temperature, pressure profiles, grind granularity—demand equipment standardization. Arabica price volatility in Brazil and Colombia transmits directly to cost-of-goods for coffee-focused operators.
- Craft Beers:Hop dosing precision and fermentation control enable batch-scale exclusivity. EU F-Gas Regulation on refrigeration systems accelerates equipment replacement cycles across German, French, and Italian taprooms.
- Specialty Teas:Origin-specific sourcing and steeping protocols appeal to wellness-oriented consumers. These offerings gain share in Chinese and Japanese markets where traditional consumption patterns support premium positioning.
- Premium Wines:Inventory carrying costs and storage climate control elevate working capital requirements. Distribution concentrates through established import channels in mature European and North American markets.
- Non-Alcoholic Mocktails:Functional beverages and adaptogenic ingredients capture occasions previously dominated by craft beer and cocktail consumption. These products align with EU Green Deal wellness narratives and municipal procurement preferences.
Margin depth favors premium wines; regulatory tailwinds favor non-alcoholic mocktails.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Western European capitals where EU Green Deal compliance costs elevate operating thresholds, while Chinese tier-one cities compress margins through algorithmic density plays. This asymmetry shapes capital allocation across the analysis window.
United States
Drive-thru beverage formats and mobile-order integration dominate suburban expansion, with McDonald's McCafé extension demonstrating throughput economics. FDA food safety codes govern extraction equipment sanitation standards across licensed premises. Greater Atlanta and Dallas-Fort Worth metro clusters witness dedicated pickup lane construction as labor costs reshape unit economics.
China
Algorithmic store placement and mini-format kitchens enable dense urban networks that reduce delivery radius costs. SAMR labeling standards enforce ingredient transparency across chain menus. Shanghai and Beijing concentrate Luckin Coffee and Cotti Coffee locations where working professionals drive out-of-home consumption expansion.
Germany
EU F-Gas Regulation mandates accelerate refrigeration retrofit cycles across taprooms and espresso bars. REACH substance restrictions eliminate certain food-contact materials from licensed premises. Berlin and Munich operators front-load equipment replacement to avoid compliance deadlines while capturing energy cost reductions.
India
FSSAI modernization simplifies licensing pathways for organized foodservice formats targeting urban professionals. Campus-adjacent locations in Mumbai and Bangalore face distinct compliance requirements for educational institution proximity. Maharashtra and Karnataka states concentrate third-place venue investment as willingness-to-pay for ambient hospitality design expands.
United Kingdom
CSRD carbon accounting requirements demand granular supply-chain disclosure from chain operators with EU exposure. London's high-footfall districts sustain premium lease portfolios for controlled-ambiance formats. Edinburgh and Manchester microbreweries capture local margin pools through batch-scale exclusivity and direct taproom distribution.
Global Cafe and Bars Market Competitive Landscape
Concentration sits with asset-heavy real estate players controlling prime urban locations, while digitally native operators compress fixed-cost structures through algorithmic site selection. The vendor base stratifies across three tiers: global chains with integrated supply chains, regional specialists leveraging local roasting relationships, and micro-format insurgents exploiting delivery infrastructure. Dominant competitive moves include controlled lease portfolio expansion in high-footfall districts and backward integration into roasting and equipment manufacturing.
Within the digitally native tier, Luckin Coffee and Cotti Coffee exemplify algorithmic density strategies that maximize capture rates per square meter in Chinese urban cores. Starbucks Corporation occupies a position representing premium-lease portfolio control, sustaining third-place ambiance investment against throughput-focused competitors. McDonald's Corporation anchors the quick-service extension archetype, leveraging existing drive-thru infrastructure for beverage-only transaction economics.
| Leading Market Players |
|---|
| McDonald's Corporation |
| Luckin Coffee |
| Starbucks Corporation |
| Luigi Lavazza S.p.A. |
| Costa Coffee |
| Nestlé S.A. |
| Tim Hortons |
| Cotti Coffee |
| Dunkin' Brands Group |
| Others |
Supply & Pricing Matrix
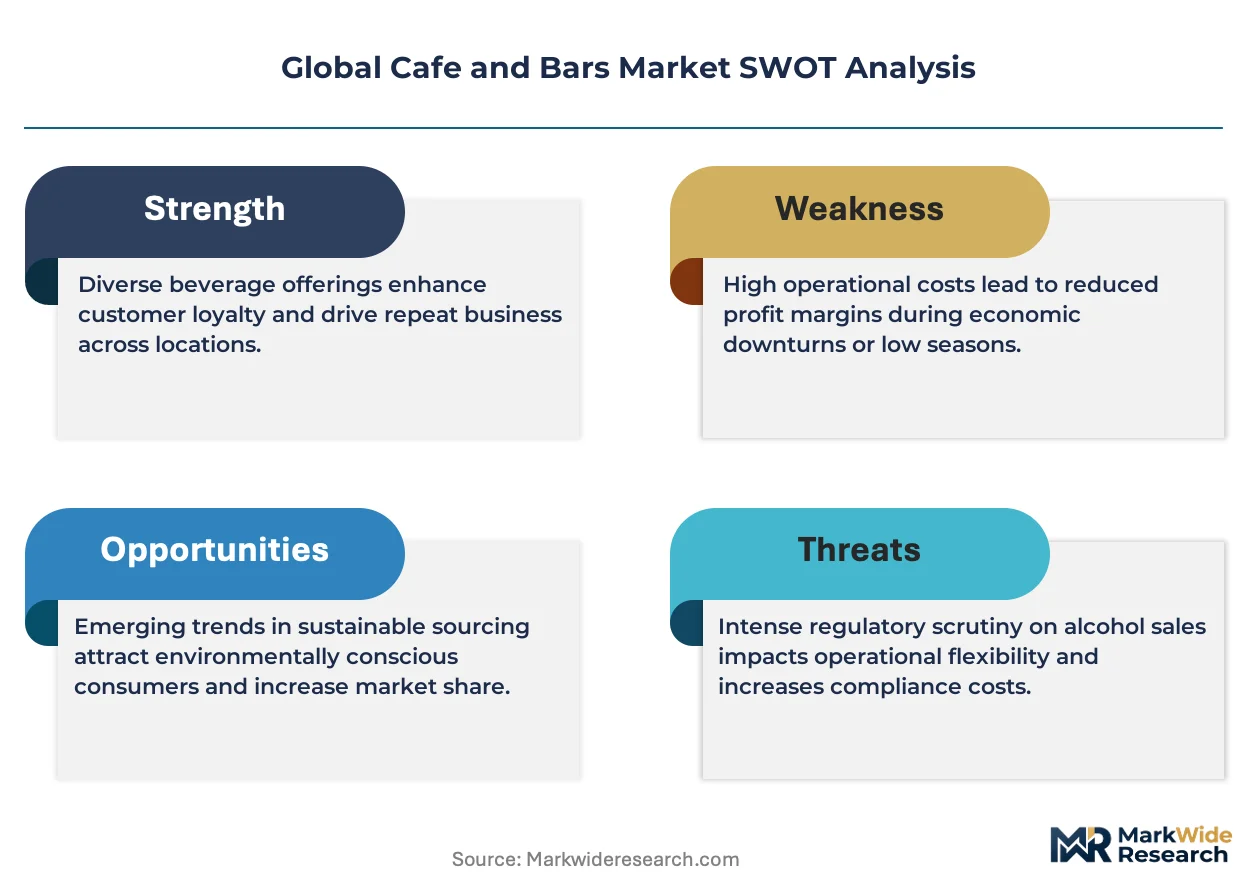
Biodegradable packaging substitution for conventional single-use plastics simultaneously shifts procurement geography toward EU-certified suppliers and compresses margin structures for operators locked into legacy inventory commitments. This input transition concentrates pricing power with converters holding EFSA food-contact approvals while tier-two chains absorb transition cost premiums.
Pricing Analysis
Customization-premium spreads separate espresso-based beverage configurations from standard drip-coffee baselines across licensed premises. Three-tier pricing structure across premium, standard, and economy levels dominates chain networks, with brand premium and geographic delivery cost as primary differentiation drivers. Cost compression in the economy tier is intensifying because arabica futures volatility transmits directly to cost-of-goods. Students demonstrate highest price sensitivity; cocktail bar patrons in metropolitan tourism corridors show lowest elasticity.
Supply Chain Analysis
Brazil and Colombia anchor arabica production volumes for espresso-forward operators, while Ethiopia and Vietnam supply specialty-grade and robusta segments respectively. Green bean sourcing draws from regional importers with direct-trade relationships, equipment manufacturing rests on Italian and German precision engineering, and cold-chain logistics hinges on domestic distribution networks. Single-source vulnerability concentrates in Brazilian climate-exposed harvest cycles. Distribution runs through national roasting hubs into direct-store-delivery or third-party foodservice wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: licensing board relationships and prime lease portfolios create switching costs that digital-native insurgents cannot replicate overnight.
For Market Incumbents: Fortify controlled lease positions in high-footfall districts through early renewal options and co-tenancy protections against emerging algorithmic-density operators. Deepen backward integration into regional roasting facilities to hedge arabica price volatility. Prioritize EU F-Gas Regulation compliance infrastructure as a competitive barrier.
For New Entrants and Emerging Players: Differentiate on delivery-only format economics in Indian metropolitan clusters where FSSAI modernization lowers licensing friction. Target ghost kitchen configurations in Mumbai and Bangalore as the most penetrable white space. Deploy subscription-locked loyalty tiers as the primary go-to-market angle for recurring revenue capture.
For Investors and Strategic Acquirers: Capital is best deployed toward algorithmic-site-selection platforms with proven unit-economics compression in Chinese tier-one cities. Long-term viability favors operators demonstrating throughput-per-square-meter optimization rather than ambiance-heavy legacy formats. Monitor SAMR enforcement intensity as the inflection signal for China market access risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Store Placement | Luckin Coffee's density strategy maximizes capture rates per square meter in Shanghai and Beijing. |
| Backward Integration into Roasting | Starbucks' controlled supply chains hedge arabica volatility while ensuring extraction parameter consistency. |
| EU F-Gas Compliance Infrastructure | German and French operators front-load equipment replacement to capture energy cost reductions ahead of deadlines. |
| Subscription Loyalty Programs | App-locked tiers migrate third-place consumption toward membership models with guaranteed seating privileges. |
| Drive-Thru Format Expansion | McDonald's McCafé extension demonstrates throughput economics replicable in suburban US markets. |
Research Methodology
A standing panel of cafe operations directors, beverage procurement managers, alcohol licensing attorneys, and commercial real estate brokers provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with chain expansion strategists and independent owner-operators, validated against secondary sources including FDA food safety code filings, EU ECHA substance restriction databases, SAMR labeling standard releases, and national trade association membership records. Bottom-up unit-economics modeling triangulated against top-down market sizing from customs import data and foodservice distributor revenue disclosures.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework segmented by outlet type, service model, customer demographic, and beverage offering, with regional regulatory clusters as a cross-cutting dimension. CAGRs were derived from regression-based trend extrapolation incorporating arabica futures curves, urban commercial lease indices, and licensed premise count trajectories as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of stable EU Green Deal implementation timelines and Chinese tier-one city consumption growth; material deviation in either would warrant model refresh. Specific risk factors include abrupt arabica supply disruption from climate events, accelerated CSRD carbon accounting compliance costs, and SAMR enforcement escalation affecting chain network expansion. Recalibration cycles align with material shifts in commodity futures curves and municipal licensing board policy revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Smart Food Logistics Market
Food Service
Food and Grocery Retail Market
Food Service
Onboard Rail Catering Market
Food Service
Global Self Heating Instant Hot Pot Market
Food Service
Instant Grocery Market
Food Service
GCC Online Grocery Market
Food Service
Contract Catering Market
Food Service
Contract Blending Services Market
Food Service
Bangladesh Food Service Market
Food Service
Commercial Beverage Dispenser Market
Food Service
Food Logistics Market
Food Service
Belgium HRI Market
Food Service
Commercial Sink Market
Food Service
Wok Market
Food Service
Commercial Ice Dispenser Market
Food Service
Meal Kit Delivery Services Market