
 North America Online Grocery Delivery Market | 2026-2036
North America Online Grocery Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
North America Online Grocery Delivery Market Analytics
Working professionals is unwinding share toward busy families as the dominant online grocery buyer archetype. Amazon.com Inc. leverages its fulfillment node density to compress delivery windows in suburban zones. Walmart Inc. anchors volume through curbside-to-door hybrid infrastructure that reduces per-order logistics cost. Instacart competes by aggregating retailer inventory across competing banners onto a single platform interface.
Online grocery delivery denotes the digital ordering and physical distribution of food and household consumables through web or mobile interfaces, requiring temperature-controlled staging zones and route-optimization algorithms to preserve product integrity and meet promised arrival windows. Its commercial purpose centers on substituting store visits with scheduled or on-demand replenishment of routine household baskets. Subscription service type captures recurring revenue predictability and builds inventory planning visibility for operators. Express delivery commands premium positioning but strains margin due to unconsolidated trip economics. App-based services dominate customer acquisition funnels, though direct retailer channels retain higher lifetime value through loyalty program integration.
FDA food code provisions and USDA FSMA traceability mandates govern perishable handling standards across interstate fulfillment networks, while state departments of agriculture in California, Texas, and New York layer additional licensing requirements on dark-store operators. The FTC scrutinizes platform fee structures and exclusivity arrangements between grocers and delivery intermediaries. Stakeholders must weigh cold-chain automation capital deployment against regulatory compliance cost trajectories as order density thresholds shift.
Market Dynamics
Cold-chain automation investments are compressing fulfillment timelines while USDA FSMA traceability mandates force infrastructure upgrades across interstate networks. The tension between margin pressure and service-level promises drives consolidation among regional dark-store operators.
Growth Catalysts
- Urban household density:Metropolitan corridors in the United States concentrate order volume above suburban break-even thresholds. Toronto and Vancouver replicate this pattern in Canada.
- USDA FSMA Rule 204:Traceability mandates accelerate technology adoption for lot-tracking compliance. Operators gain inventory visibility that reduces shrinkage.
- Subscription mechanics:Recurring revenue models stabilize demand forecasting. Retailers negotiate volume commitments with produce suppliers.
Market Restraints
- Refrigerated last-mile cost structure:Diesel fuel volatility and electric vehicle conversion capex strain per-trip economics. Unconsolidated express orders amplify this pressure.
- Dark-store real estate concentration:Prime industrial cold-storage sites cluster in California, Texas, and New York metro areas. Secondary markets face capacity scarcity.
- State cottage food amendments:Inconsistent licensing requirements across state agriculture departments create compliance fragmentation. Interstate fulfillment networks absorb administrative overhead.
Strategic Opportunities
- Mid-size metropolitan expansion:Austin, Nashville, and Calgary show order density growth without saturation. Early entrants capture habit formation.
- Meal-kit convergence:Portioned ingredient bundling merges with full-basket grocery. Cold-chain infrastructure serves both use cases.
- California CalFresh expansion:SNAP online purchasing pilots extend to delivery-eligible households. Operators integrate EBT payment rails.
Industry Challenges
- Route-optimization talent scarcity:Machine-learning engineers with perishable logistics experience command premium compensation. Operators poach from ride-sharing and parcel networks.
- Temperature-verification certification:HACCP-aligned protocols require continuous monitoring system deployment. Small intermediaries lack capital for sensor infrastructure.
- Retailer API integration complexity:Legacy inventory systems resist real-time availability synchronization. Platform aggregators absorb technical debt.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Online Grocery Delivery Market |
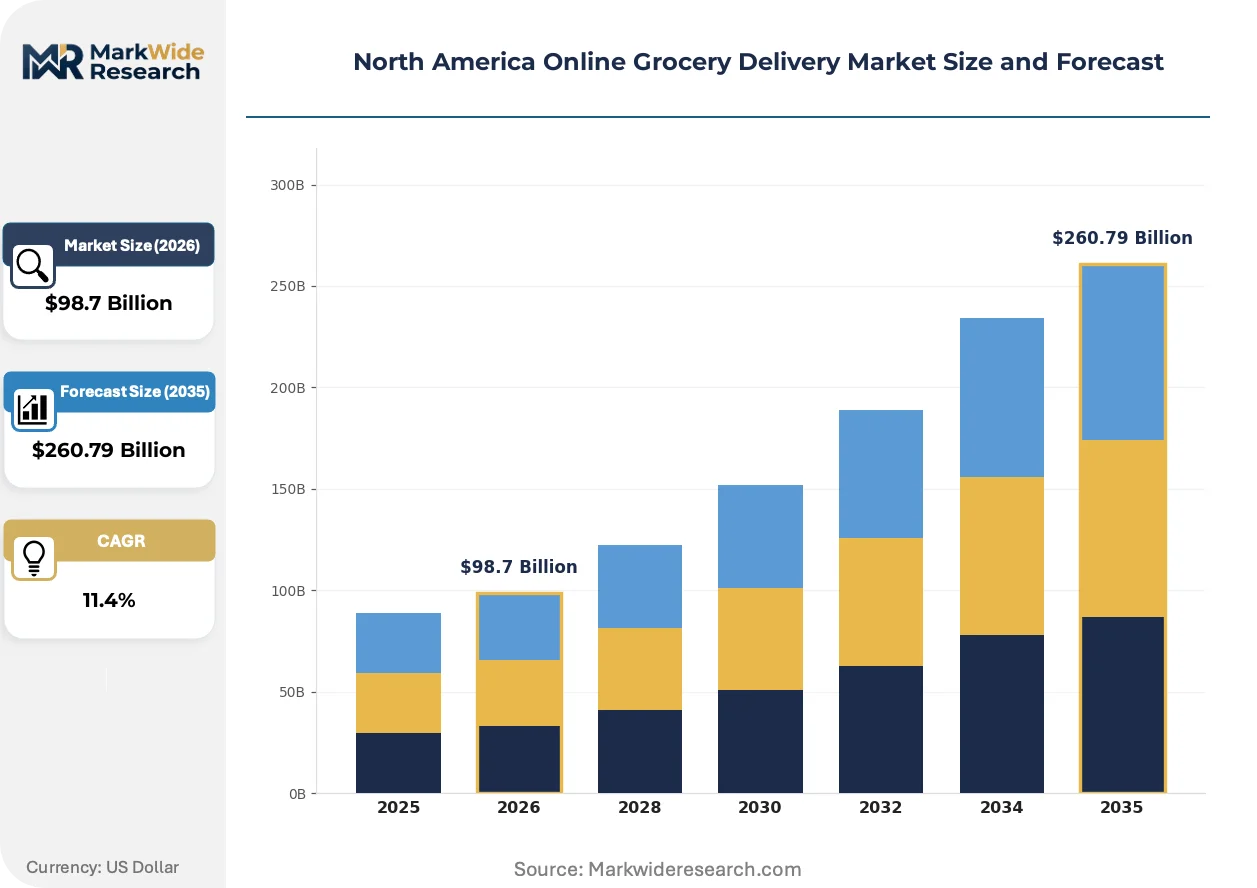
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $260.79 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Subscription, One-time Delivery, Express Delivery, Scheduled Delivery Customer Type: Households, Working Professionals, Busy Families, College Students Product Type: Fresh Produce, Packaged Foods, Frozen Items, Beverages Delivery Channel: App-based Services, Website Orders, Third-party Vendors, Direct Retailer |
| Companies Covered | Walmart Inc., Amazon.com Inc., Instacart, Costco Wholesale Corp., The Kroger Co., Albertsons Companies Inc., Ahold Delhaize USA, DoorDash Inc., Shipt LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Online Grocery Delivery Market Evolving Landscape
Automated micro-fulfillment centers are reshaping unit economics for same-day delivery promises. Three converging developments define the current transformation window.
Autonomous mobile robots in dark-store picking operations are displacing manual fulfillment labor in high-volume facilities. Kroger and Albertsons deploy these systems in California and Texas distribution nodes. The technology compresses order assembly time from twenty-five minutes to under eight, enabling narrower delivery windows without proportional labor cost expansion.
The FDA Food Code 2022 provisions on time-temperature controls are tightening staging protocols for ready-to-eat categories. Operators must install continuous data-logging systems for deli, seafood, and prepared meal segments. Canadian provincial health authorities in Ontario and British Columbia are adopting harmonized standards, reducing cross-border fulfillment complexity.
Households are consolidating weekly replenishment into fewer, larger digital baskets rather than incremental convenience trips. This pattern concentrates demand on weekend delivery slots and compresses weekday capacity utilization. Suburban families with children drive this behavior most visibly in the United States Sun Belt metros.
North America Online Grocery Delivery Market Segmentation
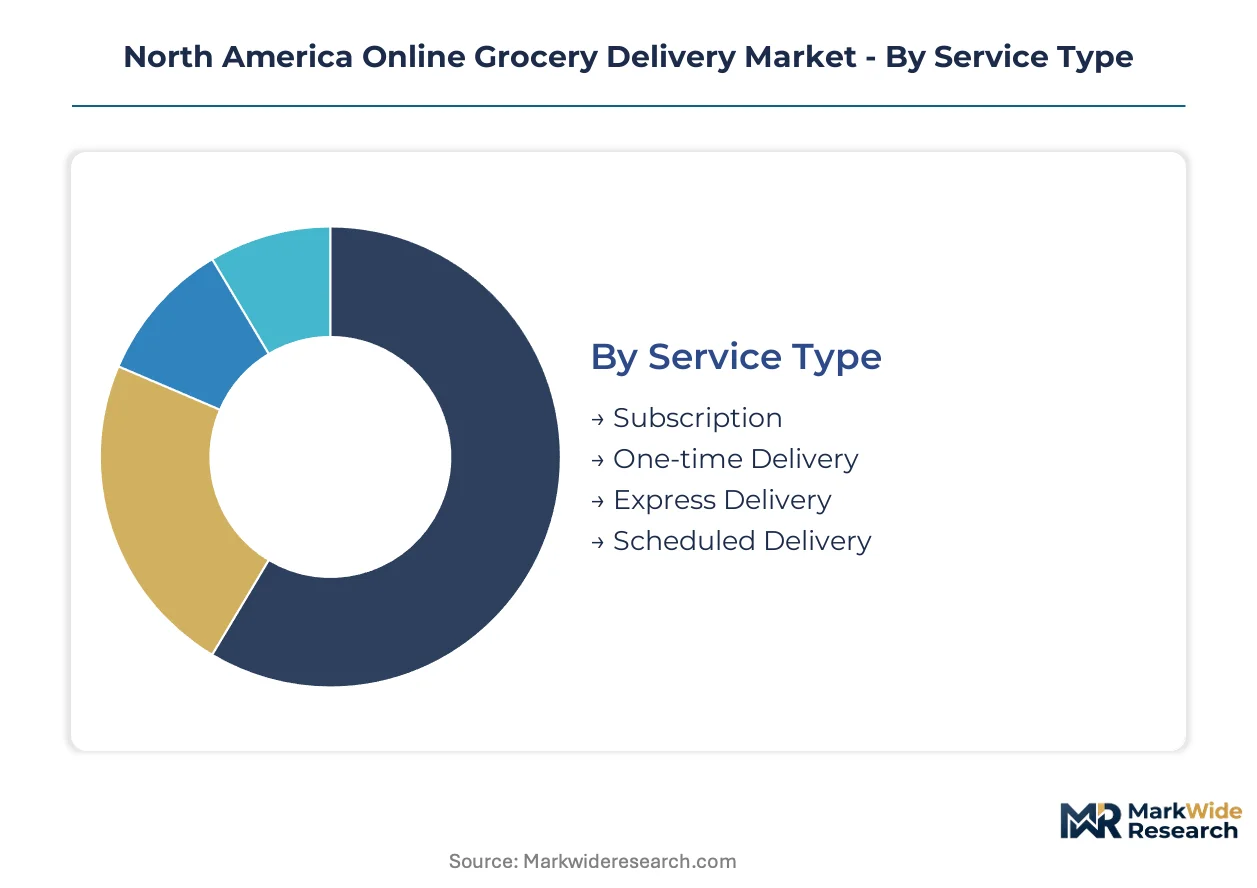
Segmentation in online grocery delivery reveals where substitution pressure from physical retail persists strongest and where digital infrastructure investments yield defensible moats. Service mechanics and customer archetypes determine fulfillment network design, while product temperature requirements dictate cold-chain capital allocation.
Service Type:
Subscription models face the sharpest substitute threat from physical warehouse clubs, while express delivery commands premium positioning that resists price-based competition.
- Subscription:Recurring weekly or bi-weekly basket commitments generate predictable demand curves that stabilize produce procurement contracts. Busy families in United States Sun Belt metros anchor this segment through automated replenishment of staple categories.
- One-time Delivery:Transactional orders without recurring commitment capture occasional shoppers and seasonal demand spikes. Working professionals in Toronto and Vancouver density corridors drive volume during promotional windows.
- Express Delivery:Sub-two-hour fulfillment promises strain unconsolidated route economics but capture urgent replenishment occasions. Cold-chain automation investments in California and Texas dark stores compress assembly timelines to enable this service tier.
- Scheduled Delivery:Day-ahead or week-ahead slot reservations optimize fleet utilization and reduce per-trip cost. Suburban households with predictable routines favor this mechanic for large weekly baskets.
Subscription anchors the volume base while express delivery gains share at the steepest rate.
Customer Type:
Cost tier stratification separates high-frequency subscription households from price-sensitive occasional users.
- Households:Multi-person residential units with consolidated purchasing authority generate the largest average order values. Weekend slot concentration in dense United States metropolitan corridors creates capacity bottlenecks.
- Working Professionals:Time-constrained singles and couples prioritize convenience over price comparison, accepting premium fees for narrow delivery windows. App-based acquisition funnels capture this segment through workplace targeting.
- Busy Families:Dual-income households with children drive the shift toward fewer, larger digital baskets replacing incremental store trips. USDA FSMA traceability mandates matter intensely for this segment's baby food and fresh protein purchases.
- College Students:Campus-adjacent micro-fulfillment nodes serve small-basket, high-frequency demand with limited cold-storage requirements. Shared housing arrangements split delivery fees across roommates.
Busy families anchor the volume base while working professionals expand most quickly through employer-subsidized programs.
Product Type:
Margin concentration in temperature-controlled categories drives supply-side specialization.
- Fresh Produce:Perishable fruits and vegetables require continuous cold-chain integrity from farm receipt through last-mile handoff. California and Florida sourcing corridors concentrate supply relationships with dark-store operators.
- Packaged Foods:Ambient shelf-stable categories tolerate longer fulfillment timelines and standard warehouse conditions. Center-store brands convert most readily from physical to digital basket composition.
- Frozen Items:Ice cream, prepared meals, and protein products demand sub-zero staging zones and insulated packaging. Summer delivery slot premiums reflect elevated failure risk from temperature excursions.
- Beverages:Heavy, low-margin liquid categories strain per-unit economics unless bundled with higher-margin produce. Texas and Arizona heat waves amplify demand for chilled beverage delivery.
Packaged foods anchor the volume base while fresh produce climbs the fastest as quality guarantees improve.
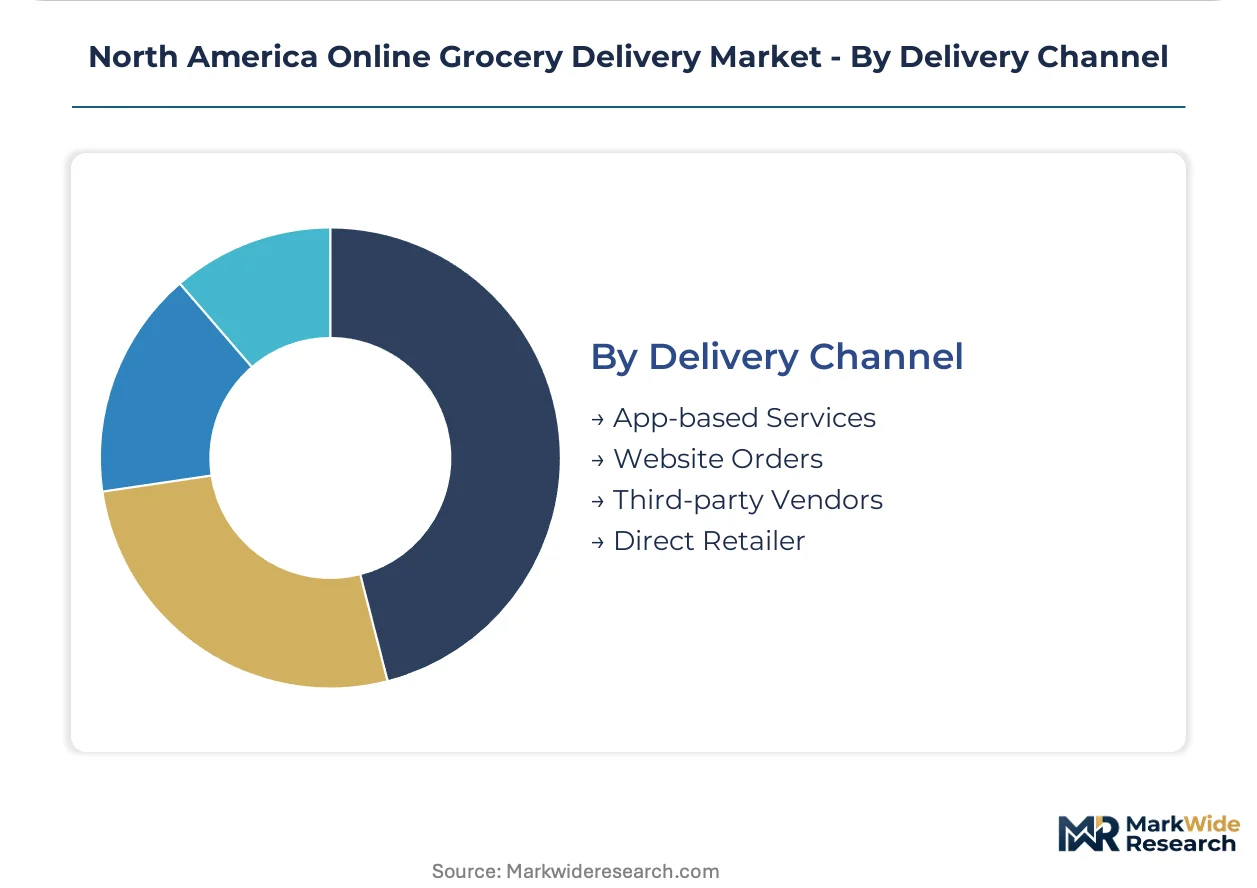
Delivery Channel:
Geography determines channel viability, with app-based penetration highest where smartphone-native demographics concentrate.
- App-based Services:Mobile-first interfaces dominate customer acquisition among younger demographics through push-notification promotions. Aggregator platforms consolidate inventory visibility across competing retailer banners.
- Website Orders:Desktop and mobile web experiences retain higher average order values through easier basket building and comparison shopping. Loyalty program integration drives repeat purchase behavior.
- Third-party Vendors:Intermediary platforms absorb technical integration costs with legacy retailer inventory systems. FTC scrutiny of fee structures and exclusivity arrangements constrains pricing power.
- Direct Retailer:First-party channels capture full margin and customer data but require proprietary fulfillment infrastructure. Walmart and Amazon deploy this model at scale.
App-based services anchor the volume base while direct retailer channels gain share fastest through loyalty program lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach cold-chain corridor anchors trans-Pacific produce flows into Southern California distribution nodes. Interstate highway density across the Great Lakes manufacturing belt enables rapid replenishment cycles for Midwest metropolitan fulfillment networks.
United States
USDA FSMA Rule 204 traceability mandates force technology upgrades across interstate fulfillment networks. Sun Belt metropolitan corridors from Phoenix to Atlanta concentrate dark-store investments as household density thresholds mature. FDA food code provisions on time-temperature controls tighten staging protocols for ready-to-eat categories in California and Texas facilities.
Canada
Toronto and Vancouver density corridors replicate US metropolitan order concentration patterns with faster scaling rates. Health Canada and PMRA harmonize cold-chain standards with FDA provisions, reducing cross-border fulfillment complexity for Ontario and British Columbia operators. Provincial health authorities in Quebec layer additional licensing requirements on automated micro-fulfillment centers.
Mexico
Mexico City metropolitan demand concentrates in high-income boroughs with limited cold-chain penetration outside capital-region corridors. The country's national health regulator enforces perishable handling standards that lag US FDA alignment, creating compliance friction for cross-border fulfillment networks. Monterrey and Guadalajara industrial clusters attract dark-store pilot investments from US-based operators testing proximity sourcing models.
North America Online Grocery Delivery Market Competitive Landscape
Listed leaders compete with private specialists across fulfillment infrastructure ownership models. The market structure concentrates around three distinct strategic archetypes: vertically integrated retailers with proprietary logistics networks, platform aggregators absorbing technical integration costs across legacy inventory systems, and specialized intermediaries focused on express delivery velocity. Consolidation pressures intensify as regional dark-store operators face margin compression from unconsolidated trip economics and cold-chain automation capex requirements.
Within the integrated retail tier, Walmart Inc. and Amazon.com Inc. anchor competitive positioning through fulfillment node density and hybrid curbside-to-door infrastructure. Instacart occupies a distinct aggregator position, consolidating inventory visibility across competing retailer banners onto single platform interfaces. These three entities exemplify the strategic divergence between first-party channel control and third-party marketplace aggregation that defines current competitive dynamics.
| Leading Market Players |
|---|
| Walmart Inc. |
| Amazon.com Inc. |
| Instacart |
| Costco Wholesale Corp. |
| The Kroger Co. |
| Albertsons Companies Inc. |
| Ahold Delhaize USA |
| DoorDash Inc. |
| Shipt LLC |
| Others |
Value Network & Pricing Analysis
Electric vehicle fleet conversion is displacing diesel-dependent refrigerated transport in California and Texas corridors, compressing fuel cost volatility while redistributing capital expenditure burdens across operator balance sheets and reshaping per-mile pricing economics for temperature-controlled last-mile fulfillment.
Pricing Analysis
Volume-discount tiering structures separate subscription households committing to weekly basket minimums from express delivery users paying surge premiums for sub-two-hour windows. Price differentiation centers on delivery speed guarantees and cold-chain certification levels, with HACCP-aligned operators commanding modest premiums over standard service tiers. Pricing pressure stems from unconsolidated express trip economics eroding per-order margins in suburban zones. Busy families demonstrate lowest price sensitivity through subscription lock-in, while college students and occasional shoppers exhibit highest elasticity to delivery fee adjustments.
Supply Chain Analysis
Inbound logistics costs through the Port of Long Beach cold-chain corridor fluctuate with trans-Pacific container availability and diesel fuel volatility affecting California produce distribution nodes. Geographic supply concentration centers on California and Florida sourcing corridors for fresh produce, Texas and Arizona for beverage and frozen categories, and Midwest grain belt states for packaged staples. Raw material dependencies span temperature-controlled packaging, refrigerant gases, and insulated container fleets. Single-source vulnerability concentrates in California industrial cold-storage real estate. Distribution runs through dark-store micro-fulfillment nodes feeding metropolitan last-mile networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a cyclical recovery phase driven by household basket consolidation behavior normalizing post-pandemic disruption patterns and stabilizing subscription renewal rates.
For Market Incumbents: Shield market position through backward integration into automated micro-fulfillment center ownership rather than leased dark-store dependencies, and accelerate cold-chain automation capex deployment ahead of USDA FSMA Rule 204 compliance deadlines. Margin pressure from unconsolidated express delivery economics and emerging platform aggregator competition demands proprietary infrastructure control.
For New Entrants and Emerging Players: Lead with mid-size metropolitan corridor specialization in Austin, Nashville, and Calgary where order density growth outpaces incumbent saturation and habit formation windows remain open. Campus-adjacent micro-fulfillment nodes serving college students offer the most penetrable entry segment with limited cold-storage capital requirements and shared-fee economics.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors regional dark-store operators with established cold-chain infrastructure and compliant traceability systems over pure-platform intermediaries. Long-term viability across the next decade hinges on fulfillment asset ownership rather than marketplace aggregation. Monitor California CalFresh EBT integration progress as an inflection signal for addressable market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Micro-Fulfillment Deployment | Kroger and Albertsons robot installations compress assembly time from twenty-five minutes to under eight. |
| Cold-Chain Certification Investment | HACCP-aligned continuous monitoring systems satisfy FDA Food Code 2022 time-temperature control provisions. |
| Subscription Mechanics Expansion | Recurring revenue models stabilize produce procurement contracts and reduce demand forecasting variance. |
| Mid-Size Metropolitan Expansion | Austin and Nashville density growth offers habit formation windows before incumbent saturation. |
| EBT Payment Rail Integration | California CalFresh eligibility extension broadens addressable household base for delivery-eligible SNAP recipients. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with grocery retail executives, dark-store operations managers, cold-chain logistics directors, and last-mile fleet coordinators. Secondary validation drew from USDA FSMA regulatory filings, FDA food code provisions, state agriculture department licensing records, and customs trade data on refrigerated container flows. Bottom-up order density modeling and top-down market sizing triangulated volume estimates.
Across the projection horizon, the analytical framework segmented by service type, customer archetype, product temperature requirement, and delivery channel geography. CAGRs were derived from cohort-based subscription renewal analysis and express delivery penetration curves. Forecast inputs incorporated household density thresholds, cold-chain automation deployment timelines, and regulatory compliance cost trajectories.
Forecasts assume regulatory continuity in FDA food code provisions and USDA FSMA traceability mandates; material policy shifts would require re-modeling. Commodity price volatility in diesel and refrigerant gases, plus electric vehicle conversion subsidy changes, constitute specific revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Global Sushi Restaurants Market
Food Service
Charbroiler Market
Food Service
Undercounter Ice Makers Market
Food Service
Latin America Airport Quick Service Restaurant Market
Food Service
Personal Chef Services Market
Food Service
Benelux Foodservice Market
Food Service
Europe Barbeque Grill Market
Food Service
International Food Subscription Box Service Market
Food Service
Smart Food Logistics Market
Food Service
India Online Grocery Market
Food Service
Latin America Online Grocery Delivery Market
Food Service
United Kingdom Barbeque Grill Market
Food Service
Airport Quick Service Restaurants Market
Food Service
Commercial Cutlery Market
Food Service
Saudi Arabia Inflight Catering Market
Food Service
Hyperlocal Grocery Delivery Market