
 Commercial Tandoor Oven Market | 2026-2036
Commercial Tandoor Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Tandoor Oven Market Outlook
Artisan metalworking labor availability is reorganizing production capacity across the commercial tandoor oven supply base. Ranvir leverages its established Uttar Pradesh fabrication clusters to sustain high-volume output of customized clay-lined units. Shri Krishna Cooking Equipments anchors its position through specialized gas-fired configurations for mid-scale catering operations. Kumar Tandoor Machine Ms competes aggressively on portable installation formats for food truck operators seeking mobility without sacrificing thermal performance.
A commercial tandoor oven is a cylindrical clay or metal cooking chamber fired by wood, gas, or electricity, designed to reach internal temperatures exceeding 480 degrees Celsius for rapid charring of marinated proteins and leavened breads in professional foodservice environments. The cooking surface typically incorporates a blend of refined clay, sand, and salt compounds that retain radiant heat while withstanding thermal cycling. Gas tandoor variants dominate current revenue flows due to faster startup times and cleaner compliance with urban emissions ordinances, though wood-fired installations command premium positioning among heritage-focused restaurants. Tabletop electric models represent the fastest-growing installation type as ghost kitchens and compact cloud-kitchen footprints proliferate in dense metropolitan zones.
India's BIS thermal efficiency mandates and the UAE's civil defense fire-safety certifications for commercial kitchens are reshaping product design priorities across export-oriented manufacturers. CE marking requirements for European foodservice equipment imports add compliance layers that favor larger fabricators with dedicated testing protocols. Stakeholders must monitor how municipal energy transition timelines in key demand centers revalue gas infrastructure against electric retrofit economics.
Market Dynamics
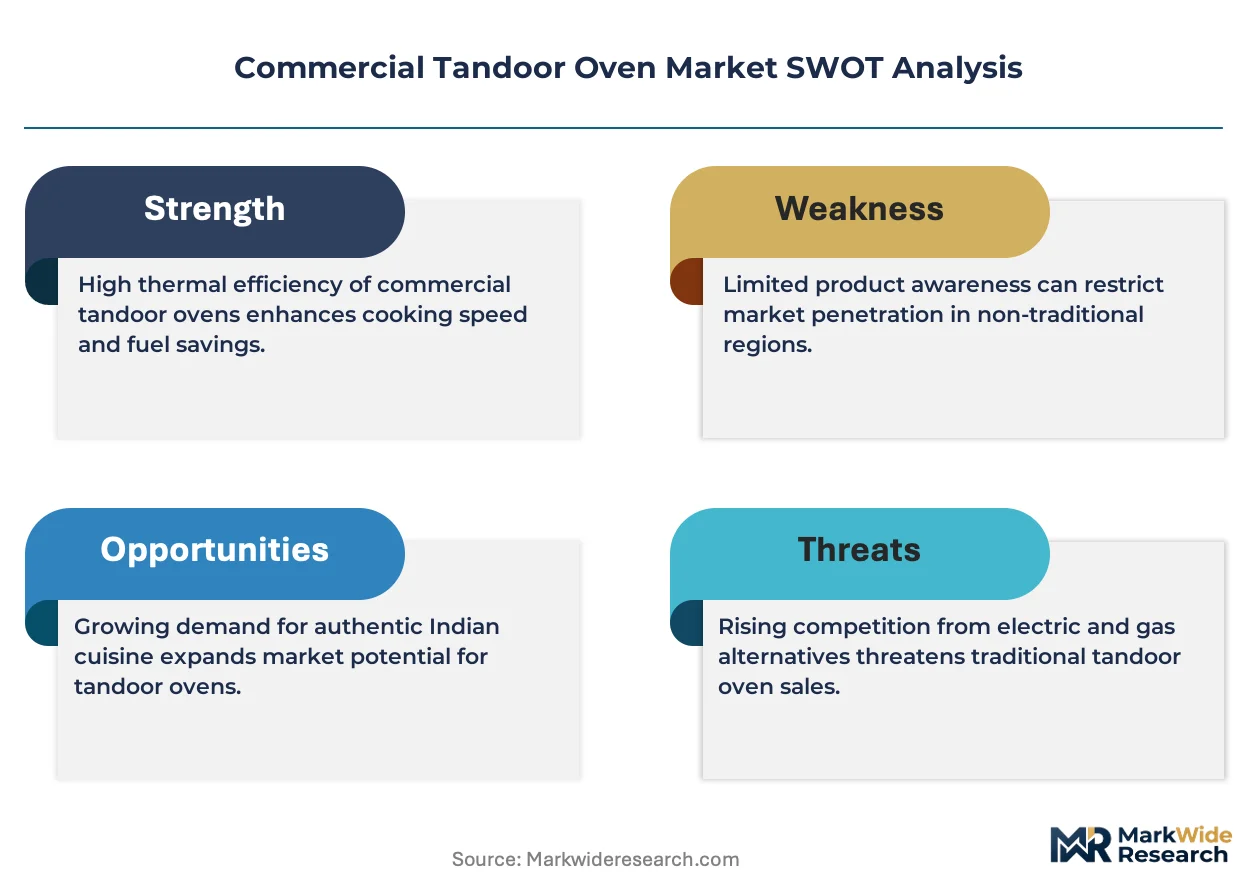
Artisan metalworking labor scarcity in Uttar Pradesh and Rajasthan is compressing production capacity for clay-lined cylindrical chambers, forcing manufacturers to relocate fabrication clusters or automate forming processes previously dependent on hand-beaten stainless steel.
Growth Catalysts
- UAE Civil Defense Certification:Dubai's mandatory fire-safety approvals for commercial kitchens are accelerating replacement cycles in South Asian themed dining concepts across the emirate's hospitality construction pipeline.
- Wood-to-Gas Conversion Subsidies:Municipal energy transition programs in Delhi and Mumbai are incentivizing restaurants to retire coal-fired installations for cleaner-burning propane configurations.
- Ghost Kitchen Proliferation:Compact cloud-kitchen footprints in dense metropolitan zones are pulling demand toward tabletop electric models with sub-30-minute preheat cycles.
Market Restraints
- Refractory Clay Supply Concentration:Premium bentonite deposits in Gujarat and Rajasthan face extraction quota restrictions, creating input cost volatility for traditional clay-lined chamber producers.
- CE Marking Compliance Burden:European foodservice equipment import requirements favor larger fabricators with dedicated testing protocols, structurally excluding smaller Uttar Pradesh workshops from EU market access.
- Induction Cooking Substitution:Flat-top induction ranges with char-simulation technology are capturing mid-scale catering operations seeking zero-emission alternatives without ventilation infrastructure.
Strategic Opportunities
- Saudi Arabia Vision 2030 Hospitality:Riyadh and Jeddah entertainment district developments are incorporating South Asian dining precincts requiring standardized commercial tandoor installations at scale.
- Internet of Things Convergence:Temperature telemetry and predictive maintenance sensors are enabling remote monitoring contracts for multi-unit restaurant chains managing distributed kitchen fleets.
- India PLI Scheme for Manufacturing:Production-linked incentive frameworks for commercial cooking appliances are subsidizing capital equipment upgrades for domestic fabricators seeking export competitiveness.
Industry Challenges
- Artisan Welding Skill Attrition:Stainless steel chamber fabrication requires specialized argon-arc techniques that younger workers in Moradabad and Saharanpur are abandoning for electronics assembly wages.
- BIS Thermal Efficiency Testing Backlogs:India's Bureau of Indian Standards certification queues are extending product launch timelines by 4-7 months for clay-insulated variants requiring repeated thermal cycling validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Tandoor Oven Market |
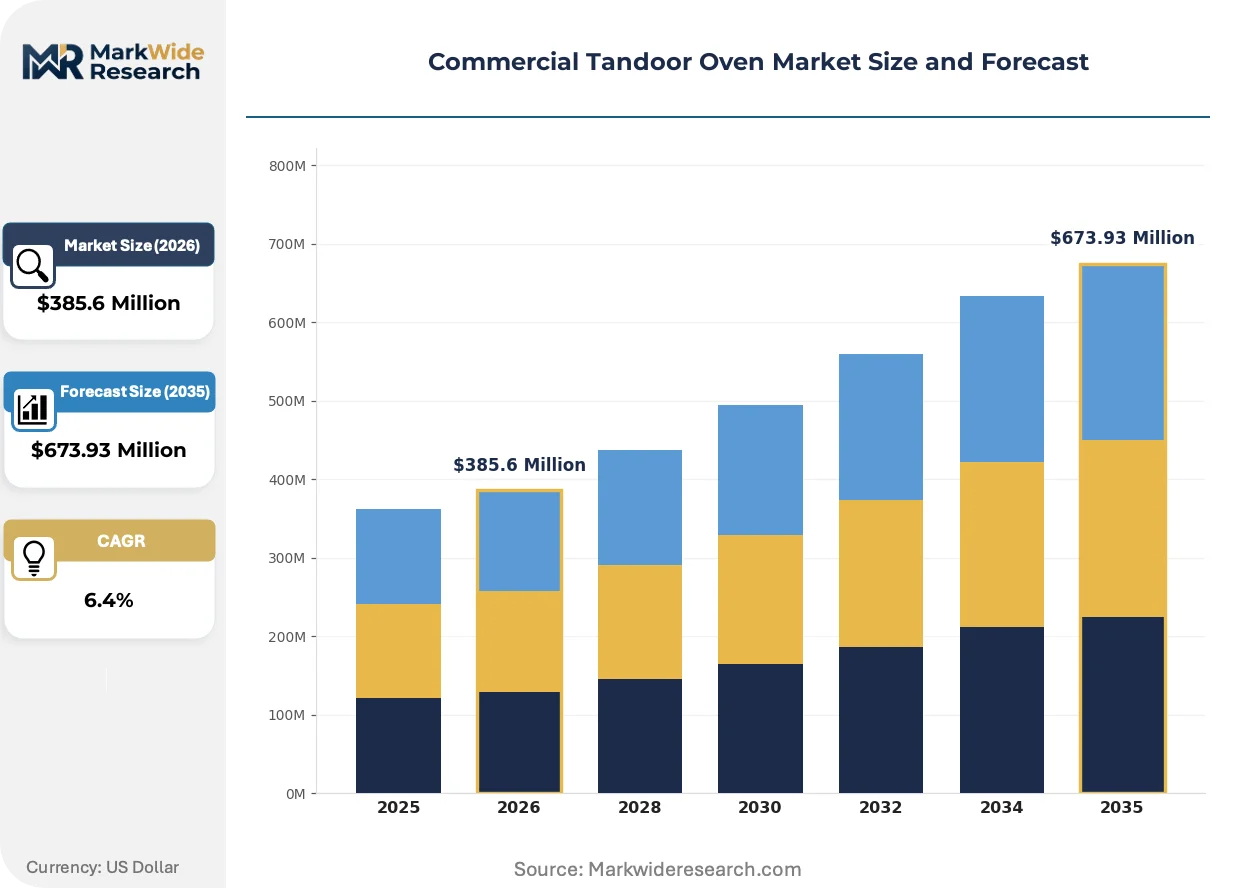
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Tandoor, Gas Tandoor, Wood-fired Tandoor, Tabletop Tandoor End User: Restaurants, Catering Services, Food Trucks, Hotels Installation Type: Built-in, Portable, Standalone, Customized Size: Small, Medium, Large, Extra Large |
| Companies Covered | Ranvir, Shri Krishna Cooking Equipments, Kumar Tandoor Machine Ms, Mohanlal Tandoors, Nand Equipment Pvt. Ltd, SS Tan Tandoor, Dhanraj Bhati Tandoorwala, GULATI Tandoors, Sabari Kitchen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Tandoor Oven Market Strategic Shifts
Electrification of thermal systems and embedded connectivity are fragmenting the traditional gas-dominant product architecture, while regulatory pressure on emissions and fire safety compresses acceptable design tolerances across all fuel types.
Hybrid gas-electric heating elements are fragmenting the conventional fuel-type segmentation by enabling operators to switch between propane and resistive coils based on local energy pricing or municipal restrictions. Mid-scale caterers in Texas and Florida are piloting these dual-mode units to hedge against volatile natural gas tariffs. The technology is fragmenting vendor specialization boundaries, as electrical component suppliers now compete directly with legacy combustion equipment fabricators.
The EU F-Gas Regulation phase-down on hydrofluorocarbon refrigerants is indirectly pressuring commercial kitchen ventilation manufacturers to redesign exhaust hood compatibility for higher-temperature appliances. Tandoor producers exporting to Germany and France must now certify thermal plume capture efficiency alongside their core cooking performance metrics. European importers are consolidating supplier relationships to reduce compliance fragmentation across multiple national building codes.
Cloud-kitchen operators are unbundling equipment ownership from facility leases, treating tandoor installations as interchangeable production assets rather than fixed capital. Third-party kitchen infrastructure providers in London and New York are standardizing on 24-inch electric tabletop formats to maximize equipment redeployment across rotating tenant brands. This asset-light model is concentrating procurement authority with real estate developers rather than individual restaurant operators.
Commercial Tandoor Oven Market Segmentation
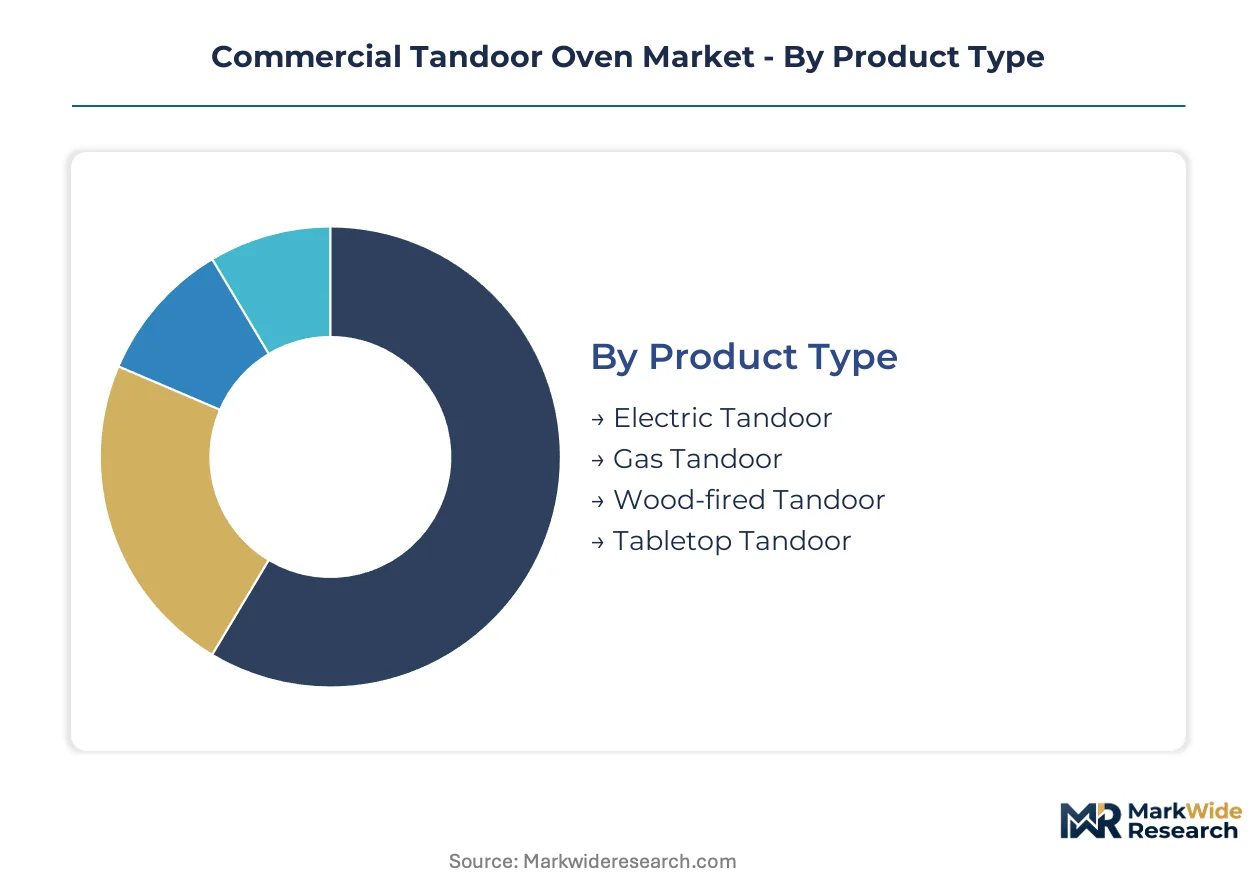
Commercial tandoor oven procurement patterns diverge sharply between heritage establishments seeking authentic thermal performance and high-volume operators prioritizing throughput consistency. Equipment specifications must align with ventilation infrastructure, fuel access, and kitchen footprint constraints that vary by venue type and geographic market.
Product Type:
Domestic Indian demand concentrates on wood-fired and gas configurations that satisfy BIS thermal efficiency mandates, while export markets pull toward electric and tabletop variants compatible with dense urban ventilation restrictions.
- Electric Tandoor:Resistive coil heating elements embedded in ceramic insulation deliver temperatures up to 450 degrees Celsius without combustion ventilation requirements. Ghost kitchen operators in London and New York deploy these units to bypass hood installation costs in leased facilities. Momentum sits with this segment as municipal gas hookup moratoriums spread across North American metropolitan zones.
- Gas Tandoor:Propane or natural gas burners beneath clay-lined chambers achieve sub-15-minute preheat cycles with precise flame modulation. Mid-scale catering operations in Texas and Florida favor these configurations for volume throughput where energy tariffs remain favorable. This segment holds the largest share of current revenue flows.
- Wood-fired Tandoor:Traditional charcoal or hardwood combustion in cylindrical clay chambers produces signature smoke char on proteins and breads. Heritage-focused restaurants in Dubai and Riyadh specify these units for authenticity positioning despite higher operational complexity.
- Tabletop Tandoor:Compact electric or gas units under 24 inches in diameter enable deployment in food trucks and cloud-kitchen pods. UAE-based South Asian dining concepts in hospitality construction pipelines specify these for space-constrained installations.
Gas configurations dominate installed base; electric variants are climbing the fastest as regulatory pressure on combustion emissions intensifies.
End User:
Volume procurement authority is shifting from independent operators toward third-party kitchen infrastructure providers managing multi-tenant facilities.
- Restaurants:Full-service establishments across the United Kingdom and North America specify customized clay-lined chambers for menu differentiation. Independent Indian restaurants in London and Birmingham drive replacement cycles as BIS-certified imports displace aging equipment.
- Catering Services:Mid-scale event operators in Delhi and Mumbai prioritize portable gas configurations with rapid setup breakdown. Municipal wood-to-gas conversion subsidies in these cities are accelerating equipment turnover.
- Food Trucks:Mobile operators require lightweight stainless steel constructions with secured fuel containment for highway transit compliance. Kumar Tandoor Machine Ms and similar fabricators compete on compact footprint designs.
- Hotels:Dubai's hospitality construction pipeline demands standardized installations across South Asian themed dining precincts. UAE Civil Defense certification requirements are compressing vendor qualification lists.
Restaurants command the largest procurement volume; food truck deployment is gaining share fastest as street food formats proliferate.
Installation Type:
Capital ownership models are fragmenting as cloud-kitchen operators treat equipment as interchangeable production assets rather than fixed infrastructure.
- Built-in:Fixed masonry or steel enclosures integrated during kitchen construction. Heritage restaurants in Rajasthan and Gujarat specify these for permanent authenticity signaling.
- Portable:Wheeled or modular units enabling redeployment across rotating cloud-kitchen tenants. Third-party infrastructure providers in New York standardize on 24-inch electric formats.
- Standalone:Self-contained floor units with integrated ventilation shrouds. Hotels in Riyadh entertainment districts specify these for standardized precinct installations.
- Customized:Fabrication-to-order chambers with dimensional or thermal specifications matched to specific menu requirements. Ranvir and Shri Krishna Cooking Equipments anchor positions in this segment.
Standalone units hold the largest share; portable configurations are expanding most quickly under asset-light operating models.
Size:
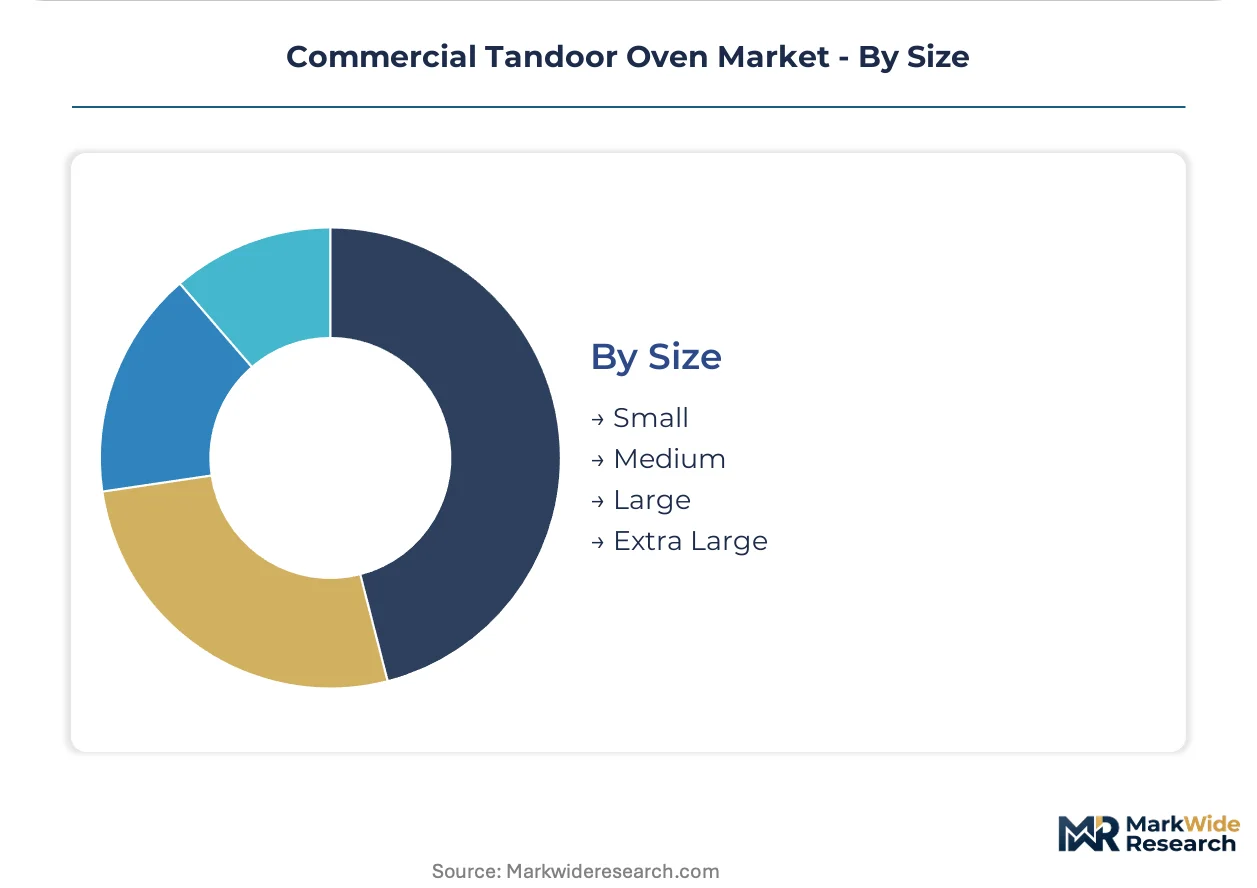
Throughput requirements and kitchen footprint constraints determine size selection, with regulatory pressure on ventilation capacity favoring smaller electric units in dense urban zones.
- Small:Chambers under 18 inches in diameter serving sub-50-cover operations. Tabletop electric models dominate this tier for ghost kitchen compatibility.
- Medium:18-24 inch diameter chambers balancing throughput with space efficiency. Catering services in Mumbai and Delhi concentrate procurement here.
- Large:24-36 inch diameter units for high-volume restaurants and hotel banquet operations. Dubai's hospitality pipeline specifies these for South Asian dining precincts.
- Extra Large:Custom fabricated chambers exceeding 36 inches for central commissary production. Limited deployment concentrated in large-scale catering cooperatives.
Medium sizes command the largest share; small formats are gaining share fastest as cloud-kitchen footprints shrink.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS certification requirements for commercial cooking appliances are reshaping product design priorities across export-oriented manufacturers. Regulatory pressure on emissions and fire safety is compressing acceptable design tolerances across all fuel types.
India
Uttar Pradesh fabrication clusters sustain high-volume output of customized clay-lined units. The Bureau of Indian Standards thermal efficiency mandates are pushing manufacturers toward standardized insulation ratings. Moradabad and Saharanpur metalworking centers face artisan welding skill attrition as younger workers abandon specialized argon-arc techniques.
United Arab Emirates
Dubai's hospitality construction pipeline continues adding South Asian themed dining concepts requiring standardized installations. UAE Civil Defense fire-safety certifications for commercial kitchens are compressing vendor qualification lists. Abu Dhabi-based hotel procurement teams specify certified units across entertainment district developments.
United Kingdom
Independent Indian restaurants across London and Birmingham are expanding authentic clay-oven menus and driving replacement cycles. CE marking requirements for European foodservice equipment imports add compliance layers favoring larger fabricators. Third-party kitchen infrastructure providers standardize on electric tabletop formats for multi-tenant facilities.
United States
Mid-scale caterers in Texas and Florida pilot hybrid gas-electric units to hedge against volatile natural gas tariffs. Municipal gas hookup moratoriums across metropolitan zones accelerate electric tandoor deployment. Ghost kitchen operators in New York treat equipment as interchangeable production assets rather than fixed capital.
Saudi Arabia
Riyadh and Jeddah entertainment district developments incorporate South Asian dining precincts requiring standardized installations at scale. Vision 2030 hospitality investments are pulling procurement toward certified commercial kitchen equipment. The central region's procurement authority is consolidating around real estate developers managing multi-tenant foodservice infrastructure.
Commercial Tandoor Oven Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the commercial tandoor oven supply base. The upper tier commands export certification capabilities and dedicated testing protocols for BIS and CE marking compliance. Below them, regional fabricators compete on customization velocity and localized service relationships. Consolidation pressure is intensifying as certification backlogs and artisan labor scarcity raise barriers for smaller workshops. Competitive moves center on geographic expansion into Gulf Cooperation Council hospitality markets and portfolio diversification toward electric and hybrid fuel configurations.
Among Uttar Pradesh-based fabricators, Ranvir leverages established metalworking clusters for high-volume customized output. Shri Krishna Cooking Equipments anchors mid-scale catering specialization through gas-fired configuration expertise. Kumar Tandoor Machine Ms occupies the portable installation segment, serving food truck operators with compact footprint designs. These three exemplify how regional specialists align production geography with distinct customer archetypes rather than competing directly across all segments.
| Leading Market Players |
|---|
| Ranvir |
| Shri Krishna Cooking Equipments |
| Kumar Tandoor Machine Ms |
| Mohanlal Tandoors |
| Nand Equipment Pvt. Ltd |
| SS Tan Tandoor |
| Dhanraj Bhati Tandoorwala |
| GULATI Tandoors |
| Sabari Kitchen |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Uttar Pradesh fabricators and UAE hospitality developers lock in both refractory clay supply access and price visibility for certified commercial tandoor installations across Dubai's construction pipeline. These contracts insulate manufacturers from Gujarat bentonite extraction quota volatility while committing buyers to standardized thermal efficiency tiers.
Pricing Analysis
Price spreads between Moradabad-fabricated units and European-certified alternatives exceed threefold, reflecting CE marking compliance costs and dedicated testing protocol investments. Three-tier pricing structure across heritage wood-fired, mid-scale gas, and compact electric tiers differentiates based on BIS certification grade and after-sales service bundling. Pricing pressure stems from induction cooking substitution in mid-scale catering operations. Food truck operators exhibit highest price sensitivity; Dubai hotel procurement teams prioritize certification over unit cost.
Supply Chain Analysis
Gujarat bentonite deposit extraction quotas underwrite refractory clay supply security for traditional chamber producers, constraining output expansion regardless of fabrication capacity. Artisan metalworking clusters in Uttar Pradesh and Rajasthan draw from stainless steel sheet, argon welding consumables, and salt-compound thermal binders. Single-source vulnerability concentrates in specialized argon-arc welding labor pools facing generational attrition. Distribution runs through regional equipment dealers serving independent restaurants and third-party kitchen infrastructure providers managing multi-tenant cloud facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance sensor contracts and remote temperature telemetry subscriptions represent a service-attach layer expanding faster than hardware shipments as multi-unit restaurant chains seek distributed kitchen fleet management capabilities.
For Market Incumbents: Compound certification capabilities across BIS, UAE Civil Defense, and CE marking to structurally exclude smaller Moradabad workshops from export market access. Defend margin position by anchoring in captive refractory clay supply through backward integration into Gujarat bentonite processing. Induction cooking substitution with char-simulation technology threatens mid-scale catering volume; prioritize hybrid gas-electric R&D to neutralize zero-emission alternatives. For New Entrants and Emerging Players: Anchor in Saudi Arabia Vision 2030 entertainment district developments where standardized procurement specifications favor certified newcomers over legacy Uttar Pradesh fabricators lacking dedicated testing protocols. Target portable electric tabletop configurations for New York and London cloud-kitchen infrastructure providers treating equipment as interchangeable production assets. Pursue white-label manufacturing partnerships with established UAE-based kitchen equipment distributors to bypass direct certification investments. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated fabricators with captive refractory supply and multi-certification testing infrastructure. Long-term viability hinges on electrification transition readiness and IoT-enabled service revenue streams. Target acquisition archetype: mid-scale Uttar Pradesh specialists with established gas-fired expertise seeking capital for electric product line expansion. Watch municipal gas hookup moratorium announcements across North American metropolitan zones as inflection indicators for electric variant demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Refractory Clay | Gujarat bentonite quarry acquisitions secure input supply against extraction quota restrictions. |
| Multi-Certification Testing Infrastructure | Dual BIS and CE marking capabilities unlock European and Middle Eastern hospitality procurement simultaneously. |
| IoT Sensor Platform Development | Temperature telemetry subscriptions generate recurring revenue from multi-unit restaurant chain clients. |
| Hybrid Fuel Configuration Launch | Gas-electric dual-mode units hedge municipal energy transition risks in Texas and Florida catering markets. |
| Cloud-Kitchen Equipment Leasing | Asset-light models align with third-party infrastructure providers standardizing on 24-inch electric formats. |
Study Parameters
A standing panel of commercial kitchen equipment procurement managers, tandoor fabrication shop owners, restaurant chain operations directors, and UAE hospitality development consultants provided ongoing calibration across primary interview cycles. Secondary validation drew from BIS certification databases, UAE Civil Defense approved equipment registries, customs export records for commercial cooking appliances, and hospitality construction pipeline announcements. Bottom-up unit shipment estimates from Uttar Pradesh and Rajasthan fabrication clusters were triangulated against top-down spending projections from hotel and restaurant capital expenditure disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The analytical framework modeled product type, end user category, installation format, and chamber size dimensions alongside fuel-type transition trajectories. CAGRs were derived from segmented growth rate differentials weighted by current revenue shares. Forecast inputs incorporated municipal energy transition timelines, ghost kitchen proliferation rates, and artisan welding labor attrition projections.
Material uncertainties — refractory clay extraction quota revisions, municipal gas infrastructure moratoriums, and induction cooking technology advancement — sit outside the modeled envelope. Forecasts reflect assumptions about certification backlog durations and hospitality construction pipeline completion rates. Practitioners should keep alternative scenarios live as Saudi Vision 2030 entertainment district procurement specifications and EU F-Gas Regulation ventilation redesign requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Global Digital Grocery Market
Food Service
Fast Food Market
Food Service
Breakfast Takeout Market
Food Service
Middle East and Africa Online Grocery Delivery Market
Food Service
Brazil Foodservice Market
Food Service
Asia-Pacific Online Grocery Delivery Market
Food Service
Commercial Charbroiler Market
Food Service
US Food Trucks Services Market
Food Service
Food Service Utensils Market
Food Service
Virtual Kitchen Market
Food Service
UAE Food Service Market
Food Service
India Online Grocery Market
Food Service
Countertop Pressure Fryer Market
Food Service
Inflight Catering Market
Food Service
Retail Bubble Tea Kits Market
Food Service
Fast Food and Quick Service Restaurant Market