
 United Arab Emirates Quick Service Restaurant Market | 2026-2036
United Arab Emirates Quick Service Restaurant Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Quick Service Restaurant Market Insights
Digital subscription loyalty programs is hardening as a core revenue layer in the UAE QSR landscape, transforming one-time transactions into recurring revenue streams. Americana Restaurants International PLC leverages its multi-brand portfolio to sustain cross-promotional loyalty mechanics across KFC, Pizza Hut, and Hardee's locations. M.H. Alshaya Co. WLL anchors its competitive stance through exclusive franchise rights that dominate mall-based food courts in Dubai and Sharjah. AlAmar Foods Co. specializes in localized menu engineering that competes for share among Gulf Arab taste preferences.
A quick service restaurant is a foodservice establishment characterized by limited table service, standardized menu offerings, and average transaction completion times under five minutes, with kitchen workflows engineered around batch-prepared proteins and rapid-assembly line configurations. Its primary commercial purpose is to deliver caloric convenience at price points accessible to high-frequency, time-constrained consumers. Burgers and sandwiches occupy the dominant volume position due to their portability and alignment with drive-thru and delivery infrastructure, while salads and wraps represent the fastest-growing product cluster as health-positioned menus attract young adult and office worker segments. Delivery service type is capturing disproportionate growth investment as aggregator platforms restructure last-mile economics across Abu Dhabi and Dubai.
MOHAP enforces Hazard Analysis Critical Control Point standards that shape kitchen design and supplier qualification across all seven emirates, while Dubai Municipality's Food Safety Department operates inspection regimes that directly affect brand operating permits. The UAE's forthcoming federal nutrition labeling requirements will force reformulation of high-sodium menu items and recalibration of children's meal portfolios. Stakeholders must monitor how MOHAP's evolving digital traceability mandates will reshape procurement relationships with protein and produce suppliers before compliance deadlines crystallize.
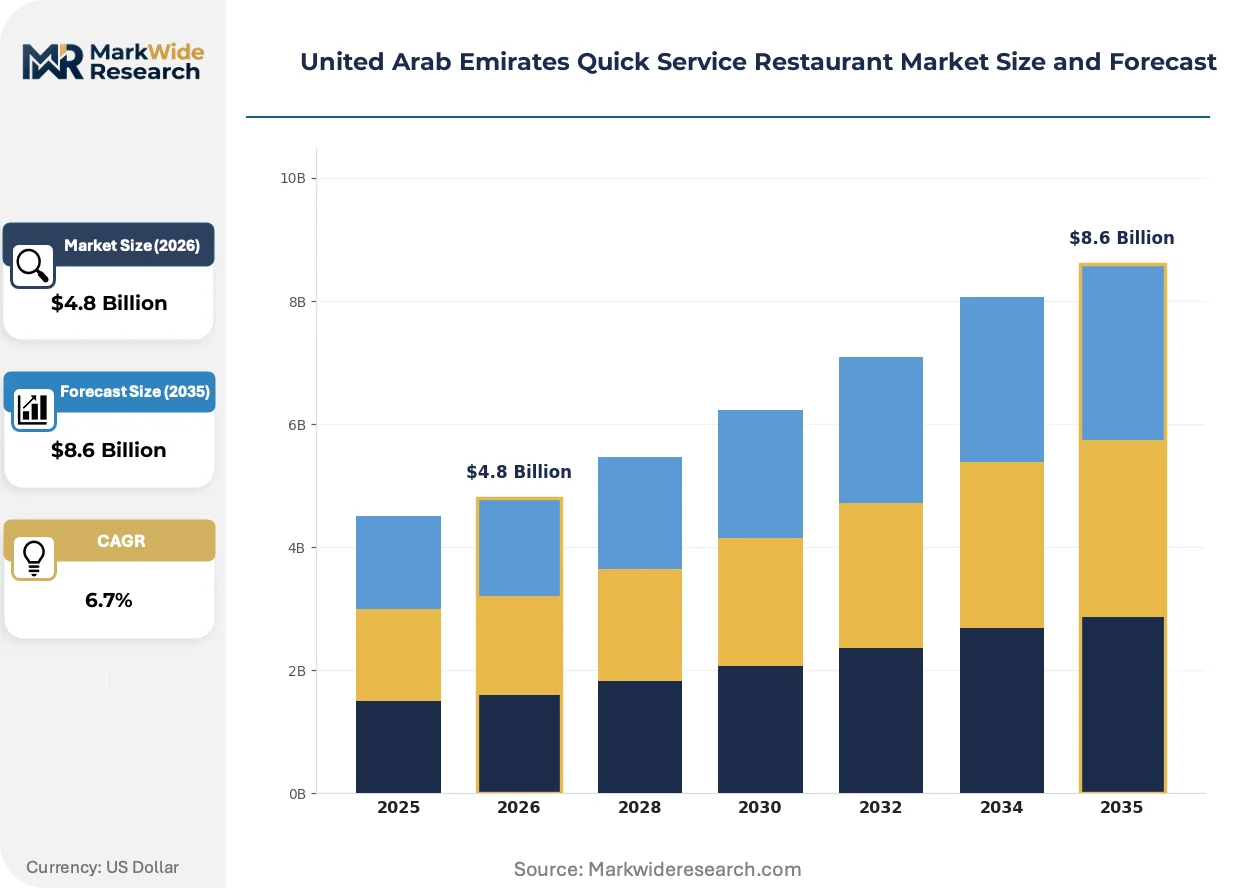
Market Dynamics
Mobile-first ordering infrastructure is compressing transaction completion times across UAE QSR operations while MOHAP's tightening food safety certification requirements force simultaneous capital deployment into kitchen redesign and digital traceability systems.
Growth Catalysts
- Aggregator platform penetration:Delivery apps restructure last-mile economics in Dubai and Abu Dhabi, expanding addressable customer bases beyond physical catchment zones.
- MOHAP digital traceability mandates:Federal compliance deadlines accelerate supplier qualification investments, filtering informal competitors from formal market participation.
- Tourism corridor density:Dubai's commercial hospitality infrastructure sustains premium throughput volumes unavailable to operators in secondary emirates.
Market Restraints
- Protein supply concentration:UAE imports over 90% of food inputs, exposing margin structures to Red Sea shipping disruptions and GCC-wide logistics bottlenecks.
- MOHAP inspection regime friction:Dubai Municipality's Food Safety Department operates permit-dependent enforcement that can halt multi-location operations for single-site violations.
- Real estate cost inflation:Mall-based food court premiums in Dubai and Sharjah compress unit economics for franchise operators locked into long-term lease structures.
Strategic Opportunities
- Northern emirate underpenetration:Ras Al Khaimah and Fujairah present whitespace for drive-thru formats with lower rent burdens and emerging residential density.
- Federal nutrition labeling tailwind:Forthcoming sodium disclosure requirements create first-mover advantage for operators with reformulated menus and children's meal portfolio recalibration.
- Cloud kitchen convergence:Dark kitchen infrastructure combined with aggregator platforms enables asset-light entry into delivery-only segments without front-of-house capital.
Industry Challenges
- HACCP certification timeline compression:MOHAP's evolving standards require continuous kitchen workflow re-engineering and staff retraining cycles that disrupt operational continuity.
- Legacy POS integration friction:Mobile ordering platforms must interface with franchise-mandated systems, creating data silos and inventory reconciliation errors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Quick Service Restaurant Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Burgers, Sandwiches, Salads, Wraps Service Type: Dine-in, Takeaway, Drive-thru, Delivery Customer Type: Families, Young Adults, Tourists, Office Workers Price Tier: Economy, Mid-range, Premium, Budget |
| Companies Covered | Americana Restaurants International PLC, M.H. Alshaya Co. WLL, Apparel Group, The Olayan Group, AlAmar Foods Co., Kamal Osman Jamjoom Group LLC, Alghanim Industries, Emirates Fast Food Company, ALBAIK Food Systems Company S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Quick Service Restaurant Market Trends and Innovations
Three interconnected shifts are restructuring UAE QSR operations: unified technology stacks compressing order-to-delivery workflows, federal nutrition mandates forcing menu architecture changes, and subscription loyalty mechanics transforming transaction frequency into predictable revenue streams.
Kitchen display systems integrated with aggregator APIs are unifying order ingestion across dine-in, drive-thru, and delivery channels into single workflow queues. Young adult consumers in Dubai expect sub-five-minute fulfillment regardless of entry point, forcing operators to abandon channel-siloed preparation lines. This consolidation is compressing labor deployment models and eliminating redundant staging stations previously dedicated to specific order sources.
MOHAP's forthcoming federal nutrition labeling requirements will force sodium disclosure on all menu boards and digital interfaces. High-sodium protein formulations face reformulation pressure, particularly in children's meal portfolios where parental purchasing decisions increasingly reference nutritional transparency. Operators are responding by engineering localized alternatives that maintain Gulf Arab taste profiles while complying with disclosure thresholds.
Subscription-based loyalty programs are displacing points-based accumulation models across Dubai and Abu Dhabi QSR networks. Young adult office workers prioritize predictable monthly meal budgets over sporadic discount chasing, shifting retention mechanics from transaction-triggered rewards to prepaid access structures. This behavioral pivot is most visible in commercial corridor locations where daily lunch frequency justifies subscription economics.
United Arab Emirates Quick Service Restaurant Market Segmentation
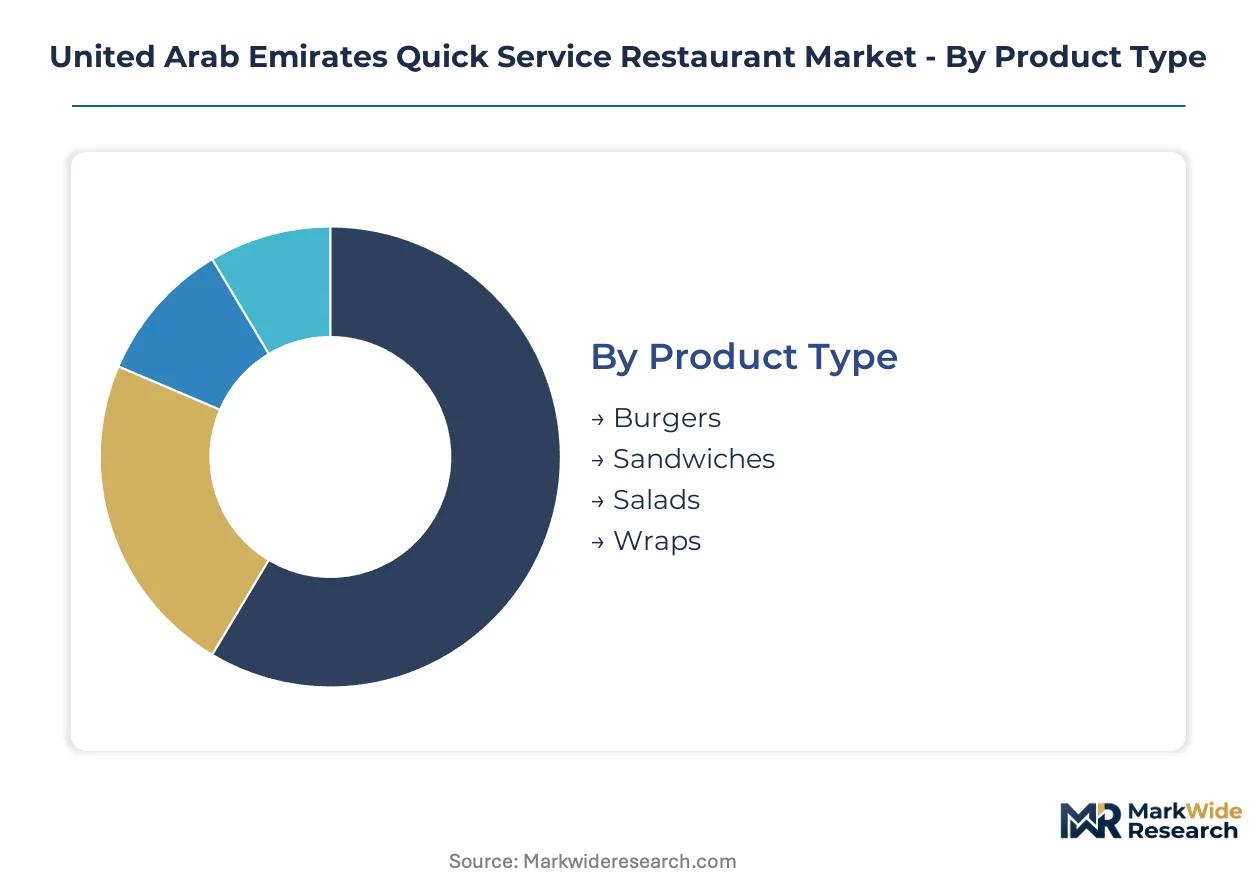
UAE QSR operators configure menu architecture, service infrastructure, and pricing ladders around distinct consumption occasions that vary by time-of-day, location density, and customer mobility constraints. Segmentation discipline determines capital allocation between front-of-house seating, drive-thru lanes, and cloud kitchen formats across Dubai's commercial corridors and emerging northern emirate catchments.
Product Type:
Menu selection hinges on portability requirements and preparation speed thresholds that align with channel-specific fulfillment constraints.
- Burgers:Batch-prepared protein patties with standardized topping configurations dominate drive-thru and delivery throughput in Dubai's tourism corridors. Demand concentrates in mall-adjacent and highway-accessible locations where execution speed sustains premium transaction volumes.
- Sandwiches:Cold and hot-pressed formats with localized fillings capture office worker lunch frequency in Abu Dhabi's commercial districts. Assembly-line configurations compress fulfillment windows below four minutes to match aggregator platform service level agreements.
- Salads:Health-positioned bowls with protein add-ons attract young adult consumers seeking nutritional transparency under forthcoming MOHAP sodium disclosure mandates.
- Wraps:Handheld formats with Gulf Arab flavor profiles compete for share in Sharjah mall food courts where family purchasing decisions prioritize shareable portion economics.
Burgers lead on scale; wraps lead on momentum.
Service Type:
Channel economics diverge sharply based on real estate cost absorption and labor deployment models across UAE emirates.
- Delivery:Aggregator-platform dependence restructures last-mile economics in Dubai and Abu Dhabi, expanding addressable customer bases beyond physical catchment zones. Dark kitchen infrastructure enables asset-light entry without front-of-house capital, though commission structures compress net margins.
- Drive-thru:Purpose-built lanes with dual-menu boards and staged payment windows sustain throughput volumes unavailable to dine-in formats in Ras Al Khaimah's emerging residential corridors.
- Dine-in:Seated service with limited table turnover competes for mall foot traffic in Dubai's hospitality zones where tourism density justifies premium rent burdens.
- Takeaway:Counter-service with minimal seating captures price-sensitive demand in Sharjah's labor camp proximate locations.
Delivery leads on expansion velocity; drive-thru leads on unit economics resilience.
Customer Type:
Purchasing frequency and average ticket size vary by demographic cohort mobility patterns and meal occasion substitution behavior.
- Young Adults:Mobile-first ordering preference with subscription loyalty program uptake concentrates in Dubai's commercial corridor office towers. Daily lunch frequency justifies prepaid monthly meal budgets over sporadic discount chasing.
- Families:Multi-person transactions with children's meal portfolio sensitivity drive weekend volume in Abu Dhabi mall food courts where nutritional transparency increasingly influences selection.
- Tourists:Transient demand with limited price elasticity sustains premium throughput in Dubai's hospitality infrastructure unavailable to operators dependent on resident repeat visitation.
- Office Workers:Time-constrained weekday lunch occasions with predictable location loyalty anchor commercial district QSR density in both emirates.
Young adults lead on digital engagement intensity; tourists lead on per-transaction yield.
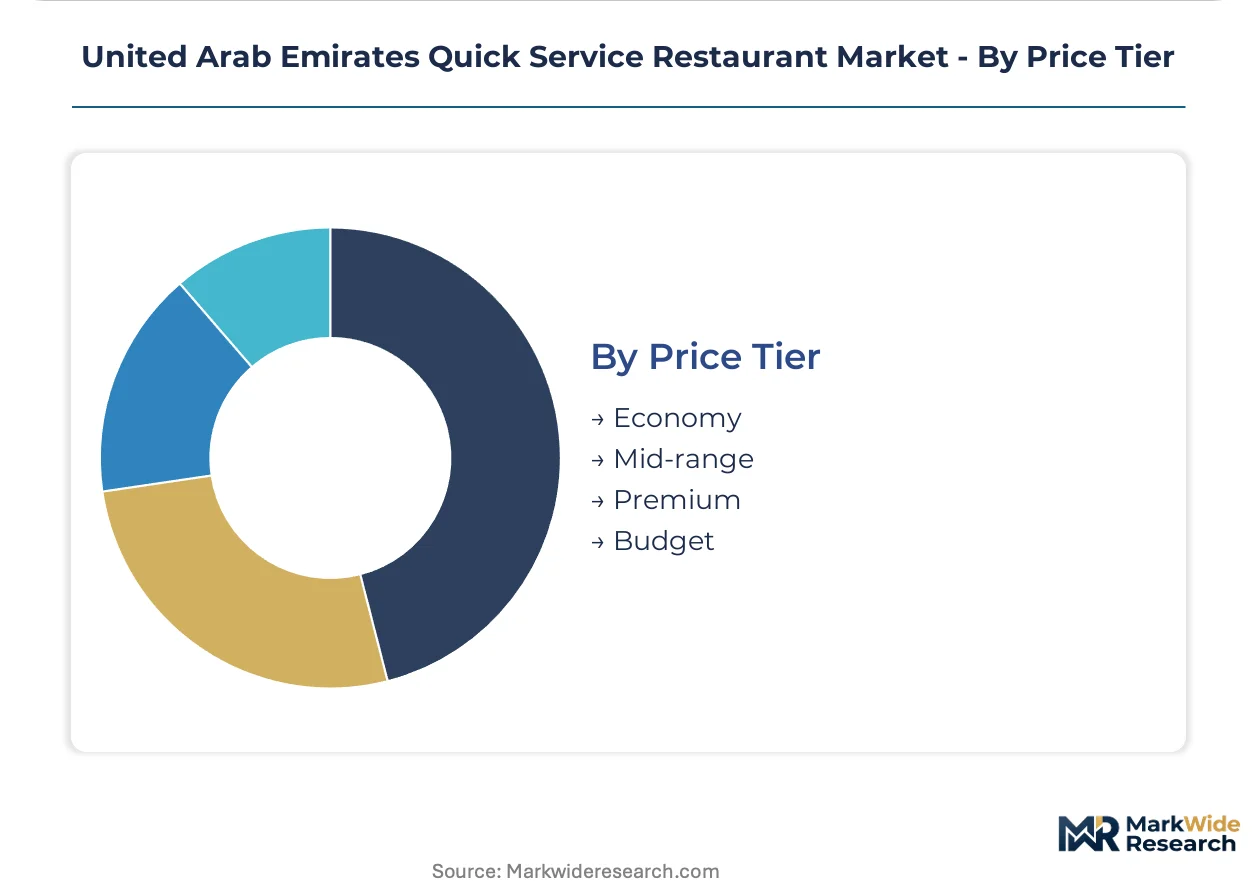
Price Tier:
Positioning on the value ladder determines ingredient sourcing flexibility and promotional depth capacity under protein cost volatility.
- Economy:Value-menu engineering with compressed protein portions and simplified topping matrices competes for price-sensitive segments in labor camp proximate Sharjah locations.
- Mid-range:Balanced quality-perception with localized menu adaptations captures mainstream family demand across Dubai's residential districts.
- Premium:Certified ingredient provenance and customization options attract affluent young adults in Abu Dhabi's high-income corridors where brand positioning justifies ticket premiums.
- Budget:Stripped-down formats with minimal service infrastructure serve migrant worker segments in northern emirates with limited disposable income.
Mid-range leads on volume concentration; premium leads on margin expansion potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai commands premium QSR throughput volumes that Abu Dhabi cannot replicate, while northern emirates remain structurally underpenetrated despite accelerating residential development.
Dubai
Tourism traffic and office density sustain transaction volumes in the commercial corridor. Dubai Municipality's Food Safety Department enforces permit-dependent inspection regimes that directly affect multi-location operating authority. Mall-adjacent and highway-accessible clusters concentrate drive-thru and delivery infrastructure where execution speed justifies premium rent burdens.
Abu Dhabi
Young adult office workers anchor daily lunch frequency with subscription loyalty program uptake in commercial district towers. MOHAP's HACCP certification requirements shape kitchen design and supplier qualification investments across the emirate. Aggregator platform penetration restructures last-mile economics, expanding addressable customer bases beyond physical catchment zones in the capital's hospitality zones.
Sharjah
Family purchasing decisions prioritize shareable portion economics in mall food courts where M.H. Alshaya Co. WLL holds exclusive franchise rights. MOHAP's tightening operational standards filter informal competitors from formal market participation. Labor camp proximate locations capture price-sensitive demand with compressed service infrastructure and stripped-down formats.
Ras Al Khaimah
Emerging residential density creates whitespace for drive-thru formats with lower rent burdens than Dubai or Abu Dhabi. Federal nutrition labeling requirements approaching compliance deadlines force menu reformulation investments. Purpose-built lanes with dual-menu boards sustain throughput volumes unavailable to dine-in formats in this developing corridor.
Fujairah
Geographic isolation from the Dubai-Abu Dhabi commercial axis limits aggregator platform service level agreement coverage. MOHAP's digital traceability mandates accelerate supplier qualification investments before compliance deadlines crystallize. Cloud kitchen infrastructure enables asset-light entry into delivery-only segments without front-of-house capital deployment.
United Arab Emirates Quick Service Restaurant Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with franchise operators dominating mall-based food courts while independent dark kitchen entrants capture delivery-only volume. The vendor base concentrates around multi-brand portfolio holders with cross-promotional loyalty mechanics and exclusive territorial rights. Three archetypes define competitive positioning: international franchise aggregators with localized menu engineering capabilities, regional conglomerates with captive real estate access, and cloud-native delivery specialists with asset-light operating models. Dominant competitive moves include portfolio diversification across protein formats and geographic expansion into northern emirate whitespace.
Among UAE-based franchise operators, Americana Restaurants International PLC and M.H. Alshaya Co. WLL exemplify the multi-brand aggregator archetype, while AlAmar Foods Co. occupies a position within the localized menu engineering tier. Americana's portfolio spans KFC, Pizza Hut, and Hardee's locations with cross-promotional loyalty mechanics. Alshaya dominates mall-based food courts in Dubai and Sharjah through exclusive franchise rights that anchor its competitive stance. AlAmar competes for share among Gulf Arab taste preferences with specialized protein and flavor profile adaptations.
| Leading Market Players |
|---|
| Americana Restaurants International PLC |
| M.H. Alshaya Co. WLL |
| Apparel Group |
| The Olayan Group |
| AlAmar Foods Co. |
| Kamal Osman Jamjoom Group LLC |
| Alghanim Industries |
| Emirates Fast Food Company |
| ALBAIK Food Systems Company S.A. |
| Others |
Pricing and Supply Chain Analysis
Outsourced protein procurement with limited backward integration into primary agriculture anchors both margin vulnerability and pricing inflexibility across UAE QSR operations. Franchise operators locked into long-term supply contracts with GCC-domiciled distributors face asymmetric cost pass-through when Red Sea shipping disruptions spike landed protein costs.
Pricing Analysis
Capacity additions in cloud kitchen infrastructure across Dubai and Abu Dhabi are reshaping price floors for delivery-only entrants, compressing premium capture for dine-in formats. Three-tier pricing structure across premium, standard, and economy levels stratifies by location rent burden and brand positioning, with mall-adjacent operators commanding ticket premiums over labor-camp proximate locations. Pricing pressure stems from aggregator commission structures that absorb 15-30 points of gross margin on delivery orders. Migrant worker segments in Sharjah and northern emirates exhibit highest price sensitivity, while tourists in Dubai's hospitality zones show least elasticity.
Supply Chain Analysis
Freight cost volatility through Jebel Ali and Khalifa Port corridors directly transmits into landed protein pricing for QSR operators dependent on frozen poultry and red meat shipments. Supply concentration rests on Brazil, Australia, and India as primary protein sources, with limited domestic production buffering import dependency. Frozen poultry cuts, processed cheese analogs, and palm oil derivatives constitute core input baskets. Single-source vulnerability runs through Brazilian beef suppliers subject to export quota restrictions. Distribution runs through cold-chain logistics operators with GCC-wide hub-and-spoke configurations serving franchise networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE QSR market functions as a regulatory compounder where MOHAP's digital traceability mandates and federal nutrition labeling requirements accelerate compliance investments that filter marginal operators from formal participation.
For Market Incumbents: Deploy cross-brand subscription loyalty mechanics to lock in young adult office worker frequency before cloud-native entrants capture digital-native demand. Americana Restaurants International PLC and M.H. Alshaya Co. WLL should accelerate kitchen display system standardization across KFC, Pizza Hut, and Hardee's locations to unify order ingestion workflows. Threat of aggregator platform disintermediation demands direct-to-consumer app investments that bypass commission structures. For New Entrants and Emerging Players: Launch via dark kitchen infrastructure in Ras Al Khaimah and Fujairah where lower rent burdens and emerging residential density create first-mover whitespace unavailable in saturated Dubai corridors. Target drive-thru formats with dual-menu board configurations to capture family demand in northern emirates lacking established QSR infrastructure. Go-to-market angle should emphasize localized menu engineering around Gulf Arab taste profiles that differentiate from standardized international franchise offerings. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-brand portfolio holders with exclusive franchise rights command mall-based food court positioning that independent operators cannot replicate. Long-term viability favors operators with backward integration into supply chain qualification systems and MOHAP compliance infrastructure. Acquisition target archetype: regional conglomerates with captive real estate access and established supplier audit protocols. Signal to watch: MOHAP digital traceability compliance deadlines crystallizing procurement relationships into defensible moats.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Kitchen Infrastructure Deployment | Dark kitchen convergence enables asset-light entry into delivery-only segments without front-of-house capital deployment across northern emirates. |
| Subscription Loyalty Program Launch | Prepaid monthly meal budgets transform young adult office worker transactions into predictable recurring revenue streams in Dubai commercial corridors. |
| MOHAP Digital Traceability Compliance Investment | Federal certification requirements filter informal competitors while accelerating supplier qualification investments that reshape procurement relationships. |
| Localized Menu Engineering | Gulf Arab flavor profile adaptations compete for family share in Sharjah mall food courts where M.H. Alshaya holds exclusive franchise rights. |
| Drive-Thru Format Expansion | Purpose-built lanes with staged payment windows sustain throughput volumes in Ras Al Khaimah's emerging residential corridors with lower rent burdens. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with QSR operations directors, franchise development executives, aggregator platform account managers, and MOHAP compliance officers with secondary validation. Secondary sources included Dubai Municipality Food Safety Department inspection records, MOHAP HACCP certification databases, customs import data for frozen protein categories, and SEC filings of listed franchise operators. Bottom-up unit economics modeling triangulated against top-down market sizing across emirate-level consumption patterns.
Historical reference periods anchored volume and value trajectories across the modeling period, with projection horizons extending through the forecast window. Segmentation dimensions modeled include product type, service channel, customer demographic, and price tier positioning. CAGRs derived from regression analysis of historical transaction frequency and ticket size evolution, incorporating tourism corridor density metrics and office worker population growth as industry-specific demand drivers.
Several conditions sit outside the modeled scope, including geopolitical disruptions to Red Sea shipping lanes, abrupt MOHAP regulatory timeline acceleration, and macroeconomic shocks affecting UAE tourism flows. Forecasts reflect assumptions about aggregator platform commission stability and protein import cost trajectories. Stakeholders should weight assumptions against their own operating context and supplier contract structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
United States Biodegradable Food Service Disposables Market
Food Service
Africa Foodservice Market
Food Service
Supermarkets Market
Food Service
Portable Buffet and Drop-In Ranges Market
Food Service
US Restaurant Point of Sale Solution Market
Food Service
Europe Smokeless Indoor Grills Market
Food Service
China Retail Bubble Tea Kits Market
Food Service
Belgium HRI Market
Food Service
One-Off Chopsticks Market
Food Service
Beverage Vending Machine Market
Food Service
Retail Bubble Tea Kits Market
Food Service
Europe Food Away from Home Market
Food Service
Stirrers Market
Food Service
United States Online Food Delivery Market
Food Service
Global Virtual Restaurant and Ghost Kitchens Market
Food Service
China Inflight Catering Market