
 Commercial Aircraft Video Surveillance Systems Market | 2026-2036
Commercial Aircraft Video Surveillance Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Video Surveillance Systems Market Intelligence
The divide between sophisticated, AI-integrated surveillance suites and basic, compliance-focused camera systems is consolidating the supplier base. Collins Aerospace leverages its incumbency in integrated avionics to offer premium, data-rich solutions. In contrast, Meggitt PLC specializes in high-reliability components, including cameras, that meet stringent aerospace environmental standards. AD Aerospace differentiates through its dedicated focus on certified video security systems specifically for aviation applications.
Commercial aircraft video surveillance systems are ruggedized camera networks engineered to meet stringent aviation environmental standards like DO-160. They serve to enhance operational safety, secure the cockpit and cabin, and provide data for incident analysis. Applications for cockpit security represent a mature base, whereas passenger monitoring and cargo inspection offer new expansion opportunities. IP-based surveillance technology is standard, but AI-enabled monitoring is reshaping system capabilities and value.
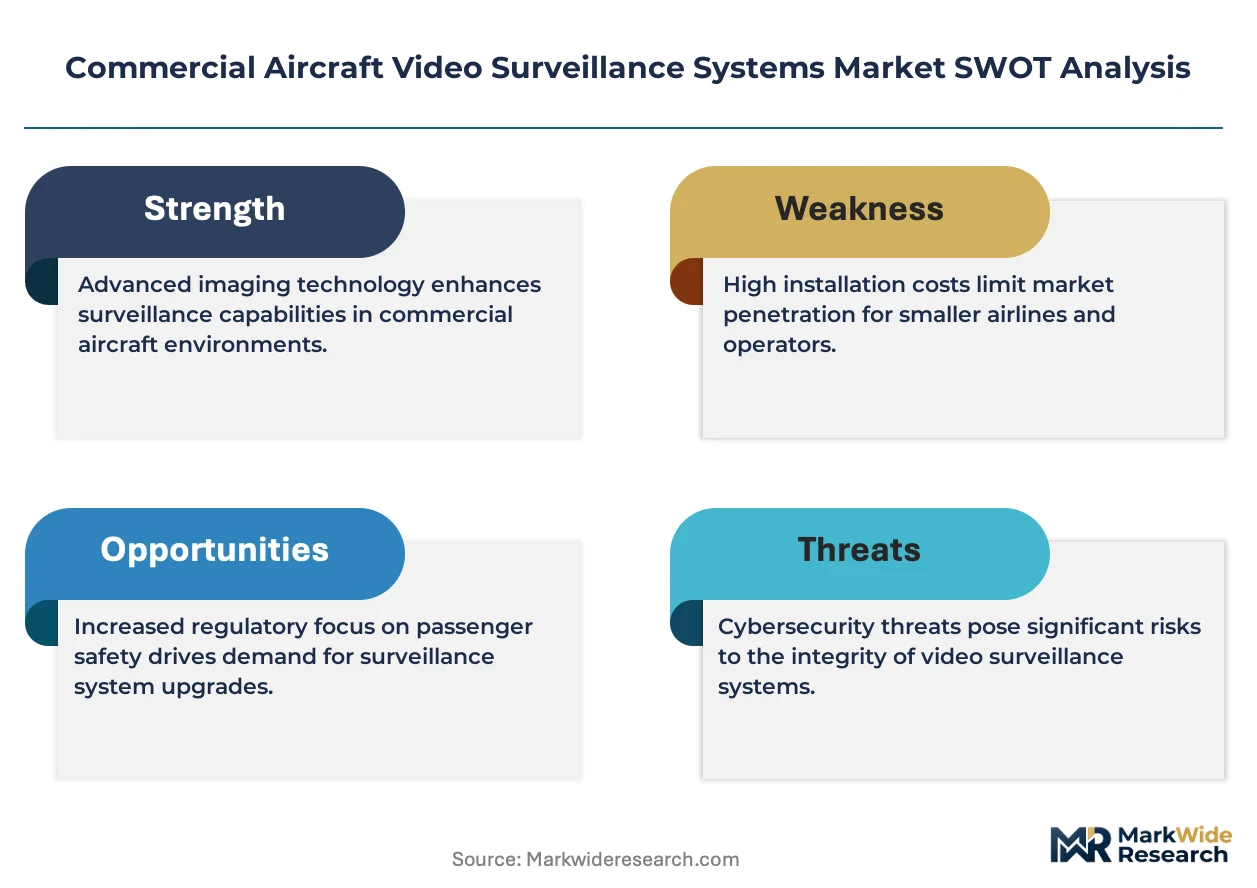
The market is shaped by stringent aviation safety regulations from authorities including the US Federal Aviation Administration (FAA) and the European Union Aviation Safety Agency (EASA). These bodies enforce mandates for systems like cockpit door surveillance and set the technical certification criteria for all onboard electronics. Aircraft manufacturers and airlines must decide whether to invest in advanced, data-intensive systems or procure minimal-compliance hardware to manage costs.
Market Dynamics
The market's core tension lies between procuring minimal-compliance hardware to satisfy FAA and EASA mandates, and investing in advanced, AI-enabled surveillance suites that provide operational intelligence beyond basic security, reshaping airline procurement strategies.
Growth Catalysts
- Regulatory Mandates:Directives from the FAA and EASA requiring cockpit door surveillance systems create a foundational, non-discretionary demand base for all new and retrofitted commercial aircraft, ensuring a stable market floor.
- Passenger Cabin Security:Airlines are increasingly deploying camera systems within the cabin to monitor passenger behavior, deter disruptive incidents, and improve crew response, expanding surveillance beyond the cockpit.
- AI-Enabled Analytics:The integration of artificial intelligence for real-time threat detection, abandoned object identification, and passenger counting enhances system value, moving beyond simple recording to proactive operational support.
Market Restraints
- Stringent Certification Costs:The rigorous environmental and performance testing required for DO-160 certification significantly elevates development costs and extends time-to-market for new surveillance components, creating high entry barriers.
- Legacy System Integration:Integrating modern IP-based video systems with older, analog-based avionics infrastructure on existing aircraft fleets presents significant technical challenges and added expense for airlines.
- Data Privacy Regulations:Regulations like the EU's GDPR impose strict limitations on the collection and use of passenger video data, complicating the deployment of advanced cabin monitoring systems in certain jurisdictions.
Strategic Opportunities
- Cargo Surveillance Expansion:Extending video monitoring into cargo holds offers a new application frontier, enabling enhanced security against tampering, improved tracking of high-value goods, and verification of load balancing.
- Predictive Maintenance Analytics:Utilizing exterior-mounted cameras with AI analytics to detect early signs of component wear, hydraulic leaks, or foreign object debris (FOD) on the tarmac presents a high-value operational use case.
- Emerging Market Retrofits:The growing fleets of airlines in Southeast Asia and the Middle East represent a significant opportunity for retrofitting older aircraft with modern surveillance systems to meet international security standards.
Industry Challenges
- Cybersecurity Vulnerabilities:The shift to IP-networked camera systems introduces significant cybersecurity risks, requiring robust protection against unauthorized access and data breaches to maintain system integrity and flight safety.
- Data Management Infrastructure:Handling the large volumes of high-definition video data generated by multi-camera systems requires substantial onboard storage and secure, high-bandwidth data offloading solutions, adding to system complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Video Surveillance Systems Market |
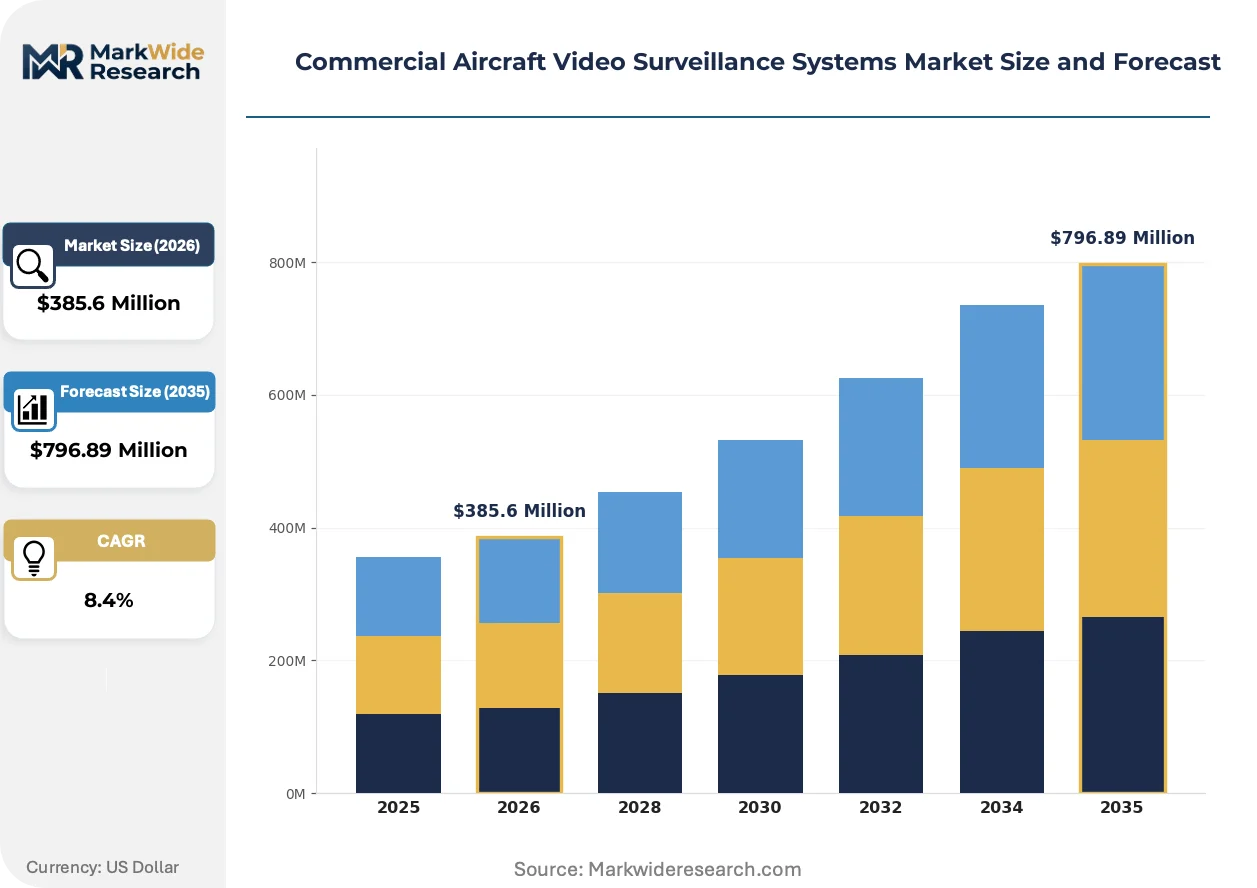
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Cameras, PTZ Cameras, Infrared Cameras, Thermal Cameras, Dome Cameras Technology: IP-Based Surveillance, Analog Surveillance, Wireless Surveillance, Cloud-Based Systems, AI-Enabled Monitoring Application: Passenger Monitoring, Cargo Inspection, Cockpit Security, Baggage Handling, Aircraft Exterior Surveillance End User: Airlines, Aircraft Manufacturers, Airport Authorities, Charter Operators |
| Companies Covered | AD Aerospace, Cabin Avionics, Collins Aerospace, Meggitt PLC, Latecoere, Kappa Optronics GmbH, Aerial View Systems, navAero, Global ePoint, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Video Surveillance Systems Market Strategic Shifts & Innovations
System evolution is defined by the transition from passive, compliance-driven recording to active, intelligent monitoring. This shift leverages AI and sensor fusion to extract actionable operational insights from video data, fundamentally changing the system's value proposition.
Edge computing within camera hardware allows for on-device AI processing, such as real-time passenger behavior analysis or object detection. Next-generation aircraft platforms and airlines focused on operational efficiency are the primary adopters of this technology. This decentralization of intelligence is electrifying the traditional centralized server architecture, enabling faster, more scalable analytics onboard.
The European Union's AI Act introduces a risk-based framework for artificial intelligence, classifying many aviation surveillance applications as high-risk systems. This legislation compels developers to implement stringent quality management and human oversight protocols. AI software providers for aviation must now navigate a more complex certification pathway, especially for systems in European airspace.
A notable demand-side shift involves airlines moving from one-time capital expenditures toward subscription-based service models. This disrupts traditional component sales, favoring integrators who bundle hardware, software updates, and analytical services into a recurring package. This procurement model is gaining traction among major carriers in North America seeking predictable costs and continuous upgrades.
Commercial Aircraft Video Surveillance Systems Market Segmentation
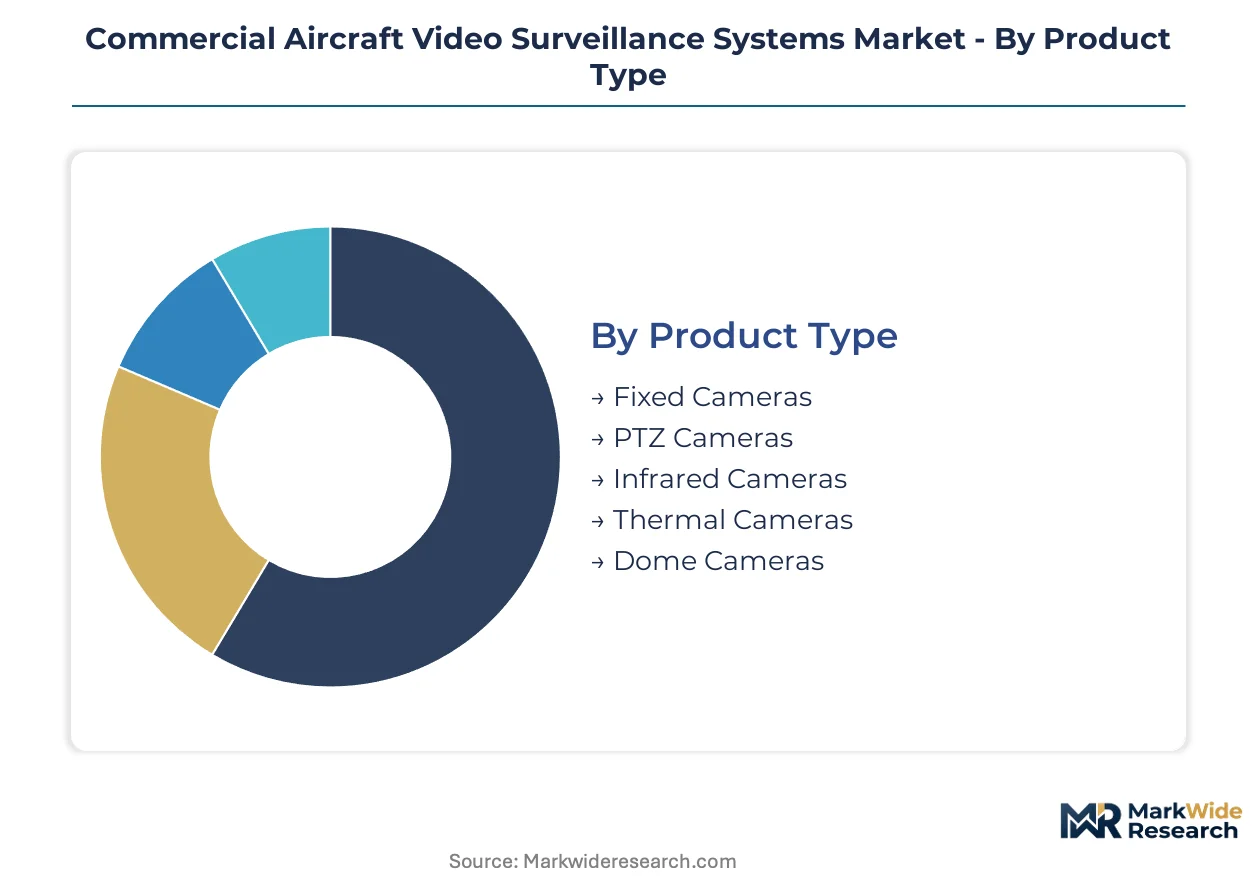
Segmentation within the commercial aircraft video surveillance systems market reveals the varied requirements for security, operational efficiency, and regulatory compliance across different aviation applications. Understanding these distinct segments helps stakeholders tailor solutions that address specific functional needs and procurement priorities.
Product Type:
The product type segmentation highlights the varying levels of camera integration, from dedicated standalone units to components embedded within broader surveillance architectures.
- Fixed Cameras:These are static cameras providing continuous monitoring of specific areas, often used for cockpit door surveillance or cabin overview. Demand concentrates in new aircraft installations and retrofit programs in the United States, driven by FAA security mandates.
- PTZ Cameras:Pan-Tilt-Zoom cameras offer dynamic coverage, allowing operators to remotely adjust view, scan, and zoom into areas of interest. Demand is expanding for passenger monitoring applications in Europe, as airlines seek to enhance crew response to disruptive incidents.
- Infrared Cameras:These cameras utilize infrared light for visibility in low-light or no-light conditions, crucial for external aircraft surveillance and cargo hold monitoring.
- Thermal Cameras:Thermal cameras detect heat signatures, enabling detection of objects or persons through smoke, fog, or complete darkness, valuable for perimeter security and fire detection.
- Dome Cameras:Encased in a protective dome, these cameras offer vandal resistance and a discreet appearance, frequently deployed in passenger cabins for unobtrusive monitoring.
Volume placements concentrate in Fixed Cameras; the faster expansion belongs to PTZ Cameras.
Technology:
Technology segmentation reveals the evolution of surveillance capabilities, from foundational methods to advanced, intelligent systems.
- IP-Based Surveillance:These systems transmit video data over internet protocol networks, enabling high-resolution digital feeds and integration with aircraft avionics. Demand is foundational across all new aircraft builds, with significant retrofit activity in France for modernization programs.
- AI-Enabled Monitoring:Incorporates artificial intelligence algorithms for automated analysis of video feeds, including object detection, behavior recognition, and threat assessment. Demand is emerging from major North American carriers seeking proactive operational intelligence and enhanced security beyond basic recording.
- Analog Surveillance:Older systems transmit video signals via coaxial cables, offering basic functionality but limited resolution and integration capabilities, primarily found in legacy aircraft.
- Wireless Surveillance:These systems use radio frequencies to transmit video, reducing cabling complexity but facing challenges with signal integrity and cybersecurity in aerospace environments.
- Cloud-Based Systems:Cloud platforms store and manage video data remotely, offering scalability and accessibility for post-flight analysis, though onboard processing remains critical for real-time applications.
Modernization efforts drive the adoption of IP-Based Surveillance; enhanced operational intelligence propels AI-Enabled Monitoring.
Application:
Application segmentation delineates the specific functional requirements addressed by video surveillance systems across various operational areas of an aircraft.
- Cockpit Security:Systems designed to monitor the cockpit door area, ensuring only authorized personnel access and complying with regulatory mandates from bodies like EASA. Demand is universal for all commercial aircraft, driven by stringent post-9/11 security protocols.
- Passenger Monitoring:Cameras installed within the cabin to observe passenger behavior, detect disruptive incidents, and assist crew in managing inflight situations. Demand is expanding among airlines in the United States aiming to improve passenger safety and operational control.
- Cargo Inspection:Surveillance systems deployed in cargo holds to monitor goods, detect tampering, and ensure proper loading, enhancing security and logistics integrity for high-value shipments.
- Baggage Handling:Video monitoring integrated into baggage loading and unloading processes helps track luggage, identify mishandling, and improve efficiency at aircraft interfaces.
- Aircraft Exterior Surveillance:Cameras mounted on the aircraft exterior monitor critical components, detect foreign object debris (FOD) on the tarmac, and assist in ground operations.
Regulatory compliance underpins Cockpit Security; operational efficiency and safety drive Passenger Monitoring.
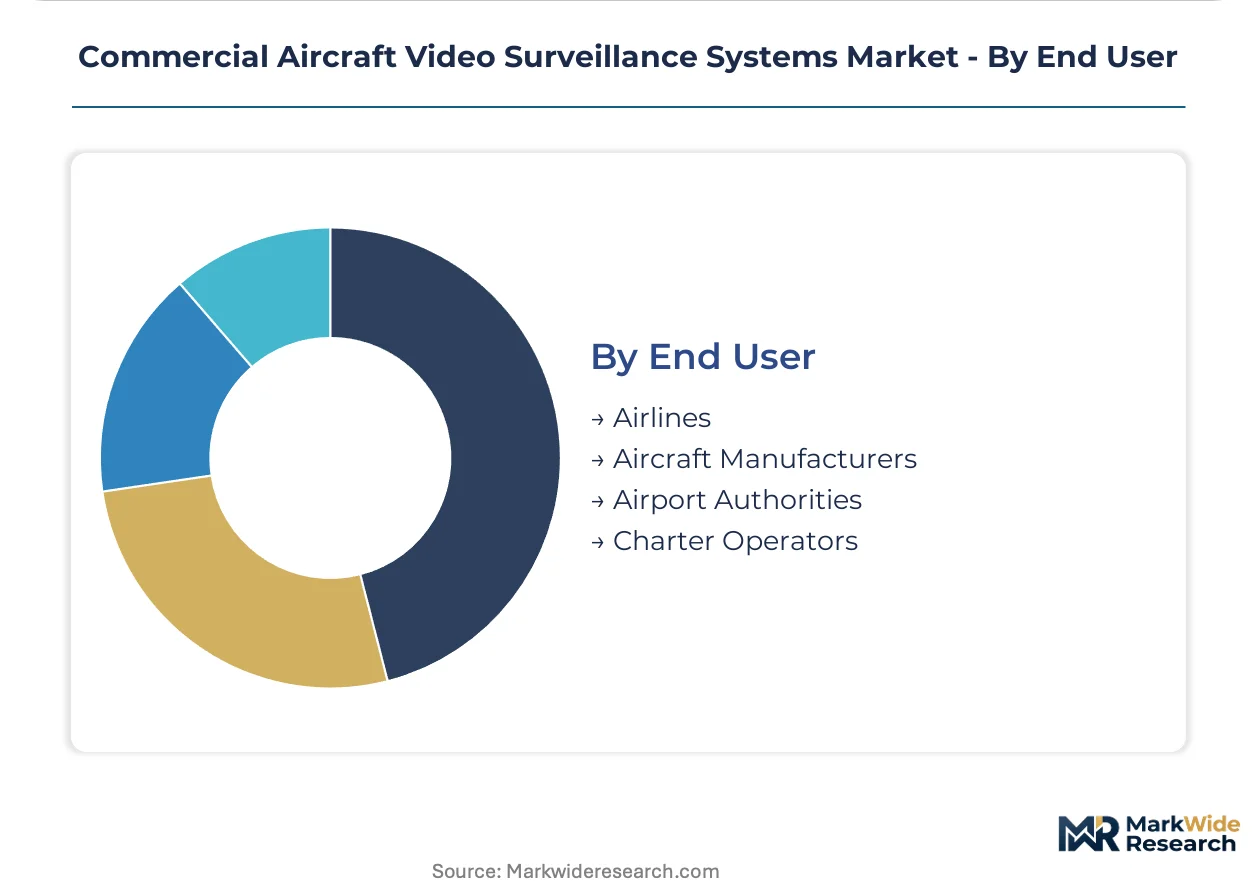
End User:
End user segmentation highlights the diverse stakeholders responsible for procuring and integrating commercial aircraft video surveillance systems, each with distinct needs.
- Airlines:These operators procure systems for their existing fleets and new aircraft deliveries, prioritizing solutions that balance security, operational data, and cost-effectiveness. Procurement strategies often involve balancing FAA and EASA mandates with advanced AI capabilities for cabin management.
- Aircraft Manufacturers:OEMs integrate surveillance systems directly into new aircraft designs, ensuring seamless compatibility with avionics and certification standards like DO-160. Major players like Boeing and Airbus drive system specifications and supplier selection during initial aircraft production.
- Airport Authorities:These entities primarily use surveillance systems for ground operations, perimeter security, and monitoring aircraft movements on the tarmac, often integrating with broader airport security infrastructure.
- Charter Operators:Smaller scale operators procure surveillance systems for their specialized fleets, often focusing on compliance with basic security mandates and cost-effective solutions for their specific operational profiles.
Airlines shape demand for operational features; Aircraft Manufacturers define integration standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The aerospace manufacturing hubs of Seattle and Toulouse significantly influence the global commercial aircraft video surveillance systems market. These centers drive demand for advanced surveillance solutions, integrating them into new aircraft designs and extensive retrofit programs. Regulatory bodies enforce stringent security protocols, shaping procurement decisions across continents.
United States
Demand for commercial aircraft video surveillance systems in the United States stems from both new aircraft installations and extensive retrofit programs. The US Federal Aviation Administration (FAA) mandates for cockpit door surveillance systems create a foundational market. Major aircraft modification centers in Wichita, Kansas, and Seattle, Washington, actively integrate advanced surveillance technologies into commercial fleets.
France
France experiences strong demand for commercial aircraft video surveillance systems, particularly for modernizing existing fleets and new aircraft production. The European Union Aviation Safety Agency (EASA) regulations drive significant adoption, especially for cockpit security applications. Toulouse, a primary European aerospace hub, concentrates substantial activity in system integration and development.
Germany
German aerospace manufacturers and airlines seek sophisticated video surveillance systems for enhanced operational safety and security. EASA mandates influence system specifications, with the German Federal Aviation Office (LBA) overseeing national compliance. Hamburg, a significant center for aircraft assembly and maintenance, drives innovation in advanced camera technologies and integration.
China
China's rapidly expanding commercial aircraft fleet fuels considerable demand for video surveillance systems, focusing on both new aircraft and retrofits. The Civil Aviation Administration of China (CAAC) sets national security and operational standards for onboard systems. Major aviation industrial zones in Xi'an and Shanghai are key centers for system integration and local manufacturing partnerships.
Japan
Japanese airlines are investing in modern video surveillance systems to upgrade aging fleets and enhance security protocols. The Japan Civil Aviation Bureau (JCAB) enforces strict safety and security regulations for all commercial aircraft operations. The Nagoya region, a prominent aerospace manufacturing cluster, supports the integration of high-reliability surveillance components into new aircraft.
Commercial Aircraft Video Surveillance Systems Market Key Industry Players
Premium-margin players sit above commodity-margin players across integration complexity and data analytics capabilities within the commercial aircraft video surveillance market. The market exhibits a tiered structure, with a few large integrated avionics providers alongside specialized component manufacturers. Companies primarily engage in strategic partnerships to expand their technology portfolios and pursue targeted geographic expansion.
Within the integrated avionics segment, Collins Aerospace leverages its broad aerospace portfolio to offer premium, data-rich surveillance solutions. Meggitt PLC, a UK-based engineering group, represents the specialized component archetype, focusing on high-reliability camera systems that meet stringent aerospace environmental standards. AD Aerospace, a dedicated specialist, anchors the certified video security systems niche, concentrating solely on aviation applications for differentiation.
| Leading Market Players |
|---|
| AD Aerospace |
| Cabin Avionics |
| Collins Aerospace |
| Meggitt PLC |
| Latecoere |
| Kappa Optronics GmbH |
| Aerial View Systems |
| navAero |
| Global ePoint |
Cost & Logistics Intelligence
DO-160 certification costs for new components elevate upstream development expenses, directly influencing the final pricing tiers for advanced surveillance systems sold to airlines and aircraft manufacturers.
Pricing Analysis
Value-based pricing, tied to operational intelligence and enhanced security outcomes, anchors premium surveillance solutions. The dominant pricing structure combines per-unit sales for hardware with subscription-based services for AI-enabled analytics. Certification level, particularly DO-160 compliance, and advanced AI analytics capability are key differentiation drivers. Pricing softness for basic systems reflects airlines prioritizing minimal compliance hardware, making them highly price-sensitive compared to aircraft manufacturers seeking integrated, data-rich solutions.
Supply Chain Analysis
Dual-sourcing requirements, often mandated by aircraft manufacturers for critical components, characterize the commercial aircraft video surveillance systems supply chain. Supply concentrates across the United States, the United Kingdom, and Germany, reflecting established aerospace component manufacturers. The chain relies on specialized imaging sensors and ruggedized electronics, creating single-source vulnerability for highly certified components. Distribution runs primarily through direct sales to aircraft OEMs and airlines, supplemented by integrators for retrofit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rigorous DO-160 certification process represents a significant capacity bottleneck for new product introduction, propping pricing for compliant systems.
For Market Incumbents: Extend integrated avionics platforms to encompass advanced AI-enabled surveillance as a standard offering. Bundle hardware, AI software, and analytical services into recurring revenue models to counter margin pressure from basic compliance hardware providers. Invest in proprietary AI model development and stringent certification processes to maintain a competitive advantage against emerging AI specialists.
For New Entrants and Emerging Players: The EU AI Act in Europe opens a window for specialized AI software providers focused on compliant, explainable AI for aviation. Target underpenetrated applications like cargo surveillance and predictive maintenance analytics on the tarmac. The retrofit market in Southeast Asia offers a penetrable segment for modern, IP-based systems through strategic partnerships.
For Investors and Strategic Acquirers: Increased airline investment in subscription-based analytical services is the leading indicator that the market's value proposition is shifting from hardware to data. The market exhibits long-term viability, underpinned by non-discretionary regulatory mandates and expanding AI-driven applications. Target acquisition archetypes include specialized AI software developers with certified aviation algorithms and robust data management solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Model Development for Predictive Analytics | This enhances system value by moving beyond recording to proactive operational support for airlines. |
| DO-160 Certification Expansion | This allows entry into new aircraft platforms and ensures compliance with stringent aviation safety regulations. |
| Subscription-based Analytics Service Launch | This shifts procurement from CapEx to OpEx, providing predictable costs and continuous upgrades for major carriers. |
| Partnership for Emerging Market Retrofits | This addresses the growing fleets of airlines in Southeast Asia and the Middle East, meeting international security standards. |
| Integration of IP-based Surveillance into New Builds | This ensures seamless compatibility with modern avionics and high-resolution digital feeds for aircraft manufacturers. |
Research Approach
Independent corroboration across regulatory filings, industry whitepapers, and technical specifications underwrites the qualitative findings and quantitative projections. This study integrated insights from primary interviews with avionics engineers, airline procurement officers, and regulatory compliance specialists. Secondary sources included EASA reports, FAA mandates, and major OEM product catalogs. A rigorous bottom-up and top-down triangulation approach ensured data consistency.
The forecast window was anchored to historical performance data from the last five years, establishing a robust baseline for future projections. The analytical framework modeled segmentation across product type, technology, application, end-user, and regional regulatory compliance. Compound annual growth rates were derived from a multi-variable regression model. Key industry-specific inputs included commercial aircraft delivery schedules and fleet retrofit program timelines.
The model assumes a particular technology adoption path; alternative pathways for AI-enabled monitoring would alter the outlook for system value. Forecasts reflect assumptions regarding cybersecurity mitigation and data privacy regulations. A model refresh is warranted upon material change in aviation security regulations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
North America Surveillance Analog Camera Market
Video Surveillance Systems
Global Body Worn Cameras Market
Video Surveillance Systems
United Kingdom Surveillance Camera Market
Video Surveillance Systems
Smart Doorbell Camera Market
Video Surveillance Systems
China Surveillance Analog Camera Market
Video Surveillance Systems
India Video Surveillance Market
Video Surveillance Systems
Asia-Pacific Surveillance Camera Market
Video Surveillance Systems
North America Crawler Camera System Market
Video Surveillance Systems
Concealed Weapon Detection Systems Market
Video Surveillance Systems
Wireless Security Camera Market
Video Surveillance Systems
Canada Surveillance Camera Market
Video Surveillance Systems
North America Smart Home Security Cameras Market
Video Surveillance Systems
In-Vehicle Video Surveillance Market
Video Surveillance Systems
Global GCC Video Surveillance Storage Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Systems Market
Video Surveillance Systems
Gunshot Detection System Market