
 Wireless Security Camera Market | 2026-2036
Wireless Security Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Security Camera Market Outlook
Shortage of embedded firmware engineers with video compression expertise is unwinding production timelines for several manufacturers. Arlo Technologies leverages its proprietary wireless protocol stack to sustain premium positioning in battery-operated segments. Ring anchors its ecosystem through deep integration with voice assistant platforms and subscription cloud storage. Reolink competes aggressively on price-performance ratios in the PoE and cellular backup categories.
A wireless security camera is a networked video surveillance device that transmits audio-visual data via radio frequency protocols rather than coaxial or Ethernet cabling, typically employing H.265 or H.266 encoding to reduce bandwidth consumption while maintaining resolution at 1080p or higher. These devices serve commercial loss prevention, residential property monitoring, and critical infrastructure perimeter defense by enabling real-time remote access through mobile applications. Dome cameras and smart cameras represent the most dynamic product categories, with the former dominating commercial retrofit installations due to vandal-resistant housings and the latter capturing margin pools through onboard AI analytics that reduce cloud dependency. Wi-Fi technology leads volume shipments across all end-user segments, though cellular connectivity is expanding fastest in rural industrial deployments where broadband infrastructure remains unreliable.
The FCC governs spectrum allocation and RF emission limits for devices operating in the 2.4 GHz and 5 GHz bands, directly constraining transmission range and power consumption trade-offs in product design. The EU AI Act and GDPR impose parallel compliance burdens on manufacturers selling facial recognition capabilities into European markets, forcing architecture decisions around edge versus cloud processing. California's SB-327 IoT security law has created a de facto national baseline for password and update requirements that most vendors now adopt across their entire product lines. Stakeholders must weigh the capital requirements of on-device inference chips against recurring cloud infrastructure costs as privacy regulations proliferate across jurisdictions.
Market Dynamics
The Wireless Security Camera Market is being fundamentally restructured by the migration of video analytics from cloud servers to edge inference chips, compressing latency and bandwidth costs while forcing architecture redesigns across the supply base.
Growth Catalysts
- California SB-327 IoT Security Law:This legislation mandates unique passwords and automatic security updates, creating de facto national standards that reduce fragmentation in firmware development cycles across manufacturers.
- Suburban single-family housing:DIY installation preferences in these developments concentrate demand for battery-operated and wire-free form factors, pulling volume toward simplified mounting systems.
- H.266/VVC codec deployment:Next-generation video compression is halving bandwidth requirements for 4K streams, enabling cellular-connected deployments in broadband-underserved industrial corridors.
Market Restraints
- Embedded firmware engineer scarcity:Talent shortages with video compression expertise are extending product development timelines by 6-12 months for multiple manufacturers.
- FCC Part 15 power limits:Unlicensed RF emission caps constrain transmission range in 2.4 GHz and 5 GHz bands, forcing battery life trade-offs in outdoor deployments.
- Cloud storage subscription fatigue:End-user resistance to recurring fees is capping attach rates for premium tiers, compressing margin pools in the residential segment.
Strategic Opportunities
- Rural industrial perimeter defense:Cellular backup connectivity is expanding fastest in broadband-unreliable zones, opening white space for solar-powered cellular cameras.
- EU AI Act compliance services:Facial recognition restrictions create demand for edge-only analytics architectures that eliminate cross-border data transfer risks.
- Smart home platform convergence:Deep voice assistant integration is becoming a table-stakes requirement, rewarding vendors with protocol-level partnerships.
Industry Challenges
- Edge inference chip qualification:Validating on-device AI performance across temperature and humidity ranges is extending certification timelines for outdoor-rated products.
- GDPR Article 35 DPIA requirements:Data protection impact assessments for biometric processing are adding legal overhead to European product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Security Camera Market |
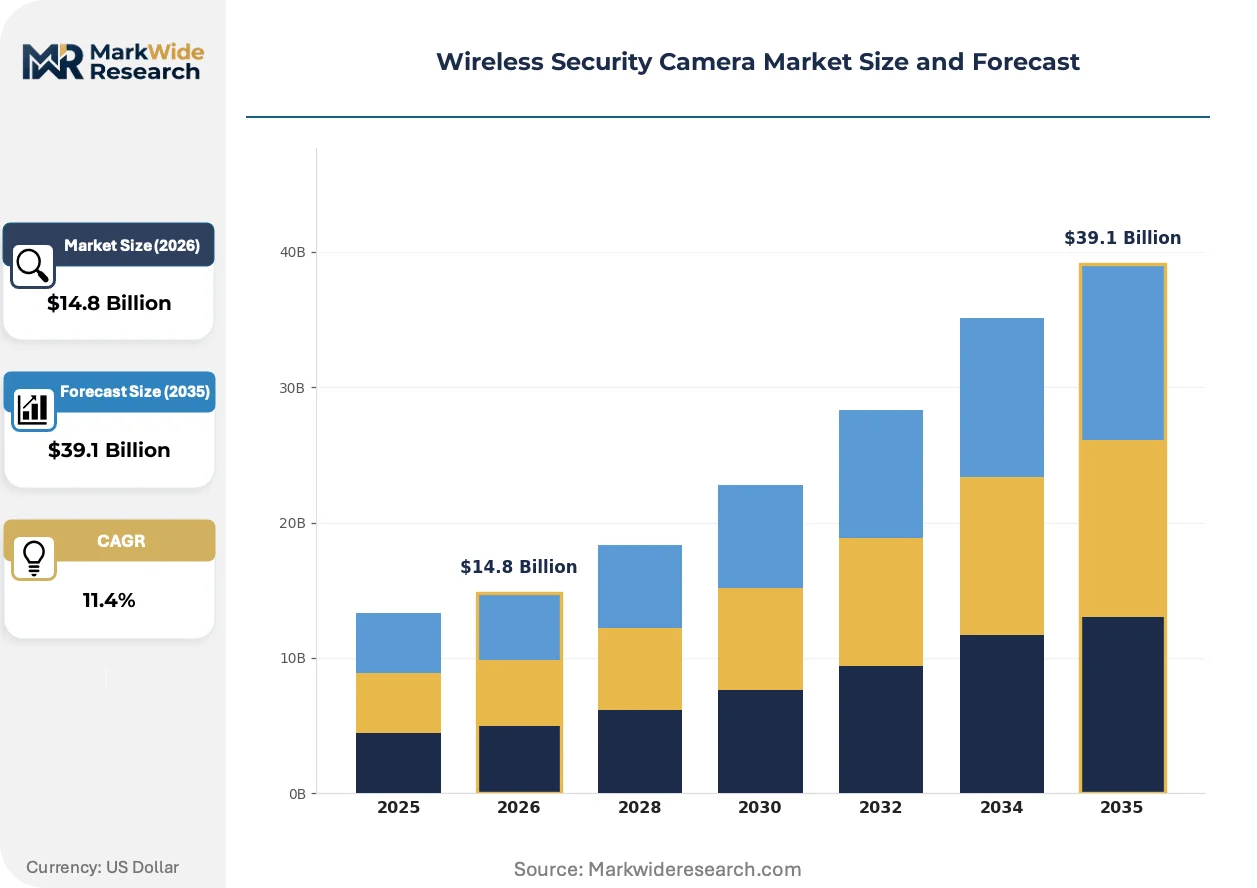
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $39.1 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bullet Cameras, Dome Cameras, PTZ Cameras, Smart Cameras Technology: Wi-Fi, Bluetooth, Zigbee, Cellular End User: Residential, Commercial, Industrial, Government Installation Type: Indoor, Outdoor, PoE, Wireless |
| Companies Covered | Arlo Technologies, Ring, Nest, Lorex, Wyze Labs, Reolink, TP-Link, Amcrest, D-Link, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Security Camera Market Strategic Shifts
Edge-native architectures are displacing cloud-dependent designs across the Wireless Security Camera Market, compressing latency and enabling privacy-compliant deployments in regulated jurisdictions.
On-device AI accelerators are supplanting cloud-based inference for motion detection and object classification. Suburban homeowners and small commercial operators are adopting these systems to eliminate subscription dependencies. This shift is compressing recurring revenue models while expanding addressable markets in bandwidth-constrained geographies.
GDPR's biometric data restrictions and the EU AI Act's facial recognition prohibitions are forcing architecture decisions around local processing. Manufacturers are redesigning European SKUs to disable cloud analytics entirely. Dome cameras with vandal-resistant housings are capturing retrofit volume in commercial installations where compliance audits are most stringent.
DIY installation preferences among suburban single-family buyers are reshaping channel economics. Big-box retailers and direct-to-consumer platforms are capturing share from professional installers. This pattern concentrates in North American markets where housing stock age and homeowner turnover sustain replacement cycles.
Wireless Security Camera Market Segmentation
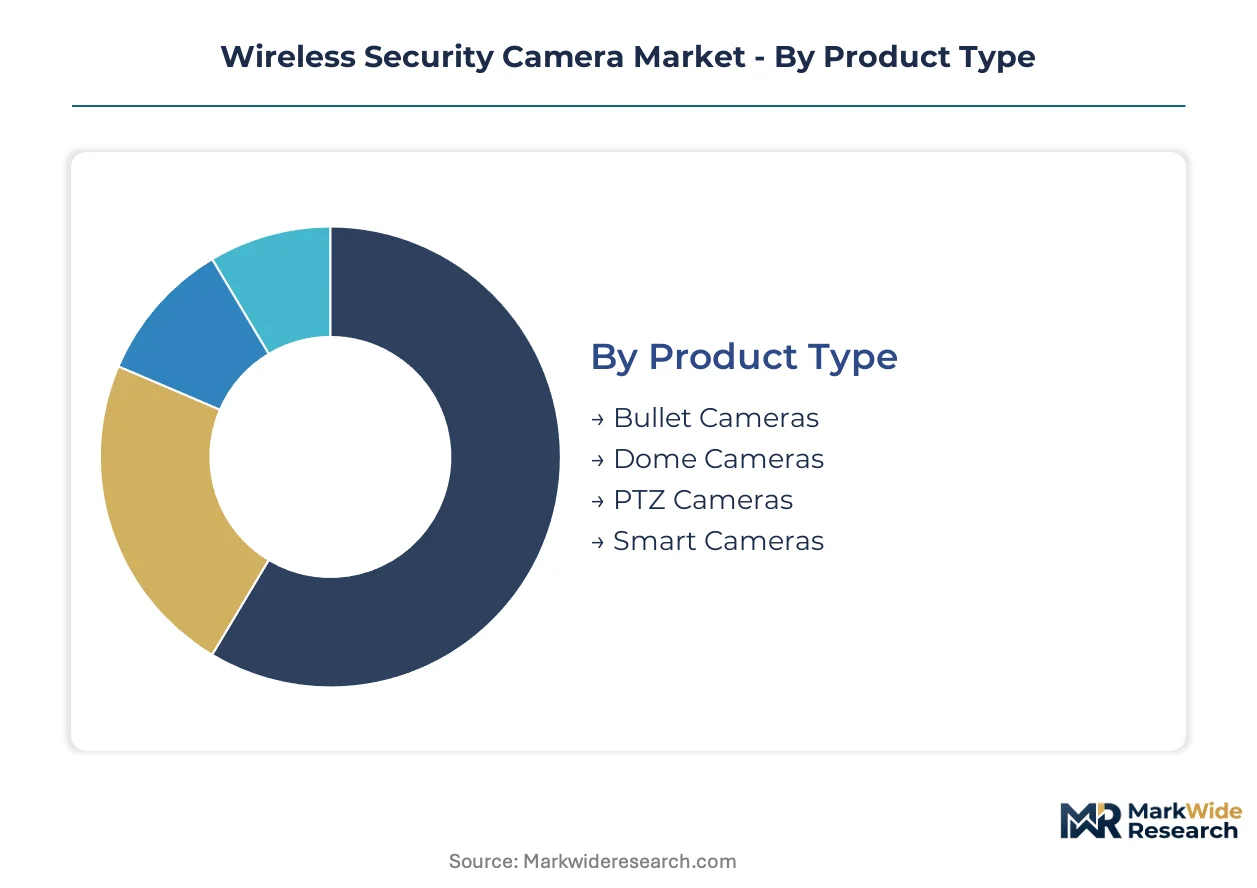
Segmentation in wireless security cameras determines compliance pathways, margin structures, and channel strategy. Product form factors dictate vandal-resistance ratings and AI chip placement. Connectivity technologies shape FCC, CE marking, and GDPR compliance burdens differentially across deployment contexts.
Product Type:
FCC Part 15 emission limits and EU AI Act facial recognition prohibitions create divergent certification costs across housing designs, with vandal-resistant commercial forms carrying heavier edge-compute validation overhead than residential variants.
- Dome Cameras:Vandal-resistant housings with tamper-proof mounting dominate commercial retrofit installations where compliance audits are most stringent. Demand concentrates in US urban retail corridors and EU transportation hubs where GDPR Article 35 data protection impact assessments are mandatory for biometric processing.
- Smart Cameras:Onboard AI accelerators enable edge-native analytics that eliminate cloud dependencies for privacy compliance. California SB-327 password mandates and automatic update requirements pull volume toward these architectures in North American suburban single-family developments.
- Bullet Cameras:Cylindrical weatherproof housings with fixed focal lengths serve cost-sensitive perimeter deployments.
- PTZ Cameras:Motorized pan-tilt-zoom mechanisms with optical zoom lenses target large-area industrial monitoring.
Established volume favors dome cameras; emerging adoption favors smart cameras.
Technology:
Cost tier stratification separates premium cellular connectivity from mass-market Wi-Fi, with subscription revenue models and hardware margins diverging sharply across protocol choices.
- Wi-Fi:IEEE 802.11ax chipsets in 2.4 GHz and 5 GHz bands deliver 1080p to 4K streams across residential deployments. FCC unlicensed spectrum rules constrain transmission range, forcing battery life trade-offs in outdoor installations across US suburban developments.
- Cellular:LTE-M and NB-IoT modems enable deployments in broadband-underserved industrial corridors where wired infrastructure is uneconomical. Rural perimeter defense in US agricultural zones and EU remote utilities drives steepest expansion trajectory for solar-powered cellular form factors.
- Bluetooth:Low-energy protocols support device provisioning and short-range hub connectivity in smart home ecosystems.
- Zigbee:Mesh networking standards integrate with home automation platforms for unified control interfaces.
Hardware margin concentrates in cellular; volume scale concentrates in Wi-Fi.
End User:
Customer type determines procurement channel, with DIY residential buyers favoring direct-to-consumer platforms and industrial purchasers requiring cellular backup and extended temperature certifications.
- Residential:Suburban single-family homeowners prioritize wire-free installation and voice assistant integration. Ring and Arlo ecosystems anchor demand through subscription cloud storage and smart home platform convergence in US metropolitan statistical areas.
- Industrial:Critical infrastructure operators require solar-powered cellular cameras with -40°C to 60°C operating ranges. US rural utilities and EU remote pipeline monitoring drive demand for H.266 compression to minimize data plan costs.
- Commercial:Retail loss prevention and office security favor dome cameras with centralized management platforms.
- Government:Municipal surveillance and law enforcement procurement faces strict data sovereignty and encryption requirements.
Subscription attach rates favor residential; equipment durability specifications favor industrial.
Installation Type:
Application environment dictates IP rating, power sourcing, and mounting complexity, with outdoor and PoE segments commanding premium pricing over indoor wireless alternatives.
- Outdoor:IP66 and IP67 ingress protection with integrated heaters and sun shields enables year-round operation. US Sun Belt states and EU Mediterranean climates concentrate replacement cycles for weather-degraded legacy units.
- PoE:IEEE 802.3af/at power sourcing eliminates separate electrical runs, reducing installation labor in commercial new construction. US office building retrofits and EU warehouse automation projects favor this approach for centralized cable management.
- Indoor:Lower IP ratings with compact form factors serve residential and small office deployments.
- Wireless:Battery and solar-powered designs target locations without electrical infrastructure access.
Installation labor savings favor PoE; deployment flexibility favors wireless.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential adoption patterns diverge sharply by geography, with suburban single-family homeowners in the United States driving wire-free form factors while European industrial corridors prioritize edge-native architectures for GDPR compliance.
United States
Suburban single-family housing developments in Texas and Florida concentrate DIY installation demand for battery-operated cameras with voice assistant integration. FCC Part 15 rules constrain transmission power in 2.4 GHz and 5 GHz bands, forcing manufacturers to optimize battery life trade-offs. The Dallas-Fort Worth metroplex anchors volume for smart home ecosystem convergence through subscription cloud storage models.
Germany
Industrial perimeter defense in the Ruhr Valley and Bavarian manufacturing zones drives demand for vandal-resistant dome cameras with edge-only analytics. EU AI Act facial recognition prohibitions and GDPR Article 35 data protection impact assessments mandate local processing architectures. Stuttgart's automotive supplier corridor deploys H.266 compression to minimize bandwidth costs in cellular-connected remote monitoring.
China
Smart city infrastructure in Shenzhen and Hangzhou scales domestic demand for AI-accelerated cameras with onboard inference chips. MIIT radio frequency regulations govern unlicensed spectrum allocation for consumer-grade Wi-Fi deployments. The Yangtze River Delta manufacturing cluster supplies global OEMs with cost-optimized sensor modules and compression chipsets.
United Kingdom
Retail loss prevention in London and Manchester commercial corridors favors centralized management platforms with centralized dome camera networks. CE marking requirements and GDPR biometric processing restrictions shape procurement specifications for edge-native deployments. The Southeast England logistics belt drives replacement cycles for weather-rated outdoor units in distribution center perimeters.
Japan
Aging population demographics in Tokyo and Osaka accelerate residential monitoring adoption for elder care applications. METI energy efficiency guidelines influence low-power design requirements for battery-operated form factors. The Nagoya industrial corridor integrates wireless cameras into factory automation systems for quality control and safety monitoring.
Wireless Security Camera Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with ecosystem architects controlling platform-level data flows while component specialists capture margin in edge inference and compression silicon. The vendor base stratifies across three archetypes: subscription-reliant ecosystem orchestrators, hardware-centric price-performance competitors, and vertical-integrated silicon-to-cloud operators. Consolidation pressure concentrates in the middle tier as scale requirements for AI chip qualification escalate. Dominant competitive moves include protocol-level smart home partnerships and geographic expansion into cellular-backup industrial segments.
Within the ecosystem-orchestrator archetype, Arlo Technologies and Ring exemplify platform-centric positioning through proprietary wireless stacks and voice assistant integration. Reolink anchors the price-performance tier with aggressive positioning in PoE and cellular backup categories. These three entities collectively represent the strategic divergence between recurring-revenue cloud models and hardware-margin-focused alternatives.
| Leading Market Players |
|---|
| Arlo Technologies |
| Ring |
| Nest |
| Lorex |
| Wyze Labs |
| Reolink |
| TP-Link |
| Amcrest |
| D-Link |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between chipset suppliers and camera OEMs lock in both H.266 encoder access and cost visibility across 24-36 month procurement windows, insulating tier-one manufacturers from spot-market volatility in edge inference silicon while compressing margin flexibility for smaller competitors lacking volume commitments.
Pricing Analysis
Subscription-tiered pricing dominates residential segments, with hardware margins subsidized by cloud storage attach rates. Price differentiation separates FCC-certified outdoor units with extended temperature validation from indoor Wi-Fi variants lacking vandal-resistant housings. Cost compression in cellular-connected industrial tiers intensifies as solar-powered form factors commoditize. DIY suburban homeowners exhibit highest price sensitivity, while critical infrastructure operators prioritize durability specifications over per-unit cost.
Supply Chain Analysis
Just-in-time inventory strategies prevail among Wi-Fi camera assemblers, whereas cellular and solar-powered industrial variants require strategic stockpiling of LTE-M modems and photovoltaic components. Manufacturing concentrates in China, South Korea, and Vietnam, with Yangtze River Delta facilities supplying compression chipsets and Shenzhen clusters handling final assembly. Supply chain risk hinges on single-source vulnerability for on-device AI accelerators. Distribution runs through big-box retail and direct-to-consumer platforms for residential segments, with industrial procurement flowing through systems integrators and security contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Professional monitoring services and integrated smart home platforms present substitution threats that hardware-centric incumbents must neutralize through ecosystem lock-in and recurring revenue attachment.
For Market Incumbents: Compound ecosystem defensibility through protocol-level voice assistant partnerships and exclusive wireless stack licensing. Deepen backward integration into edge inference chip design to reduce qualification timelines and capture margin pools from AI-native analytics. Counter subscription fatigue by bundling local storage hardware with premium firmware tiers that eliminate cloud dependency. For New Entrants and Emerging Players: CE marking fast-tracks for GDPR-compliant edge-only architectures open European industrial corridors where incumbent cloud dependencies create compliance friction. Target rural US utilities and EU remote pipeline monitoring with solar-cellular form factors underserved by Wi-Fi-centric portfolios. Pursue direct-to-consumer launch through specialty security retailers rather than competing for big-box shelf space against established ecosystems. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated silicon-to-cloud operators with captive compression codec capabilities and cellular certification expertise. Long-term viability favors entities controlling both hardware margin and recurring revenue streams rather than pure-play hardware vendors facing subscription attach rate compression. Watch cellular data plan pricing inflections as the signal triggering accelerated solar-powered industrial deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Architecture Migration | On-device AI processing eliminates GDPR cross-border transfer risks while reducing cloud infrastructure costs. |
| Cellular Connectivity Certification | LTE-M and NB-IoT module validation opens broadband-underserved industrial corridors in rural US and EU zones. |
| Smart Home Platform Integration | Deep voice assistant embedding locks in suburban residential demand through ecosystem switching costs. |
| H.266 Codec Deployment | Next-generation compression halves bandwidth requirements, enabling 4K streams over constrained cellular links. |
| Solar-Powered Form Factor Development | Photovoltaic integration with battery backup addresses perimeter defense in locations lacking electrical infrastructure. |
Study Parameters
Cross-validation between FCC equipment authorization databases and EU CE marking registries anchors the qualitative findings on certification pathway divergence. Primary interviews with embedded firmware engineers, smart home platform architects, and security contractor procurement managers combined with secondary analysis of MIIT radio frequency filings, customs trade data for image sensor modules, and hyperscaler IoT capex disclosures. Bottom-up unit economics triangulate against top-down market sizing across connectivity technology and end-use segments.
Sensitivity analysis on cellular data plan pricing and AI chip yield rates shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product form factor, connectivity protocol, installation environment, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and greenfield deployment trajectories, with inputs from H.266 adoption curves and edge inference cost decline assumptions.
Decision-makers should treat outputs as directional under stable FCC Part 15 emission limits and sustained GDPR enforcement intensity; material deviation would warrant model refresh. Forecasts reflect assumptions around firmware engineer supply elasticity and cloud storage subscription attach rate floors. Revision becomes warranted when cellular module lead times or edge chip qualification timelines cross thresholds that alter competitive entry economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Video Surveillance Software Market
Video Surveillance Systems
North America Surveillance IP Camera Market
Video Surveillance Systems
China Surveillance Camera Market
Video Surveillance Systems
Latin America Video Surveillance Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Storage Market
Video Surveillance Systems
Global Trade Surveillance Systems Market
Video Surveillance Systems
Brazil Surveillance IP Cameras Market
Video Surveillance Systems
Asia-Pacific Surveillance Camera Market
Video Surveillance Systems
North America Crawler Camera System Market
Video Surveillance Systems
Canada Surveillance Analog Camera Market
Video Surveillance Systems
Europe Surveillance Camera Market
Video Surveillance Systems
China Surveillance Storage Market
Video Surveillance Systems
Global CCTV Market
Video Surveillance Systems
Brazil Surveillance Camera Market
Video Surveillance Systems
Security Cameras (IR Illuminator) Market
Video Surveillance Systems
Canada Video Surveillance Market