
 North America Crawler Camera System Market | 2026-2036
North America Crawler Camera System Market Size, Share, and Industry Trends Forecast 2026-2036
North America Crawler Camera System Market Analytics
Aftermarket service revenue is tilting toward predictive maintenance contracts and fleet refurbishment programs. CUES Inc. leverages its established dealer network to control channel access across the United States. Deep Trekker Inc. differentiates through portable, battery-powered designs that reduce deployment complexity for municipal crews. Envirosight LLC anchors its position in sewer-specific applications with integrated software workflows for defect coding and reporting.
A crawler camera system comprises a tethered, remotely operated vehicle equipped with illumination and imaging sensors, typically rated for ingress into pipes between 6 and 60 inches in diameter, designed to capture real-time video and still imagery from the interior of inaccessible conduits. The primary commercial purpose centers on structural condition assessment, leak detection, and sediment profiling without requiring excavation or flow interruption. Pipeline Inspection applications dominate volume given regulatory mandates for gravity sewer and force main integrity programs, while Thermal Imaging camera types command premium positioning in industrial settings where heat signatures reveal active leaks or joint failures. High Definition configurations sustain the broadest addressable base across municipal and commercial end users.
The EPA enforces Clean Water Act compliance through consent decrees that mandate capacity management, operations, and maintenance programs, directly stimulating crawler camera procurement by municipal wastewater authorities. NHTSA and OSHA frameworks influence equipment design standards for roadway work zone deployment and confined space entry safety. State-level environmental regulators in California, Texas, and New York layer additional inspection frequency requirements onto federally mandated schedules. Stakeholders must monitor the divergence between federal infrastructure funding cycles and state environmental enforcement intensity to calibrate fleet investment timing and geographic prioritization.
Market Dynamics
EPA consent decrees and CMOM enforcement are compressing municipal procurement cycles, forcing wastewater utilities to accelerate crawler camera fleet modernization ahead of traditional capital replacement schedules. This regulatory pressure is restructuring vendor relationships toward predictive maintenance partnerships and fleet-as-a-service models.
Growth Catalysts
- EPA CMOM Mandates:The EPA's Capacity, Management, Operations, and Maintenance program compels municipal wastewater authorities to conduct systematic sewer condition assessments, directly stimulating crawler camera procurement across the Great Lakes industrial corridor.
- Combined Sewer Overflow Remediation:Infrastructure spending in Illinois, Ohio, and Michigan targets aging combined sewer systems, creating sustained demand for high-definition pipeline inspection equipment capable of 6-to-60-inch diameter coverage.
- Lithium-Ion Battery Advancement:Portable, battery-powered crawler designs are reducing deployment complexity for municipal inspection crews, eliminating generator dependency and enabling same-day mobilization to multiple sites.
Market Restraints
- Optical Sensor Supply Concentration:High-grade CMOS and thermal imaging sensors depend on concentrated Asian manufacturing capacity, exposing North American system integrators to lead-time volatility and tariff exposure.
- Confined Space Entry Standards:OSHA's stringent work zone safety requirements for sewer entry operations add compliance layers that extend deployment preparation timelines and elevate crew certification costs.
- Drone-Based Visual Inspection:Aerial and manhole-deployed drone systems are capturing preliminary assessment work previously reserved for crawler entry, compressing addressable volume for traditional tethered systems.
Strategic Opportunities
- Texas Water Infrastructure Gaps:Rapid municipal growth in Texas metropolitan corridors has outpaced sewer inspection capacity, creating underpenetrated demand for rental and lease-based crawler services.
- AI-Assisted Defect Coding:Machine vision algorithms trained on NASSCO PACP standards are converging with crawler hardware, enabling automated crack and infiltration classification that reduces engineering review labor.
- Force Main Assessment Expansion:Pressure-rated crawler configurations are opening inspection access to previously unexaminable force mains, extending equipment utilization beyond gravity sewer applications.
Industry Challenges
- NASSCO PACP Certification Bottlenecks:The Pipeline Assessment Certification Program's limited training capacity is constraining the supply of qualified defect coders, delaying report delivery and contract closeout.
- Legacy GIS Integration Friction:Municipal asset management systems built on decade-old geospatial databases require manual data transformation to accept modern crawler inspection outputs, extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Crawler Camera System Market |
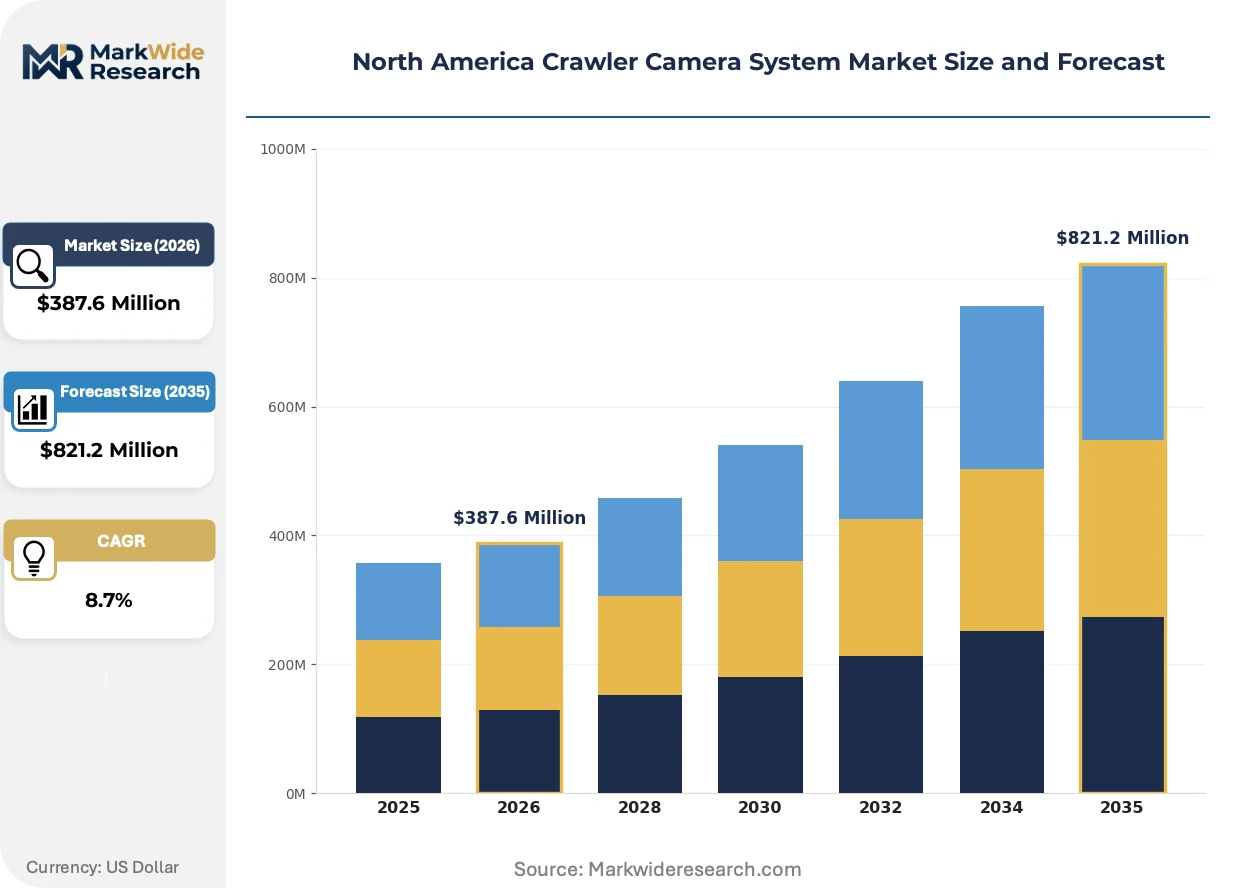
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User: Oil & Gas, Construction, Mining, Environmental Inspection Camera Type: High Definition, Thermal Imaging, 3D Camera, Pan-tilt-zoom Application: Pipeline Inspection, Structural Analysis, Underwater Exploration, Security Surveillance Distribution Channel: Direct Sales, Online Retail, Distributors, Retail Outlets |
| Companies Covered | CUES Inc., Deep Trekker Inc., Envirosight LLC, Rausch USA, ULC Pipeline Robotics, LLC, AM Industrial, Subsite Electronics, RPIC, Hathorn Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Crawler Camera System Market Evolving Landscape
Sensor fusion and software-defined inspection workflows are redefining how crawler systems capture, process, and monetize subsurface data. Equipment vendors are repositioning around data service revenue rather than hardware shipment volume.
Multi-sensor payload architectures are hybridizing traditional visual inspection with sonar profiling and laser ring measurement within single platform deployments. Municipal utilities in the Midwest are adopting these configurations to capture geometric deformation and sediment accumulation in a single pass, collapsing what required three separate equipment mobilizations into one inspection cycle. This convergence is compressing per-foot inspection costs and accelerating consent decree compliance timelines.
The EPA's escalating enforcement of Clean Water Act consent decrees is mandating documented capacity assurance across combined sewer systems. Industrial consequence includes mandatory inspection frequency minimums that outstrip manual crew availability, forcing automation investment. Large utilities in Michigan and Ohio are responding by centralizing fleet procurement under cooperative purchasing agreements to achieve volume pricing on hybrid sensor platforms.
Service unbundling is separating hardware ownership from inspection labor and data interpretation. Municipal buyers in California and New York are migrating toward contractor-managed fleet models where equipment availability guarantees replace capital ownership. This shift is most visible among mid-sized utilities lacking dedicated sewer maintenance divisions, where third-party inspection services now capture seventy percent of annual pipeline assessment volume.
North America Crawler Camera System Market Segmentation
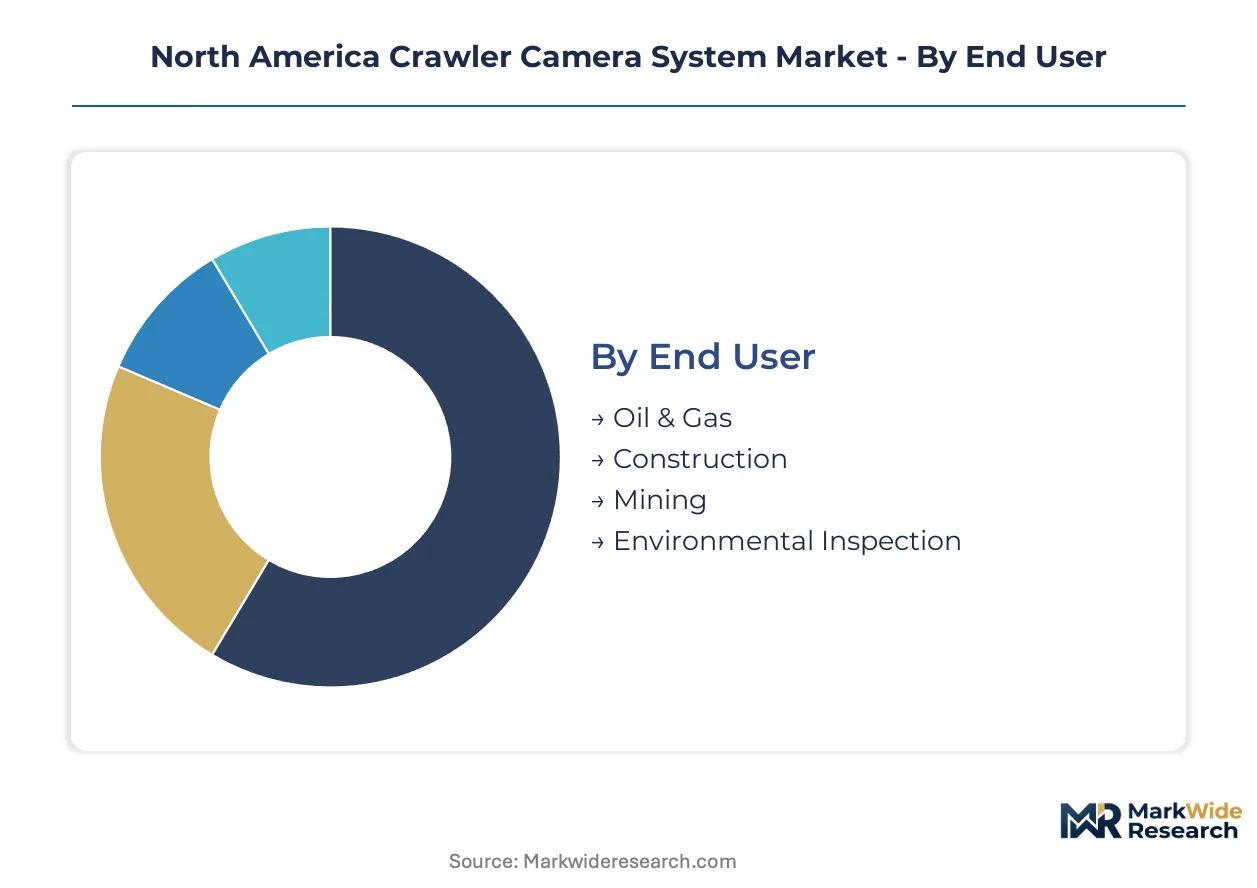
Segmentation reveals how crawler camera system demand fragments across technical specifications, procurement channels, and operational environments. Understanding these divisions illuminates where equipment specifications must diverge and where standardization yields procurement leverage.
End User:
The use-case spectrum spans hazardous industrial environments to precision municipal inspection, with each vertical imposing distinct durability, certification, and software integration requirements.
- Oil & Gas:Explosion-proof crawler configurations rated for Class I Division 1 environments dominate this segment. Demand concentrates in Texas and Louisiana shale corridors where pipeline integrity mandates drive fleet procurement for gathering line and transmission main assessment.
- Environmental Inspection:Portable, battery-powered systems with integrated PACP defect coding workflows serve municipal sewer authorities. Procurement accelerates across the Great Lakes industrial corridor under EPA consent decree pressure.
- Construction:Short-term rental models and contractor-managed fleet services address project-based quality verification needs.
- Mining:Heavy-duty tracked platforms with reinforced cable management withstand abrasive slurry and steep grade conditions.
The dominant share belongs to Environmental Inspection, while Oil & Gas is closing the gap fastest.
Camera Type:
Cost tier differentiation separates commodity visual inspection from premium sensing modalities that command equipment rental premiums.
- High Definition:Standard 1080p and 4K visible spectrum imagers constitute the volume base across municipal and commercial applications. Municipal wastewater utilities in Illinois, Ohio, and Michigan standardize on these configurations for gravity sewer PACP compliance.
- Thermal Imaging:Infrared sensors detect active infiltration and joint thermal signatures invisible to standard cameras. Industrial force main assessment programs in Texas metropolitan corridors deploy these for leak detection under pressure.
- Pan-tilt-zoom:Articulating camera heads enable circumferential pipe wall examination without crawler repositioning.
- 3D Camera:Stereo vision and structured light systems generate geometric deformation maps for structural engineering analysis.
The dominant share belongs to High Definition, though Thermal Imaging is gaining share fastest in industrial force main applications.
Application:
Volume distribution reflects regulatory enforcement intensity across infrastructure asset classes.
- Pipeline Inspection:Gravity sewer and force main condition assessment commands the largest equipment deployment. EPA CMOM mandates and combined sewer overflow remediation programs in Michigan and Ohio sustain procurement velocity.
- Structural Analysis:Bridge culvert, tunnel, and building foundation inspection requires specialized lighting and measurement payloads.
- Underwater Exploration:Potable water reservoir and outfall inspection demands pressure-rated housings and potable water certification.
- Security Surveillance:Perimeter and confined space monitoring applications utilize crawler systems for hazardous environment access.
The dominant share belongs to Pipeline Inspection, while Structural Analysis is climbing the fastest as bridge infrastructure age accelerates assessment mandates.
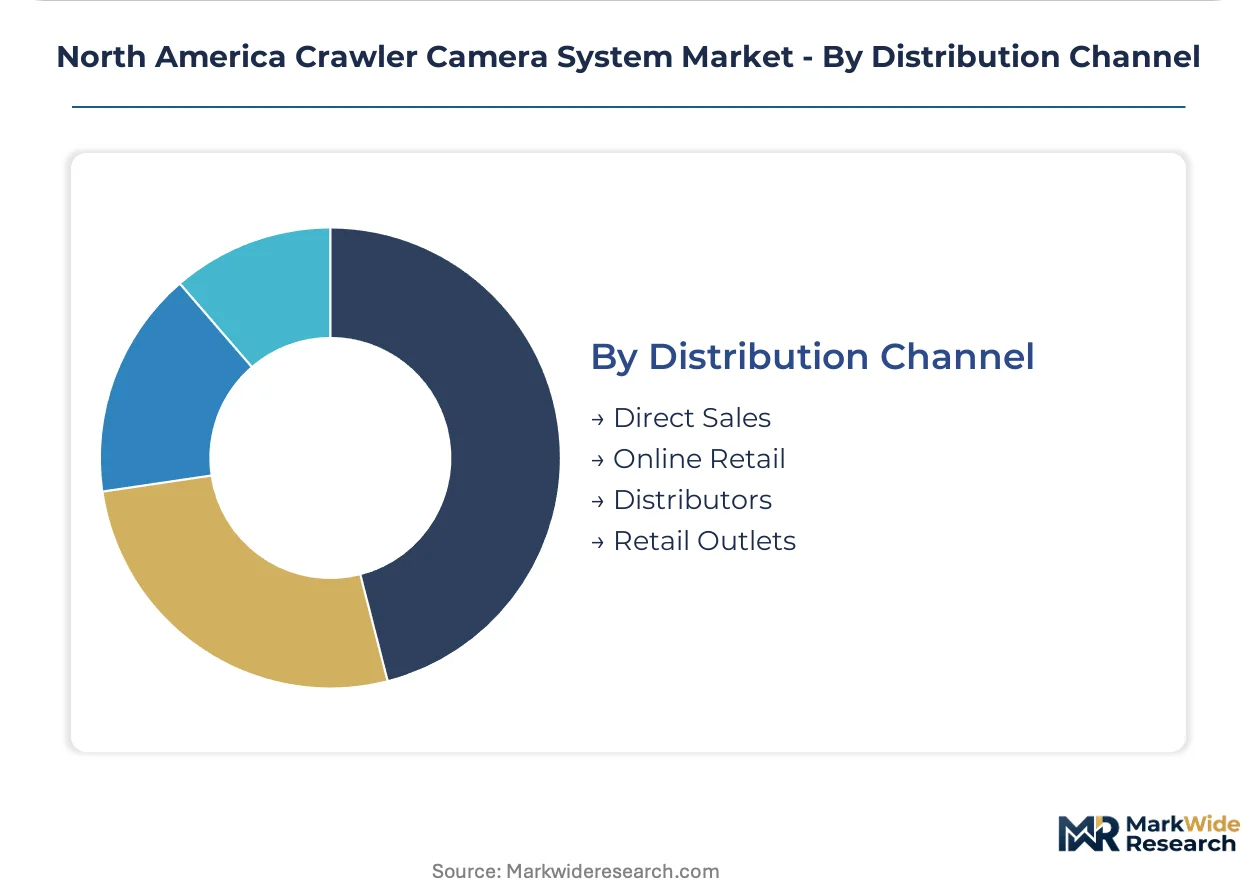
Distribution Channel:
Procurement modality selection tracks customer scale and in-house technical capability.
- Direct Sales:Large municipal utilities and integrated oil operators negotiate cooperative purchasing agreements and fleet-as-a-service contracts. Volume pricing and predictive maintenance partnerships characterize these relationships.
- Distributors:Regional dealer networks provide local service support and rapid parts availability for mid-sized contractors.
- Online Retail:Standardized portable systems move through e-commerce for small contractors and occasional-use municipal departments.
- Retail Outlets:Limited specialty equipment resellers serve emergency replacement and demonstration purposes.
The dominant share belongs to Direct Sales, though Distributors are expanding most quickly as mid-market rental services proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across North American jurisdictions. Canadian municipal buyers prioritize total cost of ownership, while Texas and California utilities absorb premium pricing for rapid deployment capability.
United States
EPA consent decrees and CMOM mandates compress procurement cycles for municipal wastewater authorities. The Clean Water Act enforcement framework compels documented sewer condition assessment across combined sewer overflow remediation programs. Industrial demand concentrates in the Great Lakes corridor spanning Illinois, Ohio, and Michigan where aging infrastructure commands priority capital allocation.
Canada
Provincial environmental regulators layer inspection frequency requirements onto municipal sewer maintenance schedules. Infrastructure Canada funding programs accelerate fleet modernization for utilities serving populations under 100,000. Ontario and Quebec municipalities dominate equipment deployment, with Toronto and Montreal metropolitan areas driving predictive maintenance contract adoption.
Mexico
NAIMEX water infrastructure investments and CONAGUA regulatory expansion create emerging demand for portable inspection systems. Federal water quality standards are tightening discharge monitoring requirements for municipal treatment operators. Mexico City and Monterrey industrial corridors represent the primary addressable base for rental and lease-based crawler services.
North America Crawler Camera System Market Competitive Landscape
Dealer-network specialists and direct-sales manufacturers split the market along customer scale lines. The vendor base concentrates around municipal wastewater specialization, with limited diversification into adjacent industrial verticals. Three archetypes dominate: established sewer-equipment incumbents with integrated software workflows, portable-system disruptors emphasizing battery-powered mobility, and robotics-focused entrants targeting force main pressure applications. Competitive moves center on cooperative purchasing agreements for volume pricing and predictive maintenance partnerships that convert hardware transactions into recurring revenue streams.
Within the established-incumbent tier, CUES Inc. and Envirosight LLC occupy positions defined by channel control and application-specific software integration. Deep Trekker Inc. exemplifies the portable-system disruptor archetype, anchoring the battery-powered mobility vector that reduces municipal crew deployment complexity. These three companies collectively represent the strategic positioning spectrum visible across the competitive set.
| Leading Market Players |
|---|
| CUES Inc. |
| Deep Trekker Inc. |
| Envirosight LLC |
| Rausch USA |
| ULC Pipeline Robotics, LLC |
| AM Industrial |
| Subsite Electronics |
| RPIC |
| Hathorn Corporation |
| Others |
Value Network & Pricing Analysis
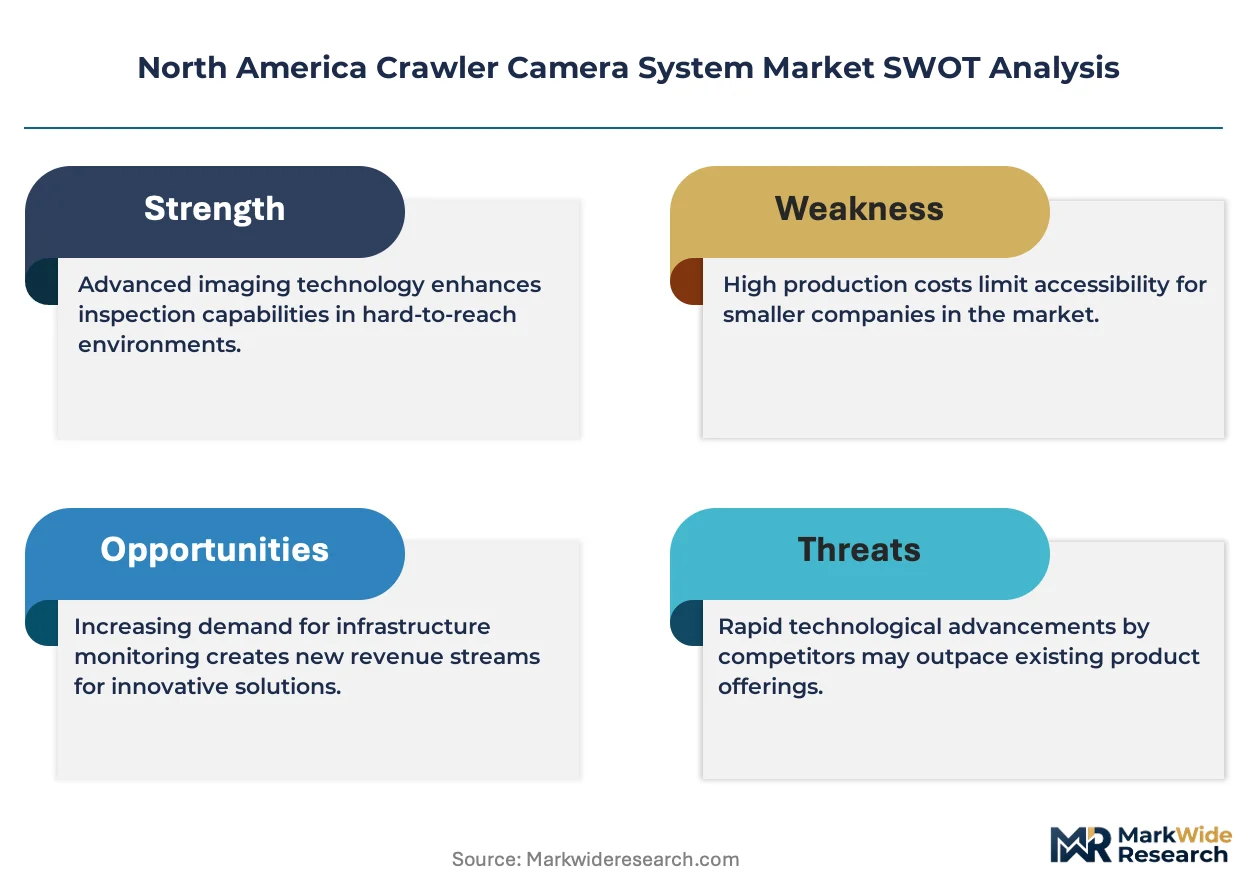
The Great Lakes freight corridor's intermodal cost dynamics compress margins for Asian-sourced optical components while amplifying price differentiation between premium thermal-imaging configurations and standard high-definition municipal packages. Supply concentration in CMOS sensor manufacturing feeds directly into tiered equipment pricing that separates explosion-proof industrial systems from portable battery-powered inspection units.
Pricing Analysis
Aftermarket service contracts and predictive maintenance agreements generate lifetime value that exceeds original equipment margins by substantial multiples. Three-tier pricing structure across premium thermal-imaging, standard high-definition, and economy visible-spectrum tiers reflects certification grade differentiation and software integration depth. Cost compression in standard municipal configurations intensifies as cooperative purchasing agreements aggregate volume across Midwest utilities. Small contractors and occasional-use municipal departments exhibit highest price sensitivity, while integrated oil operators absorb premiums for rapid-deployment capability.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for North American system integrators. High-grade CMOS and thermal imaging sensors draw from concentrated manufacturing capacity in China, South Korea, and Japan, creating single-source vulnerability for specialized infrared detectors. Lithium-ion battery cells and precision-machined aluminum housings represent additional input dependencies. Distribution runs through established dealer networks for mid-market access and direct fleet-as-a-service contracts for large utility procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through cooperative purchasing agreements among Great Lakes municipal utilities, compressing vendor margins and favoring suppliers with predictive maintenance service capabilities.
For Market Incumbents: Harden dealer network exclusivity agreements to defend channel access against portable-system disruptors. Deepen vertical integration into software-defined inspection workflows to capture recurring data service revenue. Invest in NASSCO PACP certification training capacity to alleviate industry-wide coder bottlenecks that delay contract closeout. For New Entrants and Emerging Players: Establish a beachhead in Texas metropolitan corridor rental services where infrastructure growth has outpaced inspection capacity. Target force main pressure-rated configurations as the most penetrable equipment category, where incumbent specialization in gravity sewer applications leaves defensive gaps. Pursue contractor-managed fleet models as the primary go-to-market angle for mid-sized utilities lacking dedicated maintenance divisions. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial equipment conglomerates with underoptimized sewer-robotics divisions that lack standalone software integration. Long-term viability hinges on successful transition from hardware shipment volume to data service monetization across the analysis window. Monitor EPA consent decree enforcement intensity in Ohio and Michigan as the primary inflection indicator for fleet modernization demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Partnership | Converts transactional equipment sales into recurring revenue streams with municipal utilities. |
| AI-Assisted Defect Coding Integration | Automates NASSCO PACP classification to reduce engineering labor and accelerate report delivery. |
| Battery-Powered Platform Expansion | Eliminates generator dependency for same-day multi-site mobilization by municipal crews. |
| Force Main Pressure-Rated Development | Opens inspection access to previously unexaminable pressure-rated infrastructure assets. |
| Cooperative Purchasing Agreement Participation | Captures volume pricing leverage across aggregated Midwest utility procurement cycles. |
Research Methodology
Cross-validation between municipal sewer authority procurement directors and crawler system manufacturer sales executives anchors the qualitative findings in operational reality. Primary interviews with EPA regional compliance officers, NASSCO certification trainers, and Great Lakes utility maintenance directors combined with secondary validation through EPA consent decree filings, Infrastructure Canada funding disclosures, and state-level environmental enforcement records. Bottom-up equipment deployment estimates and top-down infrastructure spending allocations triangulate market sizing.
Calibration against historical fleet replacement cycles and regulatory enforcement timelines shapes the projection framework across the analysis window. Segmentation dimensions span camera type, application environment, end-user vertical, and procurement channel structure. CAGRs derive from regression analysis of equipment shipment velocity against consent decree compliance deadlines and infrastructure funding appropriation patterns. Force main assessment expansion rates and AI integration adoption curves represent key industry-specific forecast inputs.
Sensitivities concentrate around EPA enforcement intensity variation, lithium-ion supply disruption, and drone-based inspection technology displacement. Forecasts reflect documented assumptions regarding regulatory mandate continuity and municipal capital budget stability. Macroeconomic contraction, tariff regime expansion, or breakthrough autonomous inspection capabilities would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
France Video Surveillance Market
Video Surveillance Systems
Security Camera Software Market
Video Surveillance Systems
Mexico Surveillance Analog Camera Market
Video Surveillance Systems
Night Vision System (NVS) Market
Video Surveillance Systems
Coastal Surveillance Systems Market
Video Surveillance Systems
Wireless Home Security Camera Market
Video Surveillance Systems
City Surveillance Market
Video Surveillance Systems
China Surveillance Camera Market
Video Surveillance Systems
Global Mobile Video Surveillance Market
Video Surveillance Systems
Farm Video Surveillance System Market
Video Surveillance Systems
Canada Surveillance IP Camera Market
Video Surveillance Systems
Commercial Aircraft Video Surveillance Systems Market
Video Surveillance Systems
US Video Surveillance Market
Video Surveillance Systems
Camera Alarm System Market
Video Surveillance Systems
AI in Video Surveillance Market
Video Surveillance Systems
Global Body Worn Cameras Market