
 Industrial Protective Footwear Market | 2026-2036
Industrial Protective Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Protective Footwear Market Intelligence
The traditional distributor-led sales channel is fragmenting as direct-to-consumer and e-commerce platforms gain traction with smaller businesses and individual contractors. Honeywell International Inc. leverages its extensive industrial network to maintain a strong position in large enterprise accounts. Wolverine World Wide Inc. differentiates through its portfolio of specialized brands targeting specific work environments. Bata Corporation sustains its presence through a wide retail footprint in several developing economies.
Industrial protective footwear comprises specialized shoes and boots designed to prevent workplace foot injuries. These products often incorporate features like steel or composite toe caps for impact resistance, meeting specific safety ratings for compression and impact. Leather remains a dominant material for its durability, while polyurethane soles offer superior slip and chemical resistance. Within product types, steel toe shoes represent a mature category, but composite toe footwear is seeing faster adoption in electrical hazard-sensitive applications like manufacturing plants.
Compliance with stringent safety standards is non-negotiable for market access. Regulations from the US Occupational Safety and Health Administration (OSHA) and Europe's CE marking requirements dictate minimum performance criteria for impact and puncture resistance. These frameworks compel manufacturers to invest in continuous material testing and certification. The key decision for suppliers now revolves around balancing the cost of advanced, lightweight materials against the price sensitivity of buyers in construction and warehousing.
Market Dynamics
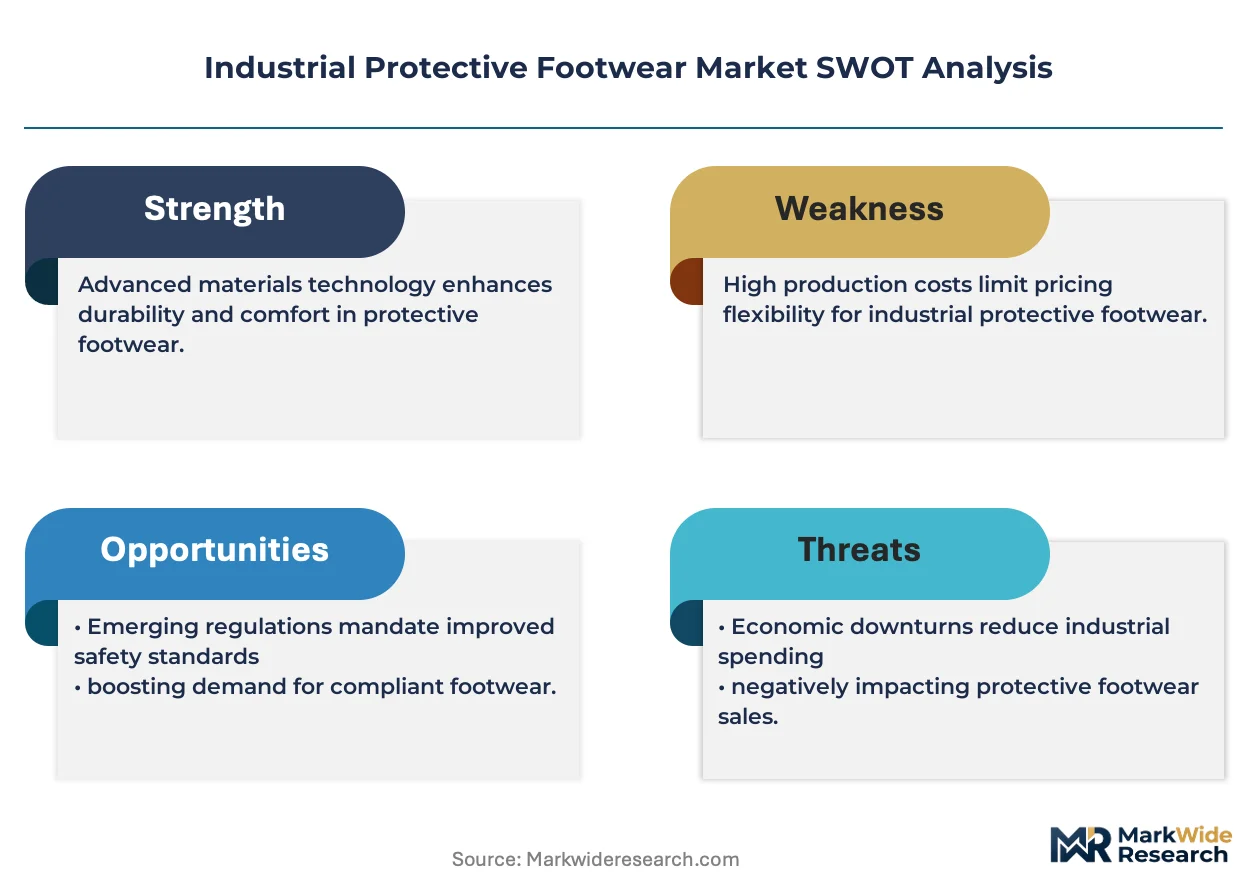
The market's core dynamic involves the tension between strict workplace safety regulations, enforced by bodies like OSHA, and the intense cost-sensitivity of major end-use sectors like construction and warehousing, shaping all product development and pricing decisions.
Growth Catalysts
- Industrialization Policy:Government-led industrialization initiatives, particularly in India, are expanding the manufacturing and construction base, creating a new cohort of workers requiring mandatory personal protective equipment.
- Construction Sector Activity:Sustained investment in public infrastructure and commercial real-estate projects globally provides a constant volume driver for durable, impact-resistant footwear.
- Material Advancement:The adoption of composite materials for toe caps offers a lightweight, metal-free alternative to steel, spurring replacement cycles in sectors sensitive to electrical hazards.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of raw materials, especially high-grade leather and petrochemical-derived polyurethane, compress manufacturer margins or force price hikes.
- Informal Sector Competition:The prevalence of low-cost, non-compliant footwear in developing economies' informal construction and agriculture sectors undermines the market for certified products.
- Comfort-Protection Trade-off:Designing footwear that meets high impact and puncture resistance standards while remaining lightweight and comfortable for all-day wear remains a key technical barrier.
Strategic Opportunities
- Gender-Specific Designs:A significant opportunity exists in developing anatomically correct protective footwear for the growing female workforce in industrial settings, a historically underserved segment.
- Smart Footwear Integration:Embedding sensors for fatigue monitoring or man-down alerts presents a new value proposition for high-risk environments like mining and emergency services.
- Sustainable Materials:Developing footwear from recycled polymers or bio-based leathers appeals to corporations with strong environmental and governance mandates, creating a premium market segment.
Industry Challenges
- Certification Complexity:Navigating the patchwork of national and regional safety standards, such as ASTM in the US and EN ISO in Europe, creates lengthy and costly certification processes for new product introductions.
- Counterfeit Goods:The rise of e-commerce has facilitated the distribution of counterfeit protective footwear that fails under stress, posing a significant risk to user safety and brand integrity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Protective Footwear Market |
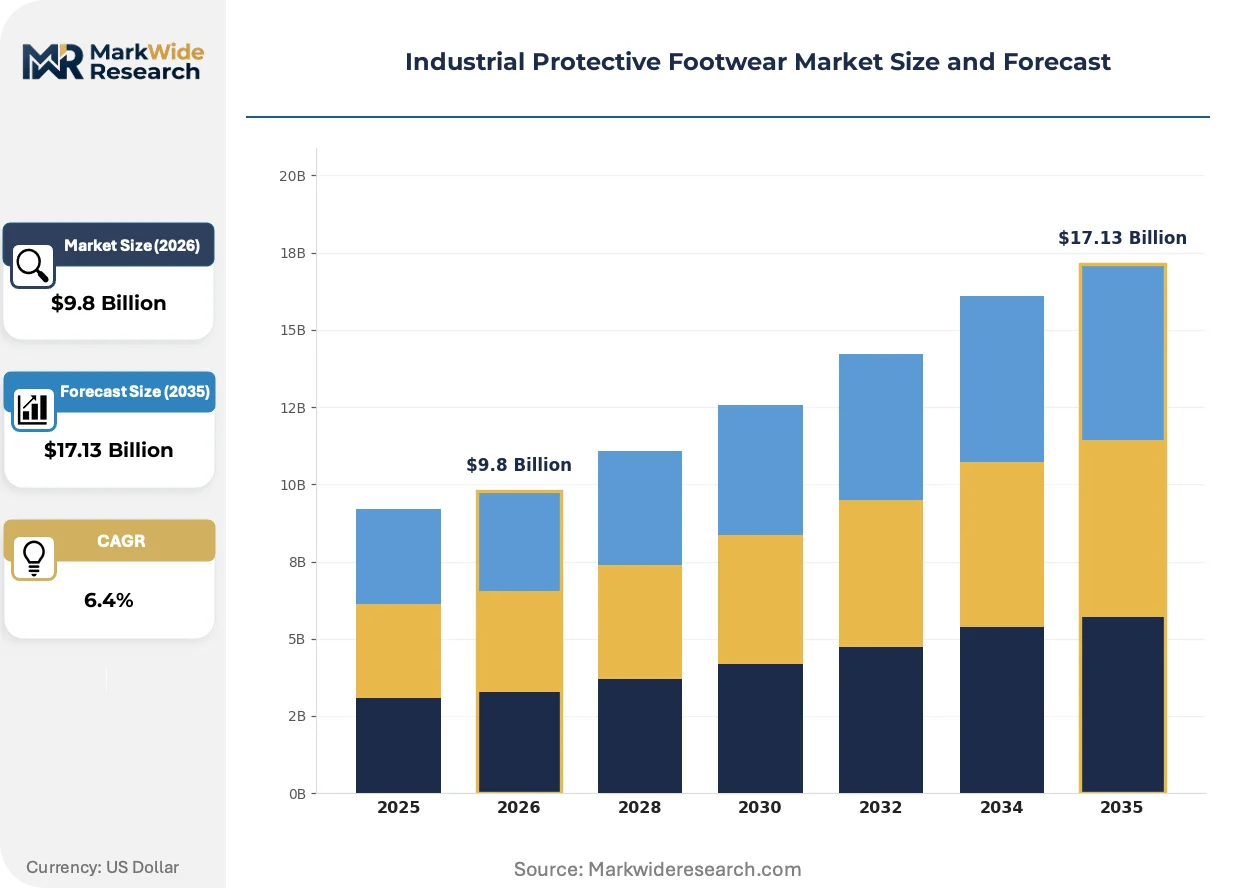
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Safety Boots, Steel Toe Shoes, Composite Toe Footwear, Puncture Resistant Shoes, Electrical Hazard Shoes Material: Leather, Rubber, Polyurethane, PVC, Thermoplastic Elastomer Application: Construction Sites, Manufacturing Plants, Chemical Processing Units, Mining Operations, Warehousing End User: Plant Operators, Maintenance Technicians, Heavy Equipment Operators, Warehouse Staff, Safety Officers |
| Companies Covered | Honeywell International Inc., Protective Industrial Products Inc., VF Corporation, Wolverine World Wide Inc., Bata Corporation, COFRA Holding, ELTEN GmbH, Uvex Group, Rahman Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Protective Footwear Market Strategic Shifts & Innovations
Material science advancements are fundamentally altering product design, while regulatory scrutiny over chemical inputs and a behavioral shift toward total lifecycle value redefine competitive benchmarks for manufacturers.
Advanced composite materials, including carbon fiber and specialized polymers, provide impact and compression resistance equivalent to steel. Sectors like advanced manufacturing and logistics are rapidly adopting this technology for its non-metallic and lightweight properties. The superior strength-to-weight ratio is rendering obsolete traditional steel components in applications where electrical hazard protection and reduced worker fatigue are critical.
Europe's REACH regulation places strict controls on chemicals used within manufactured goods, including those in footwear. This directly impacts substances used for leather tanning, sole adhesives, and synthetic material production, forcing reformulation to ensure market access. Footwear categories designed for chemical resistance are most affected, compelling investment in compliant, high-performance polymers.
A focus on worker well-being is elevating comfort and ergonomic design from a secondary feature to a primary purchasing driver. This changes the procurement calculus from simple unit cost to a total-value assessment that includes impacts on employee productivity and retention. This trend is most pronounced in the warehousing and distribution sectors of North America and Europe.
Industrial Protective Footwear Market Segmentation
Understanding the varied requirements across industrial settings and worker roles is critical for manufacturers to effectively segment the industrial protective footwear market. Tailoring product offerings to specific safety standards, material preferences, and ergonomic needs ensures market relevance and competitive advantage.
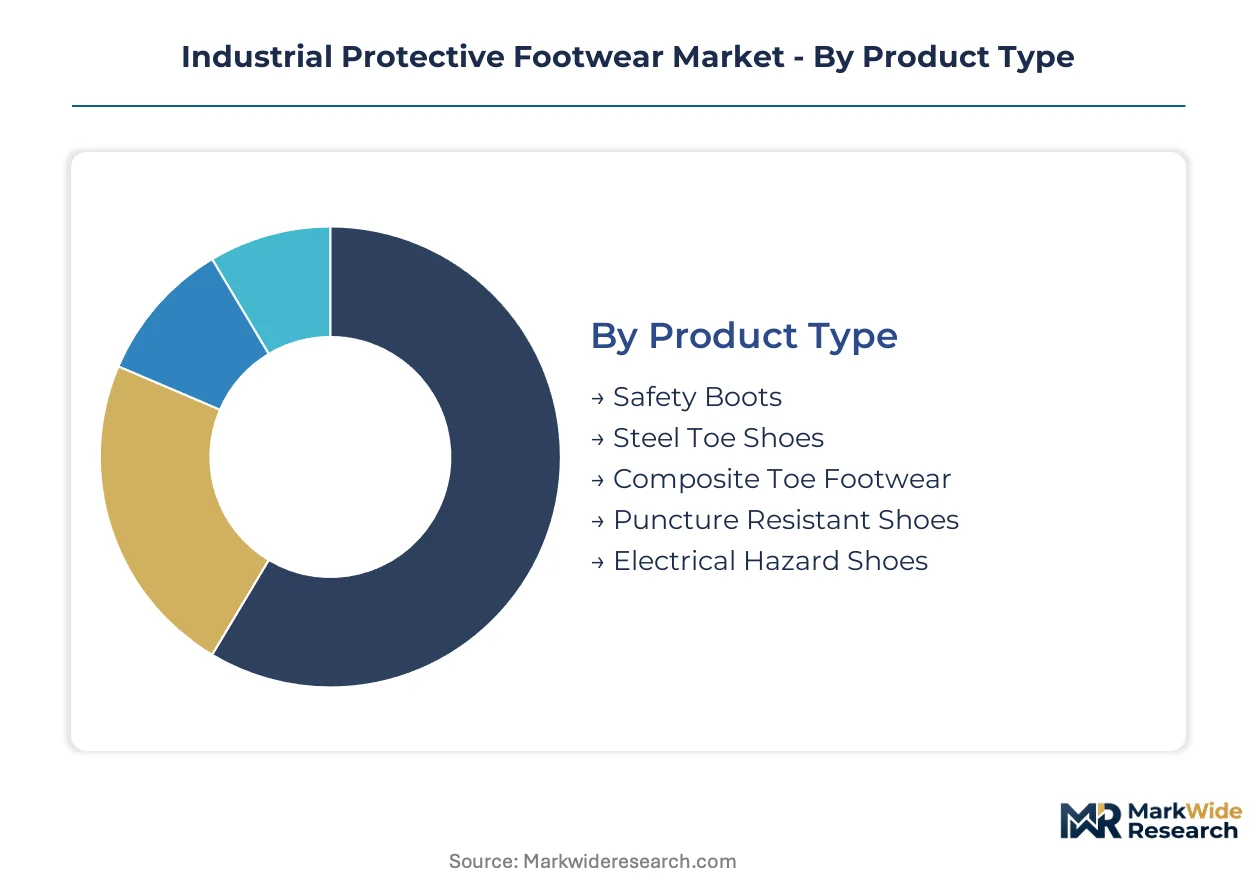
Product Type:
Segments within product type exhibit varying adoption cycles, reflecting both established safety protocols and emerging technological preferences.
- Composite Toe Footwear:These feature non-metallic toe caps, often made from carbon fiber or specialized polymers, providing impact and compression resistance. Manufacturing plants and logistics operations in Europe prioritize composite materials for electrical hazard protection and reduced worker fatigue.
- Steel Toe Shoes:This traditional protective footwear incorporates a steel cap over the toe area, primarily for impact resistance and compression protection. Construction sites and heavy industrial environments in India continue to drive volume due to cost-effectiveness and proven durability.
- Safety Boots:Comprehensive protective footwear offering ankle support and enhanced coverage for demanding work environments.
- Puncture Resistant Shoes:Footwear designed with a protective plate in the sole to prevent penetration from sharp objects on job sites.
- Electrical Hazard Shoes:Specialized footwear constructed to minimize electrical current flow through the body in high-voltage settings.
Steel Toe Shoes dominate the installed base. Composite Toe Footwear is where expansion concentrates.
Material:
Material choices directly influence the price point and specialized performance characteristics of industrial protective footwear.
- Leather:This natural hide is often treated for water resistance and durability, forming the primary upper material for many protective boots. Construction and general industrial sectors globally prioritize leather for its robust wear characteristics and traditional acceptance.
- Polyurethane:A synthetic polymer used primarily for soles, offering excellent slip, abrasion, and chemical resistance properties. Chemical processing units and food manufacturing facilities in North America require polyurethane for its superior resistance properties.
- Rubber:An elastic polymer used for soles and waterproof components, providing grip and insulation in various conditions.
- PVC:A cost-effective synthetic polymer often utilized in boots for chemical and water protection in specific industrial settings.
- Thermoplastic Elastomer:A flexible material combining rubber and plastic properties, used for lightweight and comfortable sole constructions.
Leather materials remain the volume leader. Polyurethane and advanced composites command premium pricing for specialized applications.
Application:
Specific applications dictate the required safety features and durability levels for industrial protective footwear, driving volume across sectors.
- Construction Sites:These environments require footwear with robust impact, puncture, and slip resistance due to heavy machinery and hazardous debris. Public infrastructure projects and commercial real estate developments in India and Europe consistently generate high demand for durable footwear.
- Manufacturing Plants:Controlled environments where electrical hazard protection and all-day comfort for standing workers are critical. Automotive assembly lines and electronics manufacturing in Germany and Japan increasingly adopt lightweight, composite-toe solutions.
- Chemical Processing Units:Settings necessitating footwear with high resistance to corrosive substances and potential spills.
- Mining Operations:Extremely demanding environments requiring heavy-duty, reinforced footwear for impact, abrasion, and puncture protection.
- Warehousing:Logistics facilities where slip resistance, comfort, and protection against falling objects are primary concerns for staff.
Construction Sites represent the largest demand concentration. Manufacturing Plants require highly specialized and comfortable solutions.
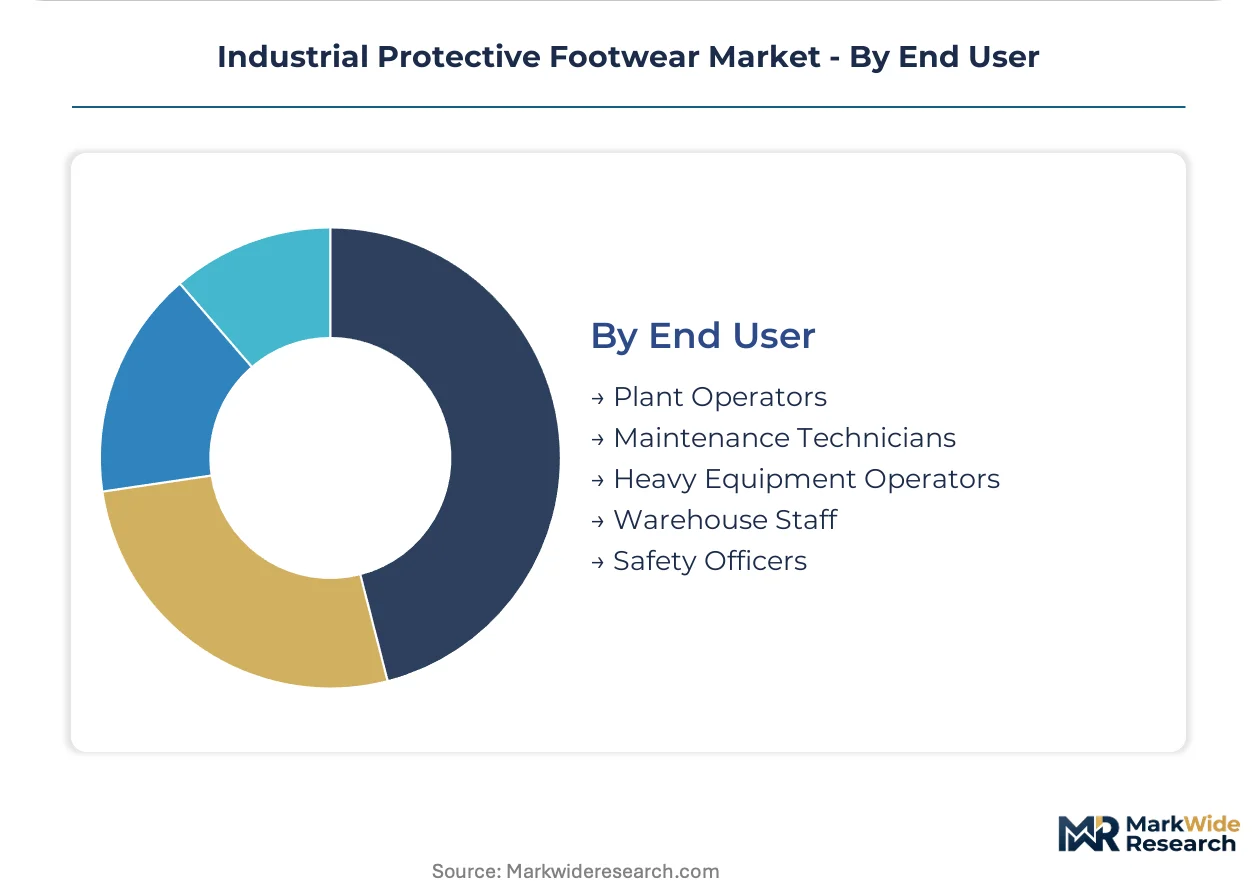
End User:
End-user roles directly influence procurement decisions, with specific job functions requiring tailored protective footwear features.
- Plant Operators:These individuals work within industrial facilities, often requiring general safety features combined with prolonged comfort for extended shifts. Large enterprises across North America prioritize ergonomic designs for plant operators to enhance productivity and reduce fatigue.
- Warehouse Staff:Personnel involved in logistics and material handling, needing slip-resistant and lightweight footwear for continuous movement and standing. E-commerce fulfillment centers in the United States and the UK drive procurement of comfortable, composite-toe options.
- Maintenance Technicians:Skilled workers performing equipment repairs, needing footwear with electrical hazard protection and good traction.
- Heavy Equipment Operators:Individuals operating large machinery, requiring robust, impact-resistant footwear with stable soles.
- Safety Officers:Personnel responsible for workplace safety compliance, influencing procurement towards certified and high-performance footwear across organizations.
Plant Operators and Warehouse Staff represent the largest user base. Innovation focuses on comfort and smart features for these segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Occupational Safety and Health Administration (OSHA) sets stringent workplace safety mandates, driving consistent demand for certified protective footwear across North America. These regulations establish baseline product specifications, ensuring manufacturers continuously innovate. Diverse regional industrial activities and varying regulatory enforcement create distinct market dynamics globally.
United States
E-commerce fulfillment centers and construction sites across the United States demand high volumes of protective footwear. OSHA mandates specific safety features, including slip resistance and impact protection, for warehouse staff. In major logistics hubs like Memphis, material handling operations create sustained procurement for comfortable, composite-toe options.
India
Government-led industrialization initiatives in India generate substantial new demand for protective gear for plant operators and construction workers. The Bureau of Indian Standards (BIS) enforces product specifications for safety footwear, ensuring minimum performance criteria. Major infrastructure projects across Mumbai and Bangalore concentrate procurement for durable steel toe shoes.
Germany
Germany's advanced manufacturing sector, including automotive assembly lines, drives demand for lightweight, composite-toe protective footwear. CE marking requirements dictate strict performance criteria for impact and puncture resistance, compelling continuous material testing. In industrial regions like Bavaria, companies prioritize ergonomic designs and electrical hazard protection.
Japan
Precision manufacturing and electronics facilities in Japan require highly specialized protective footwear with advanced material properties. Japanese Industrial Standards (JIS) specify rigorous safety benchmarks for impact, compression, and electrical hazard protection. Major industrial centers such as the Kanto region increasingly adopt composite materials to reduce worker fatigue.
United Kingdom
The United Kingdom's expanding warehousing and construction sectors create consistent demand for robust and comfortable safety footwear. CE marking regulations ensure products meet essential health and safety requirements for all protective equipment. E-commerce fulfillment centers in the Midlands and major infrastructure projects drive procurement of slip-resistant options.
Industrial Protective Footwear Market Key Industry Players
Established industrial suppliers and agile niche specialists split the industrial protective footwear market. The landscape exhibits a tiered structure, with large conglomerates maintaining extensive industrial networks for enterprise accounts. Smaller, specialized brands focus on specific work environments or direct-to-consumer channels. Companies engage in portfolio diversification and geographic expansion to capture market share across varied end-use sectors.
On the premium-tier vector, Honeywell International Inc. anchors the segment for large enterprise accounts, leveraging its extensive industrial network. Wolverine World Wide Inc. exemplifies a strategy of differentiation through its portfolio of specialized brands, targeting specific work environments. Bata Corporation, a globally recognized entity, occupies a significant position through its wide retail footprint across developing economies, sustaining its presence with accessible product lines. These players collectively represent varied approaches to market penetration and customer engagement within the industrial protective footwear sector.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Protective Industrial Products Inc. |
| VF Corporation |
| Wolverine World Wide Inc. |
| Bata Corporation |
| COFRA Holding |
| ELTEN GmbH |
| Uvex Group |
| Rahman Group |
Cost & Logistics Intelligence
Dongguan's extensive footwear manufacturing capacity, particularly for traditional steel-toe options, provides a baseline for global price points. This concentrated production influences cost structures across the industrial protective footwear market.
Pricing Analysis
Prices for industrial protective footwear vary significantly between developed economies like Germany and developing markets such as India. The dominant model remains per-unit transactional, driven by certification levels like OSHA and CE marking, specialized materials, and brand premium. Pricing pressure stems from raw material input cost volatility, especially for high-grade leather and polyurethane. Construction and warehousing buyers in India exhibit high price sensitivity, contrasting with specialized manufacturing in Germany that prioritizes performance over cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities often underpin the procurement relationships between large brands and their footwear component suppliers. Supply concentrates heavily in manufacturing hubs like China, India, and Vietnam, relying on high-grade leather, petrochemical-derived polyurethane, and advanced composite materials. Commodity price volatility for these inputs presents a structural supply chain risk. Distribution runs through a fragmented network, with traditional channels now supplemented by direct-to-consumer and e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial protective footwear market is poised for a cyclical recovery, driven by sustained investment in public infrastructure projects globally. This creates a consistent demand floor for safety-critical products.
For Market Incumbents: Insulate established market share by deepening vertical integration into advanced material production, particularly for composites. This counters margin pressure from input cost volatility and enhances control over specialized features. Invest in robust certification processes and digital authentication to combat the threat of counterfeit goods. Strengthen channel relationships with large enterprise accounts to maintain volume.
For New Entrants and Emerging Players: Underpenetration in developing economies' informal construction sectors presents a significant opportunity. Target the underserved female workforce in industrial settings with anatomically correct, gender-specific designs. Explore smart footwear integration for fatigue monitoring in high-risk environments like mining. Leverage direct-to-consumer e-commerce platforms to bypass traditional distributor networks and reach smaller businesses.
For Investors and Strategic Acquirers: Long-term, this sits as a defensive growth play because workplace safety mandates create non-discretionary demand for certified products. Target vertically integrated mid-cap specialists with strong intellectual property in advanced materials or established regional distribution networks. These firms offer resilience against raw material volatility and channel fragmentation. The signal to watch is rapid adoption of sustainable materials by large corporate buyers, indicating premium market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Gender-Specific Footwear | Addresses the historically underserved female workforce, expanding market reach and improving worker comfort. |
| Integrate Smart Sensors | Offers advanced safety features like fatigue monitoring for high-risk environments like mining, creating new value propositions. |
| Invest in Sustainable Materials | Appeals to corporations with environmental and governance mandates, fostering a premium segment for bio-based leathers. |
| Expand E-commerce Channels | Reaches smaller businesses and individual contractors, fragmenting traditional distributor-led sales channels. |
| Enhance Composite Toe Production | Meets growing demand for lightweight, metal-free options in manufacturing plants sensitive to electrical hazards. |
Research Approach
Findings reconcile primary fieldwork against secondary review of OSHA regulations, CE marking requirements, BIS standards, and company annual reports. Interviews with plant managers, safety officers, procurement leads, and material scientists provided qualitative insights. This primary data was validated against industry association reports, regulatory body publications, and company financial filings. A bottom-up and top-down triangulation approach ensured robust market sizing and segmentation.
Forecast inputs considered raw material price trends, government-led industrialization policies, and evolving workplace safety mandates. The analytical framework modeled segmentation dimensions including product type, material, application, end-user, and regional regulatory frameworks across the analysis window. Compound Annual Growth Rates were derived by analyzing historical growth patterns and projecting future demand drivers. Key industry-specific inputs included construction sector activity and the adoption rates of composite materials.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large industrial conglomerates or agile niche specialists would shift outcomes. Forecasts reflect documented assumptions regarding market dynamics, but input cost volatility, shifts in safety regulations, or rapid material science breakthroughs represent specific risk factors. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Workplace Safety
Global Industrial Safety Footwear Market
Workplace Safety
Middle East Industrial Protective Footwear Market
Workplace Safety
Workplace Safety Market
Workplace Safety
Industrial Hand Protection Gloves Market
Workplace Safety
Industrial and Workplace Safety Market
Workplace Safety
Industrial Head Protection Market
Workplace Safety
Industrial Safety Gloves Market
Workplace Safety
Industrial Safety Mats Market
Workplace Safety
Industrial Eye Protection Market
Workplace Safety
Canada Safety Services Market
Workplace Safety
Industrial Safety Market
Workplace Safety
Safety Helmets Market
Workplace Safety
Safety Glasses Market
Workplace Safety
Safety Vest Market
Workplace Safety
Construction Worker Safety Market
Workplace Safety
Machine Safety Market