
 Global GCC Video Surveillance Storage Market | 2026-2036
Global GCC Video Surveillance Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Global GCC Video Surveillance Storage Market Foresight
Shortage of certified data center engineers across Gulf Cooperation Council states is unwinding deployment timelines for large-scale surveillance archives. Seagate Technology anchors regional supply through specialized surveillance-grade drive distribution, while Dell EMC competes with integrated server-storage bundles tailored for harsh Middle Eastern operating conditions. Cisco Systems Inc. extends its footprint via network-video convergence platforms that simplify edge-to-core data pipelines for integrators lacking deep storage expertise.
GCC video surveillance storage encompasses disk arrays, solid-state tiers, and cloud gateways engineered for continuous write workloads exceeding 180 terabytes annually per medium-sized deployment, with primary purpose being forensic-grade retention and real-time analytics retrieval. Network Attached Storage leads installation volume among storage types due to its compatibility with existing IP camera networks, though Cloud Storage segments are expanding fastest as sovereign cloud zones in Riyadh and Dubai mature. Video Content Analytics within technology segments commands premium positioning because AI-enabled indexing requires low-latency flash tiers and specialized compression protocols.
Saudi Arabia's National Cybersecurity Authority mandates, UAE's NESA compliance standards, and Kuwait's data protection directives collectively shape procurement by requiring encrypted retention, localized failover, and audit-ready chain-of-custody documentation. ISO 27001 certification has become a de facto market access threshold for vendors serving government agencies and critical infrastructure operators across the six member states. Stakeholders must evaluate hybrid architecture investments against evolving sovereign cloud eligibility criteria before committing to multi-year capacity contracts.
Market Dynamics
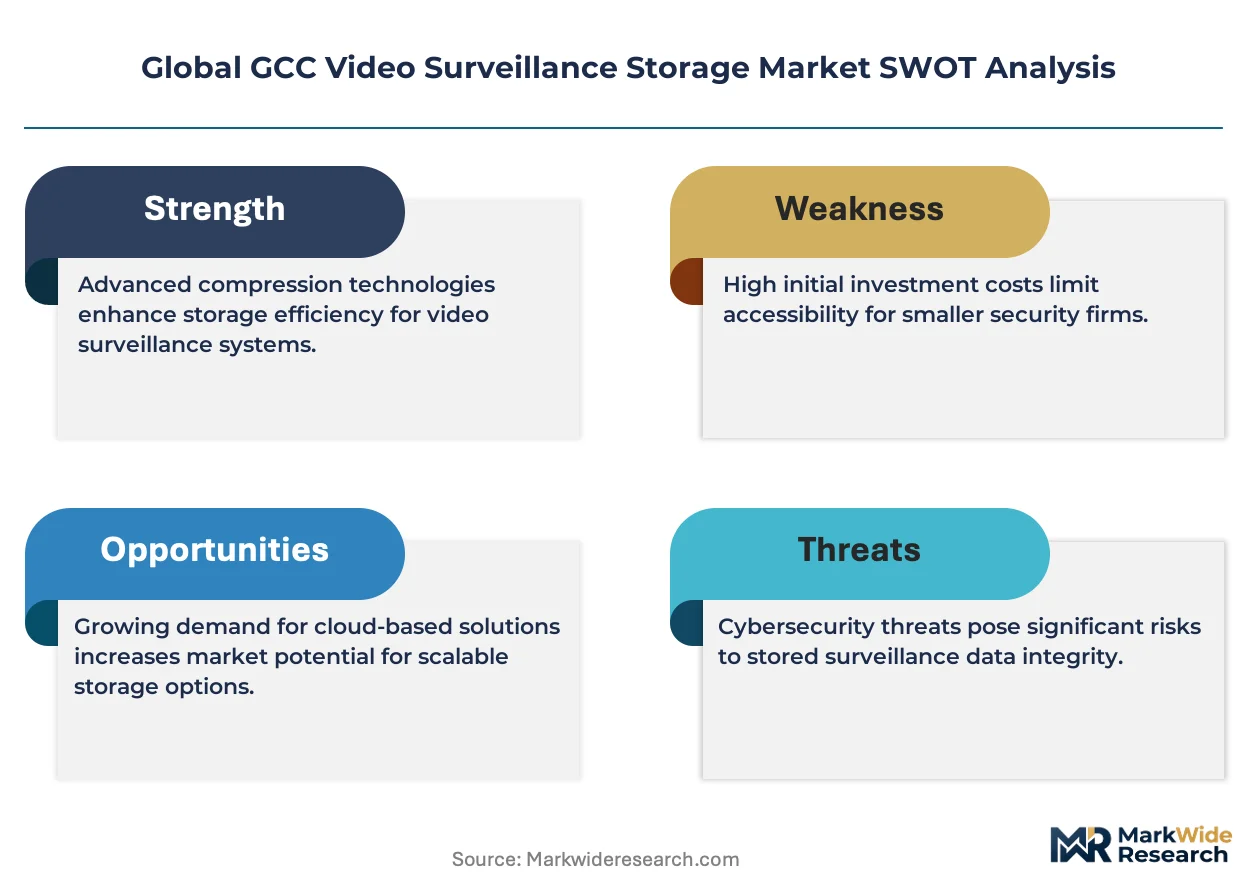
Sovereign data localization mandates across Gulf Cooperation Council member states are restructuring procurement architectures, forcing integrators to abandon pure-cloud retention models in favor of compliant hybrid storage stacks that satisfy national cybersecurity frameworks while preserving forensic retrieval capabilities.
Growth Catalysts
- Smart city infrastructure mandates:Urban development authorities in Dubai and Riyadh are specifying extended video retention periods for public safety networks, directly expanding petabyte-scale storage procurement.
- Saudi Arabia's National Cybersecurity Authority framework:Data localization requirements under NCA Directive 2.0 are redirecting infrastructure investment toward on-premise and sovereign-hybrid architectures.
- AI-enabled Video Content Analytics:Real-time indexing and facial recognition workloads are driving demand for low-latency flash tiers and specialized compression protocols in transportation and critical infrastructure verticals.
Market Restraints
- Certified engineering scarcity:Shortage of data center engineers qualified for harsh-environment Middle Eastern installations is unwinding deployment timelines for large-scale surveillance archives.
- Flash memory cost volatility:NAND supply concentration in East Asian foundries exposes Gulf integrators to input price swings that compress margin on all-flash tier proposals.
- Legacy codec incompatibility:Existing H.264 camera fleets create technical friction when migrating to H.265/HEVC storage pools, forcing costly transcoding middleware or premature endpoint replacement.
Strategic Opportunities
- Kuwait's emerging critical infrastructure vertical:Oil refinery and port security modernization programs remain underpenetrated relative to UAE and Saudi deployments, offering first-mover positioning for compliant vendors.
- Edge-to-core convergence:Integration of GPU-enabled edge appliances with centralized storage fabrics is opening service revenue streams for systems integrators lacking deep storage expertise.
- Sovereign cloud zone maturation:Dubai and Riyadh cloud zones are achieving eligibility for government workloads, enabling hybrid architectures that satisfy data residency without full on-premise capex burden.
Industry Challenges
- ISO 27001 certification timelines:Six-to-twelve month audit cycles for government market access are delaying revenue recognition for new entrants across all six GCC member states.
- Interoperability fragmentation:Proprietary video management system protocols complicate multi-vendor storage consolidation, forcing integrators into single-source dependencies or expensive API development.
- Thermal derating in desert installations:Ambient operating conditions exceeding 50°C necessitate specialized cooling architectures that inflate total cost of ownership versus temperate-climate benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global GCC Video Surveillance Storage Market |
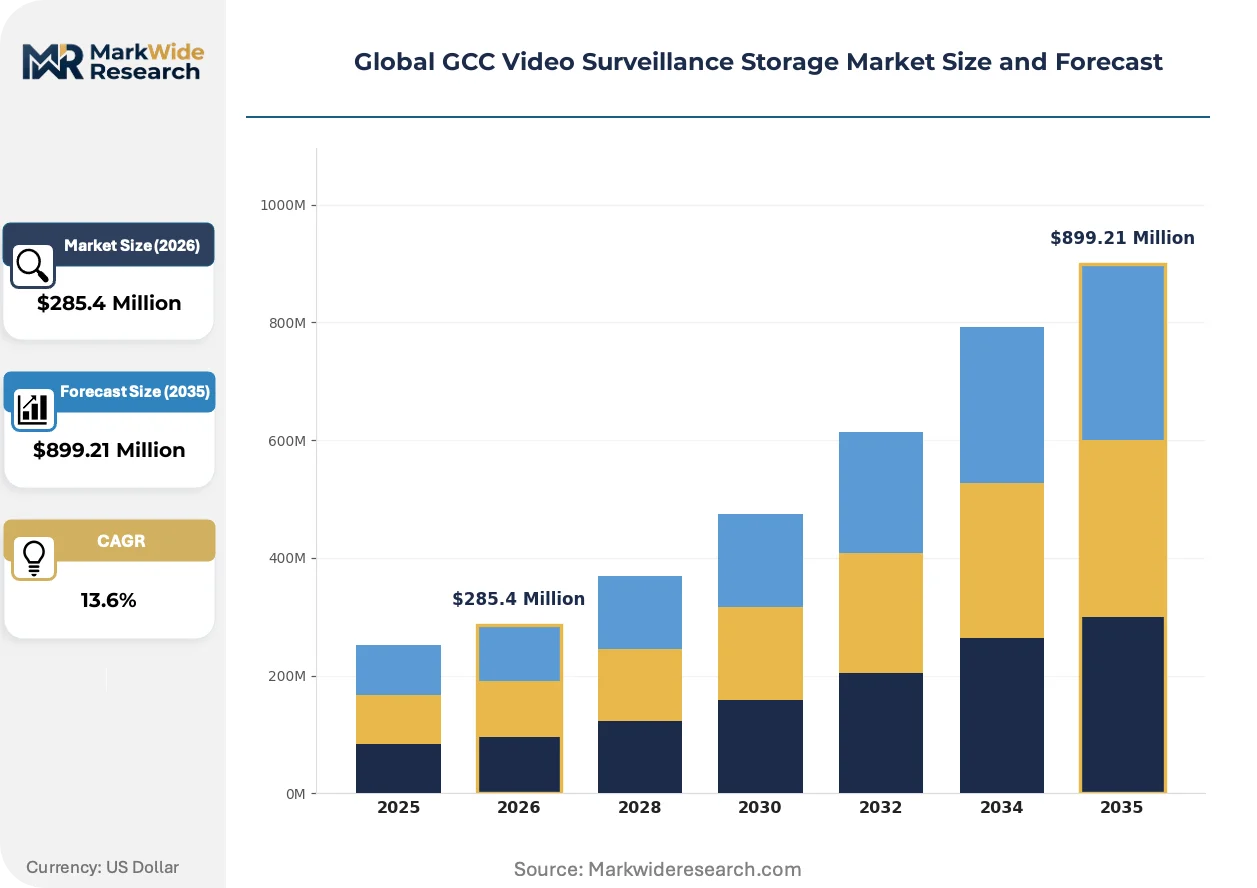
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $899.21 Million |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: Network Attached Storage, Direct Attached Storage, Storage Area Network, Cloud Storage, Hybrid Storage Technology: IP-Based Systems, Analog Systems, Hybrid Systems, Video Content Analytics, Edge Storage Application: Public Safety, Transportation Centers, Retail Outlets, Financial Institutions, Educational Campuses End User: Government Agencies, Commercial Enterprises, Critical Infrastructure, Hospitality Venues, Manufacturing Facilities |
| Companies Covered | Seagate Technology, Pelco Inc., Dell EMC, Cisco Systems Inc., Honeywell Security, Avigilon Corporation, BCD Video, Pivot3 Inc., Fujitsu Technology Solutions, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global GCC Video Surveillance Storage Market Shifts & Advancements
Compression and encoding architectures are undergoing fundamental restructuring as Gulf operators balance retention mandates against finite rack space and power budgets in climate-challenged facilities.
High-efficiency video coding (HEVC/H.265) is miniaturizing storage footprints for equivalent retention periods by halving bit-rate requirements versus legacy H.264 streams. Airport authorities and metro operators across Dubai and Doha are mandating H.265 compatibility in new procurements, compressing deployment schedules that previously assumed decade-long codec cycles. This migration is miniaturizing physical infrastructure requirements, enabling 90-day retention targets within existing rack allocations that previously supported only 30 days.
The UAE's National Electronic Security Authority (NESA) compliance standards are mandating encrypted retention with localized failover for critical infrastructure operators. Industrial consequence includes disqualification of non-compliant cloud-only providers from government and oil-sector tenders. Banking and transportation verticals are responding by specifying hybrid architectures with air-gapped on-premise tiers for 30-day hot retention and sovereign-cloud offload for extended archival.
Buyers are consolidating vendor relationships to reduce interoperability risk across multi-site deployments. Systems integrators previously managing heterogeneous storage fabrics are standardizing on single-platform Network Attached Storage architectures with unified management planes. This consolidation is most visible in Saudi Arabia's giga-project developments, where master developers are specifying end-to-end technology stacks to simplify commissioning and long-term service accountability.
Global GCC Video Surveillance Storage Market Segmentation
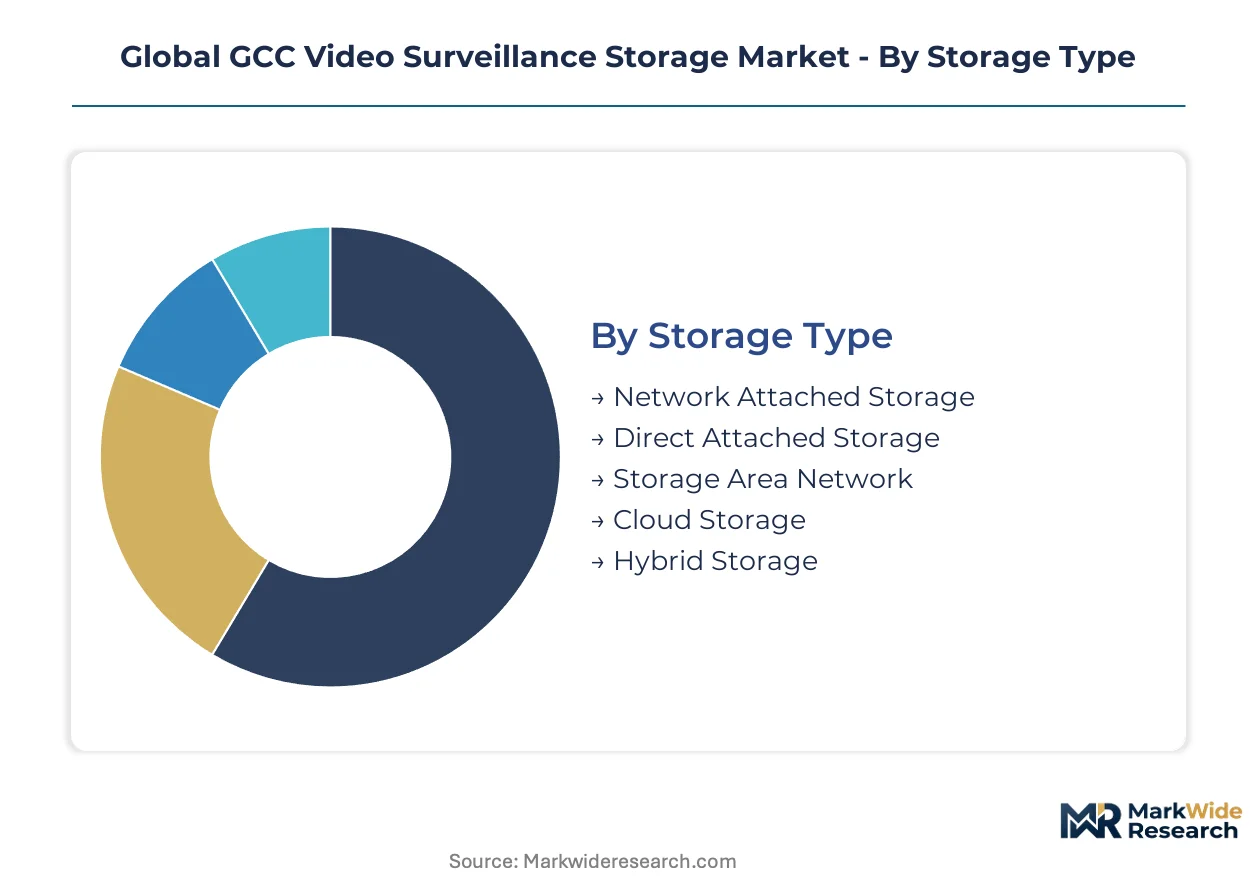
Segmentation in the GCC video surveillance storage market reveals distinct procurement patterns across infrastructure types, deployment technologies, and compliance-sensitive end-use environments. Channel strategies diverge sharply between government tenders requiring sovereign-hybrid architectures and commercial verticals prioritizing cost-optimized Network Attached Storage.
Storage Type:
Network Attached Storage flows predominantly through systems integrators serving commercial and transportation verticals, while sovereign-hybrid configurations reach government buyers via specialized security contractors with NCA certification.
- Network Attached Storage:Disk-based arrays optimized for sequential write workloads from IP camera fleets. Demand concentrates in UAE transportation hubs and Saudi commercial developments where extended retention mandates are lengthening procurement cycles. Compatibility with existing Ethernet infrastructure reduces commissioning complexity for integrators lacking deep storage expertise.
- Cloud Storage:Sovereign-hosted object storage tiers meeting NESA and NCA data localization requirements. Expansion concentrates in Dubai and Riyadh cloud zones as government workload eligibility matures, enabling hybrid architectures without full on-premise capex burden.
- Direct Attached Storage:Local drive arrays for small-scale deployments in retail and hospitality settings with sub-50 camera counts.
- Storage Area Network:Fibre Channel fabrics serving metro-scale smart city deployments with centralized management requirements.
- Hybrid Storage:Tiered architectures combining hot on-premise retention with sovereign-cloud archival for compliance-sensitive operators.
Network Attached Storage dominates installed base across commercial channels. Cloud Storage is where expansion concentrates as sovereign zone eligibility reshapes government procurement.
Technology:
Cost tier differentiation separates premium AI-enabled analytics deployments from standardized IP recording infrastructure, with margin compression most severe in legacy analog replacement cycles.
- IP-Based Systems:Gigabit Ethernet camera networks generating H.265 streams for bandwidth-efficient retention. Demand concentrates in new Saudi giga-project developments where master developers specify end-to-end technology stacks to simplify commissioning accountability.
- Video Content Analytics:GPU-accelerated indexing and facial recognition requiring low-latency flash tiers and specialized compression protocols. Expansion concentrates in Dubai airport and metro authorities mandating real-time threat detection capabilities.
- Analog Systems:Coaxial-based legacy infrastructure persisting in cost-constrained Kuwaiti and Bahraini installations.
- Hybrid Systems:Transitional architectures bridging analog endpoints with IP storage backbones during phased modernization.
- Edge Storage:GPU-enabled appliances performing local analytics preprocessing before centralized archival.
IP-Based Systems anchor volume procurement across greenfield developments. Video Content Analytics commands the steepest expansion trajectory as AI indexing becomes mandatory in critical infrastructure tenders.
Application:
Customer type segmentation separates compliance-heavy government mandates from margin-sensitive commercial deployments, with procurement authority residing in distinct organizational functions.
- Public Safety:City-wide surveillance networks with 90-day retention requirements and encrypted chain-of-custody documentation. Demand concentrates in Riyadh and Dubai smart city authorities specifying petabyte-scale archives with localized failover.
- Transportation Centers:Airport and metro operator deployments mandating H.265 compatibility for bandwidth efficiency. Saudi aviation and Qatar rail expansions are driving specification of integrated server-storage bundles rated for harsh-environment operation.
- Retail Outlets:Loss prevention systems with 30-day standard retention and cloud offload for extended archival.
- Financial Institutions:NESA-compliant retention with audit-ready indexing for banking sector regulators.
- Educational Campuses:Distributed camera networks with centralized management across multi-site university systems.
Public Safety commands the largest project scale per deployment. Transportation Centers represent the most technology-forward application environment.
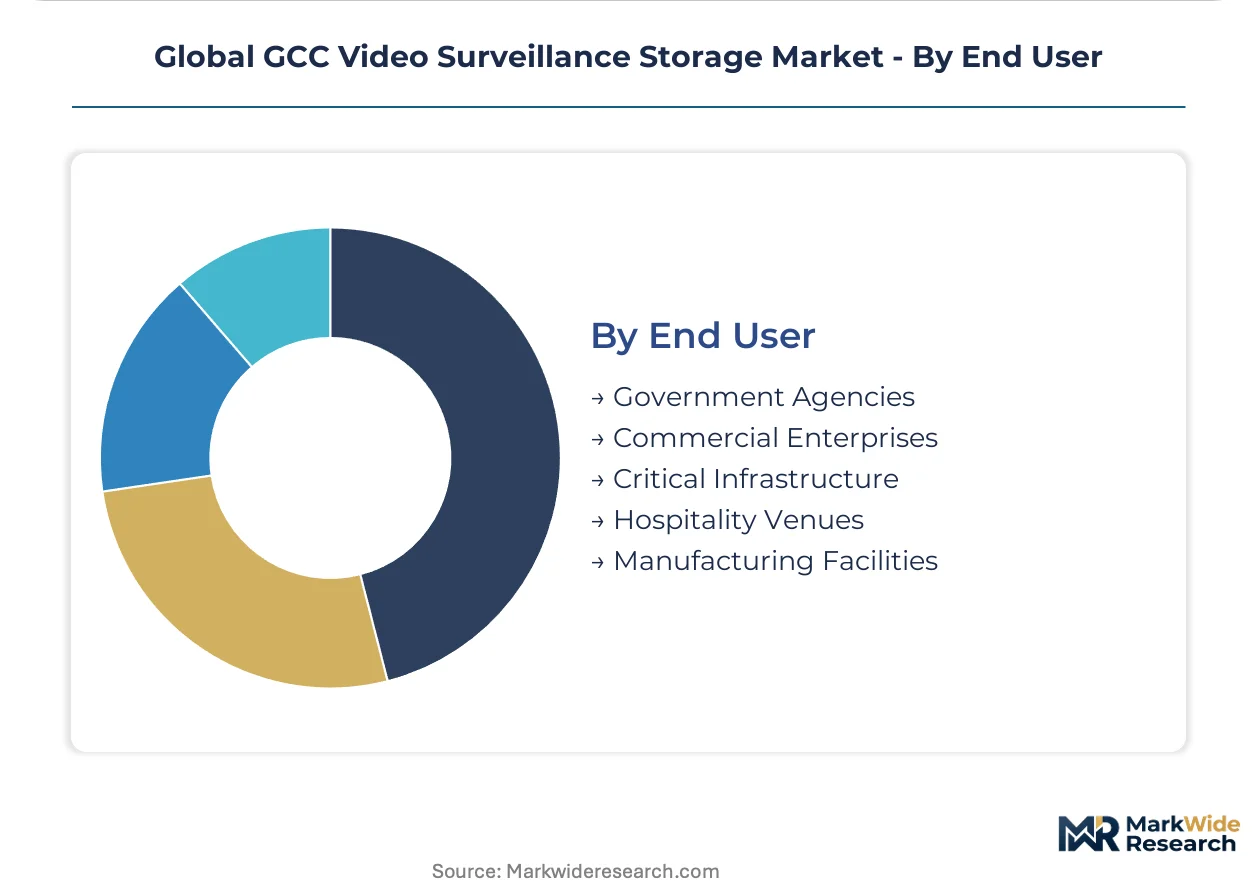
End User:
Supply concentration in certified integration channels creates distinct access barriers, with government and critical infrastructure segments requiring six-to-twelve month ISO 27001 certification cycles.
- Government Agencies:National and municipal authorities procuring through tender processes with NCA Directive 2.0 compliance mandates. Saudi ministries and UAE federal entities are redirecting infrastructure investment toward on-premise and sovereign-hybrid architectures under cybersecurity framework requirements.
- Critical Infrastructure:Oil, power, and port operators with industrial consequence classifications disqualifying non-compliant cloud-only providers. Kuwaiti refinery and port security modernization programs remain underpenetrated relative to UAE and Saudi deployments.
- Commercial Enterprises:Corporate campuses and mixed-use developments prioritizing cost-optimized retention without sovereign compliance overhead.
- Hospitality Venues:Hotel and entertainment operators with standardized 30-day retention and rapid retrieval for incident response.
- Manufacturing Facilities:Industrial sites requiring thermal-derated storage architectures for ambient conditions exceeding 50°C.
Government Agencies dominate contract value per procurement. Critical Infrastructure offers first-mover positioning for compliant vendors in underpenetrated Kuwaiti markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Saudi Arabia outstrips Kuwait by a factor of three, reflecting divergent compliance burdens and project scale. UAE buyers command mid-tier rates with superior payment terms. Bahrain and Oman operate as price-takers with compressed margins.
Saudi Arabia
Riyadh's giga-project developments and NEOM smart city construction are driving petabyte-scale storage procurement. The National Cybersecurity Authority's Directive 2.0 mandates data localization, redirecting investment toward on-premise and sovereign-hybrid architectures. Eastern Province oil operators are specifying encrypted retention with localized failover for critical infrastructure.
United Arab Emirates
Dubai airport and metro authorities mandate H.265 compatibility and real-time analytics retrieval for bandwidth efficiency. NESA compliance standards require encrypted retention with audit-ready chain-of-custody documentation. Abu Dhabi sovereign cloud zones are achieving government workload eligibility, enabling hybrid architectures without full on-premise capex burden.
Kuwait
Oil refinery and port security modernization programs remain underpenetrated relative to UAE and Saudi deployments. The country's data protection directives shape procurement by requiring localized failover and encrypted retention. Al-Zour refinery expansions are creating first-mover positioning for compliant vendors in critical infrastructure verticals.
Qatar
Rail expansion and Lusail smart city development are driving specification of integrated server-storage bundles rated for harsh-environment operation. Hamad International Airport mandates AI-enabled Video Content Analytics with low-latency flash tiers. Doha metro operators are compressing deployment schedules with H.265 stream requirements.
Bahrain
Financial institutions in Manama specify NESA-compliant retention with audit-ready indexing for banking sector regulators. Retail and hospitality operators with sub-50 camera counts rely on cost-optimized direct attached storage. The country's smaller project scale limits pricing power relative to Saudi and UAE counterparts.
Global GCC Video Surveillance Storage Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure. Specialized surveillance-grade drive manufacturers compete with integrated server-storage bundlers and network-video convergence platforms. Three archetypes dominate: component specialists with harsh-environment expertise, systems integrators with NCA certification, and cloud-gateway providers leveraging sovereign zone maturation. Competitive moves concentrate on strategic partnerships for edge-to-core convergence and portfolio diversification into AI-enabled analytics tiers.
Within the component specialist tier, Seagate Technology anchors regional supply through surveillance-grade distribution networks. Dell EMC occupies a position among integrated infrastructure providers with server-storage bundles. Cisco Systems Inc. exemplifies the network-video convergence archetype, simplifying edge-to-core data pipelines for integrators lacking deep storage expertise.
| Leading Market Players |
|---|
| Seagate Technology |
| Pelco Inc. |
| Dell EMC |
| Cisco Systems Inc. |
| Honeywell Security |
| Avigilon Corporation |
| BCD Video |
| Pivot3 Inc. |
| Fujitsu Technology Solutions |
| Others |
Supply & Pricing Matrix
Petabyte-scale procurement volumes in Saudi giga-projects and Dubai smart city deployments are concentrating buying power among master developers and government authorities, compressing margin for standard-configured storage tiers while elevating premiums for NCA-certified, thermally-derated custom architectures. This scale asymmetry between tender volumes and certified vendor capacity is anchoring price floors for compliant solutions while accelerating commoditization in sub-50 camera commercial segments.
Pricing Analysis
Configured-to-order pricing for sovereign-hybrid architectures commands spreads exceeding standard Network Attached Storage by multiples reflecting NCA Directive 2.0 compliance overhead and desert-rated thermal engineering. Pricing stratifies across NESA-certified premium tiers, ISO 27001-attained standard tiers, and uncertified economy tiers without localization features. Cost compression in commercial channels is intensifying because integrators face NAND supply volatility from East Asian foundries. Retail and hospitality operators exhibit highest price sensitivity, while Saudi government agencies accept premium positioning for encrypted chain-of-custody documentation.
Supply Chain Analysis
Inbound logistics costs through Jebel Ali and Dammam ports fluctuate with container availability on Asia-Gulf trade lanes, compressing margin for time-sensitive tender deliveries. Component supply concentrates in Taiwan, South Korea, and China for NAND flash and surveillance-optimized drive controllers. Manufacturing rests on specialized foundry capacity for thermally-derated storage enclosures and GPU-enabled edge appliances. Single-source vulnerability in NAND supply exposes Gulf integrators to input price swings. Distribution runs through certified systems integrators with NCA accreditation for government verticals, and open-channel distributors for commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across compliance tiers, codec generations, and thermal specifications is creating niche positioning opportunities as sovereign mandates splinter procurement architectures and legacy migration timelines diverge.
For Market Incumbents: Consolidate certification advantages by acquiring ISO 27001-audited integration specialists in underpenetrated Kuwaiti critical infrastructure. Deepen backward integration into thermally-engineered enclosure manufacturing to defend margin against commodity drive pricing. Channel control through exclusive NCA-certified partner networks represents the critical defensive lever against emerging sovereign-cloud gateway providers. For New Entrants and Emerging Players: Differentiate on H.265-native, AI-ready edge appliances targeting Qatar rail and Lusail smart city deployments where compressed deployment schedules favor plug-and-play architectures. White-space concentrates in Kuwaiti oil refinery security modernization and Bahraini financial institution NESA compliance. A direct engagement model with master developers in Saudi giga-projects bypasses incumbent integrator lock-in. For Investors and Strategic Acquirers: NCA-certified systems integrators with established Eastern Province oil sector relationships represent the priority acquisition archetype for exposure to Saudi localization mandates. Long-term viability hinges on hybrid architecture transition velocity rather than pure-cloud displacement. The signal to monitor is sovereign cloud zone eligibility announcements in Riyadh and Dubai, which would recalibrate capex-versus-opex preferences across government tenders.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | Enables hybrid architectures satisfying NCA data residency without full on-premise burden for Riyadh tenders. |
| Thermal Engineering Certification | Qualifies storage enclosures for 50°C-plus ambient operation in Saudi Eastern Province oil installations. |
| Video Analytics Platform Integration | Captures premium positioning in Dubai airport and metro authority H.265 mandate procurements. |
| ISO 27001 Accreditation Investment | Unlocks six-to-twelve month government tender cycles across all six GCC member states. |
| Edge-to-Core Convergence Development | Opens service revenue streams for integrators lacking deep storage expertise in Qatar rail expansion. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade records, hyperscaler capex disclosures, and NCA regulatory filings, with inputs drawn from systems integrators, data center engineering contractors, and procurement officers at Saudi master developers. Secondary validation incorporates Seagate Technology distribution data, Dell EMC server-storage bundle specifications, and Cisco Systems network-video convergence platform documentation. Bottom-up demand aggregation across camera fleet deployments triangulates against top-down infrastructure investment tracking from smart city authorities.
Segmentation dimensions modeled span storage type, deployment technology, compliance sensitivity, and end-use vertical across the analysis window. CAGRs derive from capacity expansion trajectories in sovereign cloud zones and petabyte-scale tender pipelines. Forecast inputs incorporate H.265 codec migration velocity, NCA Directive 2.0 enforcement timelines, and thermal derating requirements for desert installations.
Decision-makers should treat outputs as directional under assumptions of sustained data localization enforcement and NAND supply continuity; material deviation in sovereign cloud eligibility timelines or flash memory cost volatility would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Farm Video Surveillance System Market
Video Surveillance Systems
Smart Camera System Market
Video Surveillance Systems
Night Vision (IR) Surveillance Cameras Market
Video Surveillance Systems
Germany Surveillance Analog Camera Market
Video Surveillance Systems
United Kingdom Surveillance Camera Market
Video Surveillance Systems
Smart Doorbell Camera Market
Video Surveillance Systems
Global Body Worn Cameras Market
Video Surveillance Systems
AI Surveillance Camera Market
Video Surveillance Systems
Germany Video Surveillance Market
Video Surveillance Systems
Homeland Security Surveillance Camera Market
Video Surveillance Systems
Canada Video Surveillance Market
Video Surveillance Systems
Employee Monitoring Solutions (Automated) Market
Video Surveillance Systems
Mexico Surveillance Camera Market
Video Surveillance Systems
Brazil Video Surveillance Market
Video Surveillance Systems
Latin America Surveillance Camera Market
Video Surveillance Systems
United Arab Emirates Surveillance Camera Market