
 Gunshot Detection System Market | 2026-2036
Gunshot Detection System Market Size, Share, and Industry Trends Forecast 2026-2036
Gunshot Detection System Market Analysis
Subscription-based maintenance and remote monitoring is hardening into the core revenue stream for vendors serving municipal buyers. SoundThinking, Inc. leverages its installed base of acoustic sensors to sustain recurring service contracts across urban police departments. Shooter Detection Systems LLC anchors its competitive position through fixed-installation expertise in federal buildings and critical infrastructure. Raytheon Technologies Corporation dominates defense-sector procurement with hardened infrared detection arrays for forward operating bases.
A gunshot detection system integrates acoustic, radio frequency, or infrared sensors with real-time analytics to identify, locate, and alert authorities to firearm discharges within seconds. These systems typically process multi-channel audio signatures through machine-learning classifiers to distinguish gunshots from ambient noise, achieving location accuracy within meters across distributed microphone arrays. Hybrid systems combining acoustic and infrared modalities command premium positioning due to superior false-positive suppression and all-weather reliability. Educational institutions represent the fastest-growing end-user category as K-12 districts mandate layered security protocols, though law enforcement retains the deepest service-type margin pools through long-term implementation and support agreements.
The U.S. Department of Justice, the Federal Communications Commission, and the National Institute of Standards and Technology collectively shape procurement standards, spectrum allocation for sensor networks, and performance certification protocols. FCC Part 90 rules govern private land mobile radio frequencies carrying gunshot alerts, while NIST ballistics test methods validate sensor accuracy claims for federal grant eligibility. Stakeholders must weigh the trade-off between centralized cloud analytics architectures and edge-processing deployments as data sovereignty requirements tighten across jurisdictions.
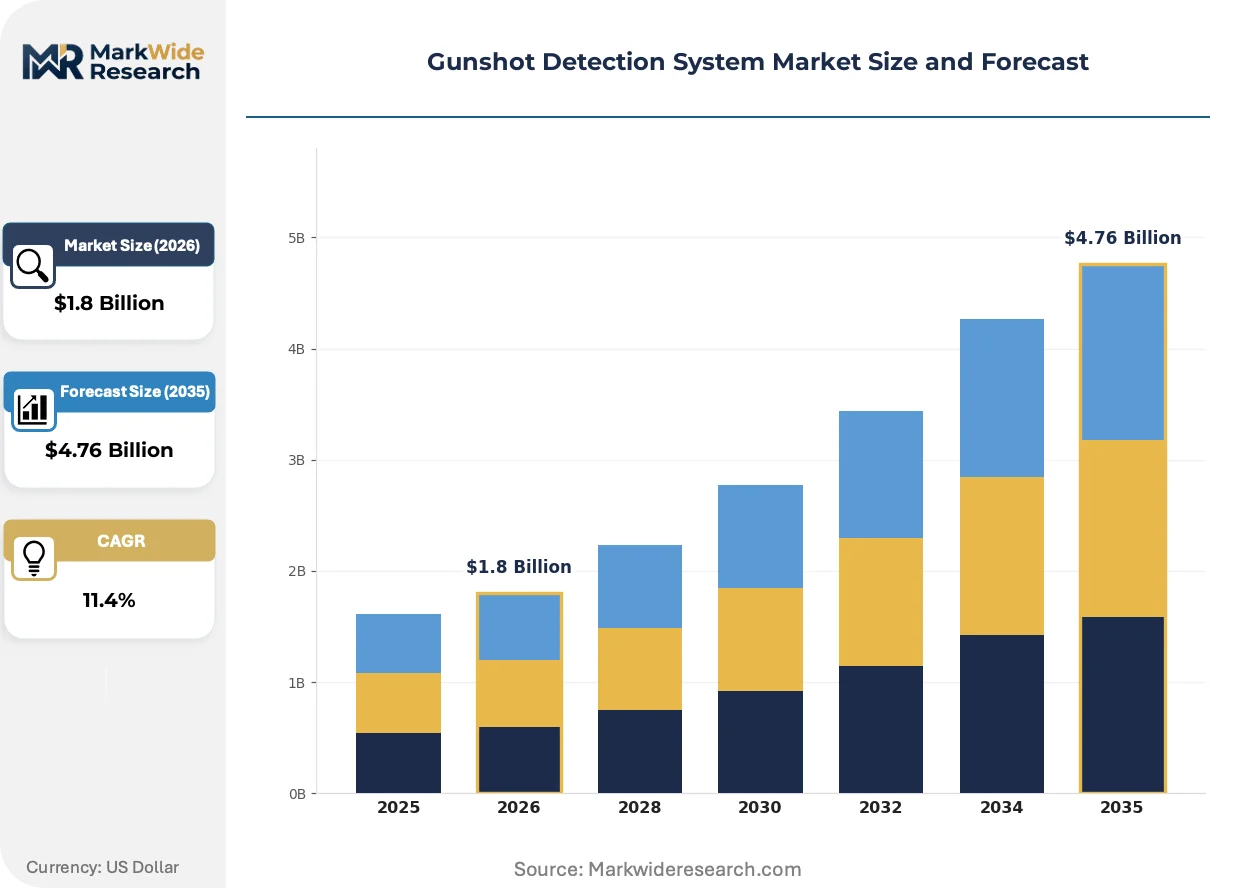
Market Dynamics
Municipal procurement cycles are compressing as federal grant programs accelerate sensor network deployments, while edge-processing architectures displace centralized cloud analytics to satisfy tightening data sovereignty mandates.
Growth Catalysts
- FCC Part 90 spectrum allocation:Private land mobile radio frequencies carrying gunshot alerts enable real-time municipal coordination without public network congestion.
- K-12 security mandates:School districts mandate layered protection protocols, creating institutional procurement pipelines independent of law enforcement budgets.
- Machine-learning classifiers:Multi-channel audio signature processing achieves meter-level accuracy, reducing false-positive rates that previously stalled adoption.
Market Restraints
- Acoustic sensor hardware costs:Distributed microphone arrays require capital-intensive installation across urban grids, straining smaller municipal budgets.
- Cloud-to-edge migration friction:Jurisdictional data sovereignty requirements force expensive re-architecture of existing centralized analytics platforms.
- Environmental audio interference:Dense urban acoustics generate signature overlap with fireworks and vehicle backfires, degrading classifier confidence.
Strategic Opportunities
- Smart city integration:Gunshot detection networks merge with traffic signal and streetlight infrastructure, reducing standalone deployment costs.
- Subscription service models:Remote monitoring contracts convert one-time hardware sales into recurring revenue streams with higher lifetime value.
- Hybrid infrared-acoustic systems:All-weather reliability and false-positive suppression command premium positioning in federal building security.
Industry Challenges
- NIST ballistics certification timelines:Federal grant eligibility requires validated sensor accuracy claims, creating months-long approval bottlenecks.
- Legacy surveillance integration:Municipal buyers demand API compatibility with existing video management systems, complicating vendor qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gunshot Detection System Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Acoustic Sensors, Radio Frequency, Infrared, Hybrid Systems End User: Law Enforcement, Military, Private Security, Educational Institutions Installation Type: Fixed, Portable, Temporary, Remote Monitoring Service Type: Consultation, Maintenance, Implementation, Support |
| Companies Covered | SoundThinking, Inc., Shooter Detection Systems LLC, Raytheon Technologies Corporation, QinetiQ Group plc, ACOEM Group, Thales Group, Databuoy Corporation, Microflown AVISA, AmberBox, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gunshot Detection System Market Emerging Trajectories
Real-time analytics architectures are bifurcating between cloud-centralized and edge-distributed models as data residency rules harden, while procurement patterns shift toward bundled service contracts.
Edge-processing nodes with onboard machine-learning inference are expanding into school district deployments, enabling sub-second alert generation without internet dependency. District technology directors prioritize these hardened units for campus lockdown automation. The shift is compressing vendor margins on hardware while expanding recurring software maintenance pools.
EU AI Act risk classification rules are reshaping procurement documentation requirements for automated threat detection systems sold into member states. Vendors must now maintain algorithmic transparency logs and human-in-the-loop override protocols. European municipal buyers are delaying purchases pending vendor compliance certification, creating a temporary demand lull.
Municipal purchasing departments are consolidating sensor procurement through state-level cooperative contracts, displacing individual city RFP processes. The Texas Department of Information Resources and similar state bodies aggregate volume for pricing leverage. This concentration favors established vendors with existing state contract vehicles over emerging competitors.
Gunshot Detection System Market Segmentation
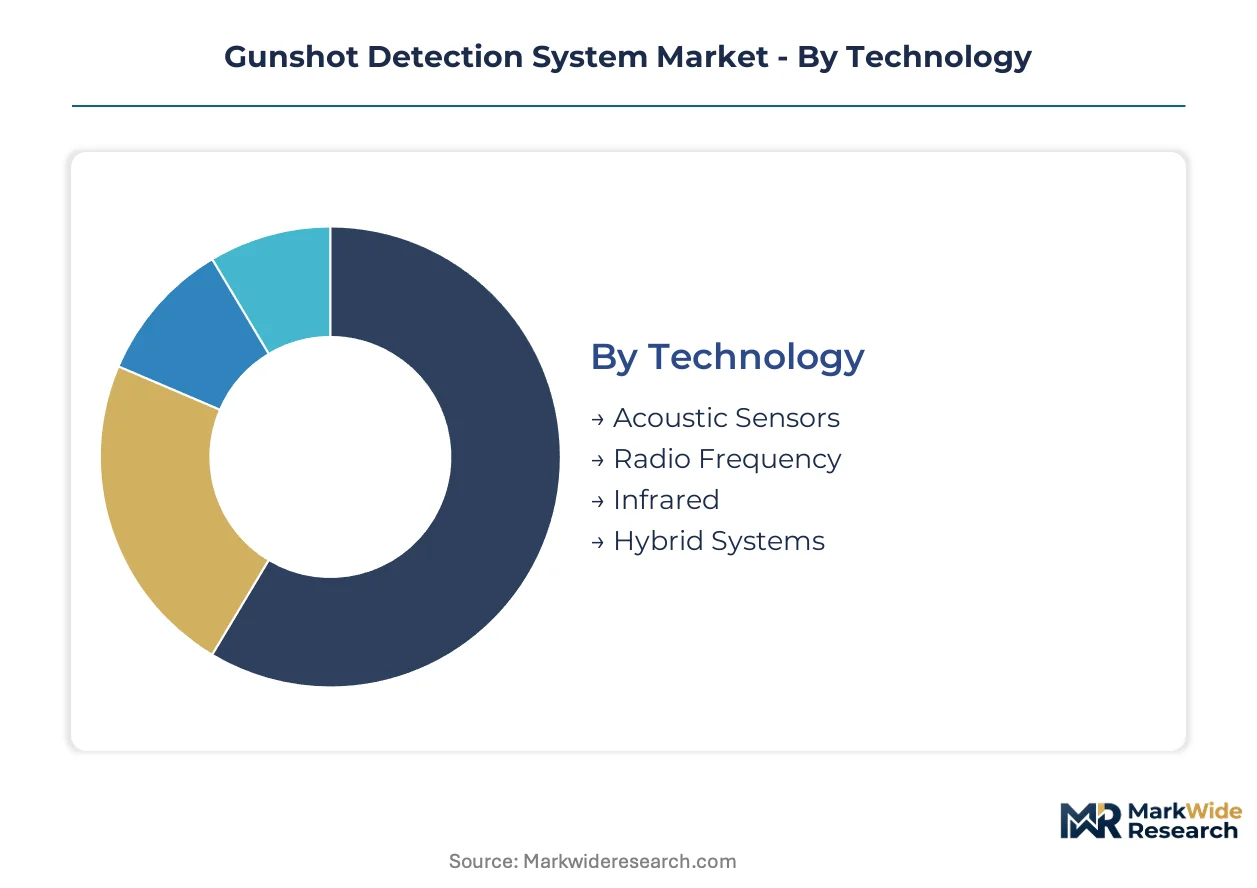
Segmentation in gunshot detection reveals how procurement authority, technical specifications, and service obligations distribute across buyer types. Certification requirements from NIST, FCC, and EU AI Act create divergent compliance burdens that reshape vendor qualification and pricing architecture.
Technology:
Acoustic sensors carry NIST ballistics certification mandates for federal grant eligibility, while hybrid systems face stacked FCC Part 90 spectrum and EU AI Act algorithmic transparency requirements.
- Acoustic Sensors:Distributed microphone arrays process multi-channel audio signatures through machine-learning classifiers. Urban police departments in Chicago and Houston anchor procurement volume, driven by legacy infrastructure compatibility and established maintenance protocols.
- Hybrid Systems:Combined acoustic-infrared modalities achieve all-weather reliability with superior false-positive suppression. Federal building security contracts in Washington D.C. and critical infrastructure operators command premium positioning despite higher unit costs.
- Infrared:Hardened detection arrays for forward operating bases and perimeter defense.
- Radio Frequency:Supplementary signal processing for signature validation in dense urban acoustics.
Acoustic sensors sit at the top of the volume ranking, with hybrid systems climbing the fastest.
End User:
Cost tier differentiation separates institutional buyers with dedicated security budgets from municipal agencies dependent on federal grant cycles.
- Law Enforcement:Urban police departments sustain the deepest service-type margin pools through multi-year implementation and support agreements. Subscription-based remote monitoring contracts convert hardware sales into recurring revenue with higher lifetime value.
- Educational Institutions:K-12 districts mandate layered protection protocols, creating procurement pipelines independent of law enforcement budgets. Edge-processing nodes with onboard inference enable sub-second alert generation for campus lockdown automation.
- Military:Forward operating base deployments require hardened infrared arrays with defense-grade specifications.
- Private Security:Corporate campuses and commercial real estate operators prioritize API compatibility with existing video management systems.
Law Enforcement commands the largest installed base, with Educational Institutions expanding most quickly.
Installation Type:
Application flexibility determines whether deployments anchor permanently to infrastructure or follow event-driven mobility patterns.
- Fixed:Permanent sensor integration with traffic signal and streetlight infrastructure reduces standalone deployment costs. Smart city coordinators in Dallas and Atlanta consolidate procurement through state cooperative contracts for pricing leverage.
- Remote Monitoring:Subscription service models centralize alert validation and maintenance oversight. Municipal buyers shift operational burden to vendors while retaining incident response authority.
- Portable:Rapid deployment units for temporary events and emergency response scenarios.
- Temporary:Short-duration installations for construction sites and special event security.
Fixed installations dominate capital expenditure allocation, with Remote Monitoring gaining share fastest.
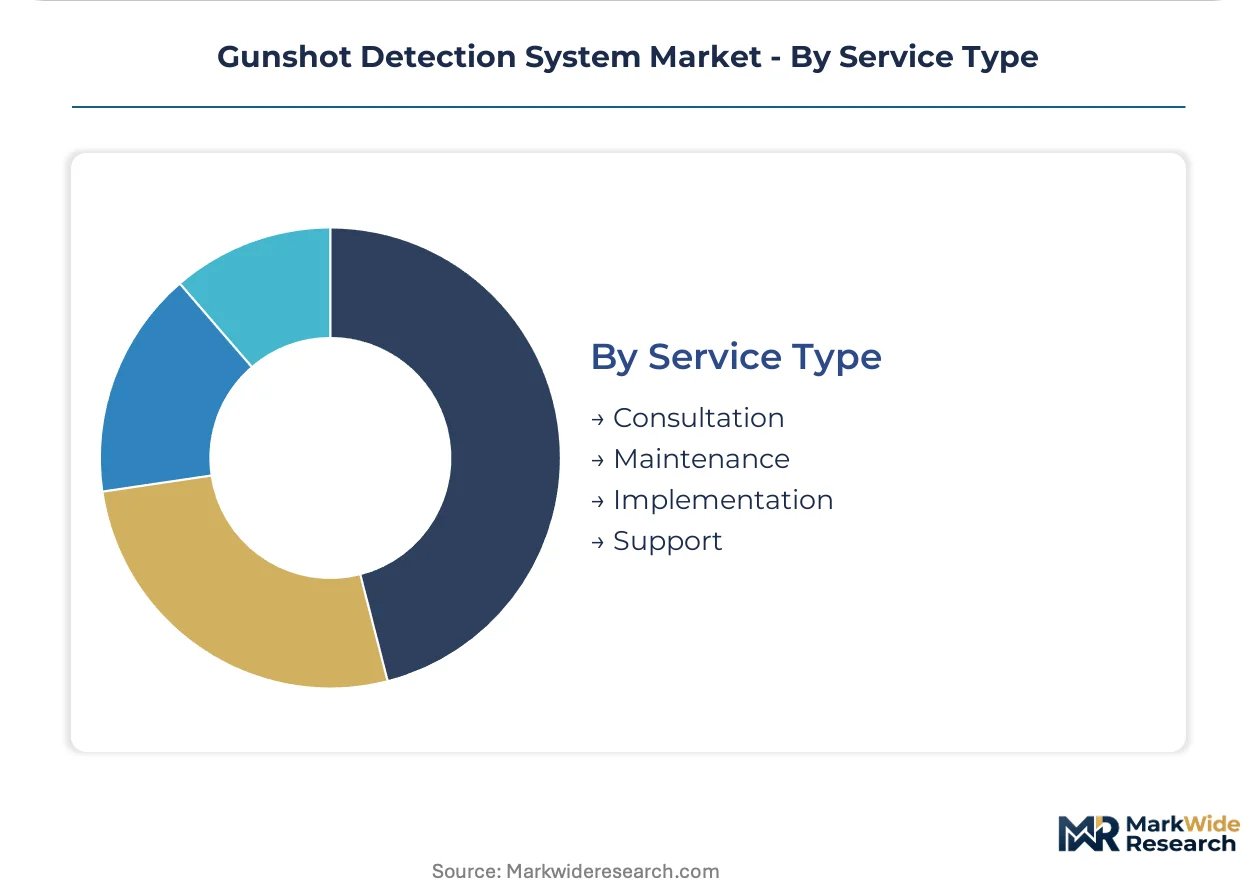
Service Type:
Margin concentration pools in post-sale obligations as hardware commoditization compresses upfront equipment pricing.
- Maintenance:Recurring service contracts sustain vendor revenue across sensor network lifecycles. Remote diagnostics and firmware updates reduce field technician dispatch frequency.
- Implementation:System integration with legacy surveillance networks and municipal IT infrastructure. API compatibility requirements complicate vendor qualification and extend sales cycles.
- Support:24/7 alert validation and law enforcement coordination services.
- Consultation:Security assessment and sensor placement optimization for greenfield deployments.
Maintenance captures the highest recurring revenue share, with Implementation showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping vendor qualification costs, with EU AI Act compliance burdens pushing procurement documentation toward US and Middle Eastern jurisdictions where federal grant mechanisms accelerate deployment cycles without algorithmic transparency mandates.
United States
Municipal police departments in Chicago and Houston anchor procurement volume through legacy acoustic sensor networks. The Department of Justice grant programs compress procurement timelines by underwriting capital-intensive distributed microphone array installations. School districts in Dallas and Atlanta consolidate purchases through Texas Department of Information Resources cooperative contracts, displacing individual city RFP processes.
Germany
Industrial security operators in the Ruhr region and Bavaria demand API compatibility with existing video management systems for critical infrastructure protection. The country's national data protection regulator enforces strict data residency requirements that force expensive re-architecture of centralized cloud analytics platforms. Frankfurt and Munich municipal buyers delay hybrid system deployments pending vendor compliance with EU AI Act algorithmic transparency logs.
United Kingdom
London Metropolitan Police sustain service-type margin pools through multi-year implementation agreements with remote monitoring vendors. The Information Commissioner's Office governs automated threat detection data processing under GDPR-derived frameworks. Greater Manchester and West Midlands police forces pilot edge-processing nodes for sub-second alert generation independent of public network congestion.
France
ANSM and CNIL jointly oversee risk classification documentation for machine-learning classifiers deployed in urban surveillance networks. Paris and Marseille smart city coordinators merge gunshot detection with streetlight infrastructure to reduce standalone deployment costs. The country's national pharmaceutical regulator has no direct jurisdiction, leaving CNIL to enforce algorithmic accountability through procurement pre-qualification.
United Arab Emirates
MOHAP and federal security procurement bodies prioritize hardened infrared arrays for federal building perimeter defense in Abu Dhabi and Dubai. The absence of EU AI Act-equivalent mandates attracts vendors seeking to bypass European compliance bottlenecks. NEOM and Riyadh-adjacent developments in Saudi Arabia create cross-border demand clusters for all-weather hybrid detection systems.
Gunshot Detection System Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with municipal procurement favoring established maintenance protocols while federal buyers prioritize hardened defense-grade specifications. The vendor base organizes around three archetypes: acoustic sensor specialists with urban police department installed bases, hybrid system integrators serving critical infrastructure, and defense contractors with infrared array expertise. Competitive moves concentrate on state cooperative contract qualification and edge-processing firmware development to satisfy tightening data sovereignty mandates.
Within the acoustic sensor tier, SoundThinking, Inc. and Shooter Detection Systems LLC exemplify divergent positioning—one leveraging recurring service contracts across urban police departments, the other anchoring fixed-installation expertise in federal buildings. Raytheon Technologies Corporation occupies the defense-contractor archetype with hardened infrared specifications for forward operating bases. These three entities collectively illustrate how procurement authority fragmentation—municipal, federal, military—creates non-overlapping competitive arenas rather than direct rivalry.
| Leading Market Players |
|---|
| SoundThinking, Inc. |
| Shooter Detection Systems LLC |
| Raytheon Technologies Corporation |
| QinetiQ Group plc |
| ACOEM Group |
| Thales Group |
| Databuoy Corporation |
| Microflown AVISA |
| AmberBox, Inc. |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up acoustic sensor specialists anchor supply discipline through centralized procurement of distributed microphone arrays, converting hardware commoditization pressure into subscription pricing power across municipal maintenance contracts. This ownership structure concentrates vendor negotiation leverage while fragmenting buyer price sensitivity across federal grant-dependent police departments and independent school district budgets.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for edge-processing chipsets that power onboard machine-learning inference. Three-tier pricing structure across premium hybrid infrared-acoustic, standard fixed-installation acoustic, and economy portable units separates federal building security contracts from school district deployments. Cost compression in the standard tier stems from state cooperative contract aggregation through vehicles like the Texas Department of Information Resources. Educational institutions exhibit highest price sensitivity due to independent capital budgeting, while defense-sector buyers show lowest sensitivity given hardened specification requirements.
Supply Chain Analysis
Regional distribution centers in Texas, California, and Illinois anchor hub-and-spoke fulfillment patterns for sensor hardware destined to urban police departments. Manufacturing concentrates in the United States, Mexico, and Germany for acoustic array assembly, with Taiwan and South Korea supplying edge-processing semiconductors. Component dependencies include MEMS microphones, infrared detectors, and ruggedized enclosure materials. Single-source vulnerability in FPGA supply from Xilinx-dependent vendors creates procurement risk. Distribution runs through state cooperative purchasing vehicles and direct municipal contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play between EU AI Act compliance costs delaying European procurement and U.S. federal grant acceleration compressing municipal sales cycles without algorithmic transparency mandates.
For Market Incumbents: Hedge against margin erosion in hardware sales by deepening recurring service contract penetration across existing urban police department installed bases. Accelerate edge-processing firmware development to satisfy tightening data sovereignty requirements in Germany and France. Counter threat from hybrid system integrators by securing state cooperative contract vehicles before procurement consolidation advances. For New Entrants and Emerging Players: Launch via state cooperative contract qualification to bypass individual municipal RFP barriers. Target K-12 school districts in Texas and Georgia as most penetrable segment given independent security budgets and edge-processing priority for campus lockdown automation. Pursue API-first integration positioning to exploit legacy surveillance compatibility requirements stalling incumbent vendor qualification. For Investors and Strategic Acquirers: Valuations sit cheapest among acoustic sensor specialists with stagnant hardware revenue but undermonetized maintenance contract bases. Long-term viability hinges on subscription service transition completion and hybrid technology portfolio expansion. Watch NIST ballistics certification approval timelines as inflection indicator for federal grant eligibility pipeline velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Processing Firmware Development | Enables sub-second alert generation for Dallas and Atlanta school districts without cloud dependency. |
| State Cooperative Contract Qualification | Secures pricing leverage through Texas Department of Information Resources aggregation vehicles. |
| Hybrid Infrared-Acoustic System Launch | Commands premium positioning in Washington D.C. federal building security with all-weather reliability. |
| API Integration Partnership | Resolves legacy video management system compatibility barriers for Chicago and Houston police departments. |
| EU AI Act Compliance Certification | Unlocks Paris and Marseille procurement pipelines currently delayed by algorithmic transparency documentation. |
Methodological Framework
Multiple input streams — sensor network deployment records, federal grant obligation databases, and vendor maintenance contract filings — were reconciled against municipal procurement documents and school district technology expenditure reports. Primary interviews with urban police department technology directors, K-12 district security coordinators, federal facilities managers, and acoustic sensor R&D engineers were cross-validated against FCC Part 90 spectrum allocation records, NIST ballistics test documentation, and EU AI Act implementation guidance. Secondary sources included Department of Justice grant program disclosures, state cooperative purchasing vehicle contracts, and smart city infrastructure investment announcements. Bottom-up unit deployment estimates and top-down addressable market sizing were triangulated to constrain forecast variance.
Historical deployment trajectories in Chicago, Houston, Dallas, and Atlanta were cross-referenced against panel input from procurement officers regarding budget cycle timing and federal grant dependency. Segmentation modeling spanned technology modality, end-user category, installation type, and service obligation structure across the projection horizon. CAGRs were derived from fitted growth curves calibrated to municipal procurement compression rates and school district mandate adoption timelines. Forecast inputs included FCC spectrum allocation stability, NIST certification backlog duration, and edge-processing cost decline curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU AI Act enforcement escalation or federal grant program suspension. Outputs reflect documented assumptions regarding municipal budget elasticity and technology refresh cycle timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Cellular Interception Market
Video Surveillance Systems
United States Surveillance Storage Market
Video Surveillance Systems
France Surveillance Analog Camera Market
Video Surveillance Systems
Smart Home Security Camera Market
Video Surveillance Systems
Crawler Camera System Market
Video Surveillance Systems
Brazil Surveillance IP Cameras Market
Video Surveillance Systems
Japan Video Surveillance Market
Video Surveillance Systems
Europe Surveillance Camera Market
Video Surveillance Systems
CCTV Camera Market
Video Surveillance Systems
Security Camera Software Market
Video Surveillance Systems
Smart Doorbell Camera Market
Video Surveillance Systems
Wireless Home Security Camera Market
Video Surveillance Systems
China Surveillance Analog Camera Market
Video Surveillance Systems
Camera Alarm System Market
Video Surveillance Systems
Wearable and Body-Worn Cameras Market
Video Surveillance Systems
Latin America Surveillance IP Cameras Market