
 Inspection Camera System Market | 2026-2036
Inspection Camera System Market Size, Share, and Industry Trends Forecast 2026-2036
Inspection Camera System Market Intelligence
Demand from the manufacturing sector for in-line quality control is expanding its share relative to mature applications in municipal pipe inspection. Olympus Corporation specializes in high-resolution systems for intricate aerospace and automotive component checks. Basler AG leverages its expertise in digital imaging for high-speed automated quality control solutions on production lines. Meanwhile, FLIR Systems, Inc. competes by integrating thermal imaging capabilities for predictive maintenance in industrial equipment.
An inspection camera system is a tool for remote visual inspection, typically comprising a camera head with integrated lighting on a flexible probe connected to a display unit. These systems often feature high-resolution CMOS sensors and articulating tips to navigate confined or hazardous spaces for non-destructive evaluation. Digital and HD video technologies are rapidly displacing older analog systems due to superior image clarity and data management capabilities. While handheld units lead in sales volume for building inspection, specialized articulating video borescopes for equipment maintenance command higher margins.
Regulatory frameworks such as Europe's CE marking dictate essential safety and electromagnetic compatibility requirements for electronic devices. In the United States, OSHA guidelines for confined space entry indirectly drive demand for remote inspection tools to ensure worker safety during maintenance. Similarly, standards from the American Society of Mechanical Engineers influence inspection protocols for pressure vessels and boilers. The ability to integrate advanced analytics and reporting software will determine future vendor leadership.
Market Dynamics
The central force shaping the inspection camera system market is the convergence of robotics and artificial intelligence. This shift transforms inspection from a manual, reactive process into an automated, data-driven component of industrial process control, particularly within advanced manufacturing.
Growth Catalysts
- Regulatory Safety Mandates:Worker safety regulations, such as OSHA's confined space entry standards in the United States, compel the use of remote visual inspection tools, reducing human exposure to hazardous environments in the oil and gas and chemical industries.
- Zero-Defect Manufacturing:The automotive industry, especially in Germany, demands rigorous quality control for electric vehicle battery and powertrain components, driving adoption of high-speed, in-line inspection systems to prevent costly recalls and ensure performance.
- Digital Technology Displacement:Superior image clarity and data management capabilities of high-definition CMOS sensors and digital video platforms are accelerating the replacement of older analog systems in critical sectors like aerospace for enhanced record-keeping and analysis.
Market Restraints
- High Capital Investment:The substantial upfront cost of advanced articulating video borescopes, particularly those integrated with AI-powered analytics software, presents a significant adoption barrier for small and medium-sized enterprises in the manufacturing sector.
- Technical Performance Limits:Current probe designs face physical limitations in flexibility, articulation range, and length, restricting access to exceptionally narrow or complex geometries found in certain nuclear and aerospace components.
- Alternative NDT Methods:In applications where surface visualization is insufficient, substitution by other non-destructive testing methods like ultrasonic, radiographic, or eddy current testing, which can detect subsurface flaws, constrains market scope.
Strategic Opportunities
- Industrialization in India:The country's expanding manufacturing base, supported by policies like the Production Linked Incentive (PLI) scheme, creates significant white space for automated quality control systems in pharmaceuticals, electronics, and automotive production.
- Renewable Energy Infrastructure:Predictive maintenance applications for wind turbine gearboxes and blades, as well as solar panel and inverter inspection, represent a fast-growing opportunity as energy grids decarbonize and asset uptime becomes critical.
- Augmented Reality Integration:The convergence of inspection cameras with AR headsets enables remote expert collaboration, allowing an off-site specialist to guide a field technician through complex repairs or inspections, reducing travel costs and downtime.
Industry Challenges
- Skilled Technician Scarcity:A persistent shortage of operators proficient in navigating complex internal structures with articulating probes and interpreting the outputs from AI-driven defect recognition software limits the effective deployment of advanced systems.
- Legacy System Integration:Integrating new digital inspection data streams into existing enterprise resource planning (ERP) and manufacturing execution systems (MES) often proves complex and costly, hindering the realization of a fully connected smart factory.
- Data Interoperability:The absence of standardized data formats for inspection imagery and AI-generated reports across different vendor platforms creates data silos, complicating efforts to perform fleet-wide analysis or switch suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inspection Camera System Market |
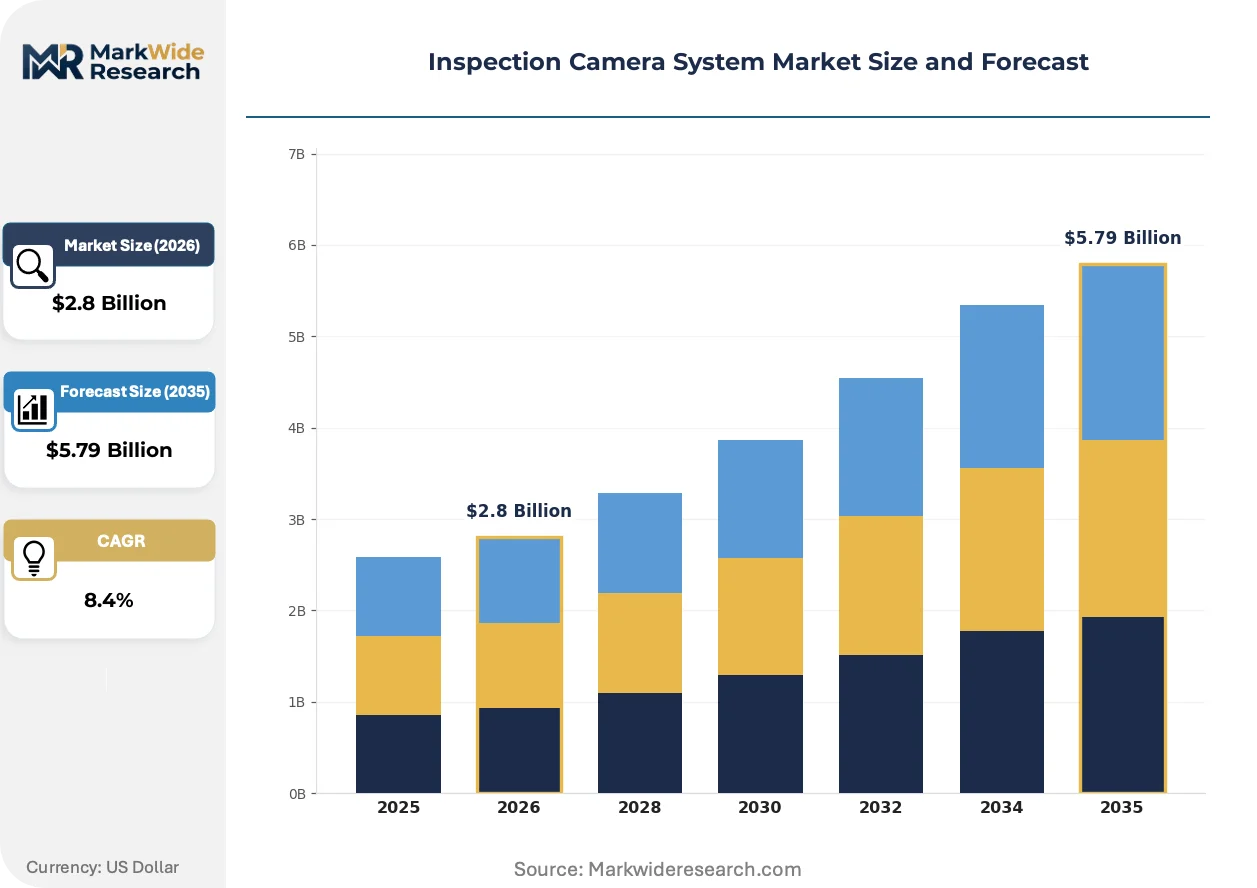
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Pipeline, Wireless, Articulating Technology: Analog, Digital, Infrared, HD Video End User: Construction, Automotive, Manufacturing, Healthcare Application: Pipe Inspection, Building Inspection, Equipment Maintenance, Quality Control |
| Companies Covered | Basler AG, Olympus Corporation, FLIR Systems, Inc., Eddyfi Technologies, Leica Microsystems, Ridgid Tools, AMETEK, Inc., Minicam Group, iPEK International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inspection Camera System Market Strategic Shifts & Innovations
The market is evolving from a focus on visualization hardware to an emphasis on data generation and analytics. This transition positions inspection systems as critical data nodes within broader industrial automation and predictive maintenance ecosystems, valuing software and connectivity as much as optics.
Artificial intelligence integrated directly into image processing units provides the ability to automatically detect, classify, and flag defects in real-time video feeds. The manufacturing sector, particularly for high-volume electronics and automotive components, is adopting this technology at a rapid pace. This capability is expanding into predictive quality analytics, where aggregated defect data is used to forecast and prevent future production line failures.
Regulatory frameworks are beginning to address the use of AI in critical applications. The European Union's proposed AI Act, for instance, will likely classify AI used for industrial quality control as high-risk, imposing strict requirements for data governance, transparency, and human oversight. Consequently, vendors targeting the German automotive and French aerospace industries are proactively embedding explainable AI (XAI) features to ensure compliance.
A significant behavioral shift is underway from one-time capital equipment sales to recurring revenue models. This trend unbundles the advanced analytics software from the physical borescope, offering "Inspection-as-a-Service" (IaaS) through subscriptions that make AI capabilities more accessible. This model is gaining traction in the North American energy sector for pipeline integrity management, where project-based operational budgets favor flexible service contracts over large upfront purchases.
Inspection Camera System Market Segmentation
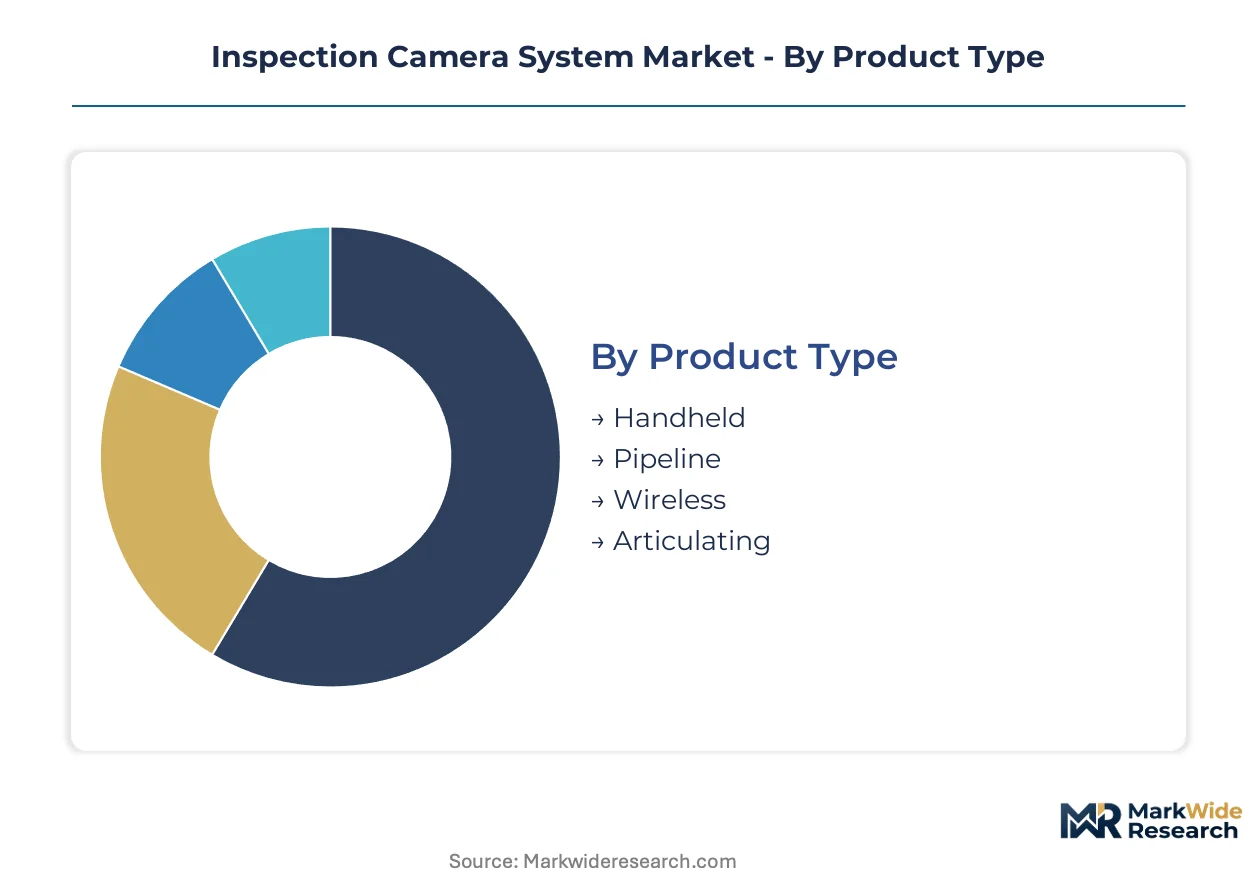
The inspection camera system market is segmented to illuminate distinct product functionalities, technological advancements, end-user requirements, and specific application scenarios. This granular breakdown helps identify areas of concentrated demand and emerging opportunities within the broader industrial and commercial landscape.
Product Type:
The product type segmentation differentiates systems based on their integration depth and operational mobility, ranging from fully portable units to specialized, semi-fixed installations.
- Articulating:These advanced systems feature flexible probes with steerable tips, enabling precise navigation around complex internal geometries for non-destructive evaluation in aerospace components and power generation turbines. Demand for these high-margin tools is concentrated in Germany for precision manufacturing and maintenance.
- Handheld:Comprising a camera and display in a single portable unit, handheld systems offer ease of use and portability, making them ideal for rapid visual checks in building diagnostics and general maintenance tasks. Sales volume for handheld units remains highest in the construction and general inspection sectors across North America.
- Pipeline:Specialized camera systems designed for traversing long, narrow conduits, often used for municipal wastewater infrastructure and industrial process piping.
- Wireless:These systems transmit video data wirelessly, enhancing maneuverability and safety by eliminating physical tethers in hazardous or hard-to-reach environments.
Volume placements concentrate in Handheld units; the faster expansion belongs to Articulating systems.
Technology:
The technology segment highlights the evolution of visual inspection capabilities, from foundational imaging methods to advanced digital and thermal solutions.
Technological advancements in imaging and data processing are fundamentally reshaping the capabilities and adoption patterns across various inspection camera system categories.
- HD Video:Offering superior image clarity and resolution, HD video platforms are rapidly displacing older formats, providing enhanced detail for defect identification and critical record-keeping in aerospace and automotive manufacturing. Integration with advanced analytics software in European factories drives its adoption.
- Digital:Digital systems convert analog signals into discrete data, allowing for easier storage, analysis, and integration with enterprise resource planning (ERP) systems for comprehensive data management. The shift from analog to digital is particularly pronounced in industrial quality control applications.
- Analog:Older systems relying on continuous electrical signals for image transmission, primarily found in legacy installations or cost-sensitive, basic visual inspection tasks.
- Infrared:These systems detect thermal radiation, enabling predictive maintenance by identifying heat anomalies in electrical components, machinery, and building envelopes.
The market is experiencing significant upgrades towards HD Video, while Analog systems face rapid obsolescence.
End User:
The end-user segmentation reveals the diverse industries leveraging inspection camera systems for quality assurance, maintenance, and safety compliance.
Different end-user industries exhibit distinct procurement patterns and technical requirements, influencing the design and feature sets of inspection camera systems.
- Manufacturing:This sector utilizes inspection cameras for automated in-line quality control, defect detection in high-volume production, and precision component verification, especially in electronics and automotive industries. Germany's advanced manufacturing base drives significant demand for these systems.
- Automotive:Inspection systems are critical for ensuring zero-defect production of powertrain components, electric vehicle batteries, and vehicle assemblies, preventing costly recalls and enhancing brand reputation. Rigorous quality standards in the German automotive industry compel advanced system adoption.
- Construction:Inspection cameras assist in structural assessments, plumbing diagnostics, and post-construction quality checks, improving safety and reducing rework.
- Healthcare:Specialized systems are employed for inspecting medical devices, ensuring sterile environments, and performing internal diagnostics of complex equipment.
Manufacturing and Automotive sectors are driving the highest demand for advanced inspection camera systems.
Application:
Application-based segmentation categorizes the market according to the specific tasks and operational challenges addressed by inspection camera systems.
The diverse range of applications underscores the versatility of inspection camera systems in addressing critical needs across various operational environments.
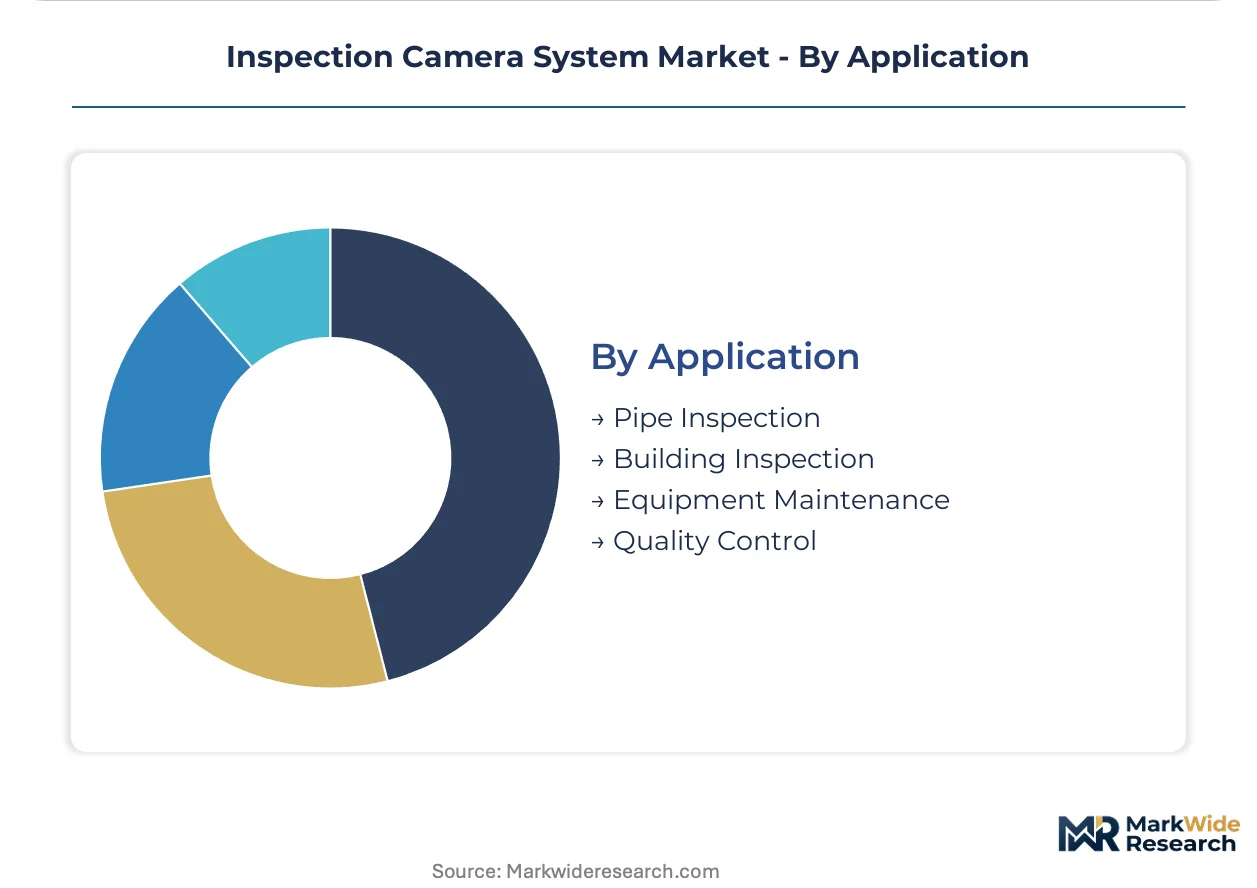
- Quality Control:This application involves automated or manual inspection of manufactured goods to detect defects, ensure compliance with specifications, and maintain production standards, particularly for electronics and precision machinery. The integration of AI for real-time defect detection is transforming this segment.
- Equipment Maintenance:Employing inspection cameras for predictive and preventive maintenance of industrial machinery, turbines, and complex systems to identify wear, damage, or potential failures before they lead to costly downtime. This application commands higher margins due to its specialized nature.
- Pipe Inspection:Focuses on internal visual assessment of pipelines for blockages, corrosion, cracks, and structural integrity in municipal, industrial, and oil and gas infrastructure.
- Building Inspection:Includes visual checks of building envelopes, HVAC systems, electrical conduits, and structural elements to identify issues like moisture, pests, or damage.
Quality Control applications are expanding most quickly, while Pipe Inspection represents a mature segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production Linked Incentive (PLI) scheme is driving significant investment in domestic manufacturing, creating substantial demand for advanced inspection camera systems. This policy initiative positions India as a rapidly emerging market for automated quality control solutions. Germany continues to lead in adoption due to its established industrial base and stringent quality requirements.
Germany
Demand for high-speed, in-line inspection systems is particularly strong in Germany, driven by its advanced automotive and precision manufacturing sectors. The CE marking regulatory framework mandates essential safety and electromagnetic compatibility for electronic devices, influencing system design. Automotive production hubs in Bavaria and Baden-Württemberg require sophisticated articulating video borescopes for zero-defect manufacturing of EV components.
United States
Worker safety regulations, such as OSHA's confined space entry standards, compel the use of remote visual inspection tools in the United States, especially in the oil and gas and chemical industries. The US manufacturing sector is adopting digital inspection systems for enhanced record-keeping and analysis. Major industrial regions like the Great Lakes area and Texas exhibit strong demand for predictive maintenance applications in critical infrastructure.
India
India's expanding manufacturing base, supported by the Production Linked Incentive (PLI) scheme, creates significant white space for automated quality control systems. The country's national quality standards, set by BIS, promote the use of precise inspection technologies in electronics and automotive production. Industrial corridors in Maharashtra and Gujarat are seeing increased investment in digital inspection capabilities for pharmaceuticals and automotive components.
Japan
Japan's precision manufacturing sector, particularly in aerospace and high-volume electronics, requires high-resolution inspection systems for intricate component checks. METI guidelines encourage technological advancements for industrial automation and quality assurance. Major industrial clusters in the Kanto region, including Tokyo, are actively integrating AI-powered image analysis for real-time defect detection in complex assemblies.
Inspection Camera System Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with a notable concentration among firms offering advanced technological capabilities. The market structure exhibits a tiered approach, where premium providers focus on specialized applications and value-added software. Strategic partnerships and technology licensing are dominant competitive moves as companies seek to expand their solution portfolios and market reach.
On the premium-tier vector, Olympus Corporation exemplifies expertise in high-resolution systems for intricate aerospace and automotive component checks. Basler AG, a German-based company, occupies a strong position by leveraging its expertise in digital imaging for high-speed automated quality control solutions on production lines. FLIR Systems, Inc. represents a specialized archetype by integrating thermal imaging capabilities for predictive maintenance in industrial equipment, serving critical infrastructure sectors.
| Leading Market Players |
|---|
| Basler AG |
| Olympus Corporation |
| FLIR Systems, Inc. |
| Eddyfi Technologies |
| Leica Microsystems |
| Ridgid Tools |
| AMETEK, Inc. |
| Minicam Group |
| iPEK International GmbH |
| Others |
Cost & Logistics Intelligence
Automotive original equipment manufacturers (OEMs) and advanced manufacturing firms drive demand for specialized inspection camera systems, which influences a value-based pricing model for high-performance units. This concentration of sophisticated buyers rewards suppliers capable of delivering integrated solutions with advanced analytics.
Pricing Analysis
Premium pricing for short lead times on custom articulating borescopes reflects specialized manufacturing and integration complexity. The pricing model often combines project-based fees for system integration with recurring subscription revenue for AI-powered analytics software. High-resolution CMOS sensor technology and articulating tip complexity are significant price differentiation drivers. Pricing softness for basic handheld units stems from commoditization and widespread availability. Large industrial firms prioritize value and performance, while small and medium-sized enterprises (SMEs) are most price-sensitive for advanced systems.
Supply Chain Analysis
Compliance with CE marking and ISO 9001 certifications acts as a significant gating factor for suppliers of inspection camera components. Geographic supply concentration for critical components includes Germany for precision optics and robotics, and Japan for high-resolution CMOS sensors. The supply chain relies on specialized micro-actuators and flexible probe materials. Single-source vulnerability for advanced sensor components presents a structural risk. Distribution runs through direct sales channels for specialized industrial systems and multi-channel distributors for handheld units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market for inspection camera systems is supply-constrained, with specialized sensor manufacturing capacity for high-resolution imaging technology propping pricing for advanced units.
For Market Incumbents:
Anchor market leadership by deepening AI integration within existing product lines, particularly for real-time defect detection in automotive and aerospace. Expand service contracts to include predictive quality analytics, mitigating the threat from lower-cost digital imaging providers. Invest in advanced R&D for probe miniaturization and enhanced articulation capabilities to access complex geometries. Secure long-term supply agreements for high-resolution CMOS sensors and precision optics.
For New Entrants and Emerging Players:
Leverage digital-channel routes to penetrate niche applications within renewable energy infrastructure, such as wind turbine blade inspection. Target underpenetrated segments like small and medium-sized enterprises (SMEs) in India's expanding manufacturing base. Offer "Inspection-as-a-Service" (IaaS) subscription models for AI analytics, lowering the barrier to entry for advanced capabilities. Focus on specialized building diagnostics for structural integrity and moisture detection.
For Investors and Strategic Acquirers:
The window for entry favors strategic acquirers seeking to consolidate fragmented software capabilities. Long-term viability remains strong as asset uptime and quality control are critical for industrial operations. Target software firms specializing in AI-powered image analytics or data integration platforms for enhanced predictive maintenance offerings. Increased regulatory mandates for predictive maintenance in critical infrastructure serve as a key signal to watch for inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen AI-powered image analysis capabilities | This enhances real-time defect detection for high-volume manufacturing processes. |
| Expand Inspection-as-a-Service (IaaS) offerings | This shifts revenue models and increases accessibility for advanced analytics features. |
| Invest in probe miniaturization R&D | This enables access to exceptionally narrow or complex internal component geometries. |
| Secure long-term supply for CMOS sensors | This mitigates single-source vulnerability for critical high-resolution imaging components. |
| Form partnerships for AR/VR integration | This facilitates remote expert collaboration during complex inspections and repairs. |
Research Approach
Independent corroboration across industry association reports, regulatory filings, and academic research underwrites the qualitative findings. This study combined primary interviews with manufacturing plant managers, quality control engineers, maintenance directors, and procurement specialists. Secondary validation included data from OSHA guidelines, CE marking directives, and non-destructive testing (NDT) organizations. A bottom-up approach was integrated with top-down triangulation to ensure comprehensive data coverage.
Comparable historical reference periods anchored the forecast window for the inspection camera system market. The analytical framework modeled segmentation dimensions including product type, technology, end-user, application, and regional adoption patterns. Compound annual growth rates (CAGRs) were derived from historical trends and projected technological advancements in imaging. Industrial automation investment rates and regulatory enforcement levels served as key industry-specific forecast inputs across the analysis window.
Inputs from public financial disclosures and industry reports were available through the study window; gaps in emerging market specific data introduce uncertainty bands. Forecasts reflect assumptions regarding the pace of AI integration and global manufacturing capital expenditure. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
North America Smart Home Security Cameras Market
Video Surveillance Systems
Mexico Video Surveillance Market
Video Surveillance Systems
Wireless Security Camera Market
Video Surveillance Systems
Germany Surveillance Analog Camera Market
Video Surveillance Systems
Integrated Video Surveillance Systems Market
Video Surveillance Systems
Canada Surveillance Storage Market
Video Surveillance Systems
Video Surveillance Market
Video Surveillance Systems
Smart Home Security Camera Market
Video Surveillance Systems
Wearable and Body-Worn Cameras Market
Video Surveillance Systems
Privacy Filters Market
Video Surveillance Systems
Crawler Camera System Market
Video Surveillance Systems
Mexico Surveillance Analog Camera Market
Video Surveillance Systems
Under-Vehicle Surveillance Market
Video Surveillance Systems
India Video Surveillance Market
Video Surveillance Systems
Middle East and Africa Video Surveillance Market
Video Surveillance Systems
Connected Enterprise Video Surveillance Solutions Market