
 India Video Surveillance Market | 2026-2036
India Video Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
India Video Surveillance Market Insights
High-definition 4K resolution tier is rotating through municipal and commercial procurement channels as the baseline specification for new installations. Hangzhou Hikvision Digital Technology Co., Ltd. leverages its manufacturing scale to dominate mid-range IP camera supply for Indian government tenders. Godrej and Boyce Mfg. Co. Ltd. anchors domestic production with localized assembly operations that compete on delivery timelines for large-scale safe city contracts. Axis Communications AB specializes in premium network camera segments where enterprise clients prioritize cybersecurity-hardened firmware architectures.
Video surveillance encompasses camera hardware, recording infrastructure, and analytics software designed to capture, store, and process visual data for security monitoring and operational intelligence; modern systems integrate CMOS sensors with H.265 compression to reduce bandwidth consumption while maintaining forensic-grade image fidelity at frame rates exceeding 25 fps. IP Cameras now lead product type deployment as analog infrastructure ages out of government and banking estates. AI-Driven Analytics represents the fastest-expanding technology segment where edge-based facial recognition and behavioral pattern detection command premium pricing. Cloud-Based architectures are displacing legacy on-premises storage in retail and transportation verticals seeking centralized multi-site visibility.
BIS certification requirements and the Ministry of Home Affairs safe city guidelines are tightening product compliance for network-connected surveillance equipment entering government projects. CDSCO oversight intersects where biometric analytics process personal health data in hospital and pharmaceutical facility deployments. SEBI mandates for banking infrastructure security are extending camera coverage requirements to ATM networks and branch perimeters. Stakeholders must weigh domestic value-add thresholds against technology access as PLI scheme incentives reshape supplier qualification criteria for public sector tenders.
Market Dynamics
AI-integrated video analytics is compressing procurement cycles across Indian state police departments as command centers demand real-time threat detection capabilities over passive recording infrastructure.
Growth Catalysts
- Ministry of Home Affairs Safe City Mandate:Central government funding for 100% camera coverage in metro transit corridors is accelerating deployment timelines for IP-based surveillance networks.
- Smart City Mission Infrastructure:Urban development authorities in Mumbai and Delhi are embedding surveillance into integrated command and control centers as core municipal assets.
- SEBI Banking Security Directives:Extended coverage mandates for ATM networks and branch perimeters are expanding camera density across financial services estates.
Market Restraints
- CMOS Sensor Import Concentration:Dependence on East Asian semiconductor supply chains exposes domestic integrators to input cost volatility and extended lead times.
- BIS Certification Friction:Bureau of Indian Standards testing protocols for network-connected equipment create 4-6 month product qualification delays before tender eligibility.
- Cloud Storage Bandwidth Costs:Limited fiber penetration in Tier-2 and Tier-3 cities constrains cloud-architecture adoption outside metropolitan zones.
Strategic Opportunities
- PLI Scheme Localization:Production-linked incentive thresholds for domestic value-add are creating qualification advantages for local assembly operations in government tenders.
- Edge AI Convergence:On-camera inference chips combined with behavioral analytics software open premium pricing tiers for real-time facial recognition deployments.
- Healthcare Biometric Integration:CDSCO oversight of patient data processing in hospital environments is driving demand for privacy-hardened analytics in pharmaceutical and clinical settings.
Industry Challenges
- AI/ML Engineering Talent Scarcity:Shortage of computer vision specialists limits domestic system integrators' ability to deploy and maintain behavioral analytics pipelines.
- Legacy Analog Migration Complexity:State police departments face integration friction when retrofitting coaxial infrastructure with hybrid IP-analog recording systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Video Surveillance Market |
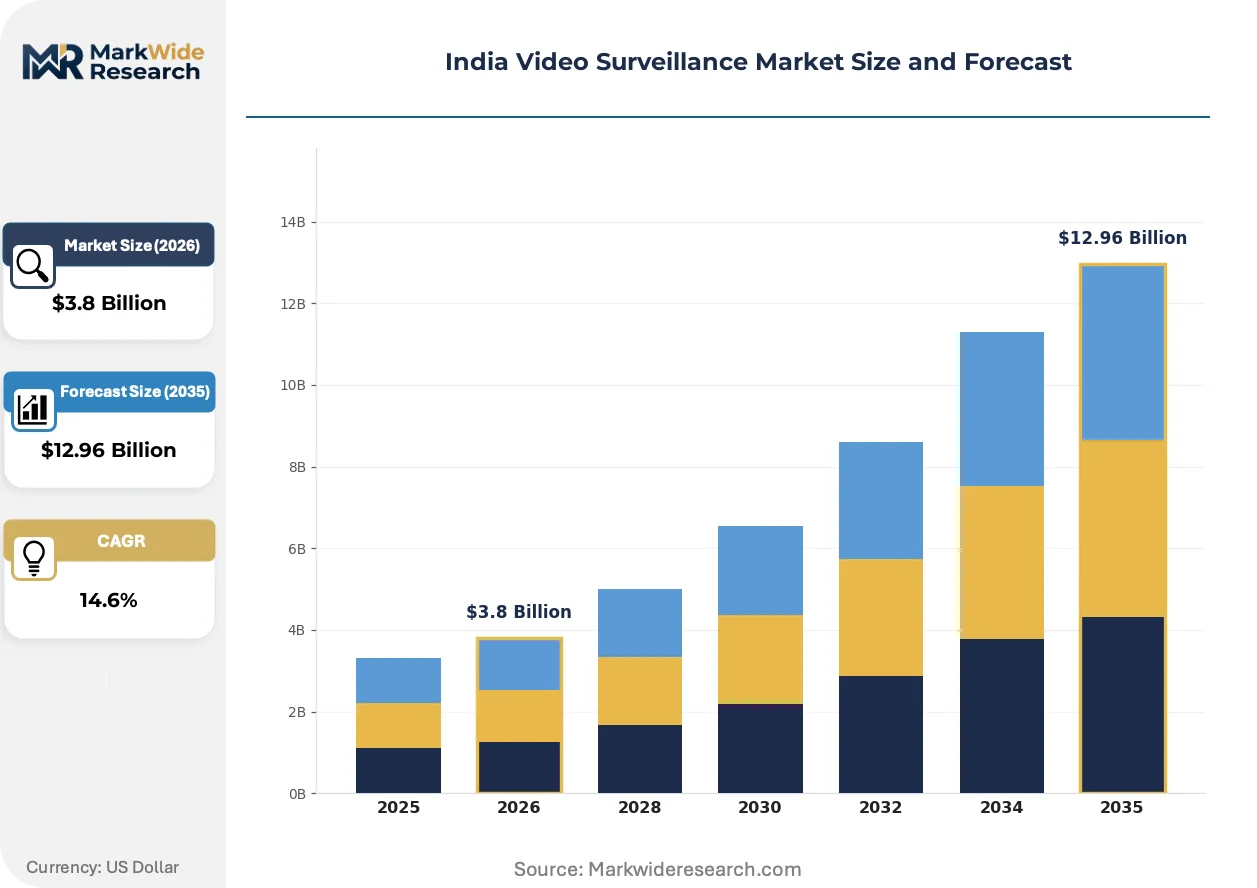
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IP Cameras, Analog Cameras, Video Recorders, Software Solutions End User: Retail, Transportation, Government, Banking Technology: Cloud-Based, On-Premises, Edge Computing, AI-Driven Analytics Installation Type: Indoor, Outdoor, CCTVs, Integrated Systems |
| Companies Covered | Axis Communications AB, Robert Bosch GmbH, Hangzhou Hikvision Digital Technology Co., Ltd., Godrej and Boyce Mfg. Co. Ltd., Panasonic Connect Co., Ltd., Zhejiang Dahua Technology Co., Ltd., Honeywell International Inc., Videonetics Technology Pvt. Ltd., CP Plus, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Video Surveillance Market Trends and Innovations
H.265 compression codecs and edge-based inference engines are reshaping hardware specifications as bandwidth efficiency becomes a decisive procurement criterion across government and commercial verticals.
Edge-based AI inference chips embedded directly into IP camera housings are displacing centralized server architectures for facial recognition workloads. Municipal police departments in Delhi and Mumbai are specifying on-camera processing to reduce backhaul bandwidth requirements. This displacement is compressing server hardware margins while elevating premium camera ASPs for AI-capable units.
BIS certification requirements for network-connected surveillance equipment are tightening electromagnetic compatibility and cybersecurity testing protocols. The Ministry of Home Affairs safe city guidelines now mandate encrypted firmware and audit logging capabilities as baseline compliance. Government tender qualification is increasingly contingent on demonstrated adherence to these standards, favoring suppliers with established certification pipelines.
State police departments are consolidating vendor relationships around system integrators capable of end-to-end deployment and 10-year maintenance contracts. This concentration is displacing fragmented procurement of cameras, storage, and software from separate suppliers. The shift is most visible in Karnataka and Tamil Nadu, where integrated command center projects bundle hardware, analytics licensing, and multi-year service agreements into single-tender awards.
India Video Surveillance Market Segmentation
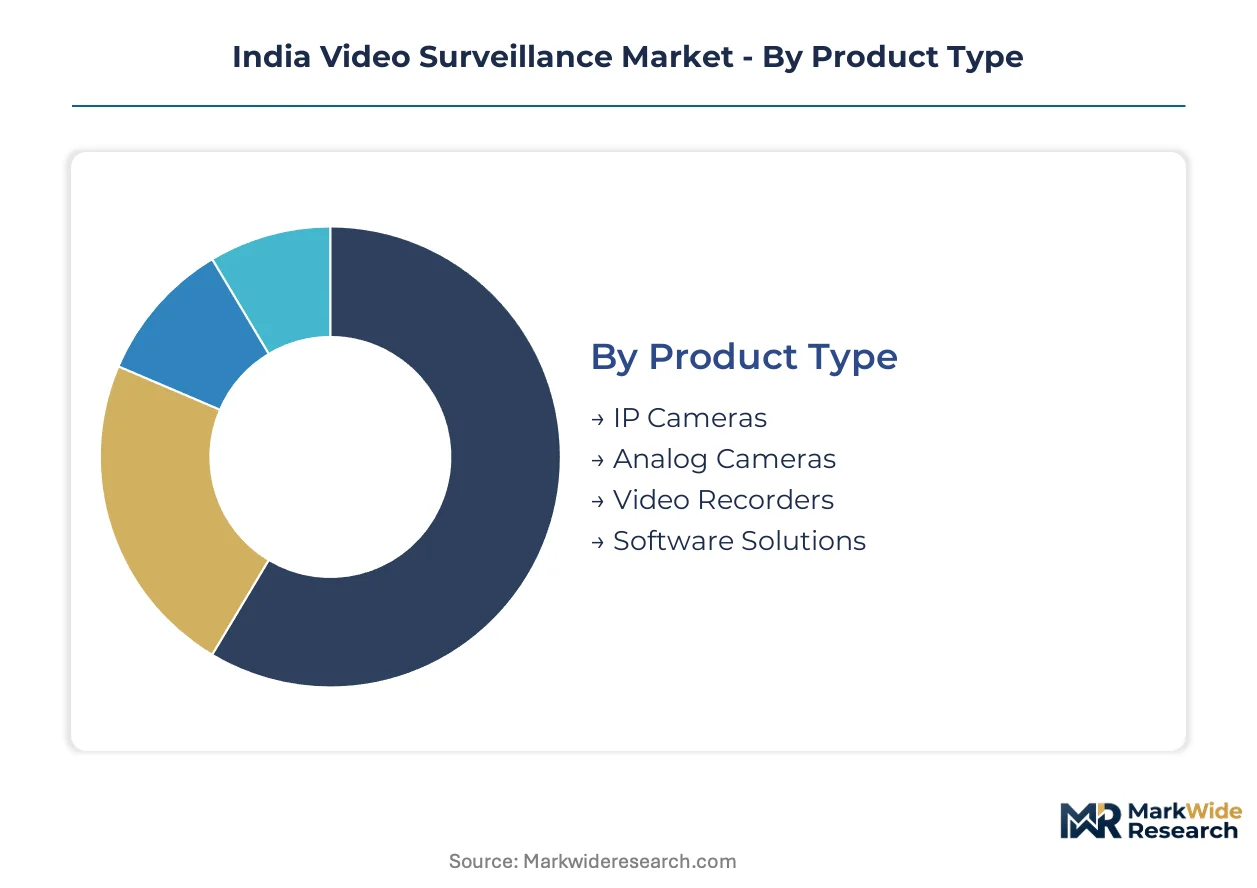
Segmentation reveals where procurement budgets concentrate across hardware, software, and service layers in India's surveillance modernization wave. Distinct margin profiles separate government tenders from commercial deployments, while technology choices determine long-term upgrade trajectories for integrators and end-users.
Product Type:
Margin pools concentrate in AI-capable hardware and recurring software licensing rather than commoditized recording infrastructure.
- IP Cameras:Network-connected units with CMOS sensors and H.265 compression now dominate municipal and banking procurement as analog estates age out. Delhi and Mumbai smart city projects specify 4K resolution with edge inference capabilities for facial recognition workloads.
- Software Solutions:Video management platforms and behavioral analytics engines command recurring license revenue from state police command centers. Karnataka and Tamil Nadu integrated control projects bundle multi-year software maintenance into single-tender awards.
- Analog Cameras:Coaxial-based legacy hardware persists in Tier-2 city retail estates where full IP migration remains capital-constrained.
- Video Recorders:NVR and DVR hardware faces margin compression as edge-based storage and cloud architectures displace centralized recording.
IP Cameras holds installed capacity. Software Solutions is rotating up the share rankings.
End User:
Volume concentration tilts toward state-funded verticals where procurement cycles extend across multi-year safe city mandates.
- Government:Ministry of Home Affairs funding for 100% transit corridor coverage drives the largest deployment scale. State police departments in Delhi, Mumbai, and Bangalore modernize command infrastructure with 10-year maintenance contracts.
- Banking:SEBI mandates extend camera density to ATM networks and branch perimeters across private and public sector banks. Compliance-driven refresh cycles create predictable replacement demand.
- Transportation:Metro rail authorities and airport operators specify cybersecurity-hardened firmware for critical infrastructure protection.
- Retail:Chain stores and malls adopt cloud architectures for centralized multi-site visibility, though Tier-2 expansion remains bandwidth-limited.
Government absorbs the dominant procurement volume. Banking maintains the steadiest replacement cadence.
Technology:
Adoption velocity separates metropolitan deployments from constrained Tier-2 rollouts based on fiber penetration and data sovereignty requirements.
- AI-Driven Analytics:Edge-based facial recognition and behavioral pattern detection command premium pricing from municipal police departments. Real-time threat detection capabilities compress procurement cycles away from passive recording.
- Edge Computing:On-camera inference chips displace centralized server architectures for bandwidth efficiency. Delhi and Mumbai police specifications increasingly mandate on-device processing.
- Cloud-Based:Centralized storage architectures gain traction in retail and transportation verticals seeking multi-site visibility, though limited fiber penetration constrains adoption outside metro zones.
- On-Premises:Legacy server-based storage persists in government estates with strict data localization requirements and air-gapped security protocols.
On-Premises retains legacy installed base. AI-Driven Analytics climbs the fastest among new deployment specifications.
Installation Type:
Specification complexity escalates with environmental exposure and integration depth into broader security ecosystems.
- Outdoor:Weather-resistant housings with thermal management and vandal-proofing dominate transit corridor and perimeter applications. BIS certification for electromagnetic compatibility adds qualification friction.
- Integrated Systems:Multi-sensor fusion with access control and alarm management commands highest project value in command center deployments. Karnataka and Tamil Nadu bundle hardware, analytics, and service into unified tenders.
- Indoor:Standard dome and bullet configurations serve retail, banking branch, and office environments with lower environmental hardening requirements.
- CCTVs:Legacy closed-circuit terminology persists in government documentation though IP infrastructure supersedes coaxial technology in new awards.
CCTVs represents legacy nomenclature. Integrated Systems is gaining specification share in large-scale tenders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CMOS sensor fabrication clusters in East Asia dominate upstream supply chains for Indian integrators. Domestic assembly operations concentrate in Maharashtra and Tamil Nadu where PLI scheme incentives attract component localization. State-level safe city mandates drive deployment velocity variation across sub-regions.
Maharashtra
Mumbai's smart city command center anchors western India's largest surveillance procurement. BIS certification requirements filter tender eligibility for network-connected equipment entering state police infrastructure. Pune's industrial corridor hosts domestic assembly operations competing on delivery timelines for government contracts.
Delhi-NCR
The national capital region absorbs the highest per-capita camera density from Ministry of Home Affairs safe city funding. SEBI mandates for banking security extend coverage requirements across ATM networks in Gurugram and Noida. Integrated command center specifications here mandate encrypted firmware as baseline compliance.
Karnataka
Bangalore's technology parks generate commercial demand for cybersecurity-hardened enterprise systems. State police modernization bundles hardware, analytics licensing, and decade-long maintenance into unified tender awards. The city's fiber backbone enables cloud-architecture adoption unavailable in Tier-2 districts.
Tamil Nadu
Chennai's port and airport authorities specify thermal imaging and perimeter detection for critical infrastructure. CDSCO oversight intersects where hospital surveillance processes biometric patient data. Domestic manufacturers leverage Chennai's electronics manufacturing cluster for localized final assembly.
Telangana
Hyderabad's metro rail authority embeds AI-integrated analytics into transit corridor monitoring. Limited fiber penetration outside the capital constrains cloud storage adoption in surrounding districts. State procurement favors integrators offering end-to-end deployment with multi-year service agreements.
India Video Surveillance Market Competitive Landscape
Concentration sits with diversified conglomerates and specialized security technology providers. The vendor base separates into three distinct tiers: multinational OEMs with certification pipelines, domestic assemblers competing on PLI qualification, and software specialists commanding analytics licensing revenue. Consolidation pressure intensifies as state police departments consolidate vendor relationships around integrated system providers. Strategic moves center on localizing manufacturing to meet domestic value-add thresholds and bundling decade-long maintenance into hardware tenders.
Among multinational OEMs, Hangzhou Hikvision Digital Technology Co., Ltd. and Axis Communications AB occupy positions at opposite ends of the pricing spectrum. Godrej and Boyce Mfg. Co. Ltd. anchors the domestic assembly tier with localized operations that compete on delivery timelines for safe city contracts. These three exemplify the archetype segmentation: scale-driven offshore supply, premium cybersecurity positioning, and PLI-qualifying domestic production respectively.
| Leading Market Players |
|---|
| Axis Communications AB |
| Robert Bosch GmbH |
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Godrej and Boyce Mfg. Co. Ltd. |
| Panasonic Connect Co., Ltd. |
| Zhejiang Dahua Technology Co., Ltd. |
| Honeywell International Inc. |
| Videonetics Technology Pvt. Ltd. |
| CP Plus |
| Others |
Pricing and Supply Chain Analysis
Decade-long maintenance contracts with embedded hardware refresh clauses lock in supply access for Indian system integrators while anchoring price visibility across tender cycles. BIS certification pipelines and PLI scheme localization thresholds reshape competitive positioning as domestic assemblers compete on delivery timelines against offshore scale suppliers.
Pricing Analysis
SEBI banking security directives dictate the pricing tier structure across financial services estates, with compliance-driven refresh cycles creating predictable replacement demand. Three-tier pricing structure across premium cybersecurity-hardened firmware, standard IP camera configurations, and economy analog legacy units separates enterprise clients from municipal procurement and Tier-2 retail estates. Cost compression in mid-range IP segments is intensifying because Hangzhou Hikvision leverages manufacturing scale for government tenders. State police departments exhibit lowest price sensitivity due to safe city mandate funding, while Tier-2 retail chains face capital constraints delaying full IP migration.
Supply Chain Analysis
Port congestion along the Nhava Sheva-Mundra corridor and container availability fluctuations on the Shenzhen-Chennai trade lane elevate inbound logistics costs for CMOS sensor-dependent integrators. Taiwan, South Korea, and Japan anchor upstream semiconductor supply for image sensors and edge inference chips. Domestic assembly draws from localized PCB fabrication, plastic housings, and power management components clustered in Maharashtra and Tamil Nadu. Single-source vulnerability concentrates in East Asian CMOS fabrication where geopolitical friction threatens input cost stability. Distribution runs through state-level system integrators bundling hardware, analytics licensing, and maintenance into unified tender awards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India video surveillance market functions as a defensive-moat industry where regulatory entrenchment through BIS certification and Ministry of Home Affairs safe city guidelines creates high barriers to tender eligibility. Switching costs escalate as state police departments consolidate around decade-long maintenance contracts with integrated system providers.
For Market Incumbents: Consolidate vendor relationships by acquiring regional system integrators with established certification pipelines and state police command center footprints. Deepen backward integration into edge AI chip assembly through PLI scheme qualification to defend margin position against offshore scale suppliers. The threat of cloud-architecture displacement by hyperscalers demands captive software development for video management platforms. For New Entrants and Emerging Players: Lead with cybersecurity-hardened firmware specialization targeting SEBI-mandated banking infrastructure where Axis Communications has established premium positioning. Healthcare biometric integration under CDSCO oversight represents the most penetrable white-space segment, with hospital surveillance processing patient data requiring privacy-hardened analytics. A direct enterprise sales model bypassing fragmented channel structures accelerates initial traction. For Investors and Strategic Acquirers: Domestic system integrators with decade-long state police maintenance contracts and demonstrated BIS certification throughput represent the highest-conviction acquisition archetype. Long-term viability hinges on localization depth meeting PLI scheme thresholds as procurement criteria tighten. The signal to watch is Ministry of Home Affairs tender specification shifts mandating encrypted firmware and audit logging capabilities as baseline compliance.| Strategic Initiative | Industry Significance |
|---|---|
| PLI Scheme Localization | Domestic value-add thresholds create qualification advantages for Maharashtra and Tamil Nadu assembly operations in government tenders. |
| Edge AI Chip Integration | On-camera inference capabilities command premium pricing from Delhi and Mumbai police departments reducing backhaul bandwidth requirements. |
| Cybersecurity Certification Pipeline | BIS electromagnetic compatibility and encrypted firmware testing protocols filter tender eligibility for network-connected surveillance equipment. |
| Healthcare Biometric Partnership | CDSCO oversight of patient data processing drives demand for privacy-hardened analytics in pharmaceutical and clinical facility deployments. |
| Integrated Command Center Bundling | Karnataka and Tamil Nadu state police consolidate hardware, analytics licensing, and decade-long maintenance into single-tender awards. |
Research Methodology
Desk research of customs trade data, BIS certification registries, and Ministry of Home Affairs tender documentation preceded structured interviews with state police procurement officers, system integrator project directors, and banking security compliance leads. Primary fieldwork with video management software developers and CMOS sensor distributors validated secondary findings on technology adoption trajectories. Bottom-up shipment analysis across IP camera, analog, and recorder categories triangulated against top-down safe city budget allocations from urban development authorities.
Variance decomposition across product type, end user vertical, technology architecture, and installation environment shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Edge AI inference chip penetration, cloud storage bandwidth availability in Tier-2 cities, and PLI scheme localization compliance curves served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained Ministry of Home Affairs funding commitments, stable East Asian semiconductor supply chains, or fiber penetration acceleration in secondary cities would require recalibration. Forecasts reflect documented assumptions on tender award velocity and certification pipeline throughput. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Asia-Pacific Surveillance Analog Camera Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Systems Market
Video Surveillance Systems
Mexico Surveillance Camera Market
Video Surveillance Systems
France Video Surveillance Market
Video Surveillance Systems
Night Vision System (NVS) Market
Video Surveillance Systems
Coastal Surveillance Systems Market
Video Surveillance Systems
Video Surveillance As a Service Market
Video Surveillance Systems
Wireless Security Camera Market
Video Surveillance Systems
Global CCTV Market
Video Surveillance Systems
Smart Security Camera Market
Video Surveillance Systems
France Surveillance Analog Camera Market
Video Surveillance Systems
China Surveillance Storage Market
Video Surveillance Systems
Latin America Surveillance Camera Market
Video Surveillance Systems
Latin America Surveillance IP Cameras Market
Video Surveillance Systems
India Surveillance IP Cameras Market
Video Surveillance Systems
Wireless Video Surveillance Market