
 China Surveillance Analog Camera Market | 2026-2036
China Surveillance Analog Camera Market Size, Share, and Industry Trends Forecast 2026-2036
China Surveillance Analog Camera Market Insights
Market Context
Shrinking pools of coaxial cable technicians is redrawing competitive dynamics across China's analog surveillance supply base. Hangzhou Hikvision Digital Technology Co Ltd leverages its vertical manufacturing footprint to sustain cost leadership in HD-TVI module production. Dahua Technology Co Ltd anchors its position through deep channel control across provincial distributor networks. Zhejiang Uniview Technologies Co Ltd competes by specializing in hybrid recorder solutions that bridge analog and digital architectures.
Technical Definition and Segment Structure
China surveillance analog cameras are imaging devices that encode video signals into analog waveforms for transmission over coaxial cable, typically operating at resolutions up to 1080p via HD-TVI or AHD modulation standards for real-time security monitoring in commercial and institutional settings. Dome cameras occupy the largest installed base among product types due to their vandal-resistant housing and discrete positioning in retail and banking environments. HD-TVI technology leads the technology dimension because of its backward compatibility with legacy CVBS infrastructure and lower per-channel retrofit costs. Outdoor installations command margin premiums driven by IP67 weatherproofing requirements and heater-blower assemblies for extreme temperature ranges.
Regulatory Framework and Outlook
MIIT enforces GB/T 28181 protocol standards for analog-to-network video gateway interoperability, while SAMR administers CCC certification mandates that constrain non-compliant import access. The central bank's security guidelines for financial institutions perpetuate analog recorder retention in secondary-branch networks. Stakeholders must monitor MIIT's timeline for potential GB standard revisions that could accelerate or delay hybrid system phase-out mandates.
Market Dynamics
Shrinking pools of coaxial cable technicians are redrawing competitive dynamics across China's analog surveillance supply base. Municipal procurement offices in tier-two cities now face extended installation timelines and rising service premiums as the skilled workforce ages out without replacement pipelines.
Growth Catalysts
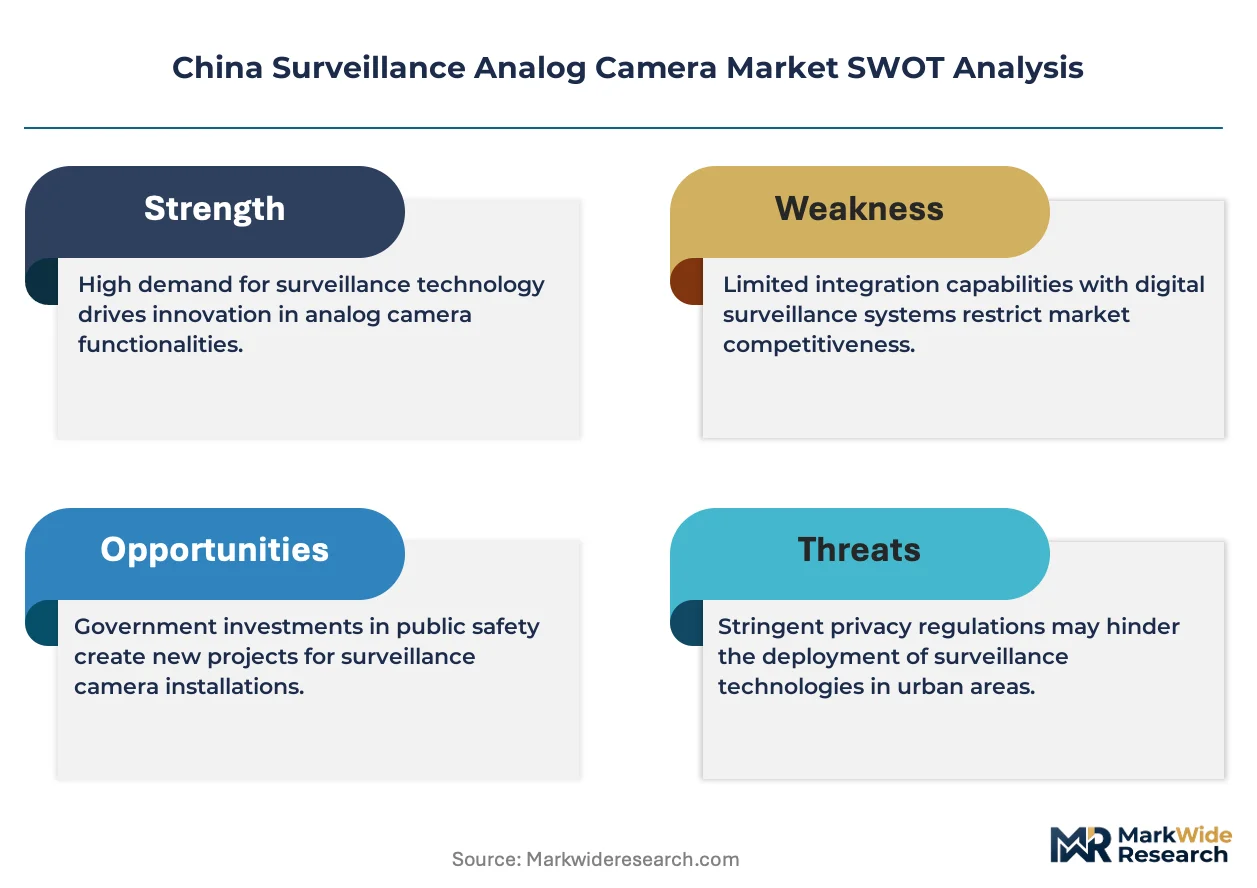
- MIIT GB/T Standards:The ministry's analog-over-coax compatibility protocols preserve interoperability across generations of installed base equipment, protecting sunk capital investments and sustaining replacement demand.
- Public Transit Infrastructure:Municipal authorities in tier-two cities prioritize cost-efficient security upgrades over full IP migration, maintaining steady procurement volumes for legacy-compatible systems.
- Central China Replacement Cycles:Aging surveillance networks in Hubei and Henan provinces face phased replacement timelines, concentrating demand in provinces with the largest installed base depreciation.
Market Restraints
- Coaxial Cable Technician Scarcity:Training pipeline collapse for legacy installation skills extends project timelines and inflates labor costs beyond budgeted parameters.
- IP Camera Substitution:Declining unit costs for network surveillance equipment erode the total-cost-of-ownership advantage that analog systems traditionally held in budget-constrained segments.
- SAMR CCC Certification Friction:Import compliance mandates constrain non-certified equipment access, limiting supplier diversification and extending procurement lead times for specialized components.
Strategic Opportunities
- Hybrid Recorder Architecture:Bridge solutions that simultaneously process analog and digital signals capture upgrade-cycle demand from facilities pursuing phased rather than wholesale infrastructure replacement.
- Secondary Financial Branch Networks:The central bank's security guidelines perpetuate analog recorder retention in peripheral banking locations, creating a protected demand pocket resistant to full digital migration.
- Heater-Blower Assembly Specialization:Outdoor installations with IP67 weatherproofing and thermal management components command margin premiums in extreme-climate western provinces.
Industry Challenges
- CVBS-to-HD-TVI Signal Interoperability:Field technicians struggle with backward compatibility troubleshooting across mixed-generation infrastructure, elevating service call frequency and customer churn risk.
- GB Standard Revision Uncertainty:Stakeholders face planning paralysis pending MIIT timeline clarity for potential hybrid system phase-out mandates that would accelerate obsolescence schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Surveillance Analog Camera Market |
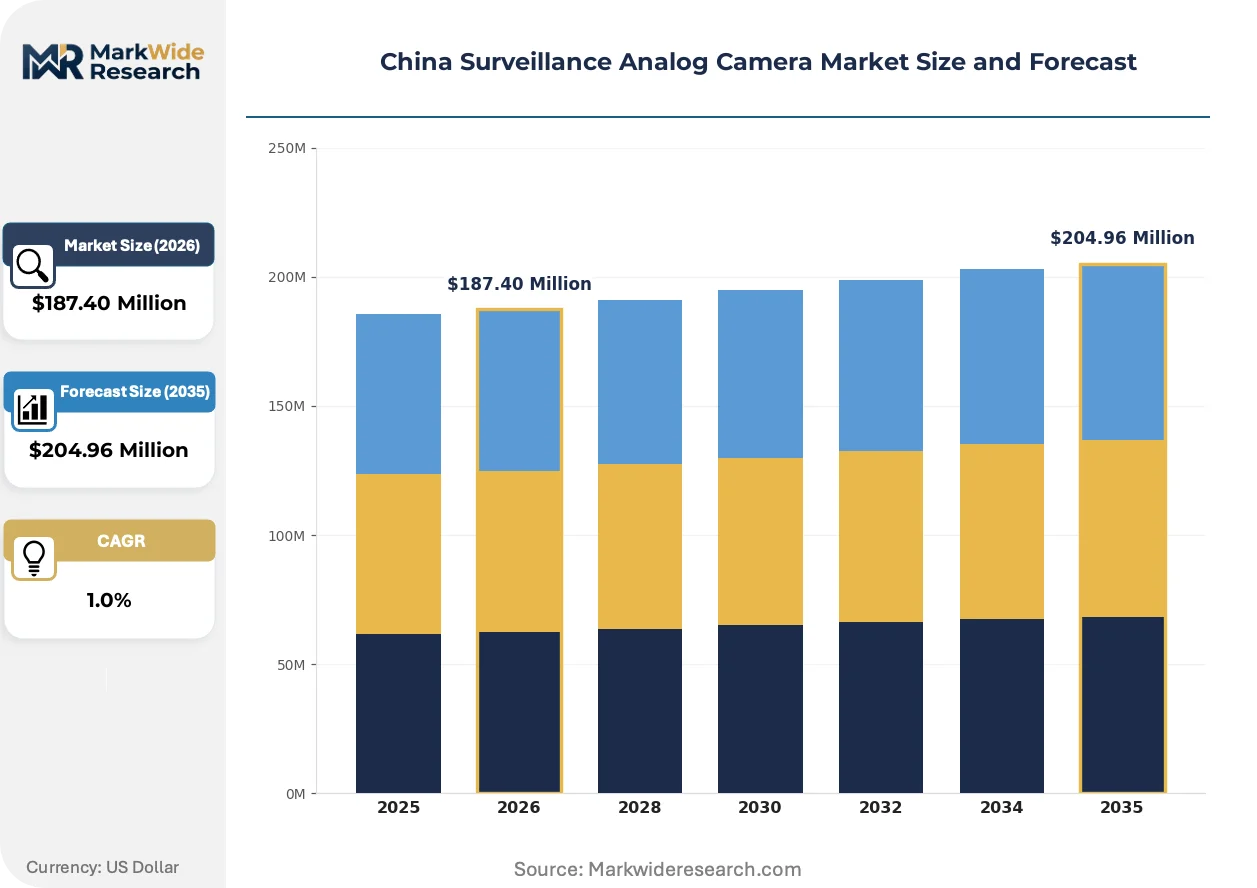
| Market Size in 2026 | $187.40 Million |
| Market Size in 2035 | $204.96 Million |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Box Camera, Dome Camera, Bullet Camera, PTZ Camera Technology: HD-TVI, HD-CVI, AHD, CVBS End User: Retail, Banking, Transportation, Education Installation: Indoor, Outdoor, Ceiling Mounted, Wall Mounted |
| Companies Covered | Hangzhou Hikvision Digital Technology Co Ltd, Dahua Technology Co Ltd, Zhejiang Uniview Technologies Co Ltd, Shenzhen Sunell Technology Corporation, Zhuhai RaySharp Technology Co Ltd, Shenzhen TVT Digital Technology Co Ltd, JER TECHNOLOGY CO LTD, Shenzhen MVTEAM Technology Co Ltd, Shenzhen LOYALTY-SECU Technology Co LTD, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Surveillance Analog Camera Market Trends and Innovations
Component miniaturization and signal processing advances are compressing form factors while extending functional lifespans of analog surveillance equipment. These technical trajectories intersect with procurement recalibrations as municipal buyers reassess total-cost methodologies.
HD-TVI chipset architecture is miniaturizing through die-shrink processes that integrate analog-to-digital conversion onto single-package solutions. Dome camera manufacturers in Zhejiang province are adopting these consolidated modules to reduce PCB footprint by approximately forty percent. The density gains enable vandal-resistant housings with expanded internal space for thermal management components.
MIIT's enforcement of GB/T 28181 protocol standards for analog-to-network video gateway interoperability is mandating uniform translation layers across manufacturer ecosystems. Industrial consequence includes accelerated R&D allocation toward software-defined bridge functionality rather than proprietary hardware lock-in. Provincial distributor networks are responding by certifying technical staff on multi-vendor gateway configuration to capture service revenue from compliance-driven upgrades.
Municipal procurement offices are consolidating vendor relationships and demanding extended warranty terms that bundle installation with decade-long maintenance coverage. Provincial security integrators are displacing traditional equipment resellers as the primary channel interface, capturing margin through lifecycle service contracts. This concentration pattern is most visible in Henan province where municipal budget offices have standardized on single-source framework agreements.
China Surveillance Analog Camera Market Segmentation
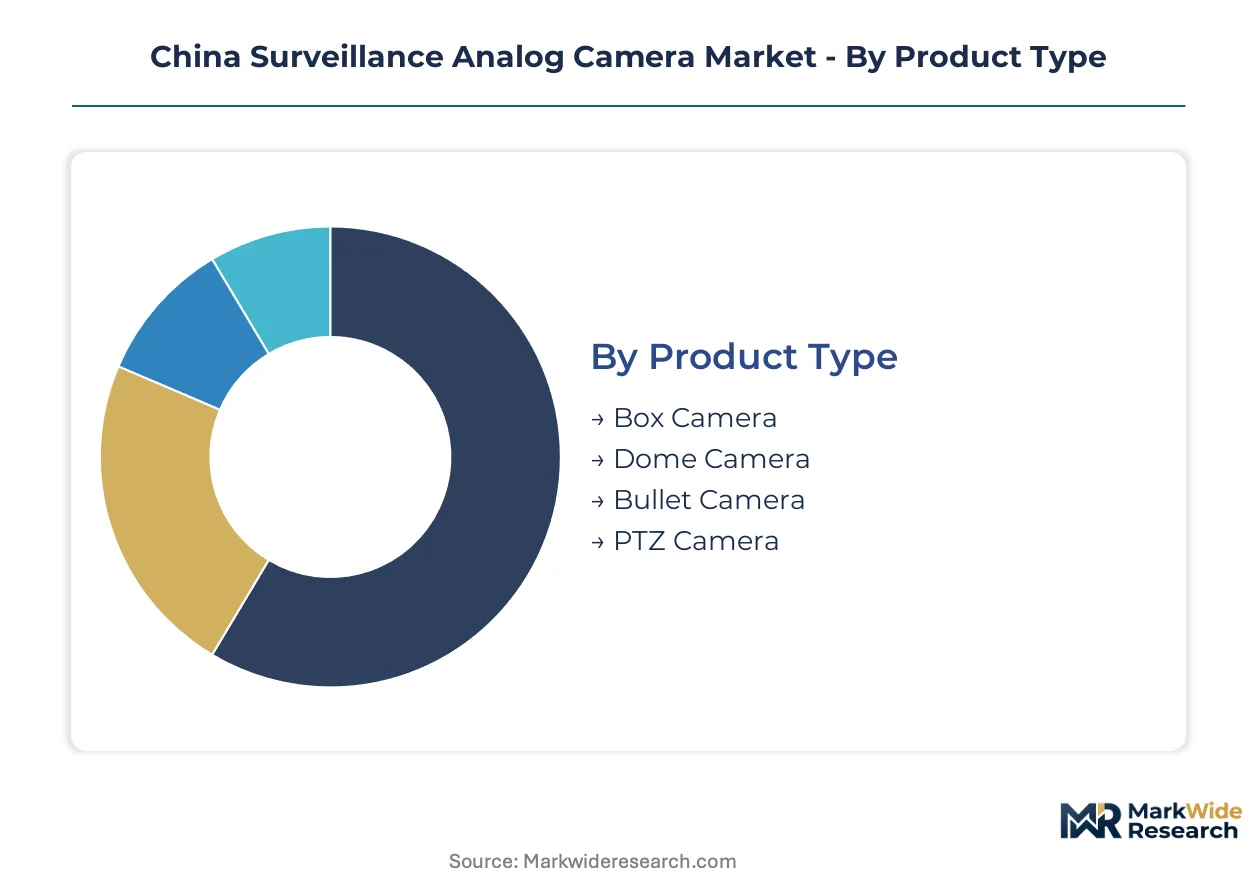
Analog surveillance procurement in China fragments across product architecture, signal modulation, institutional end-use, and mounting topology. Municipal buyers and provincial integrators navigate these dimensions through divergent channel pathways that shape margin capture and replacement cycle timing.
Product Type:
Distributor networks in Henan and Hubei provinces push dome and bullet variants through security integrators, while box cameras flow direct to industrial facilities and PTZ units require specialized vertical channels.
- Dome Camera:Vandal-resistant housings with discrete positioning profiles dominate banking and retail deployments. Demand concentrates in tier-two city commercial districts where discrete aesthetics and physical durability outweigh retrofit complexity.
- Bullet Camera:Weather-sealed cylindrical housings with fixed or varifocal lenses serve perimeter and corridor monitoring. Municipal procurement in central China replacement cycles favors these units for outdoor infrastructure refresh programs.
- Box Camera:Modular lens-interchangeable bodies for customizable field-of-view applications.
- PTZ Camera:Motorized pan-tilt-zoom mechanisms for active surveillance zones requiring operator control.
Dome cameras dominate installed base. Bullet cameras are where expansion concentrates.
Technology:
Cost tiers separate legacy CVBS infrastructure from HD-TVI and HD-CVI upgrade paths, with AHD occupying a narrow mid-band position for budget-constrained municipal buyers.
- HD-TVI:High-definition transport video interface modulates uncompressed digital signals over coaxial cable with backward CVBS compatibility. Central China provincial distributors stock HD-TVI modules most heavily due to MIIT GB/T interoperability mandates and lowest per-channel retrofit costs.
- AHD:Analog high-definition protocol offers open-source chipset availability reducing module procurement premiums. Smaller municipal buyers in tier-three cities select AHD for standalone installations where multi-vendor interoperability matters less than unit economics.
- HD-CVI:Dahua-developed high-definition composite video interface with proprietary transmission protocols.
- CVBS:Legacy composite video baseband signal standard for first-generation analog infrastructure.
HD-TVI dominates installed base. AHD is where expansion concentrates.
End User:
Application-specific procurement patterns concentrate volume in transportation and banking verticals, with retail and education exhibiting fragmented demand across regional distributor tiers.
- Transportation:Public transit authorities in tier-two cities sustain replacement demand for legacy-compatible recording infrastructure. Hubei and Henan municipal budgets prioritize cost-efficient security upgrades over full IP migration, preserving analog procurement flows.
- Banking:Central bank security guidelines perpetuate analog recorder retention in secondary-branch networks. Peripheral locations in western provinces maintain protected demand resistant to digital migration timelines.
- Retail:Discrete dome deployments in commercial storefronts and shopping corridors.
- Education:Campus perimeter and building access monitoring in budget-constrained institutional settings.
Transportation dominates installed base. Banking is where expansion concentrates.
Installation:
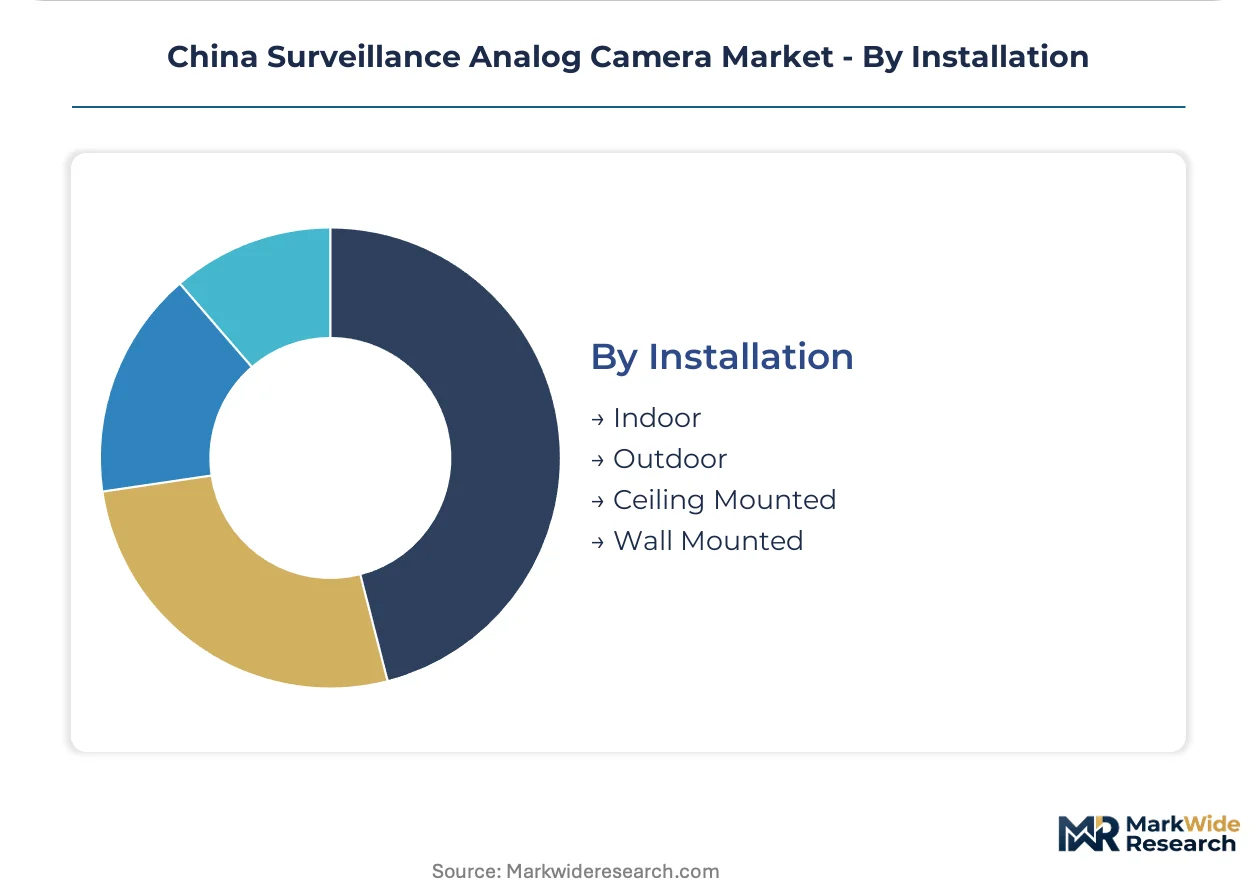
Margin structures diverge sharply between indoor and outdoor specifications, with ceiling and wall mounting configurations determining labor skill requirements and channel service capture.
- Outdoor:IP67 weatherproofing and heater-blower assemblies for extreme temperature ranges command margin premiums. Western provinces with continental climate patterns drive specification intensity for thermal management components.
- Indoor:Standard environmental protection for controlled-climate commercial and institutional interiors.
- Ceiling Mounted:Recessed and surface-mount dome configurations for discrete overhead positioning.
- Wall Mounted:Bullet and box camera bracketing for vertical surface attachment.
Outdoor dominates installed base. Ceiling mounted is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Central China provinces consume analog surveillance equipment through phased municipal replacement programs, while coastal manufacturing clusters supply components through vertically integrated production networks that differ sharply from inland procurement patterns.
Hubei Province
Wuhan municipal transit authorities drive replacement demand for legacy-compatible dome and bullet cameras across bus depots and rail stations. MIIT GB/T interoperability standards guide procurement specifications for analog-over-coax infrastructure refreshes. Provincial security integrators in Wuhan consolidate vendor relationships through single-source framework agreements bundling installation with decade-long maintenance coverage.
Henan Province
Zhengzhou municipal budget offices prioritize cost-efficient security upgrades over full IP migration in aging surveillance networks. SAMR CCC certification mandates constrain equipment sourcing to compliant domestic manufacturers. Regional distributor networks in Luoyang and Kaifeng capture margin through lifecycle service contracts displacing traditional equipment resellers.
Guangdong Province
Shenzhen manufacturing clusters produce HD-TVI chipset modules through die-shrink processes integrating analog-to-digital conversion onto single-package solutions. MIIT enforcement of GB/T 28181 protocol standards accelerates R&D allocation toward software-defined bridge functionality. Component suppliers in Zhuhai and Dongguan reduce PCB footprint by approximately forty percent through consolidated module adoption.
Zhejiang Province
Hangzhou-based manufacturers leverage vertical manufacturing footprints to sustain cost leadership in HD-TVI module production for dome camera housings. Provincial distributor networks anchor market position through deep channel control across municipal procurement offices. Manufacturers in Ningbo and Wenzhou adopt vandal-resistant housings with expanded internal space for thermal management components.
Western Provinces
Sichuan and Chongqing municipal authorities specify IP67 weatherproofing and heater-blower assemblies for extreme temperature ranges in outdoor installations. Central bank security guidelines perpetuate analog recorder retention in secondary-branch banking networks across peripheral locations. Security integrators in Chengdu capture margin premiums through specialized outdoor specification expertise.
China Surveillance Analog Camera Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in China's analog surveillance supply base. Hangzhou Hikvision Digital Technology Co Ltd and Dahua Technology Co Ltd occupy positions of scale advantage through captive manufacturing and channel density. Three strategic archetypes define competitive positioning: vertically integrated module producers, hybrid recorder specialists, and regional channel consolidators. Dominant competitive moves include backward integration into chipset fabrication and geographic expansion through provincial distributor acquisition.
Among Zhejiang-based manufacturers, Hangzhou Hikvision Digital Technology Co Ltd exemplifies the integrated leader archetype through its manufacturing footprint and channel reach. Dahua Technology Co Ltd anchors the specialist tier with proprietary transmission protocol development. Zhejiang Uniview Technologies Co Ltd occupies a position bridging analog and digital architectures through hybrid solution specialization.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co Ltd |
| Dahua Technology Co Ltd |
| Zhejiang Uniview Technologies Co Ltd |
| Shenzhen Sunell Technology Corporation |
| Zhuhai RaySharp Technology Co Ltd |
| Shenzhen TVT Digital Technology Co Ltd |
| JER TECHNOLOGY CO LTD |
| Shenzhen MVTEAM Technology Co Ltd |
| Shenzhen LOYALTY-SECU Technology Co LTD |
| Others |
Pricing and Supply Chain Analysis
MIIT GB/T certification tiers gate supplier qualification while simultaneously stratifying price bands across China's analog surveillance market. Municipal procurement offices face extended vendor onboarding timelines as SAMR CCC mandates filter non-compliant imports, compressing competitive supply pools and amplifying pricing power for certified domestic manufacturers.
Pricing Analysis
Long-term framework agreements dominate municipal procurement, with spot purchasing limited to emergency replacement scenarios. Three-tier pricing structure across premium, standard, and economy levels separates IP67 outdoor assemblies with heater-blower components from indoor dome variants and bare-module CVBS legacy units. Cost compression in standard-tier HD-TVI modules is intensifying because die-shrink consolidation reduces chipset procurement premiums. Tier-three city transit authorities exhibit highest price sensitivity, while central bank-mandated banking networks accept premium positioning for compliance-guaranteed supply security.
Supply Chain Analysis
Inventory cycles stretch to twelve-to-eighteen weeks for HD-TVI chipset modules as die-shrink fabrication concentrates in Zhejiang and Guangdong manufacturing clusters. Supply draws from coaxial cable stockpiles, metal-alloy housing materials, and analog-to-digital conversion semiconductors. Single-source vulnerability persists for proprietary HD-CVI protocol components controlled by one dominant manufacturer. Distribution runs through provincial security integrators who displace traditional equipment resellers by bundling installation with decade-long maintenance coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics reshape competitive positioning as MIIT GB/T 28181 interoperability mandates force hardware-agnostic bridge architectures, transforming proprietary lock-in into software-defined gateway competition.
For Market Incumbents: Secure backward integration into HD-TVI chipset fabrication to defend against die-shrink cost compression eroding module margins. Deepen channel control across Hubei and Henan provincial distributor networks before hybrid recorder specialists capture replacement-cycle demand. Monitor AHD open-source protocol encroachment in tier-three municipal segments. For New Entrants and Emerging Players: Anchor in secondary financial branch networks where central bank security guidelines perpetuate analog recorder retention resistant to IP migration timelines. Target western provinces with extreme-climate outdoor specifications where heater-blower assembly specialization commands margin premiums unavailable to commoditized indoor competitors. Pursue SAMR CCC certification early to bypass procurement disqualification. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate electronics divisions with dormant analog surveillance portfolios but intact GB/T certification heritage. Five-to-ten year viability hinges on hybrid architecture persistence rather than pure-play analog exposure. Signal to watch: MIIT timeline clarity for potential hybrid system phase-out mandates that would accelerate obsolescence schedules and compress exit windows.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Recorder Architecture Development | Captures phased upgrade demand from facilities avoiding wholesale infrastructure replacement across central China provinces. |
| Backward Integration into Chipset Fabrication | Secures cost leadership in HD-TVI module production against die-shrink consolidation pressures from Zhejiang competitors. |
| Provincial Distributor Network Acquisition | Consolidates channel control in Henan and Hubei where municipal framework agreements favor single-source lifecycle contracts. |
| SAMR CCC Certification Investment | Unlocks procurement access to tier-two city transit authorities constrained by import compliance mandates. |
| Heater-Blower Assembly Specialization | Captures margin premiums in Sichuan and Chongqing outdoor installations with IP67 weatherproofing requirements. |
Research Methodology
Cross-validation between provincial distributor interviews and MIIT regulatory filings anchors the qualitative findings in documented compliance timelines. Primary fieldwork encompassed security integrators in Wuhan and Zhengzhou, municipal procurement officers in tier-two transit authorities, and technical directors at Hangzhou and Shenzhen manufacturing clusters. Secondary sources included GB/T standard revision drafts, SAMR CCC certification registries, and central bank security guideline circulars. Bottom-up shipment estimates from provincial distributor networks were triangulated against top-down municipal budget allocation data.
Sensitivity analysis tested forecast robustness across alternative GB/T phase-out timeline scenarios and varying technician shortage severity assumptions. Segmentation modeling spanned product architecture, signal modulation protocol, institutional end-use vertical, and mounting topology dimensions across the projection horizon. CAGRs were derived from replacement cycle timing in Hubei and Henan aging installed bases, cross-referenced with municipal budget constraint indicators. Industry-specific inputs included coaxial cable technician pipeline collapse rates and HD-TVI chipset die-shrink adoption curves.
Decision-makers should treat outputs as directional under base assumptions of sustained MIIT interoperability mandates and gradual IP substitution; material deviation in regulatory timeline acceleration would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Japan Surveillance Analog Camera Market
Video Surveillance Systems
City Surveillance Market
Video Surveillance Systems
Wireless Video Surveillance Market
Video Surveillance Systems
Global Night Vision System and Driver Monitoring System Market
Video Surveillance Systems
Japan Surveillance Storage Market
Video Surveillance Systems
Brazil Surveillance Camera Market
Video Surveillance Systems
Video Surveillance Market
Video Surveillance Systems
Home Security Camera Market
Video Surveillance Systems
North America Surveillance IP Camera Market
Video Surveillance Systems
Night Vision (IR) Surveillance Cameras Market
Video Surveillance Systems
United Arab Emirates Surveillance Camera Market
Video Surveillance Systems
Farm Video Surveillance System Market
Video Surveillance Systems
Crawler Camera System Market
Video Surveillance Systems
AI in Video Surveillance Market
Video Surveillance Systems
US Video Surveillance Market
Video Surveillance Systems
Global Mobile Video Surveillance Market