
 Asia-Pacific Video Surveillance Systems Market | 2026-2036
Asia-Pacific Video Surveillance Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Video Surveillance Systems Market Outlook
The Asia-Pacific video surveillance landscape is consolidating around a sharp split between premium AI-analytics platforms and commoditized hardware. Hangzhou Hikvision Digital Technology Co., Ltd. leverages its integrated sensor-to-cloud stack to dominate high-margin enterprise contracts across Chinese smart city deployments. Zhejiang Dahua Technology Co., Ltd. anchors its position through deep backward integration into chipset design and domestic manufacturing scale. Hanwha Vision Co., Ltd. differentiates via Wisenet AI firmware and ethical AI certifications that unlock sensitive government verticals in South Korea and Australia.
Asia-Pacific video surveillance systems encompass networked camera arrays, digital video recorders, display monitors, and analytics software engineered for resolutions from 2MP to 8K with edge-computing inference capabilities. These systems serve commercial security, traffic management, and critical infrastructure protection through real-time object detection and forensic search. IP technology leads value capture as organizations retire coaxial analog infrastructure, while cloud-based architectures represent the fastest-expanding deployment model by offloading storage and analytics to distributed data centers. The software segment commands disproportionate margin pools through recurring license models for facial recognition and behavior analytics.
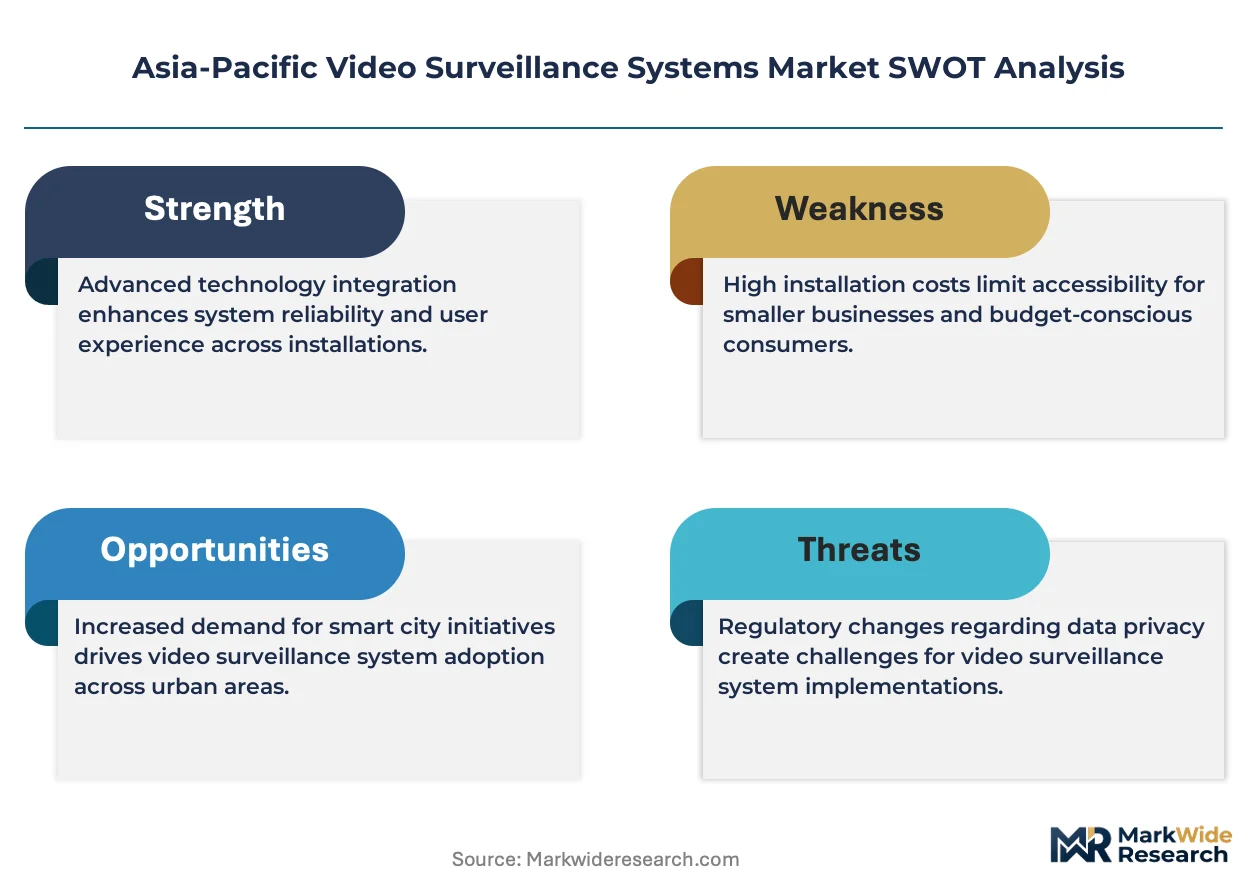
China's MIIT enforces GB/T 28181 interoperability standards and cybersecurity review for networked surveillance products, while India's BIS mandates ISI certification for electronic security equipment sold to government buyers. Australia's TGA-equivalent communications regulator and South Korea's MFDS-aligned data protection frameworks add compliance layers for biometric data handling. Stakeholders must weigh localization requirements against cloud architecture investments as fragmentation between national data sovereignty regimes intensifies.
Market Dynamics
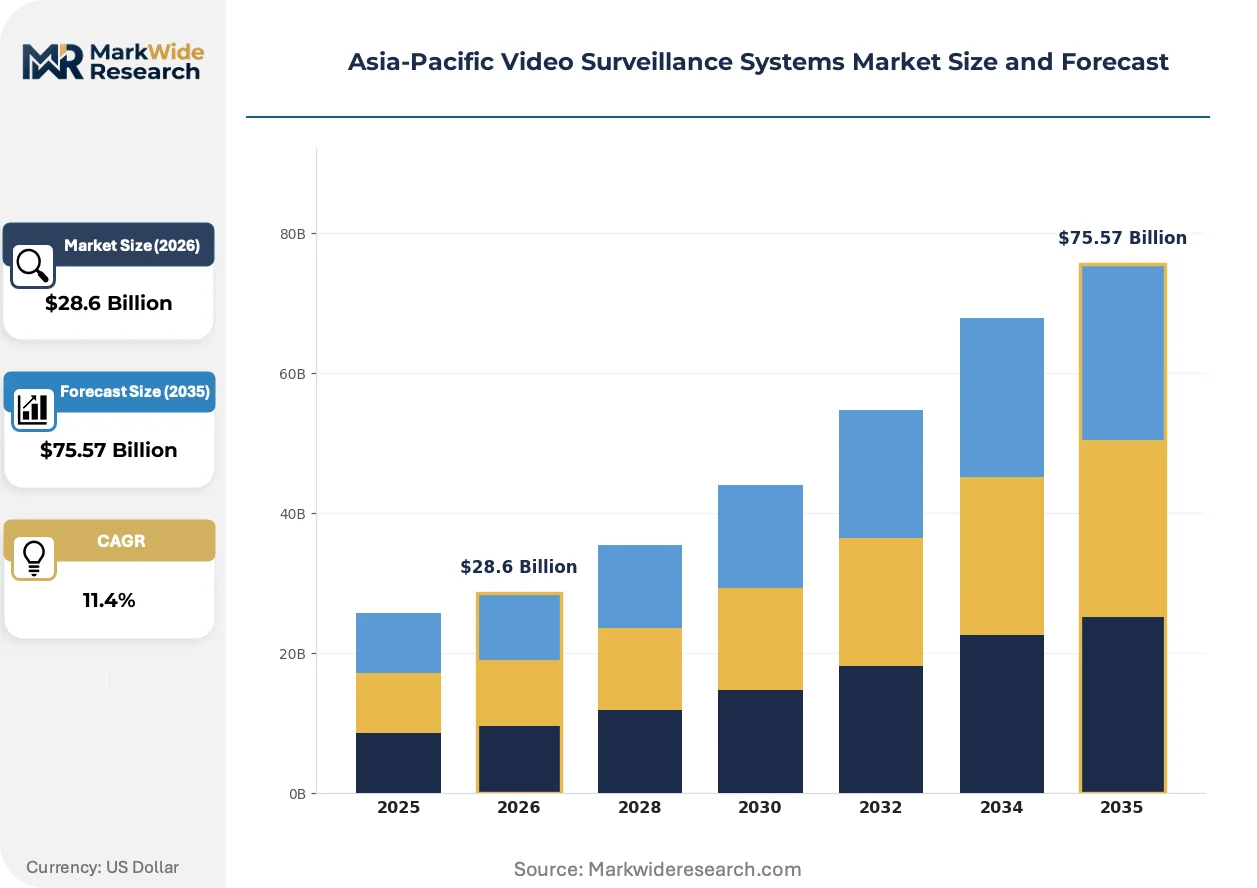
The Asia-Pacific video surveillance market is restructuring around the forced retirement of analog coaxial infrastructure, with IP-based platforms capturing procurement budgets across municipal, commercial, and industrial buyers.
Growth Catalysts
- India's Smart Cities Mission:Municipal governments in Mumbai, Delhi, and Bangalore are mandating networked camera installations for traffic management and public safety, creating sustained procurement pipelines through 2035.
- GB/T 28181 interoperability standards:China's MIIT enforcement of unified protocols is accelerating system-wide upgrades as legacy equipment loses certification eligibility for government contracts.
- Edge AI chipsets:On-camera inference engines for real-time facial recognition and anomaly detection are displacing centralized server architectures in bandwidth-constrained deployments across Southeast Asian archipelagos.
Market Restraints
- CMOS sensor supply concentration:Taiwan and South Korean foundries control advanced image sensor fabrication, exposing downstream integrators to allocation risk during semiconductor cycle tightness.
- Biometric data localization mandates:Australia's privacy regulator and South Korea's MFDS-aligned frameworks require domestic storage for facial recognition templates, fragmenting cloud architecture economics.
- Silicon carbide power component costs:Advanced thermal management for outdoor 8K cameras depends on wide-bandgap semiconductors priced at multiples of conventional alternatives.
Strategic Opportunities
- Vietnam and Indonesia smart city builds:Ho Chi Minh City and Jakarta are greenfield procurement markets where first-mover integrators can establish platform standards before legacy lock-in solidifies.
- Cloud-managed video-as-a-service:Subscription models for remote monitoring are penetrating mid-market retail chains that previously deferred capital expenditure on on-premise DVR infrastructure.
- PLI scheme incentives:India's production-linked incentive program for electronics manufacturing is attracting component assembly investments that reduce landed costs for domestic system integrators.
Industry Challenges
- IPv6 migration complexity:Legacy analog-to-IP bridge deployments require specialized network engineering talent scarce in secondary Indian and Southeast Asian cities.
- ISI certification timelines:India's BIS laboratory testing backlog for electronic security equipment extends product launch schedules by six to nine months for imported camera systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Video Surveillance Systems Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cameras, Recorders, Monitors, Software End User: Retail, Transportation, Government, Education Technology: IP, Analog, Wireless, Cloud-Based Installation Type: Indoor, Outdoor, Hybrid, Integrated |
| Companies Covered | Hangzhou Hikvision Digital Technology Co., Ltd., Zhejiang Dahua Technology Co., Ltd., Hanwha Vision Co., Ltd., Zhejiang Uniview Technologies Co., Ltd., VIVOTEK Inc., Huawei Technologies Co., Ltd., Panasonic Holdings Corporation, Honeywell International Inc., Motorola Solutions, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Video Surveillance Systems Market Strategic Shifts
Video surveillance architecture is pivoting from storage-centric to intelligence-centric designs, with compute migration toward the network edge compressing traditional hardware value chains.
Multi-spectral imaging is converging with thermal fusion analytics to enable detection through occlusion, fog, and low-light conditions. Critical infrastructure operators in Australia's mining and energy corridors are deploying these systems for perimeter breach detection. The technology is converging with radar-based verification to reduce false alarm rates that previously undermined operator trust in automated alerts.
China's GB standards for cybersecurity review of networked surveillance products are tightening firmware signing requirements and supply chain disclosure obligations. Equipment vendors must now document component provenance through three tiers of subassembly. This regulatory pressure is compressing margins for white-label manufacturers while rewarding integrated producers with captive chipset design capabilities.
Buyers are unbundling hardware procurement from software licensing and maintenance contracts. Large municipal authorities in South Korea and Australia are separating camera purchases from analytics platform selection, enabling multi-vendor environments. This pattern is most visible in transportation verticals where legacy analog-era integrators previously captured full-stack contracts.
Asia-Pacific Video Surveillance Systems Market Segmentation
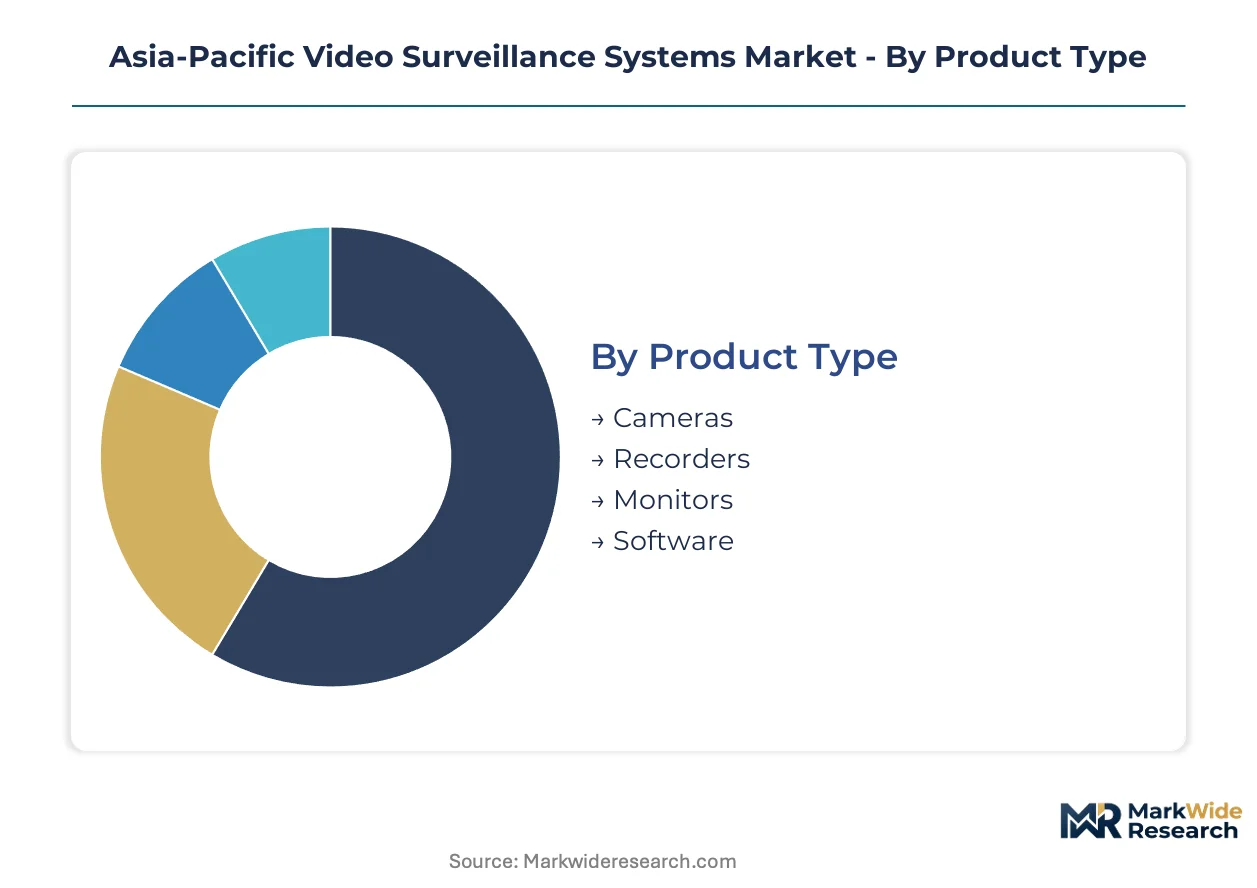
Segmentation reveals how procurement patterns diverge across the Asia-Pacific video surveillance landscape. Municipal buyers prioritize interoperability compliance while commercial operators weigh total cost of ownership against analytics depth.
Product Type:
Replacement cycles vary sharply by product category, with legacy analog equipment forcing synchronized upgrades across entire system architectures.
- Cameras:Networked units with edge AI inference engines dominate new installations across Chinese smart city corridors. Indian municipal authorities in Mumbai and Delhi are retiring coaxial dome cameras for IP-based 4K units with onboard facial recognition.
- Software:License-based analytics platforms for behavior detection and forensic search command recurring revenue streams. South Korean government verticals specify ethical AI certifications that restrict vendor pools to certified developers.
- Recorders:Hybrid NVR units bridge analog legacy and IP infrastructure during transitional deployments.
- Monitors:Display systems consolidate feeds from distributed camera arrays in traffic management centers.
Cameras sits at the top of the volume ranking, with Software climbing the fastest.
End User:
Cost tier differentiation separates budget-constrained municipal buyers from premium-allocated critical infrastructure operators.
- Government:National security and smart city mandates drive procurement of GB/T 28181-certified systems with domestic data storage. China's MIIT cybersecurity reviews restrict vendor selection to manufacturers with documented supply chain provenance.
- Transportation:Airports and metro authorities in Singapore and Sydney deploy multi-spectral fusion systems for perimeter breach detection through occlusion and low-light conditions.
- Retail:Mid-market chains adopt cloud-managed video-as-a-service to defer capital expenditure on on-premise infrastructure.
- Education:Campus security budgets prioritize corridor monitoring with privacy-compliant analytics that mask identifiable features in storage.
Government captures the largest budget allocation, with Transportation expanding most quickly.
Technology:
Application requirements dictate architecture selection, with bandwidth constraints and data sovereignty rules fragmenting deployment patterns.
- IP:Ethernet-based transmission enables centralized management and software-defined analytics upgrades. Southeast Asian archipelagos favor IP architectures with edge inference to reduce backhaul dependency.
- Cloud-Based:Distributed storage and processing offload capital burdens to operational budgets for retail and education verticals. Australia's privacy regulator mandates domestic data residency for biometric templates, complicating multi-tenant cloud economics.
- Wireless:Cellular and mesh networks serve temporary deployments and retrofit scenarios where cabling is impractical.
- Analog:Coaxial systems persist in legacy industrial sites with deferred maintenance cycles.
IP holds the installed base lead, with Cloud-Based gaining share fastest.
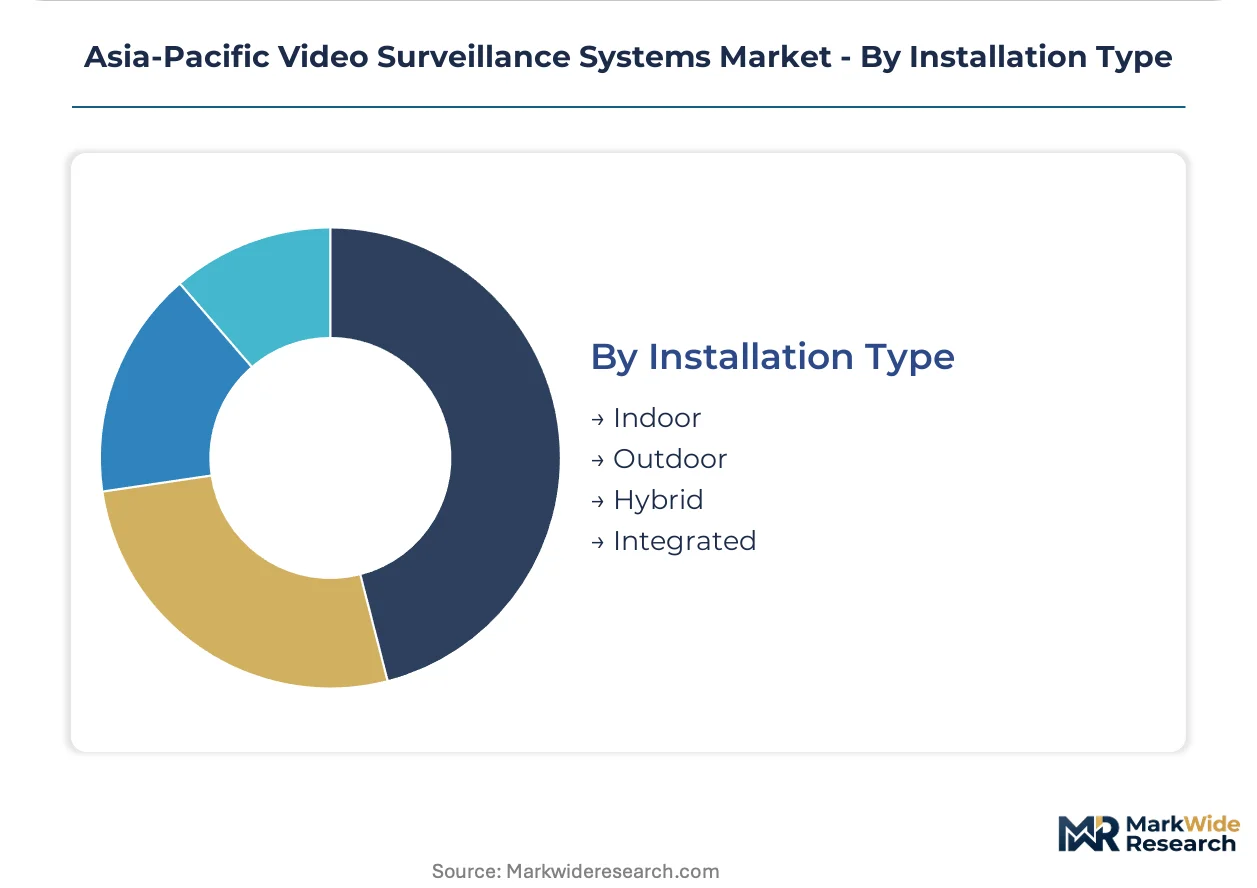
Installation Type:
Customer type segmentation separates single-site operators from multi-facility enterprises with standardized platform requirements.
- Outdoor:Weather-sealed housings with thermal management for 8K sensors protect perimeters in Australian mining and energy corridors. Silicon carbide power components elevate unit costs but ensure reliability in extreme temperature ranges.
- Hybrid:Mixed indoor-outdoor deployments allow phased upgrades that preserve existing cabling investments during analog-to-IP transitions.
- Indoor:Compact dome and turret form factors dominate retail and education verticals with aesthetic constraints.
- Integrated:Unified command centers consolidate access control, video, and alarm systems for critical infrastructure protection.
Outdoor commands the premium price tier, with Hybrid showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Hangzhou, Shenzhen, and Seoul anchor the region's video surveillance innovation clusters. These metropolitan concentrations feed directly into municipal procurement pipelines and export manufacturing bases.
China
MIIT's GB/T 28181 interoperability standards and cybersecurity review protocols are accelerating system-wide upgrades across government verticals. The Yangtze River Delta and Pearl River Delta corridors concentrate smart city deployments where networked camera arrays replace legacy analog infrastructure. Hangzhou and Shenzhen house integrated sensor-to-cloud development centers serving domestic and export markets.
India
The Smart Cities Mission drives sustained procurement in Mumbai, Delhi, and Bangalore for traffic management and public safety networks. BIS mandates ISI certification for electronic security equipment sold to government buyers, extending product launch timelines for imported systems. The Delhi-NCR corridor anchors municipal replacement cycles as analog dome cameras give way to IP-based 4K units with onboard analytics.
South Korea
MFDS-aligned data protection frameworks require domestic storage for facial recognition templates, complicating cloud architecture economics for foreign vendors. The Seoul Capital Area concentrates ethical AI certification requirements that restrict vendor pools in sensitive government verticals. Busan-Ulsan industrial zones deploy perimeter protection systems for critical infrastructure corridors.
Australia
The national privacy regulator mandates data residency for biometric templates, fragmenting multi-tenant cloud economics across state procurement. Mining and energy corridors in Western Australia and Queensland deploy multi-spectral fusion systems for perimeter breach detection through occlusion and low-light conditions. Sydney and Melbourne transportation authorities separate camera hardware from analytics platform selection.
Vietnam
Ho Chi Minh City represents a greenfield procurement market where first-mover integrators establish platform standards before legacy lock-in solidifies. National data localization requirements are emerging for government surveillance contracts. The southern economic zone attracts component assembly investments that reduce landed costs for domestic system integrators.
Asia-Pacific Video Surveillance Systems Market Competitive Environment
Top-tier vendors anchor enterprise and government contracts, while mid-scale specialists capture fragmented municipal and commercial segments. The vendor base clusters around integrated hardware-software stacks versus pure-play component suppliers. Three archetypes dominate: sensor-to-cloud integrators with captive chipset design, ethical AI-certified developers for privacy-sensitive verticals, and cloud-managed service platforms for mid-market retail chains. Competitive moves concentrate on backward integration into semiconductor sourcing and geographic expansion through localized certification compliance.
Within the integrated-stack tier, Hangzhou Hikvision Digital Technology Co., Ltd. and Zhejiang Dahua Technology Co., Ltd. represent the Chinese sensor-to-cloud model with deep manufacturing scale. Hanwha Vision Co., Ltd. occupies a position exemplifying the ethical AI certification pathway for South Korean and Australian government verticals.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co., Ltd. |
| Zhejiang Dahua Technology Co., Ltd. |
| Hanwha Vision Co., Ltd. |
| Zhejiang Uniview Technologies Co., Ltd. |
| VIVOTEK Inc. |
| Huawei Technologies Co., Ltd. |
| Panasonic Holdings Corporation |
| Honeywell International Inc. |
| Motorola Solutions, Inc. |
| Others |
Value Chain & Pricing Dynamics
China's dual carbon goals for energy-efficient manufacturing gate both qualified supply and premium-tier pricing access, as vendors with compliant foundry partnerships capture government contract eligibility while legacy assemblers face margin compression from carbon-adjusted input costs.
Pricing Analysis
The bundled-vs-unbundled service split defines competitive positioning across procurement tiers. Hardware-software bundles command project-based premiums in Chinese smart city corridors where MIIT certification requirements favor integrated stacks. Price differentiation hinges on ethical AI certification grade and domestic component ratios. Cost compression in mid-market IP cameras is intensifying because Indian PLI scheme incentives attract local assembly investments. Municipal buyers in Mumbai and Delhi show highest price sensitivity, while Australian mining operators prioritize thermal reliability over unit cost.
Supply Chain Analysis
Warehouse-distribution layer concentration in Shenzhen, Hangzhou, and Seoul shapes regional fulfillment economics for Southeast Asian deployments. CMOS sensor fabrication concentrates in Taiwan and South Korean foundries, while lens assembly and housing production anchors in China's Pearl River Delta. The supply chain rests on silicon carbide power components, advanced thermal substrates, and edge AI chipsets. Single-source vulnerability in image sensor allocation exposes integrators during semiconductor cycle tightness. Distribution runs through authorized distributor networks with hub-and-spoke patterns serving archipelago markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in software licensing tiers and cloud-managed service models, as edge AI deployment shifts value capture from hardware replacement cycles toward recurring analytics revenue.
For Market Incumbents: Extend ethical AI certification coverage into Australian and South Korean government verticals before regulatory fragmentation hardens vendor pools. Deepen backward integration into chipset design to defend against white-label competitors exploiting BIS testing backlogs. Lock in exclusive distribution partnerships in Vietnam's greenfield procurement corridors. For New Entrants and Emerging Players: Mid-market retail chains adopting cloud-managed video-as-a-service represent the most penetrable buyer archetype, with subscription models deferring capital expenditure barriers. Target Indonesian and Vietnamese smart city builds where first-mover integrators establish platform standards. Lead with remote monitoring capabilities and rapid deployment services rather than hardware specifications. For Investors and Strategic Acquirers: Valuations sit cheapest among component assemblers benefiting from India's PLI scheme but lacking captive software stacks. Long-term viability favors vendors with integrated sensor-to-cloud architectures and documented supply chain provenance for China's MIIT cybersecurity reviews. Watch ethical AI certification adoption rates in South Korean government RFPs as an inflection indicator for vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Ethical AI Certification Investment | Unlocks South Korean and Australian government verticals with MFDS-aligned data protection requirements. |
| Edge AI Chipset Integration | Enables on-camera inference for bandwidth-constrained deployments across Southeast Asian archipelagos. |
| Cloud-Managed Video-as-a-Service Launch | Captures mid-market retail chains seeking operational expenditure models over capital-intensive infrastructure. |
| Domestic Assembly Scale-Up | Reduces landed costs and BIS certification timelines for Indian Smart Cities Mission procurement. |
| Multi-Spectral Fusion Platform Development | Addresses perimeter breach detection needs in Australian mining and energy corridors through occlusion-penetrating analytics. |
Study Parameters
Multiple input streams — executive interviews with system integrators, procurement officers at municipal authorities, and chipset procurement leads — were reconciled against customs records, MIIT certification databases, and smart city tender documentation. Primary fieldwork captured deployment patterns across Chinese Yangtze River Delta corridors, Indian Smart Cities Mission implementations, and Australian critical infrastructure sites. Secondary validation drew from BIS laboratory testing disclosures, MFDS data protection guidance, and hyperscaler edge computing capex announcements. Bottom-up unit economics and top-down market sizing were triangulated to bound estimate ranges.
Historical shipment trajectories were cross-referenced against panel input from distribution channel partners to anchor growth assumptions across the projection horizon. Segmentation modeling captured product type, end user vertical, technology architecture, and installation environment dimensions. CAGRs were derived from fitted trend lines adjusted for regulatory inflection points and replacement cycle dynamics. Edge AI adoption curves, cloud storage cost trajectories, and certification timeline distributions informed scenario boundaries.
Underlying measurement precision varies by segment; IP camera volumes and software licensing flows carry tighter precision than emerging cloud-based deployment estimates. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and semiconductor allocation cycles. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Video Surveillance Market
Video Surveillance Systems
Rugged Thermal Cameras Market
Video Surveillance Systems
United Kingdom Video Surveillance Market
Video Surveillance Systems
France Video Surveillance Market
Video Surveillance Systems
Security and Surveillance Storage Market
Video Surveillance Systems
Canada Surveillance Analog Camera Market
Video Surveillance Systems
Global Mobile Video Surveillance Market
Video Surveillance Systems
Europe Surveillance IP Camera Market
Video Surveillance Systems
Asia-Pacific Surveillance Analog Camera Market
Video Surveillance Systems
Night Vision Camera Market
Video Surveillance Systems
Middle East and Africa Surveillance IP Cameras Market
Video Surveillance Systems
North America Smart Home Security Cameras Market
Video Surveillance Systems
Italy Video Surveillance Market
Video Surveillance Systems
Japan Surveillance Camera Market
Video Surveillance Systems
Home Security Camera Market
Video Surveillance Systems
Brazil Surveillance IP Cameras Market