
 In-Vehicle Video Surveillance Market | 2026-2036
In-Vehicle Video Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
In-Vehicle Video Surveillance Market Intelligence
Public transportation procurement is hardening as the dominant end-use vertical for in-vehicle video surveillance, displacing earlier reliance on personal vehicle aftermarket sales. Thinkware Corporation leverages its Korean manufacturing base to sustain cost-competitive production of dual-channel dash cameras for transit agencies. Garmin Ltd. anchors its position through specialized ruggedized units engineered for emergency services fleets operating in extreme temperature ranges. Qrontech Co. Ltd. competes aggressively on price in the portable installation segment across Southeast Asian markets.
In-vehicle video surveillance encompasses camera systems permanently or temporarily mounted within automobiles, buses, trucks, and rail vehicles to capture continuous or event-triggered footage for safety documentation, driver behavior monitoring, and incident reconstruction; these systems typically operate on 12V DC vehicle power with recording resolutions from 1080p to 4K, utilizing loop recording architecture and G-sensor impact detection to preserve critical footage while overwriting routine data. Cloud-based solutions represent the fastest-expanding technology segment as fleet managers demand real-time remote access to live feeds and automated incident flagging, while analog camera installations remain entrenched in legacy municipal bus retrofits where infrastructure replacement cycles extend across decades. Dashboard cameras command the largest product type volume, though 360-degree camera systems capture disproportionate margin pools in premium OEM installations for luxury commercial vehicles.
The U.S. Department of Transportation's Federal Motor Carrier Safety Administration shapes commercial fleet adoption through hours-of-service documentation requirements and collision accountability protocols, while the EU General Safety Regulation mandates event data recorders and driver drowsiness detection systems that integrate video verification. China's Ministry of Industry and Information Technology enforces GB standards for connected vehicle data security, restricting cross-border cloud transmission and compelling domestic cloud-based solution architectures. Stakeholders must monitor fragmentation between regional data sovereignty requirements and the technical feasibility of unified global platform deployment.
Market Dynamics
Fleet operators are consolidating procurement around cloud-connected platforms that unify real-time monitoring with automated incident detection, compressing vendor margins while elevating data sovereignty compliance as a non-negotiable purchase criterion.
Growth Catalysts
- EU General Safety Regulation:Mandates event data recorders and driver drowsiness detection systems in new vehicle categories, forcing OEM integration of video verification modules across commercial fleets.
- Commercial trucking liability exposure:North American fleet operators are expanding camera deployments to reduce insurance premiums and collision accountability disputes.
- 1080p to 4K resolution migration:Higher-definition recording enables facial recognition and license plate capture, opening municipal transit and law enforcement procurement channels.
Market Restraints
- Semiconductor supply concentration:Image sensor fabrication concentrates in East Asian foundries, exposing camera system manufacturers to geopolitical disruption and allocation delays.
- GB standards data localization:China's MIIT restrictions on cross-border cloud transmission fragment platform architectures and inflate compliance costs for multinational fleet operators.
- Legacy analog infrastructure:Municipal bus retrofits with decades-long replacement cycles anchor demand in lower-margin hardware, delaying cloud migration revenue.
Strategic Opportunities
- 360-degree camera penetration:Premium OEM installations for luxury commercial vehicles capture disproportionate margin pools as fleet managers prioritize comprehensive coverage over single-channel units.
- Rail vehicle segment:Underpenetrated relative to road transport, passenger rail operators in Germany and Japan are piloting platform-integrated surveillance for crowd management and incident reconstruction.
- Edge AI processing:On-device analytics reducing bandwidth requirements and cloud dependency is converging with 5G vehicle connectivity to enable real-time threat detection without continuous streaming.
Industry Challenges
- Embedded systems engineering scarcity:Shortage of firmware developers capable of optimizing video compression for 12V DC power constraints and thermal envelope limitations.
- Multi-jurisdiction certification timelines:FCC, CE marking, and E-Mark approvals for radio-enabled dash cameras extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Vehicle Video Surveillance Market |
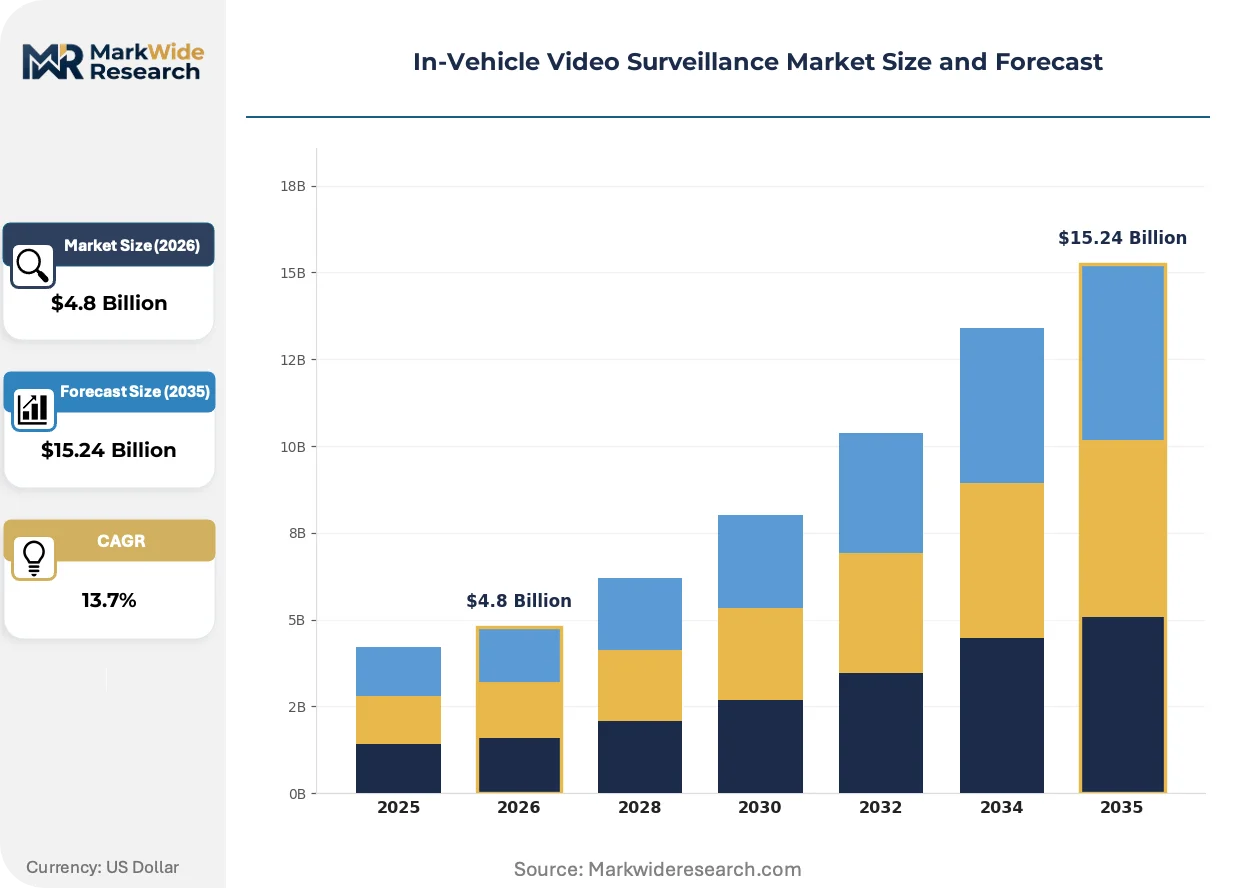
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dashboard Cameras, In-Mirror Cameras, Rear View Cameras, 360-Degree Cameras Installation Type: OEM Installation, Aftermarket Installation, Portable Installation, Integrated Systems Technology: Analog Cameras, Digital Cameras, Wireless Cameras, Cloud-Based Solutions End User: Fleet Operators, Public Transportation, Emergency Services, Personal Vehicles |
| Companies Covered | Pittasoft Co. Ltd., 70mai, Nextbase UK Ltd., Qrontech Co. Ltd., Garmin Ltd., Thinkware Corporation, Transcend Information Inc., i-PRO Co. Ltd., Vantrue Technology Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Vehicle Video Surveillance Market Strategic Shifts & Innovations
Video analytics capabilities are migrating from cloud servers to edge processors within camera housings, enabling real-time incident flagging without continuous connectivity and reshaping fleet management software architectures.
Artificial intelligence-based driver behavior monitoring is converging with telematics platforms to create unified safety scores that insurers use for dynamic premium pricing. Fleet operators in the United States are adopting these integrated systems fastest, with commercial trucking leading deployment. This convergence compresses standalone dash camera margins while elevating platform subscription revenue.
The EU General Safety Regulation mandates advanced driver assistance systems with video verification components in all new commercial vehicles above 3.5 tonnes. OEMs are redesigning electrical architectures to accommodate permanent camera installations rather than aftermarket mounting. German and Swedish commercial vehicle manufacturers are responding with factory-integrated 360-degree coverage as standard equipment.
Buying committees at municipal transit agencies are unbundling hardware procurement from software subscriptions, forcing vendors to compete on platform interoperability rather than bundled pricing. Channel partners specializing in fleet management software are displacing traditional security integrators in the United States and United Kingdom. This pattern concentrates procurement authority with IT departments rather than operations managers.
In-Vehicle Video Surveillance Market Segmentation
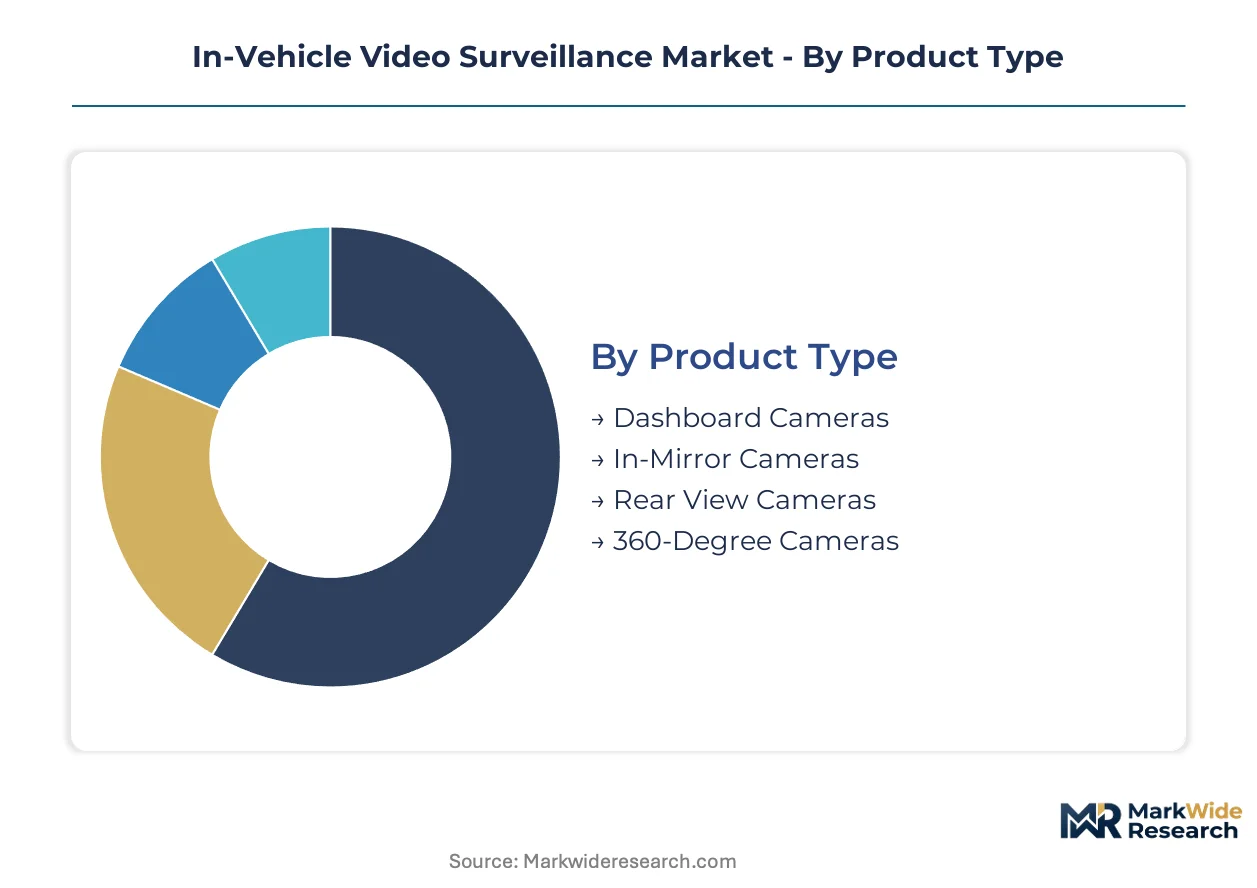
Segmentation in the In-Vehicle Video Surveillance Market reveals distinct procurement patterns between embedded OEM architectures and retrofit aftermarket solutions. Fleet operators prioritize integrated systems with cloud connectivity, while municipal agencies navigate legacy analog constraints alongside digital migration imperatives.
Product Type:
Integration depth varies sharply across form factors, with windshield-mounted units representing standalone deployment versus embedded mirror and multi-camera arrays requiring factory electrical architecture redesign.
- Dashboard Cameras:Single-lens or dual-channel units mount to windshields via adhesive or suction mechanisms, recording forward and cabin-facing footage to SD cards or onboard storage. Demand concentrates among personal vehicle owners in the United States seeking insurance premium reductions and collision documentation. Loop recording architecture with G-sensor impact detection preserves incident footage while overwriting routine data.
- 360-Degree Cameras:Multi-lens arrays stitch synchronized feeds into comprehensive vehicle-surround coverage, requiring calibration software and higher processing overhead. Fleet managers at German and Swedish commercial vehicle manufacturers prioritize these systems for liability elimination in blind-spot incidents and parking collision disputes.
- In-Mirror Cameras:Discrete units replace or overlay rearview mirrors with integrated displays, preserving cabin aesthetics while adding recording capability.
- Rear View Cameras:Backup-assist systems with recording functionality serve dual purposes in parking safety and rear-collision documentation.
Volume placements concentrate in Dashboard Cameras; the faster expansion belongs to 360-Degree Cameras.
Installation Type:
Cost tier stratification separates capital-intensive factory integration from lower-threshold aftermarket and portable alternatives with minimal vehicle modification.
- OEM Installation:Factory-integrated camera systems embed within vehicle electrical architectures during assembly, with wiring harnesses and control modules specified by commercial vehicle manufacturers. The EU General Safety Regulation mandates this installation category for new commercial vehicles above 3.5 tonnes, compelling German OEMs to redesign electrical systems around permanent camera infrastructure.
- Aftermarket Installation:Professional retrofit services hardwire camera systems to vehicle fuse boxes and 12V DC circuits, enabling fleet upgrades without vehicle replacement. North American commercial trucking operators favor this category for hours-of-service documentation and insurance premium negotiations.
- Portable Installation:Cigarette-lighter or battery-powered units require no vehicle modification, appealing to rental fleet managers and temporary deployment scenarios.
- Integrated Systems:Telematics-platform-embedded surveillance combines video with GPS, accelerometer, and engine data streams.
Aftermarket Installation commands current volume leadership; OEM Installation is gaining share fastest as regulatory mandates accelerate factory integration.
Technology:
Application maturity separates decades-old analog infrastructure from cloud-connected platforms enabling real-time fleet oversight.
- Cloud-Based Solutions:Cellular-connected cameras stream footage to remote servers, enabling live feed access and automated incident flagging via machine learning algorithms. Fleet operators in the United States consolidate procurement around these platforms for centralized monitoring across dispersed vehicle assets.
- Digital Cameras:IP-based recording at 1080p to 4K resolution enables facial recognition and license plate capture for law enforcement and municipal transit procurement channels.
- Analog Cameras:Coaxial-cable systems with lower resolution persist in legacy municipal bus retrofits where infrastructure replacement cycles extend across decades.
- Wireless Cameras:Wi-Fi or proprietary RF-linked units reduce installation complexity in applications where cable routing proves impractical.
Analog Cameras retain volume in legacy fleets; Cloud-Based Solutions are climbing the fastest as real-time monitoring becomes standard procurement criteria.
End User:
Customer type determines specification intensity, with commercial operators demanding ruggedized hardware and data sovereignty compliance versus consumer price sensitivity.
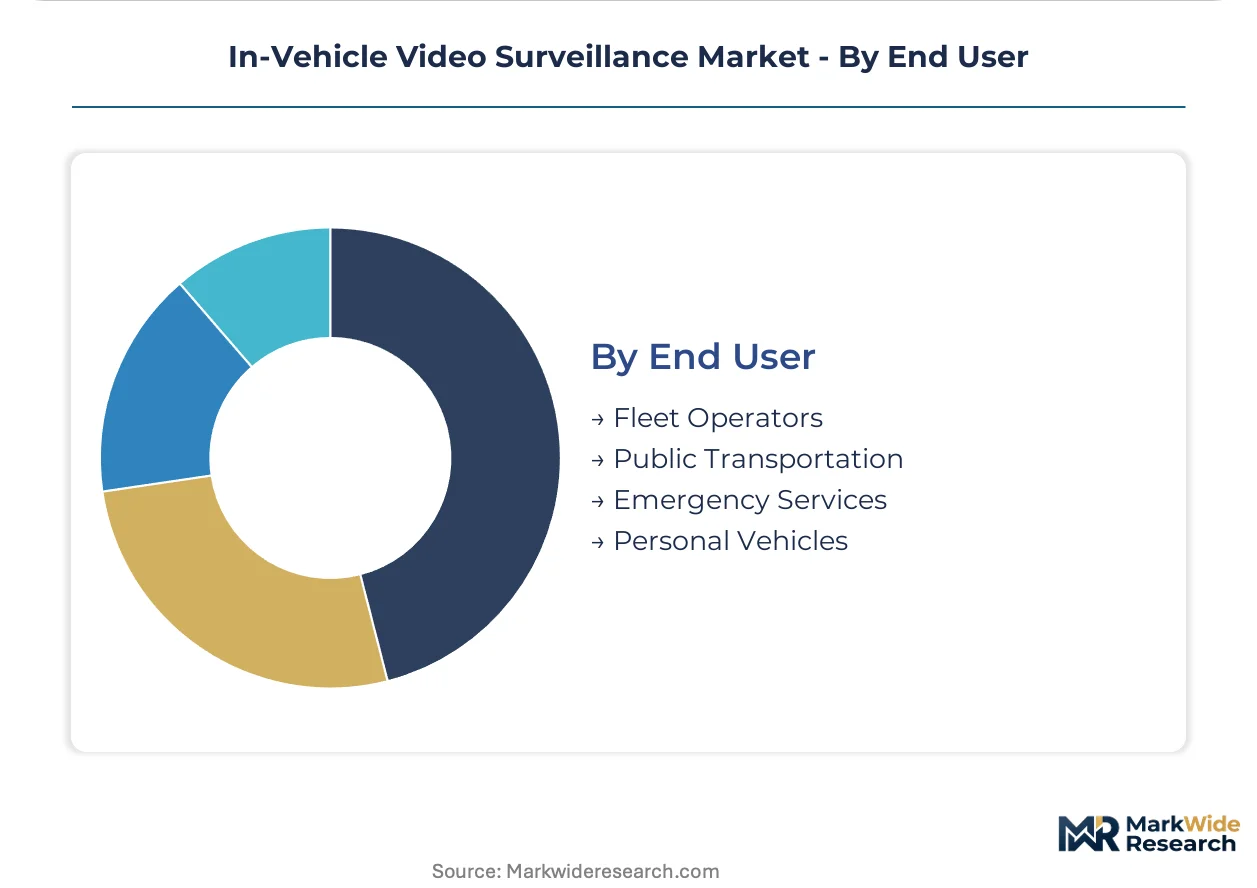
- Fleet Operators:Commercial trucking, delivery, and logistics companies deploy camera systems for driver behavior monitoring, cargo security, and collision liability reduction. The U.S. Department of Transportation's Federal Motor Carrier Safety Administration shapes adoption through hours-of-service documentation requirements.
- Public Transportation:Municipal transit agencies specify vandal-resistant housings and extended temperature ranges for bus and rail deployments. German and Japanese passenger rail operators are piloting platform-integrated surveillance for crowd management.
- Emergency Services:Police, fire, and ambulance fleets require ruggedized units engineered for extreme temperature ranges and impact resistance.
- Personal Vehicles:Individual consumers prioritize price-competitive dash cameras with simplified installation and minimal subscription dependencies.
Volume placements concentrate in Fleet Operators; Public Transportation represents the steepest expansion trajectory as municipal procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Shenzhen and Dongguan concentrate camera module assembly capacity, attracting component suppliers and test houses into tightly clustered manufacturing corridors. These zones subsidize precision optics fabrication and surface-mount technology lines serving automotive tier-1 suppliers.
United States
Commercial trucking fleets in Texas and California drive aftermarket camera procurement for hours-of-service documentation and insurance premium reduction. The Federal Motor Carrier Safety Administration mandates collision accountability protocols that elevate video verification to compliance infrastructure. Detroit-area automotive suppliers integrate dual-channel systems into heavy-duty truck electrical architectures.
Germany
Luxury commercial vehicle manufacturers in Stuttgart and Munich specify factory-integrated 360-degree coverage as standard equipment above 3.5 tonnes. The EU General Safety Regulation compels OEMs to redesign electrical systems around permanent camera infrastructure. Bavarian engineering clusters develop calibration software for multi-lens array synchronization.
China
Domestic cloud platform providers in Beijing and Shanghai architect GB-compliant data localization solutions for connected vehicle fleets. The Ministry of Industry and Information Technology restricts cross-border transmission, fragmenting multinational platform deployments. Yangtze River Delta electronics hubs manufacture image sensors and compression chipsets for regional supply security.
Japan
Passenger rail operators in Tokyo and Osaka pilot platform-integrated surveillance for crowd management and incident reconstruction. METI standards guide edge AI processing specifications for bandwidth-constrained deployment. Nagoya automotive suppliers embed thermal-resistant camera housings into factory electrical architectures.
South Korea
Transit agencies in Seoul and Busan procure cost-competitive dual-channel dash cameras for municipal fleet upgrades. Domestic manufacturers leverage captive display panel and memory semiconductor supply for integrated system cost control. Incheon free economic zone hosts test facilities for connected vehicle data security certification.
In-Vehicle Video Surveillance Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with aftermarket distribution favoring established consumer electronics names while OEM integration channels concentrate around automotive-tier suppliers with embedded systems certification. The vendor base organizes into three functional tiers: ruggedized fleet specialists, portable consumer-grade assemblers, and factory-integrated platform providers. Consolidation pressure operates most intensely in the cloud-connected segment where subscription economics favor scale. Competitive maneuvering centers on strategic partnerships with telematics platforms and backward integration into image sensor sourcing.
Within the ruggedized fleet tier, Garmin Ltd. and Thinkware Corporation exemplify geographic specialization strategies, with the former anchoring North American emergency services procurement and the latter leveraging Korean manufacturing scale for transit agency cost targets. Qrontech Co. Ltd. occupies a position in the portable installation segment where minimal vehicle modification requirements open Southeast Asian rental fleet channels. These three entities collectively represent divergent archetypes: premium-specification engineering, manufacturing-scale cost leadership, and price-aggressive temporary deployment.
| Leading Market Players |
|---|
| Pittasoft Co. Ltd. |
| 70mai |
| Nextbase UK Ltd. |
| Qrontech Co. Ltd. |
| Garmin Ltd. |
| Thinkware Corporation |
| Transcend Information Inc. |
| i-PRO Co. Ltd. |
| Vantrue Technology Co. Ltd. |
| Others |
Cost & Logistics Intelligence
The EU General Safety Regulation's mandated event data recorder requirements gate qualified supply access for OEM-integrated camera modules, restricting premium-tier pricing power to vendors with embedded systems certification and factory integration capabilities. Fleet operators seeking cloud-connected platforms face elongated procurement cycles as compliant suppliers concentrate around German and Swedish commercial vehicle manufacturers.
Pricing Analysis
Short lead-time premiums command substantial markups for emergency fleet deployments requiring FCC and CE-marked radio-enabled units within compressed windows. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling, with municipal transit agencies exhibiting acute price sensitivity versus luxury commercial vehicle OEMs. Cost compression in the portable installation segment intensifies as Southeast Asian contract manufacturers expand capacity. Price differentiation hinges on thermal envelope engineering and G-sensor calibration precision for extreme temperature applications.
Supply Chain Analysis
Reverse logistics flows for dash camera refurbishment and warranty returns concentrate processing capacity in Shenzhen and Dongguan Special Economic Zones, where test houses validate repaired units for secondary channel distribution. Image sensor fabrication centers on Taiwan and South Korea, while final assembly draws from Yangtze River Delta electronics hubs and Korean display panel corridors. Supply chain risk rests on single-source vulnerability for 12V DC power management chipsets. Distribution runs through automotive Tier 1 suppliers and fleet management software channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor foundry allocation constraints for automotive-grade image sensors prop pricing resilience across the forecast horizon, compressing margin headroom for undifferentiated hardware assemblers.
For Market Incumbents: Cement platform interoperability advantages by acquiring edge AI processing specialists before telematics consolidation accelerates. Deepen backward integration into thermal-resistant housing manufacturing to defend against emerging ruggedized specialists from Nagoya engineering clusters. Prioritize GB-compliant cloud architecture development to preempt fragmentation of multinational fleet deployments.
For New Entrants and Emerging Players: Capture underpenetrated passenger rail surveillance opportunities in German and Japanese markets where platform-integrated pilot programs lack established vendor relationships. Target portable installation segments for rental fleet managers seeking minimal vehicle modification solutions. Pursue telematics platform partnership routes rather than direct fleet sales channels.
For Investors and Strategic Acquirers: German OEM electrical architecture redesign announcements for factory-integrated 360-degree coverage are the leading indicator that OEM installation category share inflection is underway. Five-to-ten year viability favors automotive-tier suppliers with embedded systems certification over aftermarket hardware vendors. Monitor EU General Safety Regulation enforcement timelines for commercial vehicle category expansion signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Processing Acquisition | On-device analytics capability reduces cloud dependency for bandwidth-constrained fleet deployments. |
| GB-Compliant Cloud Architecture | MIIT data localization requirements fragment multinational platform deployments without domestic infrastructure. |
| Thermal Housing Backward Integration | Captive production of extreme-temperature enclosures protects margin pools in emergency services procurement. |
| Rail Platform Partnership | German and Japanese passenger rail pilot programs lack established surveillance vendor relationships. |
| Telematics Platform Integration | Unified safety scores from AI-based driver monitoring enable dynamic insurance premium pricing adoption. |
Research Approach
SEC 10-K filings, automotive production databases, and customs trade records formed the secondary backbone, supplemented by FCC equipment authorization registries and EU type-approval documentation. Primary fieldwork encompassed fleet operations directors, Tier 1 supplier procurement managers, municipal transit agency buyers, and telematics platform engineers across the United States, Germany, and South Korea. Bottom-up and top-down triangulation validated shipment volumes against OEM electrical architecture redesign timelines.
Bottom-up modeling segmented by installation type, technology architecture, and end-user vertical across the projection horizon. Top-down approaches cross-referenced regulatory mandate enforcement schedules with commercial vehicle production forecasts. CAGRs derived from elasticity-adjusted adoption curves incorporating 1080p-to-4K resolution migration and cloud connectivity penetration rates. Edge AI processing capability and 5G vehicle connectivity deployment served as technology-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor allocation disruptions and multi-jurisdiction certification timeline extensions. Forecasts reflect documented assumptions regarding EU General Safety Regulation category expansion and MIIT data localization enforcement intensity. Practitioners should monitor German OEM electrical architecture redesign announcements and Yangtze River Delta foundry capacity additions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Brazil Surveillance Camera Market
Video Surveillance Systems
Europe Video Surveillance Storage Market
Video Surveillance Systems
Crawler Camera System Market
Video Surveillance Systems
Canada Surveillance IP Camera Market
Video Surveillance Systems
Global Mobile Video Surveillance Market
Video Surveillance Systems
United States Surveillance IP Camera Market
Video Surveillance Systems
Rugged Thermal Cameras Market
Video Surveillance Systems
Video Surveillance Market
Video Surveillance Systems
United States Surveillance Analog Camera Market
Video Surveillance Systems
Middle East and Africa Surveillance Analog Camera Market
Video Surveillance Systems
Japan Surveillance Camera Market
Video Surveillance Systems
United States Surveillance Camera Market
Video Surveillance Systems
Surveillance Camera Systems Market
Video Surveillance Systems
Global Body Worn Cameras Market
Video Surveillance Systems
Security Camera Software Market
Video Surveillance Systems
India Surveillance Camera Market