
 Global Body Worn Cameras Market | 2026-2036
Global Body Worn Cameras Market Size, Share, and Industry Trends Forecast 2026-2036
Global Body Worn Cameras Market Foresight
1080p full-HD resolution specification is unwinding legacy 720p procurement standards across public safety agencies. Axon Enterprise Inc. leverages integrated cloud evidence management to anchor its position in North American police departments. Motorola Solutions Inc. competes through radio-system interoperability that sustains cross-agency deployment appeal. Panasonic Corporation specializes in ruggedized hardware design that dominates corrections and military end-user segments.
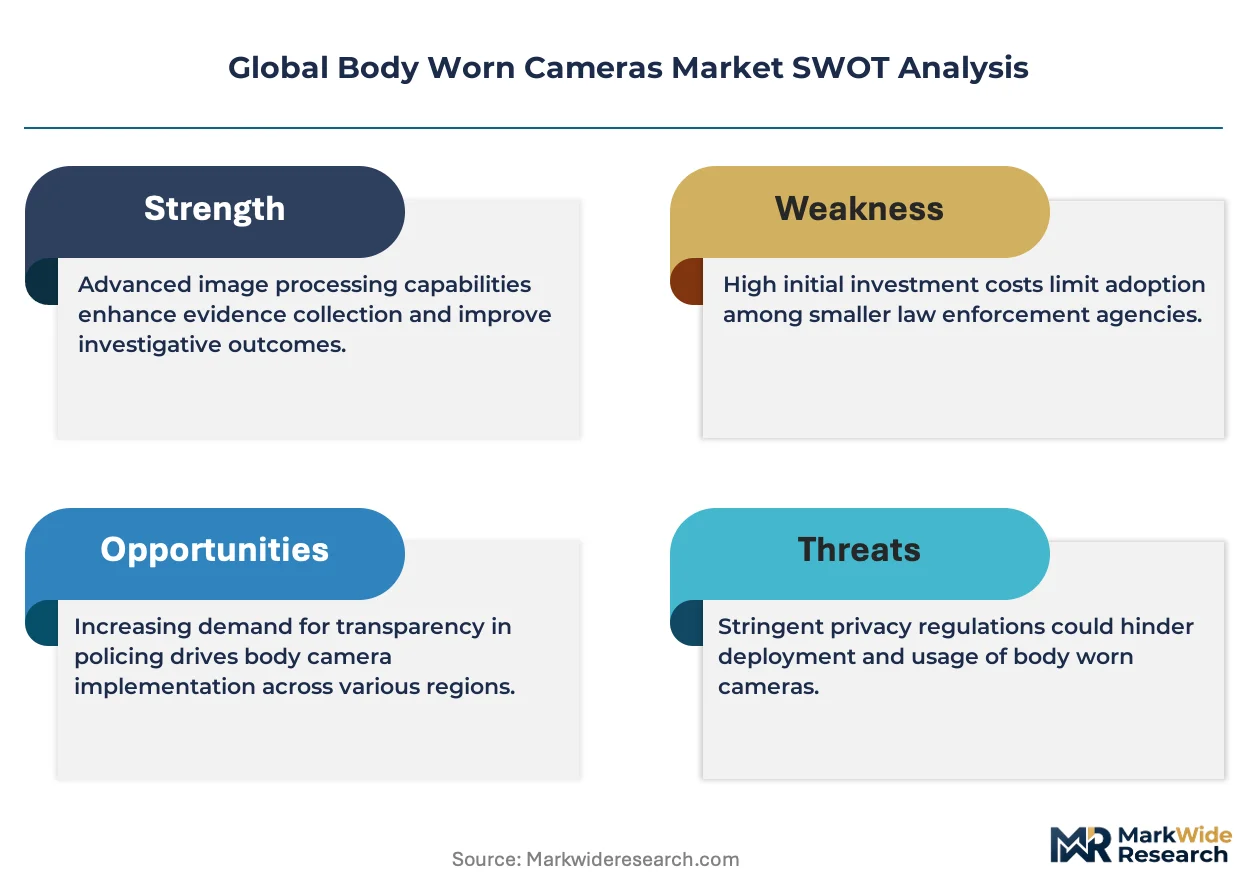
Body worn cameras are compact audiovisual recording devices, typically weighing under 150 grams, that mount on uniforms or equipment to capture timestamped, encrypted footage for evidence documentation and operational review. These devices incorporate CMOS image sensors, lithium-ion power cells, and solid-state storage sealed within IP67-rated enclosures to withstand field conditions in law enforcement and security operations. Wireless connectivity segments are capturing accelerated replacement cycles as agencies abandon dock-based file retrieval for real-time upload architectures. HD Recording technology leads unit shipments, though Infrared Night Vision commands margin premiums in tactical police and military procurement channels. Law Enforcement application demand remains structurally dominant, while Security Personnel represents the fastest-growing category as private facility operators adopt accountability protocols.
FCC equipment authorization governs radio-frequency emissions for wireless-enabled units sold in the United States, while ETSI standards regulate European spectrum compliance for body worn camera transmissions. The EU AI Act classification of biometric identification systems is reshaping product roadmaps for facial recognition integration in Reveal Media and WatchGuard Technologies devices. Stakeholders must monitor evolving chain-of-custody requirements as cloud storage jurisdictions complicate cross-border evidence admissibility.
Market Dynamics
Real-time evidence upload architectures are displacing dock-based retrieval systems across municipal police departments, forcing hardware vendors to redesign power management and wireless modules for continuous field operation.
Growth Catalysts
- Federal grant programs:United States Department of Justice funding streams accelerate municipal procurement cycles for departments with limited capital budgets.
- GDPR chain-of-custody frameworks:European evidence admissibility rules mandate encrypted timestamping and audit trails that favor certified device vendors.
- CMOS sensor advancement:Low-light sensitivity improvements enable 1080p recording at reduced power draw, extending shift-length deployment viability.
Market Restraints
- Lithium-ion cell volatility:Thermal runaway risks in compact enclosures complicate air freight logistics and field replacement protocols.
- Cloud storage jurisdiction fragmentation:Cross-border evidence admissibility disputes between EU member states create legal uncertainty for multi-national agency deployments.
- Radio-frequency spectrum congestion:FCC Part 15 unlicensed band saturation in dense urban environments degrades real-time upload reliability.
Strategic Opportunities
- Private security vertical:Corporate campus and critical infrastructure operators in Germany adopt accountability protocols previously limited to public agencies.
- AI-enabled redaction automation:EU AI Act compliance tools for biometric data masking open software service revenue streams adjacent to hardware sales.
- Interoperability mandates:Motorola radio system integration requirements in North American jurisdictions favor vendors with existing public safety communications relationships.
Industry Challenges
- Firmware security certification:FIPS 140-2 validation timelines for encryption modules delay product launches by 12-18 months.
- Legacy evidence management integration:Proprietary file formats from incumbent dock-based systems obstruct seamless migration to cloud-native architectures.
- Technical workforce scarcity:Field technicians trained in IP67 seal maintenance and antenna troubleshooting remain concentrated in coastal metropolitan labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Body Worn Cameras Market |
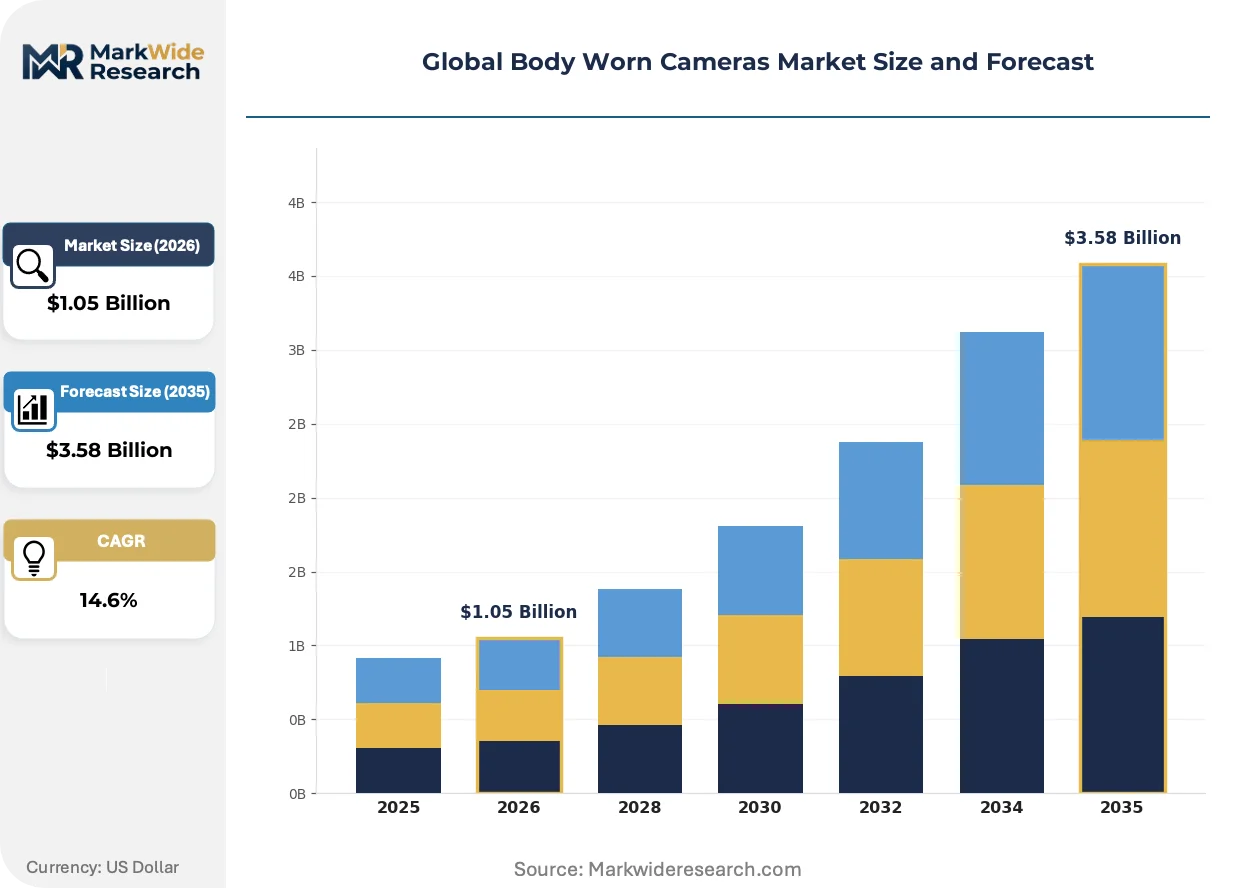
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $3.58 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired, Wireless, Hybrid, Standalone Technology: HD Recording, Infrared Night Vision, GPS Enabled, Motion Detection, Voice Activation Application: Law Enforcement, Security Personnel, Transportation Monitoring, Event Management, Private Investigations End User: Police Forces, Security Agencies, Public Transport Operators, Event Organizers, Military Units |
| Companies Covered | Axon Enterprise Inc., Motorola Solutions Inc., Digital Ally Inc., Panasonic Corporation, WatchGuard Technologies Inc., Reveal Media Ltd., GoPro Inc., Sony Corporation, LensLock Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Body Worn Cameras Market Shifts & Advancements
Edge computing capabilities are migrating processing workloads from central servers to camera hardware, reducing bandwidth costs while complicating thermal design trade-offs in compact form factors.
Artificial intelligence inference chips embedded directly into body worn camera SoCs are decomposing the traditional separation between capture devices and back-end analysis servers. Tactical police units in Australia now deploy units with on-device facial detection that flags persons of interest without continuous cellular connectivity. This silicon integration compresses vendor margins on recurring cloud analytics subscriptions while accelerating replacement cycles for legacy hardware lacking neural processing units.
EU AI Act risk classification frameworks for biometric identification systems are forcing product roadmap revisions across European deployments. Manufacturers must now document training data provenance and algorithmic accuracy rates before CE marking approval. French and German procurement authorities have suspended facial recognition feature rollouts pending compliance certification, redirecting R&D investment toward audio analytics and geolocation metadata enhancement.
Municipal purchasing departments are consolidating vendor relationships through multi-year fleet management contracts that bundle hardware, cloud storage, and technical support into single-source agreements. This aggregation displaces the previous model of discrete capital purchases with separate maintenance negotiations. The shift is most visible in United States mid-sized cities where police chiefs seek budget predictability amid municipal fiscal pressures.
Global Body Worn Cameras Market Segmentation
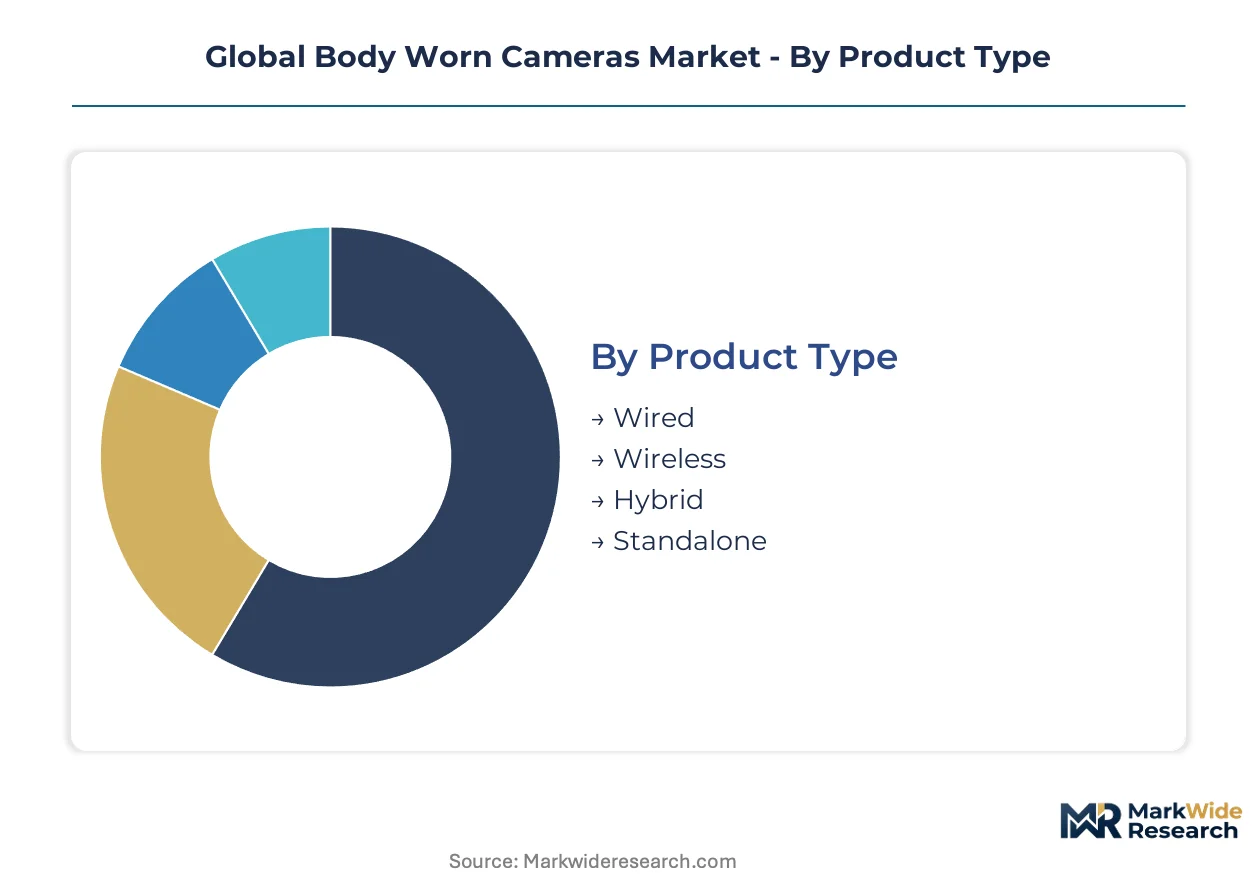
Segmentation reveals how procurement specifications diverge across institutional buyers and operational environments. Technical requirements for chain-of-custody compliance, wireless upload architectures, and biometric data governance create distinct purchasing clusters that reshape vendor product roadmaps.
Product Type:
Wireless variants dominate export flows to European and Asia-Pacific markets where real-time evidence upload mandates are tightening. Wired configurations retain domestic concentration in United States municipal departments with legacy dock infrastructure.
- Wired:Dock-dependent file retrieval systems with tethered charging and physical data transfer. United States police departments with established evidence management rooms favor these units for capital budget predictability and simplified IT security protocols.
- Wireless:Continuous cellular or Wi-Fi connectivity enabling real-time cloud upload without officer intervention. German and French procurement authorities mandate encrypted transmission protocols that favor certified wireless architectures under GDPR evidence admissibility frameworks.
- Hybrid:Dual-mode operation switching between docked retrieval and wireless upload based on network availability. Transit authorities in Australia deploy hybrid units where tunnel coverage gaps interrupt continuous connectivity.
- Standalone:Self-contained recording with removable storage and no network dependency. Military field operations in Israel and United Kingdom special forces prioritize standalone units for electromagnetic spectrum security in contested environments.
Wired configurations command the established base across legacy-equipped departments. The steepest expansion runs through wireless architectures as real-time evidence mandates proliferate.
Technology:
Cost tier stratification separates premium infrared and GPS modules from baseline HD recording, with motion detection and voice activation occupying mid-tier positioning.
- HD Recording:1080p CMOS sensor capture with H.265 compression reducing storage overhead. Baseline specification for United Kingdom police forces under Home Office procurement standards, with 720p legacy systems accelerating replacement cycles.
- Infrared Night Vision:Near-infrared LED illumination enabling low-light identification at 10-meter range. Tactical units in Sweden and Norway command margin premiums for winter darkness operations where ambient lighting fails.
- GPS Enabled:Embedded GNSS receivers tagging footage with geolocation metadata and officer tracking. Finnish border patrol agencies mandate GPS integration for remote territory coverage where radio contact is intermittent.
- Motion Detection:Accelerometer-triggered recording conserving battery and storage during static periods. Private security contractors in Singapore deploy motion-activated units for prolonged facility patrols without continuous operation.
- Voice Activation:Audio-triggered start/stop functionality responding to keyword commands or sound thresholds. Corrections officers in Canada utilize voice activation for hands-free operation during physical restraint scenarios.
HD Recording anchors volume shipments across budget-constrained agencies. Infrared Night Vision claims the steepest margin expansion trajectory in tactical procurement channels.
Application:
Customer type divergence separates public accountability mandates from private liability management, with transportation and event applications occupying intermediate regulatory territory.
- Law Enforcement:Court-admissible evidence capture with chain-of-custody documentation and audit trails. United States federal grant programs accelerate municipal department deployments where officer accountability litigation has escalated insurance costs.
- Security Personnel:Corporate campus and critical infrastructure protection with incident documentation for liability defense. German industrial operators adopt accountability protocols previously limited to public agencies under works council negotiation pressures.
- Transportation Monitoring:Driver and passenger safety documentation in buses, trains, and ride-share vehicles. Tokyo Metropolitan Bureau of Transportation mandates continuous recording following passenger violence incidents on subway lines.
- Event Management:Crowd control documentation at concerts, sporting venues, and political gatherings. Brazilian federal police require event organizer camera deployment for World Cup and Olympic legacy security frameworks.
- Private Investigations:Covert or overt surveillance documentation for legal and insurance proceedings. Swiss private security firms operate under strict cantonal licensing that limits deployment scope compared to public authority equivalents.
Law Enforcement retains the volume concentration. Security Personnel is climbing the fastest as private accountability protocols replicate public sector standards.
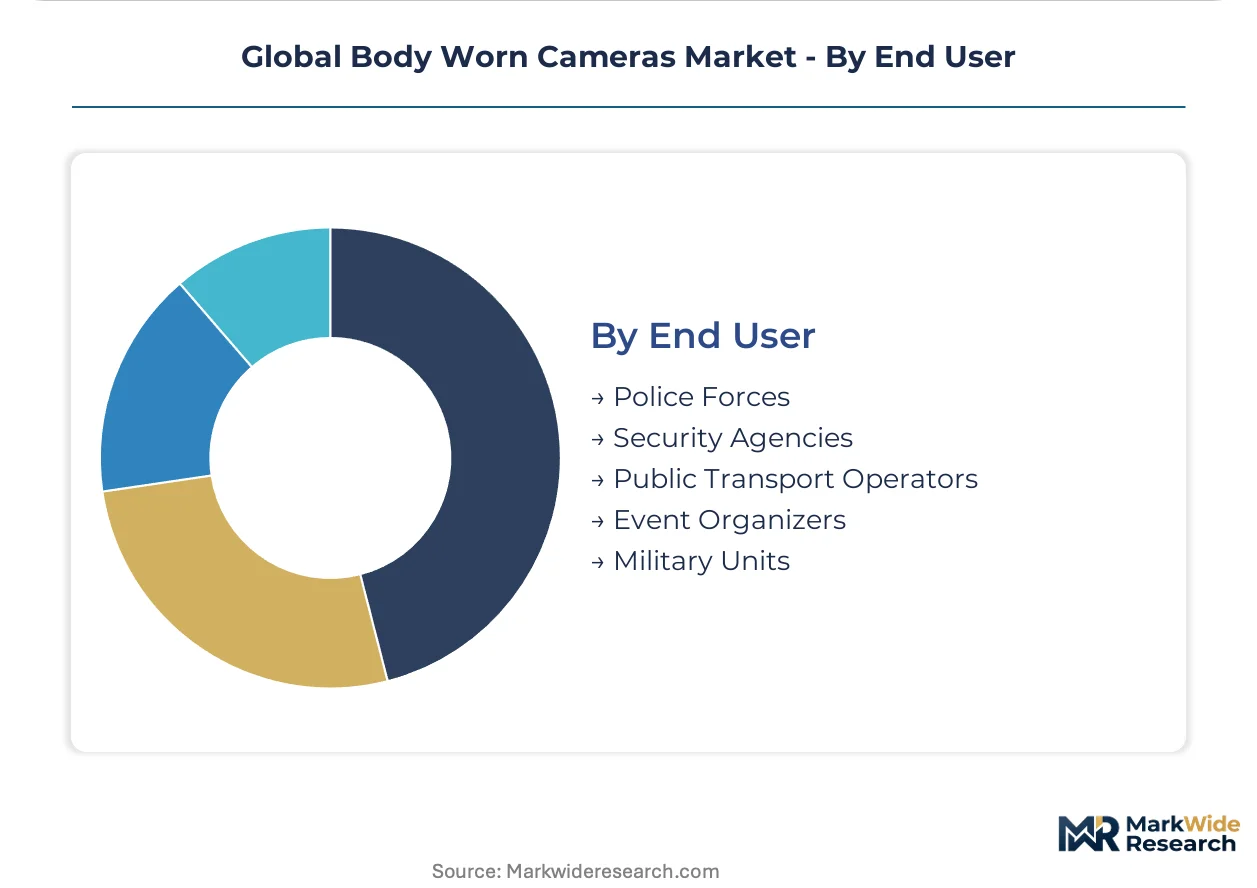
End User:
Maturity differentiation separates institutionalized procurement in police and military channels from emergent adoption patterns in event and transport operators.
- Police Forces:Municipal, state, and national law enforcement with standardized fleet deployment and centralized evidence management. Dutch National Police operate unified procurement reducing per-unit costs through volume aggregation.
- Security Agencies:Government and private security services with protective detail and facility guard mandates. Saudi Arabia's Public Security Training Institute certifies body camera operators for Hajj pilgrimage crowd management.
- Public Transport Operators:State and municipal transit authorities documenting driver-passenger interactions. New York Metropolitan Transportation Authority expanded camera deployment following assault statistics publication mandates.
- Event Organizers:Private and public venue operators managing crowd safety and liability exposure. Qatar Supreme Committee for Delivery and Legacy mandated body cameras for stadium security during FIFA tournament operations.
- Military Units:Combat and garrison forces requiring ruggedized recording for after-action review and rules-of-engagement documentation. Australian Defence Force trials integrate cameras with existing soldier modernization programs.
Police Forces represent the established procurement anchor. Event Organizers are gaining share fastest as venue liability frameworks tighten across entertainment and sporting industries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side concentration clusters in the United States, Germany, Japan, and China, where federal procurement programs and manufacturing ecosystems sustain hardware production. Demand dispersion across these markets reflects divergent regulatory timelines and institutional accountability mandates.
United States
Municipal police departments drive procurement volumes through Department of Justice grant programs that subsidize fleet deployments. FCC equipment authorization governs radio-frequency emissions for wireless-enabled units. Chicago and Los Angeles metropolitan agencies anchor the largest municipal contract aggregations, with multi-year fleet management agreements replacing discrete capital purchases.
Germany
Industrial security operators and federal police forces generate dual demand streams as private accountability protocols replicate public standards. GDPR chain-of-custody frameworks mandate encrypted timestamping and audit trails that favor certified device vendors. Bavarian manufacturing clusters around Munich supply precision optical components to upstream camera assembly operations.
Japan
Tokyo Metropolitan Bureau of Transportation mandates continuous recording following passenger violence incidents on subway lines. METI standards guide domestic procurement specifications for ruggedized hardware. Osaka-based electronics fabricators specialize in CMOS image sensor miniaturization for compact form factor requirements.
United Kingdom
Home Office procurement standards enforce 1080p resolution baselines that accelerate 720p legacy system replacement cycles. The UK Information Commissioner's Office regulates biometric data handling in facial recognition deployments. London metropolitan procurement aggregates volume across constabularies, reducing per-unit costs through unified fleet management.
Australia
Tactical police units deploy edge-computing cameras with on-device facial detection that flags persons of interest without continuous cellular connectivity. TGA-equivalent telecommunications compliance regulates spectrum allocation for body worn camera transmissions. Melbourne and Sydney anchor federal and state-level procurement coordination for unified evidence management architectures.
Global Body Worn Cameras Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure where premium positioning separates from volume manufacturing. The vendor base concentrates around integrated solution providers, specialized security hardware fabricators, and consumer electronics crossovers. Dominant competitive moves include cloud evidence management bundling and radio-system interoperability alliances. Strategic partnerships with municipal procurement departments and federal grant administrators determine market access velocity.
Within the integrated solution provider tier, Axon Enterprise Inc. and Motorola Solutions Inc. exemplify archetypes combining hardware, cloud storage, and technical support into single-source agreements. Panasonic Corporation occupies a position among diversified electronics conglomerates with ruggedized hardware specialization. Digital Ally Inc. represents mid-tier vendors competing through cost-optimized configurations for budget-constrained municipal departments. These anchors illustrate how competitive positioning depends on evidence management ecosystem control rather than hardware specifications alone.
| Leading Market Players |
|---|
| Axon Enterprise Inc. |
| Motorola Solutions Inc. |
| Digital Ally Inc. |
| Panasonic Corporation |
| WatchGuard Technologies Inc. |
| Reveal Media Ltd. |
| GoPro Inc. |
| Sony Corporation |
| LensLock Inc. |
| Others |
Supply & Pricing Matrix
Ninety-day component lead times for CMOS image sensors and lithium-ion power cells concentrate procurement leverage among Japanese and South Korean electronics fabricators, compressing margin buffers for downstream assembly operations while amplifying pricing power at the sensor tier. This inventory-to-pricing nexus forces vendors to pre-position working capital or absorb spot-market volatility, reshaping contract structures toward multi-year fleet agreements that smooth cost exposure.
Pricing Analysis
FCC Part 15 equipment authorization and GDPR chain-of-custody certification dictate the pricing tier structure across wireless-enabled body worn cameras. Three-tier pricing stratifies across premium infrared-GPS configurations, standard HD recording units, and economy wired dock-dependent systems. Price differentiation rests on FIPS 140-2 encryption validation timelines and cloud evidence management bundling. Cost compression in the economy tier intensifies as municipal departments consolidate vendor relationships. Private security contractors exhibit the highest price sensitivity, while tactical military procurement channels absorb premium positioning.
Supply Chain Analysis
Taiwan Strait shipping lanes and Shenzhen-Shezhen port congestion constitute critical chokepoints for CMOS sensor and solid-state storage module flows. Manufacturing gravity centers on China, Japan, and South Korea for image sensor fabrication, battery cell production, and precision optical component assembly. Raw material dependencies span rare earth elements for infrared LED illumination, cobalt for lithium-ion cathodes, and epoxy resins for IP67 sealant systems. Single-source vulnerability concentrates in Sony and Omnivision sensor supply. Distribution runs through direct municipal procurement channels, federal grant administrators, and specialized security equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Body worn cameras are transitioning from discrete hardware transactions to platform-economics ecosystems where cloud evidence management subscriptions and radio-system interoperability determine vendor lock-in. Motorola radio integration requirements and Axon cloud storage architectures illustrate how ecosystem control displaces unit-level competition.
For Market Incumbents: Consolidate cloud evidence management relationships through multi-year fleet management contracts that bundle hardware, storage, and technical support into single-source agreements. Deepen backward integration into CMOS sensor supply through strategic partnerships with Japanese and South Korean fabricators to buffer spot-market volatility. Defend against emerging AI-enabled redaction automation specialists by accelerating EU AI Act compliance certification timelines.
For New Entrants and Emerging Players: AI-enabled biometric data masking services represent the most penetrable white-space where incumbents under-serve GDPR-mandated compliance workflows. Target German industrial security operators and private facility managers adopting accountability protocols previously limited to public agencies. Pursue channel partnerships with municipal procurement consultants who navigate federal grant program administration.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because evidence management subscriptions and firmware update cycles generate durable cash flows beyond hardware replacement cycles. Acquisition targets should emphasize vendors with FIPS 140-2 validated encryption modules and established municipal procurement relationships. Monitor EU AI Act certification timelines as the critical inflection signal for facial recognition feature rollouts.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Evidence Management Platform Integration | Axon and Motorola bundle storage, chain-of-custody tools, and technical support into municipal contracts. |
| Radio System Interoperability Certification | Motorola Solutions leverages existing public safety communications relationships to secure cross-agency deployments. |
| EU AI Act Compliance Certification | Reveal Media and WatchGuard Technologies redirect R&D investment toward audio analytics pending facial recognition approval. |
| Edge Computing Silicon Integration | Australian tactical units deploy on-device facial detection that flags persons of interest without cellular connectivity. |
| Multi-Year Fleet Management Contracting | Chicago and Los Angeles metropolitan agencies replace discrete capital purchases with unified procurement aggregation. |
Research Methodology
Initial hypotheses were tested against primary input from police department procurement officers, evidence management IT directors, federal grant administrators, and private security operations managers, then refined through secondary validation. Primary fieldwork encompassed structured interviews with municipal fleet managers in the United States, German industrial security operators, and Australian tactical unit commanders. Secondary sources included FCC equipment authorization databases, EU AI Act regulatory filings, Department of Justice grant disbursement records, and customs trade data for CMOS sensor import flows. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Variance decomposition across product type, technology tier, application segment, and end-user category anchored the analytical framework over the projection horizon. Segmentation modeling incorporated wireless upload architecture adoption curves, infrared night vision penetration in tactical channels, and private security vertical expansion rates. CAGRs derived from logistic diffusion curves fitted to replacement cycle data and procurement budget elasticity estimates. Forecast inputs encompassed federal grant program authorization levels, EU GDPR enforcement intensity indices, and lithium-ion cell price trajectories.
Forecasts assume regulatory continuity in FCC Part 15 spectrum allocation and EU AI Act risk classification frameworks; material policy shifts would require re-modeling wireless upload reliability assumptions and biometric feature deployment timelines. Practitioners should keep alternative scenarios live as cloud storage jurisdiction rulings and cross-border evidence admissibility standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Asia-Pacific Surveillance Storage Market
Video Surveillance Systems
Gunshot Detection System Market
Video Surveillance Systems
North America Crawler Camera System Market
Video Surveillance Systems
France Surveillance Camera Market
Video Surveillance Systems
Global CCTV Market
Video Surveillance Systems
Mexico Surveillance IP Camera Market
Video Surveillance Systems
India Surveillance Storage Market
Video Surveillance Systems
North America Video Surveillance Systems Market
Video Surveillance Systems
Smart Security Camera Market
Video Surveillance Systems
Latin America Surveillance Camera Market
Video Surveillance Systems
North America Surveillance IP Camera Market
Video Surveillance Systems
Brazil Surveillance IP Cameras Market
Video Surveillance Systems
Europe Video Surveillance Systems Market
Video Surveillance Systems
Security Cameras (IR Illuminator) Market
Video Surveillance Systems
Wearable and Body-Worn Cameras Market
Video Surveillance Systems
Night Vision Camera Market