
 Smart Doorbell Camera Market | 2026-2036
Smart Doorbell Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Doorbell Camera Market Outlook
Edge AI inference on doorbell hardware is reshaping how video analytics, facial recognition, and package detection are processed locally rather than in cloud data centers. Ring leverages its parent company's cloud infrastructure to sustain subscriber attachment rates for video storage services. Eufy differentiates through on-device storage architectures that minimize third-party data transmission. Arlo competes on battery-powered industrial design that extends installation flexibility beyond wired residential thresholds.
A smart doorbell camera integrates a wide-angle image sensor, passive infrared motion detector, two-way audio codec, and wireless transceiver into a weatherproof housing mounted at entry points; units typically stream 1080p to 2K resolution video at 15-30 frames per second to homeowner mobile applications, with primary commercial purpose centered on remote visitor verification, theft deterrence, and delivery monitoring. Wireless product variants lead volume shipments due to retrofit compatibility with legacy doorbell wiring, while Power over Ethernet technology captures margin pools in commercial and multifamily new construction where structured cabling is pre-installed. The residential end-user segment remains the largest addressable base, though retail and commercial installations are expanding fastest as loss-prevention departments upgrade analog intercom infrastructure.
FCC Part 15 regulations govern unlicensed radio frequency emissions for Wi-Fi and Bluetooth connectivity in the United States, while GDPR and the EU AI Act impose constraints on biometric data retention and automated decision-making for European deployments. CE marking under RED and RoHS directives further shapes hardware design cycles and material selection for manufacturers targeting European market access. Stakeholders must monitor evolving algorithmic accountability requirements that could mandate disclosure of on-device inference capabilities and data residency protocols.
Market Dynamics
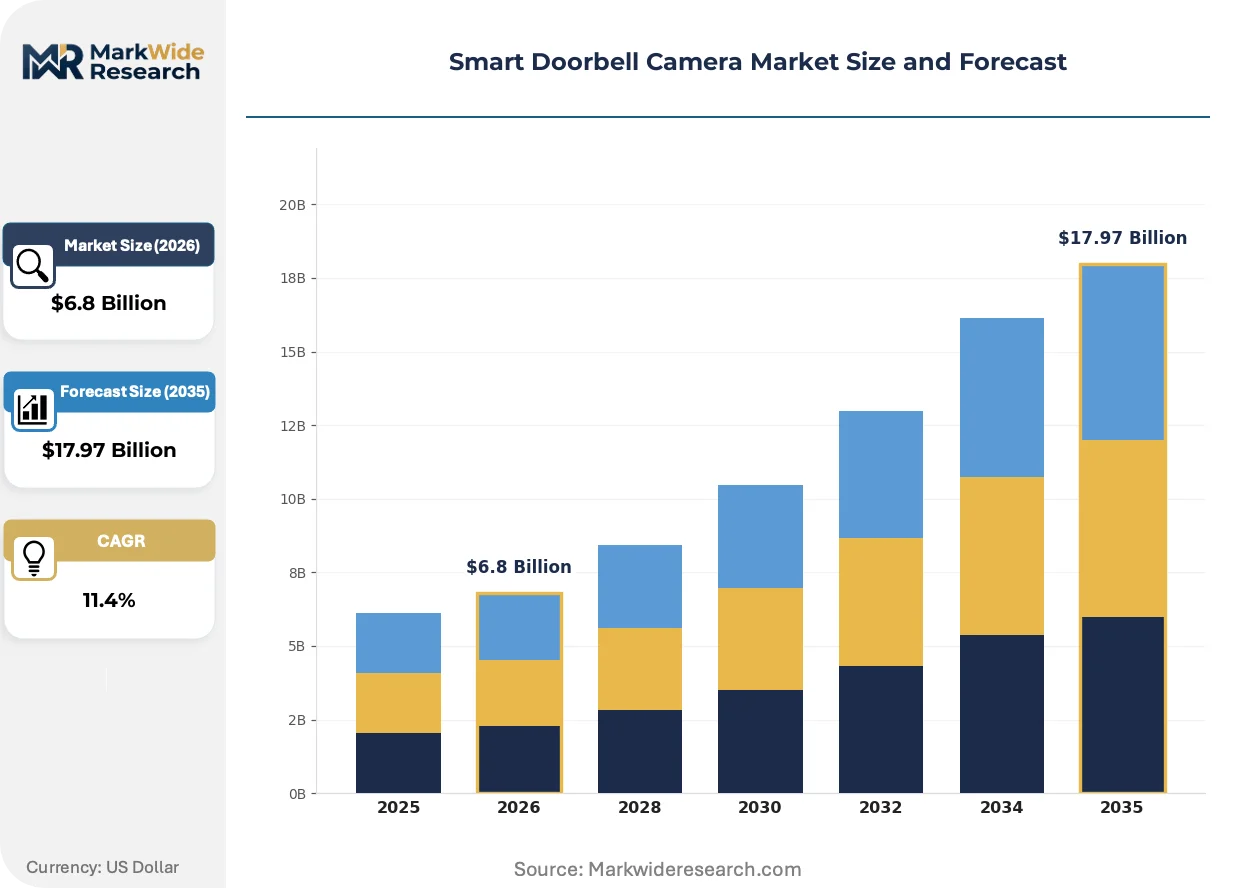
Edge AI inference is compressing cloud dependency for video analytics while FCC Part 15 and GDPR biometric constraints are elongating hardware certification cycles and fragmenting feature availability across jurisdictions.
Growth Catalysts
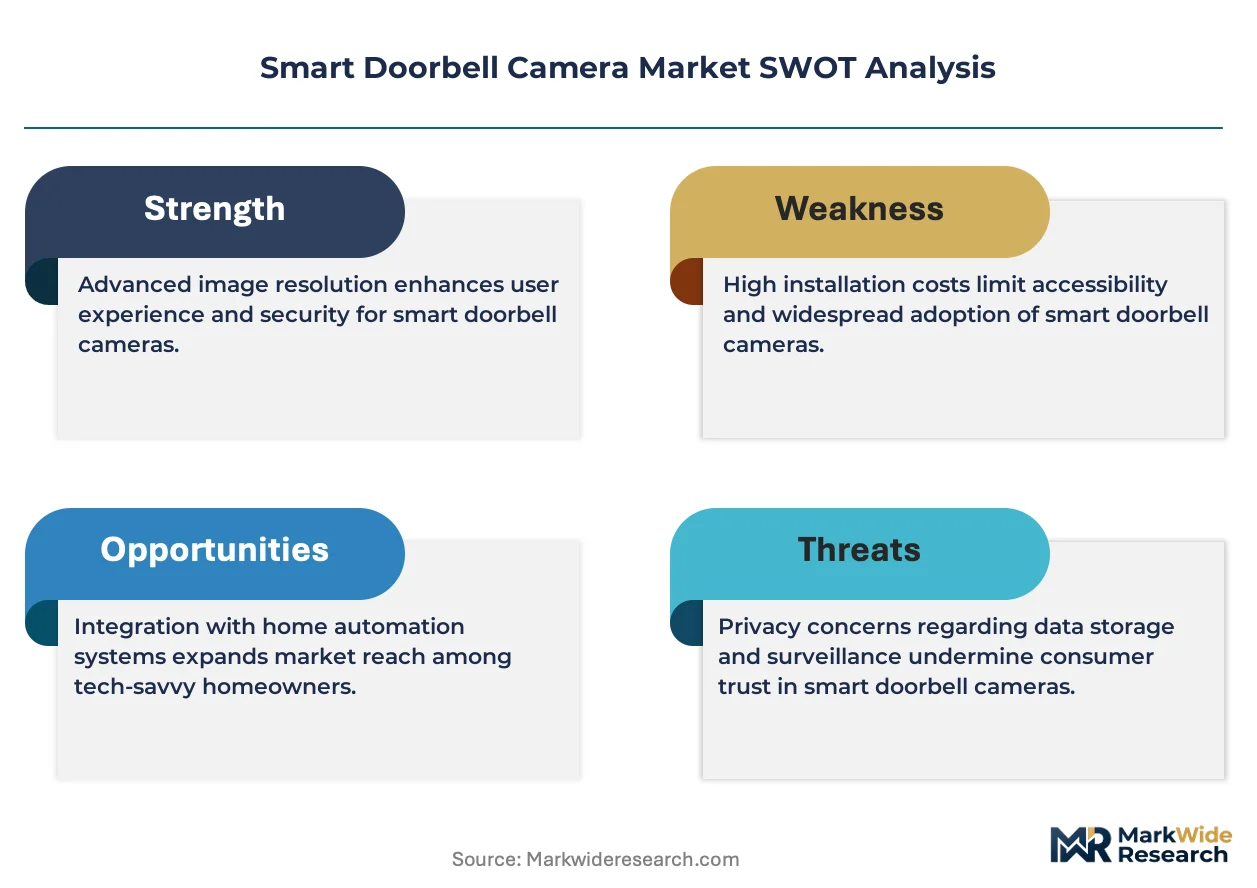
- Multi-unit residential retrofit demand:Property managers across aging housing stock in the United States and Germany are replacing analog intercoms with wireless video entry systems to reduce tenant turnover and package theft liability.
- CE marking under RED directive:Harmonized radio equipment standards are streamlining cross-border market access for OEMs, reducing duplicate testing costs for Wi-Fi 6 and Thread protocol implementations.
- On-device storage architectures:Local NAND flash and edge computing modules are eliminating recurring cloud subscription friction, appealing to privacy-conscious consumer segments in Northern Europe and Japan.
Market Restraints
- Image sensor supply concentration:Sony and OmniVision dominate CMOS supply for 2K resolution modules, creating vulnerability to foundry allocation shifts in Taiwan and South Korea.
- GDPR biometric data retention limits:Facial recognition feature sets must default to opt-in status in European deployments, complicating firmware versioning and increasing compliance engineering overhead.
- Legacy doorbell transformer incompatibility:North American homes built before 1980 often lack 16-24VAC wiring, forcing costly electrical upgrades or battery-dependent designs with shorter operational lifespans.
Strategic Opportunities
- Commercial loss-prevention upgrade cycles:Retail chains in the United Kingdom and Australia are replacing analog CCTV entry points with PoE doorbell systems integrated into centralized video management platforms.
- Matter protocol convergence:Thread and Wi-Fi interoperability standards are unifying smart home ecosystems, enabling doorbell cameras to trigger lighting and HVAC automations without proprietary hub dependencies.
- India PLI scheme for electronics manufacturing:Production-linked incentives are attracting EMS providers to establish local assembly for export markets, reducing landed cost exposure to ocean freight volatility.
Industry Challenges
- FCC Part 15 certification timelines:Unlicensed radio emission testing for new Wi-Fi 6E and 6GHz variants is extending hardware release cycles by four to six months, compressing competitive windows.
- Edge AI model optimization expertise:Firmware engineering teams face scarcity in TensorFlow Lite and ONNX runtime specialists capable of deploying facial recognition on sub-2W thermal envelopes.
- PoE installation skill gaps:Commercial contractors in fragmented metropolitan markets lack training in structured cabling termination and network switch configuration for integrated video-intercom deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Doorbell Camera Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless, Wired, Battery-Powered, Video Intercom Technology: Wi-Fi, Bluetooth, Power over Ethernet, Motion Detection End User: Residential, Commercial, Retail, Multifamily Installation Type: DIY, Professional, Integrated Systems, Smart Home |
| Companies Covered | SimpliSafe, Wyze, Ring, Logitech, Eufy, Nest, ADT, Lorex, Arlo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Doorbell Camera Market Strategic Shifts
Video analytics processing is migrating from centralized cloud infrastructure to doorbell-mounted compute modules, compressing latency and reshaping subscription revenue models across residential and commercial segments.
Local neural processing units are hybridizing cloud-dependent architectures. These dedicated inference engines execute package detection and person classification without transmitting raw video streams. Multifamily housing operators in Germany and the Netherlands are prioritizing on-device processing to satisfy tenant data sovereignty expectations. The shift is compressing recurring storage subscription attach rates while expanding upfront hardware margin pools.
The EU AI Act's risk classification framework is restructuring biometric feature deployment. Automated facial recognition systems fall under high-risk categorization, mandating conformity assessments and human oversight protocols. European OEMs are responding by disabling persistent facial databases and limiting retention to transient motion-triggered snapshots. Hardware vendors targeting France and Italy must now document algorithmic accountability measures in technical files submitted to notified bodies.
Property technology procurement is consolidating through integrated building management platforms. Facilities managers in Singapore and the United Arab Emirates are specifying doorbell cameras as edge nodes within unified access control and energy management dashboards. Channel relationships are shifting from consumer electronics retail toward commercial security integrators with certified installation networks. This rotation is elevating technical support and API documentation requirements above consumer-oriented mobile application design.
Smart Doorbell Camera Market Segmentation
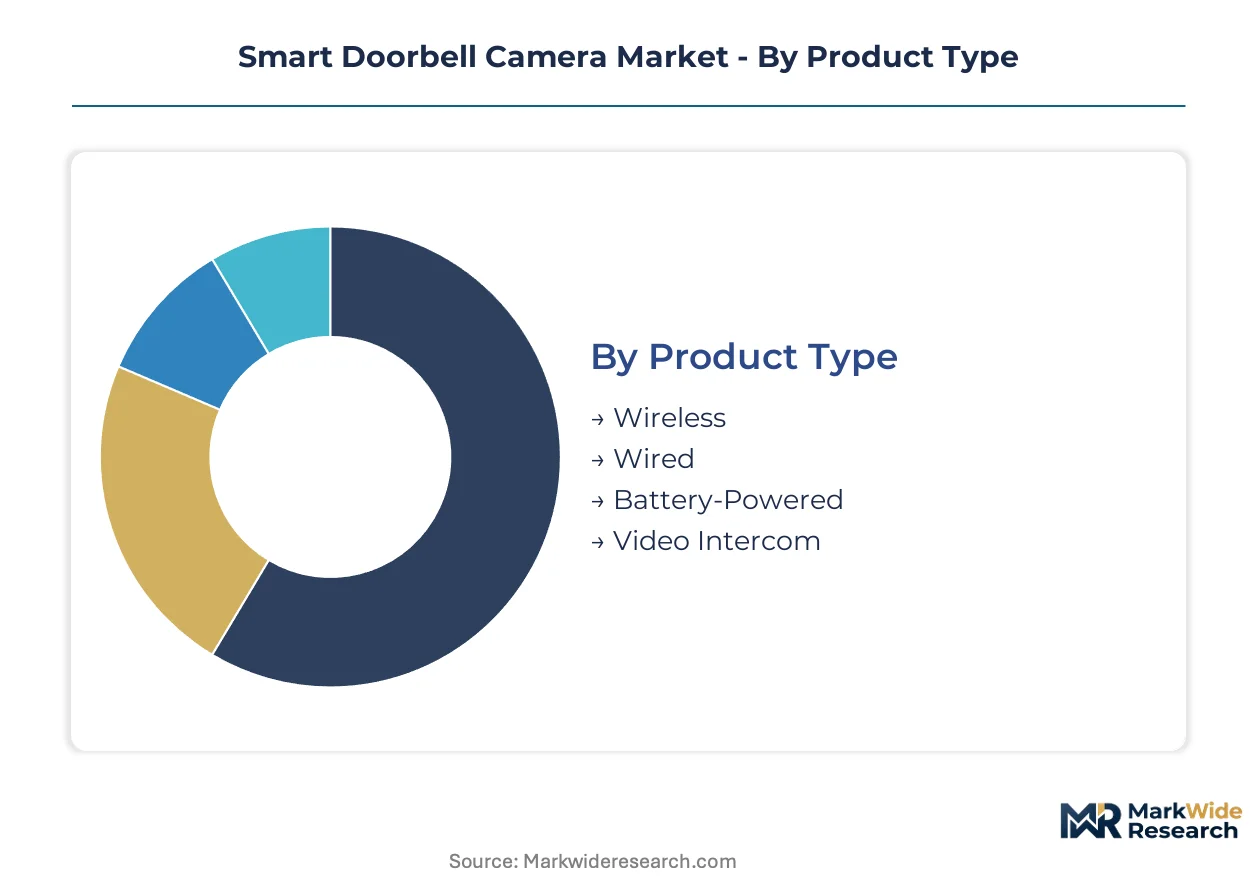
Smart doorbell camera segmentation reveals how installation constraints, connectivity protocols, and buyer sophistication reshape procurement patterns across residential retrofits and commercial security upgrades. Product architecture choices determine recurring revenue attachment, while technology selection governs latency performance and regulatory exposure.
Product Type:
Installation complexity and power availability divide the hardware landscape into retrofit-friendly versus infrastructure-dependent variants.
- Wireless:Battery or transformer-independent units transmit via 2.4GHz/5GHz Wi-Fi without dedicated cabling. Demand concentrates in United States pre-1980 housing stock where 16-24VAC doorbell wiring is absent, with property managers prioritizing tenant turnover reduction over electrical contractor dispatch.
- Wired:Continuous power from existing low-voltage doorbell circuits enables always-on streaming and eliminates battery maintenance cycles. Multifamily new construction in Germany and the Netherlands specifies wired architectures to satisfy tenant data sovereignty expectations through local edge processing.
- Battery-Powered:Lithium-ion cell architectures with 3-6 month recharge intervals target rental properties and heritage building facades where electrical modification is prohibited.
- Video Intercom:Multi-tenant entry systems with centralized indoor stations serve apartment complexes and gated communities requiring visitor screening before building access release.
Wireless holds installed capacity. Video Intercom is rotating up the share rankings.
Technology:
Connectivity protocol selection governs bandwidth allocation, installation topology, and cloud dependency architecture.
- Wi-Fi:IEEE 802.11ac/ax standards dominate residential deployments with 20-40Mbps upstream requirements for 2K resolution streaming. United Kingdom retail chains specify Wi-Fi 6E variants to minimize 2.4GHz congestion in dense urban commercial corridors.
- Bluetooth:Low-energy beacon protocols enable proximity-based arming and mobile device pairing for initial configuration without network credential exposure.
- Power over Ethernet:IEEE 802.3af/at standards deliver 15.4-30W over Cat5e/Cat6 cabling, powering edge AI inference modules without separate electrical runs. Singapore and United Arab Emirates facilities managers specify PoE for unified building management platform integration.
- Motion Detection:Passive infrared and radar-based occupancy sensing trigger recording buffers to conserve bandwidth and storage capacity.
Wi-Fi dominates unit economics. PoE is climbing the fastest as commercial specifications harden.
End User:
Buyer sophistication and procurement authority separate consumer self-service from enterprise security integration.
- Residential:Single-family homeowners prioritize mobile application simplicity and subscription-free storage options. Privacy-conscious segments in Northern Europe and Japan drive on-device NAND flash architectures that eliminate third-party data transmission.
- Commercial:Loss-prevention departments in Australia and United Kingdom retail chains replace analog CCTV entry points with centralized video management platform integration.
- Retail:Franchise operators require fleet-wide firmware management and API access for custom analytics overlay.
- Multifamily:Property technology platforms in Singapore consolidate doorbell cameras as edge nodes within unified access control and energy management dashboards.
Residential anchors volume throughput. Multifamily is gaining share fastest through integrated building procurement.
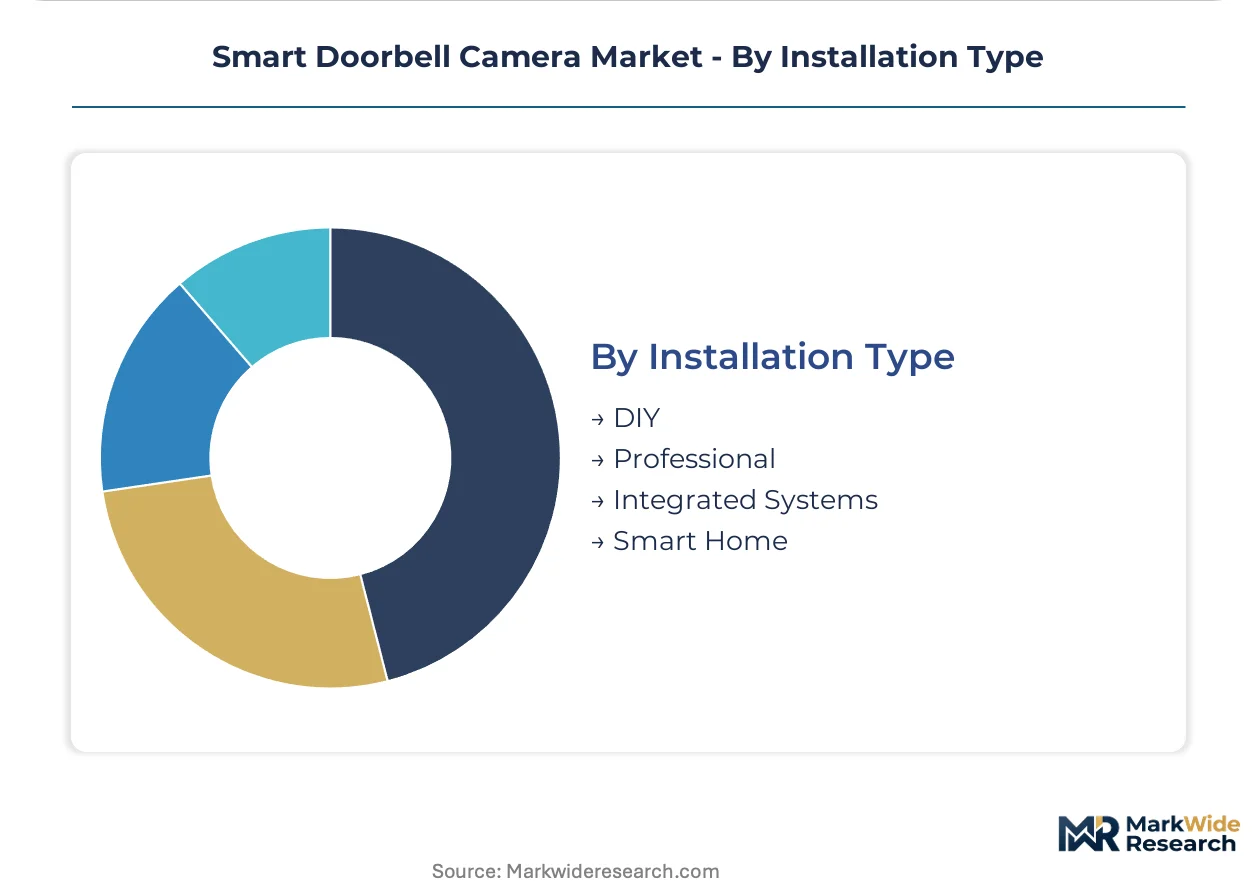
Installation Type:
Service model selection determines margin capture between hardware sale and recurring support revenue.
- DIY:Self-installation via adhesive mounts or existing doorbell screw terminals captures price-sensitive consumer segments through retail and direct-to-consumer channels.
- Professional:Certified technician deployment ensures optimal Wi-Fi signal strength and transformer compatibility, commanding 40-60% service premiums in North American suburban markets.
- Integrated Systems:Structured cabling termination and network switch configuration for PoE deployments requires commercial security integrator relationships with API documentation and technical support capabilities.
- Smart Home:Matter protocol convergence enables Thread and Wi-Fi interoperability without proprietary hub dependencies, triggering lighting and HVAC automations from doorbell motion events.
DIY commands unit velocity. Integrated Systems is rotating up the share rankings through commercial specification capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese OEM manufacturing clusters supply video streaming hardware to residential retrofit markets in Germany and the United States, establishing the dominant trade-flow corridor for doorbell camera assembly and component sourcing.
United States
Property managers across aging multifamily housing stock in Chicago and Philadelphia drive wireless video entry procurement to reduce package theft liability. FCC Part 15 certification requirements govern unlicensed radio emissions for Wi-Fi and Bluetooth connectivity, extending hardware release cycles for new 6GHz variants. Austin and Seattle tech corridors concentrate cloud infrastructure engineering talent supporting subscriber-based video storage architectures.
Germany
GDPR biometric data retention limits and the EU AI Act's high-risk classification for facial recognition systems reshape feature deployment in Berlin and Munich residential complexes. CE marking under the RED directive streamlines cross-border market access for Wi-Fi 6 and Thread protocol implementations. The Ruhr Valley industrial belt hosts EMS providers specializing in electromagnetic compliance testing for European market entry.
China
Domestic smart home ecosystem integration accelerates adoption in Shenzhen and Hangzhou, where OEM clusters manufacture 2K resolution CMOS modules for export markets. MIIT radio transmission standards and GB certification requirements shape hardware design cycles for Wi-Fi and Bluetooth implementations. The Yangtze River Delta concentration of foundry capacity produces image sensors for doorbell camera assembly across global supply chains.
Japan
Privacy-conscious consumer segments in Tokyo and Osaka prioritize on-device NAND flash storage architectures that eliminate third-party data transmission. METI standards for connected device interoperability influence Matter protocol adoption in residential installations. The Kansai region hosts precision electronics manufacturers supplying passive infrared motion detectors for regional OEM assembly.
Singapore
Facilities managers specify Power over Ethernet doorbell systems as edge nodes within unified building management platforms integrating access control and energy management. The country's national telecommunications regulator governs spectrum allocation for dense urban Wi-Fi deployments in commercial corridors. The Jurong industrial district concentrates EMS assembly for export markets across Southeast Asia and Australia.
Smart Doorbell Camera Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement authority between consumer retail, commercial security integrators, and property technology platforms. The vendor base organizes around three strategic archetypes: cloud-dependent subscription platforms, on-device storage privacy specialists, and battery-powered industrial design leaders. Consolidation pressure concentrates through M&A activity targeting video analytics capabilities and strategic partnerships with commercial security integrators requiring certified installation networks.
Within the cloud-platform archetype, Ring and Nest represent channel-controlling positions leveraging parent-company infrastructure for subscriber attachment. Eufy and Arlo occupy the product-specialist tier, with the former exemplifying on-device storage architectures and the latter representing battery-powered installation flexibility. SimpliSafe anchors the security-service-integrated position, while Wyze exemplifies price-accessible direct-to-consumer distribution. Logitech, Lorex, and ADT distribute across multiple archetypes depending on regional channel relationships.
| Leading Market Players |
|---|
| SimpliSafe |
| Wyze |
| Ring |
| Logitech |
| Eufy |
| Nest |
| ADT |
| Lorex |
| Arlo |
| Others |
Value Chain & Pricing Dynamics
Tariff exposure on Chinese-manufactured CMOS image sensors compresses margin structures across wireless and PoE product tiers while simultaneously reshaping procurement patterns toward South Korean and Japanese alternative sourcing. This dual pressure mechanism widens price spreads between premium on-device storage architectures and subscription-dependent economy offerings.
Pricing Analysis
Wi-Fi 6 versus Wi-Fi 5 versus Wi-Fi 6E generation gaps structure tiered pricing spreads across residential retrofit and commercial new-build segments. Three-tier pricing stratifies across premium edge-AI inference modules, standard cloud-dependent architectures, and economy battery-powered units lacking local storage. Price differentiation hinges on CE marking certification tier and NAND flash integration depth. Cost compression in economy wireless tiers intensifies due to transformer compatibility service bundling. DIY residential buyers in pre-1980 United States housing stock exhibit highest price sensitivity; Singapore facilities managers specifying unified building management platform integration show lowest.
Supply Chain Analysis
Export control restrictions on advanced semiconductor manufacturing equipment constrain foundry capacity allocation for neural processing units deployed in edge inference modules. Component sourcing draws from Taiwan for CMOS wafer fabrication, South Korea for NAND flash memory, and China for final assembly and electromagnetic compliance testing. Image sensor supply rests on Sony and OmniVision foundry commitments. Single-source vulnerability concentrates in 2K resolution module supply. Distribution runs through consumer electronics retail, commercial security integrators, and property technology platform procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a post-pandemic residential renovation recovery cycle propelled by multifamily property manager upgrade spending on package theft reduction infrastructure.
For Market Incumbents: Build switching cost moats through Matter protocol certification investments that lock proprietary hub architectures into interoperable smart home ecosystems. Deepen backward integration into edge AI model training pipelines to reduce TensorFlow Lite specialist scarcity exposure. Defend against battery-powered design specialists by expanding PoE commercial certification networks in Singapore and United Arab Emirates facilities management channels. For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme electronics manufacturing zones serving export markets with cost-optimized Wi-Fi 6 modules. Target German multifamily housing operators facing GDPR biometric compliance engineering overhead with pre-certified on-device storage architectures. Pursue white-label OEM relationships with Australian retail loss-prevention departments replacing analog CCTV entry points. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors video analytics capability acquisitions over hardware volume plays. Five-to-ten year viability hinges on edge AI inference IP ownership rather than cloud storage subscriber bases. Acquisition targets should demonstrate TensorFlow Lite deployment expertise and CE marking technical file documentation. Watch FCC Part 15 certification timeline extensions as inflection signal for competitive window compression.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Inference Module Development | Local neural processing units reduce GDPR cloud transmission exposure for European deployments. |
| Matter Protocol Certification Investment | Thread and Wi-Fi interoperability eliminates proprietary hub dependencies in smart home ecosystems. |
| CE Marking Technical File Expansion | RED directive compliance streamlines cross-border market access for Wi-Fi 6 and Thread implementations. |
| PoE Commercial Installer Network Buildout | Certified technician relationships capture integrated building management platform specifications. |
| On-Device NAND Flash Architecture Migration | Local storage eliminates recurring subscription friction in privacy-conscious Northern European segments. |
Study Parameters
The analysis maps wireless, wired, battery-powered, and video intercom product architectures, each validated through firmware engineering directors, commercial security integrators, property technology procurement leads, and cloud infrastructure product managers. Primary interview intelligence triangulates against FCC device certification databases, CE marking notified body registries, MIIT radio transmission filings, and hyperscaler smart home ecosystem partnership disclosures. Bottom-up unit shipment modeling cross-references top-down addressable housing stock calculations.
Fixed assumptions across the projection horizon include sustained Wi-Fi 6E spectrum allocation, stable GDPR biometric retention limits, and continued PLI scheme electronics manufacturing incentives. Segmentation dimensions span installation type, connectivity protocol, end-user sophistication tier, and regional regulatory cluster. CAGRs derive from housing formation rates, multifamily retrofit penetration curves, and commercial security upgrade cycle timing. Forecast inputs incorporate image sensor foundry capacity allocation shifts and Matter protocol adoption velocity.
Stress conditions across tariff rate volatility, Taiwan semiconductor supply disruption, and EU AI Act enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on housing stock age distribution and transformer wiring prevalence. Material shifts in FCC Part 15 6GHz certification timelines or India PLI scheme renewal terms would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Video Surveillance Software Market
Video Surveillance Systems
Latin America Video Surveillance Storage Market
Video Surveillance Systems
Japan Video Surveillance Market
Video Surveillance Systems
Cellular Interception Market
Video Surveillance Systems
North America Crawler Camera System Market
Video Surveillance Systems
Mexico Surveillance Camera Market
Video Surveillance Systems
Wearable and Body-Worn Cameras Market
Video Surveillance Systems
3D Surveillance Software Market
Video Surveillance Systems
Under-Vehicle Surveillance Market
Video Surveillance Systems
Canada Surveillance Camera Market
Video Surveillance Systems
Video Surveillance As a Service Market
Video Surveillance Systems
Asia-Pacific Surveillance Storage Market
Video Surveillance Systems
Smart Camera System Market
Video Surveillance Systems
Aircraft Video Surveillance Systems Market
Video Surveillance Systems
France Video Surveillance Market
Video Surveillance Systems
Latin America Surveillance Camera Market