
 North America Smart Home Security Cameras Market | 2026-2036
North America Smart Home Security Cameras Market Size, Share, and Industry Trends Forecast 2026-2036
North America Smart Home Security Cameras Market Intelligence
The UL 2900-2-3 cybersecurity certification standard for security and life safety signaling systems is collapsing the distinction between consumer-grade and professional-grade hardware. Ring leverages its direct-to-consumer model and brand recognition built on ease of installation. Arlo Technologies differentiates with a focus on battery-powered wireless cameras and advanced AI-based detection features. Honeywell International sustains its position through established professional installation channels and integration with broader smart home ecosystems.
North America smart home security cameras are network-connected video surveillance devices for residential and small business use. These systems typically feature 1080p to 4K resolution and utilize Wi-Fi for linking to mobile applications for remote viewing. Wireless cameras represent the fastest-growing product type due to their installation flexibility. Within the technology segment, cloud-based storage solutions are displacing local recording, creating recurring revenue opportunities for service providers.
In the United States, the Federal Communications Commission (FCC) governs the wireless spectrum used by these devices, while the Federal Trade Commission (FTC) enforces data security and privacy standards. Canadian regulations from Innovation, Science and Economic Development Canada (ISED) impose similar requirements on radio equipment certification. Future competitive advantage depends on a vendor's ability to demonstrate strong cybersecurity protocols and transparent data handling policies.
Market Dynamics
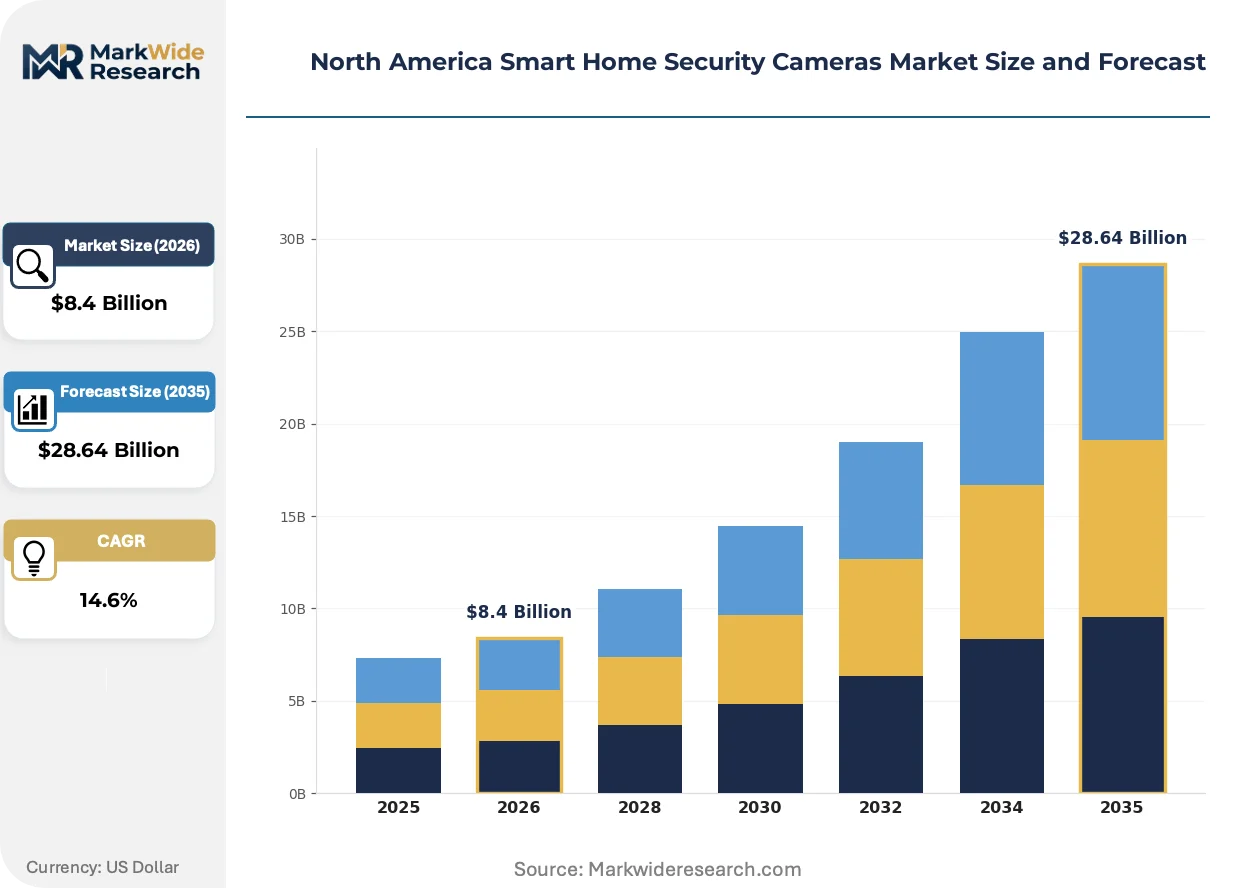
The North America smart home security camera market is defined by the dual pressures of expanding high-speed connectivity and rising cybersecurity mandates. The rollout of 5G networks enables advanced features, while standards like UL 2900-2-3 force vendors to elevate hardware security, blurring lines between consumer and professional tiers.
Growth Catalysts
- 5G Network Expansion:The proliferation of 5G infrastructure across the United States and Canada supports reliable, low-latency 4K video streaming and faster access to cloud-based storage, improving the user experience for high-resolution cameras.
- Residential Security Demand:Strong demand from the residential sector, particularly within suburban single-family homes, for enhanced property monitoring and theft deterrence continues to pull product into the market.
- Cybersecurity Standardization:The adoption of the UL 2900-2-3 standard provides a clear benchmark for cybersecurity, increasing consumer confidence and compelling manufacturers to build more secure hardware and software from the ground up.
Market Restraints
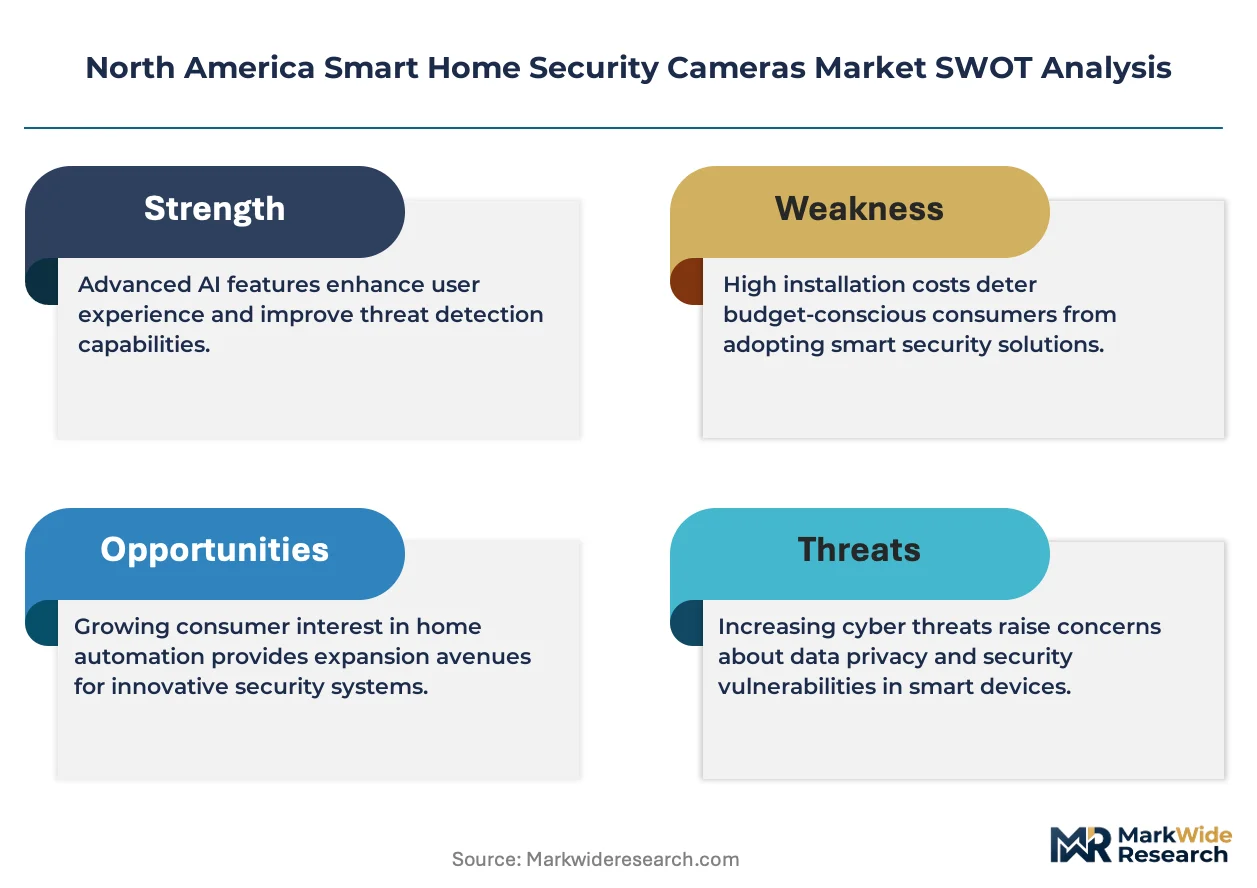
- Data Privacy Concerns:Consumer apprehension regarding data privacy and the potential for unauthorized access to video feeds acts as a significant barrier to adoption, especially following high-profile security breaches.
- High Bandwidth Requirements:The effective use of 4K and even 1080p cameras for continuous recording and cloud storage consumes substantial internet bandwidth, which can be a limiting factor in areas with poor connectivity.
- Subscription Cost Fatigue:While cloud storage creates recurring revenue, a growing consumer resistance to adding another monthly subscription for premium features can limit the uptake of advanced functionalities and services.
Strategic Opportunities
- Small Business Segment Penetration:The small and medium-sized business (SMB) segment represents an underpenetrated market for affordable, easy-to-install smart security camera systems for asset protection and operational oversight.
- Ecosystem Integration:Deepening integration with broader smart home ecosystems, including smart lighting, door locks, and voice assistants, offers a path to create more comprehensive and automated home security solutions.
- Insurance Partnerships:Collaborations with home insurance providers to offer premium discounts for homeowners who install certified smart security cameras can create a powerful incentive for new customer acquisition.
Industry Challenges
- Platform Interoperability:A lack of universal standards for interoperability creates a fragmented market where devices from different manufacturers often fail to work together seamlessly, complicating the user experience.
- Regulatory Compliance:Navigating the evolving data security and privacy regulations set by the FTC in the United States and ISED in Canada requires continuous investment in legal and technical compliance.
- Cloud Infrastructure Costs:Managing the immense and growing volume of video data stored in the cloud presents a significant operational and financial challenge for service providers, impacting service pricing and profitability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Smart Home Security Cameras Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $28.64 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome Cameras, Bullet Cameras, PTZ Cameras, Wireless Cameras Technology: Wi-Fi, Ethernet, Cloud-Based, Infrared End User: Residential, Small Business, Large Enterprise, Retail Distribution Channel: Online Retail, Direct Sales, Distributors, Retail Stores |
| Companies Covered | SimpliSafe, Ring, Samsung Electronics, Honeywell International, Nest Labs, Vivint Smart Home, Arlo Technologies, Brinks Home Security, ADT, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Smart Home Security Cameras Market Strategic Shifts & Innovations
Intelligence and proactive security are reshaping the market’s value proposition. The focus is shifting from passive video recording to systems that use AI to interpret events in real-time, providing users with actionable alerts and reducing the noise of irrelevant motion notifications.
On-device AI processing, powered by dedicated neural engine chipsets, enables sophisticated, real-time analysis of video feeds directly on the camera. The residential end-user segment is adopting this for more accurate person, package, and vehicle detection. This capability is bifurcating the market into basic cloud-dependent cameras and premium edge-computing devices that deliver faster alerts and enhanced privacy by minimizing data transmission.
The Federal Trade Commission (FTC) is intensifying its enforcement of data security standards for Internet of Things (IoT) devices. This regulatory pressure compels manufacturers to embed robust security features like end-to-end encryption and multi-factor authentication. The consumer-grade product segment is most affected, as vendors must now build in security protocols once reserved for professional systems to mitigate legal risks and maintain brand reputation.
A demand-side shift toward subscription-based services is altering revenue models away from one-time hardware sales. This unbundling allows vendors to offer tiered access to premium features such as extended cloud video history, advanced AI-powered analytics, and connections to professional monitoring centers. This trend is highly visible in the United States market, where recurring payment models for digital services have gained widespread consumer acceptance.
North America Smart Home Security Cameras Market Segmentation
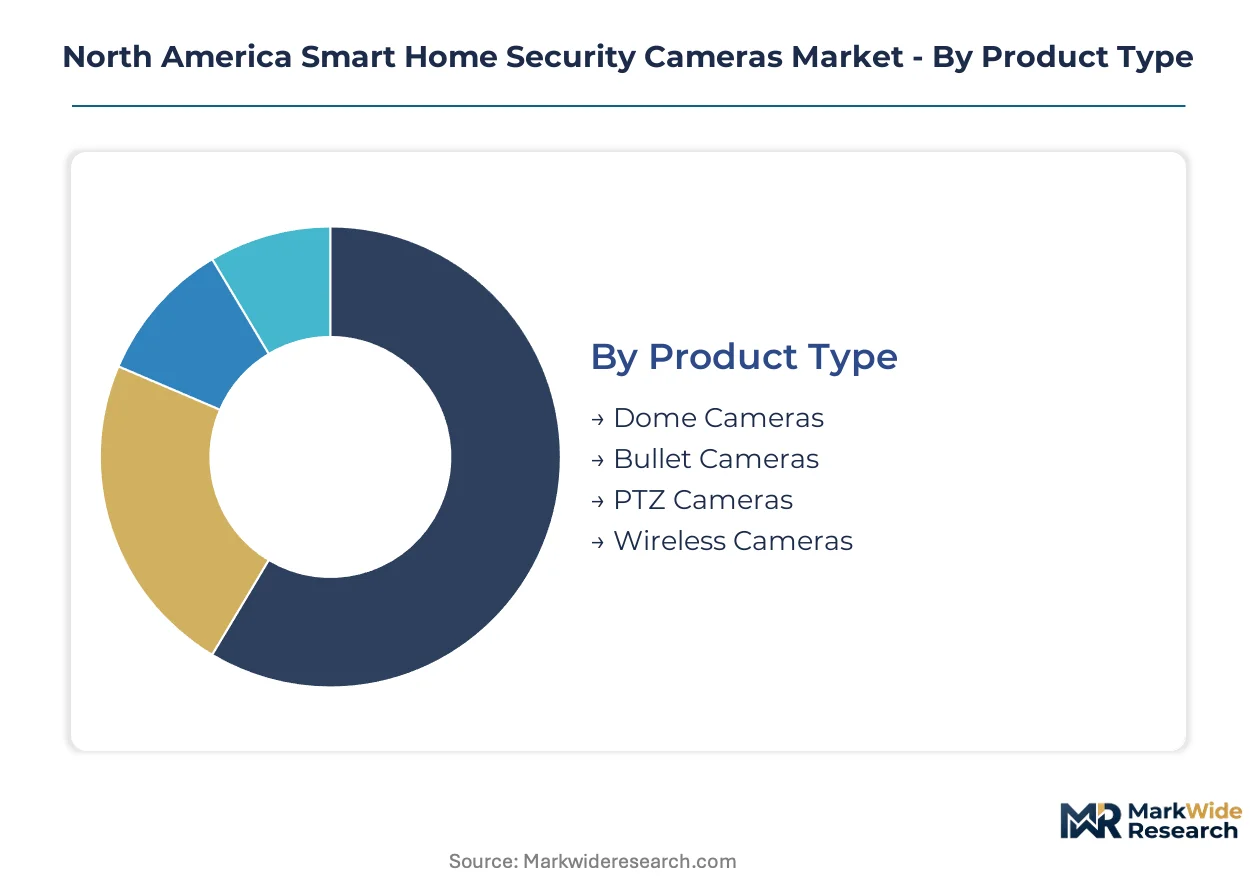
The North America smart home security cameras market exhibits distinct characteristics across its various segments, influencing product development and market penetration strategies. Understanding these divisions helps stakeholders identify key demand drivers and competitive dynamics. Each segment responds differently to technological advancements and consumer preferences.
Product Type:
Product type differentiation is increasingly driven by evolving cybersecurity regulations and installation flexibility across North America. Manufacturers are adapting designs to meet both performance and security benchmarks.
- Wireless Cameras:These devices operate without physical data cables, relying on Wi-Fi or cellular connectivity for data transmission and often battery power for operation. Residential end-users, particularly in suburban single-family homes, prioritize their ease of installation and flexible placement for enhanced property monitoring.
- Bullet Cameras:Characterized by their cylindrical shape and robust, often weather-resistant housing, bullet cameras are common for outdoor surveillance. Demand for these cameras remains strong in residential settings for visible deterrence and focused area monitoring, especially for front yards and driveways.
- Dome Cameras:Featuring a discreet, dome-shaped casing, these cameras offer a wide field of view and are often vandal-resistant, suitable for both indoor and outdoor use.
- PTZ Cameras:Pan-Tilt-Zoom cameras provide remote control over their viewing direction and optical zoom capabilities, enabling dynamic surveillance of larger areas.
Wireless Cameras handle the majority of throughput; Wireless Cameras are the fastest mover on share.
Technology:
Technological segmentation reflects the core functional capabilities and data handling methodologies integrated into smart home security cameras. These distinctions directly impact performance, privacy, and long-term operating costs for users.
- Cloud-Based:This technology stores video footage remotely on internet servers, offering accessible playback from anywhere and reducing the need for local storage hardware. Service providers generate recurring revenue from these subscriptions, which are increasingly adopted in the United States market for extended video history.
- Wi-Fi:Wi-Fi connectivity enables seamless integration of cameras into existing home networks, facilitating remote viewing and control via mobile applications. Its widespread availability and ease of setup drive significant adoption within the residential segment across North America.
- Ethernet:Ethernet-connected cameras provide a stable and secure wired connection, often preferred for installations requiring maximum reliability and bandwidth for high-resolution streaming.
- Infrared:Infrared technology allows cameras to capture clear video footage in low-light or complete darkness, essential for nighttime surveillance and enhanced security.
Cloud-Based solutions are gaining significant market traction, while Wi-Fi connectivity remains foundational for most consumer devices.
End User:
Segmentation by end-user highlights the diverse requirements and purchasing behaviors of different customer groups for smart home security cameras. Each segment seeks specific features and deployment models.
- Residential:This segment includes homeowners and renters seeking to monitor their properties for security, package delivery, and general oversight. Strong demand from suburban single-family homes in the United States drives the market, prioritizing ease of installation and mobile accessibility.
- Small Business:Small and medium-sized businesses utilize these cameras for asset protection, employee monitoring, and operational oversight without requiring complex enterprise systems. This underpenetrated market represents a significant strategic opportunity for vendors offering affordable, easy-to-install solutions.
- Large Enterprise:Large enterprises typically require highly integrated, scalable surveillance systems with advanced analytics and centralized management, often beyond the scope of consumer-grade smart home cameras.
- Retail:Retail establishments deploy cameras for loss prevention, customer flow analysis, and employee safety, often demanding robust features and compliance with specific industry standards.
The Residential segment generates the largest volume, with the Small Business segment showing promising expansion.
Distribution Channel:
The distribution channels for smart home security cameras illustrate the various routes products take to reach end-consumers. These channels influence pricing, brand visibility, and customer support models.
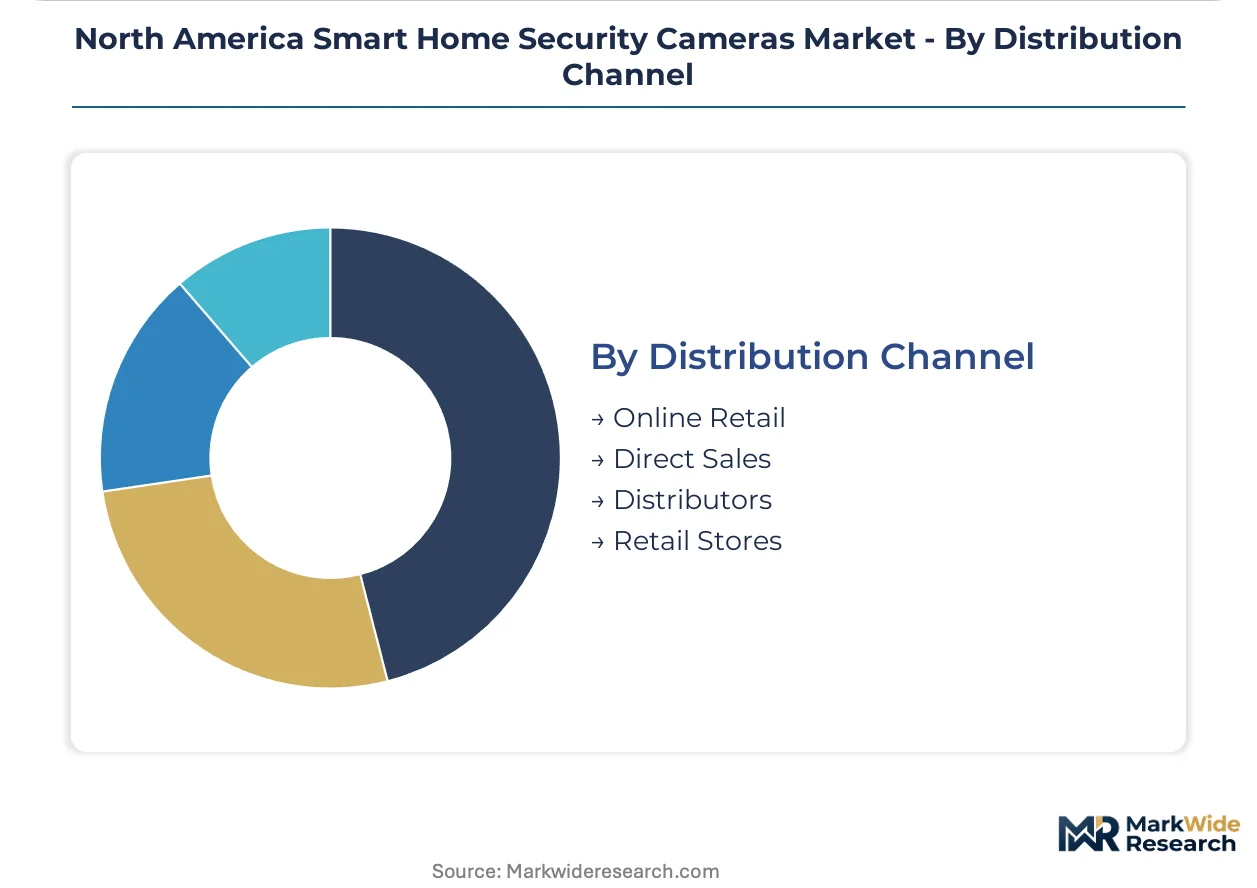
- Online Retail:E-commerce platforms provide broad market reach and convenience for consumers, offering extensive product choices and competitive pricing. This channel is particularly effective for direct-to-consumer brands leveraging strong brand recognition.
- Retail Stores:Physical retail outlets allow customers to experience products firsthand and receive in-person assistance, catering to those who prefer tangible interaction before purchase. Major electronics retailers in North America drive significant volume through this channel.
- Direct Sales:Manufacturers directly sell to consumers or businesses, often through their own websites or dedicated sales teams, allowing for greater control over branding and customer relationships.
- Distributors:Distributors act as intermediaries, purchasing products in bulk from manufacturers and then selling them to smaller retailers or installers, streamlining the supply chain.
Online Retail captures a substantial portion of sales, while Retail Stores maintain a strong presence for immediate customer access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North America smart home security cameras market is driven by a concentrated demand from residential end-users, particularly within suburban single-family homes. These consumers prioritize enhanced property monitoring and theft deterrence, seeking solutions that offer both ease of installation and robust security features. The region's advanced technological infrastructure supports the widespread adoption of these sophisticated devices.
United States (Residential)
Residential demand for smart home security cameras is strong across suburban areas for enhanced property monitoring and package delivery oversight. The Federal Trade Commission (FTC) enforces data security and privacy standards, compelling manufacturers to embed robust security features. Major metropolitan areas like Dallas and Atlanta exhibit concentrated demand for easy-to-install wireless systems due to high rates of new home construction.
United States (Small Business)
The small business segment in the United States represents a significant strategic opportunity for asset protection and operational oversight. The Federal Communications Commission (FCC) governs the wireless spectrum used by these devices, ensuring reliable connectivity. Emerging business districts in cities such as Denver and Austin show promising expansion for affordable, scalable camera solutions.
Canada
Canadian consumers exhibit strong demand for smart home security cameras, driven by a desire for enhanced home security and remote property management. Innovation, Science and Economic Development Canada (ISED) imposes strict requirements on radio equipment certification and data handling. Major urban centers like Toronto and Vancouver are hubs for smart home technology adoption, integrating cameras into broader ecosystems.
Mexico
Mexico's market for smart home security cameras is experiencing growth, fueled by increasing awareness of personal and property security needs. The Instituto Federal de Telecomunicaciones (IFT) regulates telecommunications and spectrum use, impacting device connectivity. Cities such as Mexico City and Monterrey demonstrate rising adoption rates, particularly for basic surveillance and remote monitoring capabilities.
North America Smart Home Security Cameras Market Key Industry Players
Player mix skews toward direct-to-consumer brands and established smart home ecosystem providers. The market structure is characterized by both specialized technology innovators and broader electronics conglomerates. Strategic archetypes include consumer-focused brands, professional-grade solution providers, and AI-driven hardware developers. Competitive moves center on ecosystem integration and expanding subscription-based service offerings.
Companies specializing in consumer-grade solutions, like Ring, leverage direct-to-consumer models and strong brand recognition built on ease of installation. Arlo Technologies exemplifies innovation with a focus on battery-powered wireless cameras and advanced AI-based detection features. Honeywell International sustains its position through established professional installation channels and deep integration with broader smart home ecosystems, serving both residential and commercial clients.
| Leading Market Players |
|---|
| SimpliSafe |
| Ring |
| Samsung Electronics |
| Honeywell International |
| Nest Labs |
| Vivint Smart Home |
| Arlo Technologies |
| Brinks Home Security |
| ADT |
| Others |
Cost & Logistics Intelligence
Expanded 5G network capacity and cloud infrastructure scale drive down per-unit data handling costs, shaping supply concentration and influencing price floors across the North America smart home security cameras market. This scale enables more affordable cloud-based storage solutions, impacting revenue models for service providers.
Pricing Analysis
Subscription-based models, offering tiered access to premium features like extended cloud video history and advanced AI analytics, form the dominant pricing structure. Price differentiation stems from certification levels, such as UL 2900-2-3 compliance, and the integration of advanced on-device AI for real-time detection. Pricing softness reflects increasing competition from direct-to-consumer brands and consumer resistance to multiple monthly subscriptions. The residential segment, particularly for basic surveillance, exhibits the highest price sensitivity, while small businesses may prioritize reliability over lowest cost.
Supply Chain Analysis
Rising inbound logistics costs, particularly for semiconductor components and camera modules, impact manufacturing expenses and final product pricing. Geographic supply concentrates in East Asian nations for specialized chipsets and electronic components, with assembly operations increasingly shifting to Mexico for North American distribution. Raw material dependencies include advanced image sensors, Wi-Fi connectivity modules, and secure memory solutions. Geopolitical tensions impacting semiconductor trade represent a significant structural risk. Distribution runs through a hybrid model combining online retail platforms, major physical electronics stores, and professional installation channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America smart home security cameras market presents a capability gap in advanced cybersecurity integration and AI-driven privacy solutions. This scarcity requires strategic investment to build consumer trust and meet evolving regulatory demands.
For Market Incumbents:Consolidate market share by acquiring specialized AI firms and cybersecurity solution providers to enhance product capabilities and meet UL 2900-2-3 standards. Deepen smart home ecosystem integrations with voice assistants and other IoT devices to create sticky user experiences, mitigating the threat of fragmented interoperability. Invest in professional installation networks to maintain channel control and differentiate from consumer-grade offerings.
For New Entrants and Emerging Players:A service-layer gap exists in affordable, privacy-centric solutions for the small business segment, which incumbents often under-serve. Target emerging business districts in cities like Denver and Austin with easy-to-install, scalable camera systems. A subscription-first go-to-market angle, emphasizing transparent data handling policies and robust cybersecurity, can attract privacy-conscious consumers and small business owners.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors AI-driven hardware developers and cybersecurity specialists with proven IoT security protocols. Long-term viability hinges on companies demonstrating strong data privacy compliance and seamless integration into broader smart home ecosystems. Acquisition targets should possess proprietary on-device AI processing capabilities or robust cloud security infrastructure. The growth in adoption rates of UL 2900-2-3 certified devices serves as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire AI-Driven Analytics Firms | This move enhances real-time event interpretation and reduces false alerts for end-users. |
| Deepen Smart Home Ecosystem Integration | This strategy creates more comprehensive and automated security solutions for residential customers. |
| Invest in UL 2900-2-3 Certification | This action builds consumer confidence and meets evolving cybersecurity mandates from the FTC. |
| Expand into Small Business Segment | This initiative taps into an underpenetrated market for affordable asset protection systems. |
| Develop Subscription-Based Monitoring Services | This approach shifts revenue models toward recurring income and offers tiered feature access. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and extensive secondary research anchors the qualitative findings. This approach ensures robust data integrity and contextual understanding across the North America smart home security cameras market.
Sensitivity analysis informs the forecast framework, evaluating market dynamics across the analysis window. Segmentation dimensions modeled include product type, technology, end-user, distribution channel, and regional adoption patterns within North America. CAGRs were derived from historical growth trends and projected market drivers, with 5G network penetration rates and smart home device interoperability standards serving as key forecast inputs.
Forecasts assume regulatory continuity in United States (FTC, FCC) and Canadian (ISED) regimes; material policy shifts would require re-modeling. These projections reflect current market conditions and anticipated technological advancements. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Wearable and Body-Worn Cameras Market
Video Surveillance Systems
Coastal Surveillance Systems Market
Video Surveillance Systems
Privacy Filters Market
Video Surveillance Systems
Europe Video Surveillance Systems Market
Video Surveillance Systems
Inspection Camera System Market
Video Surveillance Systems
Canada Surveillance IP Camera Market
Video Surveillance Systems
Night Vision Camera Market
Video Surveillance Systems
Integrated Video Surveillance Systems Market
Video Surveillance Systems
Global Night Vision System and Driver Monitoring System Market
Video Surveillance Systems
Brazil Surveillance IP Cameras Market
Video Surveillance Systems
Japan Surveillance Camera Market
Video Surveillance Systems
Global Video Surveillance Systems Market
Video Surveillance Systems
Aircraft Video Surveillance Systems Market
Video Surveillance Systems
Wireless Security Camera Market
Video Surveillance Systems
CCTV Camera Market
Video Surveillance Systems
People Counting System Market