
 Commercial Smoke Alarm Market | 2026-2036
Commercial Smoke Alarm Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Smoke Alarm Market Analytics
The EU Green Deal is decoupling legacy smoke alarm portfolios from future-proof building certifications across European commercial real estate. Honeywell International Inc. leverages its integrated building management platform to bundle detection with HVAC and access control, deepening account stickiness. Johnson Controls International plc anchors its position through captive fire safety distribution channels that bypass third-party installers. Hochiki Corporation specializes in high-sensitivity optical chambers for clean-room and data center environments where false-alarm tolerance sits near zero.
Commercial smoke alarms are self-contained fire detection devices that sense combustion byproducts through ionization, photoelectric, or multi-criteria sensing chambers and trigger audible and visual alerts plus building system integration signals. Photoelectric alarms dominate new commercial construction due to superior smoldering-fire detection and reduced false-alarm rates in dusty industrial settings. Smart alarms represent the fastest-expanding product category as cloud-connected devices enable remote diagnostics and predictive maintenance for facility managers overseeing distributed building portfolios. Hardwired installation types retain the largest revenue share among integrated systems in new builds, though wireless retrofits gain traction in historic structures where conduit runs prove cost-prohibitive.
The National Fire Protection Association (NFPA) 72 standard in the United States and the EU Construction Products Regulation (CPR) together enforce minimum response sensitivity and interoperability benchmarks that shape procurement specifications. The U.S. FDA does not regulate smoke alarms directly, but OSHA workplace safety mandates drive institutional purchasing in industrial facilities. Facility managers and building owners must monitor evolving smart building certification requirements that increasingly embed fire detection data into broader environmental health and safety dashboards.
Market Dynamics
Building decarbonization mandates across Germany, the United Kingdom, and the United States are forcing synchronous replacement of legacy fire detection infrastructure with smart, interconnected systems that feed environmental health dashboards.
Growth Catalysts
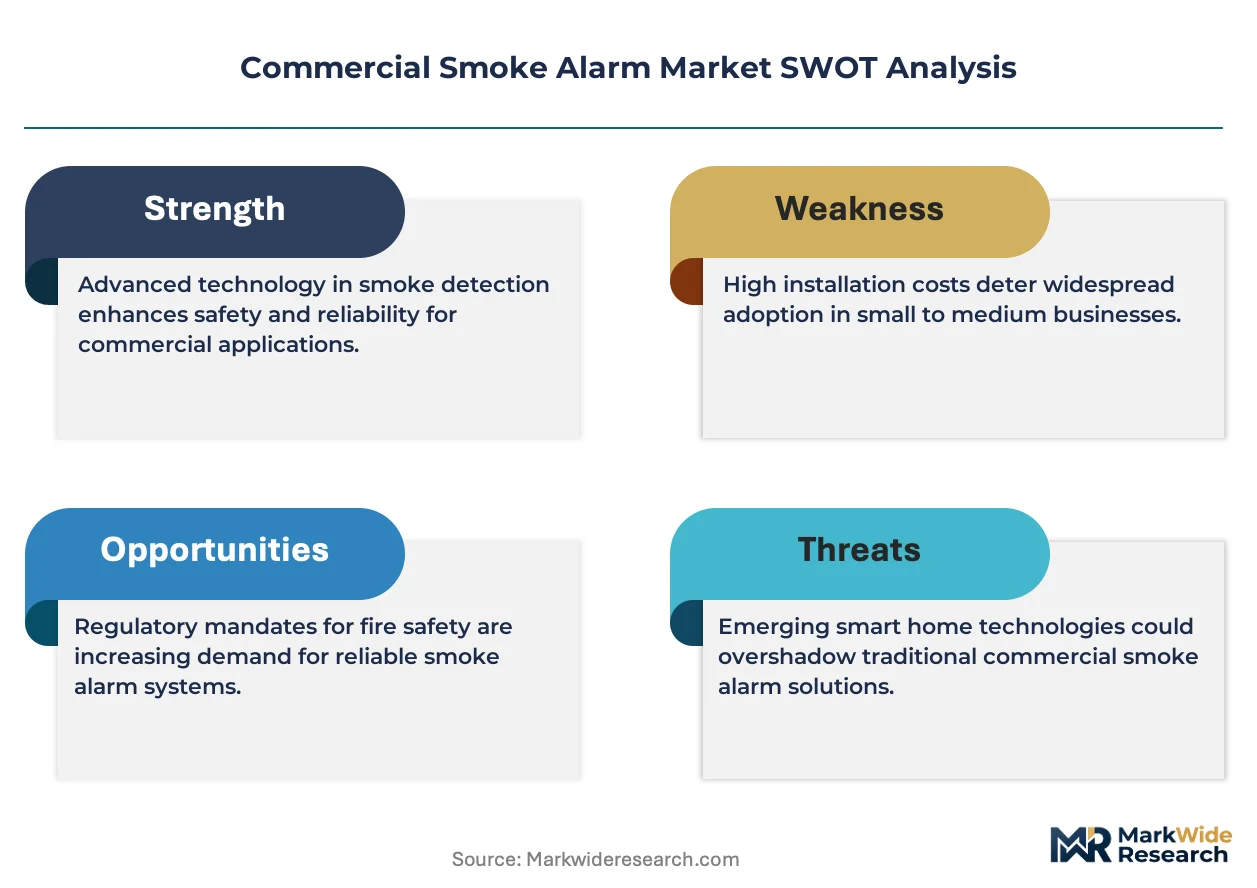
- EU Green Deal retrofit mandates:National building decarbonization codes in Germany and the United Kingdom accelerate replacement cycles for outdated detection systems in commercial real estate portfolios.
- Hospitality sector expansion:North American and European hotel chains are scaling fire safety retrofit programs across aging properties to meet stricter liability standards.
- Photoelectric sensing dominance:Superior smoldering-fire detection and reduced false-alarm rates in dusty industrial settings drive specification shifts in new commercial construction.
Market Restraints
- Semiconductor input volatility:MEMS sensors and wireless communication chipsets face supply concentration risks from East Asian foundries, inflating bill-of-materials unpredictability.
- Wireless retrofit cost barriers:Battery-powered smart alarms carry higher unit economics than hardwired alternatives, compressing margins in price-sensitive municipal and institutional procurement.
- Legacy system interoperability friction:Proprietary communication protocols from incumbent building management platforms create technical lock-in that slows third-party device integration.
Strategic Opportunities
- Historic building wireless penetration:United States preservation codes and European heritage restrictions prohibit conduit installation, creating captive demand for battery-powered mesh networks.
- Predictive maintenance service layers:Cloud-connected diagnostics enable recurring revenue streams from facility managers overseeing geographically distributed property portfolios.
- Clean-room specialization:Data center and pharmaceutical manufacturing environments demand high-sensitivity optical chambers with near-zero false-alarm tolerance.
Industry Challenges
- NFPA 72 and EU CPR synchronization:Divergent sensitivity and interoperability benchmarks between United States and European certification regimes force dual-sku product strategies.
- Cybersecurity integration complexity:Connected alarms must satisfy IEC 62443 industrial cybersecurity standards while maintaining real-time latency for life-safety applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Smoke Alarm Market |
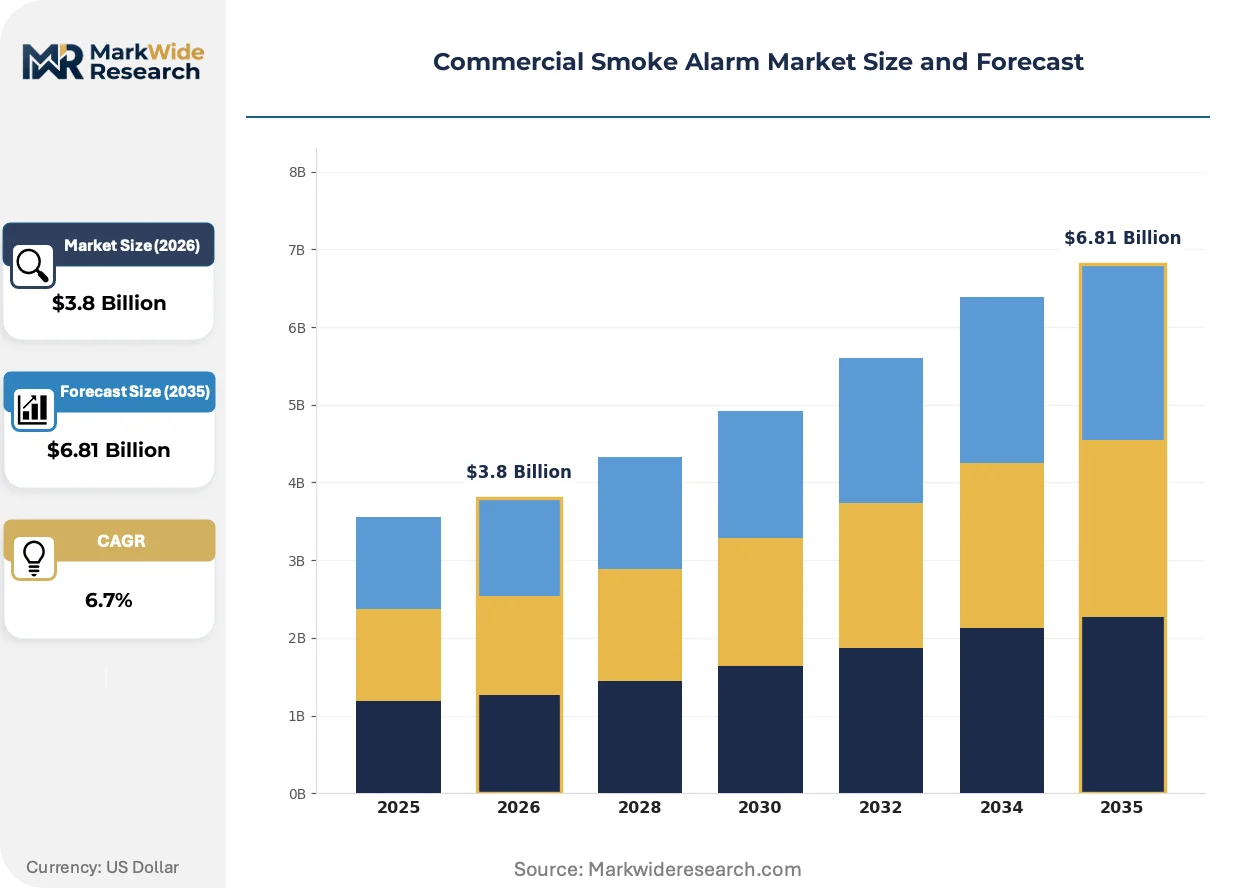
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ionization Alarms, Photoelectric Alarms, Dual-Sensor Alarms, Smart Alarms Installation Type: Hardwired, Battery-Powered, Wireless, Integrated Systems Application: Office Buildings, Industrial Facilities, Retail Stores, Educational Institutions End User: Facility Managers, Building Owners, Safety Officers, Emergency Responders |
| Companies Covered | Robert Bosch GmbH, Schneider Electric SE, Honeywell International Inc., Halma plc, Carrier Global Corporation, Johnson Controls International plc, Hochiki Corporation, Gentex Corporation, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Smoke Alarm Market Evolving Landscape
Edge computing architectures and mesh networking protocols are redistributing intelligence from central panels to distributed detection nodes, compressing response latency while enabling granular environmental monitoring.
Multi-criteria sensing chambers combining photoelectric and thermal detection is decentralizing alarm decision-making from building control centers to individual device nodes. Data center operators and pharmaceutical manufacturers are adopting these systems fastest, driven by zero-tolerance false-alarm requirements. Facility managers gain localized diagnostic visibility without centralized panel dependency, reducing infrastructure overhead.
REACH substance restrictions and RoHS hazardous material limits are tightening supply chains for ionization chamber components containing americium-241. European manufacturers are accelerating photoelectric platform development to preempt compliance-driven product obsolescence. Germany's Federal Institute for Materials Research and Testing is validating alternative sensing chemistries ahead of anticipated amendments.
Facility managers now specify outcome-based detection performance rather than device-centric procurement, unbundling hardware from monitoring services. Third-party integrators and managed service providers are displacing traditional electrical contractors in commercial retrofit channels. This pattern concentrates in United States multi-site retail and hospitality portfolios where centralized environmental dashboards command premium pricing.
Commercial Smoke Alarm Market Segmentation
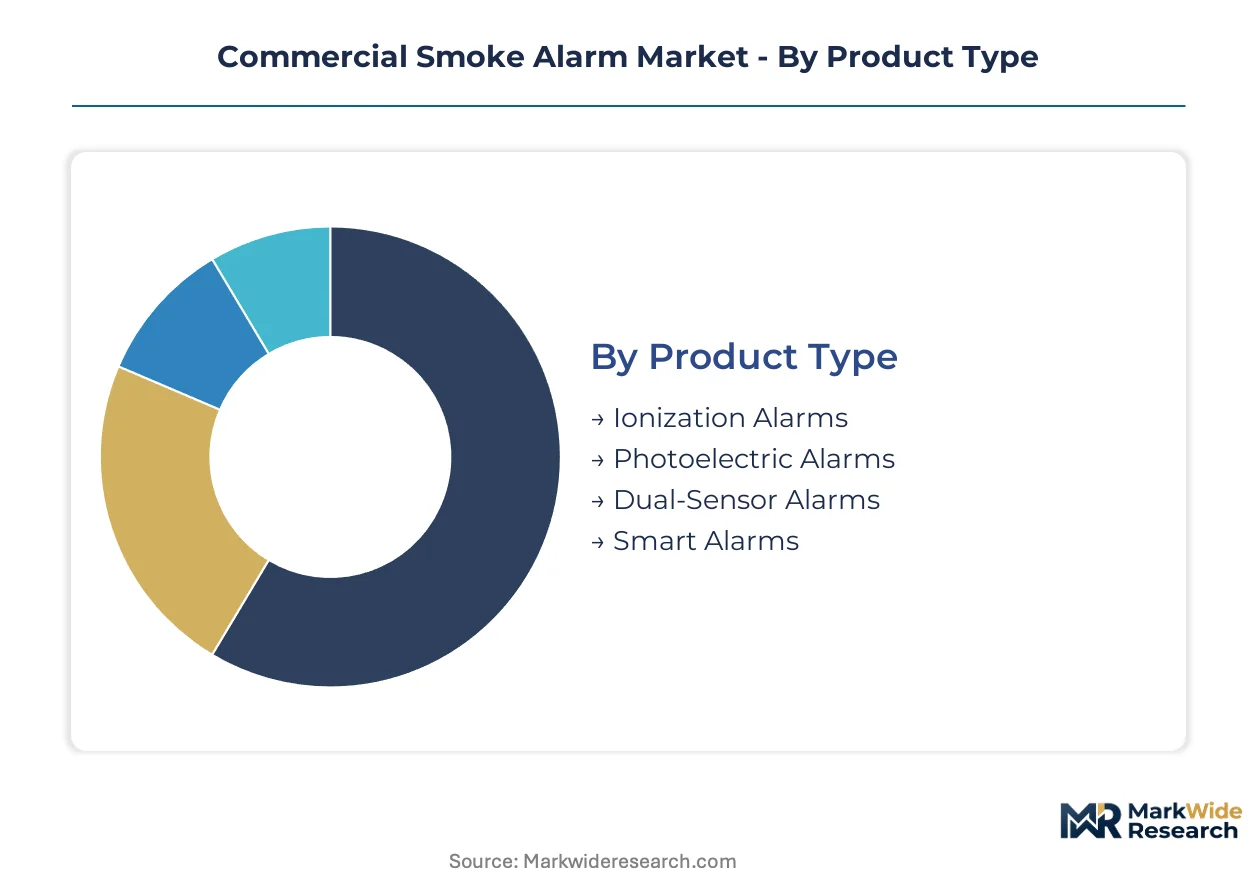
Commercial smoke alarm procurement splits across four structural dimensions that determine replacement cadence, installation economics, and compliance burden. Upgrade cycles vary sharply by product technology and building vintage, creating divergent revenue pools for manufacturers and integrators.
Product Type:
Replacement cycles accelerate where regulatory pressure intersects with sensing technology obsolescence, particularly as legacy ionization chambers face substance restrictions.
- Photoelectric Alarms:Optical sensing chambers detect smoldering fires through light-scatter measurement, eliminating americium-241 dependency. Demand concentrates in Germany and the United Kingdom where EU Green Deal retrofit mandates favor reduced-false-alarm specifications in commercial real estate portfolios.
- Smart Alarms:Cloud-connected devices embed mesh networking and edge diagnostics for predictive maintenance. The steepest expansion trajectory sits with facility managers overseeing distributed United States retail and hospitality portfolios requiring centralized environmental dashboards.
- Ionization Alarms:Americium-241-based chambers face REACH substance restriction pressure across European supply chains.
- Dual-Sensor Alarms:Combined photoelectric and thermal detection addresses zero-tolerance clean-room requirements in data center and pharmaceutical manufacturing environments.
Volume placements concentrate in photoelectric platforms; the faster expansion belongs to smart alarms.
Installation Type:
Cost tier differentiation separates new construction specifications from retrofit constraints where conduit access determines feasibility.
- Hardwired:Mains-powered devices with battery backup dominate new United States commercial construction under NFPA 72 integrated system requirements. Building owners in Texas and Florida specify these for liability standard compliance in multi-tenant office portfolios.
- Wireless:Battery-powered mesh networks circumvent heritage restrictions prohibiting structural modification. Historic building retrofit demand in Massachusetts and European preservation zones drives procurement where conduit runs prove cost-prohibitive.
- Battery-Powered:Standalone units serve transitional and temporary commercial installations with lower capital thresholds.
- Integrated Systems:Panel-connected architectures feed building management platforms for centralized monitoring.
Hardwired systems anchor revenue in new construction; wireless retrofits are gaining share fastest in constrained-access structures.
Application:
End-use maturity shapes specification intensity, with high-occupancy and high-liability settings demanding multi-criteria sensing and redundant communication paths.
- Office Buildings:Multi-tenant commercial properties require addressable detection networks with tenant-isolation capabilities. Facility managers in Chicago and London prioritize smart building certification compatibility for environmental health dashboard integration.
- Industrial Facilities:Dust-laden and high-vibration environments demand sealed optical chambers with reduced false-alarm tolerance. OSHA workplace safety mandates drive institutional purchasing across United States manufacturing zones.
- Educational Institutions:Campus-wide networks with mass notification integration serve K-12 and university portfolios.
- Retail Stores:Distributed footprints favor standardized, serviceable units for national chain consistency.
Industrial facilities lead specification complexity; office buildings provide the broadest volume base.
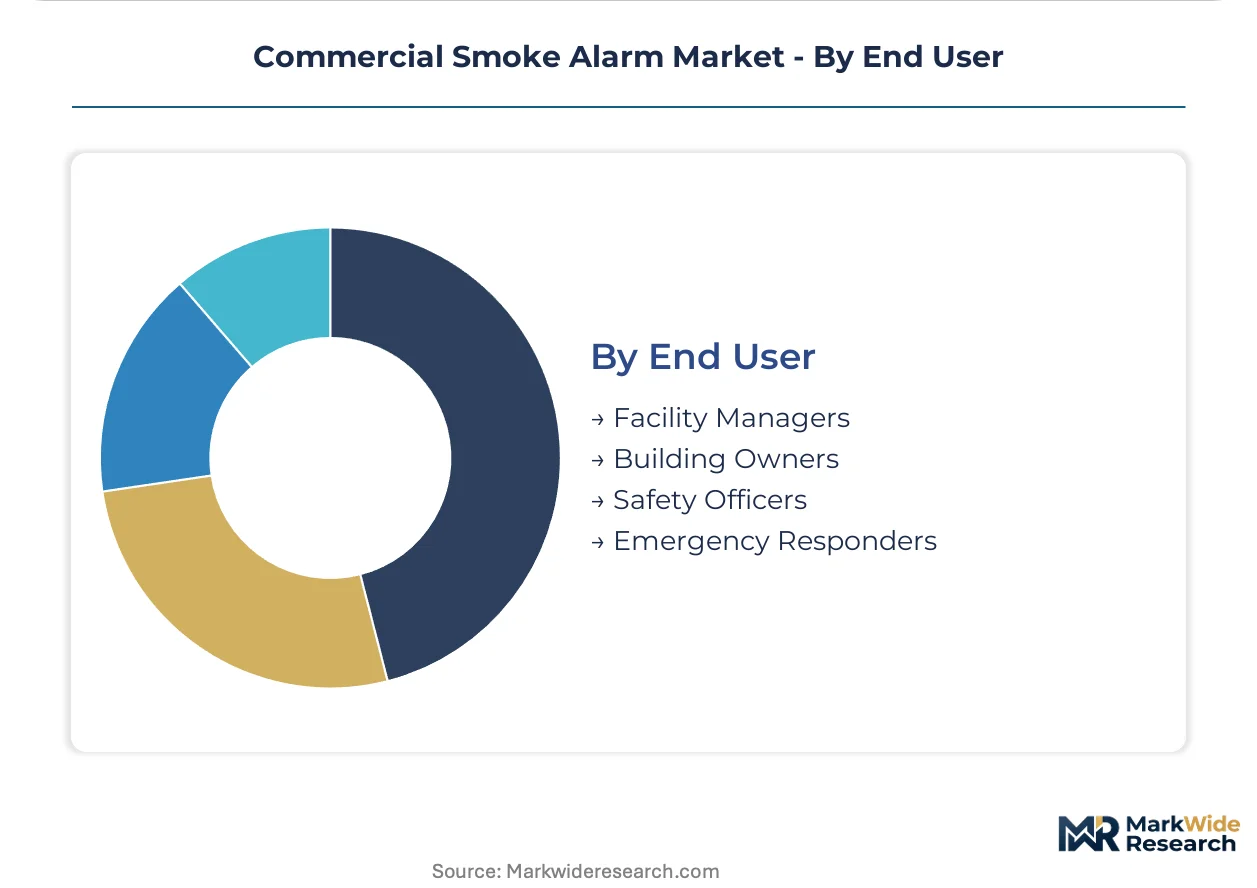
End User:
Procurement authority is shifting from traditional electrical contractors to outcome-based service purchasers with centralized portfolio oversight.
- Facility Managers:Operational decision-makers with multi-site accountability specify predictive maintenance service layers over hardware-centric procurement. United States hospitality and retail chains delegate fire safety to third-party integrators with dashboard capabilities.
- Building Owners:Asset holders face stricter liability standards across North America and Europe, accelerating replacement of legacy detection infrastructure in aging commercial real estate.
- Safety Officers:Compliance-focused roles mandate adherence to NFPA 72 and EU CPR sensitivity benchmarks.
- Emergency Responders:Municipal fire departments influence pre-incident planning specifications for signal transmission protocols.
Facility managers are displacing traditional contractors fastest; building owners retain capital allocation authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial smoke alarm procurement concentrates in Germany, the United Kingdom, and the United States where building decarbonization mandates and stricter liability standards force synchronous infrastructure replacement. Facility managers in these markets prioritize smart building certification compatibility and predictive maintenance capabilities.
United States
Hospitality chains and multi-tenant office portfolios drive retrofit demand across aging commercial real estate. OSHA workplace safety mandates enforce institutional purchasing in industrial zones. Texas and Florida building owners specify hardwired integrated systems under NFPA 72 for liability compliance.
Germany
Federal building decarbonization codes accelerate replacement cycles for legacy detection systems in commercial portfolios. The EU Green Deal and REACH substance restrictions push photoelectric platform adoption. Industrial clusters in Bavaria and North Rhine-Westphalia validate alternative sensing chemistries ahead of regulatory amendments.
United Kingdom
Heritage restrictions and preservation codes prohibit structural modification in historic buildings, creating captive demand for wireless mesh networks. National building decarbonization targets align with EU CPR interoperability benchmarks. London facility managers delegate fire safety to third-party integrators with centralized dashboard capabilities.
Japan
Data center operators and pharmaceutical manufacturers demand high-sensitivity optical chambers with near-zero false-alarm tolerance. METI industrial standards shape procurement specifications for clean-room environments. Tokyo and Osaka metropolitan areas lead smart building integration for environmental health monitoring.
China
Rapid commercial construction expansion in Yangtze River Delta and Pearl River Delta regions generates volume demand for photoelectric sensing platforms. GB standards and MIIT regulations enforce minimum response sensitivity for new builds. Shenzhen and Shanghai facility managers specify cloud-connected diagnostics for distributed property oversight.
Commercial Smoke Alarm Market Competitive Landscape
United States and European producers anchor one tier; Japanese specialists hold differentiated positions in high-sensitivity applications. The vendor base stratifies across integrated building management platforms, captive distribution channels, and component-level optical chamber suppliers. Three archetypes dominate: diversified industrial conglomerates with cross-selling capabilities, fire safety pure-plays with deep vertical expertise, and electronics specialists leveraging semiconductor integration. Competitive moves concentrate on bundling detection with HVAC and access control systems, plus predictive maintenance service layer expansion.
Among diversified industrial conglomerates, Honeywell International Inc. and Johnson Controls International plc exemplify platform-integration strategies. Hochiki Corporation occupies a specialist position in high-sensitivity optical chambers for clean-room and data center environments. These three anchors demonstrate how geographic origin and corporate structure shape competitive archetype selection.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Schneider Electric SE |
| Honeywell International Inc. |
| Halma plc |
| Carrier Global Corporation |
| Johnson Controls International plc |
| Hochiki Corporation |
| Gentex Corporation |
| Siemens AG |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists in Germany and Japan anchor premium pricing through captive optical chamber production, insulating themselves from commodity volatility while forcing price discipline on contract manufacturers dependent on East Asian MEMS sourcing.
Pricing Analysis
Short-lead-time premiums command pricing power for photoelectric platforms serving data center retrofit deadlines, while spot inventory of legacy ionization chambers trades at distressed levels. Three-tier pricing structure across NFPA 72-certified integrated systems, standard wireless mesh networks, and economy battery-powered standalone units differentiates by certification burden and after-sales service bundling. Cost compression in municipal procurement channels is intensifying because battery-powered smart alarms carry higher unit economics than hardwired alternatives. Facility managers overseeing distributed hospitality portfolios exhibit least price sensitivity, prioritizing predictive maintenance service layers; price-sensitive municipal buyers in Texas and Florida drive hardwired specification shifts.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale data center operator demand for high-sensitivity optical chambers, while electrical contractor networks and third-party integrators distribute wireless retrofit kits to historic building portfolios. Manufacturing concentrates in China for photoelectric sensing platforms, Germany for precision optical components, and Japan for clean-room-grade detection chambers. Raw material dependencies include americium-241 for legacy ionization chambers, MEMS sensors from Taiwanese foundries, and lithium battery cells for wireless mesh networks. Single-source vulnerability in East Asian semiconductor fabrication creates supply concentration risk for smart alarm chipsets. Distribution runs through captive fire safety channels that bypass traditional electrical contractors in North American commercial retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial smoke alarm market sits in a technology-transition phase as photoelectric and multi-criteria sensing chambers displace legacy ionization platforms facing REACH substance restrictions.
For Market Incumbents: Cement platform stickiness by bundling detection with HVAC and access control through integrated building management architectures, countering displacement by third-party integrators with predictive maintenance service layers. Deepen backward integration into optical chamber production to defend margin position against MEMS sensor cost volatility from East Asian foundries. Prioritize certification investment in dual NFPA 72 and EU CPR compliance to streamline product portfolios. For New Entrants and Emerging Players: Historic building facility managers in Massachusetts and European preservation zones represent an underserved buyer archetype with captive demand for wireless mesh networks where conduit installation is prohibited. Target clean-room specialization for data center and pharmaceutical manufacturing environments demanding near-zero false-alarm tolerance, where incumbent optical chamber suppliers hold limited penetration. Deploy outcome-based detection performance contracting to displace traditional electrical contractors in United States multi-site retail portfolios. For Investors and Strategic Acquirers: Distressed-cycle entries favor fire safety pure-plays with deep vertical expertise in Germany and the United Kingdom, where EU Green Deal retrofit mandates accelerate replacement cycles for legacy detection infrastructure. Long-term viability hinges on cloud-connected diagnostics capabilities and predictive maintenance service layer expansion across geographically distributed property portfolios. Watch for inflection signals in GB standards enforcement across Yangtze River Delta commercial construction as indicator of smart alarm specification intensity in emerging volume markets.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Service Layer Launch | Cloud-connected diagnostics enable recurring revenue from facility managers overseeing distributed United States hospitality portfolios. |
| Dual Certification Streamlining | Unified NFPA 72 and EU CPR product platforms reduce SKU complexity for manufacturers serving transatlantic commercial real estate. |
| Wireless Mesh Network Expansion | Battery-powered retrofit systems penetrate historic buildings in Massachusetts and European preservation zones where conduit runs are prohibited. |
| Optical Chamber Backward Integration | In-house production of high-sensitivity sensing components insulates margins from MEMS sensor volatility in East Asian supply chains. |
| Clean-Room Specialization Investment | Near-zero false-alarm detection systems capture premium positioning in Tokyo and Osaka data center and pharmaceutical manufacturing markets. |
Research Methodology
Independent corroboration across facility manager interviews, building owner procurement assessments, and third-party integrator channel audits underwrites the qualitative findings in this study. Primary fieldwork engaged fire safety directors, commercial real estate asset managers, electrical contractor purchasing leads, and regulatory compliance officers across Germany, the United Kingdom, and the United States. Secondary validation drew from NFPA 72 technical documentation, EU Construction Products Regulation filings, OSHA workplace safety enforcement data, and commercial building permit databases. Bottom-up unit placement estimates triangulated against top-down construction spending allocations across office, hospitality, and industrial verticals.
Historical reference periods spanning pre-pandemic baseline, retrofit acceleration phases, and smart building certification emergence anchored the projection framework. The analytical model segmented by product technology, installation type, application intensity, and end-user procurement authority across the analysis window. CAGRs derived from replacement cycle modeling, regulatory mandate implementation timelines, and sensing technology substitution curves. Forecast inputs incorporated EU Green Deal decarbonization code enforcement trajectories and REACH substance restriction phase-out schedules for americium-241 components.
Revisions become necessary when semiconductor supply concentration shifts, cybersecurity standard amendments, or building decarbonization code accelerations materialize beyond modeled assumptions. Forecasts reflect base-case assumptions regarding regulatory synchronization and technology substitution rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Fire Alarm and Detection System Market
Fire Safety & Protection
UAE Fire Protection System Market
Fire Safety & Protection
Fire Extinguisher Market
Fire Safety & Protection
Fire Resistant Glass Market
Fire Safety & Protection
Smart Smoke Detector Market
Fire Safety & Protection
High Pressure Fixed Firefighting Misting System Market
Fire Safety & Protection
US Fire Alarm and Detection Market
Fire Safety & Protection
Laser Smoke Detector Market
Fire Safety & Protection
Wireless Fire Detection Systems Market
Fire Safety & Protection
Global Flame Arrestors Market
Fire Safety & Protection
Fire Suppression Agent Market
Fire Safety & Protection
Fire and Rescue Helmets Market
Fire Safety & Protection
Smoke Pressure System Market
Fire Safety & Protection
Australia Emergency Lighting Market
Fire Safety & Protection
Fire Rated Cables Market
Fire Safety & Protection
United States Fire Sprinklers Market