
 United Kingdom Surveillance Camera Market | 2026-2036
United Kingdom Surveillance Camera Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Surveillance Camera Market Insights
UK-based security integrators and component suppliers is rebalancing production schedules to address backlogs in IP-based system deployments. Bosch Security and Safety Systems anchors its position through deep manufacturing scale across European assembly plants. Axis Communications AB differentiates via open-platform software ecosystems that reduce vendor lock-in for British end users. Hangzhou Hikvision Digital Technology Co Ltd competes aggressively on cost-optimized dome and bullet camera lines sold through UK distribution channels.
Surveillance cameras in the United Kingdom encompass fixed and pan-tilt-zoom imaging devices that capture, process, and transmit video for security monitoring, typically operating at resolutions from 1080p to 4K with infrared night-vision capability and edge-based analytics processing. These systems serve law enforcement, commercial property managers, and transport operators seeking real-time situational awareness and post-incident forensic review. IP cameras and IP-Based technology configurations capture expanding margin pools as analog infrastructure ages out of service across British public sector estates. Dome cameras retain dominance in indoor retail and healthcare settings where vandal resistance and discreet positioning matter, while PTZ cameras lead in transportation hubs requiring operator-controlled sweep coverage.
The Surveillance Camera Commissioner enforces the National Surveillance Camera Strategy, which mandates encryption, data retention limits, and public signage for all operational systems in England and Wales. The Investigatory Powers Act and GDPR compliance requirements from the Information Commissioner's Office shape how footage is stored, accessed, and shared with police forces. The Health and Safety Executive influences camera placement in industrial workplaces through duty-of-care obligations. Stakeholders must monitor pending amendments to the Data Protection and Digital Information Bill that could relax certain processing constraints while tightening accountability for biometric analytics deployments.
Market Dynamics
The migration from analog to IP-based surveillance infrastructure across British public estates is compressing replacement cycles and redrawing supplier relationships as local authorities consolidate procurement frameworks.
Growth Catalysts
- Transport network modernization:London Underground, Manchester Metrolink, and Birmingham New Street are deploying edge-analytics cameras for real-time crowd flow management and automated incident detection.
- Surveillance Camera Commissioner mandates:The National Surveillance Camera Strategy requires encryption and data retention limits, forcing upgrades of legacy systems and expanding addressable market for compliant hardware.
- Retail corridor densification:Urban commercial zones in Leeds, Liverpool, and Glasgow are installing integrated video-analytic networks to reduce shoplifting and optimize footfall analysis.
Market Restraints
- Semiconductor input volatility:Image sensor and SoC shortages have extended lead times for IP camera deliveries, constraining deployment schedules for NHS trusts and university estates.
- GDPR compliance friction:The Information Commissioner's Office biometric guidance creates legal uncertainty for facial recognition deployments, delaying pilot programs in policing and border control.
- Cloud storage substitution:On-premise NVR installations face displacement from subscription-based cloud video management platforms that shift capital expenditure to operational budgets.
Strategic Opportunities
- Scottish healthcare estates:NHS Scotland hospital networks remain underpenetrated by advanced video analytics, presenting first-mover advantage for patient safety and fall-detection applications.
- Welsh critical infrastructure:Port of Milford Haven and energy transmission sites require hardened camera systems for perimeter intrusion detection under updated CPNI guidelines.
- AI-biometric convergence:Integration of thermal imaging with behavioral analytics opens new service contracts for stadium operators and event venues seeking automated threat assessment.
Industry Challenges
- Cybersecurity certification backlog:NCSC Cyber Essentials Plus accreditation delays are slowing procurement approvals for police forces and government departments.
- Legacy coaxial integration:Hybrid analog-digital environments in Victorian-era public buildings create interoperability failures and inflated commissioning costs for integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Surveillance Camera Market |
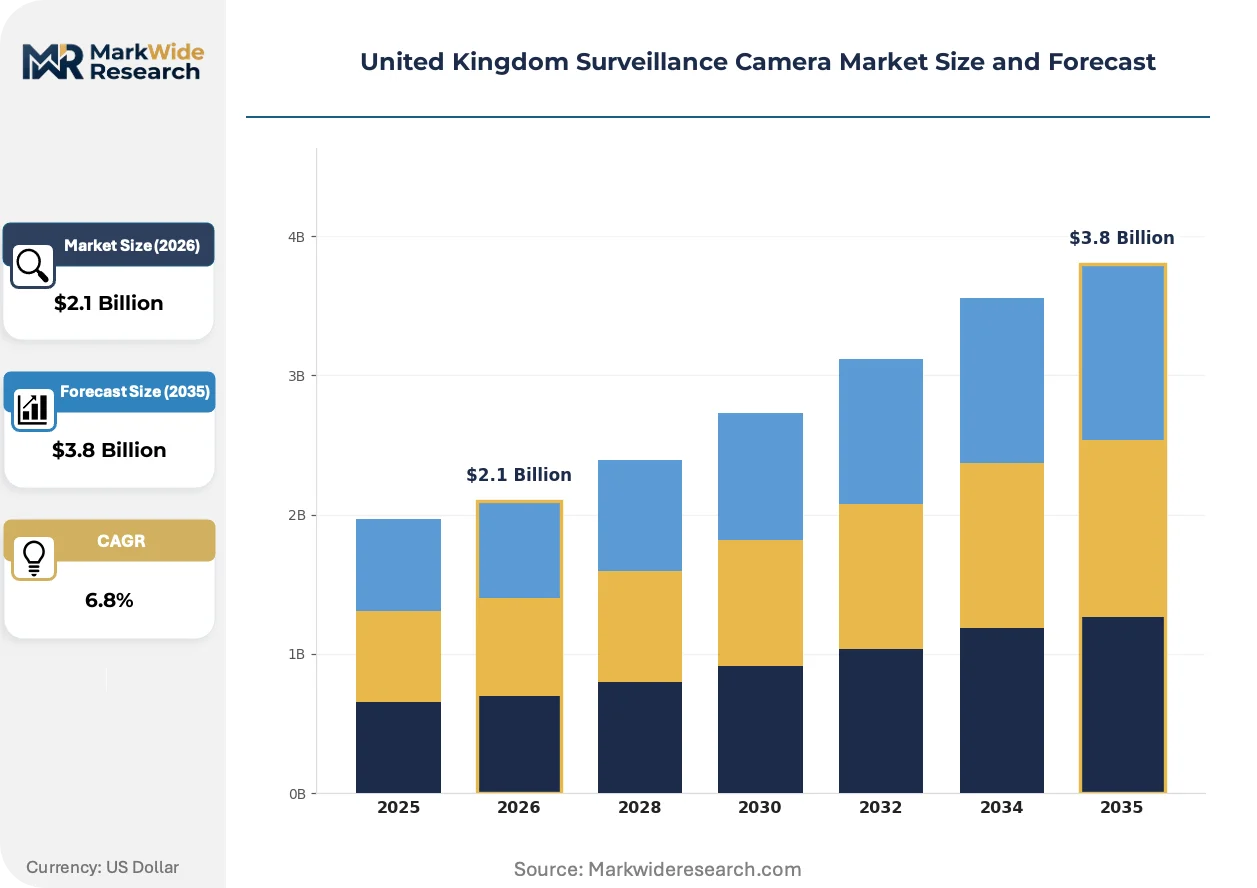
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome Cameras, Bullet Cameras, PTZ Cameras, IP Cameras Technology: Analog, Digital, HD-TVI, IP-Based Installation Type: Indoor, Outdoor, On-Premises, Remote End User: Retail, Transportation, Residential, Healthcare |
| Companies Covered | Bosch Security and Safety Systems, Milesight, Axis Communications AB, Samsung Electronics Co Ltd, Avigilon Corporation, Hangzhou Hikvision Digital Technology Co Ltd, Teledyne FLIR LLC, Honeywell International Inc, Dahua Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Surveillance Camera Market Trends and Innovations
Edge-based processing architectures are redistributing computational load from central servers to camera hardware, enabling real-time analytics without bandwidth saturation. This shift is altering how British integrators specify storage, networking, and software layers.
Artificial intelligence inference chips embedded directly into dome and bullet cameras is overtaking server-based video analytics for license plate recognition and object classification. British Transport Police and Highways England are specifying these units for motorway monitoring. The technology is compressing infrastructure costs and reducing dependency on fiber backhaul to control rooms.
The Investigatory Powers Act 2016 and pending Data Protection and Digital Information Bill amendments are tightening accountability for biometric data processing. Police forces must now conduct Data Protection Impact Assessments before deploying live facial recognition. Manufacturers are responding with privacy-by-design features including automatic face-blurring and audit-logging firmware.
Consolidated framework agreements are displacing spot purchasing across UK public sector estates. Crown Commercial Service and NHS Supply Chain now mandate five-year total-cost-of-ownership evaluations. Scottish local authorities and Northern Irish health trusts have adopted similar procurement models, favoring vendors with in-country technical support and spare parts warehousing.
United Kingdom Surveillance Camera Market Segmentation
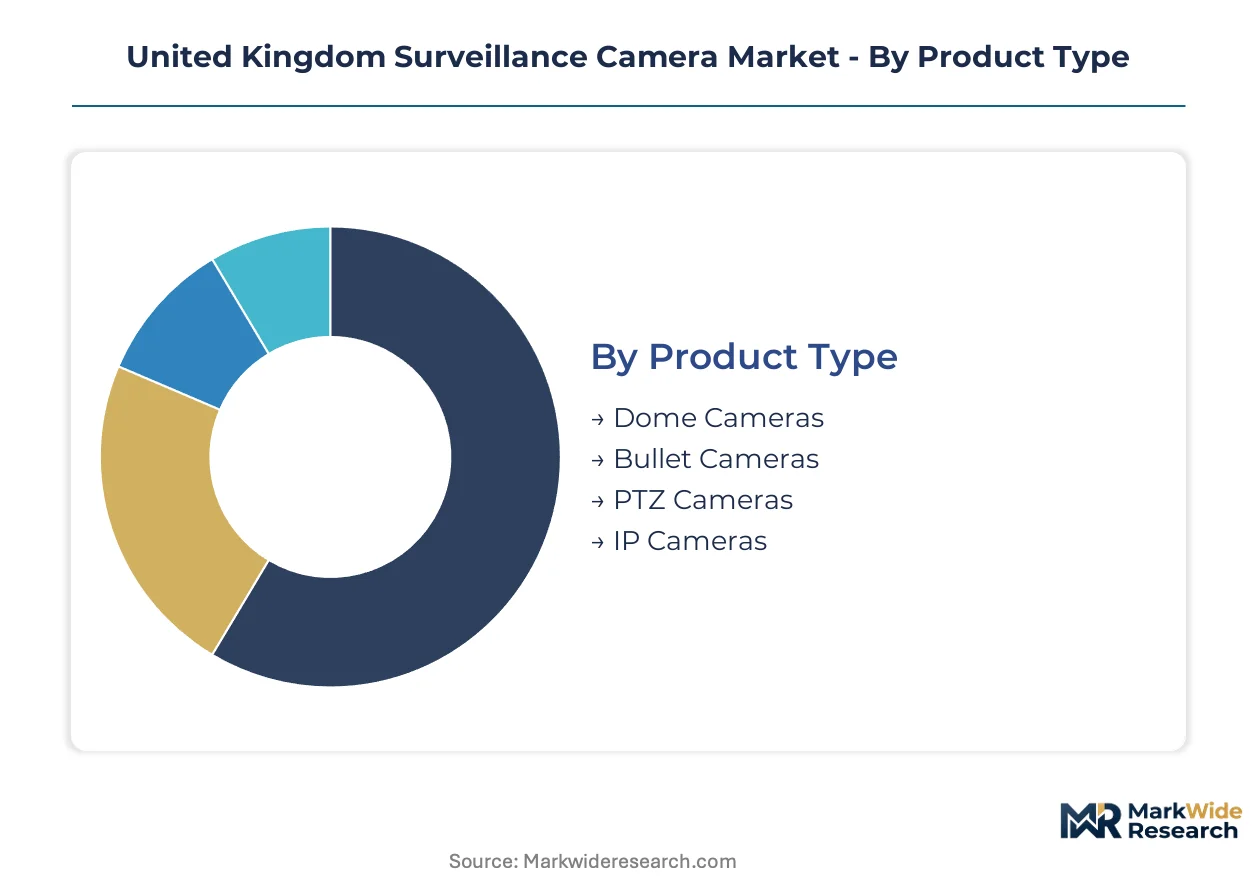
UK surveillance camera procurement splits across four structural dimensions. Each dimension reflects distinct upgrade pressures from aging analog estates, compliance mandates, and shifting customer specifications.
Product Type:
The replacement cycle from analog to IP infrastructure is redrawing product mix across British installations, with form factor choices driven by vandal resistance needs and operator control requirements.
- Dome Cameras:Vandal-resistant housings with 360-degree coverage and discreet ceiling mounting. Demand concentrates in NHS hospital corridors and retail banking branches across Greater London and Manchester, where aesthetics and tamper-proofing outweigh cost sensitivity.
- IP Cameras:Network-addressable devices supporting Power-over-Ethernet and edge analytics processing. Scottish health trusts and Transport for London are consolidating procurement around these units to satisfy Surveillance Camera Commissioner encryption mandates and reduce coaxial cabling replacement costs.
- Bullet Cameras:Weather-sealed cylindrical housings optimized for long-range perimeter monitoring. Industrial estates in the Midlands favor these for outdoor boundary protection.
- PTZ Cameras:Motorized pan-tilt-zoom mechanisms with operator-controlled sweep patterns. Birmingham New Street and Manchester Piccadilly deploy these for real-time crowd management during peak transit hours.
Volume placements concentrate in Dome Cameras; the faster expansion belongs to IP Cameras.
Technology:
Cost tiers separate legacy infrastructure preservation from full-digital replacement strategies, with hybrid formats bridging budget-constrained estates.
- IP-Based:Fully digital transmission with H.265 compression and embedded analytics firmware. West Midlands Police and Highways England specify these for motorway incident detection, where bandwidth efficiency and metadata tagging reduce control room staffing loads.
- Analog:Coaxial-based CVBS signaling with limited resolution and no native encryption. Victorian-era public buildings in Liverpool and Newcastle retain these systems where full rewiring costs exceed capital budgets.
- Digital:Early-generation digital video recorders with proprietary encoding formats. Small retail operators in Leeds commercial zones maintain these as stopgap measures.
- HD-TVI:High-definition transport video interface enabling 1080p over existing coaxial infrastructure. Welsh local authorities leverage this for cost-controlled upgrades of school and library estates.
Procurement volumes cluster in IP-Based technology; HD-TVI is climbing the fastest among constrained budgets.
Installation Type:
Customer type and margin structure diverge sharply between permanent on-site deployments and managed service arrangements with remote accessibility.
- Outdoor:IP67-rated housings with heater-blower assemblies and anti-condensation coatings. Port of Milford Haven and energy transmission sites across rural Scotland require these for CPNI-compliant perimeter hardening.
- Indoor:Lower IP ratings with emphasis on discrete form factors and PoE simplicity. Oxford Street retail corridors and Glasgow shopping centers dominate this category.
- On-Premises:Local NVR storage with dedicated network segmentation. University estates in England favor this architecture for GDPR-controlled data sovereignty.
- Remote:Cloud-integrated architectures with subscription-based VMS access. SME commercial landlords in Bristol and Brighton are shifting capital expenditure to operational budgets through these arrangements.
On-Premises installations retain the largest installed base; Remote configurations are gaining share fastest among private sector adopters.
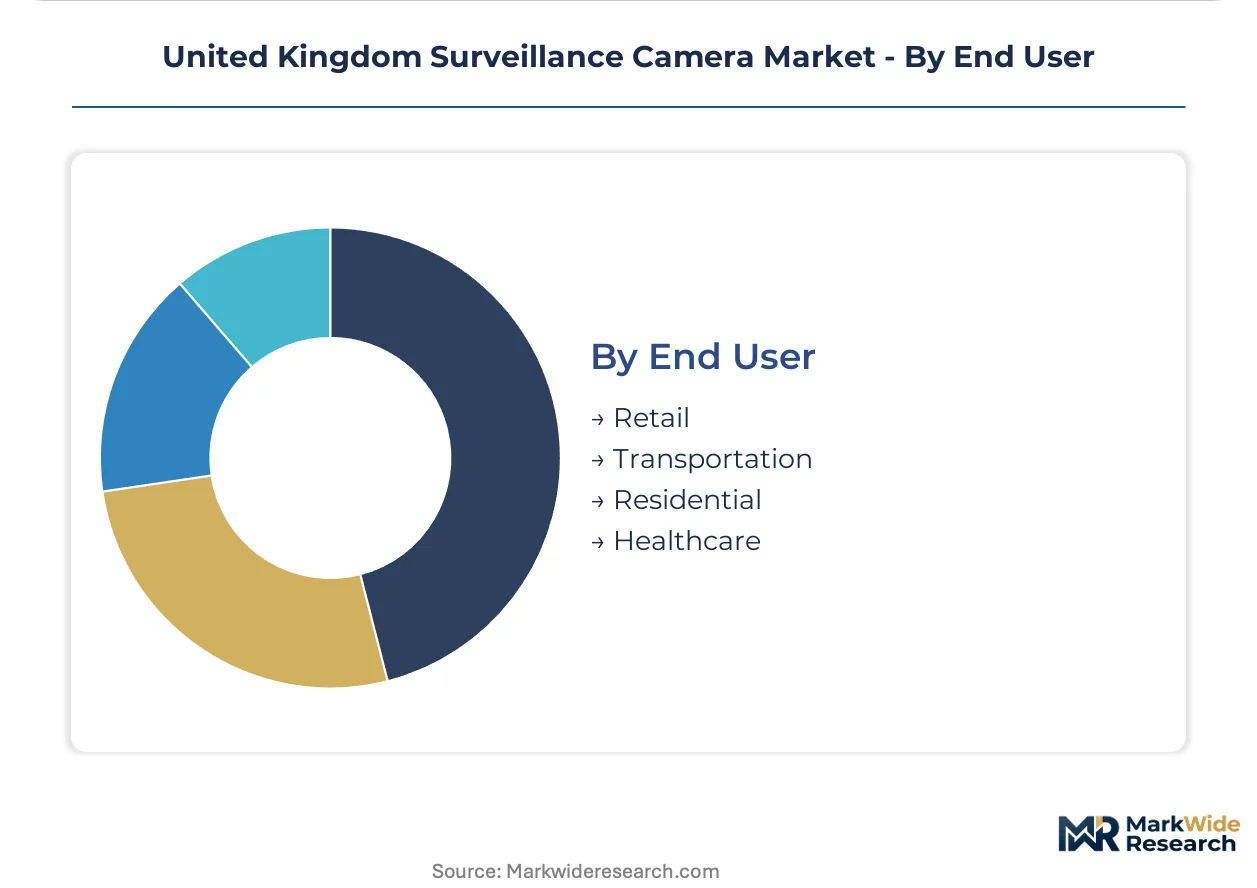
End User:
Application-specific compliance requirements and incident response protocols create divergent specification standards across vertical markets.
- Transportation:Edge-analytics cameras with real-time crowd flow algorithms and automated incident flagging. London Underground, Manchester Metrolink, and Network Rail stations are standardizing on these for passenger safety mandates.
- Healthcare:Fall-detection analytics and patient privacy masking for ward monitoring. NHS Scotland hospital networks remain underpenetrated, presenting expansion opportunity for patient safety applications.
- Retail:Integrated video-analytic networks combining loss prevention with footfall heatmapping. Urban commercial zones in Liverpool, Leeds, and Glasgow are densifying deployments.
- Residential:Consumer-grade WiFi cameras with mobile app integration and cloud storage subscriptions. New-build apartment developments in Birmingham and Manchester are bundling these into service charge structures.
Transportation commands the highest unit volumes; Healthcare represents the steepest expansion trajectory among regulated estates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon image sensors from East Asian fabrication nodes supply the optical core of British surveillance deployments, while domestic system integrators concentrate in England's technology corridors and Scottish industrial zones.
London and Southeast England
Transport for London's Underground and Overground networks drive demand for edge-analytics cameras with real-time crowd flow management. The Surveillance Camera Commissioner's National Surveillance Camera Strategy mandates encryption standards that accelerate IP-based infrastructure replacement. Oxford Street retail corridors and Heathrow Airport perimeter systems anchor the highest camera density per square kilometer in the UK.
Midlands
Birmingham New Street and Manchester Piccadilly stations deploy PTZ cameras for automated incident detection during peak transit hours. West Midlands Police specify H.265-compressed IP units for motorway monitoring under Highways England frameworks. Victorian-era public buildings in Liverpool and Newcastle retain hybrid analog-digital environments where full rewiring costs exceed capital budgets.
Scotland
NHS Scotland hospital networks remain underpenetrated by advanced video analytics, presenting expansion opportunity for patient safety and fall-detection applications. The Scottish Government's public sector procurement frameworks mandate five-year total-cost-of-ownership evaluations. Glasgow shopping centers and Edinburgh transport hubs concentrate indoor dome camera deployments.
Wales
Port of Milford Haven and energy transmission sites require hardened camera systems for perimeter intrusion detection under updated CPNI guidelines. Welsh local authorities leverage HD-TVI technology for cost-controlled upgrades of school and library estates. Cardiff commercial zones are shifting capital expenditure to operational budgets through cloud-integrated surveillance arrangements.
Northern Ireland
Cross-border transport infrastructure and Belfast port facilities drive demand for cybersecurity-certified camera systems. NCSC Cyber Essentials Plus accreditation delays are slowing procurement approvals for police forces. SME commercial landlords in Belfast and Derry are adopting remote-managed service architectures.
United Kingdom Surveillance Camera Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native software ecosystems and edge-AI specialization. The vendor base clusters around three strategic archetypes: European manufacturers with deep manufacturing scale, Chinese cost-optimized hardware suppliers, and Nordic open-platform software specialists. Consolidated framework agreements across Crown Commercial Service and NHS Supply Chain are displacing spot purchasing, favoring vendors with in-country technical support. Geographic expansion through distribution partnerships and portfolio diversification into thermal-analytics represent the dominant competitive vectors.
Among European-headquartered security specialists, Bosch Security and Safety Systems anchors the manufacturing-scale tier through continental assembly plant networks. Axis Communications AB exemplifies the open-platform archetype that reduces vendor lock-in for British end users. Hangzhou Hikvision Digital Technology Co Ltd occupies the cost-optimized position, competing aggressively through UK distribution channels for dome and bullet camera lines. Samsung Electronics Co Ltd and Dahua Technology represent additional hardware-centric entrants, while Avigilon Corporation and Teledyne FLIR LLC sit within the premium-analytics specialization tier.
| Leading Market Players |
|---|
| Bosch Security and Safety Systems |
| Milesight |
| Axis Communications AB |
| Samsung Electronics Co Ltd |
| Avigilon Corporation |
| Hangzhou Hikvision Digital Technology Co Ltd |
| Teledyne FLIR LLC |
| Honeywell International Inc |
| Dahua Technology |
| Others |
Pricing and Supply Chain Analysis
Crown Commercial Service framework agreements concentrate procurement power among consolidated public sector buyers, forcing vendors toward five-year total-cost-of-ownership contracts with embedded service tiers rather than transactional hardware sales.
Pricing Analysis
Warranty and firmware update bundling separates premium vendor tiers from economy-positioned competitors. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and encryption compliance under Surveillance Camera Commissioner mandates. Price differentiation hinges on NCSC Cyber Essentials Plus accreditation status and in-country spare parts warehousing commitments. Cost compression in economy tiers intensifies because Chinese manufacturers compete aggressively through UK distribution channels. NHS trusts and university estates exhibit highest price sensitivity, while CPNI-guided critical infrastructure sites prioritize compliance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Transport for London and Highways England, while value-added distributors serve fragmented municipal and commercial accounts. Image sensor fabrication concentrates in Taiwan, South Korea, and China, with SoC packaging anchored in Malaysian and Vietnamese facilities. British system integrators draw from East Asian optical components, European assembly plants, and domestic warehousing networks. Single-source vulnerability in advanced AI inference chips creates procurement risk for edge-analytics camera deployments. Distribution runs through tier-one security distributors holding Crown Commercial Service accreditation and regional integrators with NCSC-certified installation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom surveillance camera market functions as a cost-of-compliance arena where Surveillance Camera Commissioner encryption mandates and GDPR biometric processing rules erect regulatory moats favoring vendors with established certification infrastructure.
For Market Incumbents: Hedge against cloud-native displacement by embedding edge-AI firmware directly into camera hardware, reducing dependency on centralized analytics servers. Secure NCSC Cyber Essentials Plus accreditation for entire product portfolios before pending Data Protection and Digital Information Bill amendments tighten accountability requirements. Extend technical support footprints into Scottish health trust territories where advanced video analytics remain underpenetrated. For New Entrants and Emerging Players: Security integrators with Crown Commercial Service framework access represent the critical channel pathway for market penetration. Welsh local authority estates and Northern Irish health trusts offer most penetrable procurement entry points given slower consolidation of five-year total-cost-of-ownership evaluations. Lead with thermal-analytics specialization for CPNI-compliant perimeter applications at energy transmission sites where incumbent coverage remains thin. For Investors and Strategic Acquirers: The window for entry favors vendors with privacy-by-design firmware capabilities and established GDPR compliance infrastructure. Long-term viability centers on acquisition targets possessing automated face-blurring technology and audit-logging architectures that anticipate Investigatory Powers Act enforcement trends. Monitor NCSC certification backlog resolution as inflection indicator for procurement velocity recovery across police forces and government departments.| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-by-Design Firmware Development | Automatic face-blurring capabilities satisfy ICO biometric guidance before live facial recognition deployments expand. |
| Crown Commercial Service Accreditation | Framework access unlocks consolidated procurement streams across NHS Supply Chain and public sector estates. |
| Edge-AI Chip Integration | Embedded inference processing reduces fiber backhaul costs for Highways England motorway monitoring contracts. |
| Scottish Healthcare Estate Expansion | NHS Scotland hospital networks present first-mover advantage for fall-detection analytics applications. |
| CPNI-Compliant Perimeter Hardening | Port of Milford Haven and energy transmission sites require hardened camera systems under updated guidelines. |
Research Methodology
Document review covered Surveillance Camera Commissioner guidance documents, Crown Commercial Service framework agreements, and Information Commissioner's Office biometric processing guidance, complemented by interviews with security system integrators, NHS estates procurement managers, transport authority technology directors, and police force surveillance leads. Secondary validation drew from NCSC certification databases, NHS Supply Chain procurement records, and CPNI critical infrastructure protection guidelines. Bottom-up deployment volume estimates triangulated against top-down market sizing from public sector capital expenditure disclosures.
Cross-referencing historical procurement cycle data against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product form factor, technology generation, installation architecture, and end-use vertical with regional regulatory cluster overlay. CAGRs derived from polynomial curve fitting of replacement cycle acceleration patterns and analog-to-IP migration velocity. Forecast inputs incorporated Surveillance Camera Commissioner mandate compliance deadlines and pending Data Protection and Digital Information Bill amendment timelines.
Caveats apply where semiconductor input volatility or NCSC certification backlog resolution delays could materially shift the outlook for deployment schedules across police forces and NHS trusts. Forecasts reflect assumptions regarding GDPR enforcement consistency and Crown Commercial Service framework consolidation velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Canada Video Surveillance Market
Video Surveillance Systems
Video Surveillance As a Service Market
Video Surveillance Systems
People Counting System Market
Video Surveillance Systems
Latin America Video Surveillance Storage Market
Video Surveillance Systems
Global Body Worn Cameras Market
Video Surveillance Systems
Farm Video Surveillance System Market
Video Surveillance Systems
China Surveillance Storage Market
Video Surveillance Systems
Smart Security Camera Market
Video Surveillance Systems
Night Vision System (NVS) Market
Video Surveillance Systems
Asia-Pacific Video Surveillance Systems Market
Video Surveillance Systems
Smart Camera System Market
Video Surveillance Systems
Night Vision (IR) Surveillance Cameras Market
Video Surveillance Systems
Aircraft Video Surveillance Systems Market
Video Surveillance Systems
Italy Video Surveillance Market
Video Surveillance Systems
United Kingdom Surveillance Analog Camera Market
Video Surveillance Systems
Germany Video Surveillance Market