
 Asia-Pacific Epoxy Powder Coatings Market | 2026-2036
Asia-Pacific Epoxy Powder Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Epoxy Powder Coatings Market Outlook
The gap between premium thermoset formulations and commodity epoxy hybrids is rebalancing as automotive and electronics buyers separate performance specifications from price-driven procurement. Akzo Nobel N.V. leverages its marine and protective coatings heritage to dominate high-durability segments across Southeast Asian shipyards. PPG Industries, Inc. anchors its position through backward integration into resin synthesis, securing supply continuity for Chinese appliance manufacturers. Kansai Paint Co., Ltd. specializes in thin-film powder technologies that reduce material consumption for Japanese electronics OEMs.
Asia-Pacific epoxy powder coatings comprise thermosetting polymer systems based on bisphenol-A or bisphenol-F epoxy resins cured with dicyandiamide or phenolic hardeners, applied electrostatically at film builds of 40–120 micrometres and baked at 180–200°C to deliver chemical resistance and electrical insulation. The automotive application segment leads value contribution as EV battery tray manufacturers specify thicker, thermally conductive powder coats for flame-retardant properties. Solid form formulations occupy the fastest-growing position as dry-blend technologies eliminate solvent handling costs and align with China's tightening VOC enforcement in Jiangsu and Zhejiang provinces.
China's MEE enforces GB 30981 limits on industrial coating VOC content, while Japan's METI promotes low-carbon manufacturing incentives that favour energy-efficient powder cure processes over liquid alternatives. India's BIS certification requirements for construction and appliance coatings are expanding compliance scope for imported formulations. Stakeholders must monitor how China's dual carbon goals and India's PLI scheme for domestic manufacturing reshape regional supply chain configurations and local content thresholds.
Market Dynamics
China's dual carbon goals and tightening GB 30981 VOC limits are compressing solvent-based coating capacity while redirecting capital toward powder cure infrastructure across Jiangsu and Guangdong manufacturing clusters.
Growth Catalysts
- Automotive OEM expansion:EV battery tray manufacturers in China and India specify thermally conductive epoxy powder formulations for flame-retardant properties, creating dedicated coating line investments.
- MEE enforcement trajectory:China's Ministry of Ecology and Environment is accelerating facility inspections in the Pearl River Delta, forcing appliance and electronics contract manufacturers to convert liquid spray booths to electrostatic powder systems.
- Dry-blend technology maturation:Solid form formulations eliminate solvent handling costs entirely, aligning with Zhejiang province's industrial emissions reduction mandates while reducing insurance and hazardous waste liabilities.
Market Restraints
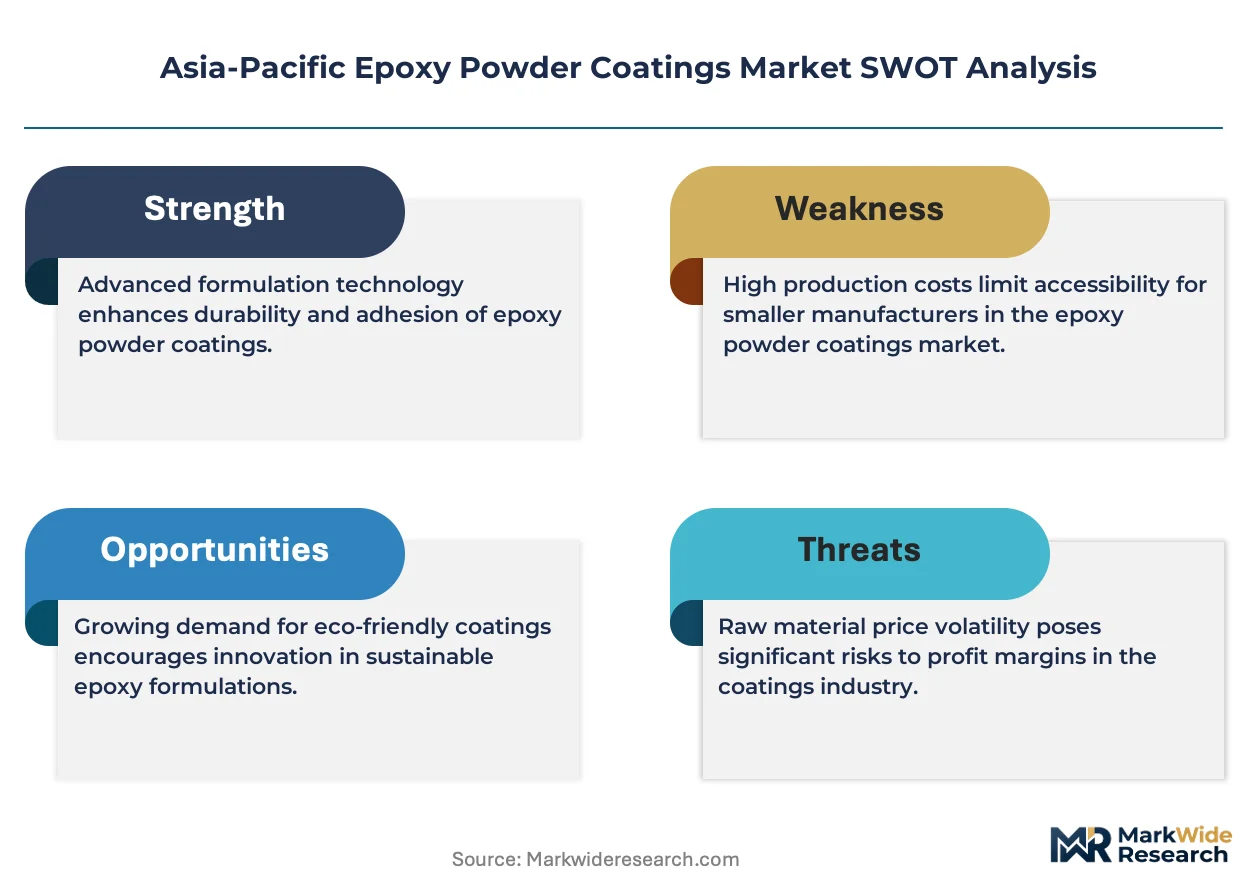
- Bisphenol-A feedstock concentration:Epoxy resin precursors depend on petrochemical complexes concentrated in China's Shandong and Jiangsu provinces, exposing formulators to naphtha price volatility and regional supply disruptions.
- Cure temperature inflexibility:Standard epoxy powder systems require 180–200°C substrate temperatures, excluding heat-sensitive substrates like certain engineered plastics and pre-assembled electronics from addressable applications.
- Polyurethane liquid coating substitution:Thin-film polyurethane alternatives capture automotive interior and premium appliance segments where aesthetic versatility and lower bake temperatures outweigh epoxy's chemical resistance advantages.
Strategic Opportunities
- India PLI scheme leverage:India's production-linked incentive scheme for domestic appliance and component manufacturing is attracting greenfield coating facility investments in Gujarat and Tamil Nadu, creating first-mover powder system integration opportunities.
- Thin-film powder penetration:Japanese electronics OEMs are qualifying 25–40 micrometre film builds for circuit board enclosures and connector housings, opening material efficiency premiums unavailable in standard architectural applications.
- UV-curable hybrid convergence:Epoxy-acrylate hybrid powders incorporating photoinitiator packages enable lower-temperature cure cycles for temperature-sensitive automotive electronics, expanding addressable substrate scope.
Industry Challenges
- Electrostatic application technician scarcity:Proper Faraday cage penetration and film thickness uniformity require specialized operator training that vocational programs in Vietnam and Indonesia have not yet scaled to match facility expansion rates.
- BIS certification timeline compression:India's Bureau of Indian Standards has expanded mandatory testing scope for imported powder formulations, creating 4–6 month approval delays that disrupt just-in-time supply contracts for appliance assemblers.
- Legacy liquid system retrofit complexity:Converting existing spray booths from solvent-based to powder capture requires ventilation reengineering and explosion-proof electrical upgrades that strain mid-tier coating shop capital budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Epoxy Powder Coatings Market |
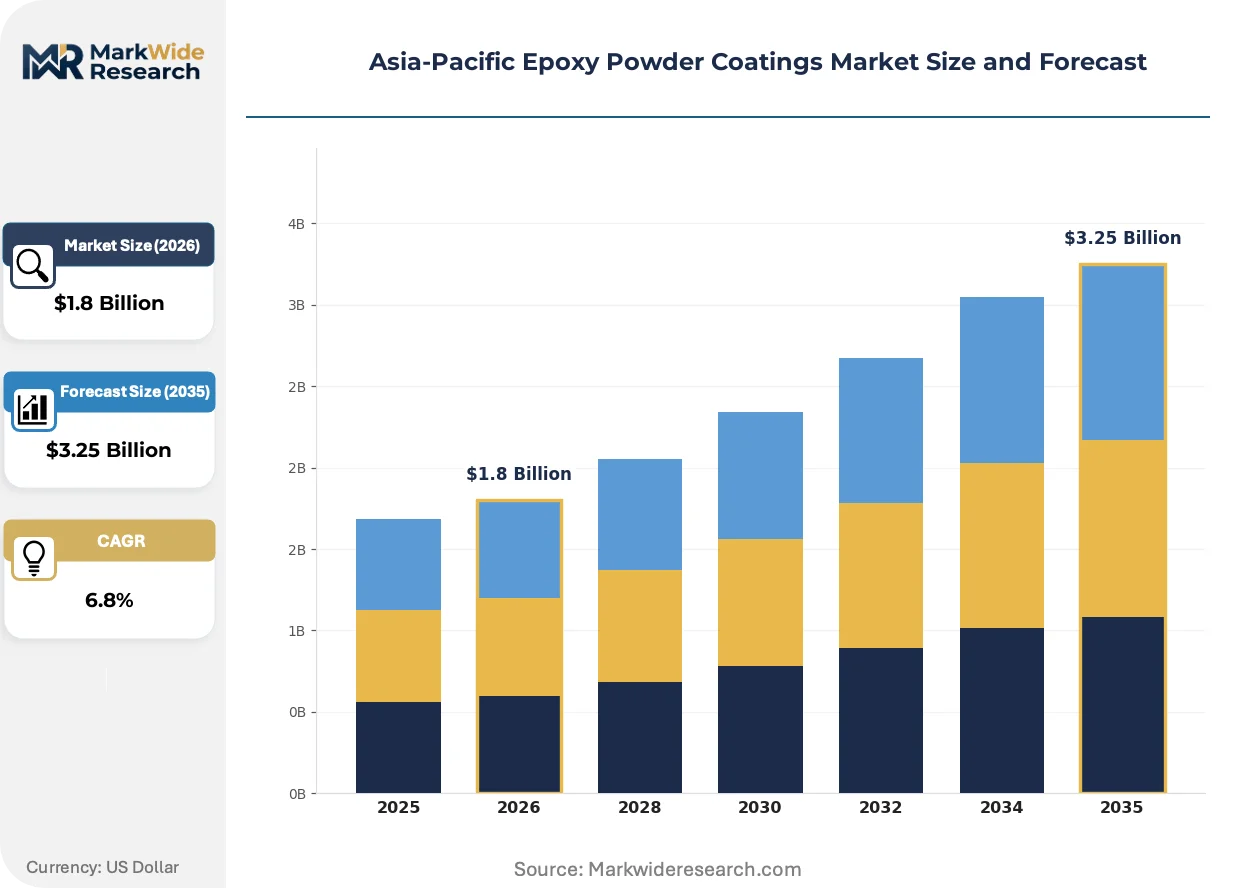
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Automotive, Electronics, Appliances, Furniture Form: Solid, Liquid, Primer, Topcoat End User: Manufacturers, Contractors, Wholesale Distributors, Retailers Deployment: In-House, Outsourced, Mobile Units, Fixed Plants |
| Companies Covered | Akzo Nobel N.V., PPG Industries, Inc., The Sherwin-Williams Company, Jotun, 3M, Axalta Coating Systems, Kansai Paint Co., Ltd., Asian Paints, Nippon Paint Holding Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Epoxy Powder Coatings Market Strategic Shifts
Formulation chemistry, cure process innovation, and procurement model restructuring are simultaneously reshaping competitive positioning across the Asia-Pacific epoxy powder coatings value chain.
Low-temperature cure epoxy powders incorporating latent catalyst packages are converging with induction heating systems to enable 140–160°C cure cycles on aluminum automotive components. Korean EV battery housing manufacturers are piloting these systems at scale to protect sensitive cell-adjacent electronics from thermal degradation. This convergence is compressing the traditional barrier between powder coatings and liquid alternatives in temperature-constrained applications.
Japan's METI low-carbon manufacturing incentive framework now awards certification premiums to coating operations demonstrating 15% energy reduction versus solvent-based benchmarks. Appliance manufacturers in Osaka and Nagoya industrial corridors are restructuring supplier scorecards to prioritize METI-certified powder coaters, reallocating contract volumes away from uncertified competitors. The construction and heavy equipment segments in Japan's Chubu region show the fastest compliance-driven conversion rates.
Integrated coating service contracts are displacing traditional material-plus-labor procurement across Chinese appliance OEMs. Haier and Midea operations in Qingdao and Foshan now specify finished component pricing that transfers formulation risk and application yield responsibility to coating contractors. This model concentrates purchasing power among vertically integrated powder coaters with captive resin synthesis and recycling capabilities, marginalizing independent job shops in Shandong and Hebei provinces.
Asia-Pacific Epoxy Powder Coatings Market Segmentation
Epoxy powder coating procurement patterns diverge sharply across application environments, formulation states, and supply chain positions. Understanding these fault lines reveals where formulation premiums command pricing power versus where commodity competition dominates.
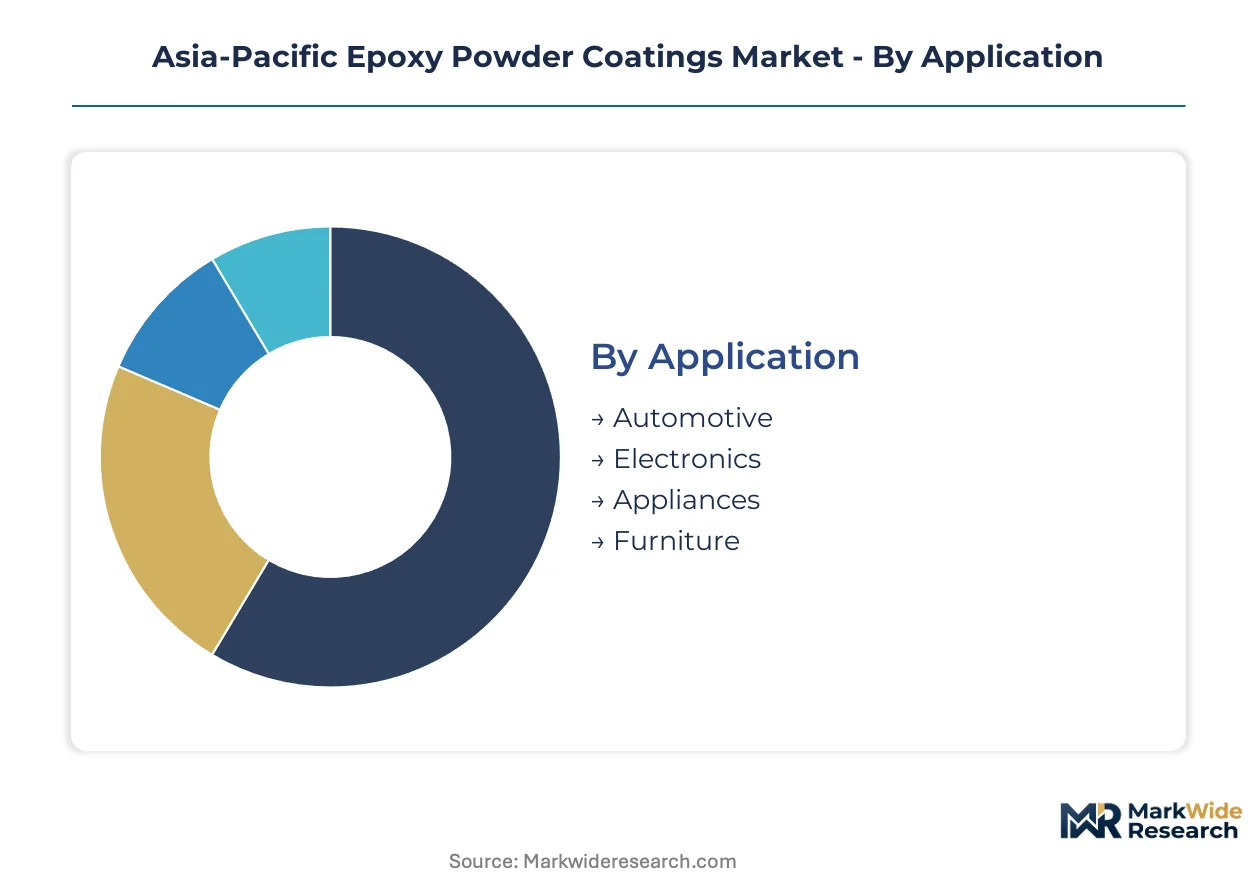
Application:
Automotive buyers separate chassis specifications from interior aesthetics; electronics OEMs prioritize thin-film precision over film build.
- Automotive:EV battery tray manufacturers specify thermally conductive epoxy formulations with flame-retardant properties at 80–120 micrometre film builds. China's BYD and CATL supplier parks in Shenzhen and Changzhou drive dedicated coating line investments for underbody and structural components.
- Electronics:Japanese OEMs in Osaka and Nagoya industrial corridors qualify 25–40 micrometre powder coats for circuit board enclosures and connector housings. METI low-carbon manufacturing incentives reward energy-efficient cure processes that eliminate solvent handling entirely.
- Appliances:Haier and Midea operations in Qingdao and Foshan specify finished component pricing that transfers formulation risk to coating contractors.
- Furniture:Metal office and outdoor furniture manufacturers in Vietnam and Indonesia favor standard epoxy hybrids where price sensitivity outweighs performance differentiation.
Volume sits with Automotive; growth tilts toward Electronics.
Form:
Physical state determines handling infrastructure, regulatory exposure, and geographic mobility of coating operations.
- Solid:Dry-blend technologies eliminate solvent handling costs and hazardous waste liabilities entirely. Zhejiang province's industrial emissions reduction mandates accelerate conversions from liquid spray booths across Ningbo and Wenzhou manufacturing clusters.
- Liquid:Solvent-borne systems retain share in automotive interior segments where aesthetic versatility and lower bake temperatures outweigh chemical resistance requirements.
- Primer:Corrosion-resistant base coats concentrate in marine and protective applications across Southeast Asian shipyards where Akzo Nobel maintains formulation leadership.
- Topcoat:Decorative finish layers command premium pricing in appliance and furniture segments where color consistency and gloss retention determine procurement decisions.
Solid formulations dominate current throughput; UV-curable hybrid powders are climbing the fastest as temperature-sensitive substrates enter addressable scope.
End User:
Supply chain position determines technical specification authority and inventory risk allocation.
- Manufacturers:Captive coating facilities at Chinese appliance and electronics OEMs integrate resin synthesis, application, and recycling under single ownership, concentrating purchasing power among vertically integrated operators.
- Contractors:Independent job shops in Shandong and Hebei provinces face margin compression as integrated service contracts displace material-plus-labor procurement.
- Wholesale Distributors:Regional distributors stock standard formulations for mid-tier furniture and construction applications where specification authority rests with applicators rather than end buyers.
- Retailers:Direct-to-consumer channels remain marginal, serving maintenance and repair segments with limited volume contribution.
Procurement authority concentrates with Manufacturers; channel expansion favors Wholesale Distributors serving Vietnam and Indonesia facility buildouts.
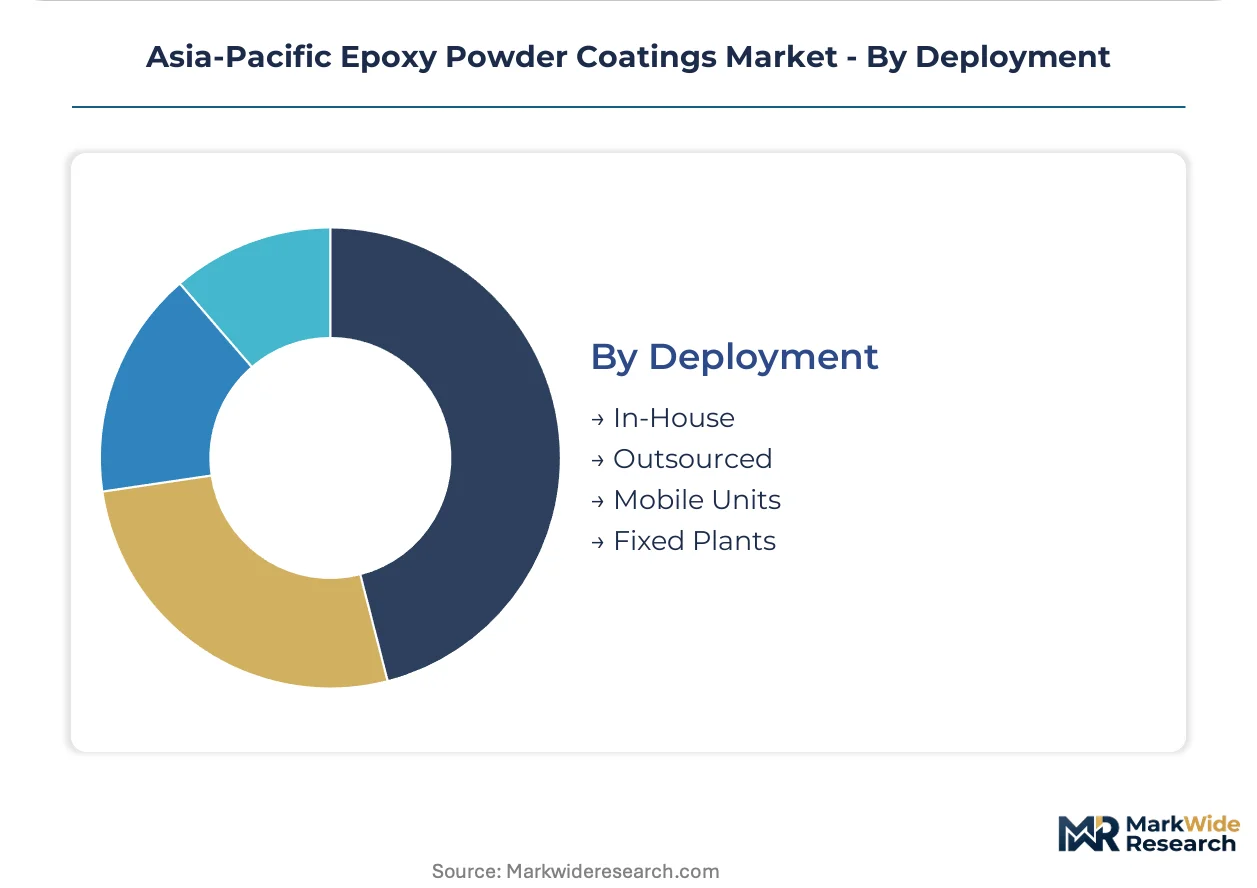
Deployment:
Capital intensity and operational flexibility trade off across coating operation models.
- In-House:Captive facilities at automotive and appliance OEMs control formulation IP and application yield, requiring explosion-proof electrical infrastructure and ventilation reengineering that strains mid-tier capital budgets.
- Outsourced:Third-party coating services absorb capital burden and regulatory compliance complexity, appealing to electronics assemblers with fluctuating volume requirements.
- Mobile Units:Transportable electrostatic systems serve construction equipment and heavy machinery segments where on-site coating eliminates logistics costs for oversized components.
- Fixed Plants:Permanent installations dominate high-volume automotive and appliance production where line speed and film thickness uniformity determine cost competitiveness.
Fixed Plants anchor regional capacity; Mobile Units are gaining share fastest in Australia's mining equipment maintenance corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pearl River Delta manufacturing corridor spanning Shenzhen, Guangzhou, and Foshan anchors Asia-Pacific epoxy powder coatings demand through integrated appliance and electronics coating facilities. China's dual carbon policy framework and provincial emissions mandates are restructuring regional supply configurations across four major economies.
China
EV battery tray manufacturers in Shenzhen and Changzhou specify thermally conductive epoxy formulations with flame-retardant properties at dedicated coating lines. MEE enforcement of GB 30981 VOC limits is accelerating facility inspections across Guangdong and Jiangsu provinces. The Yangtze River Delta manufacturing cluster in Ningbo and Wenzhou is converting liquid spray booths to electrostatic powder systems under Zhejiang's industrial emissions reduction mandates.
Japan
Electronics OEMs in Osaka and Nagoya industrial corridors qualify 25–40 micrometre powder coats for circuit board enclosures and connector housings. METI low-carbon manufacturing incentives reward coating operations demonstrating 15% energy reduction versus solvent-based benchmarks. The Chubu region around Nagoya shows the fastest compliance-driven conversion rates for construction and heavy equipment segments.
India
Appliance and component manufacturers in Gujarat and Tamil Nadu are attracting greenfield coating facility investments under the PLI scheme for domestic manufacturing. BIS certification requirements for imported powder formulations have expanded mandatory testing scope, creating 4–6 month approval delays. Contract manufacturers in Pune and Chennai face margin compression as integrated service contracts displace traditional material-plus-labor procurement.
South Korea
EV battery housing manufacturers are piloting low-temperature cure epoxy powders at scale to protect sensitive cell-adjacent electronics from thermal degradation. The country's national industrial regulator promotes energy-efficient manufacturing incentives favoring powder cure processes. Korean automotive suppliers in Gyeonggi Province are restructuring supplier scorecards to prioritize certified powder coaters.
Vietnam
Metal office and outdoor furniture manufacturers in Ho Chi Minh City and Binh Duong province favor standard epoxy hybrids where price sensitivity outweighs performance differentiation. Vocational training programs have not yet scaled electrostatic application technician capacity to match facility expansion rates. Independent job shops face procurement authority concentration as regional distributors stock standard formulations for mid-tier applications.
Asia-Pacific Epoxy Powder Coatings Market Competitive Environment
Capital-heavy producers compete with asset-light designers across formulation chemistry and application service delivery. The market structure concentrates among multinational coating specialists with backward integration into resin synthesis and regional job shops dependent on distributor supply chains. Three archetypes dominate: vertically integrated resin-to-coating operators, technology-licensed regional formulators, and captive appliance OEM coating divisions. Capacity expansion and strategic partnerships represent the dominant competitive moves as participants secure supply continuity and geographic coverage.
Among multinational specialists, Akzo Nobel N.V., PPG Industries, Inc., and Kansai Paint Co., Ltd. exemplify distinct strategic positions. Akzo Nobel occupies a heritage-driven anchor role in marine and protective applications across Southeast Asian shipyards. PPG Industries represents the backward-integrated archetype through captive resin synthesis capabilities serving Chinese appliance manufacturers. Kansai Paint sits within the precision-technology tier, specializing in thin-film powder systems for Japanese electronics OEMs requiring material efficiency premiums.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| Jotun |
| 3M |
| Axalta Coating Systems |
| Kansai Paint Co., Ltd. |
| Asian Paints |
| Nippon Paint Holding Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Bisphenol-A feedstock costs cascade through three distinct pricing tiers as petrochemical complexes in Shandong and Jiangsu provinces transmit naphtha volatility to formulators, tier-one OEMs, and independent job shops across the Pearl River Delta.
Pricing Analysis
Finished-component pricing anchors procurement contracts at Haier and Midea operations in Qingdao and Foshan, transferring formulation risk and application yield responsibility to coating contractors. Three-tier pricing structure across premium, standard, and economy levels separates METI-certified low-carbon coaters from uncertified competitors and commodity epoxy hybrid suppliers. Price differentiation centers on certification grade and volume scale, with pricing pressure stemming from India's BIS certification timeline compression and the concentration of procurement authority among vertically integrated manufacturers. Appliance OEMs exhibit lowest price sensitivity due to captive facility economics, while Vietnamese furniture manufacturers face acute margin compression.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from BYD and CATL supplier parks, while regional distributors stock standard formulations for mid-tier applications. Raw material supply concentrates in China, South Korea, and Japan, with epoxy resin precursors drawing from petrochemical complexes tethered to naphtha feedstocks. Bisphenol-A, dicyandiamide hardeners, and phenolic curing agents constitute critical input dependencies. Single-source vulnerability in Shandong province feedstock supply creates structural risk exposure. Distribution runs through vertically integrated resin-to-coating operators and technology-licensed regional formulators serving contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's MEE enforcement trajectory and India's PLI scheme are compressing margins for independent job shops, forcing consolidation toward operators with captive resin synthesis and METI certification.
For Market Incumbents: Anticipate polyurethane liquid coating substitution in automotive interior segments by accelerating low-temperature cure R&D investments and securing BIS certification ahead of India's expanded testing scope. Defensive consolidation moves center on backward integration into resin synthesis in Jiangsu province and METI certification acquisition for Japanese electronics OEM supplier scorecards. Capacity addition in Gujarat and Tamil Nadu under PLI scheme leverage protects regional share. For New Entrants and Emerging Players: E-commerce platform channels for specialty thin-film formulations offer the lowest barrier to Japanese electronics OEM qualification programs. White-space targets include UV-curable hybrid powders for temperature-sensitive automotive electronics and mobile coating units for Australian mining equipment maintenance corridors. The most penetrable segment sits with 25–40 micrometre film build applications for circuit board enclosures. A technical service partnership model with Osaka and Nagoya industrial corridor assemblers accelerates qualification timelines. For Investors and Strategic Acquirers: BIS approval delays exceeding four months are the leading indicator that supply chain disruption premiums will concentrate among domestic Indian formulators with established certification pathways. Long-term viability over the next decade favors vertically integrated operators with captive resin production and recycling capabilities. Acquisition target archetype: mid-tier Chinese coaters with GB 30981 compliance infrastructure and existing appliance OEM service contracts. The signal to monitor is MEE facility inspection acceleration rates across Guangdong province.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | PPG Industries' captive supply model secures continuity for Chinese appliance manufacturers facing feedstock volatility. |
| METI Low-Carbon Certification Program | Osaka and Nagoya coaters gain supplier scorecard priority from appliance OEMs restructuring procurement criteria. |
| Greenfield Facility Investment in Gujarat | PLI scheme leverage attracts first-mover powder system integration for domestic appliance component manufacturing. |
| UV-Curable Hybrid Powder Development | Epoxy-acrylate formulations with photoinitiator packages expand addressable substrate scope for automotive electronics. |
| Long-Term Service Contract Restructuring | Integrated coating contracts at Haier and Midea operations displace material-plus-labor procurement, concentrating purchasing power. |
Study Parameters
Trade statistics from China Customs, Japan Chemical Industry Association publications, and BIS certification registries formed the secondary backbone, cross-referenced with primary interviews involving coating plant managers, procurement leads at BYD and CATL supplier parks, distribution channel partners in Ho Chi Minh City, and technical R&D directors at Japanese electronics OEMs. Bottom-up facility capacity assessments and top-down trade flow analysis enabled triangulation across data sources.
Historical trendline analysis of powder coating line investments tracked conversion rates from liquid spray booths across Jiangsu and Zhejiang provinces. The analytical framework modeled segmentation across application environment, formulation state, and supply chain position throughout the forecast period. CAGRs were derived from production capacity buildouts, regulatory enforcement trajectories, and OEM coating line expansion announcements. Industry-specific inputs included EV battery tray specification shifts and METI incentive program uptake rates.
The model holds under continued MEE enforcement of GB 30981 limits and stable naphtha feedstock pricing; deviation in India's BIS approval timelines or Shandong province supply disruptions would shift regional growth trajectories. Forecasts reflect assumptions about PLI scheme implementation pace and dry-blend technology adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Polymer Modified Cementitious Coatings Market
Coatings
PU Coatings Market
Coatings
Global Anti-Reflective Coatings Market
Coatings
Process Pipe Coating Market
Coatings
Japan Architectural Coatings Market
Coatings
Diamond-Like Carbon Coatings Market
Coatings
Wood Preservative Coatings Market
Coatings
South America Thermal Spray Market
Coatings
ASEAN Protective Coatings Market
Coatings
Paper Coating Binders Market
Coatings
US Protective Coatings Market
Coatings
Plastic-Coated Wires Market
Coatings
Global Anti-Smudge Coatings Market
Coatings
Anti-Microbial Powder Coatings Market
Coatings
Solvent Borne Coatings Market
Coatings
United States Automotive OEM Coatings Market