
 Functional Coil Coating Market | 2026-2036
Functional Coil Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Functional Coil Coating Market Intelligence
Expertise in polymer chemistry and sustainable formulation is reorganizing the competitive landscape for coil coating specialists. Akzo Nobel leverages its extensive R&D in fluoropolymer and polyurethane systems to serve high-performance architectural applications. PPG Industries sustains its market position through a global manufacturing footprint and strong relationships with OEMs in the HVAC and appliance sectors. Beckers Group specializes in customized solutions for niche industrial segments, differentiating on service and technical support.
Functional coil coating is a continuous, automated process applying a liquid paint layer onto metal strips before fabrication. These coatings, cured at high temperatures, provide a uniform finish with specific properties like enhanced durability. Their primary purpose is to deliver corrosion protection and aesthetic appeal for finished metal goods. Polyester-based systems represent the largest volume segment, whereas fluoropolymer coatings offer premium performance for demanding building exteriors. The HVAC equipment application also shows consistent demand from industrial manufacturers.
Regulatory frameworks like the EU's REACH directive and VOC limits from the US EPA directly influence coating formulations. In parallel, China's national GB standards for construction materials are impacting market access and product specifications. These environmental and safety regulations compel a shift toward lower-impact chemistries. Consequently, suppliers face strategic decisions on investing in bio-based polyester resins versus advanced waterborne polyurethane systems to secure future market share.
Market Dynamics
Intensifying regulatory pressure for sustainability is the central force shaping the functional coil coating market. Mandates from bodies like the EU's ECHA and China's MEE are compelling a fundamental shift in polymer chemistry toward low-impact formulations.
Growth Catalysts
- Energy-Efficient Construction:Demand for cool-roof and solar-reflective coatings on architectural panels, driven by green building codes, stimulates growth. These coatings reduce building energy consumption, providing a clear performance incentive for adoption in commercial and residential construction.
- Infrastructure Investment:Government-backed infrastructure projects in the United States and India are expanding the use of coated metal for bridges, tunnels, and public buildings. This creates sustained, large-volume demand for durable and corrosion-resistant polyester and polyurethane systems.
- Appliance Sector Modernization:The continuous modernization of home appliances, particularly in the HVAC and refrigeration segments, requires coatings that offer enhanced chemical resistance, flexibility, and specialized aesthetics, supporting demand for customized solutions.
Market Restraints
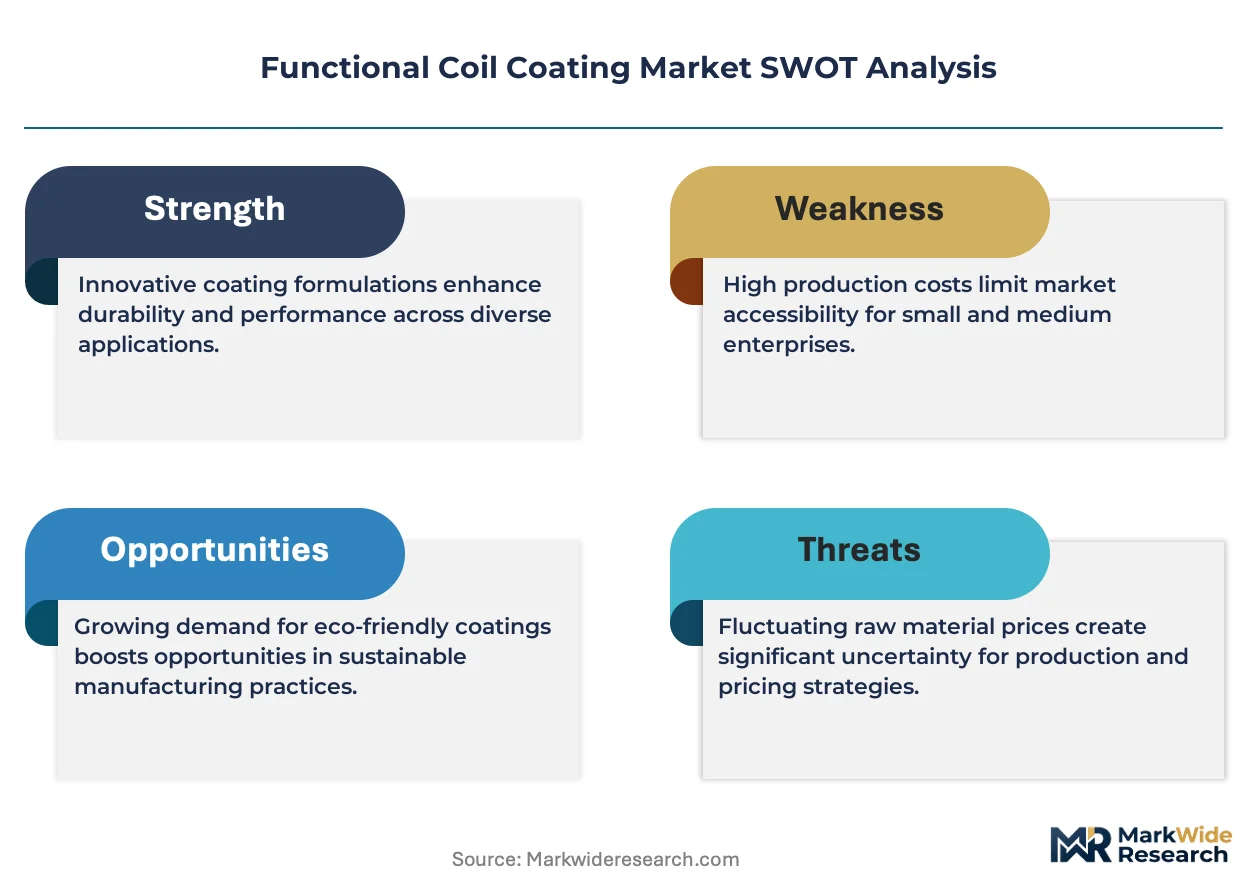
- Raw Material Price Volatility:Key inputs like polyester resins, fluoropolymers, and titanium dioxide pigments are subject to significant price fluctuations tied to petrochemical feedstock costs. This volatility complicates cost forecasting and can compress supplier margins.
- High Capital Investment:Coil coating lines represent a substantial capital expenditure, creating a high barrier to entry. The cost of installing new lines or retrofitting existing ones to handle advanced waterborne or UV-curable chemistries can deter investment.
- Threat of Substitution:In some industrial and construction applications, powder coatings and post-painting processes present a viable alternative. These methods can offer advantages in handling complex shapes or for smaller production runs, challenging coil coating's dominance.
Strategic Opportunities
- Bio-Based Resin Development:Investing in the formulation of bio-based polyester and polyurethane resins presents a significant opportunity. This aligns with sustainability mandates and offers a key point of differentiation for suppliers targeting environmentally conscious specifiers and OEMs.
- Coatings for Electric Mobility:The expanding electric vehicle market creates new applications for functional coatings, including lightweight battery enclosures and thermal management components. These require specialized properties like dielectric insulation and corrosion resistance.
- Expansion in Southeast Asia:Rapid urbanization and industrialization in countries like Vietnam and Indonesia create untapped markets. Targeting the growing construction and manufacturing sectors in this region offers a path to geographic diversification and new revenue.
Industry Challenges
- Regulatory Fragmentation:Suppliers operating globally face a complex web of differing environmental and safety standards, from the EU's REACH to China's GB standards. Navigating these disparate compliance requirements for formulations increases R&D costs and time-to-market.
- Formulation Expertise Scarcity:There is a persistent shortage of polymer chemists and formulation experts skilled in developing next-generation waterborne and low-VOC coating systems. This talent gap can slow innovation and product development cycles for coating manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Functional Coil Coating Market |
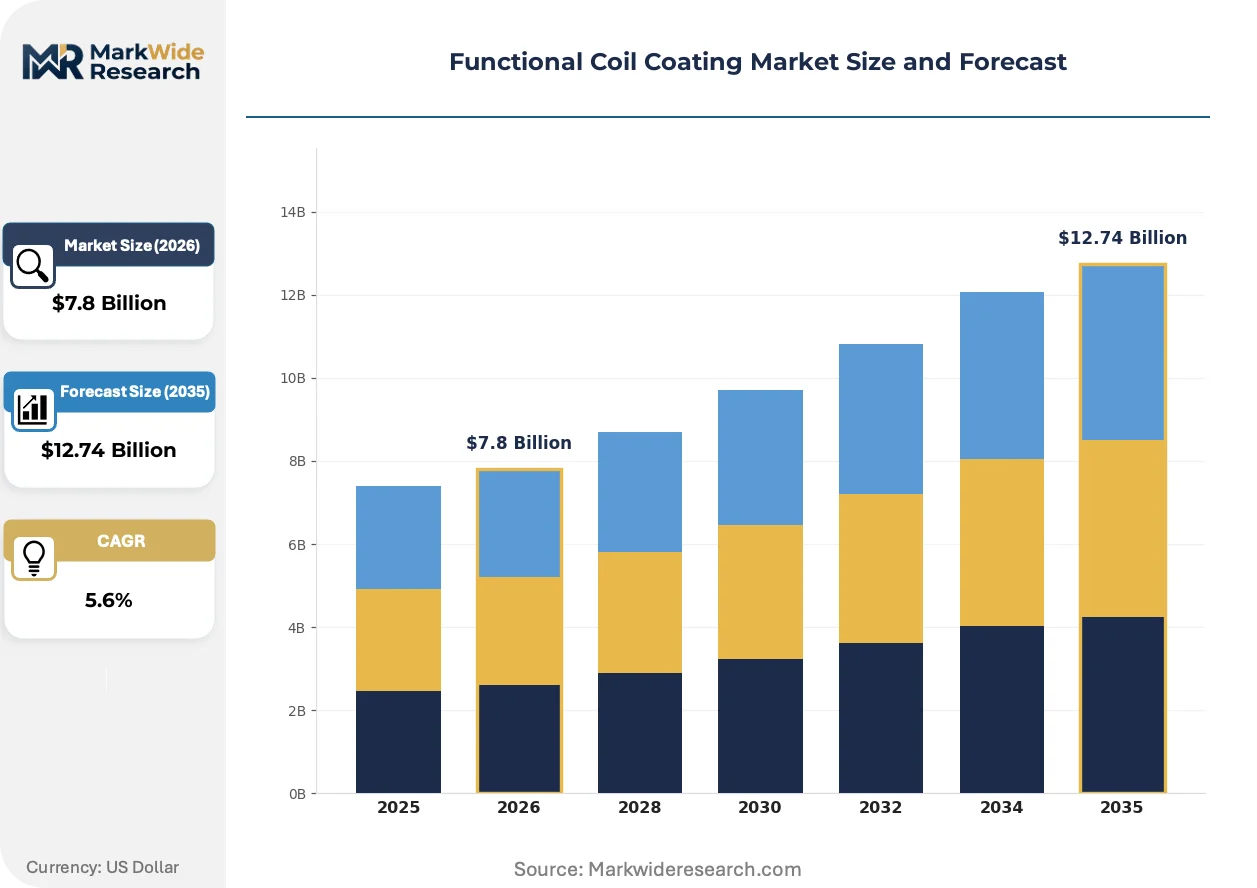
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.74 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluoropolymer, Epoxy, Polyester, Polyurethane, Acrylic, Silicone Application: Building Exteriors, Household Appliances, HVAC Equipment, Transportation Equipment, Metal Furniture, Solar Panels Coating Property: Weather Resistance, Chemical Resistance, Scratch Resistance, UV Protection, Anti-Corrosion, Thermal Insulation End User: OEMs, Metal Fabricators, Contractors, Distributors, Architectural Firms, Industrial Manufacturers |
| Companies Covered | Akzo Nobel, PPG Industries, BASF, Beckers Group, Axalta Coating Systems, Valspar, Nippon Paint Holdings, Kansai Paint, KCC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Functional Coil Coating Market Strategic Shifts & Innovations
Innovation in the functional coil coating market is converging on the dual objectives of enhanced performance and environmental compliance. Material science advancements are enabling thinner, more functional films while regulatory pressures accelerate the phase-out of traditional solvent-borne chemistries.
Self-Stratifying Coating Systems
Self-stratifying coatings are advanced formulations that form multiple distinct, functional layers from a single liquid application during the curing process. Appliance and industrial equipment manufacturers are early adopters, seeking to streamline production and reduce material waste. This technology is miniaturizing the total required film thickness, delivering complex functionalities like a primer and topcoat in one pass without compromising performance.
Mandatory VOC Reduction Frameworks
The EU's Industrial Emissions Directive and complementary national regulations set stringent limits on Volatile Organic Compound (VOC) emissions from industrial processes, including coil coating. This directly impacts formulation choices, forcing a systemic shift away from solvent-borne polyester and toward waterborne acrylic or high-solids polyurethane systems. The building products segment is most affected, with panel producers reformulating to ensure continued market access across Europe.
Specification Based on Lifecycle Data
A significant shift in procurement involves architects and engineers specifying products based on certified Environmental Product Declarations (EPDs). This disrupts traditional sales models focused on price and technical data sheets, giving an advantage to suppliers who provide transparent lifecycle and carbon footprint data. This trend is most advanced in Northern European construction markets, where it is often a prerequisite for public tenders.
Functional Coil Coating Market Segmentation
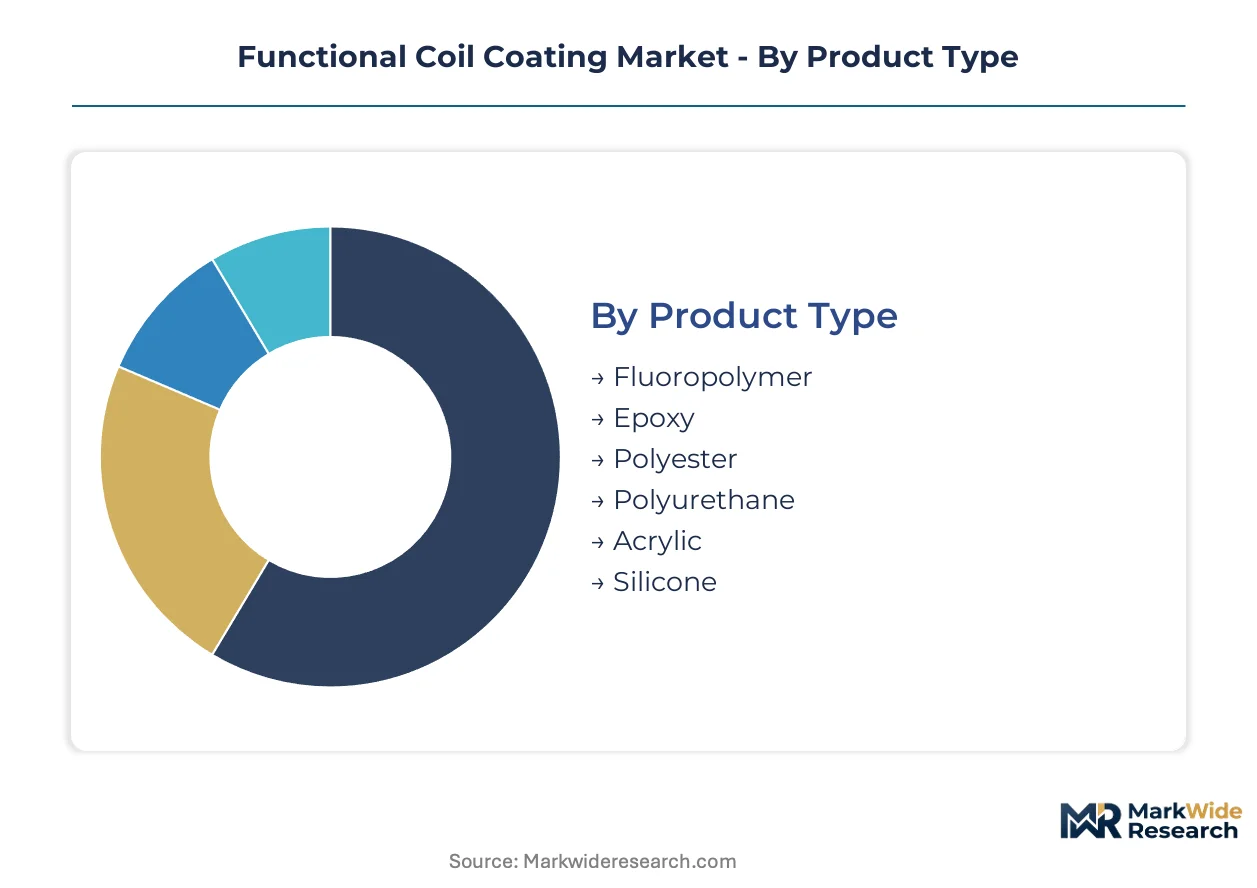
Functional coil coating market segmentation clarifies the diverse product types, applications, and end-user requirements driving industry growth. Understanding these distinct segments helps manufacturers align their R&D and production capabilities with specific market demands. This granular analysis reveals opportunities for product differentiation and strategic market entry.
Product Type:
Margin pools within the product type category gravitate toward specialized, high-performance formulations.
- Fluoropolymer:These coatings, based on resins like PVDF, offer exceptional UV stability, weatherability, and chemical resistance. Demand concentrates in high-performance architectural panels for building exteriors, driven by extended warranty requirements and aesthetic longevity.
- Polyester:Polyester-based systems represent the largest volume segment due to their cost-effectiveness, good flexibility, and broad color palette. Their demand is concentrated in general construction and appliance applications, supported by established manufacturing processes and widespread adoption.
- Epoxy:Epoxy coatings provide excellent adhesion and corrosion protection, often used as primers.
- Polyurethane:Polyurethane systems offer abrasion resistance and flexibility, used in industrial and transportation.
- Acrylic:Acrylic coatings deliver good color retention and gloss, for interior architectural elements.
- Silicone:Silicone-modified coatings provide enhanced heat resistance and flexibility for specific industrial equipment.
Polyester holds installed capacity. Fluoropolymer is rotating up the share rankings.
Application:
Demand focus for coil coatings shifts across various end-use applications, each presenting unique performance requirements.
- Building Exteriors:This segment includes architectural panels, roofing, and wall cladding, requiring coatings with superior weatherability, UV resistance, and energy-efficient properties. Green building codes and a push for solar-reflective cool-roof coatings drive demand in commercial and residential construction.
- HVAC Equipment:Coatings for heating, ventilation, and air conditioning units demand chemical resistance, corrosion protection, and aesthetic appeal. Industrial manufacturers consistently seek durable solutions for both indoor and outdoor components, ensuring long-term product performance.
- Household Appliances:Coatings for appliances prioritize aesthetic finish, chemical resistance, and ease of cleaning.
- Transportation Equipment:This segment requires coatings offering durability and corrosion protection for vehicle parts.
- Metal Furniture:Coatings for furniture emphasize aesthetic appeal, scratch resistance, and environmental durability.
- Solar Panels:Coatings for solar panel frames need corrosion protection and weather resistance in diverse climates.
Building Exteriors are expanding most quickly. HVAC Equipment shows consistent, high-volume requirements.
Coating Property:
Customer type preferences significantly influence the desired coating properties, driven by functional needs and regulatory compliance.
- Anti-Corrosion:These coatings provide essential protection against rust and degradation, extending the lifespan of metal substrates. Demand is pervasive across all applications, particularly in infrastructure projects and marine environments where metal exposure is high.
- Weather Resistance:Coatings designed for weather resistance protect against UV radiation, rain, and temperature fluctuations, maintaining aesthetic appeal and structural integrity. This property is critical for building exteriors and outdoor industrial equipment in varied climates.
- UV Protection:UV protective coatings prevent color fading and material degradation from sunlight exposure.
- Chemical Resistance:These coatings withstand exposure to various chemicals, vital for industrial machinery.
- Scratch Resistance:Scratch-resistant coatings enhance surface durability and aesthetic longevity in consumer goods.
- Thermal Insulation:Thermal insulation coatings reduce heat transfer, contributing to energy efficiency in buildings.
Anti-Corrosion is climbing the fastest. Weather Resistance maintains broad appeal.
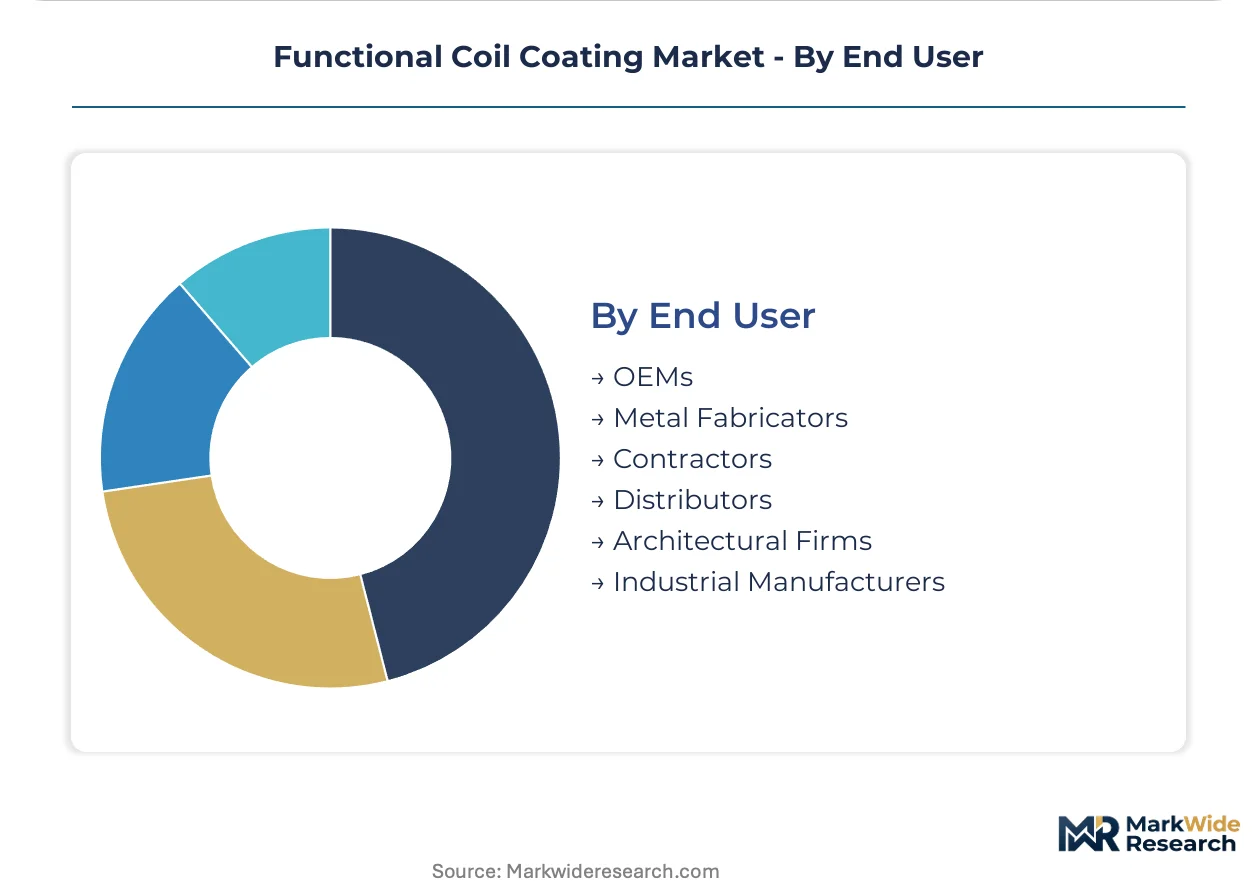
End User:
Procurement patterns among end users vary, reflecting differing scales of operation and technical specification needs.
- Industrial Manufacturers:This segment includes producers of HVAC equipment, automotive components, and other heavy machinery requiring specialized coatings for durability and performance. They often engage in long-term contracts for high-volume, custom-formulated solutions.
- OEMs:Original Equipment Manufacturers, particularly in the appliance and electronics sectors, demand consistent quality, color matching, and supply chain reliability. Their procurement focuses on standardized coatings integrated into large-scale production lines.
- Metal Fabricators:Metal fabricators purchase coil coatings for subsequent processing into various components.
- Contractors:Contractors specify coatings based on project requirements, durability, and cost-effectiveness.
- Architectural Firms:Architectural firms influence material selection, prioritizing aesthetic and sustainability criteria.
- Distributors:Distributors serve smaller fabricators and contractors, offering standard coil coating products.
Industrial Manufacturers are gaining share fastest. OEMs maintain significant purchasing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Functional coil coating consumption varies significantly across regions, driven by distinct building practices and industrial priorities. The United States emphasizes infrastructure durability and commercial construction, while European markets prioritize environmental compliance and energy efficiency. Asian economies focus on rapid urbanization and manufacturing expansion, driving demand for cost-effective and versatile coatings.
United States
Government-backed infrastructure projects and commercial construction stimulate demand for functional coil coatings in the United States. The US EPA's VOC limits compel manufacturers to invest in lower-impact coating formulations. The Gulf Coast region, with its established petrochemical industry, drives innovation in polymer feedstock for new coating systems.
Germany
Energy-efficient construction and high-performance architectural panels drive demand for advanced coil coatings in Germany. The EU's Industrial Emissions Directive and ECHA's REACH framework influence coating chemistry toward sustainable solutions. The Rhine-Ruhr area, a hub for chemical manufacturing, develops advanced waterborne and high-solids polyurethane systems.
China
Rapid urbanization and the expanding construction materials sector fuel demand for functional coil coatings in China. The country's dual carbon goals and national GB standards for construction materials impact product specifications. The Yangtze River Delta, a major manufacturing base, sees significant adoption in appliance and building product sectors.
India
Government-backed infrastructure investment and residential building expansion contribute to functional coil coating demand in India. National building codes increasingly mandate durable and protective coatings for long-term asset performance. Industrial corridors around Mumbai and Delhi support manufacturing demand for polyester and polyurethane systems in construction and industrial applications.
Vietnam
Rapid industrialization and growing manufacturing sectors characterize the demand for functional coil coatings in Vietnam. Local environmental regulations are influencing the shift towards lower-VOC formulations in industrial processes. Ho Chi Minh City and Hanoi regions experience rising demand for coated metal in new commercial and residential developments.
Functional Coil Coating Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the functional coil coating market. This tiered structure reflects varying capabilities in R&D, global reach, and raw material sourcing. Global material science conglomerates, specialized regional players, and niche solution providers define the competitive landscape. Companies pursue strategic partnerships for technology co-development and engage in targeted capacity expansion to meet regional demand.
Within the global material science segment, Akzo Nobel, PPG Industries, and Beckers Group exemplify distinct market approaches. Akzo Nobel, a Dutch multinational, often represents the material science conglomerate archetype, leveraging extensive R&D in fluoropolymer and polyurethane systems. PPG Industries, a US-based entity, occupies a position of global scale and broad market penetration. Beckers Group, a Swedish company, anchors the specialized solutions segment, focusing on customized offerings for niche industrial applications.
| Leading Market Players |
|---|
| Akzo Nobel |
| PPG Industries |
| BASF |
| Beckers Group |
| Axalta Coating Systems |
| Valspar |
| Nippon Paint Holdings |
| Kansai Paint |
| KCC Corporation |
Cost & Logistics Intelligence
A 6-8 week lead time for specialized coil coating systems directly shapes contract negotiations and supplier pricing power within the functional coil coating market.
Pricing Analysis
Long-term offtake agreements characterize pricing for high-volume functional coil coatings in the appliance sector. Price differentiation stems from customization levels for niche industrial segments and the performance grade of fluoropolymer systems. Pricing pressure stems from raw material price volatility, particularly for polyester resins. Household appliance OEMs represent the most price-sensitive buyers, while architectural firms specifying high-performance building exteriors are least sensitive.
Supply Chain Analysis
Port congestion in Southeast Asian hubs currently impacts inbound logistics costs for key petrochemical feedstocks. Geographic supply concentration for critical raw materials like titanium dioxide and fluoropolymers centers on China and Germany. Raw material price volatility represents a significant structural supply chain risk for coating manufacturers. Downstream distribution runs primarily through direct channels for large industrial manufacturers and OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A recent consolidation among large industrial manufacturers shifts buying power in the functional coil coating market.
For Market Incumbents:
Secure long-term supply agreements for critical bio-based resins to mitigate raw material price volatility. Expand R&D into advanced waterborne polyurethane systems to counter the threat of stringent VOC regulations. Invest in capacity additions within Southeast Asia to capitalize on rapid urbanization. Enhance technical support and customization capabilities for niche industrial segments to defend margin against new entrants.
For New Entrants and Emerging Players:
A fast-track certification program for sustainable low-VOC coatings offers a clear entry point for new suppliers. Target the expanding building exteriors segment in Vietnam with energy-efficient architectural panels. Focus on offering specialized solutions for thermal management in the electric mobility sector. Leverage a value-based pricing strategy that highlights environmental compliance and lifecycle benefits.
For Investors and Strategic Acquirers:
Long-term, this sits as a niche technology play because specialized formulation expertise remains a high barrier to entry. Target acquisition profiles include mid-sized firms with proprietary bio-based resin technologies or strong market positions in specific regional regulatory clusters. The signal to watch is the rate of adoption for certified Environmental Product Declarations in public tenders.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Bio-Based Resin R&D | This aligns with sustainability mandates and offers differentiation for environmentally conscious specifiers. |
| Expand Capacity in Southeast Asia | This capitalizes on rapid urbanization and manufacturing growth in Vietnam and India. |
| Develop Advanced Waterborne Systems | This ensures compliance with stringent VOC reduction frameworks like the EU's Industrial Emissions Directive. |
| Form Strategic Partnerships with OEMs | This secures long-term contracts and integrates coating solutions early in product design cycles. |
| Acquire Niche Formulation Specialists | This strengthens expertise in high-performance fluoropolymer or polyurethane systems for demanding applications. |
Research Approach
Findings reconcile primary fieldwork against secondary review of industry association reports, regulatory body publications, and company financial filings. This involved conversations with R&D chemists, procurement managers at industrial manufacturers, architectural specifiers, and plant operators. Bottom-up and top-down triangulation validated market sizing and growth projections.
Product type, application, coating property, end user, and regional regulatory compliance define the core dimensions modeled for this analysis. The analytical framework derives compound annual growth rates by assessing historical trends and future industry-specific inputs like construction spending forecasts. Electric vehicle production forecasts also serve as a key input for specialized coating demand across the analysis window.
Underlying assumptions cover stable geopolitical conditions and consistent regulatory enforcement, with deviation risk concentrated in raw material supply disruptions. Unexpected shifts in environmental regulations for VOCs represent another critical risk factor. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
North America Epoxy Powder Coatings Market
Coatings
South America Thermal Spray Market
Coatings
United Arab Emirates Protective Coatings Market
Coatings
Europe Super Hydrophobic Coatings Market
Coatings
Global Plastic Coatings Market
Coatings
Asia-Pacific Floor Coatings Market
Coatings
Coating Binders Market
Coatings
Diamond-Like Carbon Coatings Market
Coatings
Global Solar Panel Coatings Market
Coatings
Coating Pre-Treatment Market
Coatings
Self-Healing Coatings Market
Coatings
Epoxy Powder Coatings Market
Coatings
Russia Protective Coatings Market
Coatings
Canada Automotive OEM Coatings Market
Coatings
Stealth Coating Material Market
Coatings
Anti-Microbial Coatings Market