
 Global Surface Protection Films Market | 2026-2036
Global Surface Protection Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surface Protection Films Market Intelligence
The EU's REACH regulation, governing chemical substances, is hardening market entry requirements for films utilizing certain adhesives. 3M Company leverages its extensive R&D in adhesive chemistry to comply with such evolving standards. Nitto Denko Corporation specializes in high-performance films for the electronics sector, navigating complex specifications. Meanwhile, Berry Global Inc. competes on manufacturing scale and broad-portfolio offerings for industrial applications.
Surface protection films are temporary, adhesive-coated plastic layers designed to prevent scratches, abrasion, and contamination on various substrates. These films, often made from polyethylene or polypropylene, feature controlled adhesion levels to ensure clean removal without leaving residue. Polyethylene-based films command the largest volume due to cost-effectiveness, while Polyurethane films see strong demand in high-value automotive assemblies. Within applications, the construction finishes segment is mature, whereas electronics applications for displays and components represent a high-growth area.
Compliance with ISO 9001 for quality management is a baseline expectation for suppliers. Regulations like the EU's RoHS directive and China's GB standards for electronics restrict hazardous substances, influencing film composition. Stakeholders must monitor the development of bio-based and recyclable film materials to align with corporate sustainability goals and circular economy mandates.
Market Dynamics
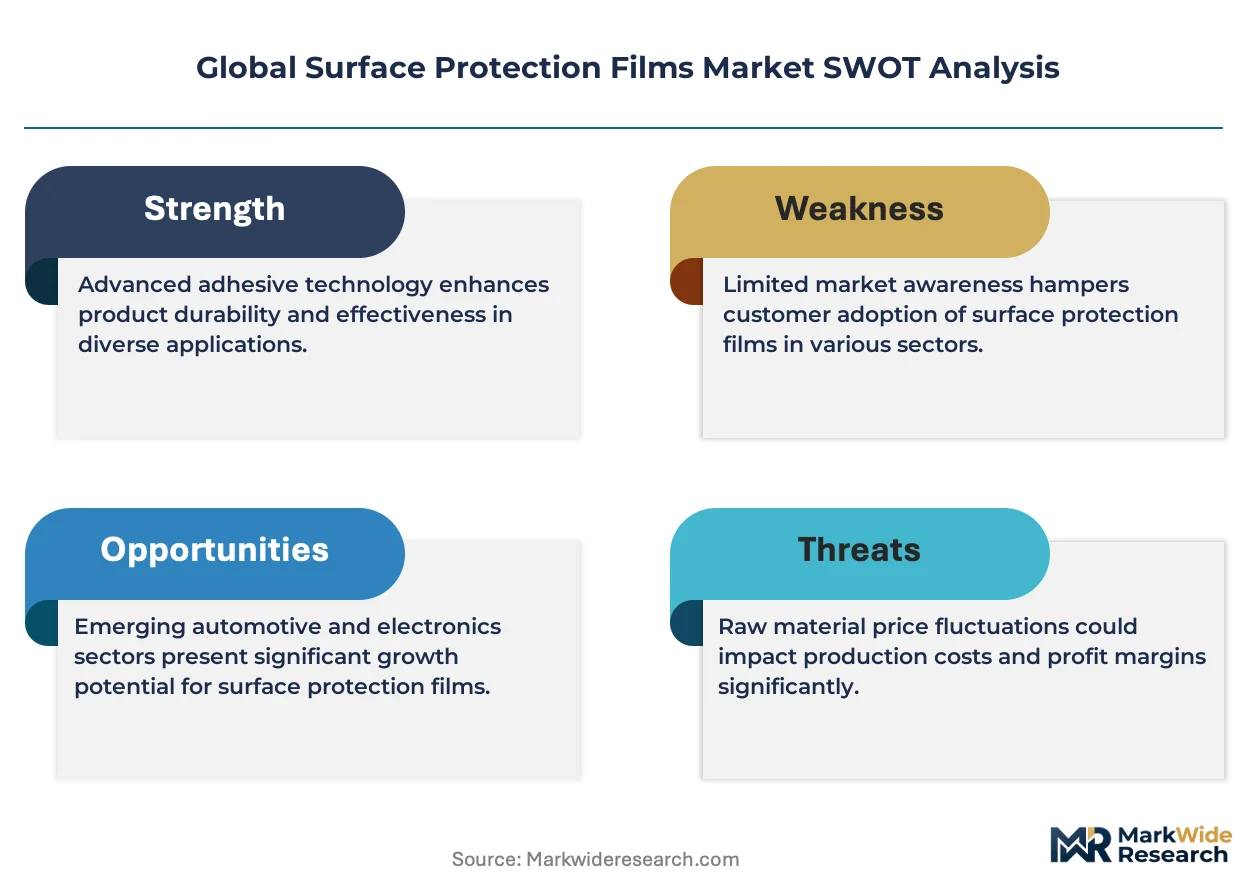
The market's central tension lies between the demand for cost-effective protection using commodity polymers and escalating regulatory pressures on chemical compositions. This dynamic forces innovation in adhesive chemistry to meet standards like REACH without compromising performance or price competitiveness.
Growth Catalysts
- Self-Healing Coatings:The development of self-healing and anti-fingerprint coatings is a key driver, particularly within the automotive assemblies sector for protecting high-gloss components and sensitive electronics during transport and installation.
- Electronics Manufacturing:Demand is concentrating within China's electronics manufacturing hubs, where films are essential for protecting displays, lenses, and other sensitive components from scratches and contamination throughout the assembly process.
- Construction Finishes:The construction industry's use of films to protect finished surfaces like metal panels, glass, and decorative laminates provides a mature but stable volume base, supported by commercial and residential building activity.
Market Restraints
- Input Cost Volatility:The market is sensitive to price fluctuations in petroleum-based raw materials, specifically polyethylene and polypropylene resins, which can compress manufacturer margins and impact end-user pricing.
- Regulatory Friction:The EU's REACH regulation imposes stringent requirements on chemical substances, complicating market entry for films using certain adhesives and increasing the cost of compliance and formulation development.
- Residue and Removal Issues:Inconsistent adhesion control can lead to film-lifting or adhesive residue upon removal, causing substrate damage and reputational risk for suppliers, particularly in high-value applications like automotive paint.
Strategic Opportunities
- Bio-Based Materials:The development of films from bio-based polymers or with recycled content presents an opportunity to align with corporate sustainability goals and circular economy mandates, appealing to environmentally conscious customers.
- Functional Film Integration:There is a significant opportunity in developing films with added functionalities, such as anti-microbial properties for medical surfaces or UV-blocking capabilities for long-term outdoor protection of building materials.
- High-Value Electronics:Targeting emerging applications in flexible displays, foldable devices, and advanced optical components offers a high-margin growth avenue for specialized, high-performance protective films.
Industry Challenges
- Adhesion Customization:Developing and scaling production for films with precise adhesion levels tailored to a wide variety of substrates and environmental conditions remains a significant technical challenge requiring extensive R&D investment.
- Compliance Timelines:Navigating the complex and evolving landscape of substance regulations, such as the EU's RoHS directive and China's GB standards for electronics, creates long lead times for product qualification and certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surface Protection Films Market |
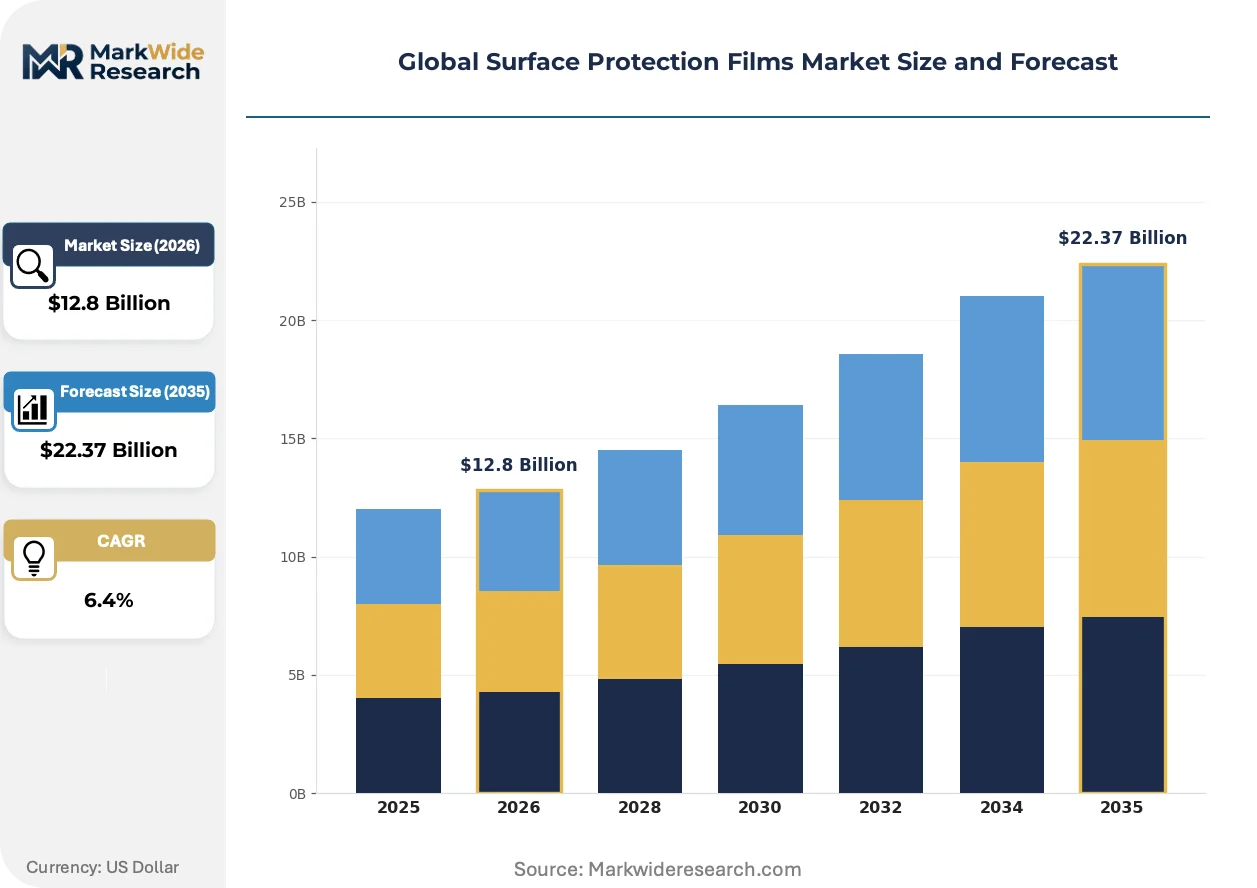
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polyvinyl Chloride, Polyurethane, Acrylic, Polyester, Polypropylene Application: Electronics, Construction Finishes, Packaging Protection, Automotive Assemblies, Furniture Surfaces, Marine Equipment End User: OEM Assemblers, Commercial Builders, Packaging Manufacturers, Vehicle Manufacturers, Interior Designers, Shipyards Distribution Channel: Direct Sales, Distributors, E-Commerce Platforms, Wholesale Suppliers, Retail Outlets, Industrial Supply Stores |
| Companies Covered | Tesa SE, Toray Industries, Inc., 3M Company, Saint-Gobain Performance Plastics, Berry Global Inc., Nitto Denko Corporation, LINTEC Corporation, XPEL, Inc., Avery Dennison Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surface Protection Films Market Strategic Shifts & Innovations
The convergence of advanced material science and application-specific performance demands is transforming surface protection films from simple protective layers into functional components. This evolution is driven by technological advancements in coatings, stricter environmental regulations, and shifts in end-user procurement criteria.
Self-healing coatings are a class of smart polymers integrated into the film's top layer that can repair minor scratches and abrasions. The automotive and high-end consumer electronics sectors are the primary adopters, seeking to preserve pristine surface finishes on premium products. The integration of this advanced chemistry into the film's structure is unifying the separate functions of temporary protection and long-term surface preservation.
The EU's Circular Economy Action Plan is compelling film manufacturers to prioritize material sustainability and end-of-life management. This regulatory push accelerates the transition from complex, multi-material laminates toward mono-material polyethylene films with easily separable, non-contaminating adhesives. The construction and industrial metal fabrication segments are most affected, redesigning specifications to improve the recyclability of both the film and the protected substrate.
A notable behavioral shift is occurring as buyers increasingly specify films based on empirical performance data rather than traditional material metrics. This disrupts legacy sales channels that relied on established relationships, creating an opening for suppliers who provide comprehensive technical data on adhesion, clean removal, and substrate compatibility. This data-driven selection process is most pronounced in the precision-critical electronics industry, particularly in South Korea and China.
Global Surface Protection Films Market Segmentation
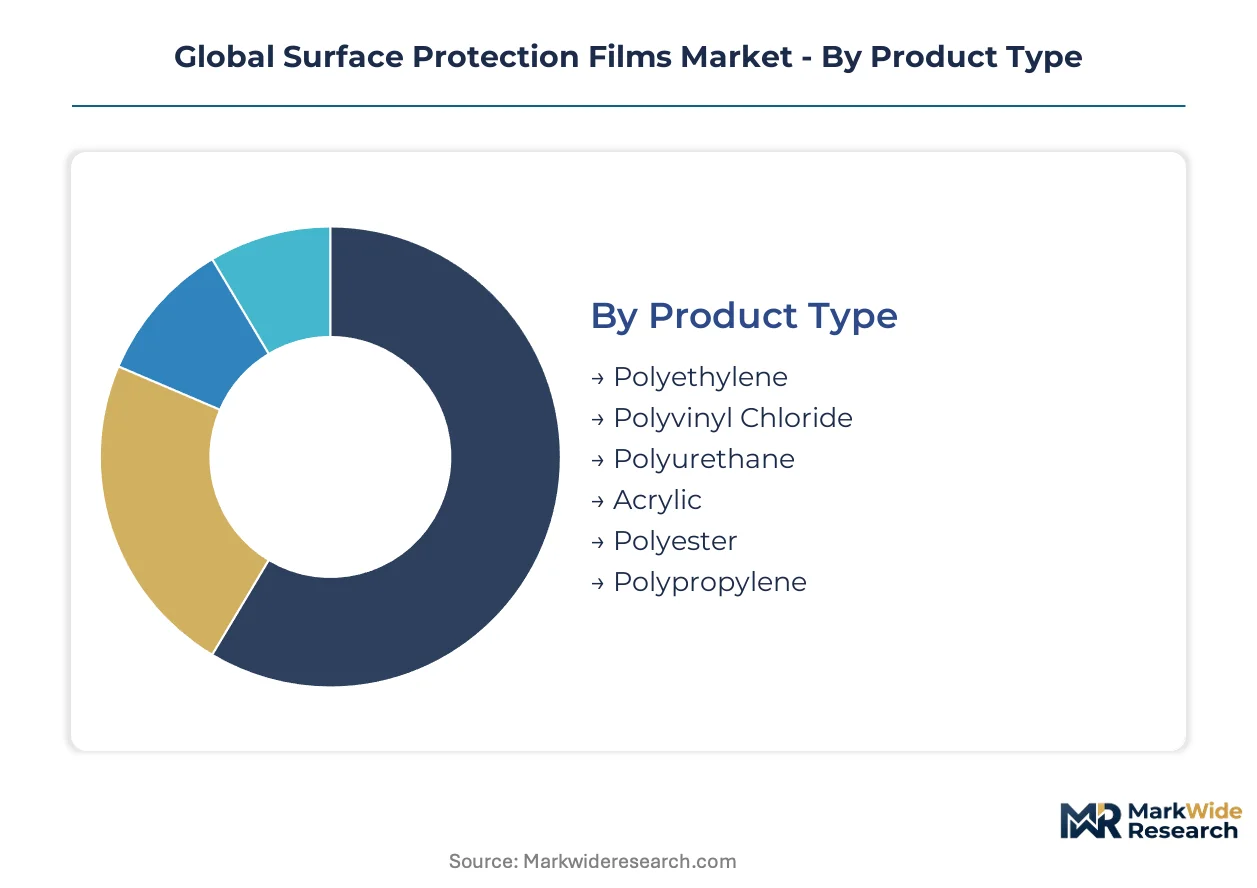
The Global Surface Protection Films Market divides into distinct segments, each driven by specific material properties, application demands, and end-user requirements. Understanding these granular divisions helps identify areas of concentrated demand and specialized growth opportunities within the broader market landscape.
Product Type:
Product type segmentation highlights the material science and formulation choices critical for film performance across diverse applications.
- Polyethylene:These films, derived from petroleum-based resins, command the largest volume due offering cost-effectiveness and versatile adhesion properties. Demand is widespread across industrial and construction sectors, particularly for temporary surface protection of large panels.
- Polyurethane:Known for superior abrasion resistance and elasticity, polyurethane films protect high-value surfaces from impact and scratches. Strong demand originates from automotive assemblies, where these films safeguard painted surfaces and interior components during transport and installation.
- Polyvinyl Chloride:PVC films provide good chemical resistance and conformability, often used in applications requiring durable, weather-resistant protection. The construction finishes segment utilizes these films for window profiles and exterior cladding.
- Acrylic:Acrylic-based films deliver excellent optical clarity and UV resistance, making them suitable for displays and outdoor applications. Electronics manufacturers often specify these films for sensitive screen protection.
- Polyester:Polyester films offer high tensile strength and dimensional stability, preferred for applications needing robust, tear-resistant protection. These films find use in demanding industrial processes and high-temperature environments.
- Polypropylene:Polypropylene films balance cost and performance, providing good moisture barrier properties and moderate scratch resistance. Packaging protection and some general industrial applications represent the primary end-uses.
Polyethylene leads on scale; Polyurethane leads on momentum.
Application:
Application-based segmentation reveals how surface protection films integrate into various industry workflows and product life cycles.
The application of surface protection films is highly specialized, addressing distinct needs from high-tech manufacturing to heavy industry.
- Electronics:Films are essential for safeguarding displays, lenses, and sensitive components from scratches and contamination during assembly and transit. Demand concentrates within China's electronics manufacturing hubs for protecting consumer devices.
- Automotive Assemblies:These films protect vehicle components, such as painted body panels, interior trim, and high-gloss surfaces, from damage throughout the manufacturing, transport, and pre-delivery stages. High-value automotive segments in Germany and Japan drive the adoption of specialized films.
- Construction Finishes:This mature segment utilizes films to protect finished surfaces like metal panels, glass, and decorative laminates during building construction and renovation. Commercial and residential building activity across North America provides a stable volume base.
- Packaging Protection:Films secure products within packaging against abrasion, dust, and moisture, maintaining aesthetic integrity for consumer goods. Manufacturers of sensitive or high-gloss packaged items rely on these protective layers.
- Furniture Surfaces:Films prevent scratches and scuffs on furniture components and finished pieces during manufacturing, shipping, and installation. Interior designers and furniture manufacturers often specify these films.
- Marine Equipment:Protective films guard boat hulls, decks, and interior surfaces against environmental damage, UV exposure, and operational wear. Shipyards and marine maintenance companies use these films for both new builds and repairs.
Electronics applications expand most quickly, while construction finishes provide substantial volume.
End User:
End-user segmentation identifies the primary customer groups and their specific procurement behaviors for surface protection films.
Different end-user groups require tailored film solutions, reflecting varied operational scales and technical specifications.
- OEM Assemblers:These manufacturers integrate components into final products, requiring films with precise adhesion and clean removal to protect surfaces during assembly. The electronics and automotive sectors represent significant OEM demand.
- Vehicle Manufacturers:Automotive original equipment manufacturers procure specialized films for protecting vehicle exteriors and interiors throughout the production and logistics chain. Compliance with stringent automotive standards drives film selection.
- Commercial Builders:Construction companies and contractors use protective films to safeguard installed finishes like windows, flooring, and metalwork from damage during project completion. Large-scale infrastructure projects fuel consistent demand.
- Packaging Manufacturers:Companies producing packaging materials integrate protective films to enhance product safety and maintain aesthetic quality for their clients. The consumer goods industry relies heavily on these suppliers.
- Interior Designers:These professionals specify films for protecting high-end furniture, fixtures, and architectural elements during installation and client handover. Customization and aesthetic preservation are key considerations.
- Shipyards:Marine construction and repair facilities utilize robust films to protect sensitive surfaces on vessels from welding spatter, paint overspray, and general damage. Durability in harsh environments is a critical requirement.
OEM Assemblers represent broad demand, while Vehicle Manufacturers prioritize performance.
Distribution Channel:
Distribution channel segmentation outlines the various routes through which surface protection films reach their diverse end-users.
The distribution landscape reflects both direct engagement for large-volume customers and broad access for smaller, specialized buyers.
- Direct Sales:Manufacturers engage directly with large industrial clients and OEM partners, offering custom solutions and technical support. This channel is prevalent for high-volume, specialized film orders in automotive and electronics.
- Distributors:Independent distributors provide regional market access, stocking a range of products and offering localized logistics and customer service. Small to medium-sized enterprises often source films through this channel.
- E-Commerce Platforms:Online marketplaces facilitate broader reach for standardized film products, particularly for smaller businesses and niche applications. Digital sales platforms are gaining share for convenience and transparency.
- Wholesale Suppliers:These suppliers purchase films in bulk from manufacturers and resell them to a network of smaller distributors, retailers, or directly to large end-users. This channel supports high-volume, commodity film distribution.
- Retail Outlets:Retail stores cater to individual consumers and small businesses, offering smaller quantities of general-purpose protective films. Hardware stores and specialty shops fall into this category.
- Industrial Supply Stores:These specialized stores provide a range of industrial products, including protective films, to manufacturing facilities and construction sites. They offer convenience for immediate operational needs.
Direct Sales maintains strategic importance; E-Commerce Platforms exhibit the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Highly skilled engineering and manufacturing workforces across key global regions anchor demand for surface protection films. These specialized teams require advanced protective solutions for sensitive components and high-value assemblies. Regional variations in industrial focus and regulatory frameworks influence market dynamics.
China
China's vast electronics manufacturing capabilities drive significant demand for surface protection films, particularly for displays and components. Compliance with China's GB standards for electronics influences film composition and material selection. The Pearl River Delta and Yangtze River Delta regions concentrate extensive electronics assembly operations.
Germany
Germany's advanced automotive sector demands high-performance surface protection films for painted body panels and interior components. The EU's REACH regulation imposes stringent requirements on chemical substances used in adhesive formulations. Automotive manufacturing clusters in Bavaria and Baden-Württemberg consistently procure specialized films.
United States
The United States construction finishes segment provides a stable volume base for protective films, alongside growing demand from aerospace manufacturing. Environmental Protection Agency (EPA) guidelines influence material disposal and recyclability considerations for film products. Major industrial clusters in the Southeast and West Coast utilize films for high-value manufacturing.
Japan
Japan's precision manufacturing industries, especially in automotive and advanced electronics, require highly specialized surface protection films. Compliance with JIS standards ensures quality and performance benchmarks for film suppliers. The Kanto and Chubu regions, home to major automotive and electronics companies, drive continuous innovation.
South Korea
South Korea's leadership in flexible displays and foldable devices creates a high-growth avenue for specialized, high-performance protective films. National quality standards guide film selection and application within the country's advanced manufacturing sectors. The Seoul Capital Area and Busan-Ulsan regions are key centers for electronics and automotive production.
Global Surface Protection Films Market Key Industry Players
The competitive structure tilts toward specialized manufacturers offering tailored adhesive solutions for diverse industrial applications. While a few large corporations command significant market share, numerous niche players focus on high-performance films for specific end-uses. Strategic archetypes include integrated material science giants, specialized film converters, and regional industrial suppliers. Dominant competitive moves involve strategic partnerships for new material development and continuous portfolio diversification into high-value segments.
Specialists in advanced adhesive chemistry and material science, such as 3M Company, occupy a position at the premium end of the market. These entities leverage extensive research and development capabilities to comply with evolving regulations like the EU's REACH directive. Nitto Denko Corporation exemplifies high-performance film providers, catering to the complex specifications of the electronics sector. Meanwhile, Berry Global Inc. represents large-scale manufacturers competing on broad-portfolio offerings for industrial and packaging applications. These players collectively anchor innovation in film functionality, driving advancements like self-healing and anti-fingerprint coatings.
| Leading Market Players |
|---|
| Tesa SE |
| Toray Industries, Inc. |
| 3M Company |
| Saint-Gobain Performance Plastics |
| Berry Global Inc. |
| Nitto Denko Corporation |
| LINTEC Corporation |
| XPEL, Inc. |
| Avery Dennison Corporation |
| Others |
Cost & Logistics Intelligence
OEM Assemblers, particularly in electronics, concentrate demand for contract-based pricing. This model ensures stable supply and customized film solutions for high-volume manufacturing.
Pricing Analysis
Bundled offerings, including technical support and custom formulation, command premium pricing in specialized segments. Unbundled per-unit transactional pricing dominates commodity polyethylene films. Price differentiation stems from customization levels for high-value applications and volume scale for industrial buyers. Pricing softness reflects input cost volatility in petroleum-based raw materials, particularly for polypropylene and polyethylene resins. Commercial Builders are highly price-sensitive for construction finishes, while Vehicle Manufacturers prioritize performance over cost for critical automotive assemblies.
Supply Chain Analysis
Direct Sales channels handle high-volume OEM demand, particularly for specialized films in automotive and electronics. Distributors provide localized access for smaller industrial and construction clients across North America and Europe. China and Germany are key production hubs for films and their raw materials. The market sources polyethylene and polypropylene resins from global petrochemical suppliers. Commodity price volatility for petrochemical feedstocks presents a significant structural risk for manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The surface protection films market presents a geographic-arbitrage opportunity, leveraging lower manufacturing costs in China against the high-performance demands and stringent EU's REACH regulations in Europe. This dynamic encourages strategic sourcing and production alignment.
For Market Incumbents: Anticipate increasing regulatory scrutiny on chemical compositions by investing heavily in R&D for bio-based and recyclable materials. Deepen vertical integration into adhesive chemistry development to control formulation and secure compliance with evolving standards like the EU's RoHS directive. Expand capacity in high-growth electronics manufacturing regions, particularly within China, to counter market share erosion from regional specialists.
For New Entrants and Emerging Players: Independent distributors offer a viable entry point into the fragmented construction finishes segment, which provides a stable volume base. Focus on developing functional films with anti-microbial or UV-blocking properties for niche applications in medical or outdoor building materials. Leverage e-commerce platforms to reach smaller businesses requiring standardized, general-purpose films with clear performance data.
For Investors and Strategic Acquirers: Integrated material science giants are the most active acquirers in this space, seeking specialized adhesive chemistry and functional film technologies. Long-term viability depends on acquiring firms with robust R&D pipelines for self-healing and bio-based materials, aligning with future sustainability mandates. Watch for increased M&A activity targeting companies with proven expertise in high-value electronics applications as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D for Bio-based Films | Drives compliance with circular economy mandates and appeals to environmentally conscious customers. |
| Capacity Expansion in Asia | Secures supply for China's electronics manufacturing hubs and reduces logistics costs. |
| Partnerships for Adhesive Tech | Accelerates development of self-healing coatings for high-gloss automotive components. |
| Acquisition of Niche Specialists | Enhances portfolio in high-value electronics applications and specialized optical components. |
| Digital Sales Channel Development | Expands market reach for standardized film products, improving accessibility for SMEs. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region. This involved combining extensive primary interviews with industry stakeholders such as R&D directors, procurement leads at OEM Assemblers, and distribution channel partners. Secondary validation drew from customs data, regulatory filings like EU's REACH documents, and industry association reports. Bottom-up and top-down triangulation ensured data integrity.
Volume and value outputs were modeled at a granular level across product type, application, end-user, and distribution channel. The analytical framework projected demand throughout the forecast period, with CAGRs derived from historical growth trends and anticipated technological advancements. Key forecast inputs included petroleum-based raw material price trends and evolving regulatory compliance costs.
Revisions become necessary when significant shifts in global trade policies or unforeseen raw material supply disruptions materialize. Forecasts reflect assumptions regarding stable regulatory environments and consistent technological adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Sol-Gel Coatings Market
Coatings
Industrial Coatings Market
Coatings
Electrical Insulation Coatings Market
Coatings
Packaging Coatings Market
Coatings
Australia Industrial Coatings Market
Coatings
Compound Coating Market
Coatings
Glazes Market
Coatings
Electronic Protection Device (EPD) Coatings Market
Coatings
Global Plastic Coatings Market
Coatings
Wood Preservative Coatings Market
Coatings
Fillers and Coating Market
Coatings
Anti-Microbial Coatings Market
Coatings
Global Flat Glass Coatings Market
Coatings
Intumescent Fire Retardant Coating Market
Coatings
Thermal Barrier Coatings Market
Coatings
Morocco Automotive OEM Coatings Market