
 Hydrophilic Coatings Market | 2026-2036
Hydrophilic Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrophilic Coatings Market Intelligence
Expertise in polymer science and surface modification is bifurcating the competitive landscape. Surmodics Incorporated leverages its deep R&D in surface chemistry to develop proprietary coating solutions for complex medical devices. DSM competes on the basis of its broad portfolio of high-performance polymers and scalable manufacturing capabilities. Biocoat Incorporated specializes in custom-developed coatings for the cardiovascular and neurovascular device markets.
Hydrophilic coatings are ultrathin surface layers engineered to attract and hold water molecules, creating a lubricious surface. These coatings, often based on polymers like polyurethanes or polyvinylpyrrolidone (PVP), reduce the coefficient of friction on devices, primarily to enhance patient comfort and device maneuverability during medical procedures. The medical devices application represents the largest and most profitable segment, driven by demand for minimally invasive surgical tools. Polymer-based formulations dominate the product landscape, while UV-cured coating technologies are gaining share due to their rapid cure times and solvent-free nature.
Regulatory frameworks from the U.S. FDA, the European Union's EMA under its Medical Device Regulation (MDR), and China's NMPA impose stringent requirements for biocompatibility and leachables. These regulations directly influence material selection and the validation processes for coatings applied to medical devices, creating high barriers to entry. Suppliers must therefore continuously invest in clinical data and documentation to secure market access across key geographies.
Market Dynamics
The central dynamic shaping the hydrophilic coatings market is the increasing stringency of global regulatory frameworks for medical devices. This pressure from bodies like the EU's EMA under its MDR is forcing innovation in both polymer chemistry and application processes to ensure biocompatibility.
Growth Catalysts
- Minimally Invasive Procedures:The rising volume of minimally invasive surgeries worldwide, especially for an aging population in countries like Japan, directly increases the need for lubricious coatings on catheters, guidewires, and endoscopic devices to improve patient outcomes.
- UV-Curing Technologies:Advances in ultraviolet (UV) curing offer rapid, solvent-free processing, which reduces manufacturing cycle times and environmental impact. This efficiency is a significant pull for high-volume medical device manufacturers.
- Medical Technology Clusters:Concentrated government support and private investment in medical device manufacturing hubs, such as those in Ireland, create dense ecosystems of demand and foster close collaboration between device makers and coating specialists.
Market Restraints
- Regulatory Hurdles:The extensive time and high cost required to achieve and maintain regulatory compliance with standards from the U.S. FDA, the EU's MDR, and China's NMPA create significant barriers to entry for new coating formulations and suppliers.
- Raw Material Price Volatility:The market is sensitive to price fluctuations and supply chain disruptions for key specialty polymers, such as medical-grade polyvinylpyrrolidone (PVP) and polyurethanes, which can compress margins for coating formulators.
- Substrate Adhesion Complexity:Ensuring durable adhesion of hydrophilic coatings to novel and complex polymer substrates used in next-generation devices presents a persistent technical challenge. This requires continuous research and development to avoid delamination issues during procedures.
Strategic Opportunities
- Functional Coating Integration:There is a significant opportunity to develop and commercialize coatings that combine hydrophilicity with other active properties, such as antimicrobial, anti-thrombogenic, or drug-eluting capabilities, creating higher-value, multifunctional surfaces.
- Expansion into Industrial Applications:Adapting hydrophilic coating technologies for non-medical sectors offers new growth avenues. Potential uses include creating anti-fog surfaces for automotive sensors and optical lenses or developing anti-fouling coatings for marine equipment.
- Emerging Market Penetration:Targeting nascent medical device manufacturing sectors in geographies like Brazil and India presents a key opportunity. Local device makers in these regions often lack in-house coating expertise, creating demand for specialized partners.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of polymer scientists and chemical engineers with dual expertise in surface modification chemistry and the intricacies of medical device regulatory pathways constrains R&D and scale-up activities for many firms.
- Documentation and Validation Burden:The operational challenge of continuously generating, managing, and updating extensive documentation on biocompatibility and leachables to satisfy diverse international regulators like Health Canada and Swissmedic is resource-intensive.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrophilic Coatings Market |
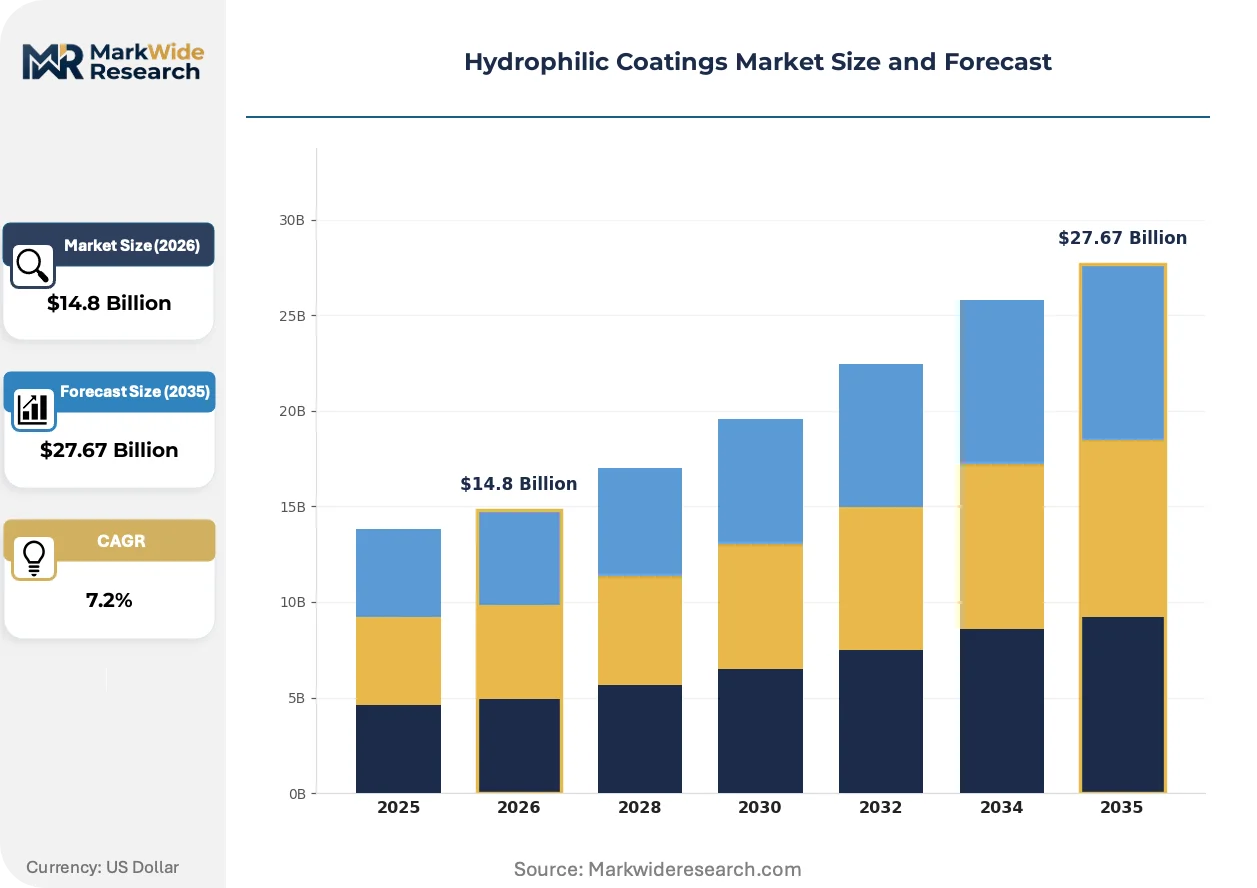
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $27.67 Billion |
| CAGR (2026 – 2036) | 7.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer, Silicone, Hydrogel, Bio-based Coatings Application: Medical Devices, Automotive, Electronics, Textile End User: Healthcare, Automotive Manufacturers, Electronics Firms, Textile Producers Coating Technology: Solvent-based, Water-based, UV-cured, Spray Coating |
| Companies Covered | Applied Medical Coatings, Corning Inc., Aculon, Inc., Harland Medical Systems, Surmodics Incorporated, Biocoat Incorporated, AST Products, Inc., DSM, Hydromer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrophilic Coatings Market Strategic Shifts & Innovations
Material science advancements and data-driven process controls are converging to produce more reliable and functional hydrophilic surfaces. This evolution is shifting the competitive focus from simple lubricity to predictable, long-lasting performance documented through rigorous validation for specific medical applications.
Self-healing hydrophilic coatings represent a significant product evolution. These materials are engineered to autonomously repair minor surface scratches, thereby preserving their lubricious properties throughout a medical procedure. High-value device segments, including neurovascular and complex cardiology, are the primary early adopters for these advanced formulations. This innovation is decomposing the established paradigm of a coating's static performance life, introducing a more resilient and dynamic surface functionality.
The European Union's Medical Device Regulation (MDR) is a major policy shift impacting the entire supply chain. It imposes stricter requirements for clinical evidence, post-market surveillance, and traceability for all medical devices, including those with surface coatings. This forces coating suppliers to engage in deeper partnerships with device manufacturers to generate the necessary validation data, particularly affecting market access in key EU countries like Germany and France.
A notable demand-side shift involves the move from simple component sourcing to integrated solution partnerships. Medical device original equipment manufacturers are increasingly bypassing transactional purchasing of coatings. They now favor strategic suppliers who provide a comprehensive service bundle, including formulation development, application process optimization, and direct support for regulatory submissions, a trend highly visible in the United States.
Hydrophilic Coatings Market Segmentation
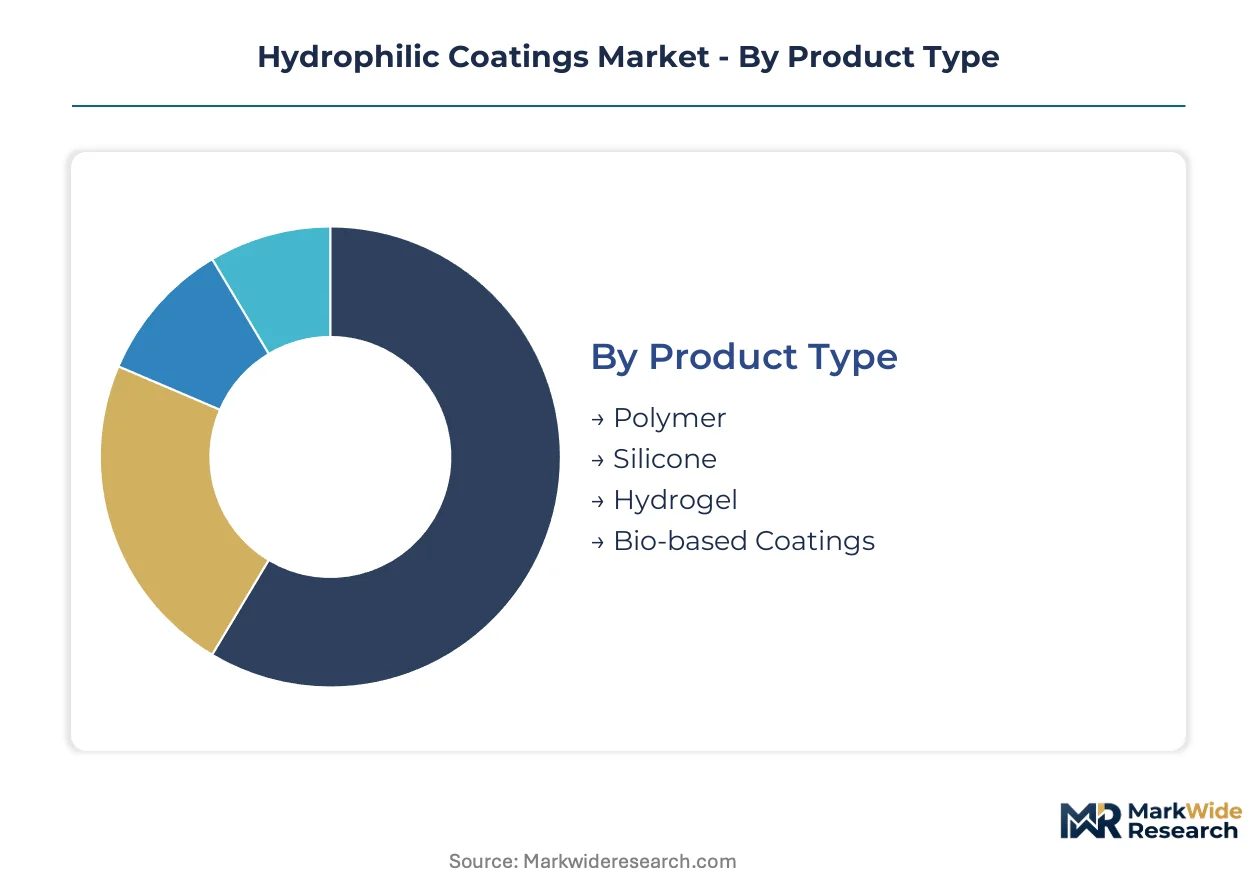
Understanding the hydrophilic coatings market requires a granular view of its diverse segments, each presenting unique material science challenges and commercial opportunities. This segmentation analysis dissects the market across product types, applications, end-users, and coating technologies, revealing distinct competitive dynamics and growth trajectories.
Product Type:
The hydrophilic coatings market faces significant substitution pressure, particularly from conventional lubricious materials, compelling product developers to emphasize performance differentiation and regulatory compliance.
- Polymer:These coatings, often based on polyurethanes or PVP, provide excellent lubricity and biocompatibility. Demand concentrates in medical devices, where enhanced patient comfort and device maneuverability are critical.
- Hydrogel:Comprising highly cross-linked polymeric networks that absorb water, hydrogels offer superior lubricity and a soft, tissue-like interface. Their application expands rapidly in neurovascular and ophthalmic devices.
- Silicone:Silicone-based hydrophilic coatings offer a balance of lubricity and durability, used in applications requiring repeated sterilization or long-term implantation.
- Bio-based Coatings:Derived from natural sources like hyaluronic acid, these coatings offer enhanced biocompatibility and biodegradability, appealing to sustainable product development.
Polymer-based formulations retain volume leadership; hydrogel coatings hold the steepest expansion curve.
Application:
The varied application landscape for hydrophilic coatings reflects distinct performance requirements, from critical medical interventions to consumer products, each driving specific material and process innovations.
- Medical Devices:This largest and most profitable application encompasses catheters, guidewires, and endoscopic tools. Demand is propelled by global increase in minimally invasive surgeries and stringent patient safety requirements.
- Automotive:Hydrophilic coatings are applied in automotive sensors and optical components to prevent fogging and improve visibility. This application is driven by advancements in autonomous driving and enhanced safety features.
- Electronics:These coatings are used for anti-smudge and anti-fog properties on touchscreens and displays, enhancing user experience and device longevity.
- Textile:Hydrophilic treatments for textiles improve moisture-wicking properties and comfort in sportswear, medical garments, and technical fabrics.
The largest segment by volume is Medical Devices, while Automotive applications demonstrate the most dynamic expansion.
End User:
Customer types within the hydrophilic coatings market exhibit diverse procurement patterns, with large-scale manufacturers often seeking integrated solution partnerships, contrasting with transactional purchasing from smaller firms.
- Healthcare:This sector, including hospitals and medical device manufacturers, is the primary end-user, demanding coatings that meet rigorous biocompatibility and regulatory standards. Increasing surgical procedures drive sustained demand.
- Automotive Manufacturers:These firms integrate hydrophilic coatings into vehicle components, particularly for ADAS sensors and interior displays. Their procurement emphasizes scalability, cost-effectiveness, and durability.
- Electronics Firms:Manufacturers of consumer electronics and industrial displays utilize these coatings for functional surfaces, prioritizing optical clarity and wear resistance.
- Textile Producers:Textile companies apply hydrophilic coatings to enhance fabric performance, focusing on breathability and moisture management for specialized garments.
Procurement patterns from Healthcare are undergoing significant shifts, contrasting with the stable requirements of Textile Producers.
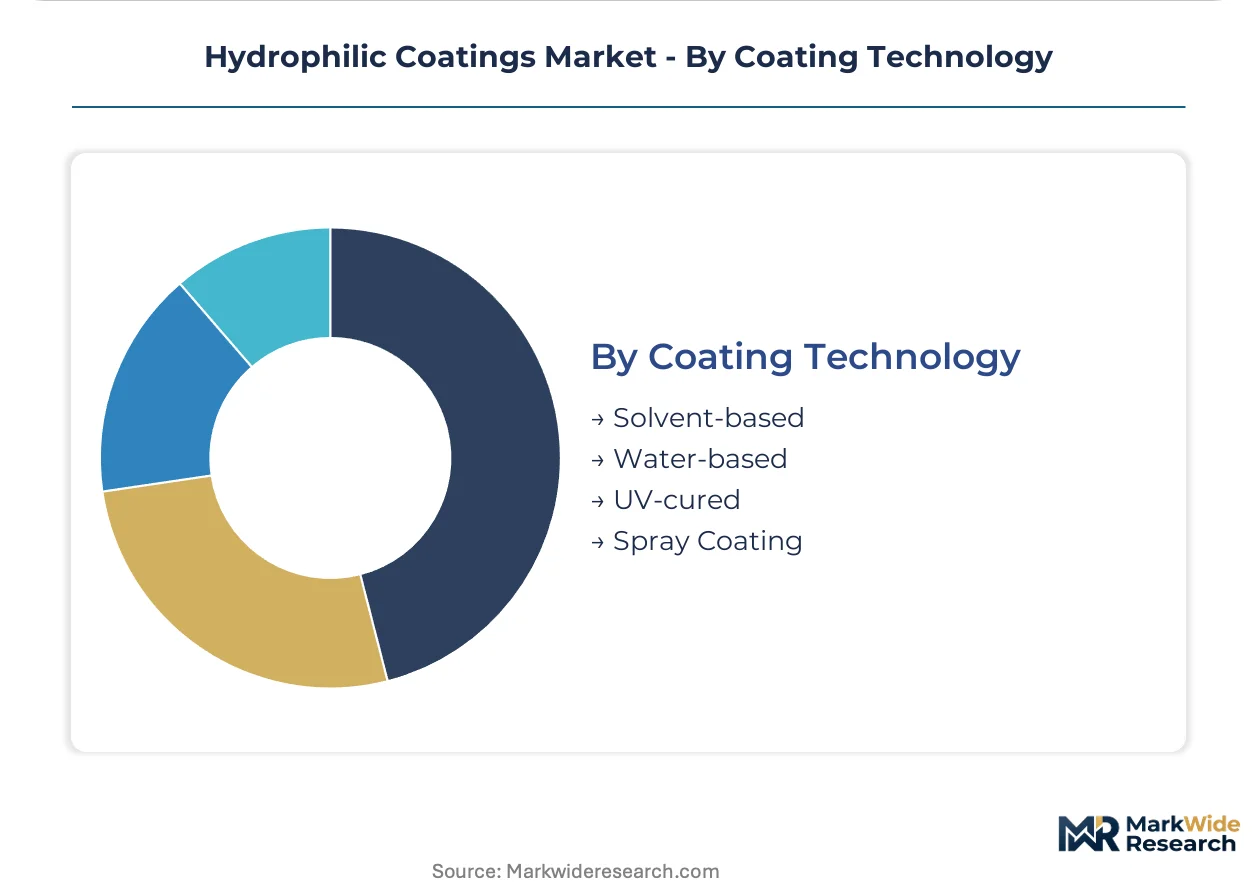
Coating Technology:
The technological maturity spectrum across coating application methods dictates investment priorities, with established processes facing pressure from innovative, environmentally conscious, and rapid-cure alternatives.
- UV-cured:These technologies involve rapid polymerization initiated by ultraviolet light, enabling fast processing times and solvent-free application. UV-cured coatings gain share due to their efficiency and reduced environmental impact for high-volume medical device manufacturing.
- Water-based:Utilizing water as the primary solvent, these coatings offer environmental benefits and reduced volatile organic compound (VOC) emissions. Water-based formulations are increasingly preferred in regions with strict environmental regulations.
- Solvent-based:Traditional solvent-based coatings offer versatility in material formulation and robust adhesion, though they face regulatory scrutiny due to VOC emissions.
- Spray Coating:This application method allows for uniform coating of complex geometries and large surfaces, widely used across various industries for efficient material deposition.
While Solvent-based technologies maintain a mature market presence, the future growth is increasingly driven by innovations in UV-cured methods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. FDA sets a global benchmark for medical device regulatory approval, significantly influencing hydrophilic coating development. This regulatory stringency drives innovation and market access strategies across diverse geographies. Regional demand patterns reflect varying healthcare infrastructure maturity and technological adoption rates.
United States
Demand for advanced medical devices, particularly for cardiovascular and neurovascular interventions, drives coating consumption. The U.S. FDA's rigorous pre-market approval process mandates extensive biocompatibility testing for new coating formulations. Boston and Minneapolis medical technology hubs foster collaboration between device manufacturers and coating specialists, accelerating product development.
Germany
Europe's largest medical device market demands high-performance hydrophilic coatings for surgical instruments and implants. The European Union's Medical Device Regulation (MDR) under the EMA imposes strict requirements for clinical evidence and post-market surveillance. Medical technology clusters in Bavaria and North Rhine-Westphalia concentrate research and manufacturing, supporting coating innovation.
China
Increasing healthcare expenditure and a growing elderly population fuel demand for minimally invasive surgical tools. China's NMPA actively streamlines approval processes for innovative medical devices, while maintaining stringent safety standards. The Yangtze River Delta region, including Shanghai, serves as a significant manufacturing base for medical devices, attracting coating suppliers.
Japan
An aging demographic and a focus on advanced healthcare technologies create a sustained need for lubricious coatings on catheters and guidewires. Japan's PMDA regulates medical devices, emphasizing product quality and patient safety throughout the device lifecycle. Tokyo and Osaka host major medical device companies and research institutions, driving material science advancements in coatings.
Ireland
A robust medical device manufacturing sector, supported by foreign direct investment, generates strong demand for specialized coatings. Compliance with the European Union's MDR is a primary concern for Irish manufacturers exporting medical devices. Galway and Cork are key medical technology hubs, where numerous device companies partner with coating providers for R&D and application.
Hydrophilic Coatings Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the hydrophilic coatings market. This tiered structure reflects varying levels of R&D investment and manufacturing scale. Strategic archetypes include large chemical conglomerates offering broad polymer portfolios and niche specialists focused on custom medical device applications. Companies engage in strategic partnerships to expand application expertise and undertake targeted M&A to acquire new coating technologies. Portfolio diversification into adjacent industrial applications also represents a common growth strategy.
On the premium-tier vector, Surmodics Incorporated represents companies leveraging deep R&D in surface chemistry for complex medical devices. Biocoat Incorporated exemplifies specialists providing custom-developed coatings for cardiovascular and neurovascular markets. DSM, a global materials science company, occupies a position among large chemical conglomerates offering broad polymer portfolios and scalable manufacturing capabilities. These entities anchor distinct segments of the market, from highly specialized medical applications to broader high-performance polymer solutions.
| Leading Market Players |
|---|
| Applied Medical Coatings |
| Corning Inc. |
| Aculon, Inc. |
| Harland Medical Systems |
| Surmodics Incorporated |
| Biocoat Incorporated |
| AST Products, Inc. |
| DSM |
| Hydromer |
Cost & Logistics Intelligence
Long-term supply agreements for medical-grade polymers like PVP and polyurethanes lock in both supply access and provide greater price visibility for hydrophilic coating formulators. This contract structure mitigates raw material price volatility for key specialty polymers.
Pricing Analysis
Geographic price spreads for hydrophilic coatings reflect regional regulatory compliance costs and local market competition. The dominant pricing model is value-based, driven by performance differentiation and regulatory support services. Price differentiation stems from certification level (e.g., U.S. FDA, EU MDR compliance) and customization for complex medical device substrates. Pricing softness affects standard industrial applications due to lower barriers to entry. Medical device manufacturers exhibit the lowest price sensitivity for critical, high-performance coatings, prioritizing validated solutions.
Supply Chain Analysis
Single-source vulnerability for highly specialized medical-grade polymers represents a significant chokepoint in the hydrophilic coatings supply chain. Geographic supply for key raw materials like PVP and polyurethanes draws from manufacturers primarily in China and Germany. The market relies on specialty polymers and advanced UV-curable monomers. Regulatory restrictions, particularly around biocompatibility and leachables, create a structural risk for material sourcing. Distribution primarily occurs through direct sales channels to medical device OEMs and specialized coating applicators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
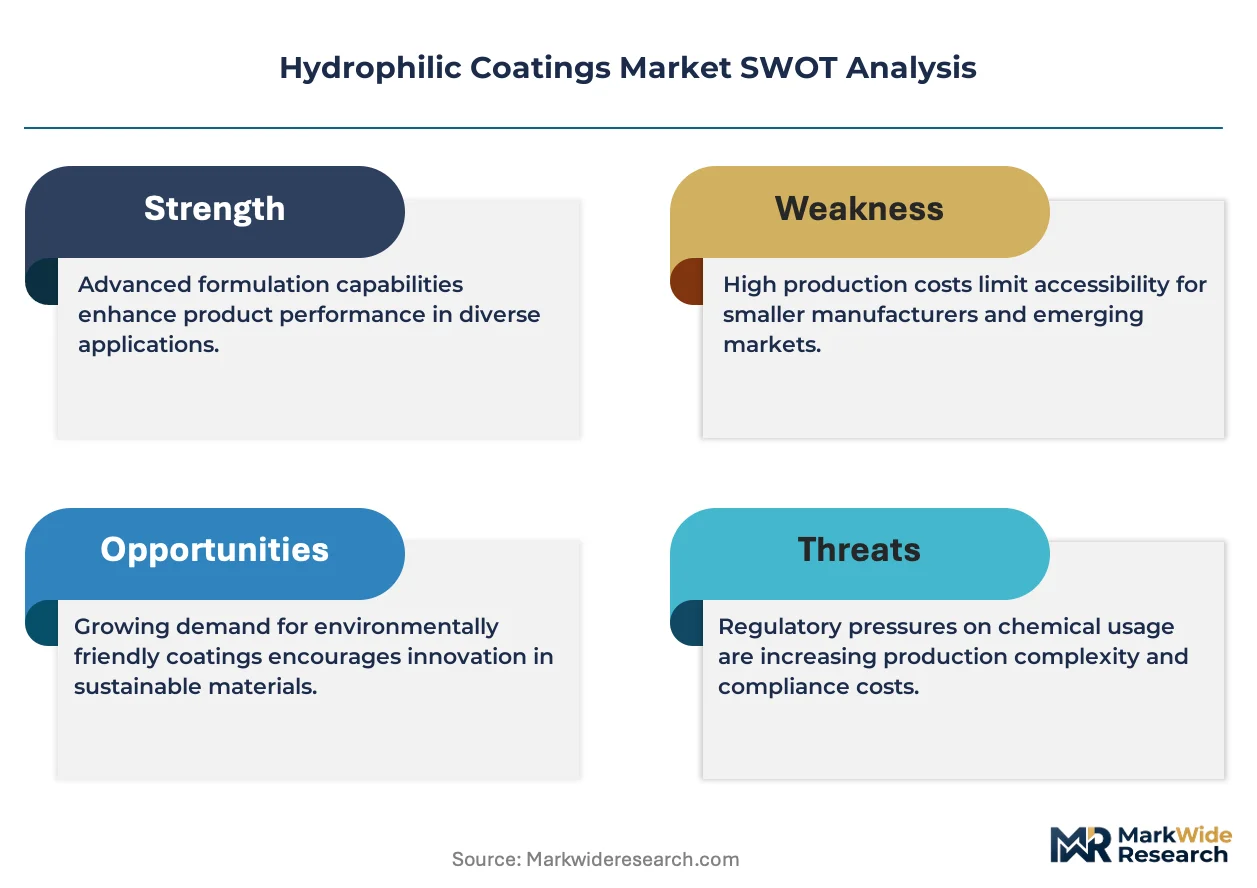
The hydrophilic coatings market represents a defensive-moat story, primarily due to the significant regulatory entrenchment required for medical device applications. This structural advantage creates high barriers to entry and fosters stable demand for compliant solutions.
For Market Incumbents: Secure long-term supply agreements for critical raw materials to mitigate price volatility and ensure production continuity. Deepen partnerships with medical device OEMs, offering comprehensive regulatory support and co-development of new formulations to counter emerging entrant archetypes. Invest in R&D for advanced self-healing and multifunctional coatings to maintain performance leadership against substitute technologies. Continuous investment in clinical data for EU MDR compliance is a necessary lever to defend market share.
For New Entrants and Emerging Players: Lead with specialized coating solutions for niche, high-value segments like neurovascular or ophthalmic devices, where performance differentiation commands a premium. Target emerging medical device manufacturing sectors in geographies like Brazil and India, which often lack in-house coating expertise. The most penetrable segment lies in applications requiring novel functionalities beyond simple lubricity, such as antimicrobial properties. A strategic go-to-market angle involves offering integrated service bundles, including application process optimization and validation support.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized coating technology firms with strong intellectual property in surface chemistry and a proven regulatory track record. The long-term viability of this market over the next five to ten years remains robust, driven by persistent demand for advanced medical devices. Acquisition targets should be niche specialists offering proprietary coating solutions for complex medical applications. The signal to watch is the increasing adoption rate of multifunctional coatings in high-value device segments.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Multifunctional Coatings | Develops surfaces combining hydrophilicity with antimicrobial or drug-eluting properties for higher-value medical devices. |
| Regulatory Compliance Investment | Ensures market access in key EU countries and the U.S. by meeting stringent EMA MDR and U.S. FDA standards. |
| Strategic Partnerships with OEMs | Facilitates co-development and deep integration into medical device manufacturing processes, securing long-term contracts. |
| Capacity Expansion for UV-Cured Coatings | Addresses the growing demand for rapid, solvent-free processing in high-volume medical device production. |
| Geographic Expansion into Emerging Markets | Captures growth opportunities in nascent medical device manufacturing hubs in regions like Brazil and India. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary market intelligence anchors the qualitative findings of this study. Interviews included R&D directors, regulatory affairs leads, procurement managers at medical device OEMs, and polymer scientists. Secondary validation drew from U.S. FDA filings, EU EMA Medical Device Regulation documentation, and trade association reports. The analysis utilized both bottom-up and top-down triangulation to ensure data accuracy and comprehensive market sizing.
Sensitivity analysis informed the analytical framework, assessing market dynamics across the projection horizon. Segmentation dimensions modeled included product type, application, end-user, and coating technology, alongside regional regulatory landscapes. Compound annual growth rates were derived from historical trends and anticipated technological advancements. Forecast inputs incorporated the increasing volume of minimally invasive surgeries and evolving material science advancements in polymer chemistry.
Underlying assumptions cover stable regulatory environments and consistent raw material supply, with deviation risk concentrated in unforeseen policy shifts or major supply chain disruptions. Forecasts reflect these assumptions, acknowledging potential impacts from global economic volatility. Practitioners should keep alternative scenarios live as medical device regulatory frameworks and polymer supply dynamics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Passive Fire Protection Coatings Market
Coatings
Phosphate Conversion Coatings Market
Coatings
PACVD-Based Coatings Market
Coatings
Thermal Barrier Coatings Market
Coatings
Coating Binders Market
Coatings
Rail Coatings Market
Coatings
Europe Super Hydrophobic Coatings Market
Coatings
Thailand Architectural Coatings Market
Coatings
Middle-East and Africa Thermal Spray Market
Coatings
Coating Auxiliaries Market
Coatings
Global Flat Glass Coatings Market
Coatings
South Korea Protective Coatings Market
Coatings
Global Intumescent Coatings Market
Coatings
Coating Agents for Synthetic Leather Market
Coatings
ASEAN Automotive OEM Coatings Market
Coatings
North America Hydrocarbon Fire Intumescent Coating Services Market