
 Breathable Antimicrobial Coatings Market | 2026-2036
Breathable Antimicrobial Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Breathable Antimicrobial Coatings Market Intelligence
The price-performance gap between premium breathable antimicrobial coatings and commodity-grade alternatives is hardening as healthcare buyers demand validated efficacy data and textile manufacturers face stricter durability benchmarks. DuPont leverages its polymer science heritage to sustain leadership in fluorine-free breathable membranes with integrated silver-ion antimicrobial functionality. Sherwin-Williams Company anchors its position through distribution depth across North American hospital networks and industrial laundries.
Breathable antimicrobial coatings constitute thin, permeable films engineered with biocidal agents such as silver nanoparticles, quaternary ammonium compounds, or copper complexes, applied to substrates at thicknesses typically ranging from 0.1 to 50 micrometers to inhibit microbial colonization while permitting moisture vapor transmission. Water-based formulations lead volume shipments due to lower volatile organic compound emissions and compatibility with textile finishing lines, though UV-cured systems represent the fastest-expanding technology segment as manufacturers seek energy-efficient curing and instant line speeds. Nano-coating approaches command premium positioning in medical device applications where sub-micron precision governs breathability-to-protection ratios.
EPA antimicrobial pesticide regulations and the EU Biocidal Products Regulation impose registration burdens that filter out undercapitalized coating suppliers, while FDA device coating standards for indwelling medical applications create additional compliance layers for healthcare-facing formulations. ISO 22196 antimicrobial surface testing protocols serve as the baseline reference for performance claims across export markets, with Japan's METI guiding domestic adoption through JIS Z 2801 alignment. Stakeholders must monitor evolving substance restrictions under REACH and state-level disclosure mandates in California and New York to anticipate reformulation cycles and qualification timelines.
Market Dynamics
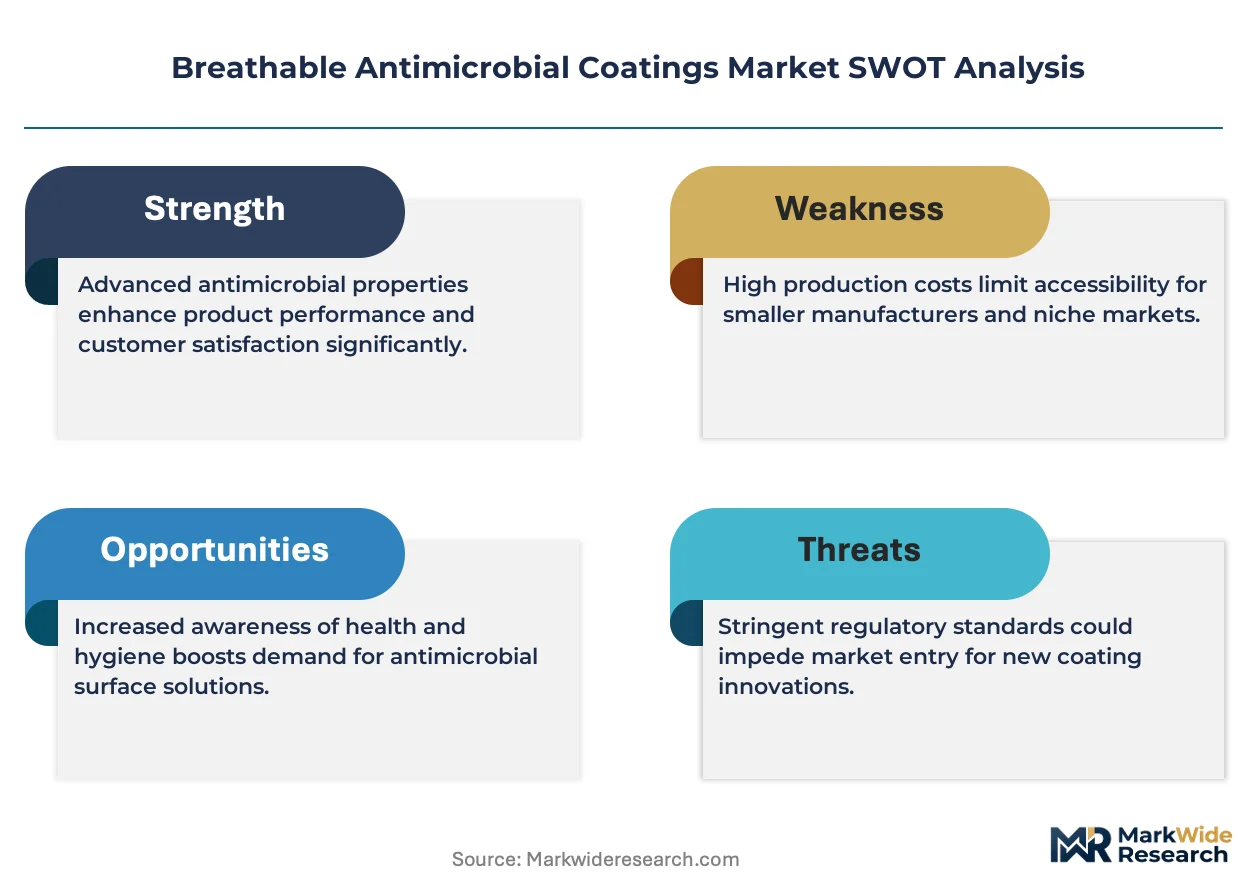
The breathable antimicrobial coatings sector is experiencing acute pressure from regulatory substance restrictions that force simultaneous reformulation of biocidal actives and validation of moisture-vapor transmission performance under new test protocols.
Growth Catalysts
- EU Biocidal Products Regulation renewal cycles:Re-registration requirements for silver-ion and quaternary ammonium compound coatings are consolidating supplier bases and rewarding early-movers with validated dossiers.
- Medical textile demand in Germany and China:Domestic manufacturing scale-up of surgical gowns and antimicrobial linens is pulling coating volumes through localized finishing operations.
- UV-cured coating technology:Energy-efficient instant curing is displacing thermal drying lines in textile finishing plants, reducing water consumption and enabling thinner film deposition.
Market Restraints
- Silver price volatility:Primary biocidal active costs fluctuate with precious metals markets, compressing margin stability for mid-tier coating formulators.
- Fluoropolymer precursor supply concentration:Breathable membrane substrates depend on concentrated fluorochemical feedstock sources in China and Japan, exposing downstream coaters to export control risks.
- REACH substance restriction timelines:Anticipated listing of additional biocidal candidates under Annex XIV is forcing premature R&D redirection before commercial payback.
Strategic Opportunities
- India medical device coating underpenetration:CDSCO regulatory harmonization with ISO 10993 biocompatibility standards is opening import substitution pathways for domestic coating applicators.
- Copper-complex antimicrobial integration:Convergence of copper-thin-film sputtering with textile lamination processes enables dual-function breathable barriers with viral inactivation claims.
- Industrial laundry service channel:Hospital network outsourcing of linen processing to centralized facilities with coating-reapplication capabilities creates recurring revenue attachment points.
Industry Challenges
- ISO 22196 test method standardization delays:Inconsistent inter-laboratory reproducibility for antimicrobial efficacy claims prolongs customer qualification timelines and raises dispute resolution costs.
- Multilayer coating integration complexity:Achieving adhesion between hydrophilic antimicrobial topcoats and hydrophobic breathable substrates without compromising vapor transmission rates requires specialized formulation expertise that remains scarce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breathable Antimicrobial Coatings Market |
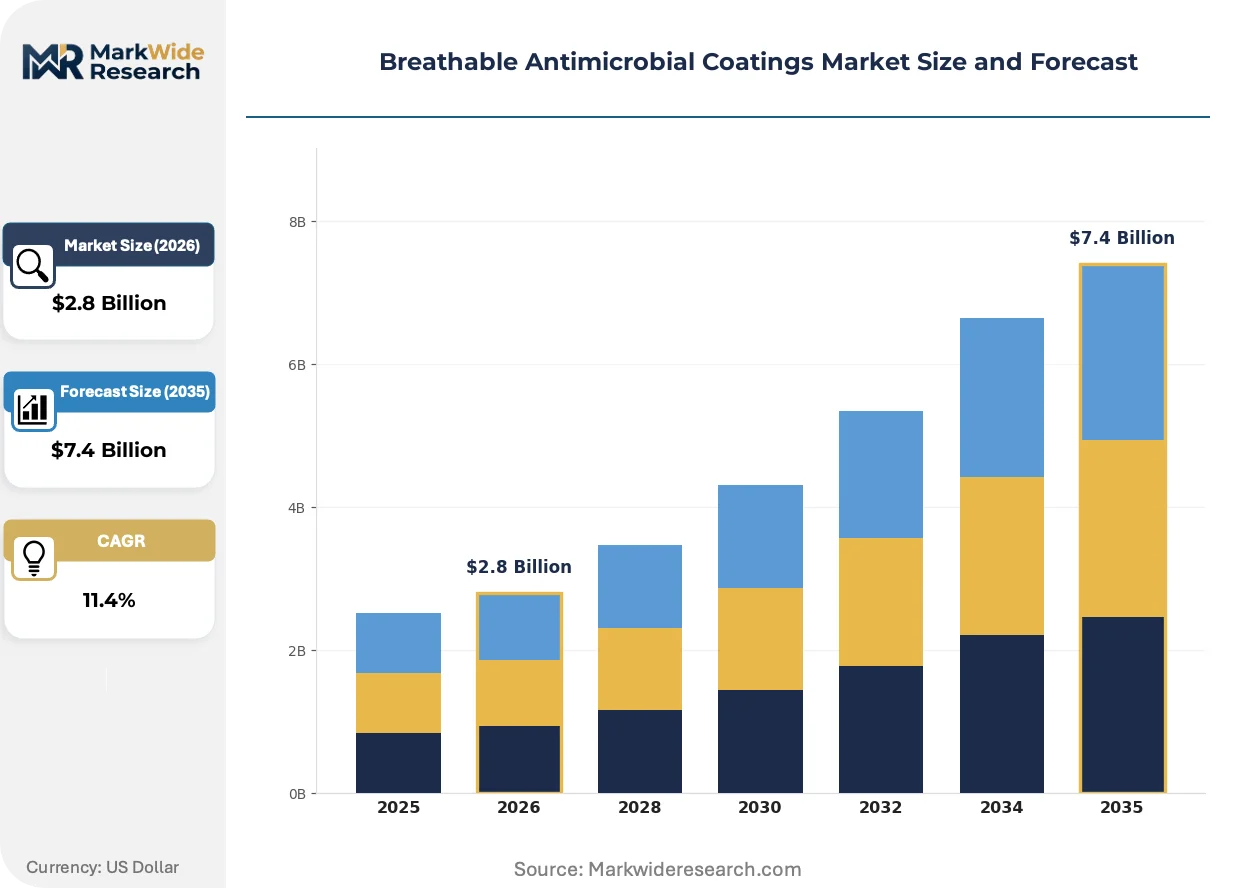
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Powder Coatings, UV-Cured End User: Healthcare, Textile, Automotive, Construction Technology: Nano-Coating, Chemical Vapor Deposition, Spray Coating, Thin Film Coating Application: Surface Protection, Metal Finishing, Fabric Treatment, Drug Packaging |
| Companies Covered | DuPont, Sherwin-Williams Company, PPG Industries, H.B. Fuller Company, Covalon Technologies, SANITIZED AG, Paradigm Labs, Stahl Holdings, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breathable Antimicrobial Coatings Market Strategic Shifts & Innovations
Active coating architectures are fragmenting into application-specific stacks that sacrifice universal performance claims for targeted efficacy in defined use environments. This specialization is compressing product development cycles while raising the bar for validation data.
Nano-structured antimicrobial surfaces are modularizing through layer-by-layer deposition systems that permit independent tuning of pore size distribution and biocidal release kinetics. Medical device manufacturers in Switzerland and the United States are piloting these systems for implantable textile components. The technology is modularizing supplier relationships, as coating houses must now coordinate with precision deposition equipment vendors and metrology labs rather than operating standalone formulation lines.
EPA's amended antimicrobial pesticide data requirements under the Federal Insecticide, Fungicide, and Rodenticide Act are extending registration timelines for novel biocidal coatings by 18-24 months. The industrial consequence is a freeze on experimental active ingredient adoption until full dossier costs can be amortized across projected volumes. Healthcare-facing formulations containing silver nanoparticles are most affected, with registrants pursuing conditional approvals while generating supplemental environmental fate data.
Hospital procurement departments are consolidating coating specifications into master service agreements that bundle substrate supply, coating application, and reprocessing logistics under single-source contracts. This behavior compresses the coating vendor base in United States hospital networks from multi-supplier bidding to preferred-partner frameworks. The shift is most visible in industrial laundry channels serving acute-care facilities, where coating durability guarantees now extend across 100+ commercial wash cycles with documented efficacy retention.
Breathable Antimicrobial Coatings Market Segmentation
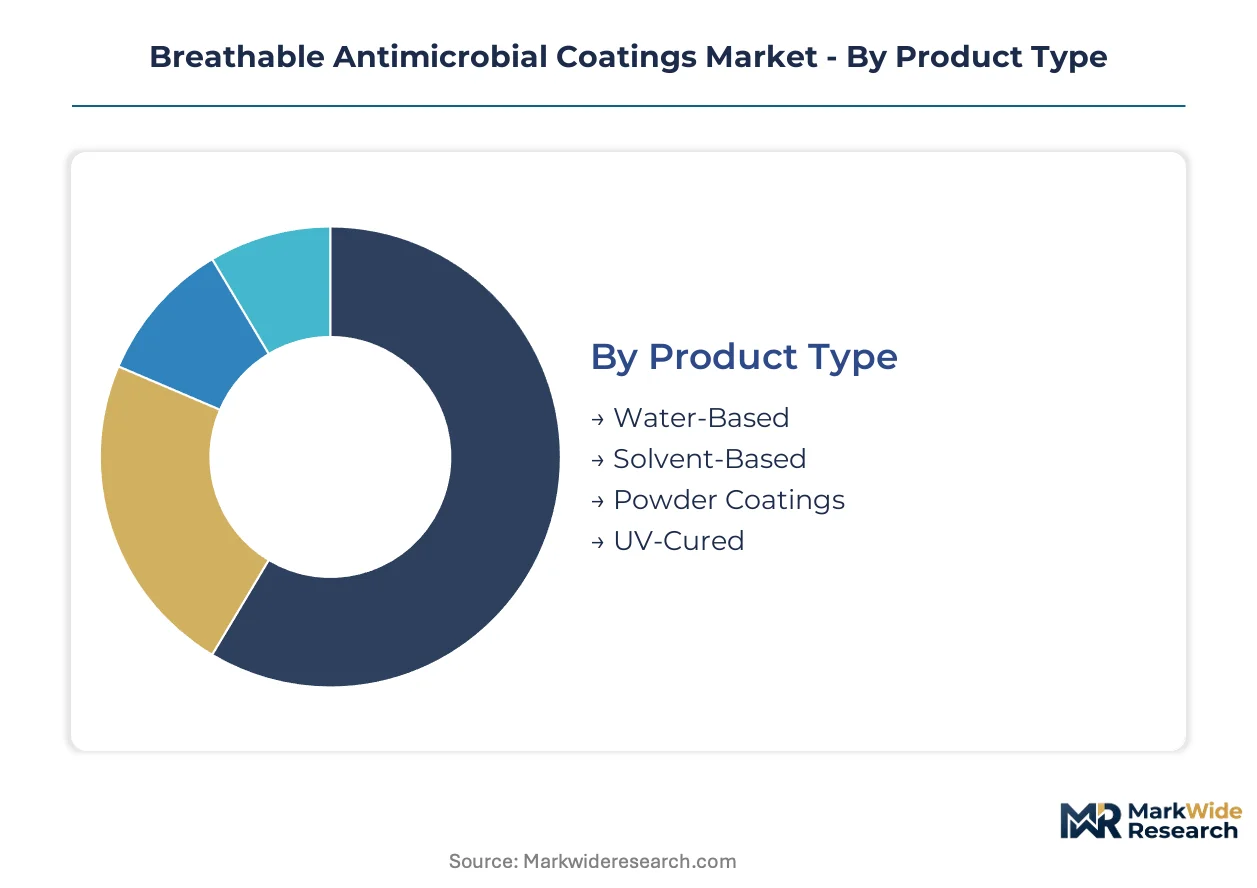
Breathable antimicrobial coatings fragment across formulation chemistry, deposition physics, and end-use performance requirements. Each segmentation axis carries distinct regulatory footprints and margin structures that reshape supplier positioning.
Product Type:
Customization intensity ranges from commodity water-based systems to precision-engineered UV-cured architectures with embedded biocidal release kinetics.
- Water-Based:Acrylic and polyurethane dispersions dominate textile finishing lines due to low VOC compliance with EPA and EU solvent emission directives. Hospital linen processors in Germany specify these formulations for compatibility with industrial tunnel washers.
- UV-Cured:Photoinitiator-activated acrylates enable sub-10-micron films with instant cure, reducing energy intensity versus thermal drying. Medical device manufacturers in Switzerland pilot these systems for implantable textile components where moisture vapor transmission precision governs biocompatibility.
- Solvent-Based:Fluoropolymer solutions persist in automotive interior applications where aggressive chemical resistance outweighs emission compliance costs.
- Powder Coatings:Thermoset epoxy and polyester systems serve metal HVAC components in healthcare facilities, applied through electrostatic spray with zero solvent content.
Leading the category by volume: Water-Based. Growing fastest: UV-Cured.
End User:
Application maturity spans regulated healthcare procurement to emerging automotive cabin hygiene specifications.
- Healthcare:Surgical gowns, antimicrobial linens, and implantable textiles drive validation-heavy demand. US hospital networks consolidate coating specifications into master service agreements bundling substrate supply, coating application, and reprocessing logistics.
- Textile:Performance apparel and protective equipment manufacturers in China scale domestic finishing operations, pulling coating volumes through localized supply chains.
- Automotive:Cabin air filtration and seat fabric treatments gain specification traction as OEMs respond to post-pandemic interior hygiene expectations.
- Construction:HVAC ductwork and antimicrobial wall coatings serve infection control in senior living facilities, with durability guarantees extending across maintenance cycles.
Healthcare generates the steepest margin premiums. Textile manufacturing scales fastest in China and Germany.
Technology:
Deposition precision separates commodity applicators from specialists controlling sub-micron film architecture.
- Nano-Coating:Layer-by-layer assembly permits independent tuning of pore size distribution and biocidal release kinetics. Medical device manufacturers pilot these systems for implantable components where ISO 10993 biocompatibility compliance is mandatory.
- Spray Coating:Conventional airless and electrostatic systems dominate textile finishing plants, with coating houses coordinating with precision deposition equipment vendors for quality assurance.
- Chemical Vapor Deposition:Copper-thin-film sputtering enables dual-function breathable barriers with viral inactivation claims, converging with textile lamination processes.
- Thin Film Coating:Physical vapor deposition serves semiconductor and electronics packaging where moisture barrier precision governs device reliability.
Nano-Coating commands the highest technical barriers to entry. Spray Coating maintains the broadest installed base.
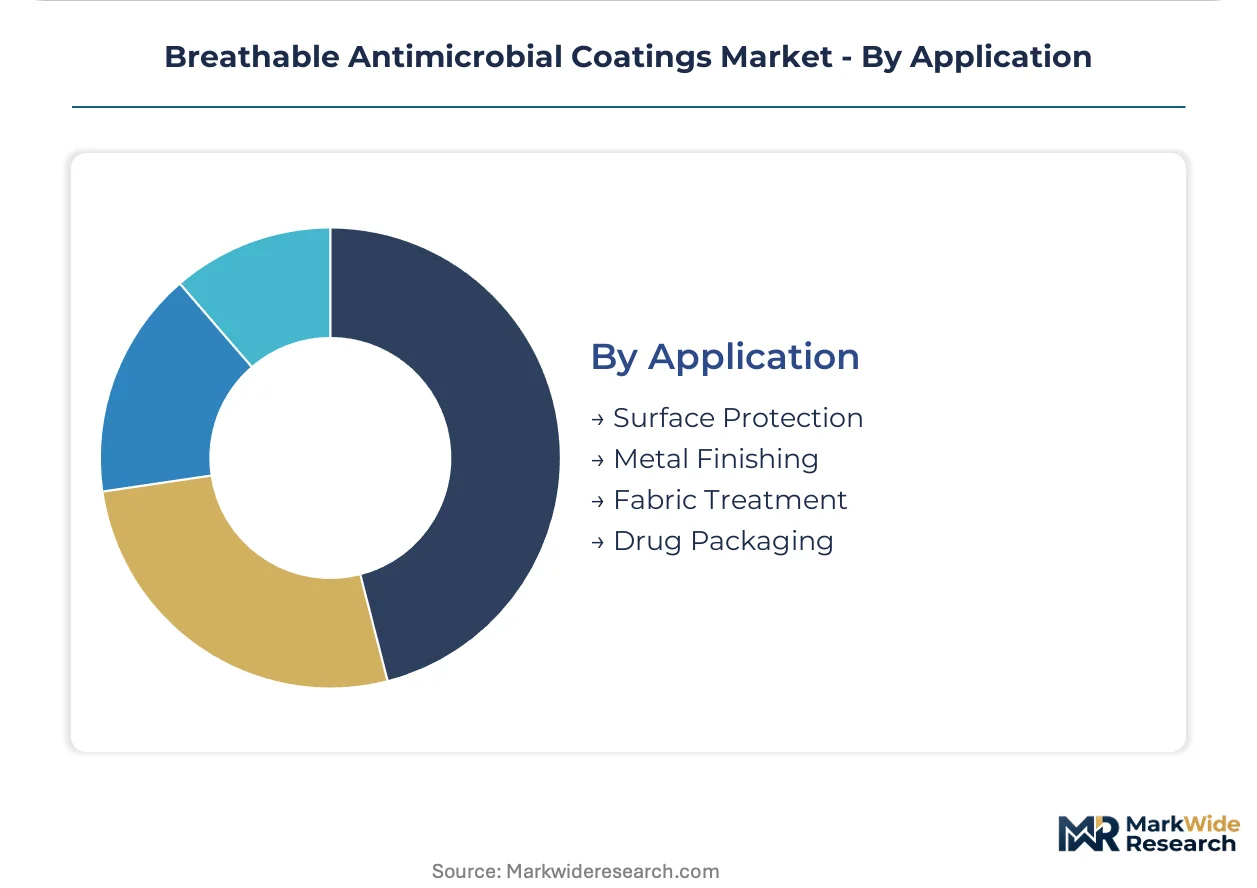
Application:
Performance validation requirements intensify from aesthetic metal finishing to regulated drug contact surfaces.
- Surface Protection:Countertops, touchscreens, and high-frequency contact surfaces in US hospital networks carry EPA antimicrobial pesticide registration requirements, extending qualification timelines.
- Drug Packaging:Blister packs and medical device pouches require FDA compliance for indirect food contact and ISO 15378 pharmaceutical packaging standards.
- Fabric Treatment:Surgical gowns and antimicrobial linens undergo ISO 22196 antimicrobial surface testing with durability validation across 100+ commercial wash cycles.
- Metal Finishing:HVAC components and surgical instruments balance corrosion resistance with biocidal efficacy, serving construction and healthcare end uses.
Surface Protection scales across the widest end-use base. Drug Packaging imposes the most stringent regulatory burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Basel anchors European pharmaceutical coating innovation, while Shanghai's Yangtze River Delta corridor scales domestic textile finishing capacity. Hospital procurement networks in Boston and Berlin are consolidating antimicrobial surface specifications under single-source contracts.
United States
Hospital network procurement consolidation drives coating volumes through industrial laundry channels serving acute-care facilities. EPA antimicrobial pesticide registration requirements under FIFRA extend qualification timelines for novel silver-ion formulations. Massachusetts medical device clusters around Boston and Cambridge pilot nano-structured deposition systems for implantable textile components.
Germany
Domestic manufacturing scale-up of surgical gowns and antimicrobial linens pulls coating volumes through localized finishing operations in North Rhine-Westphalia. EU Biocidal Products Regulation renewal cycles for quaternary ammonium compounds reward early-movers with validated dossiers. Stuttgart's automotive OEMs specify cabin air filtration coatings responding to post-pandemic interior hygiene expectations.
China
Textile manufacturers in the Yangtze River Delta and Pearl River Delta scale domestic finishing operations for protective equipment exports. NMPA alignment with ISO 10993 biocompatibility standards opens regulatory pathways for medical device coatings. Zhejiang province's chemical parks concentrate fluoropolymer precursor production, exposing downstream coaters to export control monitoring.
Switzerland
Medical device manufacturers in Basel and Zurich pilot layer-by-layer nano-coating systems for implantable components requiring ISO 10993 compliance. Swissmedic device coating standards create additional validation layers for healthcare-facing formulations. Precision deposition equipment vendors cluster around Lake Geneva, coordinating with coating houses on metrology integration.
India
CDSCO regulatory harmonization with ISO 10993 standards opens import substitution pathways for domestic coating applicators in Maharashtra and Gujarat. Hospital linen outsourcing to centralized industrial laundry facilities creates recurring revenue attachment points for coating reapplication services. Tamil Nadu's medical textile manufacturing corridor scales finishing capacity for surgical gown exports.
Breathable Antimicrobial Coatings Market Key Industry Players
Premium-margin players sit above commodity-margin players across formulation complexity and validation data depth. The supplier base concentrates around polymer science heritage companies and specialized coating houses with regulatory dossier capabilities. Three archetypes dominate: integrated chemical conglomerates with antimicrobial active production, precision coating specialists serving medical device OEMs, and textile finishing houses with hospital network distribution. Competitive moves center on fluorine-free membrane development and UV-curing technology licensing to capture energy efficiency mandates.
Within the integrated chemical tier, DuPont and BASF occupy positions leveraging polymer science heritage and global active ingredient supply chains. Among North American coating specialists, Sherwin-Williams Company anchors distribution depth across hospital networks and industrial laundries. Swiss precision deposition specialists including Covalon Technologies exemplify the medical device-facing archetype where ISO 10993 compliance and sub-micron film architecture command technical barriers.
| Leading Market Players |
|---|
| DuPont |
| Sherwin-Williams Company |
| PPG Industries |
| H.B. Fuller Company |
| Covalon Technologies |
| SANITIZED AG |
| Paradigm Labs |
| Stahl Holdings |
| BASF |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up coating specialists dominate the mid-tier supplier base, compressing working capital cycles and enforcing quarterly pricing discipline that favors volume commitments over spot transactions. This ownership structure concentrates bargaining power with fluoropolymer precursor suppliers in China and Japan, forcing downstream coaters to absorb feedstock volatility or surrender margin to secure allocation.
Pricing Analysis
Value-based pricing anchored to validated antimicrobial efficacy across commercial wash cycles separates premium coating houses from commodity applicators. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 22196 certification tier and durability guarantee length. Cost compression in the economy tier is intensifying because silver-ion registrants amortize EPA dossier expenses across shrinking batch sizes. Hospital procurement committees exhibit the sharpest price sensitivity, while medical device OEMs prioritize biocompatibility validation over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with fluoropolymer precursor production concentrated in China's Zhejiang province and Japan's chemical corridors. Downstream coating formulation draws from silver nanoparticle suppliers, photoinitiator chemical houses, and precision deposition equipment vendors. Tariff exposure on fluorochemical feedstocks threatens margin stability for US-based textile finishers. Distribution runs through industrial laundry networks serving hospital systems and direct OEM supply agreements with medical device manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints on fluoropolymer precursors and extended EPA registration timelines prop pricing power for validated incumbents, creating a seller-favorable environment through the forecast window.
For Market Incumbents: Deploy regulatory dossier depth as a moat by accelerating EU Biocidal Products Regulation re-registration investments before consolidation windows close. Prioritize backward integration into silver-ion active production to offset precious metals volatility threatening mid-tier competitors. Channel control through master service agreements with industrial laundry networks locks out challenger brands. For New Entrants and Emerging Players: A price-point gap between Swiss precision deposition specialists and Chinese commodity coaters creates entry space for mid-tier UV-cured system providers. Target India's CDSCO harmonization pathway for medical device coatings, where import substitution demand outpaces domestic formulation capacity. Lead with industrial laundry service bundling to bypass direct hospital procurement barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor European coating houses with stalled EU BPR dossiers in Germany and Switzerland, where regulatory capital exhaustion forces divestiture. Long-term viability hinges on fluorine-free membrane IP positions aligned with REACH substance restriction trajectories. Watch for EPA conditional approval conversions to full registration as the inflection signal for silver-ion formulation value recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Fluorine-Free Membrane Development | DuPont and BASF investments align with REACH precursor restrictions and automotive OEM sustainability mandates. |
| UV-Curing Technology Licensing | Energy efficiency compliance in German textile finishing plants drives technology transfer demand from equipment vendors. |
| EU BPR Dossier Acceleration | Early-mover registration rewards consolidate supplier bases ahead of quaternary ammonium compound renewal deadlines. |
| India CDSCO Harmonization Pathway | Regulatory alignment with ISO 10993 opens import substitution opportunities for domestic coating applicators in Maharashtra. |
| Industrial Laundry Service Integration | Hospital network outsourcing creates recurring revenue attachment points for coating reapplication across 100+ wash cycles. |
Research Approach
SEC 10-K filings, EPA antimicrobial pesticide registration databases, and EU ECHA biocidal product dossiers formed the secondary backbone, cross-referenced with customs trade data on fluoropolymer precursor flows. Primary interviews with coating formulation chemists, hospital procurement managers, industrial laundry operations directors, and medical device regulatory affairs leads validated demand assumptions and pricing dynamics. Bottom-up volume modeling triangulated against top-down market sizing from polymer feedstock consumption patterns.
Historical trendline analysis of water-based and UV-cured coating shipments established baseline growth trajectories across the projection horizon. Segmentation dimensions modeled include formulation chemistry, deposition technology, end-use vertical, and regional regulatory cluster. CAGR derivation incorporated EPA registration timeline delays, silver price volatility bands, and textile manufacturing capacity expansion schedules in China and Germany.
Inputs from FDA device coating guidance documents and ISO 22196 test protocol revisions were available through the study window; gaps in real-time silver spot price correlation data introduce uncertainty bands around margin forecasts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Asia-Pacific Anti-Friction Coatings Market
Coatings
High Temperature Coatings Market
Coatings
Consumer Appliance Coatings Market
Coatings
France Protective Coatings Market
Coatings
Dispersion Coating Market
Coatings
Liquid-Applied Roof Coating Market
Coatings
Global Polyaspartic Coatings Market
Coatings
Global Antiviral Coatings Market
Coatings
Germany Automotive OEM Coatings Market
Coatings
Fluoropolymer Coating Market
Coatings
Canada Protective Coatings Market
Coatings
Europe Protective Coatings Market
Coatings
Coating Equipment Market
Coatings
Ethylene Tetrafluoroethylene (ETFE) Coatings Market
Coatings
Transportation Coating Market
Coatings
Self-Cleaning Coatings Market