
 Polyvinylidene Chloride (PVDC) Coated Films Market | 2026-2036
Polyvinylidene Chloride (PVDC) Coated Films Market Size, Share, and Industry Trends Forecast 2026-2036
Polyvinylidene Chloride (PVDC) Coated Films Market Analytics
Multi-source procurement for PVDC resin is decoupling from traditional petrochemical supply chains as converters seek alternative vinylidene chloride feedstock pathways. Kureha Corporation anchors Asian supply through captive polymerization capacity in Japan. Mondi Group plc leverages European extrusion assets to serve pharmaceutical blister formats. Glenroy Inc specializes in narrow-web coated films for North American healthcare packaging.
Polyvinylidene chloride coated films consist of a thin PVDC barrier layer, typically 2-6 micrometers, deposited via solvent or aqueous coating onto polyester, polypropylene, or paper substrates to achieve oxygen transmission rates below 1 cc/m²/day. Flexible films dominate volume consumption in processed meat and cheese packaging where oxygen exclusion determines shelf life. Pharmaceutical packaging represents the fastest-expanding application segment as moisture-sensitive biologics require WVTR performance below 0.1 g/m²/day. Rigid films occupy a mature position in unit-dose tablet blisters with stable margins tied to FDA 21 CFR 177.1990 compliance costs.
FDA migration thresholds under 21 CFR 177.1990 and EU REACH restrictions on residual vinylidene chloride monomer shape formulation chemistry and coating line investments. EFSA evaluations of PVDC recyclability under PPWR packaging waste rules are forcing redesigns toward mono-material compatible barrier structures. Stakeholders must monitor regulatory divergence between US FDA and EU ECHA frameworks while positioning coating capacity near pharmaceutical manufacturing clusters in Switzerland, Germany, and Singapore.
Market Dynamics
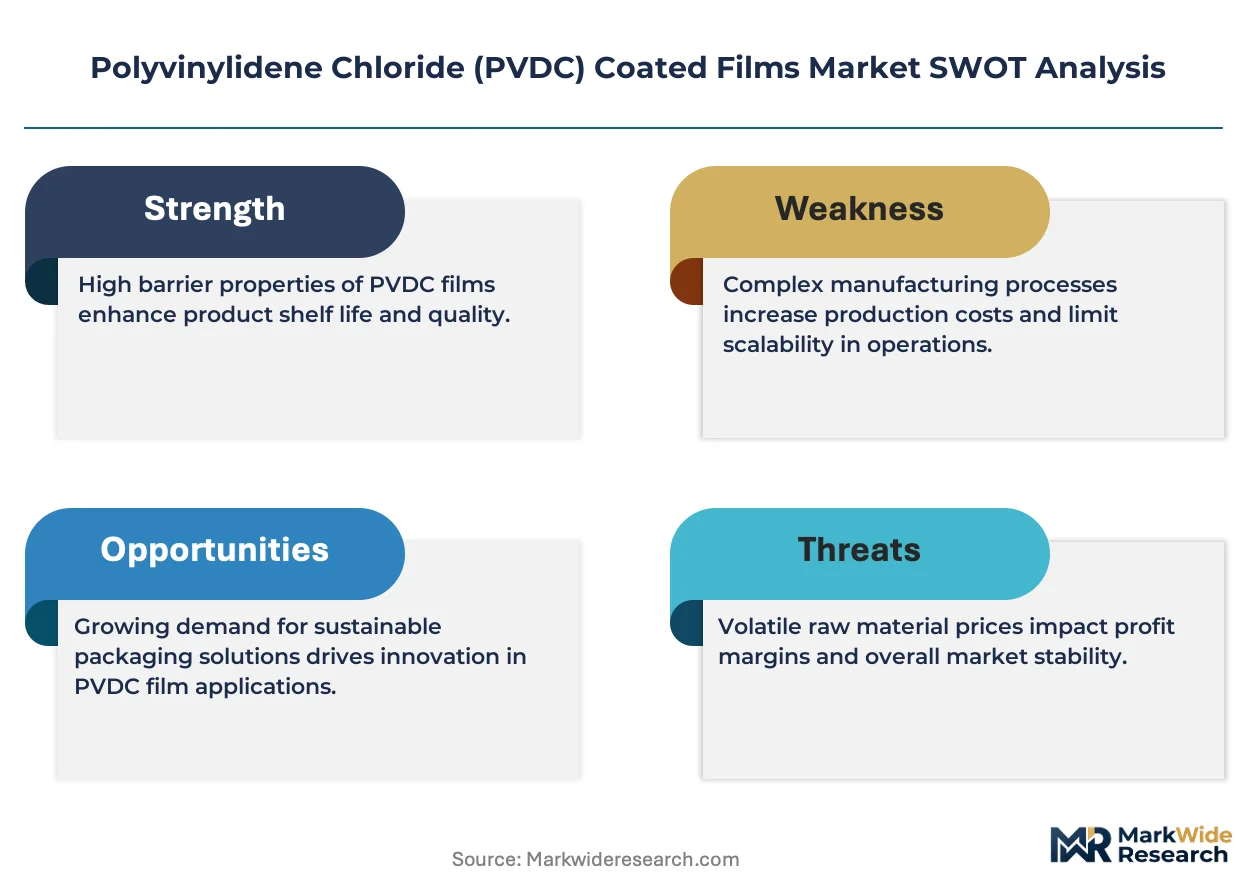
PVDC coated films face structural pressure from the EU Packaging and Packaging Waste Regulation (PPWR), which mandates mono-material recyclability and is forcing converters to redesign multi-layer barrier structures or abandon PVDC entirely for alternative chemistries.
Growth Catalysts
- EU MDR migration limits:Pharmaceutical blister packs in Germany and Switzerland require sub-ppm residual monomer compliance, locking in PVDC for moisture-sensitive biologics where performance thresholds exclude competing materials.
- Japan's pharmaceutical cluster:METI-backed domestic manufacturing incentives for active pharmaceutical ingredients are expanding captive packaging demand near Osaka and Tokyo production hubs.
- Co-extrusion advances:Thin-film deposition techniques below 3 micrometers are reducing resin intensity per square meter while maintaining oxygen transmission rates under 1 cc/m²/day.
Market Restraints
- Vinylidene chloride feedstock concentration:Asian petrochemical complexes control over 70% of global VDC monomer supply, exposing European and North American converters to freight and tariff volatility.
- REACH authorization friction:ECHA's scrutiny of chlorinated polymers under SVHC candidate listing creates formulation uncertainty and extended compliance timelines.
- Ethylene vinyl alcohol substitution:EVOH co-extrusion is capturing shelf-stable food applications where oxygen barrier requirements have relaxed below PVDC-grade thresholds.
Strategic Opportunities
- Indian pharmaceutical expansion:CDSCO's phased implementation of Schedule M(GMP) standards for domestic drug manufacturing is creating first-mover advantage for barrier film suppliers near Hyderabad and Ahmedabad clusters.
- Aqueous coating convergence:Water-based PVDC emulsion technology combined with corona surface treatment is eliminating solvent recovery capex and enabling smaller-batch pharmaceutical contract manufacturing.
- Singapore biologics hub:HSA's accelerated approval pathways for temperature-sensitive injectables are concentrating demand for ultra-low WVTR packaging within the Tuas biomedical manufacturing zone.
Industry Challenges
- Coating technician scarcity:Solvent-based line operation requires specialized handling certification that few vocational programs outside Japan and Germany currently offer.
- Validation timeline compression:FDA 21 CFR 177.1990 compliance documentation for new coating formulations now averages 18-24 months, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyvinylidene Chloride (PVDC) Coated Films Market |
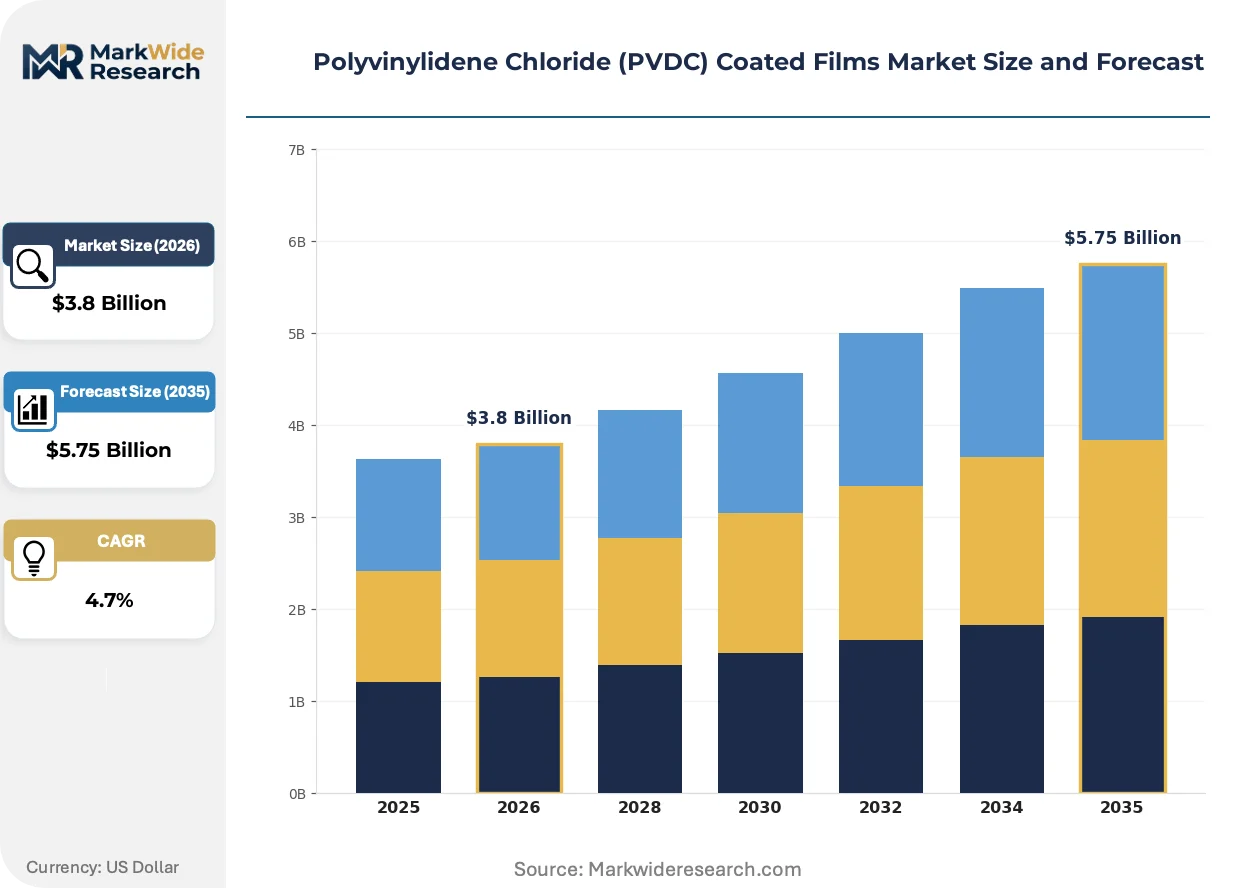
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Films, Rigid Films, Coated Papers, Laminates Application: Food Packaging, Pharmaceutical Packaging, Industrial Packaging, Cosmetic Packaging End User: Food Industry, Healthcare, Consumer Goods, Electronics Distribution Channel: Direct Sales, Online Retail, Wholesale Distributors, Specialty Stores |
| Companies Covered | Cosmo Films Ltd, Glenroy Inc, Mondi Group plc, Innovia Films, Vibac Group S.p.A., Kureha Corporation, Bilcare Limited, Polinas Corporate, Jindal Poly Films Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyvinylidene Chloride (PVDC) Coated Films Market Evolving Landscape
Barrier film technology is fragmenting across competing chemistries and deposition methods as sustainability mandates collide with performance requirements in pharmaceutical and food packaging end-uses.
Atomic layer deposition of aluminum oxide onto flexible substrates is decentralizing high-barrier production away from centralized coating facilities. Mid-size pharmaceutical converters in Switzerland and Singapore are adopting compact ALD units for in-house barrier application. This equipment shift is compressing minimum efficient scale and enabling regionalized supply for clinical-trial-scale drug packaging.
EFSA's draft opinion on PVDC recyclability under PPWR circularity targets is accelerating mono-material redesign investments. Coating houses in Germany are trialing strippable PVDC layers that separate from PET substrates during mechanical recycling. The pharmaceutical blister segment faces the steepest compliance curve given FDA 21 CFR 177.1990 stability requirements that resist rapid material substitution.
Hospital and pharmacy procurement consolidation is consolidating vendor relationships around full-service barrier film suppliers. Large North American healthcare distributors now specify integrated coating, slitting, and sterilization capabilities as qualifying criteria. This bundling pressure is most visible in the United States, where three national distributors control over 60% of unit-dose medication packaging flow.
Polyvinylidene Chloride (PVDC) Coated Films Market Segmentation
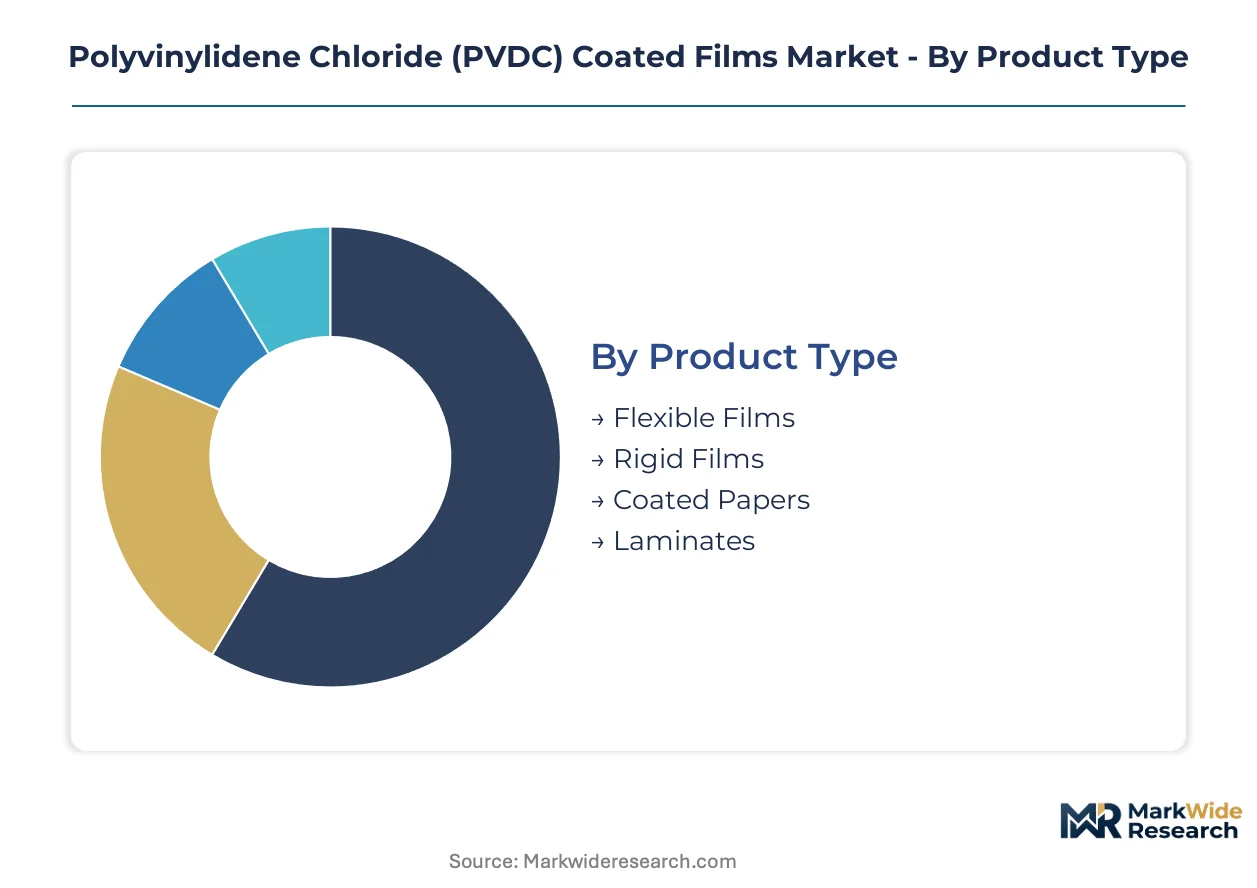
PVDC coated films serve divergent performance requirements across pharmaceutical moisture barriers and food oxygen exclusion, with substrate flexibility and regulatory compliance driving distinct procurement patterns by end-use sector.
Product Type:
Buyers select substrate-barrier combinations based on mechanical handling requirements and downstream converting equipment compatibility.
- Flexible Films:Polyester and polypropylene substrates carry 2-6 micrometer PVDC layers achieving oxygen transmission rates below 1 cc/m²/day. Processed meat and cheese packaging in Germany and Switzerland concentrates demand where EFSA shelf-life standards mandate high-barrier performance.
- Rigid Films:Thermoformable PVC or PP bases with thicker PVDC deposition suit unit-dose tablet blisters requiring dimensional stability. FDA 21 CFR 177.1990 compliance documentation locks in supplier relationships for North American pharmaceutical contract manufacturers.
- Coated Papers:Cellulose substrates with aqueous PVDC emulsion barriers serve moisture-sensitive confectionery and dried food segments.
- Laminates:Multi-layer structures combining PVDC with aluminum foil or metallized films address ultra-high-barrier pharmaceutical applications.
Volume sits with Flexible Films; growth tilts toward Laminates.
Application:
Regulatory stringency and product sensitivity create tiered pricing power across end-use segments.
- Food Packaging:Oxygen and moisture exclusion for processed meats, cheeses, and dried goods represents the baseline volume driver. FDA and EFSA migration limits shape formulation choices for converters supplying retail-ready formats.
- Pharmaceutical Packaging:Blister packs for moisture-sensitive biologics and generics command premium positioning. EU MDR sub-ppm residual monomer requirements and FDA stability protocols exclude lower-barrier alternatives, expanding fastest among applications.
- Industrial Packaging:Corrosion-inhibiting films for metal components and machinery use lower-grade PVDC deposition with less stringent certification overhead.
- Cosmetic Packaging:Fragrance and active-ingredient protection in premium personal care occupies a niche position with batch-scale production economics.
Food Packaging carries volume concentration; Pharmaceutical Packaging climbs the fastest.
End User:
Procurement scale and technical specification depth vary sharply across customer categories.
- Food Industry:Retail brand owners and co-packers drive standardized high-volume orders with price-sensitive contracting.
- Healthcare:Pharmaceutical manufacturers and contract packaging organizations demand validated supply chains with audit documentation. CDSCO Schedule M(GP) implementation in India and METI incentives in Japan are expanding regional sourcing requirements.
- Consumer Goods:Household product and personal care brand owners seek moisture barriers for detergents and cleaning agents with moderate technical complexity.
- Electronics:Static-dissipative and moisture-barrier films for semiconductors and components represent a specialized segment with Japanese and South Korean demand concentration.
The Food Industry dominates procurement tonnage; Healthcare expands most quickly.
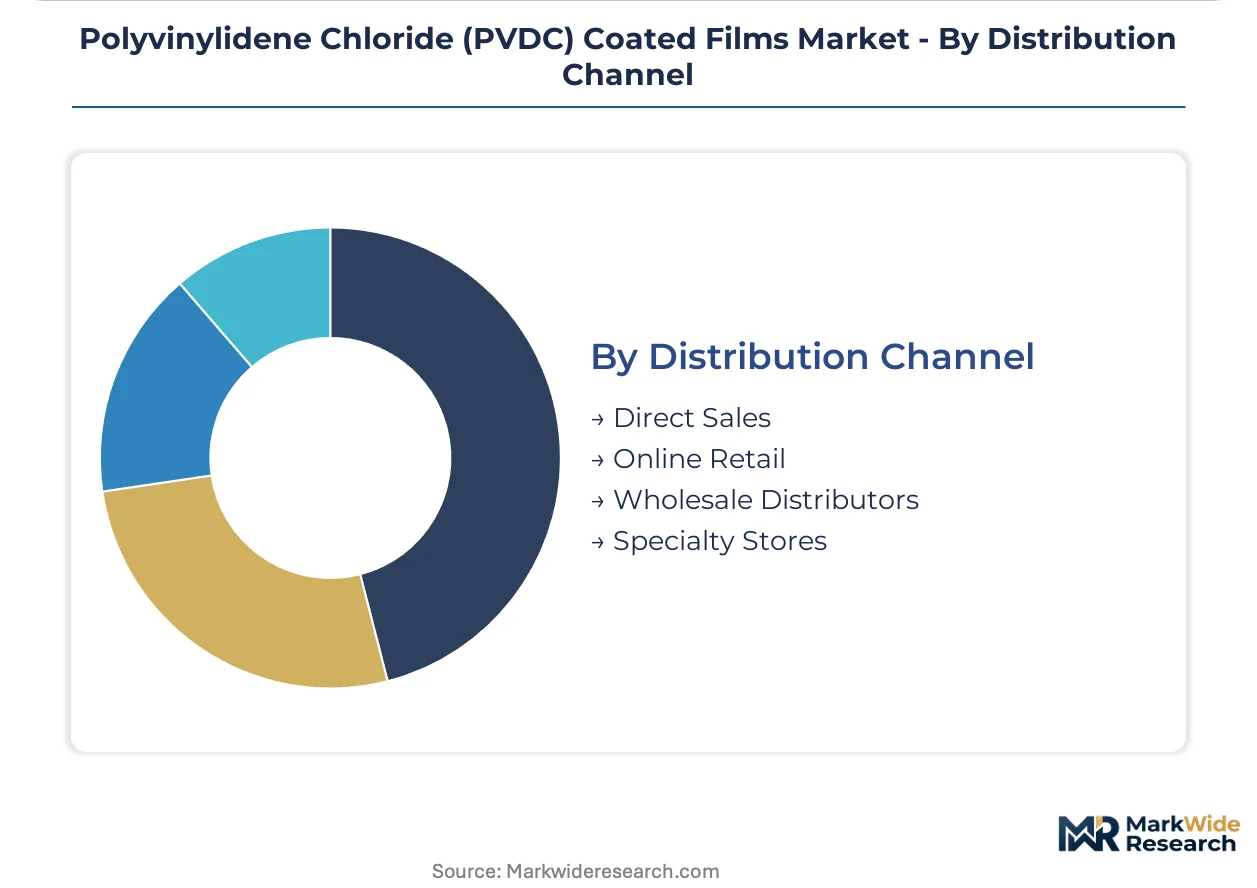
Distribution Channel:
Order size and technical service requirements determine channel selection across customer tiers.
- Direct Sales:Pharmaceutical and large food manufacturers negotiate multi-year supply agreements with technical support and validation documentation. Kureha Corporation and Mondi Group plc operate direct salesforces for major accounts.
- Online Retail:Small-batch and specialty converters source standard grades through digital procurement platforms with limited technical consultation.
- Wholesale Distributors:Regional inventory stocking serves mid-tier food processors and cosmetic manufacturers with shorter lead time requirements.
- Specialty Stores:Technical film distributors cater to R&D laboratories and clinical-trial-scale pharmaceutical packaging with custom slitting and small-order fulfillment.
Direct Sales commands volume leadership; Specialty Stores gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vinylidene chloride monomer supply concentrates in Japanese and Chinese petrochemical complexes, anchoring Asian coating capacity while European and North American converters navigate feedstock import dependencies and regulatory divergence.
United States
FDA 21 CFR 177.1990 compliance documentation requirements lock in supplier relationships for pharmaceutical contract manufacturers. The agency's stability protocols for moisture-sensitive biologics exclude lower-barrier alternatives, preserving PVDC demand in blister pack applications. Greater Boston and Research Triangle Park clusters concentrate biologics manufacturing with captive packaging specifications.
Germany
EU MDR sub-ppm residual monomer mandates drive specification intensity for pharmaceutical blister formats. EFSA evaluations of PVDC recyclability under PPWR circularity targets are forcing coating houses in Baden-Württemberg to trial strippable barrier layers. The Rhine-Main pharmaceutical corridor anchors domestic demand from Merck KGaA and Boehringer Ingelheim supply chains.
Japan
METI-backed domestic manufacturing incentives for active pharmaceutical ingredients expand captive packaging demand. Kureha Corporation's captive polymerization capacity in Iwaki anchors regional resin supply. Osaka and Tokyo production hubs concentrate demand for ultra-low WVTR films in temperature-sensitive injectables packaging.
India
CDSCO's phased implementation of Schedule M(GMP) standards for domestic drug manufacturing creates qualification requirements for barrier film suppliers. Hyderabad and Ahmedabad pharmaceutical clusters are expanding validated supply chain sourcing. FSSAI migration limits for food-contact applications run parallel to pharmaceutical-grade specifications.
Switzerland
Swissmedic's accelerated approval pathways for biologics concentrate demand for ultra-high-barrier packaging. Basel's pharmaceutical manufacturing density drives specification intensity for moisture-sensitive formulations. Compact atomic layer deposition units are enabling mid-size converters to regionalize supply for clinical-trial-scale packaging.
Polyvinylidene Chloride (PVDC) Coated Films Market Competitive Landscape
Global majors compete with regional champions across coating capacity and regulatory validation capabilities. The vendor base separates into three tiers: integrated resin-to-film producers with captive polymerization, specialized coating houses with pharmaceutical validation depth, and substrate converters licensing barrier technology. Strategic moves center on aqueous coating technology licensing and mono-material recycling compatibility investments ahead of PPWR deadlines.
Within the integrated resin tier, Kureha Corporation exemplifies captive supply chain control from monomer through finished film. Among European coating specialists, Mondi Group plc occupies a position shaped by pharmaceutical validation documentation and extrusion asset leverage. Glenroy Inc represents North American narrow-web capability focused on healthcare packaging formats with FDA compliance overhead.
| Leading Market Players |
|---|
| Cosmo Films Ltd |
| Glenroy Inc |
| Mondi Group plc |
| Innovia Films |
| Vibac Group S.p.A. |
| Kureha Corporation |
| Bilcare Limited |
| Polinas Corporate |
| Jindal Poly Films Limited |
| Others |
Value Network & Pricing Analysis
Captive polymerization capacity in Japan anchors both supply security and pricing power for integrated resin-to-film producers, while converters without upstream control face margin compression from vinylidene chloride monomer import dependencies. Kureha Corporation's Iwaki facility demonstrates how backward integration into monomer production insulates against freight volatility and tariff exposure.
Pricing Analysis
Validation documentation bundling separates pharmaceutical-grade suppliers from commodity converters, with FDA 21 CFR 177.1990 compliance packages commanding substantial premiums over food-contact grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, resin purity grades, and geographic delivery scope. Cost compression in flexible film tiers is intensifying because EVOH substitution in shelf-stable food applications has relaxed oxygen barrier requirements. Food industry buyers exhibit highest price sensitivity, while pharmaceutical contract manufacturers prioritize supply assurance over unit economics.
Supply Chain Analysis
Regional distribution centers in Germany, Switzerland, and Singapore concentrate finished film inventory near pharmaceutical manufacturing clusters, compressing lead times for validated supply chains. Vinylidene chloride monomer production rests on Japanese and Chinese petrochemical complexes, with European and North American converters drawing from Asian feedstock sources. Single-source vulnerability concentrates in Kureha Corporation's captive resin capacity, which supplies coating lines across multiple continents. Distribution runs through direct salesforces for major pharmaceutical accounts, supplemented by wholesale distributors serving mid-tier food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a technology-transition phase as aqueous coating emulsions displace solvent-based deposition systems, eliminating recovery capital expenditure and enabling smaller-batch pharmaceutical manufacturing.
For Market Incumbents: Anchor aqueous coating technology licensing programs to defend against EVOH co-extrusion substitution in food packaging. Pursue mono-material recycling compatibility investments ahead of EU PPWR deadlines, positioning strippable PVDC layer development as a compliance hedge. ECHA's SVHC candidate listing scrutiny for chlorinated polymers threatens formulation stability, making early regulatory engagement a critical defensive lever.
For New Entrants and Emerging Players: CDSCO's Schedule M(GMP) implementation in India opens a window for barrier film qualification near Hyderabad and Ahmedabad pharmaceutical clusters, where validated supply chains remain underdeveloped. Target Singapore's Tuas biomedical manufacturing zone for ultra-low WVTR film demand from temperature-sensitive injectables production. License aqueous emulsion coating technology from established Japanese suppliers to bypass solvent-handling certification barriers.
For Investors and Strategic Acquirers: Exit pathways concentrate in pharmaceutical validation depth, with coating houses possessing FDA 21 CFR 177.1990 documentation libraries commanding strategic premiums. Long-term viability hinges on mono-material recyclability solutions that preserve barrier performance under EU circularity mandates. Watch EFSA's final PPWR recyclability opinion as an inflection indicator for coating chemistry obsolescence risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Aqueous Coating Technology Licensing | Eliminates solvent recovery capital expenditure for pharmaceutical contract manufacturers. |
| Mono-Material Recycling Compatibility Investment | Positions suppliers ahead of EU PPWR circularity mandates for blister pack formats. |
| Regional Distribution Center Expansion | Compresses lead times near Basel and Singapore pharmaceutical manufacturing density. |
| Pharmaceutical Validation Documentation Acquisition | Accelerates FDA 21 CFR 177.1990 compliance timelines for new market entrants. |
| Strippable Barrier Layer Development | Enables PVDC separation from PET substrates during mechanical recycling processes. |
Research Methodology
Multi-period observation of coating capacity utilization, regulatory submission timelines, and vinylidene chloride monomer trade flows anchored the trend analysis, supplemented by interviews with pharmaceutical packaging engineers, coating line operators, regulatory affairs specialists, and polymer procurement directors. Secondary validation drew from FDA 21 CFR 177.1990 filing databases, ECHA SVHC candidate list updates, EU PPWR draft implementing acts, and customs trade records for VDC monomer shipments. Bottom-up segment sizing triangulated against top-down industry association estimates.
Segment-weighting across product type, application, end user, and distribution channel dimensions structured the analytical framework, with pharmaceutical blister pack growth rates derived from biologics pipeline analysis and moisture-barrier specification intensity. Food packaging volume projections incorporated processed meat and cheese retail format evolution, while industrial and cosmetic segments received lower weighting coefficients. CAGRs across the analysis window reflect resin intensity per square meter trends from thin-film deposition advances.
The model assumes a particular technology adoption path; alternative pathways for atomic layer deposition of aluminum oxide would alter the outlook for PVDC coating demand in clinical-trial-scale packaging. Forecasts reflect assumptions about EU PPWR implementation timing and FDA stability protocol persistence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Qatar Protective Coatings Market
Coatings
Coatings and Fillings Market
Coatings
Global Passive Fire Protection Coatings Market
Coatings
Dispersion Coating Market
Coatings
Polymer Modified Cementitious Coatings Market
Coatings
Global Solar Panel Coatings Market
Coatings
United States Automotive OEM Coatings Market
Coatings
Fluid Bed and Coating System Market
Coatings
Global Fireproofing Coatings for Wood Market
Coatings
Noise and Vibration Coatings Market
Coatings
Waterborne Wood Coatings Market
Coatings
Japan Marine Coatings Market
Coatings
Mexico Industrial Wood Coatings Market
Coatings
Acrylic Surface Coating Market
Coatings
Electrocoat Market
Coatings
Thermal Insulation Coating Market