
 Global Depth Filtration Market | 2026-2036
Global Depth Filtration Market Size, Share, and Industry Trends Forecast 2026-2036
Global Depth Filtration Market Foresight
Modular filter-train configurations is repositioning how biopharmaceutical buyers evaluate capital versus operating expenditure. Merck KGaA leverages integrated single-use assemblies to capture high-value bioprocessing contracts. Pall Corporation sustains dominance in pleated depth formats for plasma-derived therapies. Sartorius AG differentiates through automated integrity-testing modules bundled with filter cartridges.
Depth filtration employs porous media—cellulose, diatomaceous earth, or synthetic fiber matrices—with graded density structures that retain particles throughout the matrix rather than solely at the surface, achieving nominal ratings from 0.1 to 100 micrometers for clarification and bioburden reduction. Cartridge filters occupy the largest installed base across water treatment and pharmaceutical applications, while melt-blown synthetic media represents the fastest-growing technology segment driven by chemical compatibility demands in specialty chemical processing. Module filters command premium positioning in semiconductor fabrication where ultrapure water specifications from SEMI standards apply.
FDA enforces sterilization-grade filtration validation under guidance documents that mandate bacterial challenge testing and integrity test correlations, while EMA's Annex 1 revision tightens contamination-control expectations for aseptic processing. China's NMPA aligns with PIC/S standards for imported filtration systems used in domestic vaccine production. Buyers must monitor divergence between FDA, EMA, and NMPA validation protocols when specifying multi-regional manufacturing equipment.
Market Dynamics
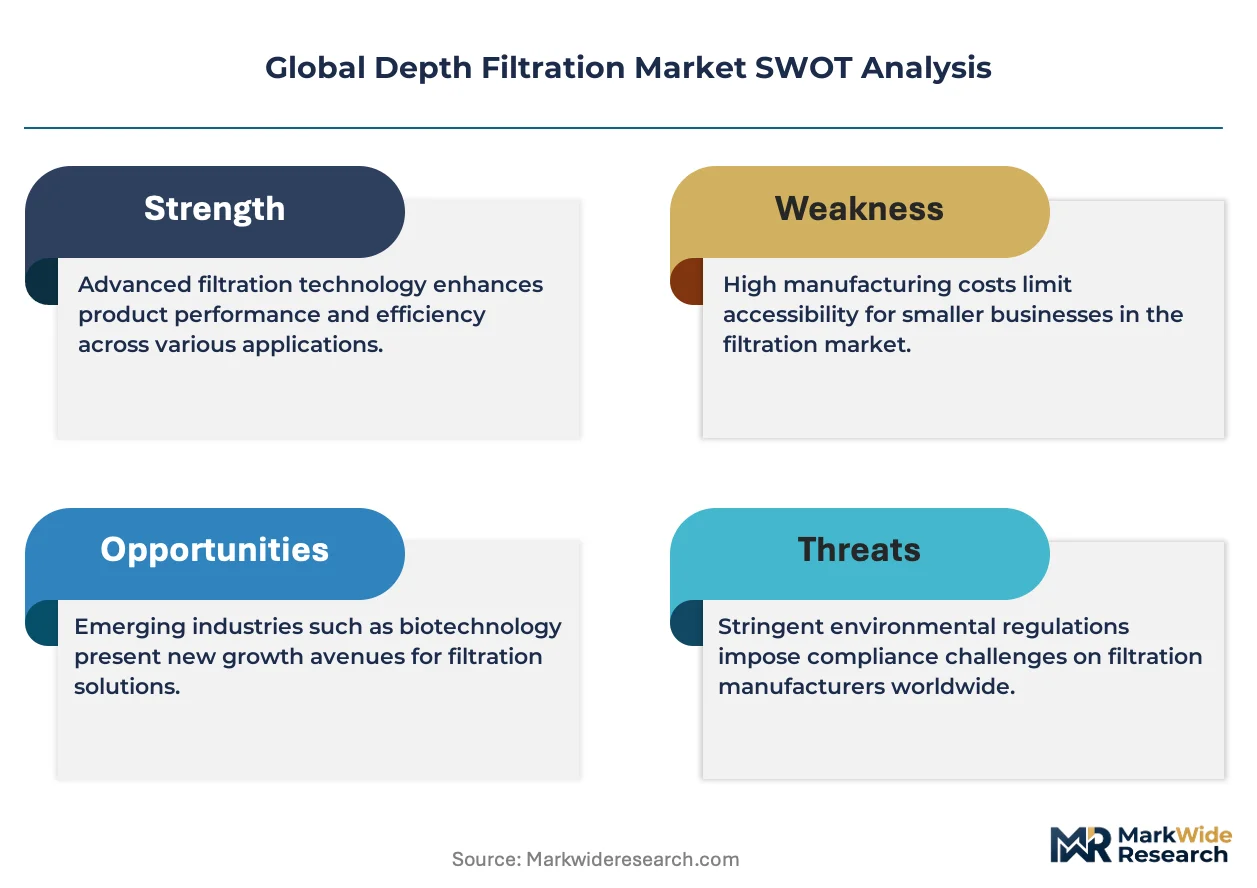
Single-use filtration architectures are forcing biopharmaceutical buyers to restructure capital deployment models, compressing validation timelines while expanding operating expenditure flexibility.
Growth Catalysts
- FDA sterilization-grade validation mandates:Bacterial challenge testing requirements under FDA guidance documents are accelerating replacement cycles for legacy filtration trains in parenteral drug manufacturing.
- Cellulose depth media:Graded-density cellulose matrices with diatomaceous earth blends are capturing share in plasma-derived therapy clarification where protein binding minimization matters.
- China vaccine manufacturing:NMPA alignment with PIC/S standards for imported filtration systems is driving capacity expansion in domestic vaccine production facilities.
Market Restraints
- Polypropylene resin volatility:Melt-blown synthetic media production faces margin compression from petrochemical feedstock price swings.
- German pleated depth concentration:Supply risk concentrates among specialized membrane converters in Baden-Württemberg industrial clusters.
- Surface filtration substitution:Tangential flow and membrane alternatives threaten depth formats in high-value mAb clarification steps.
Strategic Opportunities
- India biosimilar production:CDSCO regulatory harmonization with ICH guidelines creates entry pathways for sterilization-grade filtration vendors.
- Semiconductor ultrapure water:Module filters meeting SEMI F63 standards command premium positioning in wafer fabrication facilities.
- EMA Annex 1 revision:Contamination-control mandates for aseptic processing are expanding integrity-testing automation attach rates.
Industry Challenges
- Integrity test correlation expertise:Validation engineers capable of linking bubble point diffusion data to bacterial retention studies remain scarce across contract manufacturing organizations.
- Legacy stainless steel integration:Single-use depth filtration skids face mechanical and control-system incompatibility with existing buffer preparation infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Depth Filtration Market |
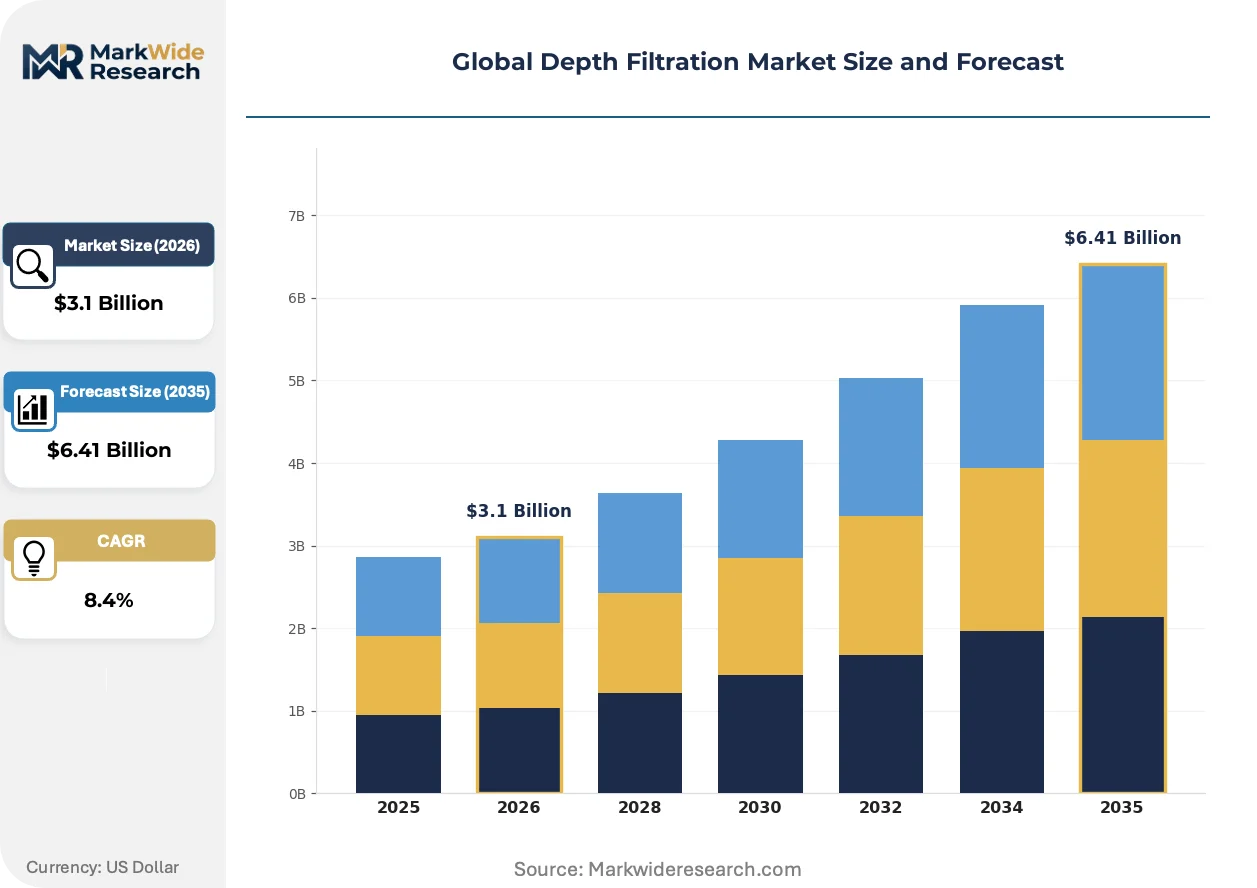
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.41 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cartridge Filters, Bag Filters, Sheet Filters, Module Filters Filtration Technology: Fiberglass, Cellulose, Synthetic Fiber, Melt-Blown Application: Water Treatment, Chemical Processing, Food & Beverage, Pharmaceuticals, Electronics Manufacturing End User Industry: Municipal Utilities, Specialty Chemicals, Consumer Packaged Goods, Biopharmaceutical Companies, Semiconductor Fabricators |
| Companies Covered | Merck KGaA, Pall Corporation, Sartorius AG, 3M, Parker Hannifin Corporation, Donaldson Company, Eaton Corporation, Graver Technologies, Amazon Filters Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Depth Filtration Market Shifts & Advancements
Filtration architecture is pivoting from permanent capital equipment toward disposable process trains, rewriting vendor-customer relationships and service revenue models.
Multi-layer synthetic depth media is absorbing clarification duties previously assigned to centrifugation and precipitation steps in antibody manufacturing. Bioprocess engineers at mammalian cell culture facilities are specifying these formats for harvest operations, reducing footprint and cleaning validation burden. The technology is absorbing capital expenditure that would otherwise flow to separation equipment, compressing facility build-out timelines by twelve to eighteen months.
EMA's Annex 1 revision on sterile medicinal products is tightening particulate and endotoxin limits for aseptic processing environments. Pharmaceutical manufacturers must now demonstrate continuous monitoring of filtration integrity across production campaigns. Plasma fractionators in Germany and Switzerland are responding by bundling automated integrity-test modules with cartridge procurement contracts, shifting supplier relationships toward performance-guarantee structures.
Biopharmaceutical procurement teams are consolidating filtration spend under platform agreements spanning multiple manufacturing sites. Distributor intermediaries face disintermediation as Merck KGaA, Pall Corporation, and Sartorius AG build direct field service organizations. This pattern is most visible in the United States, where top-twenty biologics manufacturers have collapsed vendor panels from twelve suppliers to four preferred partners since 2022.
Global Depth Filtration Market Segmentation
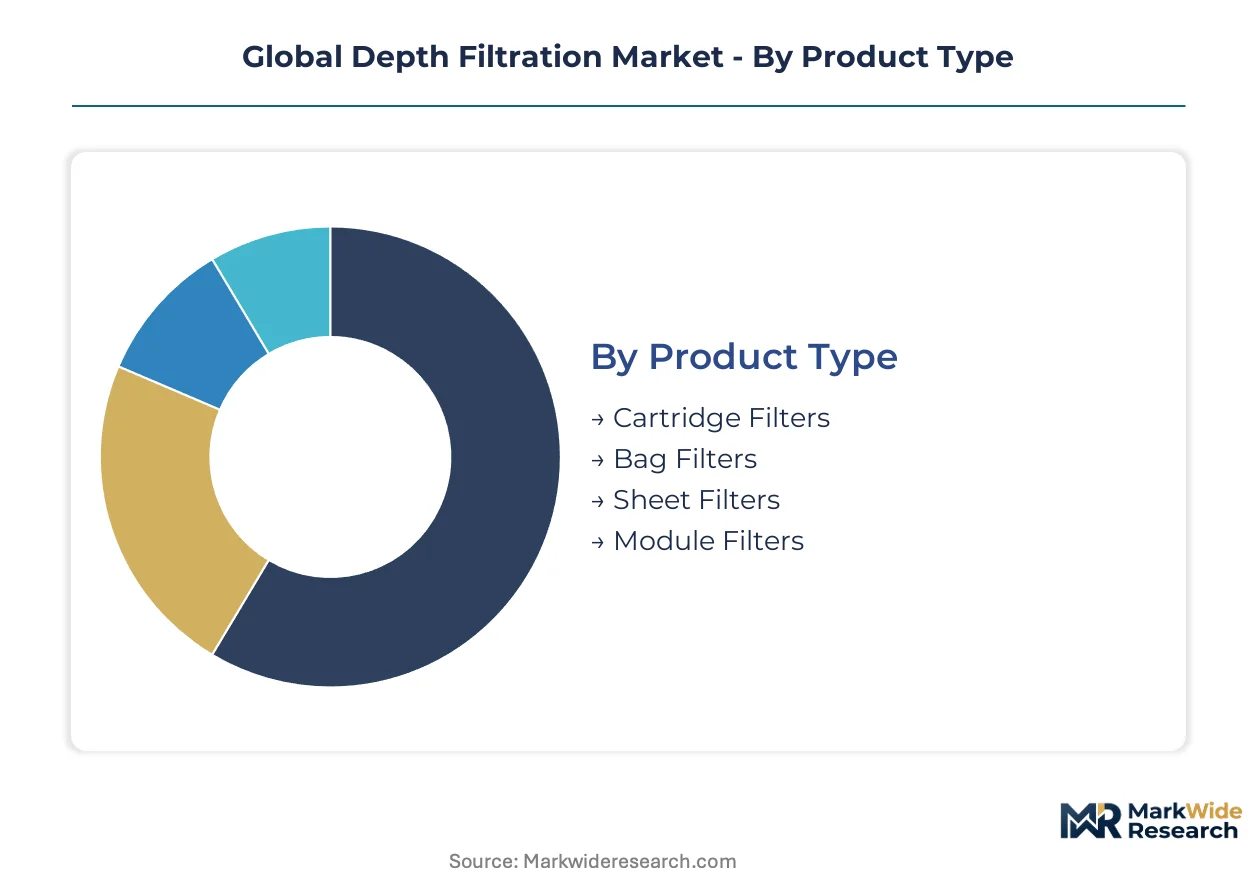
Depth filtration architectures fragment across four distinct product configurations, each commanding different validation protocols and capital intensity. Biopharmaceutical procurement teams weight single-use compatibility against stainless steel permanence when specifying filtration trains for viral clearance operations.
Product Type:
Customization intensity varies sharply across this category, from standardized bag formats to engineered module assemblies requiring site-specific integration.
- Cartridge Filters:Pleated depth configurations with graded-density cellulose or synthetic media dominate installed base across parenteral drug manufacturing. Demand concentrates in Germany and Switzerland where plasma fractionators specify sterilization-grade formats with automated integrity-test compatibility.
- Module Filters:Encapsulated multi-layer assemblies command premium positioning in semiconductor fabrication facilities meeting SEMI F63 ultrapure water specifications. Expansion concentrates in China where domestic wafer foundries are localizing filtration supply chains.
- Bag Filters:Single-use depth formats with polypropylene felt or mesh construction serve buffer preparation and pre-filtration steps in bioprocessing.
- Sheet Filters:Flat-sheet depth media in plate-and-frame configurations retain niche position in small-batch plasma-derived therapy clarification.
Most installed capacity flows through cartridge formats. Expansion is steepest in module configurations.
Filtration Technology:
Material selection here determines chemical compatibility boundaries and extractables profiles that gate regulatory approval pathways.
- Cellulose:Graded-density matrices blended with diatomaceous earth achieve protein-binding minimization critical to plasma fractionation harvest steps. Demand anchors in German and Swiss facilities where EMA Annex 1 revision tightens particulate limits for aseptic processing.
- Melt-Blown:Polypropylene microfiber matrices produced via extrusion-based fiber formation capture share in specialty chemical processing where solvent compatibility exceeds cellulose limits. China chemical parks are absorbing capacity fastest as domestic specialty chemical production scales.
- Fiberglass:Borosilicate glass microfiber depth media serve high-temperature applications and aggressive chemical environments.
- Synthetic Fiber:Engineered polymer blends including PES and PVDF formats bridge performance between cellulose and pure synthetic extremes.
Cellulose retains the largest installed base. Melt-blown formats are climbing the fastest.
Application:
End-use specifications fragment this category across validation intensity, from routine utility water to sterile medicinal product manufacturing.
- Pharmaceuticals:Sterilization-grade depth filtration for parenteral drug manufacturing demands bacterial challenge validation and FDA-compliant integrity test correlations. United States biologics facilities drive specification intensity as top-twenty manufacturers consolidate vendor panels.
- Electronics Manufacturing:Ultrapure water filtration for semiconductor wafer fabrication requires SEMI-standard compliance with sub-micron particle control. China wafer foundries in Shanghai and Hefei are expanding module filter procurement fastest.
- Water Treatment:Municipal and industrial water clarification employs cartridge and bag formats with nominal ratings from 1 to 100 micrometers.
- Chemical Processing:Solvent and intermediate filtration in specialty chemical production prioritizes chemical compatibility over bioburden reduction.
- Food & Beverage:Edible oil clarification and beverage stabilization employ food-grade cellulose and diatomaceous earth depth media.
Pharmaceutical applications command the highest unit economics. Electronics manufacturing is gaining share fastest.
End User Industry:
Procurement sophistication divides this category between regulated life sciences and specification-driven industrial sectors.
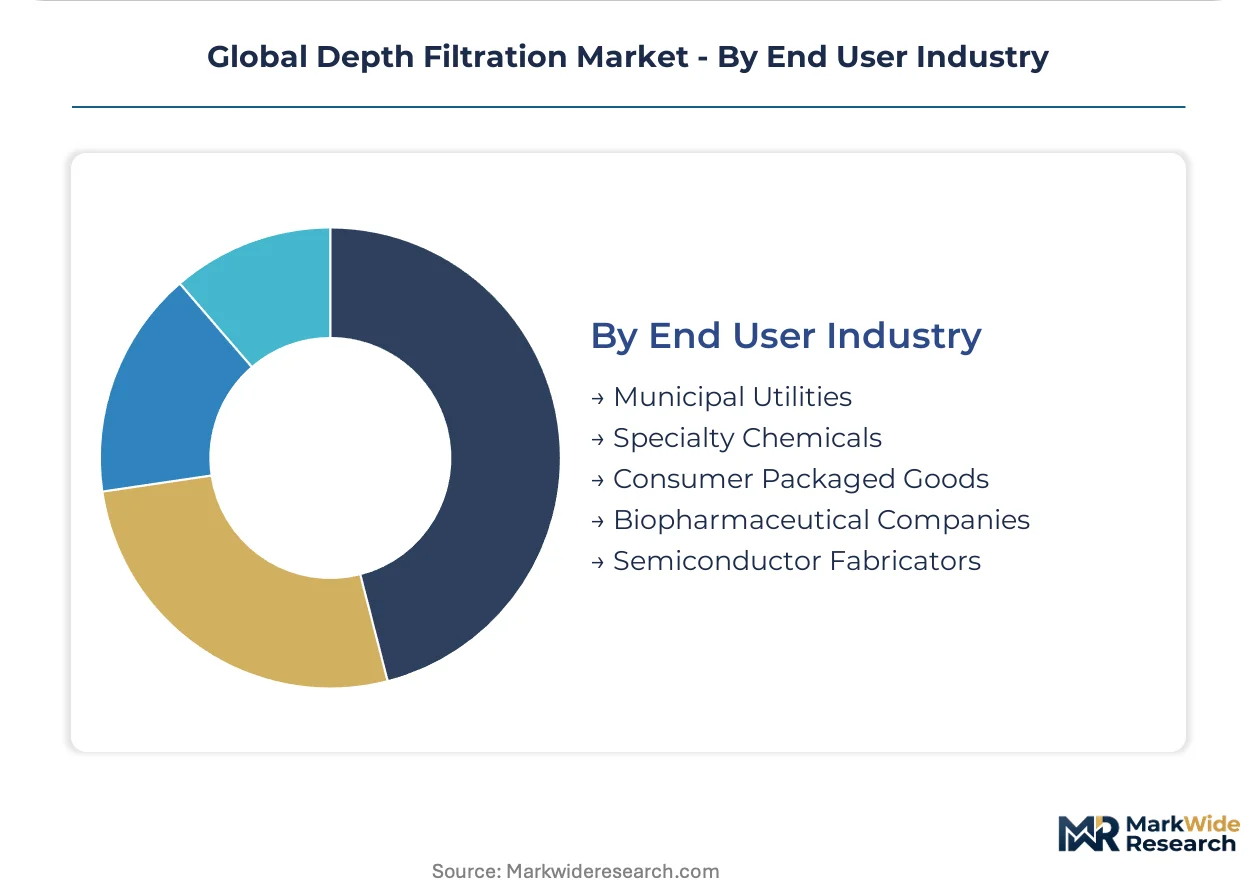
- Biopharmaceutical Companies:Mammalian cell culture facilities specify single-use depth filtration trains for harvest clarification and viral clearance steps. United States and Chinese vaccine manufacturers are scaling capacity fastest under FDA and NMPA alignment pressures.
- Semiconductor Fabricators:Wafer fabrication facilities demand module filters with documented SEMI F63 compliance and particle shedding validation. China domestic foundries are localizing supply chains to reduce import dependency.
- Municipal Utilities:Drinking water and wastewater treatment plants employ standardized cartridge and bag formats with minimal customization.
- Specialty Chemicals:Agrochemical and fine chemical producers specify melt-blown synthetic media for solvent filtration and catalyst recovery.
- Consumer Packaged Goods:Food and beverage manufacturers balance food-grade certification against cost optimization in high-volume clarification operations.
Biopharmaceutical companies absorb the highest-value filtration formats. Semiconductor fabricators are expanding procurement most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Depth filtration technology originated in German industrial chemistry during the early twentieth century, with diatomaceous earth processing establishing the foundational media formats now deployed worldwide. The technology's migration into biopharmaceutical applications accelerated from Basel and Frankfurt manufacturing clusters during the 1980s recombinant protein era.
United States
FDA sterilization-grade validation mandates are compressing replacement cycles for legacy filtration trains across parenteral drug manufacturing facilities. The agency's bacterial challenge testing requirements under current guidance documents force continuous upgrade investment. Massachusetts and North Carolina biologics corridors concentrate procurement consolidation, with top-twenty manufacturers reducing vendor panels from twelve suppliers to four preferred partners since 2022.
Germany
Plasma fractionators in Baden-Württemberg and Hesse specify sterilization-grade cartridge formats with automated integrity-test compatibility for protein-binding minimization. EMA's Annex 1 revision tightens particulate and endotoxin limits for aseptic processing, expanding automation attach rates. Specialized membrane converters in the Stuttgart industrial cluster face supply risk concentration as buyers seek dual-source validation.
China
NMPA alignment with PIC/S standards for imported filtration systems is driving capacity expansion in domestic vaccine production facilities. Shanghai and Hefei wafer foundries are localizing module filter procurement for SEMI F63 ultrapure water compliance. The regulator's harmonization push is accelerating import substitution timelines across bioprocessing equipment categories.
Switzerland
Plasma-derived therapy manufacturers in the Basel region are bundling automated integrity-test modules with cartridge procurement contracts under performance-guarantee structures. Swissmedic maintains stringent contamination-control expectations that exceed baseline EMA requirements. The country's fractionation facilities represent the highest specification intensity for cellulose depth media globally.
India
CDSCO regulatory harmonization with ICH guidelines is creating entry pathways for sterilization-grade filtration vendors serving biosimilar production. Maharashtra and Gujarat pharmaceutical clusters are scaling mammalian cell culture capacity requiring harvest clarification systems. Domestic specialty chemical parks in Gujarat are absorbing melt-blown synthetic media for solvent filtration applications.
Global Depth Filtration Market Competitive Landscape
Premium-margin players sit above commodity-margin players across validation depth and service integration intensity. The market structures around three tiers: integrated system providers capturing platform agreements, specialized media fabricators serving niche chemical compatibility requirements, and regional distributors facing disintermediation pressure. Strategic archetypes include single-use assembly integrators, pleated depth specialists, and automated testing module bundlers. Dominant competitive moves span direct field service organization build-outs and multi-site procurement consolidation targeting top-twenty biologics manufacturers.
Among Germany-based diversified technology groups, Merck KGaA and Sartorius AG occupy positions within the integrated system provider tier, exemplifying the shift toward performance-guarantee contracting structures. Pall Corporation represents the pleated depth specialization archetype, anchoring historical dominance in plasma-derived therapy applications. These three entities collectively illustrate the vendor panel consolidation pattern visible across United States and Chinese biopharmaceutical procurement.
| Leading Market Players |
|---|
| Merck KGaA |
| Pall Corporation |
| Sartorius AG |
| 3M |
| Parker Hannifin Corporation |
| Donaldson Company |
| Eaton Corporation |
| Graver Technologies |
| Amazon Filters Ltd. |
| Others |
Supply & Pricing Matrix
Single-use filtration train adoption simultaneously compresses capital expenditure timelines and concentrates procurement leverage among top-twenty biologics manufacturers, reshaping both cost structures and supplier pricing power across sterilization-grade depth media categories.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates depth filtration procurement, with premium tiers commanding substantial markups for FDA-validated bacterial challenge documentation and automated integrity-test bundling. Price differentiation hinges on certification grade against EMA Annex 1 and FDA guidance standards, alongside volume scale commitments under multi-site platform agreements. Cost compression in standard-tier cellulose cartridges is intensifying because Chinese domestic manufacturers are scaling melt-blown synthetic capacity. Contract manufacturing organizations exhibit highest price sensitivity, while plasma fractionators in Germany and Switzerland demonstrate lowest sensitivity due to protein-binding minimization requirements.
Supply Chain Analysis
Polypropylene resin supply rests on petrochemical feedstock producers in the United States, China, and Germany, with specialty cellulose and diatomaceous earth media drawing from Nordic pulp processors and French mineral extraction sites. Raw material dependencies include borosilicate glass microfiber from Japanese specialty glass manufacturers, PES and PVDF polymer resins from South Korean chemical conglomerates, and graded-density cellulose matrices from Austrian pulp refiners. Single-source vulnerability concentrates in Baden-Württemberg membrane converter clusters, where specialized pleating equipment and validation expertise anchor European supply. Distribution runs through direct field service organizations built by integrated system providers, disintermediating traditional distributor channels across United States and Chinese biopharmaceutical procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in automated integrity-test module bundling and performance-guarantee contracting structures, as EMA Annex 1 revision and FDA validation mandates shift buyer preference toward outcome-based supplier relationships.
For Market Incumbents: Lock in platform agreements across multiple manufacturing sites before vendor panel consolidation completes, particularly targeting United States and Chinese vaccine manufacturers scaling under NMPA-FDA alignment pressures. Deepen backward integration into cellulose pulp refining and diatomaceous earth processing to defend margin position against commodity resin volatility. Prioritize certification investment for SEMI F63 compliance to capture semiconductor ultrapure water module filter premiums. For New Entrants and Emerging Players: The price-point gap between premium sterilization-grade cartridges and economy bag filters creates entry pathways for mid-tier synthetic depth media with validated extractables profiles. Target India biosimilar production facilities in Maharashtra and Gujarat clusters, where CDSCO-ICH harmonization is expanding sterilization-grade filtration demand without entrenched incumbent relationships. Pursue go-to-market angles through CDMO partnerships rather than direct biopharmaceutical procurement, leveraging validation expertise scarcity as differentiation. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized membrane converters with automated pleating capabilities but limited direct field service infrastructure. Long-term viability over the coming decade favors assets with dual FDA-EMA validation dossiers and established semiconductor industry relationships. Watch NMPA import substitution timelines as the critical inflection signal, where accelerated domestic vaccine manufacturing localization would revalue China-facing filtration supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Integrity-Test Module Bundling | EMA Annex 1 revision mandates continuous filtration monitoring across aseptic processing campaigns. |
| Backward Integration into Cellulose Media | Nordic pulp supply control insulates against diatomaceous earth blend cost volatility. |
| SEMI F63 Certification Investment | Shanghai and Hefei wafer foundries localize module filter procurement for ultrapure water compliance. |
| Multi-Site Platform Agreement Consolidation | Top-twenty biologics manufacturers collapsed vendor panels from twelve suppliers to four preferred partners. |
| CDMO Channel Partnership Development | Validation engineer scarcity across contract manufacturing organizations creates service attach opportunities. |
Research Methodology
Bottom-up biopharmaceutical facility modeling reconciled against top-down filtration media production tracking forms the analytical core of this study. Primary interviews with bioprocess engineers, regulatory affairs leads at plasma fractionators, CDMO procurement directors, and semiconductor fab utility managers combined with secondary validation from FDA 483 inspection observations, EMA GMP inspection reports, SEMI standards documentation, and NMPA import registration filings. Triangulation across these sources ensures demand-side consumption estimates align with supply-side capacity disclosures.
Input-output matrices map filtration technology adoption across product type, material chemistry, application severity, and end-user procurement sophistication dimensions over the projection horizon. CAGRs derive from segment-level volume build-ups reconciled against macro-level biologics capacity expansion announcements and semiconductor wafer fab construction pipelines. Industry-specific forecast inputs include mammalian cell culture harvest clarification step absorption rates and single-use train validation timeline compression factors.
Caveats apply where NMPA regulatory acceleration, polypropylene resin price volatility, or tangential flow membrane substitution advances could materially shift the outlook. Forecasts reflect assumptions regarding continued FDA-EMA validation protocol convergence and sustained Chinese domestic manufacturing localization momentum. A small set of named triggers—NMPA PIC/S harmonization pace, EMA Annex 1 enforcement intensity, and semiconductor capital expenditure cycles—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Canada Filtration and Separation Market
Filters
High-Efficiency Particulate Air (HEPA) Filters Market
Filters
United States Activated Carbon Market
Filters
ePTFE Filter Film Market
Filters
Global Filter Press Market
Filters
US Baghouse Filters Market
Filters
Compact Filters Market
Filters
Furnace Filters Market
Filters
Aerospace Filter Market
Filters
Global Sterile Filtration Market
Filters
Europe Industrial Air Filtration Market
Filters
Global Industrial Filters Market
Filters
Coolant Filtration Systems Market
Filters
Nonwoven Filter Media Market
Filters
Anti-Microbial Filter Market
Filters
Diatomaceous Filter Aid Market