

Coolant Filtration Skids Market Size, Share, and Industry Trends Forecast 2026-2036
Coolant Filtration Skids Market Insights
Premium coolant filtration skids with real-time particle monitoring and automated backflush cycles is decoupling from commodity units with basic bag or cartridge systems. Donaldson Company leverages its vertical integration into filter media manufacturing to sustain margin advantages in high-purity applications. Pall Corporation anchors the semiconductor fabrication segment with membrane-based skids that compete on sub-micron retention ratings.
Coolant filtration skids are self-contained process units engineered to remove particulate, tramp oil, and bacterial contaminants from industrial cutting and grinding fluids, typically operating at flow rates from 20 to 500 gallons per minute with filtration precision ranging from 100 microns down to 0.1 micron depending on technology configuration. Their primary purpose is to extend coolant life, reduce tool wear, and ensure dimensional accuracy in precision machining operations. Stationary skids dominate installed base across large machine shops and power generation facilities where continuous throughput justifies permanent infrastructure, while portable skids are gaining traction in job-shop environments that require flexibility across multiple work cells. Modular skids occupy the fastest-expanding niche as chemical processors and semiconductor fabricators demand scalable capacity that integrates with existing plant distributed control systems.
The US EPA enforces effluent limitations under the Clean Water Act that prohibit direct discharge of metalworking fluids containing heavy metals and biocides, compelling facilities to adopt closed-loop filtration or bear escalating pretreatment costs. OSHA's metalworking fluid standards further shape product design by mandating mist control and microbial exposure limits that filtration skids must address through integrated coalescence and UV sterilization modules. Stakeholders must monitor how evolving semiconductor fabrication node transitions below 3 nanometers will redefine coolant purity thresholds and filtration technology selection criteria.
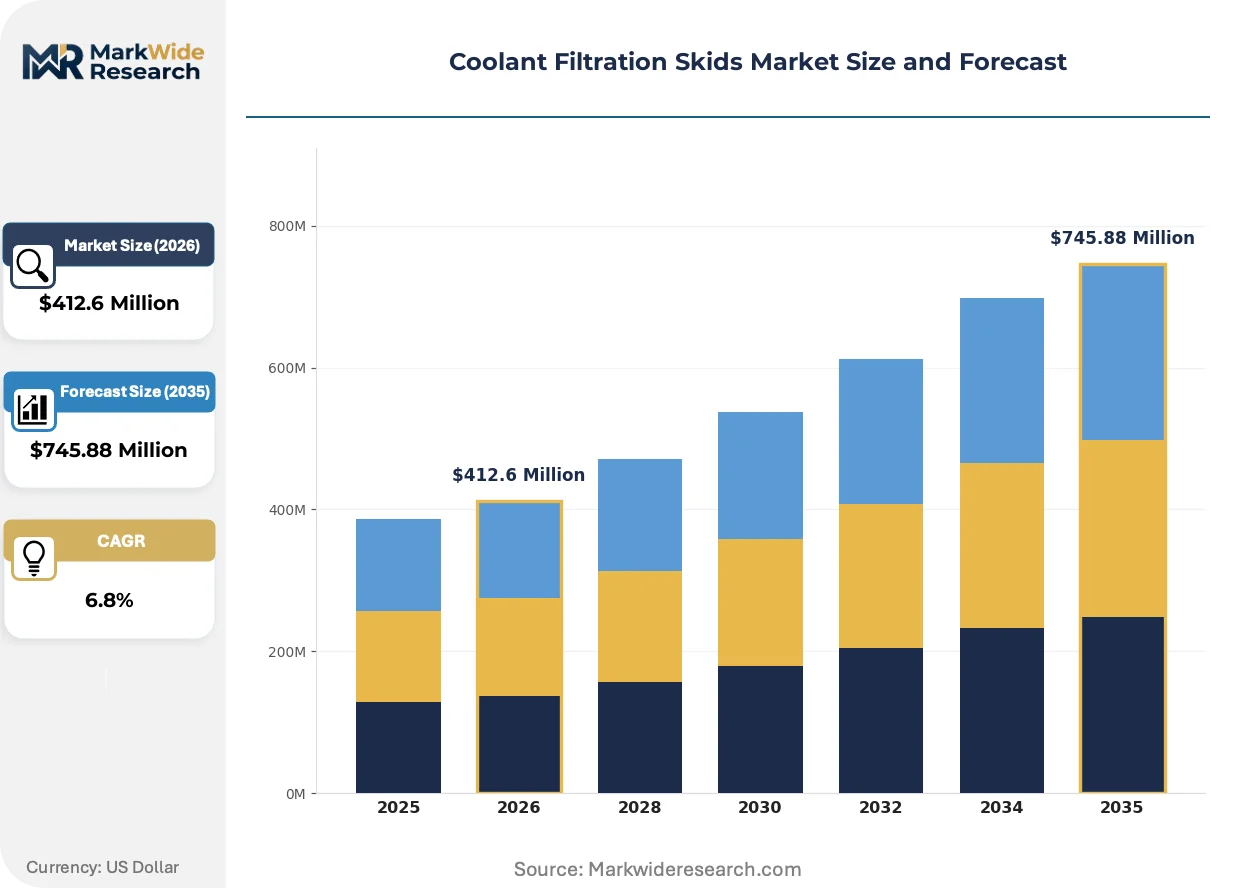
Market Dynamics
The transition to sub-3-nanometer semiconductor nodes is compressing coolant purity thresholds from 0.1 micron toward 0.01 micron, forcing filtration skid architectures toward membrane-UV hybrid systems that legacy bag-filter infrastructure cannot retrofit economically.
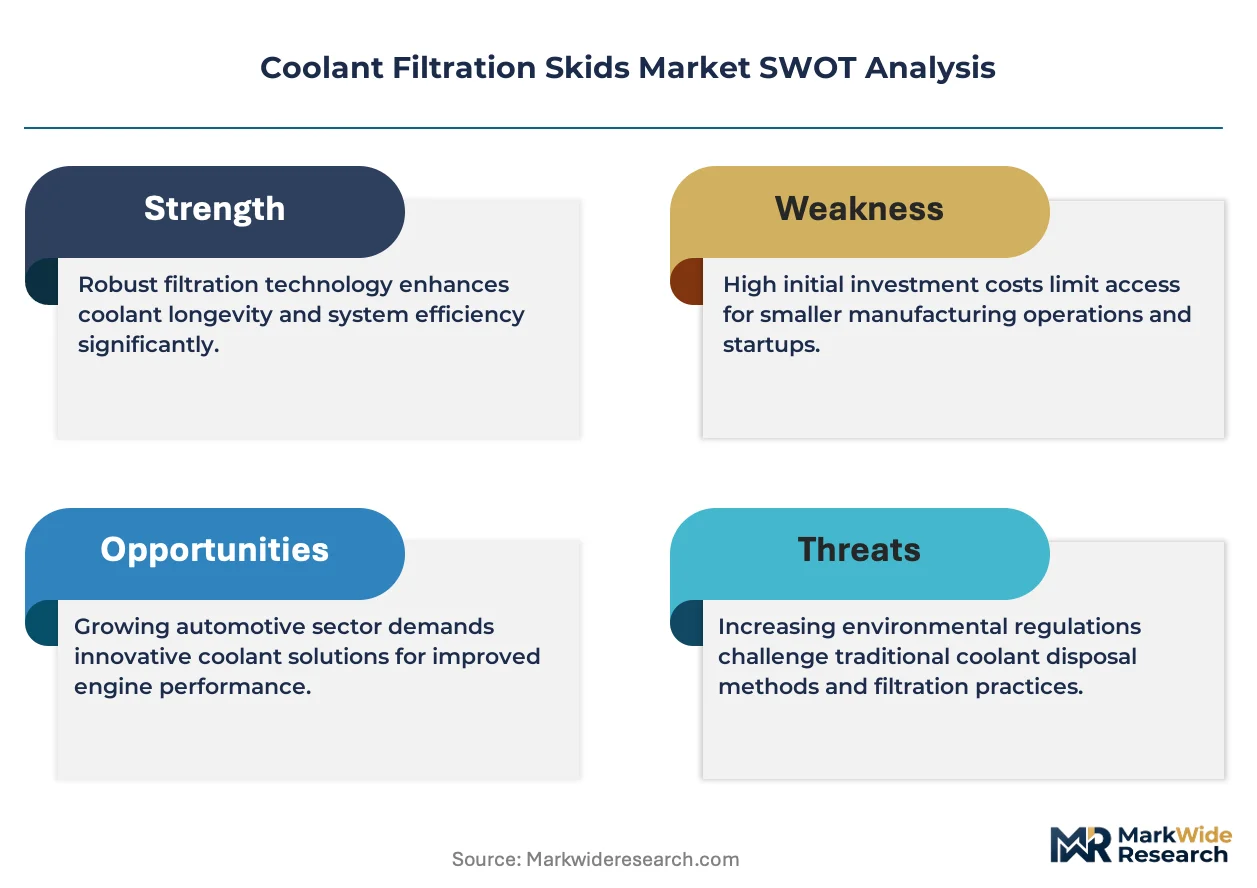
Growth Catalysts
- OSHA metalworking fluid standards:Mist control mandates and microbial exposure limits in the United States are accelerating replacement of open-sump systems with enclosed skids integrating coalescence and UV sterilization modules.
- Semiconductor fabrication clusters:Taiwan, South Korea, and Germany are expanding captive coolant recycling infrastructure to support advanced packaging and EUV lithography operations requiring near-zero particle counts.
- Closed-loop chemistry:Advanced coalescing media and electrostatic oil separation are extending coolant service life from weeks to months, reducing disposal volumes and chemical procurement cycles for machine shops.
Market Restraints
- Stainless steel and membrane input costs:316L vessel fabrication and PES membrane supply concentrate among Japanese and German specialty suppliers, creating margin pressure during commodity cycles.
- Skilled technician scarcity:Commissioning of automated backflush systems requires cross-trained personnel fluent in both hydraulics and PLC programming, a capability gap acute in North American job shops.
- Tramp oil removal limitations:Conventional coalescers struggle with emulsified synthetic coolants below 20 cSt viscosity, forcing premature membrane replacement in high-pressure grinding applications.
Strategic Opportunities
- Indian precision manufacturing:PLI scheme incentives for machine tools and automotive components are creating first-mover advantage for skid suppliers offering localized service networks.
- UV-ozone convergence:Integration of UV sterilization with advanced oxidation processes addresses bacterial resistance in long-life coolants, opening premium positioning in medical device machining.
- Retrofit channel development:Direct-to-factory technical sales bypassing traditional distributor markups is capturing margin in mid-size German and Japanese machine shop segments.
Industry Challenges
- Legacy DCS integration:Semiconductor fabricators require skid control systems to communicate via EtherNet/IP and Profinet protocols, demanding software engineering capabilities absent from traditional filtration vendors.
- ISO 19443 certification timelines:Nuclear supply chain qualification for coolant skids used in fuel fabrication extends validation cycles to 18-24 months, compressing revenue recognition windows.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coolant Filtration Skids Market Trends and Innovations
Real-time particle monitoring and predictive maintenance algorithms are repositioning coolant filtration from passive utilities to active process control nodes within smart manufacturing architectures.
Membrane-based ultrafiltration is consolidating position in semiconductor coolant loops by achieving consistent 0.05-micron retention across variable flow demands. Taiwan Semiconductor Manufacturing and Samsung Foundry are specifying these systems for EUV tool cooling circuits. The technology is consolidating aftermarket service revenues around membrane replacement schedules rather than consumable filter media.
REACH restrictions on biocides in metalworking fluids are compelling European manufacturers toward physical sterilization methods. The European Chemicals Agency's 2023 updated candidate list for Substances of Very High Concern is accelerating UV and ozone module adoption in German automotive powertrain machining. Component suppliers are responding with modular skid designs that segregate European-specification sterilization from standard configurations.
Machine shops are unbundling after-sales service from initial equipment procurement, selecting third-party fluid management specialists for coolant analysis and optimization. This pattern disrupts traditional OEM service contracts in the United States Midwest manufacturing belt. Buyers in Ohio and Michigan machine shop clusters now prioritize open-architecture skids compatible with independent fluid chemistry monitoring services.
Coolant Filtration Skids Market Segmentation
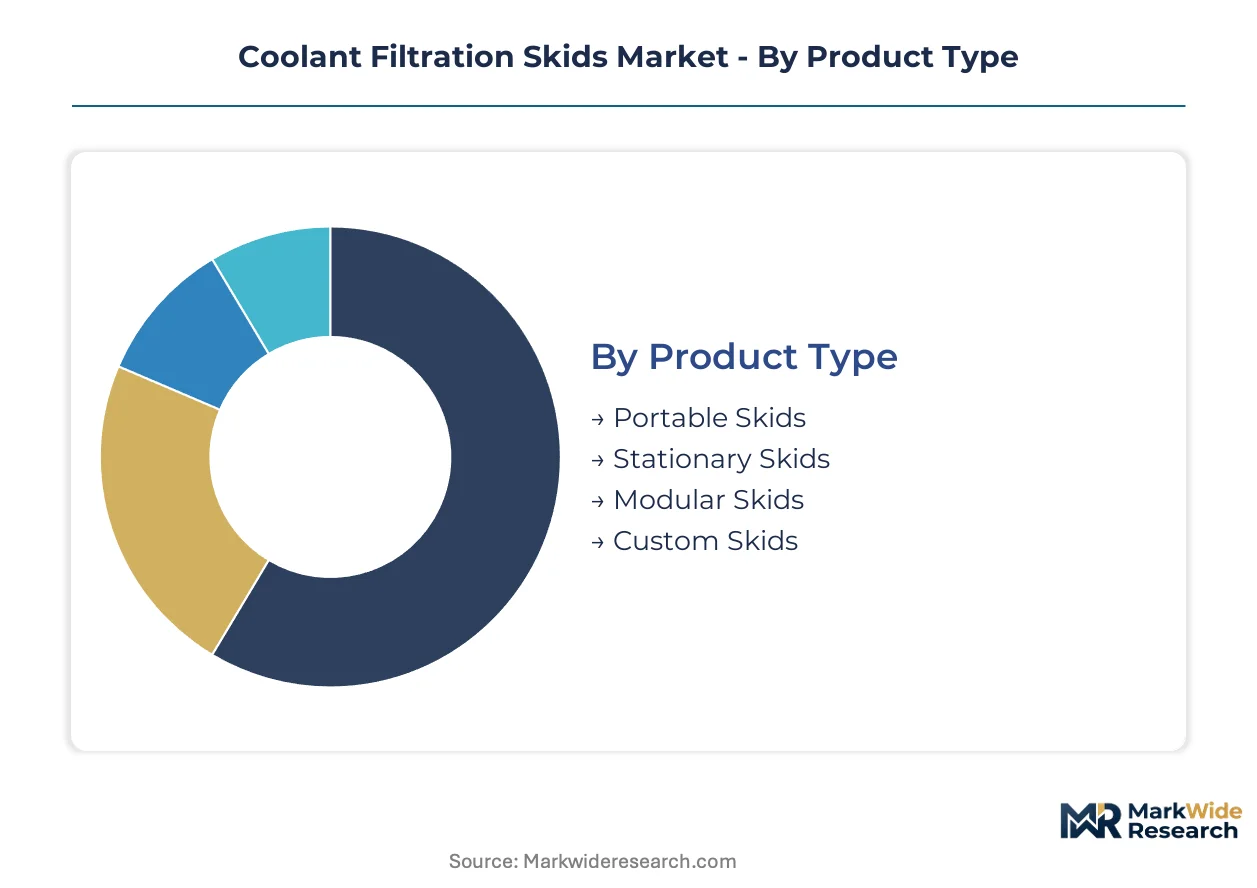
Coolant filtration skids serve divergent certification regimes across semiconductor, nuclear, and automotive supply chains. Product architecture and filtration technology selection determine compliance burden and service revenue potential.
Product Type:
Stationary and portable skids carry distinct certification obligations under OSHA enclosure standards and semiconductor cleanroom protocols.
- Stationary Skids:Permanent installations engineered for continuous flow rates exceeding 200 gallons per minute with 316L stainless steel pressure vessels. Demand clusters in German power generation facilities and Japanese automotive powertrain machining centers where EPA and METI efficiency mandates require permanent infrastructure.
- Portable Skids:Mobile units mounted on casters or forklift pockets for flexible deployment across work cells. Ohio and Michigan job shops favor these for multi-machine coverage, though OSHA mist control compliance adds enclosure costs that compress margins.
- Modular Skids:Scalable configurations integrating with plant distributed control systems via EtherNet/IP or Profinet protocols. Taiwan and South Korean semiconductor fabricators specify these for EUV lithography cooling circuits.
- Custom Skids:Engineered-to-order systems for nuclear fuel fabrication or medical device machining requiring ISO 19443 or FDA validation cycles extending 18-24 months.
Stationary skids sit at the top of the volume ranking, with modular skids climbing the fastest.
Filtration Technology:
Technology selection maps directly to coolant purity thresholds and replacement part revenue models.
- Membrane Filtration:Polyethersulfone and ceramic membranes achieving 0.05-micron retention for EUV tool cooling. Samsung Foundry and Taiwan Semiconductor Manufacturing specify these systems, consolidating aftermarket revenues around scheduled membrane replacement rather than consumable media.
- Mechanical Filtration:Bag and cartridge systems handling 10-100 micron particulate removal for general machining. German automotive suppliers deploy these for cost-sensitive high-volume grinding operations where coolant life extension justifies capital outlay.
- Centrifugal Separation:Tramp oil removal through rotational force separation without filter media consumption. Struggles with emulsified synthetics below 20 cSt viscosity in high-pressure applications.
- Magnetic Filtration:Rare-earth drum or rod configurations capturing ferrous particles in honing and grinding operations. Japanese machine tool builders integrate these for cast iron machining in Nagoya manufacturing clusters.
Mechanical filtration dominates installed base by unit volume, while membrane filtration delivers the steepest expansion trajectory.
Application:
Application verticals separate regulated discharge environments from closed-loop captive systems.
- Metalworking:Cutting and grinding fluid management across automotive, aerospace, and general machining. US EPA Clean Water Act enforcement drives closed-loop adoption in Midwest machine shop belts.
- Electronics Manufacturing:Sub-3-nanometer semiconductor fabrication requiring near-zero particle counts. South Korean and German clusters specify membrane-UV hybrid architectures.
- Chemical Processing:Aggressive fluid handling with corrosion-resistant vessel specifications. Modular skids integrate with existing plant control systems.
- Power Generation:Turbine and generator cooling water filtration with continuous duty requirements. Stationary skids predominate in base-load facilities.
Metalworking commands the largest equipment base, with electronics manufacturing gaining share fastest.
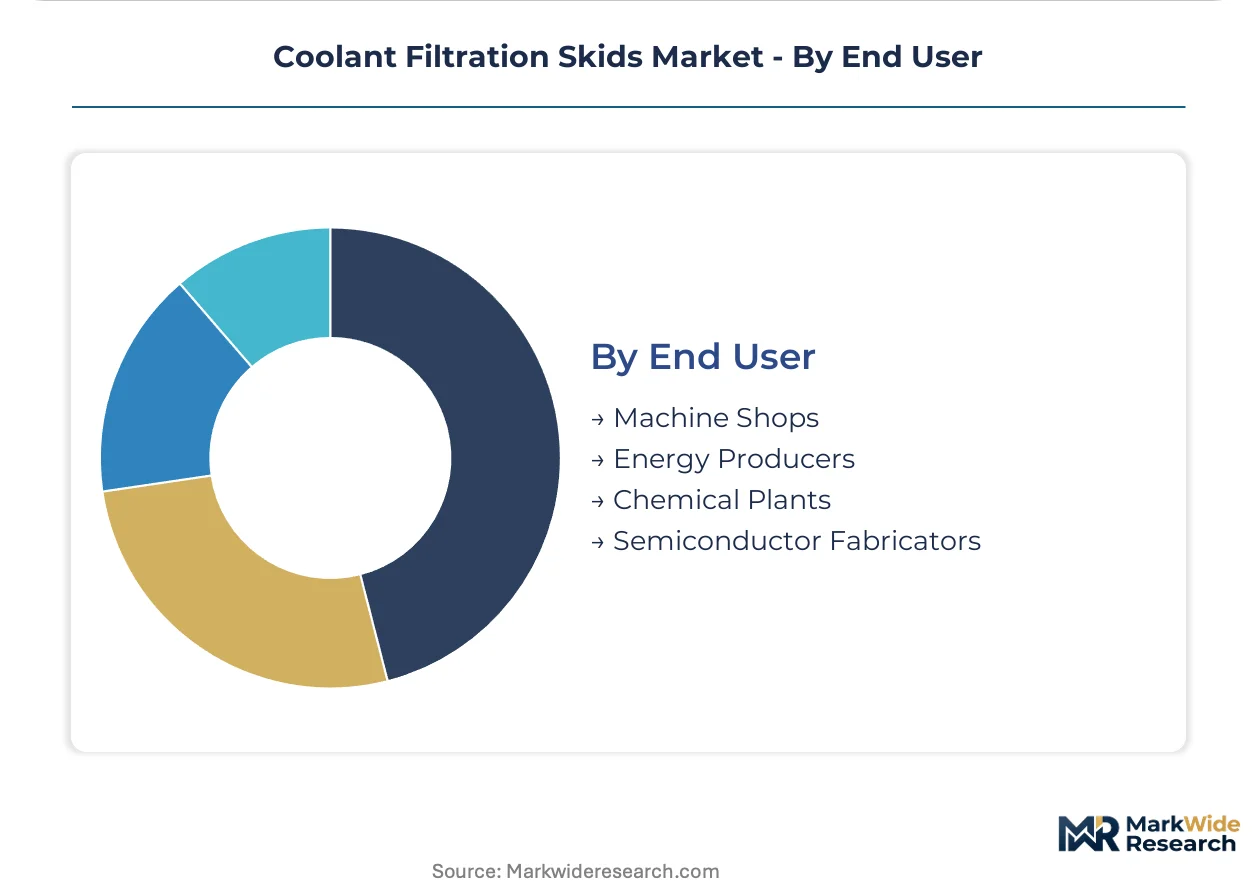
End User:
End user categories reflect divergent procurement sophistication and service unbundling trends.
- Semiconductor Fabricators:Captive coolant recycling infrastructure with specification power over filtration architecture. Taiwan and South Korean foundries drive membrane technology roadmaps.
- Machine Shops:Independent job shops and contract manufacturers prioritizing open-architecture skids compatible with third-party fluid management services. Ohio and Michigan buyers increasingly bypass OEM service contracts.
- Chemical Plants:Process integration requirements favoring modular skids with DCS connectivity. REACH biocide restrictions accelerate physical sterilization adoption in European facilities.
- Energy Producers:Continuous-duty applications favoring stationary skids with minimal intervention requirements. Nuclear fuel fabrication imposes ISO 19443 certification timelines.
Machine shops represent the broadest addressable base, while semiconductor fabricators concentrate the highest value per installation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision manufacturing clusters demand membrane-grade filtration, while the United States enforces stricter discharge limits through EPA action. Japan and South Korea compete on semiconductor coolant purity thresholds. India emerges as a cost-sensitive volume opportunity.
United States
OSHA metalworking fluid standards and EPA Clean Water Act enforcement drive closed-loop system adoption. Midwest machine shop belts in Ohio and Michigan favor portable skids with third-party fluid management compatibility. The Southeast automotive corridor specifies stationary systems for powertrain machining.
Germany
REACH biocide restrictions accelerate physical sterilization module demand across automotive powertrain operations. METI efficiency mandates align with permanent infrastructure investments in Baden-Württemberg manufacturing clusters. Bavarian semiconductor equipment suppliers specify modular skids with Profinet integration.
Japan
Sub-3-nanometer node transitions at Nagoya-area fabrication facilities compress coolant purity requirements toward 0.01 micron. METI industrial efficiency programs support captive recycling infrastructure. Cast iron machining clusters in Chubu specify magnetic filtration integration for honing operations.
South Korea
Samsung Foundry and memory fabricators drive membrane-UV hybrid architecture specification for EUV tool cooling. National semiconductor self-sufficiency initiatives expand captive coolant recycling capacity. Busan-Ulsan chemical processing corridors demand corrosion-resistant modular configurations.
India
PLI scheme incentives for machine tools and automotive components create first-mover positioning for localized service networks. BIS standards for industrial fluid quality remain less stringent than OECD benchmarks. Gujarat and Tamil Nadu precision manufacturing clusters prioritize cost-optimized mechanical filtration over membrane systems.
Coolant Filtration Skids Market Competitive Landscape
Top-tier vendors anchor the premium membrane and semiconductor-grade segment, while mid-tier fabricators compete on mechanical filtration and job-shop portability. The vendor base stratifies across three archetypes: diversified filtration conglomerates with captive media production, specialized coolant system houses with regional service density, and industrial automation suppliers leveraging control system integration. Competitive moves concentrate on backward integration into membrane manufacturing and direct technical sales channel development bypassing traditional distribution.
Within the diversified conglomerate tier, Donaldson Company and Parker Hannifin occupy positions defined by upstream control over filter media supply chains. Pall Corporation exemplifies the semiconductor-specialist archetype through membrane-based system representation. Among German-origin industrials, MANN+HUMMEL and HYDAC sit within the automotive-fluid management tradition. Eaton Filtration and Filtration Group represent North American scale-driven positioning across multi-industry applications.
| Leading Market Players |
|---|
| Donaldson Company |
| Eaton Filtration |
| Filtration Group |
| HYDAC |
| MANN+HUMMEL |
| Barnes International |
| Mayfran International |
| Pall Corporation |
| Parker Hannifin |
| Others |
Pricing and Supply Chain Analysis
Captive membrane manufacturing by Japanese and German specialty suppliers anchors both supply security and pricing power for premium coolant filtration skids, insulating tier-one vendors from commodity cycle volatility while forcing mid-tier fabricators toward stainless steel sourcing flexibility. This integration pattern concentrates margin capture among filtration conglomerates with in-house PES membrane production, leaving price-takers exposed to 316L vessel input fluctuations.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for membrane-based skids as Samsung Foundry captive demand absorbs domestic production. Pricing stratifies across premium, standard, and economy tiers with differentiation driven by ISO 19443 certification status and after-sales service bundling. Cost compression in mechanical filtration segments is intensifying because Indian PLI scheme incentives attract low-cost entrants. Machine shops in Ohio and Michigan exhibit highest price sensitivity, while semiconductor fabricators in Taiwan and Germany prioritize purity thresholds over unit economics.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Nagoya, and Austin operate hub-and-spoke patterns feeding precision manufacturing clusters. Geographic supply concentrates in Japan, Germany, and the United States for 316L pressure vessels and PES membrane substrates. Raw material dependencies draw from specialty steel mills in North Rhine-Westphalia, ceramic membrane foundries in Aichi Prefecture, and rare-earth magnetic components from domestic Japanese suppliers. Single-source vulnerability in EUV-grade membrane supply creates structural risk. Distribution runs through authorized technical sales channels bypassing traditional industrial distributors in mid-size German and Japanese machine shop segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-biocide-restricted European demand for physical sterilization modules and India's cost-optimized mechanical filtration growth, with regulatory divergence creating premium positioning opportunities in Germany against volume scaling in Gujarat.
For Market Incumbents: Deploy direct technical sales channel control to defend against distributor disintermediation in Ohio and Michigan machine shop belts. Invest in ISO 19443 certification infrastructure to capture nuclear fuel fabrication qualification timelines extending revenue recognition windows. Consolidate membrane replacement service contracts before third-party fluid management specialists unbundle aftermarket revenues.
For New Entrants and Emerging Players: Job shops in India's Tamil Nadu precision manufacturing clusters represent the most penetrable buyer archetype. Target localized service network gaps under PLI scheme incentives where incumbent footprint remains thin. Pursue modular skid architectures with EtherNet/IP compatibility to bypass legacy DCS integration barriers that stall traditional filtration vendors.
For Investors and Strategic Acquirers: Roll-up economics work for regional coolant system houses with dense service networks because semiconductor fabricator specification power is fragmenting procurement across captive recycling infrastructure. Target mid-tier fabricators with backward integration into filter media manufacturing. Watch for EUV node transitions below 3 nanometers as inflection indicator for membrane-UV hybrid system demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Manufacturing | Captive PES supply secures margin retention for EUV-grade filtration specifications. |
| Direct Technical Sales Channel Development | Bypassing distributor markups captures margin in Baden-Württemberg automotive powertrain machining. |
| ISO 19443 Certification Investment | Nuclear fuel fabrication qualification extends validation cycles and compresses competitive entry. |
| Modular Skid Architecture with DCS Integration | Profinet compatibility opens Bavarian semiconductor equipment supplier procurement. |
| Localized Service Network Expansion | PLI scheme incentives in Gujarat and Tamil Nadu create first-mover positioning against incumbent gaps. |
Research Methodology
Bottom-up semiconductor fabrication and machine shop modeling reconciled against top-down filtration equipment production tracking forms the analytical core. Primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads combined with secondary validation from EPA enforcement databases, METI industrial efficiency program disclosures, SEC 10-K filings, and customs trade records. Triangulation across stakeholder inputs and documentary sources ensures segment-level precision.
Historical trendline analysis of installed base replacement cycles and captive recycling infrastructure buildouts informs projection methodology. Segmentation dimensions span product architecture, filtration technology, application vertical, and end-user procurement sophistication across the modeling period. CAGRs derive from capacity expansion announcements, regulatory compliance deadline clustering, and node transition roadmaps. Forecast inputs incorporate EUV lithography cooling circuit specifications and REACH biocide restriction implementation timelines.
Underlying measurement precision varies by segment; semiconductor fabrication and nuclear fuel fabrication carry tighter precision than general machine shop applications. Forecasts reflect assumptions around regulatory enforcement intensity, node transition pacing, and skilled technician availability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.