
 Global Filter Press Market | 2026-2036
Global Filter Press Market Size, Share, and Industry Trends Forecast 2026-2036
Global Filter Press Market Analysis
The gap between premium membrane systems and commodity chamber units is repositioning procurement patterns across the industry. ANDRITZ leverages its Austrian engineering base to dominate high-pressure membrane applications for mining tailings. Jingjin Equipment anchors volume production of standard chamber presses for China's municipal water sector. Alfa Laval differentiates through automated self-cleaning architectures that reduce labor intensity in European food processing plants.
A filter press is a batch-operated pressure filtration device comprising a series of recessed plates or membranes arranged in a frame, where hydraulic pressure drives slurry dewatering to cake solids contents of 15–40 percent by weight depending on feed characteristics. Its primary industrial purpose is to separate liquids from solids in slurries across wastewater, mining, chemical, and food processing operations. Membrane press configurations command the strongest margin pools due to their ability to achieve lower cake moisture through secondary squeezing with inflatable diaphragms. Automatic operation mode is displacing manual and semi-automatic systems as labor costs rise and continuous processing demands intensify in North American water treatment facilities. Sludge dewatering remains the dominant application by installed base, though reclamation applications in battery metals recycling are gaining traction.
EPA effluent limitation guidelines under the Clean Water Act shape product specifications for U.S. municipal and industrial installations, while the EU Industrial Emissions Directive mandates best available techniques that elevate membrane press adoption across German and French chemical complexes. China's MEE enforces progressively tighter discharge standards that filter press vendors must certify against for market access. Stakeholders should monitor how evolving lithium extraction regulations in multiple jurisdictions redirect equipment demand toward higher-corrosion-resistance alloy configurations.
Market Dynamics
The divergence between membrane squeeze technology and conventional chamber designs is fragmenting procurement patterns across mining, chemical, and municipal water sectors. Equipment buyers now face distinct capital-labor tradeoffs that reshape vendor selection criteria and installation timelines.
Growth Catalysts
- Tailings dewatering mandates:Chilean mining regulators enforce dry-stack tailings requirements that compel copper and lithium operators to install high-pressure membrane systems. Australian coal and iron ore producers follow similar compliance pathways.
- EPA effluent standards:The Clean Water Act's updated limitation guidelines force U.S. municipal wastewater facilities to replace aging belt presses with automated filter press trains capable of achieving 18-22 percent cake solids.
- Battery metals reclamation:Lithium hydroxide and nickel sulfate recovery operations in China's Jiangsu province deploy corrosion-resistant alloy presses to extract value from spent cathode material.
Market Restraints
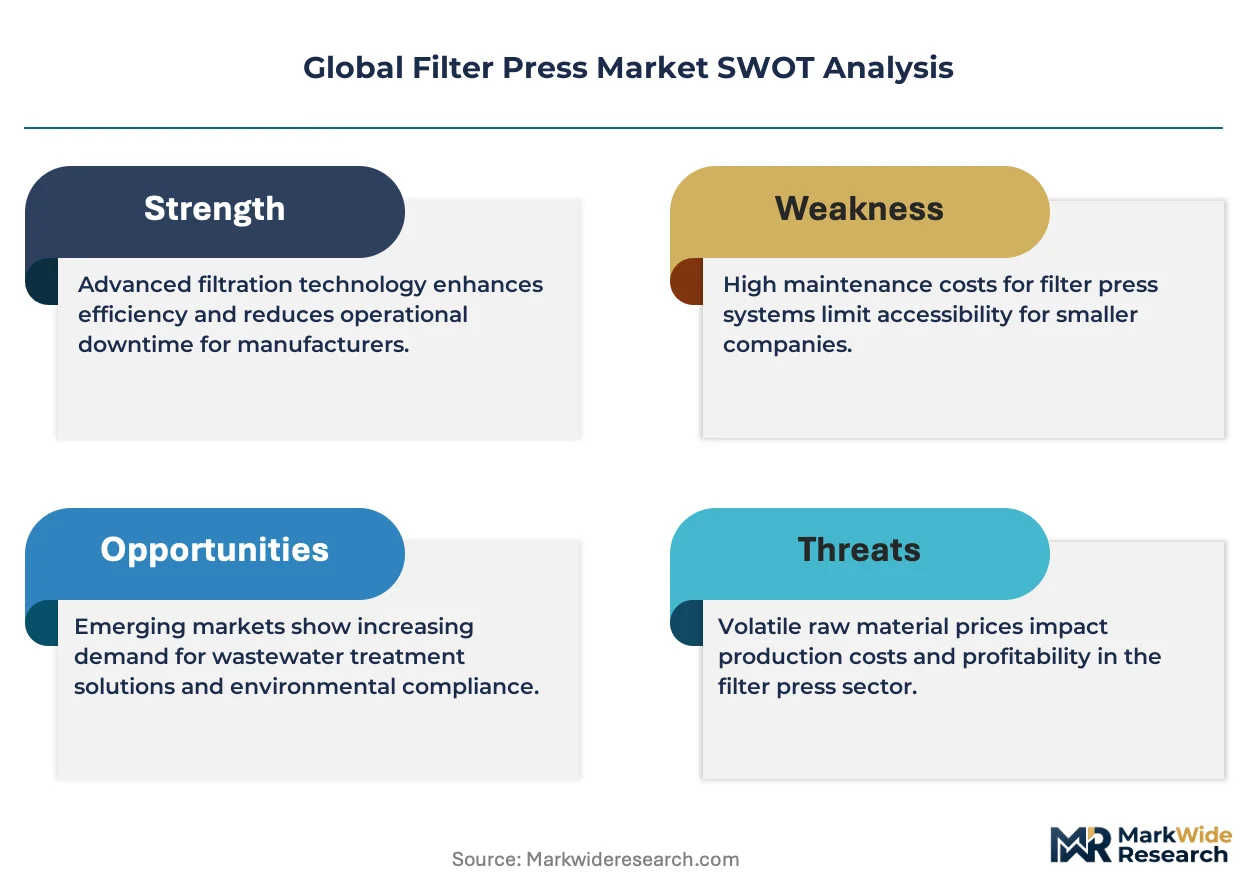
- Stainless steel price volatility:Austenitic grades 316L and 904L constitute 35-45 percent of membrane press fabrication costs, exposing manufacturers to nickel and molybdenum commodity swings.
- Filter cloth supply concentration:Polypropylene monofilament weaving capacity clusters in Germany's Baden-Württemberg region, creating single-source vulnerability for North American OEMs.
- Technical limitation in high-temperature feeds:Standard elastomer diaphragms degrade above 85°C, excluding filter presses from certain hot acid leach circuits in rare earth processing.
Strategic Opportunities
- Indonesia's nickel processing corridor:HPAL (high-pressure acid leach) facilities on Obi Island and Halmahera require tailings dewatering capacity that local suppliers cannot yet provide.
- EU Green Deal industrial water reuse targets:The European Commission's 2030 water efficiency directive creates mandated demand for closed-loop sludge handling in Spanish and Italian food processing clusters.
- Digital twin integration:IoT-enabled predictive maintenance platforms from industrial automation vendors are converging with filter press hardware to create subscription-based performance contracts.
Industry Challenges
- Specialized hydraulic technician scarcity:Mining operators in remote jurisdictions struggle to staff maintenance teams capable of servicing 200-bar membrane squeeze systems.
- Legacy control system incompatibility:Municipal water utilities running 1990s-era SCADA architectures face integration friction when specifying automated cake discharge and cloth washing cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Filter Press Market |
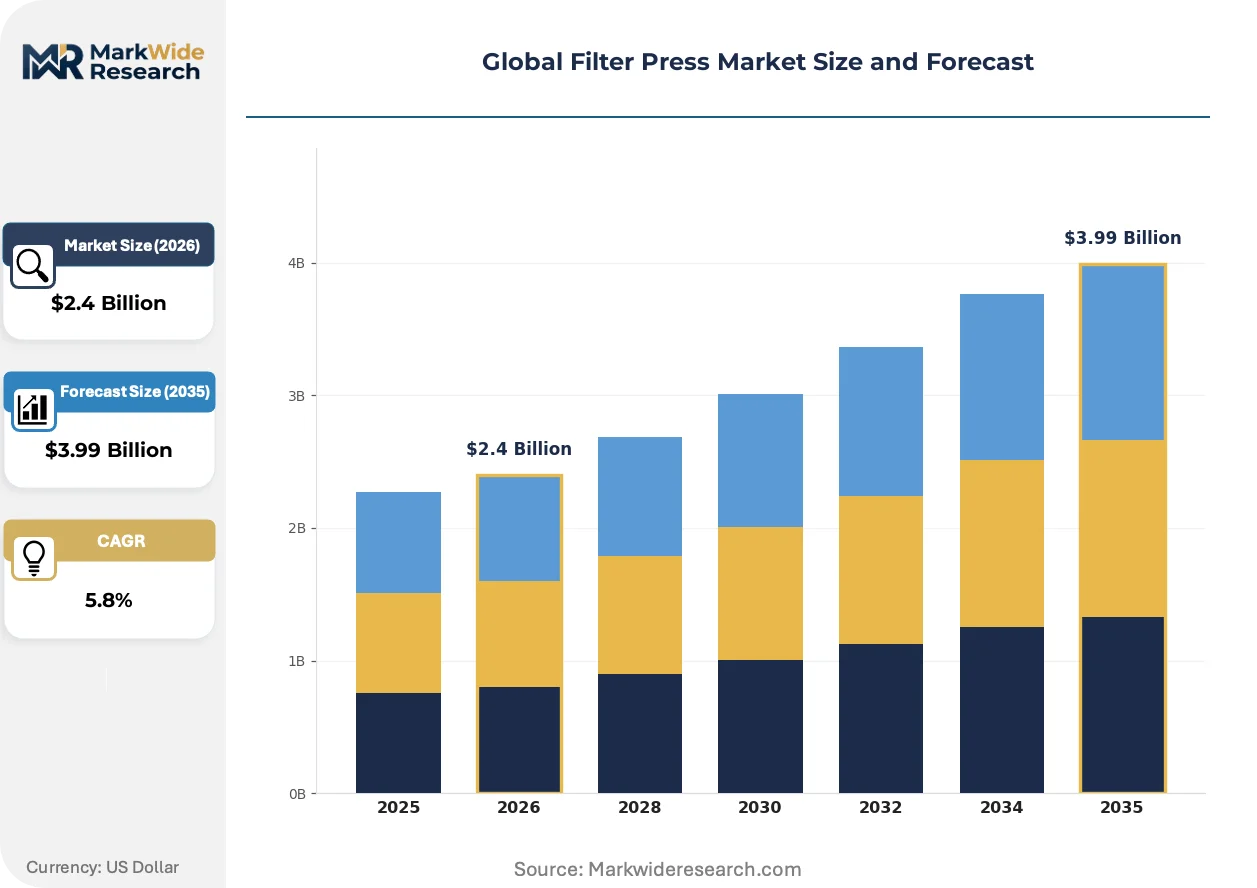
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plate Press, Chamber Press, Membrane Press, Frame Press End User: Water Treatment, Mining, Chemicals, Food & Beverage Operation Mode: Manual, Automatic, Semi-Automatic, Continuous Application: Sludge Dewatering, Clarification, Separation, Reclamation |
| Companies Covered | Jingjin Equipment, ANDRITZ, Metso, Evoqua Water Technologies, Alfa Laval, FLSmidth & Co., Zhongda Bright Filter Press, ISHIGAKI, Aqseptence Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Filter Press Market Emerging Trajectories
Automation architectures and material science advances are compressing batch cycle times while elevating final cake dryness. These developments alter capital allocation patterns across buyer segments and force incumbent vendors to recalibrate R&D priorities.
Membrane squeeze technology with inflatable elastomer diaphragms is expanding into copper concentrate dewatering circuits previously dominated by vacuum disc filters. Chilean state-owned mining operations have piloted 1500mm chamber formats that reduce residual moisture from 14 percent to 9 percent, enabling truckable tailings. The structural consequence is a compression in tailings dam construction demand as dry stacking becomes technically viable for large-scale operations.
China's MEE (Ministry of Ecology and Environment) has tightened discharge standard GB 8978-1996 enforcement for chemical parks along the Yangtze River. Facilities in the Shanghai-Ningbo corridor must now achieve total suspended solids below 50 mg/L, a threshold that legacy sedimentation cannot meet. Membrane press vendors are responding with skid-mounted, containerized systems that reduce site installation timelines from twelve weeks to four weeks.
Equipment-as-a-service contracting is displacing traditional capital purchase models among North American municipal water authorities. Veolia and Suez now offer throughput-guaranteed sludge dewatering packages where the vendor retains cloth inventory risk and maintenance responsibility. This shift is most visible in California's Central Valley, where drought-driven biosolids hauling cost inflation has made operational expenditure structures preferable to upfront capital deployment.
Global Filter Press Market Segmentation
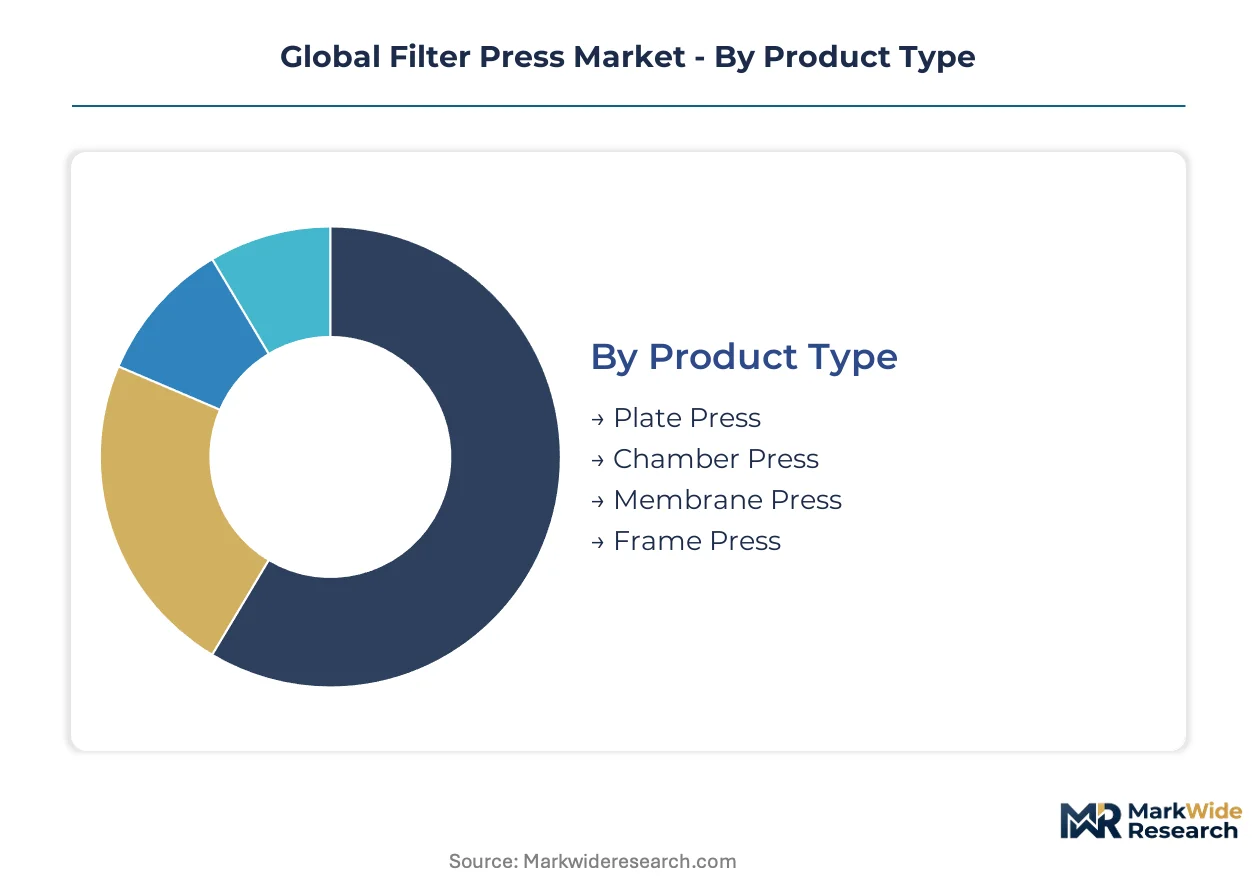
Filter press procurement fractures across four distinct dimensions that reshape vendor positioning and margin capture. Product type determines capital intensity and technical complexity. End user concentration in mining tailings and municipal water creates divergent performance requirements. Operation mode reflects labor cost pressures and integration depth. Application specificity governs alloy selection and cycle optimization.
Product Type:
Membrane configurations command premium pricing while chamber units anchor volume shipments across emerging markets.
- Plate Press:Recessed plate designs with fixed cavities handle lower-pressure dewatering duties in small-scale food processing and textile wastewater. Demand clusters in India's Gujarat chemical belt where SMEs face capital constraints.
- Chamber Press:Standard recessed chamber formats dominate China's municipal water infrastructure buildout. Municipal procurement in Jiangsu and Zhejiang provinces favors these units for sludge handling at 8-15 bar operating pressure.
- Membrane Press:Inflatable elastomer diaphragms enable secondary squeezing cycles that drive cake solids above 30 percent by weight. Chilean copper tailings operations and Australian iron ore producers specify these for dry-stack compliance.
- Frame Press:Simpler plate-and-frame architectures serve laboratory-scale and pilot plant applications in European pharmaceutical development. Limited industrial adoption outside R&D and specialty chemical batch processing.
Today's leader: Membrane Press. Tomorrow's challenger: Chamber Press.
End User:
Application-specific corrosion resistance and throughput requirements fragment the customer base across divergent technical specifications.
- Water Treatment:Municipal sludge dewatering in California's Central Valley and Germany's Ruhr region demands automated cake discharge and cloth washing. EPA and EU Urban Wastewater Treatment Directive enforcement elevates replacement cycles.
- Mining:Copper concentrate filtration in Chile and lithium tailings processing in Western Australia require 316L and 904L stainless construction. Dry-stack tailings mandates in both jurisdictions compel membrane press adoption.
- Chemicals:China's Yangtze River chemical parks deploy skid-mounted systems to meet MEE discharge standards below 50 mg/L total suspended solids. Shanghai-Ningbo corridor facilities prioritize rapid deployment over customization.
- Food & Beverage:European dairy and brewing operations in Denmark and the Netherlands specify automated self-cleaning architectures. Labor cost escalation drives preference for reduced operator intervention.
Water Treatment captures current installed base dominance. Mining claims the steepest expansion trajectory.
Operation Mode:
Labor availability and integration complexity determine automation tier selection across facility types.
- Manual:Hand-operated hydraulic closure and cake discharge persist in India's fragmented SME sector and African mining camps with limited technical staffing. Lowest capital entry point carries highest labor intensity.
- Automatic:Programmable logic controllers manage cloth washing, cake discharge, and filter press sequencing without operator presence. North American municipal utilities specify these to offset technician scarcity and overtime liability.
- Semi-Automatic:Hybrid configurations automate filtration cycles while retaining manual cake handling. Bridges cost-performance requirements in Southeast Asian chemical processing and Latin American food plants.
- Continuous:Belt press derivatives and specialized indexing systems serve high-volume applications where batch cycling creates throughput bottlenecks. Limited penetration in traditional filter press markets due to cake dryness limitations.
Automatic systems lead current procurement. Semi-Automatic formats defend share in cost-constrained emerging markets.
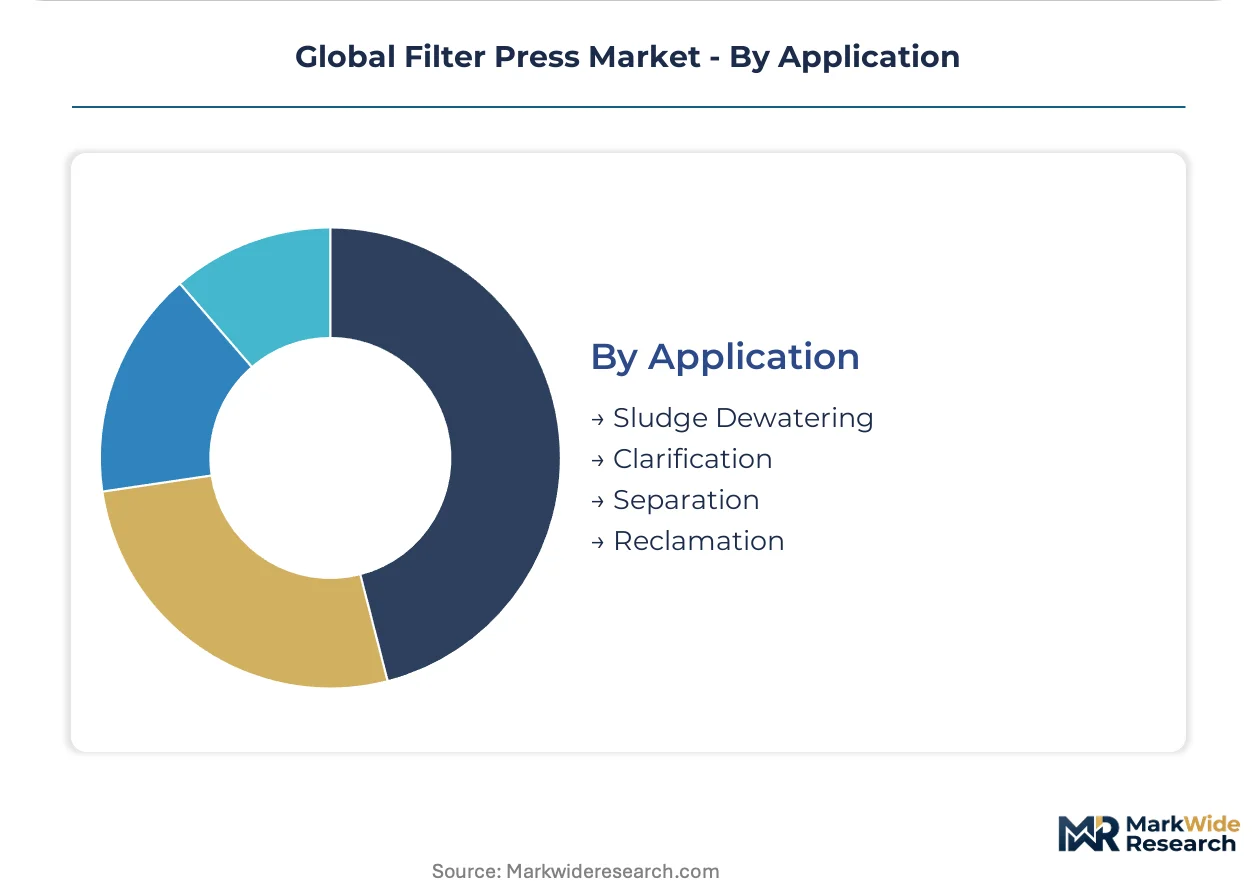
Application:
Final moisture targets and solids recovery economics govern equipment specification and operational parameters.
- Sludge Dewatering:Municipal and industrial wastewater biosolids reduction constitutes the largest installed base. California's drought-driven hauling cost inflation has accelerated equipment-as-a-service contracting models.
- Clarification:Polishing filtration for process water reuse in European food processing and semiconductor fabrication. EU Green Deal water efficiency targets mandate closed-loop implementation.
- Separation:Liquid-solid partitioning in chemical crystallization and hydrometallurgical circuits. Indonesia's HPAL nickel processing corridor on Obi Island generates emerging demand for high-pressure acid leach residue handling.
- Reclamation:Spent battery cathode material recovery and rare earth element extraction. Jiangsu province lithium hydroxide operations deploy corrosion-resistant alloy presses for nickel sulfate and cobalt recovery.
Sludge Dewatering anchors present revenue. Reclamation applications gain share fastest on battery metals recycling expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized hydraulic technicians cluster in Germany's industrial belt and China's Yangtze River corridor, anchoring regional service capabilities for high-pressure membrane systems. These workforce concentrations shape where vendors locate technical centers and where mining operators source maintenance support.
United States
California's Central Valley municipal utilities drive automated filter press procurement to manage drought-inflated biosolids hauling costs. EPA effluent limitation guidelines under the Clean Water Act mandate 18-22 percent cake solids achievement. Equipment-as-a-service contracting proliferates from Fresno to Sacramento as water authorities prefer operational expenditure structures.
Chile
Copper concentrate and lithium tailings operations in the Atacama Desert deploy membrane squeeze systems for dry-stack compliance. Chilean mining regulators enforce strict tailings management protocols that eliminate conventional dam construction. State-owned Codelco operations near Calama have piloted 1500mm chamber formats reducing residual moisture to 9 percent.
Germany
Ruhr region wastewater facilities and Baden-Württemberg chemical complexes upgrade to membrane presses under EU Industrial Emissions Directive enforcement. The country's national environmental regulator mandates best available techniques for sludge dewatering. Polypropylene monofilament weaving capacity concentrates in Baden-Württemberg, creating supply chain vulnerability for North American OEMs.
China
Jiangsu and Zhejiang province municipal authorities favor standard chamber presses for sludge handling at 8-15 bar operating pressure. MEE tightened GB 8978-1996 enforcement for Yangtze River chemical parks. Shanghai-Ningbo corridor facilities deploy skid-mounted containerized systems compressing installation timelines from twelve weeks to four weeks.
Australia
Western Australian lithium tailings processing and Pilbara iron ore operations specify 316L and 904L stainless construction for corrosion resistance. State mining regulators mirror Chilean dry-stack mandates. Queensland coal producers follow similar compliance pathways for tailings dewatering infrastructure.
Global Filter Press Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the filter press supply base. Equipment fabricators owning foundry and machining capabilities face pressure from engineering houses outsourcing plate manufacturing to specialized forges. The market structure fragments across three strategic archetypes: integrated European engineering conglomerates with membrane technology leadership, Chinese volume manufacturers dominating standard chamber production, and Nordic specialists in automated self-cleaning architectures. Competitive moves concentrate on geographic expansion through local assembly partnerships and backward integration into filter cloth weaving capacity.
Within the integrated engineering tier, ANDRITZ and Alfa Laval exemplify divergent positioning strategies. ANDRITZ leverages its Austrian engineering base to anchor high-pressure membrane applications for mining tailings, while Alfa Laval occupies a position emphasizing automated architectures that reduce labor intensity in food processing installations. Among Chinese fabricators, Jingjin Equipment represents the volume-production archetype serving municipal water infrastructure buildouts. Metso and FLSmidth & Co. sit within the mining-specialist segment where tailings dewatering mandates concentrate procurement decisions.
| Leading Market Players |
|---|
| Jingjin Equipment |
| ANDRITZ |
| Metso |
| Evoqua Water Technologies |
| Alfa Laval |
| FLSmidth & Co. |
| Zhongda Bright Filter Press |
| ISHIGAKI |
| Aqseptence Group |
| Others |
Supply Flow & Price Mechanics
Membrane squeeze premium tier divergence from commodity chamber units creates distinct pricing corridors that map directly onto supply chain sourcing strategies. Buyers of high-pressure mining systems absorb 316L and 904L stainless steel cost volatility through long-term service contracts, while municipal water authorities in China's Jiangsu province secure standard chamber presses through volume procurement frameworks that compress supplier margins.
Pricing Analysis
Bundled equipment-as-a-service contracts now capture municipal water treatment demand in California's Central Valley, where drought-driven biosolids hauling cost inflation has shifted preference toward operational expenditure structures. Unbundled capital purchase persists in mining tailings applications where buyers prioritize customization over after-sales support. Price differentiation rests on corrosion-resistant alloy grade and automation tier, with membrane configurations commanding premium positioning against chamber alternatives. Cost compression in standard chamber production is intensifying because Chinese volume manufacturers have expanded Jiangsu and Zhejiang assembly capacity. Municipal utilities exhibit highest price sensitivity due to constrained capital budgets, while lithium extraction operators in Western Australia demonstrate lowest sensitivity given compliance-driven procurement mandates.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale mining buyer demand for membrane systems, while distributor networks serve fragmented municipal water procurement across mid-sized North American utilities. Manufacturing concentration clusters in Germany's Baden-Württemberg region for polypropylene monofilament filter cloth weaving, China's Yangtze River corridor for standard chamber fabrication, and Austria for high-pressure membrane engineering. Raw material dependencies draw from nickel and molybdenum markets for austenitic stainless grades, polypropylene resin for filter media, and specialized elastomer compounds for inflatable diaphragms. Single-source vulnerability in German filter cloth weaving capacity exposes North American OEMs to supply disruption. Distribution runs through regional technical service partnerships that co-locate hydraulic technicians with mining operations in Chile and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market stems from automation tier upgrades displacing labor-intensive manual systems, particularly where EPA and EU enforcement elevates performance requirements above commodity specifications.
For Market Incumbents: Anchor membrane technology leadership through captive supply of corrosion-resistant alloy plate manufacturing, mitigating exposure to nickel price volatility that erodes fabrication margins. Defend against emerging Chinese volume manufacturers by certifying automated self-cleaning architectures under EU Industrial Emissions Directive best available technique standards, creating regulatory switching costs for European chemical complex buyers.
For New Entrants and Emerging Players: Digital-channel aftermarket platforms offer the lowest-friction entry path, enabling predictive maintenance subscription contracts that bypass capital-intensive manufacturing. Indonesia's nickel processing corridor on Obi Island and Halmahera represents the most penetrable geography, where HPAL tailings dewatering demand outstrips local supply capacity. Target equipment-as-a-service contracting models that transfer cloth inventory risk and maintenance responsibility to the vendor, mirroring Veolia and Suez structures in California's Central Valley.
For Investors and Strategic Acquirers: Consolidation pressure builds where filter cloth weaving capacity concentrates in single-region clusters, creating acquisition opportunities for vertical integration into polypropylene monofilament manufacturing. Long-term viability favors vendors with backward integration into alloy plate forging and membrane diaphragm compounding capabilities. The signal to watch is MEE enforcement intensity along China's Yangtze River chemical parks, which would accelerate replacement demand for skid-mounted systems and compress installation timeline advantages to sub-four-week deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filter Cloth Weaving | Captive supply of polypropylene monofilament eliminates Baden-Württemberg single-source vulnerability for membrane press OEMs. |
| Skid-Mounted Containerized System Deployment | Compressed installation timelines from twelve weeks to four weeks capture MEE-driven replacement demand in Shanghai-Ningbo corridor. |
| Equipment-as-a-Service Contracting | Throughput-guaranteed structures transfer cloth inventory risk to vendors and align revenue with California drought-driven biosolids handling inflation. |
| Corrosion-Resistant Alloy Certification | 316L and 904L grade validation opens lithium hydroxide and nickel sulfate recovery applications in Jiangsu province battery metals recycling. |
| Digital Twin Integration Partnership | IoT-enabled predictive maintenance platforms from industrial automation vendors create subscription-based performance contracts for municipal water authorities. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with maintenance directors at Chilean copper operations, plant engineers in Germany's Ruhr region wastewater facilities, OEM procurement teams at mining equipment suppliers, and aftermarket service heads at membrane press distributors. Secondary validation drew from EPA effluent limitation guideline filings, EU Industrial Emissions Directive enforcement documentation, China's MEE discharge standard GB 8978-1996 amendments, customs records for stainless steel plate imports, and ACC process equipment expenditure surveys. Bottom-up installation base enumeration and top-down capital expenditure triangulation anchored market sizing.
Comparable-period historical analysis anchored the projection horizon to documented replacement cycles in municipal water infrastructure and mining tailings compliance-driven upgrades. Segmentation modeling spanned product type tier, end-use industry concentration, operation mode automation level, and application-specific corrosion resistance requirements. CAGRs derived from regression analysis against mineral processing capacity expansion, wastewater treatment capital budget trajectories, and battery metals recycling facility commissioning schedules. Alloy price index volatility and filter cloth weaving capacity utilization served as industry-specific forecast sensitivity inputs.
Regulatory enforcement intensity shifts, stainless steel commodity price spikes, and specialized hydraulic technician availability constraints are the dominant revision risks that could compress or extend projected replacement demand. Forecasts reflect assumptions regarding sustained EPA and EU directive enforcement trajectories, continued Chinese MEE standard tightening, and stable nickel-molybdenum alloy supply conditions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
ePTFE Filter Film Market
Filters
String Wound Filter Materials Market
Filters
Residential Filters Market
Filters
North America Gas Filtration Media Market
Filters
Respirator Cartridges and Filters Market
Filters
Global Laboratory Filtration Market
Filters
Fabric Filters Market
Filters
Global Filter Market
Filters
Anti-Microbial Filter Market
Filters
Fabric Filter System Market
Filters
Melt-Blown Polypropylene Filters Market
Filters
Filtration and Separation Market
Filters
Zeolite Adsorbents Market
Filters
Homopolymer Acrylic Filter Bags Market
Filters
Global Tangential Flow Filtration Market
Filters
GCC Industrial Air Filtration Market