
 Compact Filters Market | 2026-2036
Compact Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Compact Filters Market Insights
Multi-source procurement for filter media and pleated elements is restructuring supply relationships across the compact filters industry. Donaldson Company leverages its captive manufacturing network to sustain cost discipline in heavy-duty industrial applications. Camfil anchors European demand through specialized cleanroom and healthcare filtration systems. Bosch Rexroth competes by integrating hydraulic and pneumatic filter lines into automated manufacturing platforms.
Compact filters are enclosed, replaceable filtration units engineered to remove particulates, aerosols, or gaseous contaminants from air and fluid streams, typically rated between MERV 8 and HEPA H14 efficiency depending on pleat density and media composition. These devices serve critical roles in protecting equipment, ensuring occupational safety, and maintaining controlled environments across manufacturing, transportation, and building infrastructure. HEPA and activated carbon product types command premium positioning where healthcare and semiconductor cleanrooms require certified performance guarantees. HVAC systems and industrial processes applications generate volume scale, while nanofiber and membrane technologies capture margin pools through extended service intervals and reduced pressure-drop energy penalties.
The EPA enforces National Ambient Air Quality Standards that mandate filtration upgrades in commercial and industrial buildings, directly expanding replacement demand for compact filter assemblies. ISO 16890 and EN 1822 testing protocols classify fine particulate removal efficiency, creating compliance barriers for uncertified imports and rewarding manufacturers with accredited laboratory networks. Stakeholders must monitor evolving MEE air quality directives in China and tightening F-Gas Regulation requirements in Europe, as these frameworks will determine which media technologies and product form factors secure market access in the highest-volume geographies.
Market Dynamics
EPA Clean Air Act amendments and ISO 16890 standard upgrades are forcing simultaneous media composition changes and testing protocol overhauls across the compact filters supply base.
Growth Catalysts
- Healthcare Infection Control Mandates:HEPA-grade compact filters are becoming standard equipment in surgical suites and isolation wards as Joint Commission accreditation requirements tighten across US hospital systems.
- REACH and F-Gas Regulation:European frameworks are accelerating phase-out of synthetic media containing persistent organic pollutants, creating replacement demand for bio-based and glass fiber alternatives.
- Automotive Precision Manufacturing:Stuttgart and Munich industrial clusters are procuring premium compact filters for paint booths and clean assembly environments to meet OEM contamination specifications.
Market Restraints
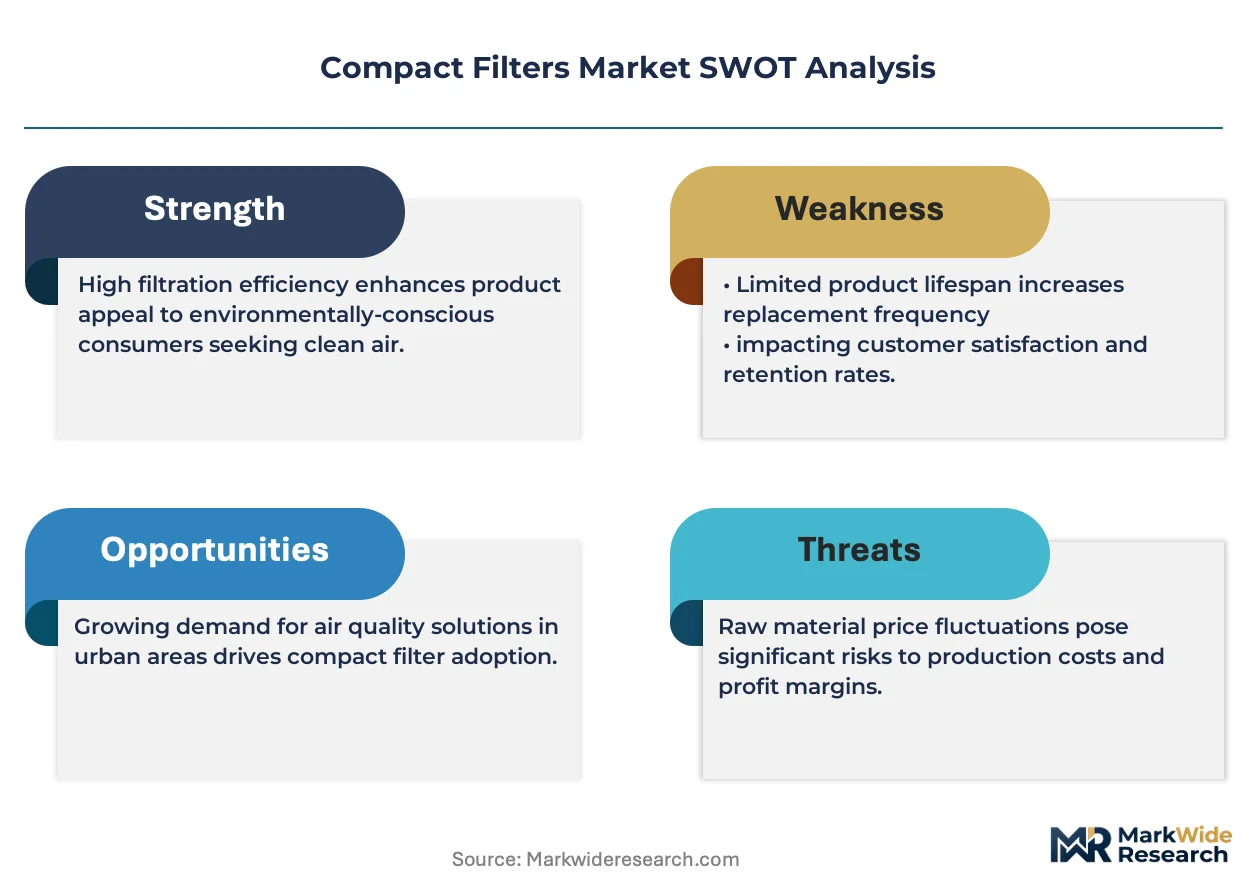
- Glass Fiber Supply Concentration:High-efficiency media production concentrates among a limited set of European and Japanese suppliers, exposing filter assemblers to input volatility.
- Technical Performance Ceiling:Conventional pleated designs face physical limits in pressure-drop optimization that nanofiber overlays are only partially addressing.
- MEE Air Quality Directive Compliance Costs:China's Ministry of Ecology and Environment is imposing testing and certification burdens that raise barriers for uncertified import sources.
Strategic Opportunities
- Semiconductor Fabrication Expansion:Cleanroom-grade compact filters are capturing margin pools as Taiwan, South Korea, and Arizona fab construction accelerates.
- Activated Carbon Convergence:Hybrid designs combining particulate and gas-phase removal are opening specification slots in pharmaceutical and chemical processing applications.
- Direct OEM Channel Development:Filter manufacturers are bypassing traditional distribution to embed replacement schedules into HVAC and compressor OEM service platforms.
Industry Challenges
- ISO 16890 Laboratory Accreditation Backlogs:Testing capacity constraints are extending product certification timelines and delaying market entry for new media formulations.
- Legacy System Integration Complexity:Retrofitting compact filter housings into existing HVAC infrastructure requires custom engineering that fragments order economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compact Filters Market |
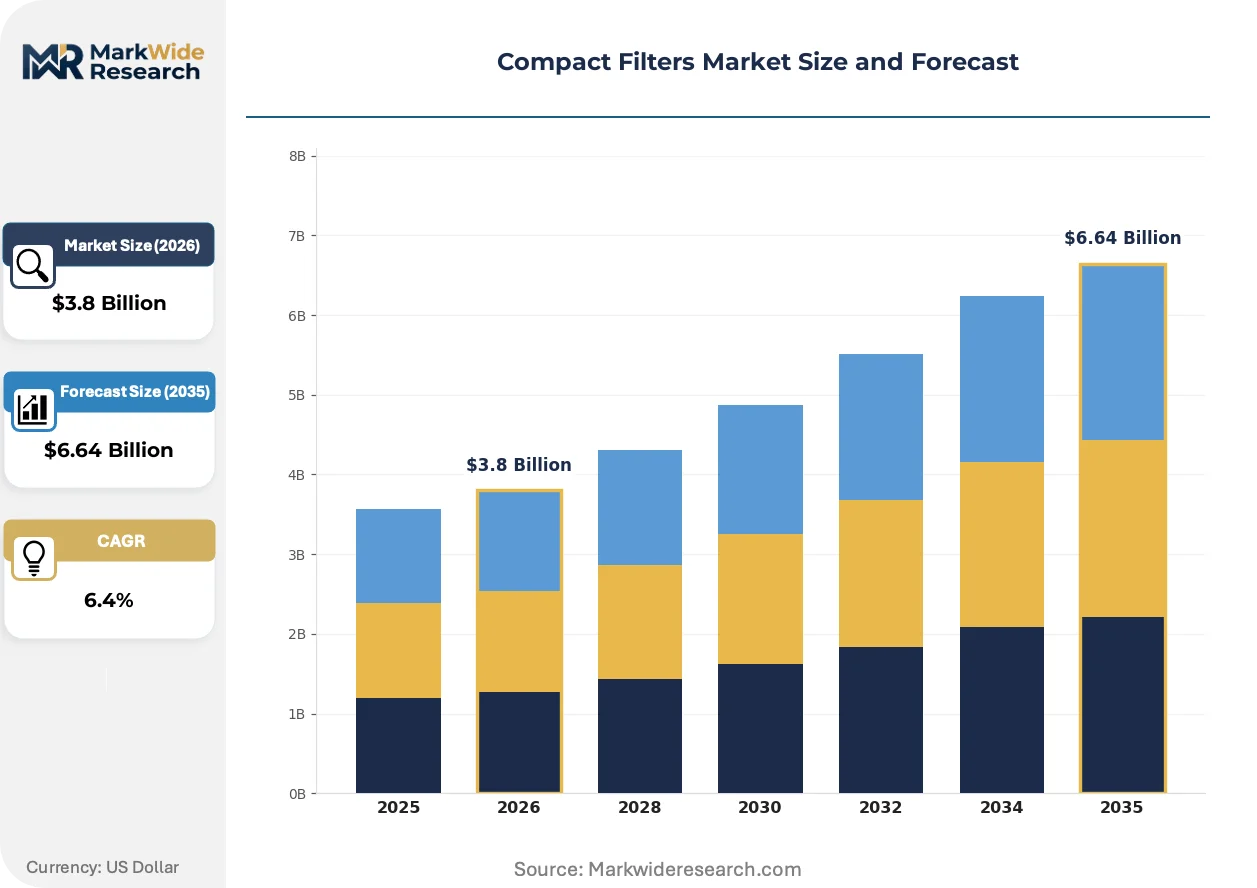
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
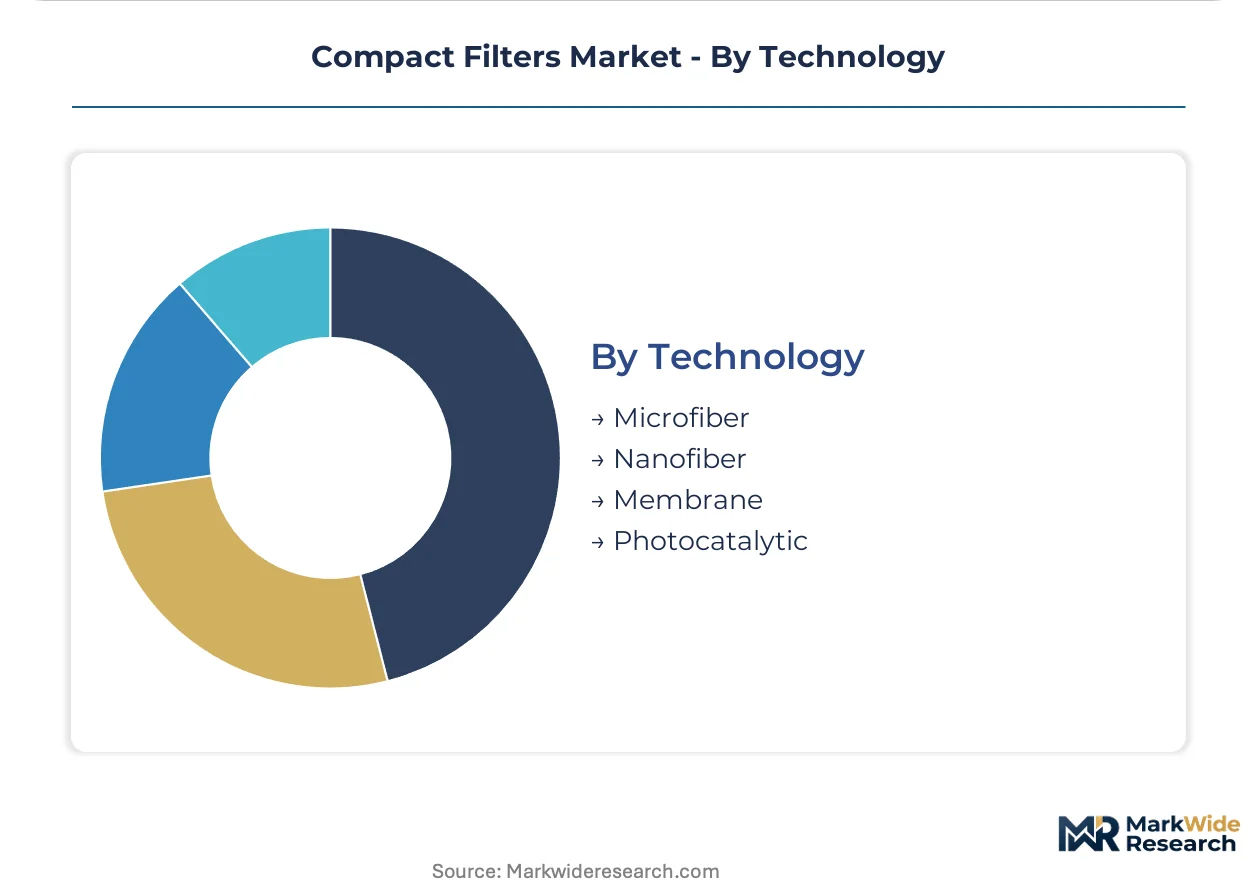
| Segmentation | Product Type: HEPA, Activated Carbon, Electrostatic, Ceramic Application: Air Purification, Water Treatment, Industrial Processes, HVAC Systems End User: Residential, Commercial, Automotive, Healthcare Technology: Microfiber, Nanofiber, Membrane, Photocatalytic |
| Companies Covered | Donaldson Company, Inc., Camfil, Parker Hannifin Corporation, Pall Corporation, Eaton Corporation, Bosch Rexroth, Shandong Xunmiao Purification Equipment Co., Ltd, Freudenberg Filtration Technologies, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compact Filters Market Trends and Innovations
Filter media chemistry and pleating automation are converging to extend service intervals while meeting stricter efficiency certifications. Three developments are restructuring product positioning and procurement patterns.
Nanofiber surface loading technology is electrifying the competitive landscape for mid-efficiency applications. Synthetic nanofiber layers applied to conventional substrates enable MERV 13+ performance with pressure-drop profiles previously associated with lower-grade media. Data center operators and commercial building managers are specifying these configurations to reduce fan energy consumption. The technology is electrifying substitution dynamics by compressing the performance gap between standard and premium product tiers.
EPA enforcement of National Ambient Air Quality Standards is tightening filtration upgrade timelines for commercial and industrial buildings. Non-attainment designations are triggering mandatory equipment retrofits that expand replacement demand for compact filter assemblies. The industrial processing segment faces the most acute compliance pressure, with facilities in California and Texas metropolitan areas accelerating specification reviews.
Service-contract bundling is restructuring buyer-supplier relationships in the HVAC aftermarket. Facility management firms are consolidating filter procurement into multi-year performance agreements that specify pressure-drop thresholds and replacement intervals rather than unit pricing. This model is most visible in US healthcare and education verticals where capital budgeting constraints favor operational expenditure structures.
Compact Filters Market Segmentation
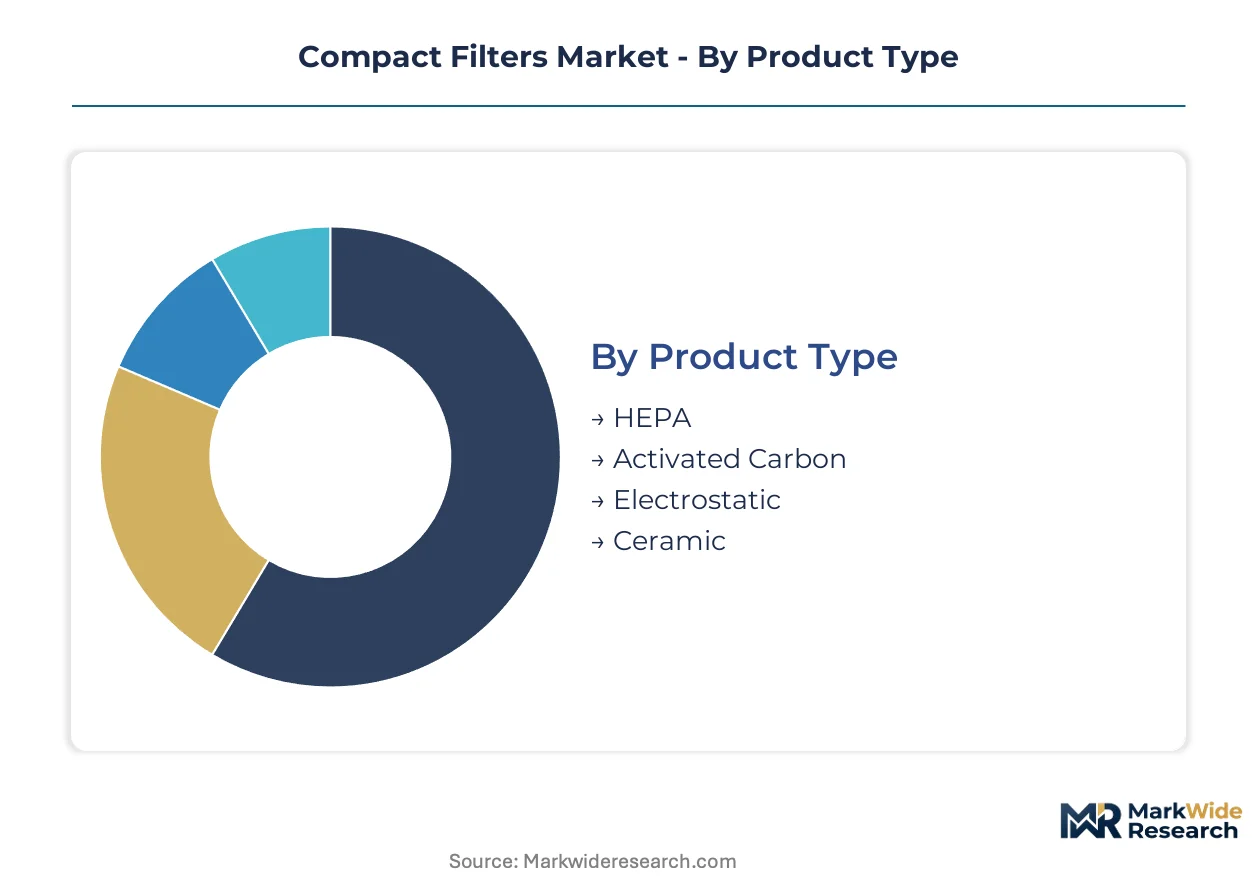
Compact filter procurement patterns diverge sharply across product grades and installation contexts. Replacement cycles, efficiency certifications, and regulatory compliance burdens create distinct margin profiles that reward technology-specific positioning strategies.
Product Type:
Upgrade trajectories vary by media chemistry and pleat density, with certification requirements driving differential replacement frequencies across installed bases.
- HEPA:Glass fiber or PTFE membrane media rated H13-H14 capture 0.3 micron particles at 99.97% efficiency. Demand concentrates in German healthcare construction and US hospital Joint Commission compliance retrofits where certification documentation is mandatory.
- Activated Carbon:Impregnated carbon pellets or bonded fiber matrices adsorb VOCs and gaseous contaminants. German automotive paint booths in Stuttgart industrial clusters specify these for OEM contamination protocols, creating premium specification slots.
- Electrostatic:Charged synthetic media attracts particles through electrostatic attraction rather than mechanical interception. Commercial building operators in US non-attainment zones favor washable configurations for cost containment.
- Ceramic:Sintered aluminum oxide or silicon carbide structures withstand extreme temperatures in metal processing and kiln applications. Industrial facilities in China's manufacturing belts specify these for thermal durability.
Volume placements concentrate in HEPA for healthcare compliance; the faster expansion belongs to activated carbon as hybrid gas-phase designs penetrate pharmaceutical processing.
Application:
Cost tier stratification separates commodity replacement demand from engineered system integrations requiring custom housing designs.
- Air Purification:Standalone residential and commercial units deploy pleated cartridges or panel filters in portable configurations. China's MEE air quality directives are expanding replacement demand in Beijing and Shanghai metropolitan installations.
- Water Treatment:Membrane and depth filters remove suspended solids and microbiological contaminants from process and potable streams. US municipal infrastructure upgrades under EPA Safe Drinking Water Act amendments are accelerating specification reviews.
- Industrial Processes:Protective filtration for compressors, hydraulic systems, and pneumatic equipment extends machinery service intervals. German precision manufacturing clusters around Munich prioritize contamination control for CNC equipment protection.
- HVAC Systems:Building air handling units integrate pleated or bag filters rated MERV 8-16 depending on occupancy codes. US commercial real estate in California and Texas non-attainment areas faces mandatory filtration upgrade timelines.
Revenue concentration sits with HVAC replacement cycles; industrial process applications are climbing the fastest as predictive maintenance contracts bundle filter procurement.
End User:
Customer type determines procurement modality, with institutional buyers favoring multi-year performance contracts against residential spot purchasing.
- Residential:Consumer-grade purifiers and HVAC retrofits utilize standardized panel and cartridge formats. US big-box retail channels dominate volume distribution with private-label alternatives pressuring branded pricing.
- Commercial:Facility management firms consolidate filter procurement across property portfolios through service agreements. US healthcare and education verticals are shifting toward operational expenditure structures with defined pressure-drop thresholds.
- Automotive:OEM specifications for cabin air and powertrain protection drive qualification requirements. German manufacturers in Stuttgart and Munich industrial clusters enforce contamination limits that cascade through supplier tiers.
- Healthcare:Surgical suites, isolation wards, and clean corridors require HEPA-grade performance with documented certification. US Joint Commission accreditation requirements are tightening specification standards across hospital systems.
Commercial placements generate the steadiest replacement revenue; healthcare represents the fastest-growing trajectory as infection control mandates expand HEPA deployment.
Technology:
Supply concentration in specialized media production creates tiered access barriers that fragment competitive positioning across efficiency grades.
- Microfiber:Melt-blown synthetic webs achieve MERV 11-13 efficiency through mechanical depth filtration. Volume production concentrates in Asian manufacturing bases serving standardized HVAC replacement demand.
- Nanofiber:Surface-loaded electrospun layers deliver MERV 13+ performance with reduced pressure-drop penalties. US data center operators are specifying these configurations to compress fan energy consumption.
- Membrane:Track-etched or phase-inversion polymers provide absolute filtration for sterile process applications. Pharmaceutical manufacturers in Switzerland and Ireland prioritize these for aseptic manufacturing compliance.
- Photocatalytic:Titanium dioxide coatings generate reactive oxygen species under UV activation for VOC degradation. Japanese building automation integrators are embedding these into smart HVAC platforms for indoor air quality management.
Microfiber dominates unit volume through cost positioning; nanofiber is gaining share fastest as energy efficiency specifications tighten in commercial building codes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glass fiber feedstock availability in Germany's Rhineland-Palatinate region anchors European compact filter manufacturing. Stuttgart and Munich industrial clusters drive premium specification demand for automotive and precision manufacturing applications.
United States
Healthcare construction and EPA non-attainment designations propel HEPA-grade filter demand. The EPA enforces National Ambient Air Quality Standards that mandate filtration upgrades in California and Texas metropolitan facilities. Boston and New York hospital systems accelerate Joint Commission compliance retrofits.
Germany
Automotive OEM contamination protocols and REACH chemical regulations shape procurement patterns. The F-Gas Regulation accelerates synthetic media phase-out for bio-based alternatives. Stuttgart's paint booth suppliers and Munich's CNC equipment manufacturers enforce cascading supplier tier requirements.
China
MEE air quality directives expand replacement demand in Beijing and Shanghai metropolitan installations. The Ministry of Ecology and Environment imposes testing and certification burdens that raise barriers for uncertified import sources. Yangtze River Delta manufacturing belts specify ceramic filters for thermal durability in metal processing.
Japan
Building automation integrators embed photocatalytic filtration into smart HVAC platforms. METI standards guide indoor air quality management specifications. Tokyo and Osaka metropolitan commercial real estate operators favor energy-efficient nanofiber configurations.
South Korea
Semiconductor fabrication expansion in Seoul Capital Area and Busan-Ulsan clusters drives cleanroom-grade filter procurement. MFDS pharmaceutical manufacturing standards reinforce aseptic process requirements. Domestic foundry construction accelerates specification reviews for absolute filtration membranes.
Compact Filters Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers secure media supply and certification access. The vendor base stratifies across three tiers: diversified industrial conglomerates with captive filtration divisions, specialized cleanroom and healthcare-focused specialists, and regional fabricators serving standardized HVAC replacement demand. Two competitive moves structure positioning: M&A activity consolidates testing laboratory networks, while backward integration into nanofiber media production captures margin pools from energy-efficient product tiers.
Within the diversified industrial tier, Donaldson Company, Inc. and Parker Hannifin Corporation exemplify scale-driven positioning through extensive manufacturing footprints. Camfil occupies a specialist position anchored in European cleanroom and healthcare filtration systems. Among Asia-Pacific fabricators, Shandong Xunmiao Purification Equipment Co., Ltd represents regional production capacity serving standardized demand segments.
| Leading Market Players |
|---|
| Donaldson Company, Inc. |
| Camfil |
| Parker Hannifin Corporation |
| Pall Corporation |
| Eaton Corporation |
| Bosch Rexroth |
| Shandong Xunmiao Purification Equipment Co., Ltd |
| Freudenberg Filtration Technologies |
| 3M Company |
| Others |
Pricing and Supply Chain Analysis
Automotive OEM procurement clusters in Stuttgart and Munich anchor contract-based pricing with multi-year performance guarantees replacing spot purchasing. HEPA-grade healthcare buyers absorb premium positioning through Joint Commission compliance mandates, while HVAC facility managers negotiate pressure-drop thresholds over unit costs.
Pricing Analysis
Warranty and service-bundling separates installed-base contracts from unbundled transactional sales. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 16890 certification grade and pleat density. Cost compression in mid-efficiency tiers is intensifying because nanofiber overlays compress performance gaps. Residential spot buyers exhibit highest price sensitivity; semiconductor cleanroom operators show lowest.
Supply Chain Analysis
ISO 16890 laboratory accreditation functions as supply gating, fragmenting qualified supplier pools. Glass fiber media production concentrates in Germany and Japan; pleated element assembly spreads across China and Mexico. Feedstock dependencies include borosilicate microfiber, synthetic melt-blown substrates, and activated carbon pellets. Single-source vulnerability runs through European high-efficiency media suppliers. Distribution runs through HVAC OEM service platforms and industrial distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards backward integration into nanofiber media production as the decisive upstream lever. Captive supply of electrospun layers captures margin pools from energy-efficient product tiers while insulating against glass fiber feedstock volatility.
For Market Incumbents: Deepen certification laboratory networks to accelerate ISO 16890 testing throughput and lock out uncertified imports. Expand captive nanofiber production capacity to defend against substitute technology displacement from membrane filtration. Prioritize direct OEM channel embedding over distributor relationships to capture replacement schedule visibility.
For New Entrants and Emerging Players: Enter via photocatalytic hybrid designs for Japanese building automation integrators seeking smart HVAC platform differentiation. Target US data center operators specifying nanofiber configurations for fan energy reduction. Pursue white-label supply agreements with regional HVAC OEMs lacking in-house filtration engineering.
For Investors and Strategic Acquirers: The window for entry favors nanofiber media specialists with accredited testing partnerships over commodity pleated element fabricators. Long-term viability hinges on regulatory certification moats rather than scale economics. Watch MEE enforcement intensity in China as inflection indicator for import substitution opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nanofiber Media | Captures margin pools from MERV 13+ energy-efficient configurations specified by US data centers. |
| ISO 16890 Laboratory Accreditation Expansion | Accelerates product certification timelines and creates compliance barriers for uncertified Asian imports. |
| Direct OEM Channel Development | Embeds replacement schedules into HVAC and compressor service platforms, displacing distributor intermediaries. |
| Hybrid Activated Carbon Convergence | Opens specification slots in German automotive paint booths and pharmaceutical gas-phase removal applications. |
| Photocatalytic Technology Licensing | Enables Japanese building automation integrators to embed VOC degradation into smart HVAC platforms. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with HVAC OEM procurement directors, facility management firm operations heads, filter media R&D leads, and cleanroom certification specialists validated demand assumptions. EPA enforcement databases, ISO 16890 laboratory accreditation registries, and MEE air quality directive filings supplied regulatory trajectory inputs. Bottom-up installation base modeling and top-down industrial output indices were triangulated against filter replacement cycle assumptions.
Segment-level granularity modeled efficiency grades, media chemistry types, application contexts, and end-user procurement modalities across the projection horizon. CAGRs derived from replacement cycle velocity, regulatory upgrade timelines, and technology substitution elasticities. Forecast inputs included semiconductor fab construction pipelines, German automotive production forecasts, and US hospital construction permitting data.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt MEE enforcement escalations or glass fiber supply disruptions. Forecasts reflect documented assumptions regarding ISO 16890 adoption curves and nanofiber cost-down trajectories. A model refresh is warranted upon material change in EPA non-attainment designation timelines or REACH synthetic media phase-out schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Filters
Single-Use Filtration Assemblies Market
Filters
Coolant Filtration Skids Market
Filters
Filters and Particle Monitoring Market
Filters
Fabric Filter System Market
Filters
Zeolite Adsorbents Market
Filters
Liquid Filter Bags Market
Filters
Filtration and Separation Market
Filters
Global High Temperature Filters Market
Filters
High-Efficiency Particulate Air (HEPA) Filters Market
Filters
Diatomaceous Filter Aid Market
Filters
Fabric Filters Market
Filters
Canada Filtration and Separation Market
Filters
Global Sterile Filtration Market
Filters
Respirator Cartridges and Filters Market
Filters
Industrial Filtration Market
Filters
Activated Carbon Market