
 Cold Laser Therapy Market | 2026-2036
Cold Laser Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Laser Therapy Market Intelligence
Customer concentration in the cold laser therapy market is shifting from specialized pain management practices towards a more fragmented base of physiotherapy clinics and sports medicine centers. This diversification of the end-user landscape creates new opportunities for device manufacturers. Erchonia Corporation specializes in low-level laser technology, securing numerous FDA market clearances. THOR Photomedicine Ltd leverages its deep research in photobiomodulation to serve elite sports teams. Meanwhile, LiteCure focuses on high-power laser therapy devices for both human and veterinary applications.
Cold laser therapy, also known as low-level laser therapy (LLLT), is a non-invasive treatment that utilizes specific wavelengths of light, typically between 600 and 1000 nanometers, to stimulate healing. The light energy is absorbed by photoreceptors in the cells, triggering a cascade of biological reactions that reduce pain and inflammation without generating heat. Handheld devices represent the largest product segment by volume, favored by smaller physiotherapy clinics for their portability and lower cost. Demand from sports medicine facilities and rehabilitation centers for stationary units is growing, driven by the need for treating musculoskeletal disorders and chronic pain.
The regulatory environment for cold laser devices is stringent, directly shaping market access and product design. In the United States, the FDA classifies these products, often as Class II medical devices, requiring premarket notification. Similarly, in Europe, manufacturers must comply with the CE marking requirements under the Medical Device Regulation (MDR). The path to broader adoption hinges on the expansion of reimbursement coverage and the continued accumulation of clinical evidence supporting efficacy across various therapy areas.
Market Dynamics
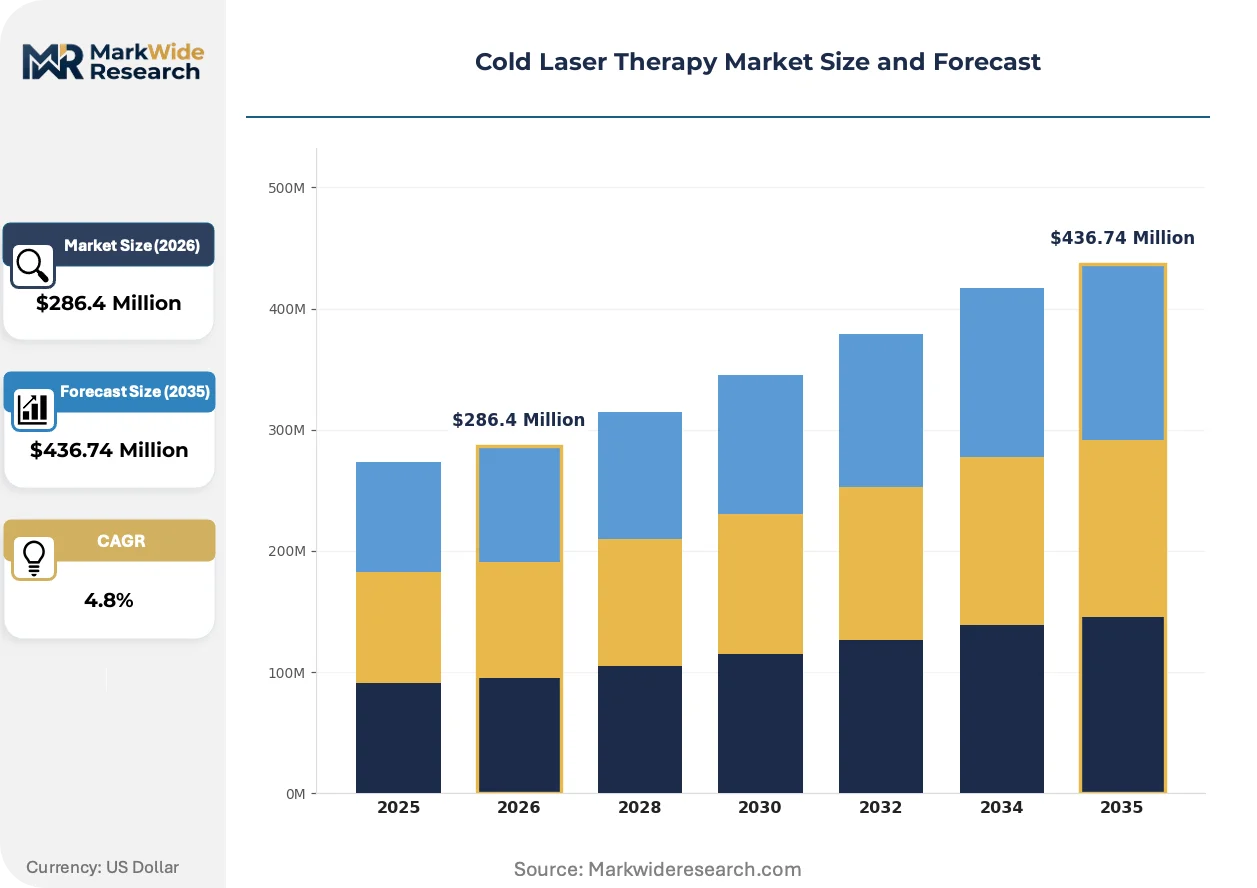
The central force shaping the cold laser therapy market is the fragmentation of its end-user base. Demand is decentralizing from specialized pain management centers to a broader, more distributed network of physiotherapy clinics and sports medicine facilities, creating new channel dynamics.
Growth Catalysts
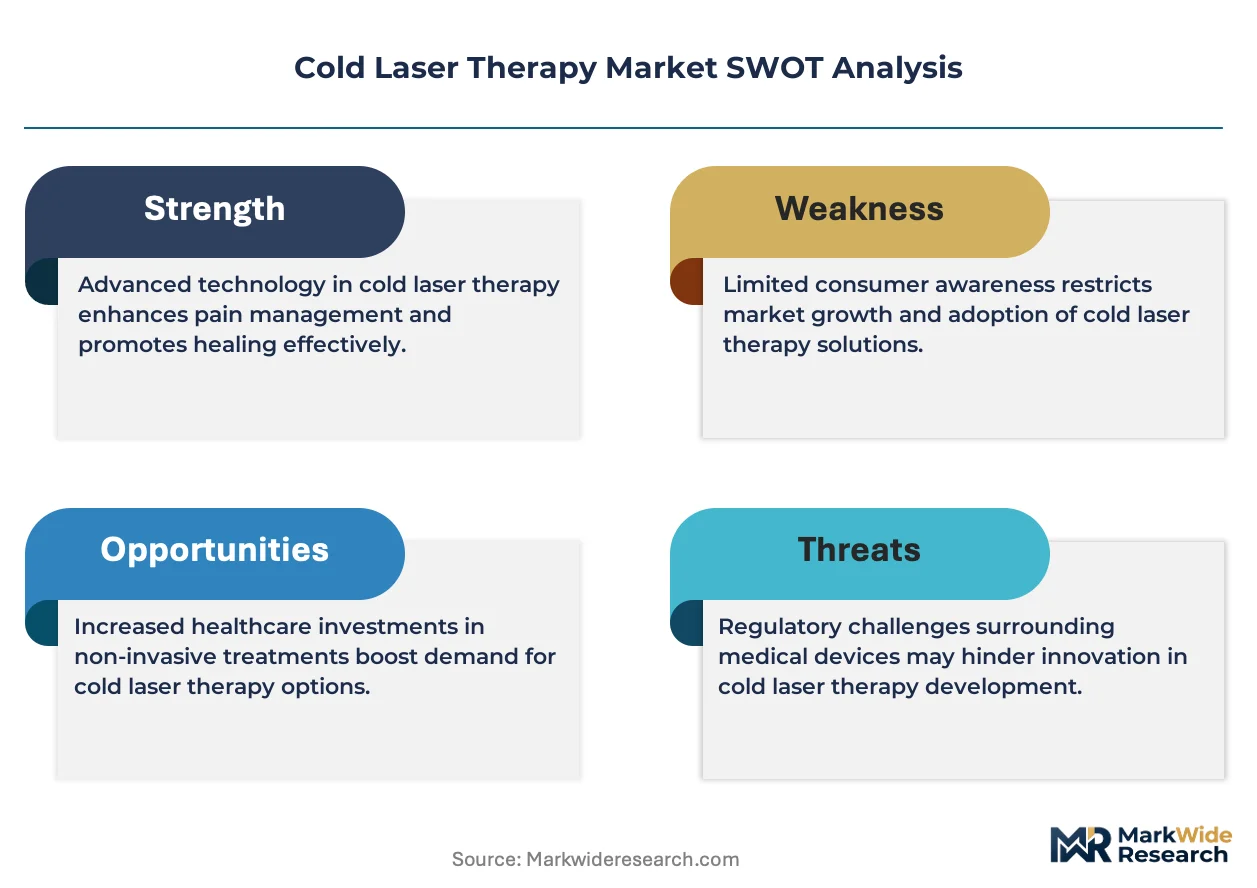
- Favorable Regulatory Pathways:Regulatory approvals, including FDA clearance for specific indications in the United States and CE marking in Europe, validate product safety and efficacy, facilitating market entry and building practitioner confidence.
- Sports Medicine Adoption:Demand from sports medicine centers is a significant catalyst, driven by the need for non-invasive, drug-free treatments to accelerate athlete recovery from musculoskeletal injuries and reduce downtime.
- Established Healthcare Infrastructure:The United States, with its high participation in sports and well-funded healthcare system, provides a concentrated source of demand and a template for clinical application development.
Market Restraints
- Limited Reimbursement Coverage:Inconsistent or absent reimbursement policies from public and private payers in many countries remains a primary structural barrier, limiting patient access and discouraging investment by smaller clinics.
- Substitution by High-Power Lasers:The availability of high-power laser therapy devices, which offer different therapeutic effects and treatment times, presents a substitution threat for certain applications and clinical preferences.
- Clinical Evidence Gaps:While evidence for some conditions is strong, a perceived lack of large-scale, standardized clinical trials for other potential applications can slow adoption by more conservative medical practitioners.
Strategic Opportunities
- Veterinary Medicine Expansion:The application of cold laser therapy for animals, particularly in equine and companion animal care for pain and inflammation, represents a significant and underpenetrated commercial opportunity.
- Home-Use Device Development:Creating simplified, safe, and FDA-cleared or CE-marked devices for patient self-administration at home could open a new direct-to-consumer market for managing chronic pain conditions.
- Integration with Telehealth:Combining portable devices with telehealth platforms allows for remote monitoring and guidance of treatment protocols, expanding access for patients in rural or underserved areas.
Industry Challenges
- Protocol Standardization:A lack of universally accepted treatment protocols for specific conditions creates inconsistencies in clinical outcomes, challenging the ability of manufacturers to demonstrate uniform efficacy and train practitioners effectively.
- Navigating MDR Compliance:For manufacturers targeting the European market, the transition to the more stringent Medical Device Regulation (MDR) requires substantial investment in clinical data generation and quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Laser Therapy Market |
| Market Size in 2026 | $286.4 Million |
| Market Size in 2035 | $436.74 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Stationary Units, Portable Systems, Integrated Laser Modules Therapy Area: Musculoskeletal Disorders, Neurological Conditions, Dermatological Treatments, Chronic Pain Management End User: Physiotherapy Clinics, Rehabilitation Centers, Sports Medicine Facilities, Pain Management Practices Distribution Channel: Direct Sales, Online Retailers, Medical Equipment Distributors, Specialty Stores |
| Companies Covered | Theralase Inc., Multi Radiance Medical, Erchonia Corporation, Apira Science Inc, THOR Photomedicine Ltd, Zimmer MedizinSysteme GmbH, DJO Global, Inc., LiteCure, BTL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Laser Therapy Market Strategic Shifts & Innovations
The market is being reshaped by the miniaturization of laser technology and the development of more sophisticated software. This trend is democratizing access, moving devices from dedicated hospital departments into the hands of a wider range of independent practitioners.
Advanced solid-state diode technology enables the core function of producing specific, stable wavelengths of light in a compact form. Smaller physiotherapy clinics and sports therapists are rapidly adopting these new handheld units due to their portability and lower capital cost. This technological shift is electrifying the practitioner segment, allowing for the delivery of therapy in diverse settings beyond traditional clinical walls.
Europe's Medical Device Regulation (MDR) has intensified scrutiny on all medical devices, including cold laser therapy units. This regulation demands a higher level of clinical evidence for efficacy and a more rigorous system for post-market surveillance than its predecessor. Manufacturers of devices classified under the MDR, often as Class IIa or IIb, are most affected, needing to update technical files and potentially conduct new studies to maintain their CE marking.
A notable behavioral shift involves clinics moving away from outright capital purchases toward more flexible acquisition models. This disrupts the traditional direct sales channel, as equipment leasing programs and subscription-based services gain traction, particularly among new or smaller practices. This pattern is most visible in the competitive private clinic markets of the United States and Canada, where managing upfront costs is a critical operational priority.
Cold Laser Therapy Market Segmentation
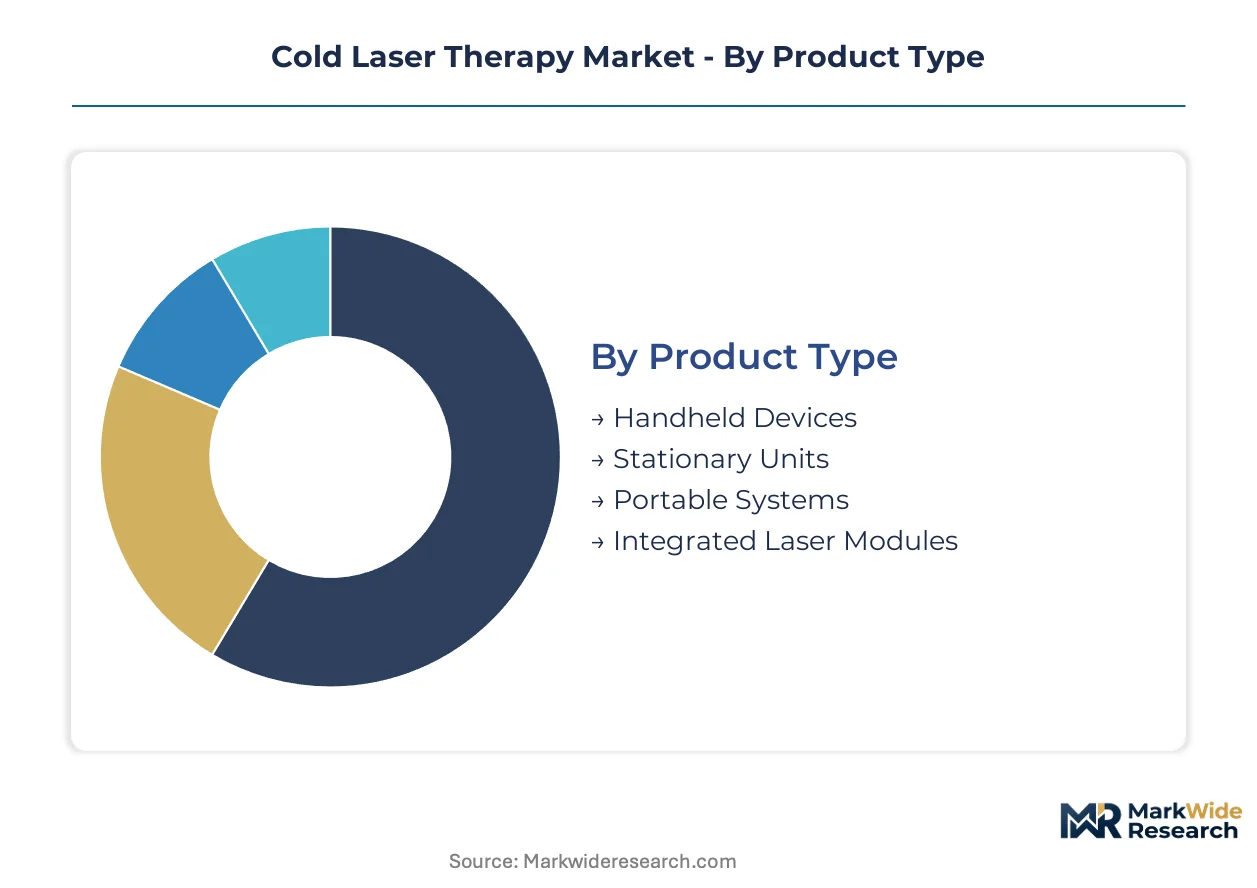
The Cold Laser Therapy Market categorizes therapeutic devices and applications to understand diverse user needs and operational models. This segmentation highlights the distinct technological requirements and clinical settings driving demand for low-level laser technology. Analyzing these segments clarifies where device innovation and market penetration are most impactful.
Product Type:
The product type spectrum ranges from highly standardized, mass-produced handheld units to more customized, complex integrated laser modules. Manufacturers balance cost-effectiveness with specialized functionality across these device categories. This differentiation allows for tailored solutions catering to various clinical environments and treatment protocols.
- Handheld Devices:These compact, battery-operated units typically offer single or multiple laser diodes, emitting specific wavelengths between 600 and 1000 nanometers. Demand concentrates in smaller physiotherapy clinics and home-use settings due to their portability and lower capital investment requirements.
- Stationary Units:Larger, more powerful systems often feature multiple applicators and advanced control interfaces, designed for continuous operation in clinical environments. Rehabilitation centers and sports medicine facilities drive demand for these units, focusing on treating extensive musculoskeletal disorders and chronic pain.
- Portable Systems:These devices offer a balance between the power of stationary units and the flexibility of handheld models, often used for mobile practitioners or larger clinics requiring versatility.
- Integrated Laser Modules:These are core laser components designed for incorporation into larger medical systems or custom-built therapeutic platforms, offering specialized wavelength delivery for specific research or advanced clinical applications.
Most installed capacity flows through Handheld Devices. Expansion is steepest in Stationary Units.
Therapy Area:
Therapeutic applications for cold laser technology span various medical disciplines, addressing distinct patient needs and physiological responses. Each area requires specific wavelength protocols and treatment durations to optimize therapeutic outcomes. The efficacy in these areas drives adoption among specialized medical practitioners.
- Musculoskeletal Disorders:This segment involves treating conditions such as sprains, strains, tendonitis, and arthritis, utilizing laser therapy to reduce inflammation and accelerate tissue repair. Sports medicine facilities and rehabilitation centers primarily focus on this application, aiding athlete recovery and general patient mobility.
- Chronic Pain Management:Cold laser therapy offers a non-pharmacological approach to alleviate persistent pain associated with conditions like fibromyalgia, neuropathy, and lower back pain. Pain management practices and physiotherapy clinics increasingly integrate these devices to improve patient quality of life.
- Neurological Conditions:Applications in this area explore neuroprotective effects and nerve regeneration, targeting conditions such as carpal tunnel syndrome and certain neuropathies.
- Dermatological Treatments:This segment includes the use of cold laser for wound healing, scar reduction, and certain skin inflammatory conditions, leveraging its regenerative and anti-inflammatory properties.
Demand for cold laser therapy is highest in musculoskeletal applications. The fastest growth trajectory is observed in chronic pain management.
End User:
The end-user landscape for cold laser therapy devices reflects diverse operational models and patient demographics. Each facility type integrates low-level laser technology based on its specific clinical focus and patient flow. Understanding these user profiles is crucial for manufacturers in developing targeted distribution and support strategies.
- Physiotherapy Clinics:These clinics represent a fragmented but growing base, utilizing cold laser therapy for a broad range of patient rehabilitation and pain relief. Their demand for portable and cost-effective handheld devices is significant, supporting localized treatment for diverse conditions.
- Sports Medicine Facilities:Elite sports teams and athletic training centers are prominent users, deploying cold laser therapy to accelerate injury recovery and reduce athlete downtime. These facilities often invest in more powerful stationary units to treat musculoskeletal injuries efficiently.
- Rehabilitation Centers:These centers integrate cold laser therapy into comprehensive recovery programs for post-surgical patients or individuals with long-term physical impairments.
- Pain Management Practices:Specialized practices focus on chronic pain conditions, employing cold laser as a non-invasive adjunct to other therapies, seeking to reduce reliance on pharmaceuticals.
Physiotherapy clinics represent the largest volume of end-users. Adoption is accelerating most rapidly within sports medicine facilities.
Distribution Channel:
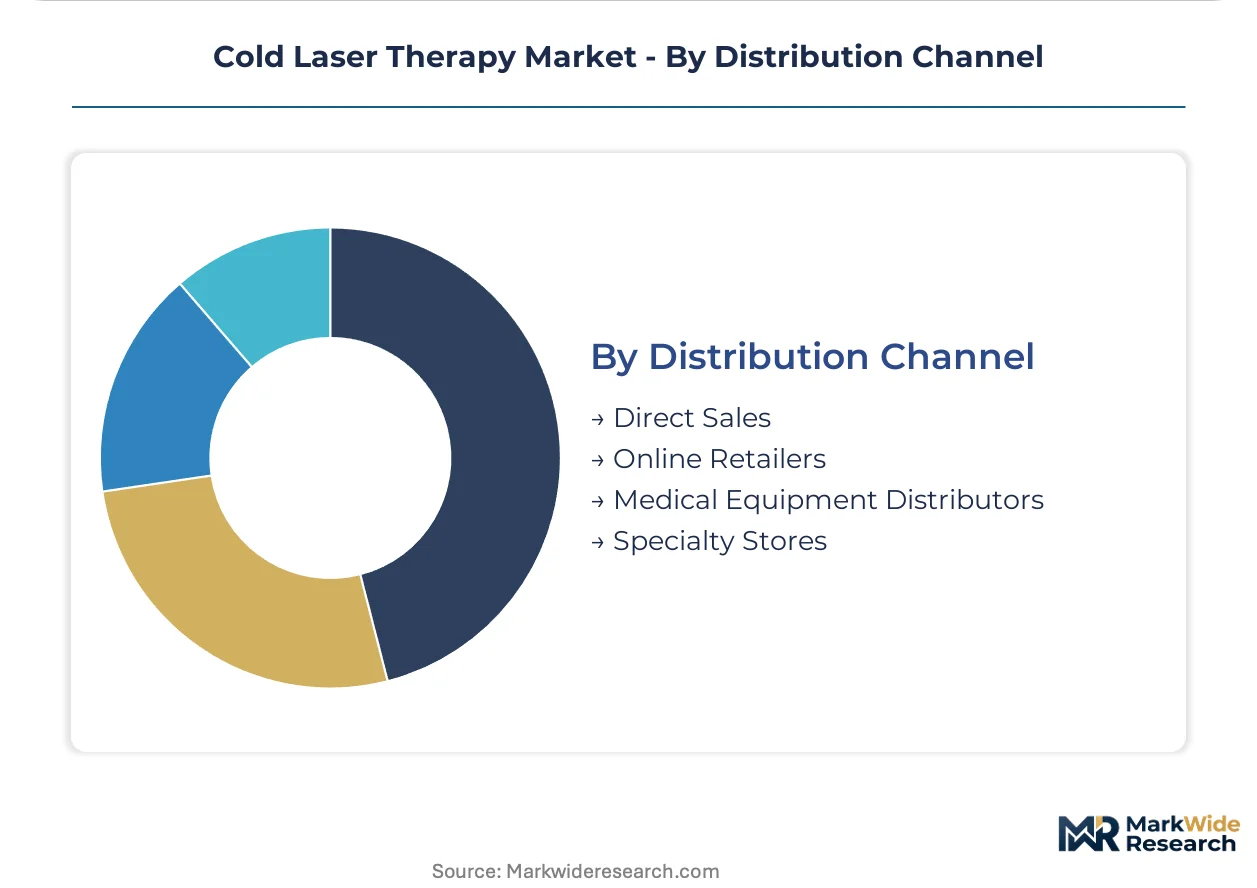
The distribution channels for cold laser therapy devices influence market access and product visibility. Manufacturers navigate a mix of direct engagement and intermediary partnerships to reach diverse end-users. The choice of channel often reflects the complexity of the device and the target customer's purchasing preferences.
- Direct Sales:Manufacturers engage directly with large hospitals, sports organizations, and established clinics, often providing comprehensive training and support packages. This channel allows for direct feedback and stronger customer relationships, particularly for high-value stationary units.
- Medical Equipment Distributors:These intermediaries provide broader market reach, particularly to smaller clinics and independent practitioners, handling logistics, local support, and sales across various regions. Distributors are crucial for penetrating fragmented end-user bases like physiotherapy clinics.
- Online Retailers:E-commerce platforms facilitate the sale of simpler, often handheld or portable devices, catering to individual practitioners and, increasingly, the emerging home-use market.
- Specialty Stores:These outlets, sometimes focused on rehabilitation or sports recovery products, offer a curated selection of cold laser devices alongside complementary therapeutic equipment.
Direct sales remain a primary channel for high-value units. Medical equipment distributors are expanding their reach across the market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A concentrated pool of skilled medical professionals and researchers anchors the cold laser therapy market across key global regions. These specialists drive both the demand for advanced devices and the development of new therapeutic protocols. Regulatory frameworks significantly influence market access and adoption rates in these diverse healthcare landscapes.
United States
The United States healthcare system, with its extensive sports medicine network, generates significant demand for cold laser therapy. FDA clearance for specific indications validates product safety and efficacy, building practitioner confidence. Major metropolitan areas like Boston and Los Angeles, home to numerous professional sports teams, represent key adoption clusters for advanced rehabilitation technologies.
Germany
Germany's robust medical technology sector supports a strong market for cold laser therapy, driven by advanced rehabilitation practices. Compliance with CE marking requirements under the Medical Device Regulation (MDR) is essential for market entry and product validation. Research institutions in cities such as Munich and Heidelberg contribute to clinical evidence and technological advancements.
United Kingdom
United Kingdom healthcare providers increasingly integrate cold laser therapy into physiotherapy and sports injury recovery programs. The Medicines and Healthcare products Regulatory Agency (MHRA) ensures device safety and performance within the UK market. London’s numerous private clinics and elite sports facilities are significant centers for device deployment.
Japan
Japan's emphasis on non-invasive treatments and its aging demographic contribute to the steady adoption of cold laser therapy devices. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates medical device approvals, influencing market access for new technologies. Clinical research centers in Tokyo and Osaka actively explore new applications and treatment protocols.
Cold Laser Therapy Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a dynamic competitive landscape in the cold laser therapy market. The market exhibits fragmentation, with numerous companies vying for market share through innovation and strategic positioning. Key archetypes include established medical device manufacturers, specialized low-level laser technology providers, and agile startups. Portfolio diversification, often into veterinary applications, and strategic partnerships with sports organizations are common competitive moves.
Specialists in low-level laser technology, such as Erchonia Corporation, have secured numerous FDA market clearances, highlighting a focus on regulatory validation. THOR Photomedicine Ltd exemplifies a company leveraging deep research in photobiomodulation to serve elite sports teams, emphasizing performance-driven solutions. Meanwhile, LiteCure occupies a position among manufacturers developing high-power laser therapy devices for both human and veterinary applications, showcasing a broad market approach.
| Leading Market Players |
|---|
| Theralase Inc. |
| Multi Radiance Medical |
| Erchonia Corporation |
| Apira Science Inc |
| THOR Photomedicine Ltd |
| Zimmer MedizinSysteme GmbH |
| DJO Global, Inc. |
| LiteCure |
| BTL |
| Others |
Cost & Logistics Intelligence
Specialized engineering talent in European medical technology hubs drives higher R&D costs, influencing the premium pricing of advanced cold laser therapy systems compared to more commoditized units assembled with lower labor costs in other regions.
Pricing Analysis
Bundled service packages for cold laser therapy devices often integrate installation, training, and maintenance contracts, creating a hybrid pricing model distinct from unbundled device-only sales. Pricing differentiation stems from FDA/CE certification levels and the comprehensiveness of after-sales support. Pricing softness runs through the handheld device segment, reflecting increased competition from new market entrants. Smaller physiotherapy clinics exhibit higher price sensitivity, whereas elite sports medicine facilities prioritize advanced features and comprehensive support over upfront cost.
Supply Chain Analysis
Domestic content mandates in the United States and Europe are gradually reshaping sourcing strategies for cold laser device components. The supply chain for these devices largely centers on specialized optical components from Germany and precision electronics from China, relying heavily on high-quality laser diodes, optical lenses, and microcontrollers. A structural risk involves single-source vulnerability for highly specialized laser components. Downstream distribution primarily occurs through a network of medical equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cold laser therapy market presents a geographic-arbitrage opportunity, driven by varying regulatory approval timelines between the US FDA and the more stringent European MDR requirements.
For Market Incumbents:
Hedge against the substitution threat from high-power lasers by investing in differentiated low-level laser technology for specific indications. Incumbents should deepen R&D into novel wavelength protocols to expand clinical evidence for LLLT efficacy. Strategic acquisitions of smaller firms specializing in niche applications or advanced software integration can consolidate market share. Expanding direct sales channels to sports medicine facilities reinforces customer relationships against emerging competitors.
For New Entrants and Emerging Players:
Launch via online retailers and specialized e-commerce platforms to bypass established direct sales channels. New entrants should target the underpenetrated veterinary medicine market, particularly for companion animal care, and develop simplified home-use devices. The most penetrable segment remains smaller physiotherapy clinics, seeking cost-effective and portable solutions. A key go-to-market angle involves emphasizing device portability and affordability, coupled with clear, user-friendly treatment protocols.
For Investors and Strategic Acquirers:
Established medical device manufacturers are the most active acquirers in this space, seeking to diversify their therapeutic portfolios. The cold laser therapy market exhibits long-term viability, poised for steady expansion over the next decade, driven by non-invasive treatment preferences. Ideal acquisition targets include specialists in low-level laser technology with robust FDA market clearances and strong clinical evidence. The expansion of reimbursement coverage across major healthcare systems represents the critical inflection signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Expansion | Generates robust evidence for new cold laser therapy indications, validating efficacy for broader practitioner adoption. |
| FDA/CE Marking Pursuit | Secures market access and builds practitioner confidence in device safety and performance within regulated markets. |
| Telehealth Integration | Expands patient access to cold laser therapy by enabling remote monitoring and guidance for home-use devices. |
| Veterinary Product Line Diversification | Captures significant untapped commercial opportunities in animal pain management and rehabilitation applications. |
| Subscription Model Development | Attracts smaller physiotherapy clinics by lowering upfront capital costs and offering flexible device acquisition. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region informing the market analysis. This involved extensive interviews with physiotherapists, sports medicine physicians, medical device engineers, and hospital procurement managers. Secondary validation drew from FDA filings, CE marking databases, medical journals, and industry association reports. A bottom-up and top-down triangulation approach ensured data consistency and accuracy.
Rate-of-change decomposition framed the analytical approach, assessing shifts across various market dimensions. The model segmented by product type, therapy area, end-user, distribution channel, and device power output over the projection horizon. Compound Annual Growth Rates were derived from historical trends and projected future demand. Key industry-specific inputs included regulatory approval timelines and evolving reimbursement policy changes.
Several conditions sit outside the modeled scope, including the impact of unforeseen global health crises or rapid technological obsolescence. Forecasts reflect assumptions regarding steady clinical adoption and stable regulatory environments, though major shifts in medical consensus or unexpected competitive entries represent risk factors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Medicine
Homeopathy Products Market
Alternative Medicine
Traditional Chinese Medicine Market
Alternative Medicine
Europe Complementary and Alternative Medicine Market
Alternative Medicine
Vacuum Cupping Market
Alternative Medicine
Natural Cold, Cough, and Sore Throat Remedies Market
Alternative Medicine
US Aromatherapy Market
Alternative Medicine
Global OTC Herbal and Traditional Medicine Market
Alternative Medicine
Disposable Acupuncture Needle Market
Alternative Medicine
Electrotherapy Market
Alternative Medicine
Traditional Chinese Herbal Medicine Market
Alternative Medicine
Ozone Therapy Units Market
Alternative Medicine
Botanicals & Acupuncture Market
Alternative Medicine
Fire Cupping Market
Alternative Medicine
Global Homeopathic Product Market
Alternative Medicine
Global Acupuncture Market
Alternative Medicine
Biopuncture Treatment Market