
 Natural Cold, Cough, and Sore Throat Remedies Market | 2026-2036
Natural Cold, Cough, and Sore Throat Remedies Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Cold, Cough, and Sore Throat Remedies Market Analytics
Direct-to-consumer subscription financing is reconfiguring capital requirements for natural remedy brands, enabling asset-light entrants to scale without heavy retail slotting fees. Himalaya Global Holdings leverages its integrated herb cultivation network across the Indian subcontinent to control raw material quality from seed to shelf. Schwabe Group dominates European pharmacy channels through decades of clinician trust in its standardized plant extracts. Dabur competes in emerging markets by extending its Ayurvedic heritage into modern gummy and powder formats.
Natural cold, cough, and sore throat remedies comprise botanically derived formulations—typically containing standardized concentrations of polyphenols, volatile oils, or mucilage compounds—processed through aqueous extraction or cold-pressing methods to preserve thermolabile actives. These products function primarily as symptomatic relief agents that modulate mucosal inflammation or support immune response through phytochemical pathways. Herbal teas and syrups lead volume sales due to their familiarity and immediate consumption ritual, while gummies within the formulation category capture the fastest household penetration by converting pediatric and young adult users from conventional tablets. Essential oils and lozenges concentrate margin pools through premium positioning in health stores and specialized pharmacy counters.
The FDA's enforcement discretion framework for homeopathic products and the EU Traditional Herbal Medicinal Products Directive together shape which formulations achieve market access in North America and Europe. India's CDSCO and the Ministry of AYUSH govern export certification for Ayurvedic ingredients, directly influencing supply reliability for multinational brands sourcing from the subcontinent. Stakeholders must monitor how regulatory convergence between pharmacovigilance standards and sustainability disclosure requirements will reshape ingredient traceability investments across the value chain.
Market Dynamics
Millennial and Gen Z pharmacy purchasing patterns are compressing traditional retail margins while elevating direct-to-consumer subscription models that bypass slotting-fee structures entirely.
Growth Catalysts
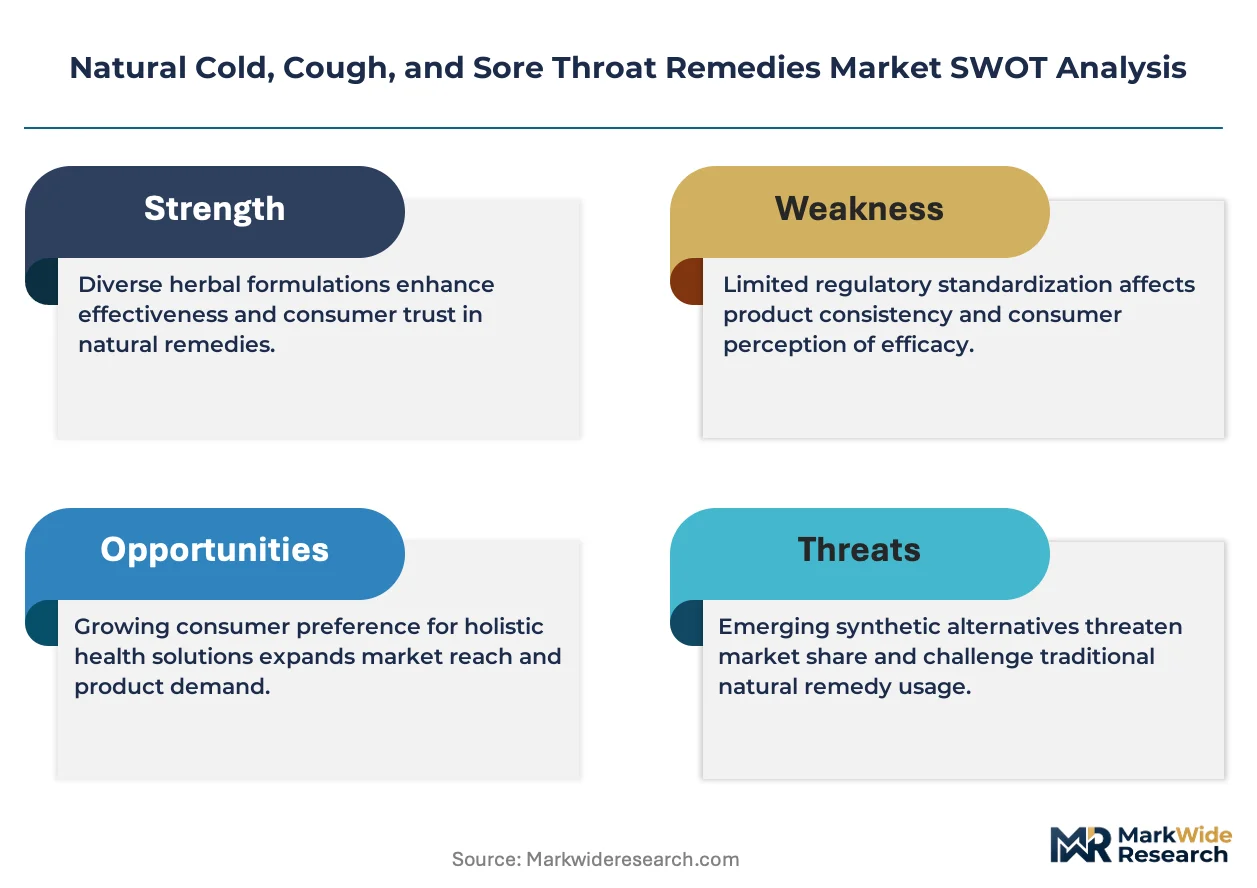
- FDA Homeopathic Enforcement Discretion:The FDA's evolving labeling guidance pressures manufacturers to substantiate efficacy claims, accelerating consolidation around clinically validated formulations.
- Germany Pharmacy Channel Trust:German consumers demonstrate sustained preference for pharmacy-led herbal remedy distribution, creating stable demand anchors for standardized extract products.
- Ayurvedic Export Certification:India's CDSCO and Ministry of AYUSH governance of export certification ensures supply reliability for multinational brands sourcing botanical actives.
Market Restraints
- Raw Material Volatility:Herb cultivation cycles and climate sensitivity of Indian subcontinent sourcing regions create input cost instability for mucilage and volatile oil extracts.
- Regulatory Friction:The EU Traditional Herbal Medicinal Products Directive creates divergent compliance pathways that fragment formulation standardization across Atlantic markets.
- Substitution Threat:Synthetic antitussives and decongestants retain pharmacy shelf priority through established reimbursement codes and clinician prescribing habits.
Strategic Opportunities
- Pediatric Format Conversion:Gummy and powder Ayurvedic formulations capture household penetration by converting young adult users from conventional tablet consumption rituals.
- Subscription Channel Innovation:Direct-to-consumer financing models enable asset-light entrants to scale without heavy retail slotting fee burdens.
- Traceability Investment:Regulatory convergence between pharmacovigilance standards and sustainability disclosure requirements creates competitive differentiation for seed-to-shelf integrated supply chains.
Industry Challenges
- Standardization Delays:Polyphenol and volatile oil concentration consistency across aqueous extraction batches requires capital-intensive quality infrastructure.
- Compliance Timeline Compression:Dual-track navigation of FDA homeopathic frameworks and EU herbal directives stretches regulatory affairs capacity for mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Cold, Cough, and Sore Throat Remedies Market |
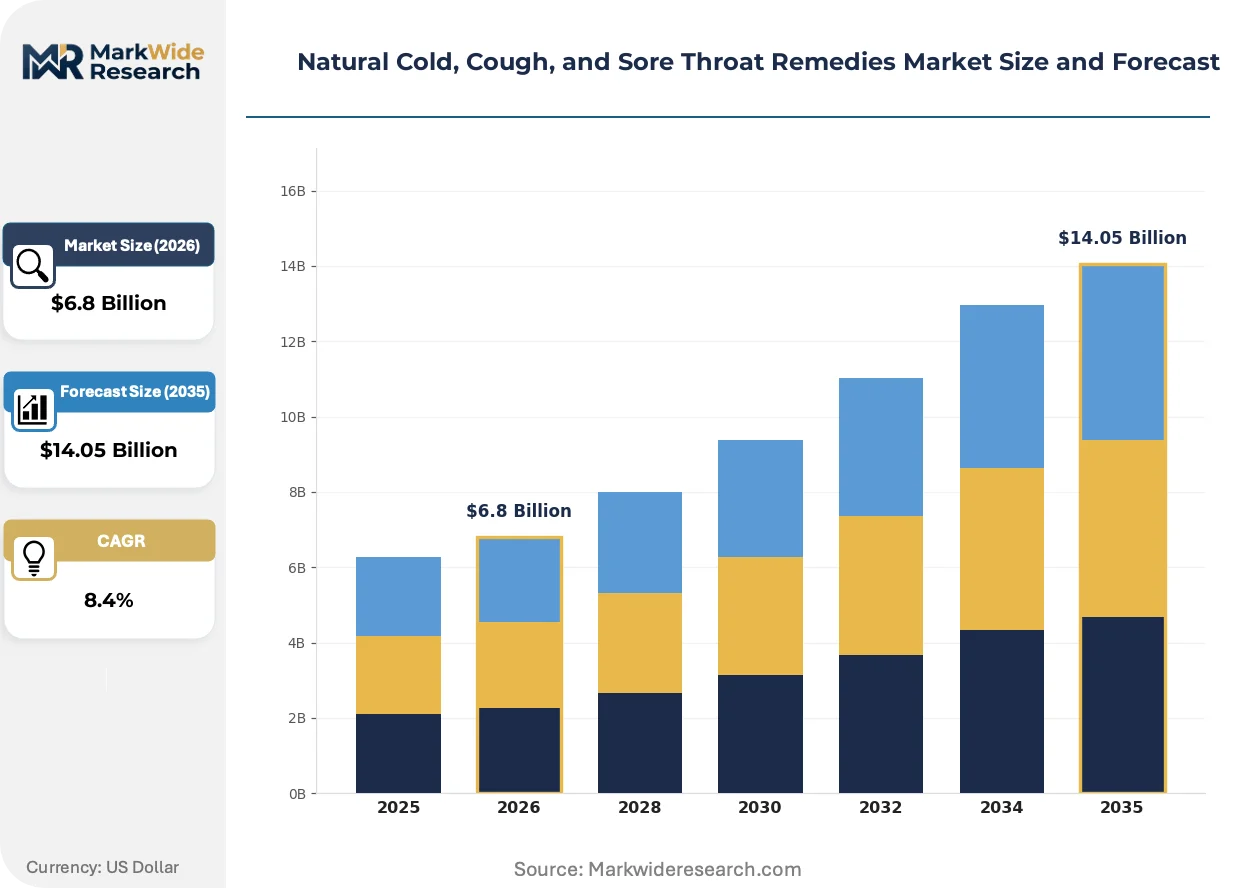
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Teas, Syrups, Lozenges, Essential Oils Ingredient Type: Honey, Ginger, Echinacea, Licorice Root Formulation: Liquid, Powder, Capsule, Gummies Distribution Channel: Pharmacies, Online Retail, Supermarkets, Health Stores |
| Companies Covered | Hyland's, Himalaya Global Holdings, Schwabe Group, Dabur, Zandu Pharmaceuticals, Tsumura & Co, Blackmores Limited, Procter & Gamble, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Cold, Cough, and Sore Throat Remedies Market Evolving Landscape
Formulation science and distribution architecture are undergoing parallel transformation as thermolabile preservation methods converge with channel-agnostic purchasing behaviors.
Supercritical CO2 extraction is migrating from niche essential oil production to mainstream syrup and lozenge manufacturing. Premium health store buyers now demand cold-pressed botanical integrity previously reserved for aromatherapy applications. This migration from thermal processing is compressing margin pools for conventional aqueous extract suppliers while elevating equipment capex thresholds.
The EU Traditional Herbal Medicinal Products Directive is tightening monograph compliance requirements for thyme, ivy, and primrose root preparations. Manufacturers must now demonstrate 15-year traditional use documentation or pivot toward food supplement classification with restricted health claims. German and Austrian pharmacy counters are responding by consolidating shelf space around Schwabe and Bionorica standardized extracts with established THMP registrations.
Subscription-based replenishment is displacing episodic pharmacy purchasing among North American households with children. Direct-to-consumer brands capture recurring revenue by bundling seasonal immune support kits with pediatric-friendly gummy formats. This behavioral shift concentrates most visibly in urban coastal markets where convenience-oriented parents prioritize doorstep delivery over in-person consultation.
Natural Cold, Cough, and Sore Throat Remedies Market Segmentation
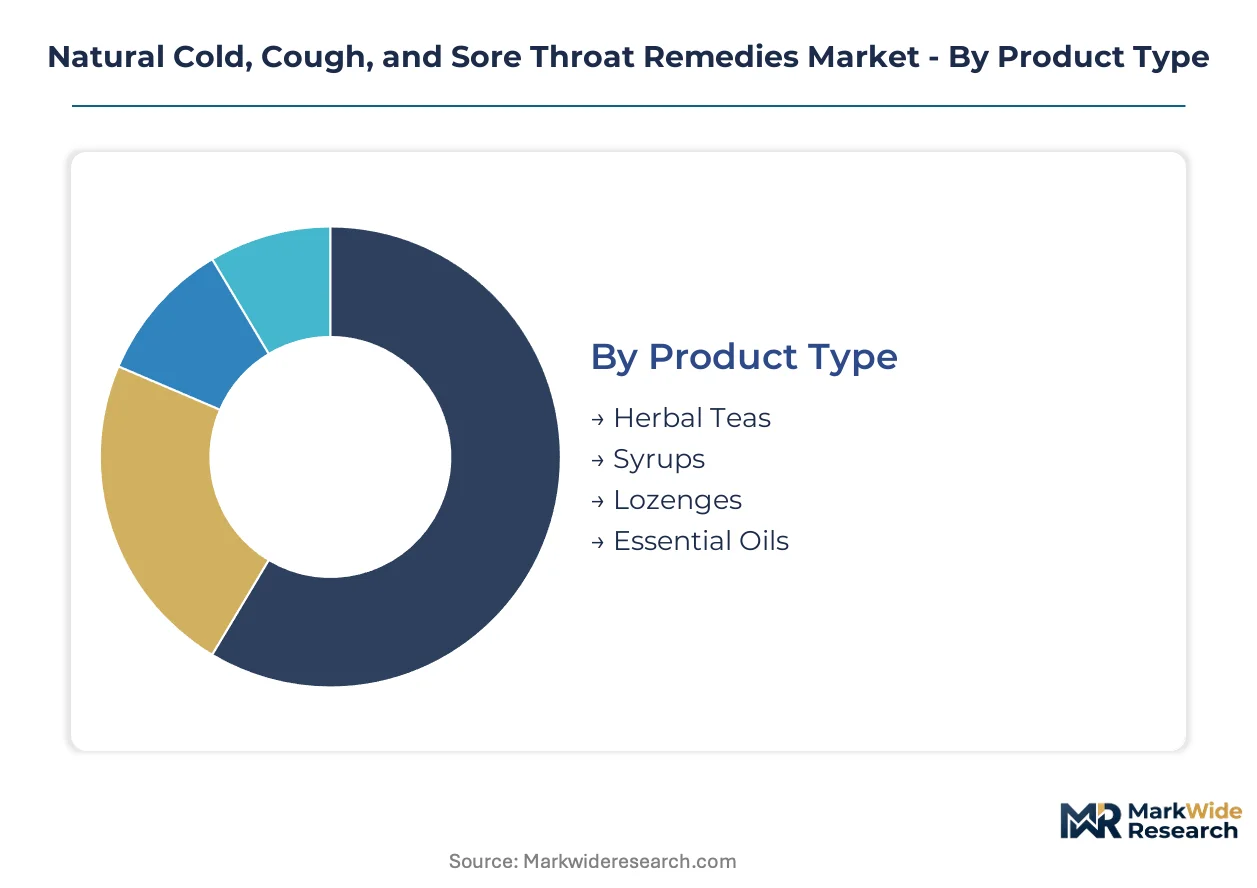
Segmentation in natural cold, cough, and sore throat remedies reveals how formulation chemistry and channel economics create divergent margin architectures. Manufacturers must align thermolabile preservation capabilities with the trust mechanisms inherent to each purchasing context.
Product Type:
Mature consumption rituals anchor volume in traditional formats, while emerging delivery systems capture household penetration through convenience repositioning.
- Herbal Teas:Aqueous infusions of dried botanicals delivering polyphenol and volatile oil actives through immediate consumption rituals. German pharmacy counters sustain demand concentration through clinician endorsement of standardized thyme and ivy preparations.
- Syrups:Viscous aqueous or hydroalcoholic extracts suspending mucilage compounds for mucosal coating action. North American Millennial parents drive household replenishment through subscription bundling of pediatric-friendly variants.
- Lozenges:Solid oral dosage forms releasing demulcent or antiseptic actives through controlled dissolution. Health store channels in urban coastal markets favor premium positioning with certified organic ingredient claims.
- Essential Oils:Concentrated volatile oil preparations for inhalation or topical application. Cold-pressed extraction integrity commands price premiums in aromatherapy crossover segments.
Herbal teas retain volume leadership; gummies hold the steepest expansion curve.
Ingredient Type:
Cost tier stratification separates commodity botanicals from clinically validated extracts with documented monograph compliance.
- Honey:Osmotic and enzymatic antimicrobial properties from floral nectar sources with geographic indication premiums. New Zealand manuka and European buckwheat varieties anchor premium tier positioning through UMF and MGO certification schemes.
- Ginger:Rhizome-derived gingerol and shogaol compounds with antiemetic and anti-inflammatory activity. Indian subcontinent cultivation networks supply bulk raw material for aqueous extraction operations.
- Echinacea:Alkylamide-rich aerial parts and root extracts standardized for immune-modulating polysaccharides. EU Traditional Herbal Medicinal Products Directive compliance requires 15-year traditional use documentation for pharmacy channel access.
- Licorice Root:Glycyrrhizin-containing root extracts with demulcent and expectorant properties. Deglycyrrhizinated variants address safety constraints in hypertensive patient populations.
Honey commands premium tier pricing; echinacea faces the steepest regulatory documentation burden.
Formulation:
Customer type differentiation separates acute symptomatic users from preventive immune support households with distinct consumption cadences.
- Liquid:Ready-to-consume aqueous or hydroalcoholic preparations with immediate bioavailability. Pharmacy-led distribution in Germany and Austria sustains preference for standardized extract syrups with THMP registration.
- Powder:Dried botanical extracts or whole-plant material for reconstitution in hot water. Ayurvedic heritage brands in emerging markets leverage this format for traditional consumption ritual preservation.
- Capsule:Encapsulated dried extracts or powdered botanicals for taste-masked delivery. Adult professionals in time-constrained urban markets favor discrete portability.
- Gummies:Gelatin or pectin-based matrices suspending standardized botanical extracts in palatable formats. Pediatric and young adult conversion from conventional tablets accelerates fastest in North American direct-to-consumer channels.
Liquid formulations retain pharmacy channel dominance; gummies gain share fastest among subscription-based households.
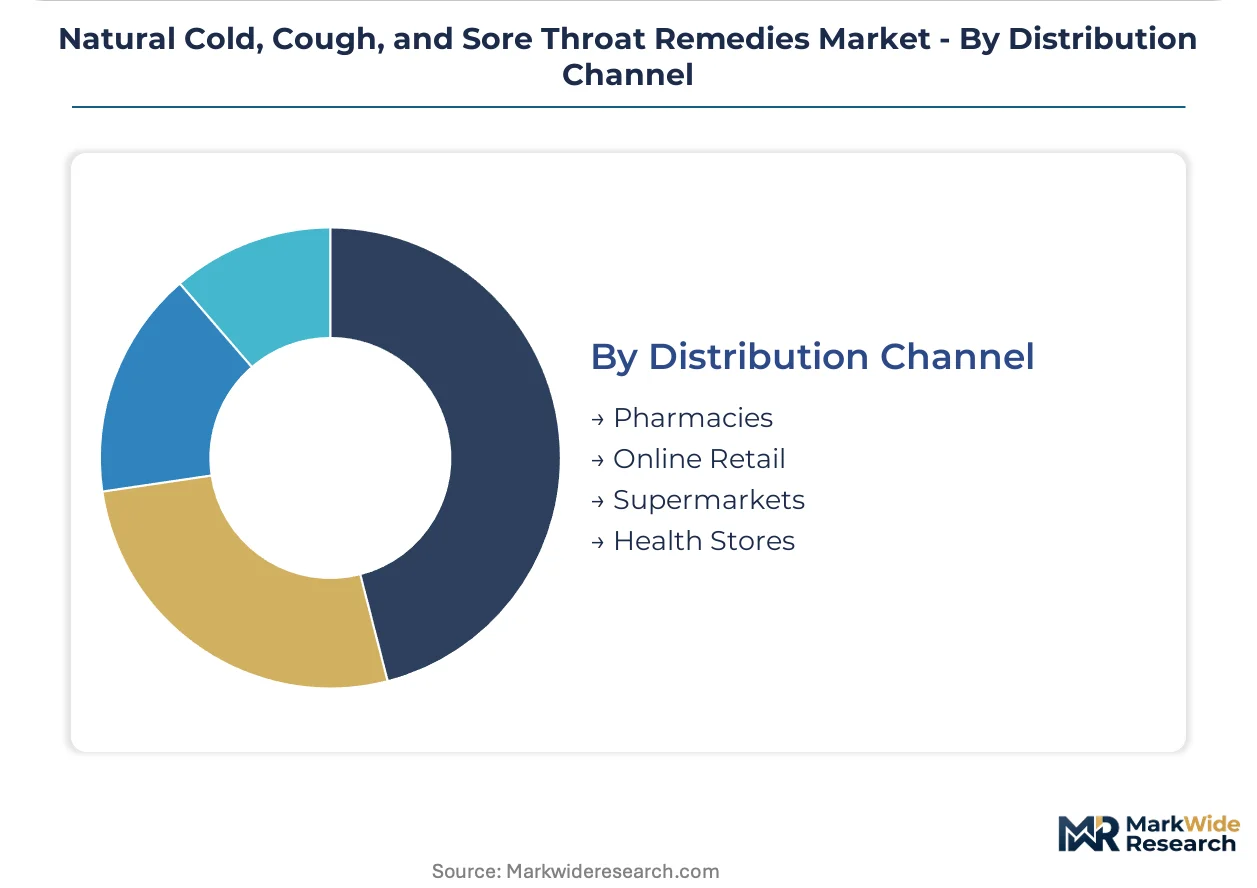
Distribution Channel:
Geography determines trust architecture, with pharmacy consultation cultures sustaining premium pricing against convenience-oriented mass retail.
- Pharmacies:Clinician-staffed counters with trained personnel capable of guiding product selection based on symptom presentation. German and Austrian markets demonstrate sustained preference for this channel with standardized extract concentration.
- Online Retail:Direct-to-consumer platforms enabling subscription replenishment and bypass of traditional slotting fee structures. North American coastal urban markets concentrate demand for bundled seasonal immune support kits.
- Supermarkets:Mass retail placement with price-competitive positioning and impulse purchase visibility. Private label penetration pressures branded margin pools in this channel.
- Health Stores:Specialized retail with educated staff and certified organic or non-GMO product curation. Premium positioning concentrates around cold-pressed extraction claims and single-origin botanical sourcing.
Pharmacies retain margin leadership in regulated European markets; online retail climbs fastest in North American household penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export certification from Indian subcontinent cultivation networks underpins supply reliability for multinational brands, while German pharmacy channels anchor premium pricing for standardized extracts. The United States drives direct-to-consumer subscription growth, diverging from European consultation-based purchasing cultures.
Germany
Pharmacy-led distribution sustains clinician trust in standardized thyme and ivy preparations with Traditional Herbal Medicinal Products Directive registration. The BfArM federal institute governs monograph compliance for demulcent and expectorant formulations. Bavaria's herbal extract manufacturing cluster around Munich supplies standardized concentrates to Austrian and Swiss pharmacy counters.
United States
Millennial and Gen Z households compress traditional retail margins through subscription-based seasonal immune support kits. FDA enforcement discretion on homeopathic labeling pressures manufacturers toward substantiated efficacy claims. Brooklyn and Austin direct-to-consumer brands bypass slotting fees through bundled pediatric gummy formats.
India
Ayurvedic heritage drives gummy and powder format conversion for young adult users shifting from conventional tablets. CDSCO and Ministry of AYUSH export certification governs botanical active supply chains for multinational sourcing. Karnataka's herb cultivation networks around Bangalore control raw material quality from seed to shelf for integrated brands.
Japan
Traditional Kampo medicine integration sustains pharmacy channel preference for standardized botanical combinations. PMDA oversight of quasi-drug classification creates compliance pathways for symptomatic relief formulations. Tokyo-Osaka metropolitan corridors concentrate health store distribution of cold-pressed extraction products.
United Kingdom
Health store channels in London and Southeast England favor premium positioning with certified organic ingredient claims. MHRA alignment with EU Traditional Herbal Medicinal Products Directive post-Brexit creates transitional documentation requirements. Manchester-based formulation specialists supply aqueous extraction concentrates to independent pharmacy networks.
Natural Cold, Cough, and Sore Throat Remedies Market Competitive Landscape
On the supply side, the industry is consolidating around clinically validated formulations as regulatory documentation burdens filter out mid-scale manufacturers. Three archetypes dominate: integrated herb cultivation networks with seed-to-shelf quality control, pharmacy-centric standardized extract specialists with decades of clinician trust, and direct-to-consumer brands leveraging subscription financing to bypass retail slotting structures. Competitive moves concentrate on M&A for THMP registration portfolios and backward integration into captive cultivation capacity.
Within the heritage Ayurvedic tier, Dabur and Zandu Pharmaceuticals occupy positions exemplifying format innovation from traditional powders toward pediatric-friendly delivery systems. Himalaya Global Holdings anchors the integrated cultivation archetype through subcontinent herb network control. Schwabe Group represents the European pharmacy-channel specialist model with standardized extract concentration. These three entities collectively illustrate how geographic origin and distribution architecture determine competitive positioning across Atlantic and Asia-Pacific markets.
| Leading Market Players |
|---|
| Hyland's |
| Himalaya Global Holdings |
| Schwabe Group |
| Dabur |
| Zandu Pharmaceuticals |
| Tsumura & Co |
| Blackmores Limited |
| Procter & Gamble |
| Johnson & Johnson |
| Others |
Value Network & Pricing Analysis
Climate volatility across Indian subcontinent herb cultivation zones compresses margin pools for mucilage and volatile oil suppliers while simultaneously widening spreads between certified organic and commodity-grade botanical inputs. This agricultural risk concentration forces manufacturers to either absorb input cost instability or pass through premiums to pharmacy and direct-to-consumer channels.
Pricing Analysis
Health store buyers anchor three-tier pricing structure across premium, standard, and economy levels based on organic certification grade and cold-pressed extraction integrity. Price differentiation separates UMF-certified manuka honey formulations from bulk floral nectar syrups, with subscription bundling in North America softening per-unit price sensitivity among Millennial parents. Cost compression in economy-tier aqueous extracts is intensifying because of private label penetration in mass retail channels. Pharmacy procurement committees in Germany demonstrate lowest price sensitivity due to clinician trust in THMP-registered standardized extracts.
Supply Chain Analysis
India's CDSCO export certification regime restricts unverified Ayurvedic ingredient flows to compliant multinational brands, concentrating upstream control among integrated cultivation networks. Geographic supply concentration centers on India for ginger and licorice root, Germany for thyme and ivy extracts, and New Zealand for manuka honey. Raw material dependencies include subcontinent rhizome cultivation, Bavarian pharmaceutical-grade extraction capacity, and verified floral nectar sources. Single-source vulnerability runs through Karnataka herb clusters exposed to monsoon variability. Distribution runs through pharmacy-led channels in regulated European markets and direct-to-consumer platforms in North American coastal corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Natural cold, cough, and sore throat remedies operate within seasonal demand cyclicality, with winter respiratory illness peaks driving inventory build cycles and subscription renewal timing across temperate climate zones.
For Market Incumbents: Build regulatory documentation moats around THMP registration portfolios and FDA homeopathic substantiation pathways. Consolidate shelf space in German pharmacy channels through clinician education programs on standardized extract bioequivalence. Deepen backward integration into captive Karnataka cultivation capacity to secure polyphenol concentration consistency against climate-driven raw material volatility from emerging Ayurvedic entrants. For New Entrants and Emerging Players: Japanese health store corridors in Tokyo-Osaka metropolitan areas offer underpenetrated white space for cold-pressed extraction products with Kampo medicine positioning. Target pediatric gummy format conversion in North American subscription channels where convenience-oriented parents bypass traditional pharmacy consultation. Pursue white-label supply partnerships with established Bavarian extraction specialists to bypass capital-intensive quality infrastructure buildout. For Investors and Strategic Acquirers: FDA enforcement discretion on homeopathic labeling reshapes the acquisition landscape toward clinically validated formulation portfolios with documented efficacy substantiation. Long-term viability across the analysis window favors targets with integrated seed-to-shelf supply chains and established pharmacy channel relationships in regulated European markets. Monitor CDSCO export certification backlog clearance rates as the signal indicating supply reliability inflection for multinational sourcing strategies.| Strategic Initiative | Industry Significance |
|---|---|
| THMP Registration Portfolio Acquisition | Secures pharmacy channel access under EU Traditional Herbal Medicinal Products Directive compliance pathways. |
| Backward Integration into Cultivation | Captures Karnataka herb network control to ensure polyphenol concentration consistency across extraction batches. |
| Direct-to-Consumer Subscription Launch | Bypasses retail slotting fee structures through bundled seasonal immune support kits in Brooklyn and Austin markets. |
| Pediatric Gummy Format Extension | Converts young adult users from conventional tablets through palatable gelatin matrices with standardized botanical extracts. |
| Cold-Pressed Extraction Scale-Up | Commands health store price premiums through thermolabile preservation integrity previously reserved for aromatherapy segments. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with regulatory affairs leads at Ayurvedic heritage brands, pharmacy procurement managers in German and Austrian markets, and direct-to-consumer brand founders in North American coastal corridors; and secondary validation through CDSCO export certification records, EU THMP registration databases, FDA homeopathic enforcement discretion guidance documents, and customs trade data on botanical active imports. Bottom-up triangulation across formulation-level volume estimates and top-down reconciliation against channel shipment data anchored the market sizing framework.
Forecast inputs considered product type segmentation across herbal teas, syrups, lozenges, and gummies; ingredient type tiering from commodity botanicals to certified organic extracts; formulation chemistry including aqueous extraction and cold-pressed methods; and distribution channel dynamics spanning pharmacy-led, online retail, and health store architectures. CAGRs were derived through regression analysis of historical subscription penetration rates and seasonal demand elasticity coefficients, with cross-validation against clinician prescribing pattern surveys and parental format preference studies.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by integrated cultivation networks or accelerated FDA substantiation timelines among homeopathic specialists would shift outcomes. Material shifts in monsoon patterns affecting Karnataka herb yields or EU THMP directive enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Medicine
Homeopathy Products Market
Alternative Medicine
Aromatherapy Market
Alternative Medicine
Traditional Chinese Medicine Market
Alternative Medicine
Ozone Therapy Units Market
Alternative Medicine
Disposable Acupuncture Needle Market
Alternative Medicine
US Chiropractic Market
Alternative Medicine
Global Homeopathic Product Market
Alternative Medicine
Global Acupuncture Market
Alternative Medicine
Biopuncture Treatment Market
Alternative Medicine
Acupuncture Lasers Market
Alternative Medicine
Botanicals & Acupuncture Market
Alternative Medicine
Allergy Immunotherapy Market
Alternative Medicine
Orthomolecular Medicine Market
Alternative Medicine
US Aromatherapy Market
Alternative Medicine
Global OTC Herbal and Traditional Medicine Market
Alternative Medicine
Global Complementary and Alternative Medicines Market