
 North America Down Syndrome Market | 2026-2036
North America Down Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
North America Down Syndrome Market Analytics
Genetic counseling subscription models is pivoting how prenatal screening services are packaged and reimbursed across North American healthcare networks. BioMarin leverages its enzyme therapy expertise to sustain leadership in rare-disease metabolic interventions. Illumina, Inc. anchors the sequencing infrastructure that underpins non-invasive prenatal testing workflows. Myriad Genetics, Inc. specializes in hereditary cancer and prenatal risk assessment portfolios that compete for clinician mindshare.
Down syndrome encompasses a trisomy 21 chromosomal condition characterized by cognitive impairment, congenital heart defects, and distinct craniofacial features requiring multidisciplinary clinical management. Prenatal cell-free DNA screening detects fetal aneuploidy from maternal blood samples with high sensitivity, enabling earlier intervention planning than traditional karyotyping. Diagnostic Tests command the largest revenue share within Product Type segments due to established reimbursement for NIPT and confirmatory karyotype analysis. Therapeutics represents the fastest-expanding category as pharmaceutical developers advance disease-modifying candidates through clinical pipelines. Support Services maintains steady demand through Educational Institutions and Nonprofit Organizations that coordinate early-intervention programs across state-level Medicaid structures.
FDA oversight governs therapeutic approval pathways and prenatal test analytical validity claims, while HIPAA mandates shape how genetic data flows between laboratories, clinicians, and families. State-level newborn screening programs operate under variability in coverage for developmental follow-up services, creating uneven access landscapes across provincial and territorial boundaries. Stakeholders must monitor CMS reimbursement decisions for novel therapeutic categories and state Medicaid expansion dynamics that determine patient out-of-pocket exposure for lifelong care coordination.
Market Dynamics
FDA's evolving guidance framework for cell and gene therapies is compressing development timelines while reshaping how therapeutic developers allocate capital across preclinical and clinical stages. This regulatory momentum intersects with expanding preimplantation genetic testing adoption in fertility clinics, creating dual pressure on diagnostic and therapeutic pipelines.
Growth Catalysts
- Preimplantation Genetic Testing:Fertility clinics across the United States are integrating expanded carrier screening and embryo biopsy protocols into standard IVF workflows, elevating detection rates for trisomy 21 prior to implantation.
- HIPAA-Mandated Data Infrastructure:Genetic counseling platforms and laboratory information systems have invested in interoperable architectures that streamline secure data exchange between maternal-fetal medicine specialists and pediatric care coordinators.
- California Biomedical Corridor:Concentrated venture deployment into cell therapy manufacturing facilities around San Diego and San Francisco is accelerating translational research from academic medical centers into regulated clinical trials.
Market Restraints
- Specialized Cell Therapy Manufacturing:Viral vector production capacity constraints and cleanroom facility scarcity in the United States create bottlenecks for gene therapy candidates targeting cognitive impairment phenotypes.
- State Medicaid Variability:Uneven coverage determination processes across state-level programs generate reimbursement uncertainty for longitudinal developmental follow-up services and early-intervention program enrollment.
- Confirmatory Karyotyping Requirements:Positive cell-free DNA screening results still mandate invasive diagnostic procedures that carry procedural risk, limiting complete substitution of amniocentesis and chorionic villus sampling.
Strategic Opportunities
- Massachusetts Clinical Research Hub:Boston-Cambridge's concentration of academic medical centers and contract research organizations offers specialized patient recruitment infrastructure for rare-disease neurodevelopmental trials.
- Subscription-Based Genetic Counseling:Health systems are piloting annual membership models that bundle prenatal risk assessment, carrier screening, and postnatal care navigation into predictable per-patient revenue streams.
- CMS Innovation Center Demonstrations:Value-based payment pilots for pediatric complex care coordination present pathways for integrated Down syndrome clinic models to capture shared savings through reduced emergency utilization.
Industry Challenges
- Neurodevelopmental Endpoint Validation:Cognitive assessment instruments for pediatric populations with intellectual disability require adapted validation protocols that extend regulatory submission timelines compared to standard therapeutic categories.
- Laboratory Director Certification:High-complexity molecular testing under CLIA regulations demands specialized personnel credentials that constrain expansion velocity for regional reference laboratories entering the NIPT market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Down Syndrome Market |
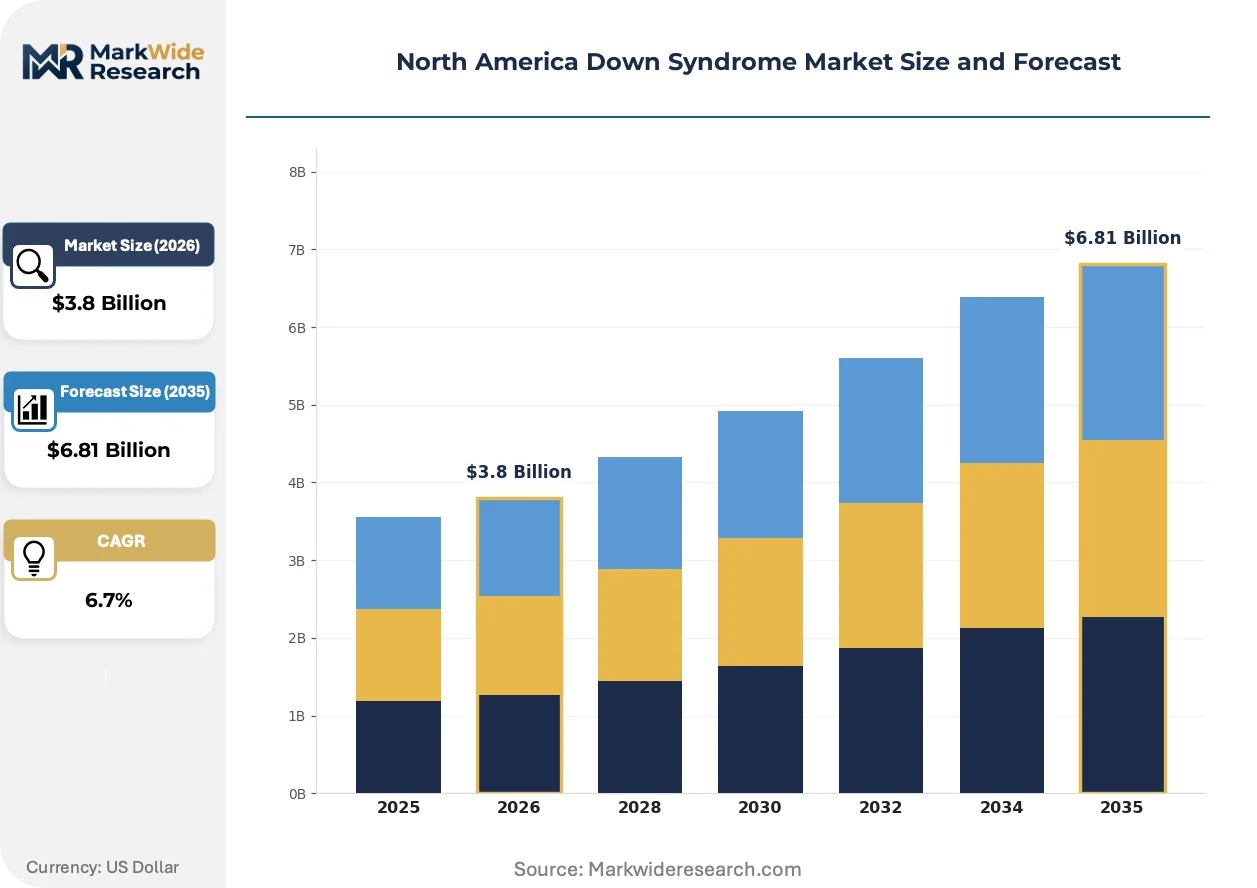
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Tests, Therapeutics, Support Services, Educational Resources End User: Hospitals, Clinics, Educational Institutions, Nonprofit Organizations Care Setting: In-Home Care, Outpatient Care, Institutional Care, Rehabilitation Facilities Delivery Mode: Online Platforms, In-Person Sessions, Mobile Units, Community Outreach |
| Companies Covered | BioMarin, Illumina, Inc., Myriad Genetics, Inc., Natera, Inc., Thermo Fisher Scientific Inc., Annovis Bio, Inc., Aphios Corporation, Karyopharm, PerkinElmer, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Down Syndrome Market Evolving Landscape
Artificial intelligence-assisted karyotype interpretation and automated fetal fraction quantification are compressing diagnostic turnaround times while reducing cytogeneticist labor intensity. These computational advances intersect with shifting care delivery models that emphasize preconception and first-trimester intervention windows.
Deep learning algorithms applied to chromosomal microarray and sequencing data are modularizing how cytogenetics laboratories structure their analytical workflows. Mid-sized reference labs in Texas and Illinois are adopting cloud-based variant interpretation platforms that separate wet-lab processing from bioinformatics execution. This technology is modularizing the traditional integrated laboratory model into discrete service components that can be outsourced or insourced based on volume economics.
FDA's 2023 guidance on human gene therapy products for neurodegenerative diseases is clarifying preclinical study design expectations for disease-modifying candidates targeting cognitive endpoints. Developers must now demonstrate translatable biomarker engagement in appropriate animal models prior to IND submission. Pediatric neurodevelopmental therapeutic developers are responding by establishing dedicated natural history study infrastructure to support longitudinal control data collection.
Direct-to-consumer genetic testing platforms are conditioning expectant parents to anticipate comprehensive prenatal information prior to clinical encounters. Maternal-fetal medicine practices in urban markets are restructuring consultation workflows to incorporate externally sourced screening results into standardized risk counseling protocols. This behavioral shift is most pronounced in metropolitan California health systems where consumer-initiated testing penetration exceeds national benchmarks.
North America Down Syndrome Market Segmentation
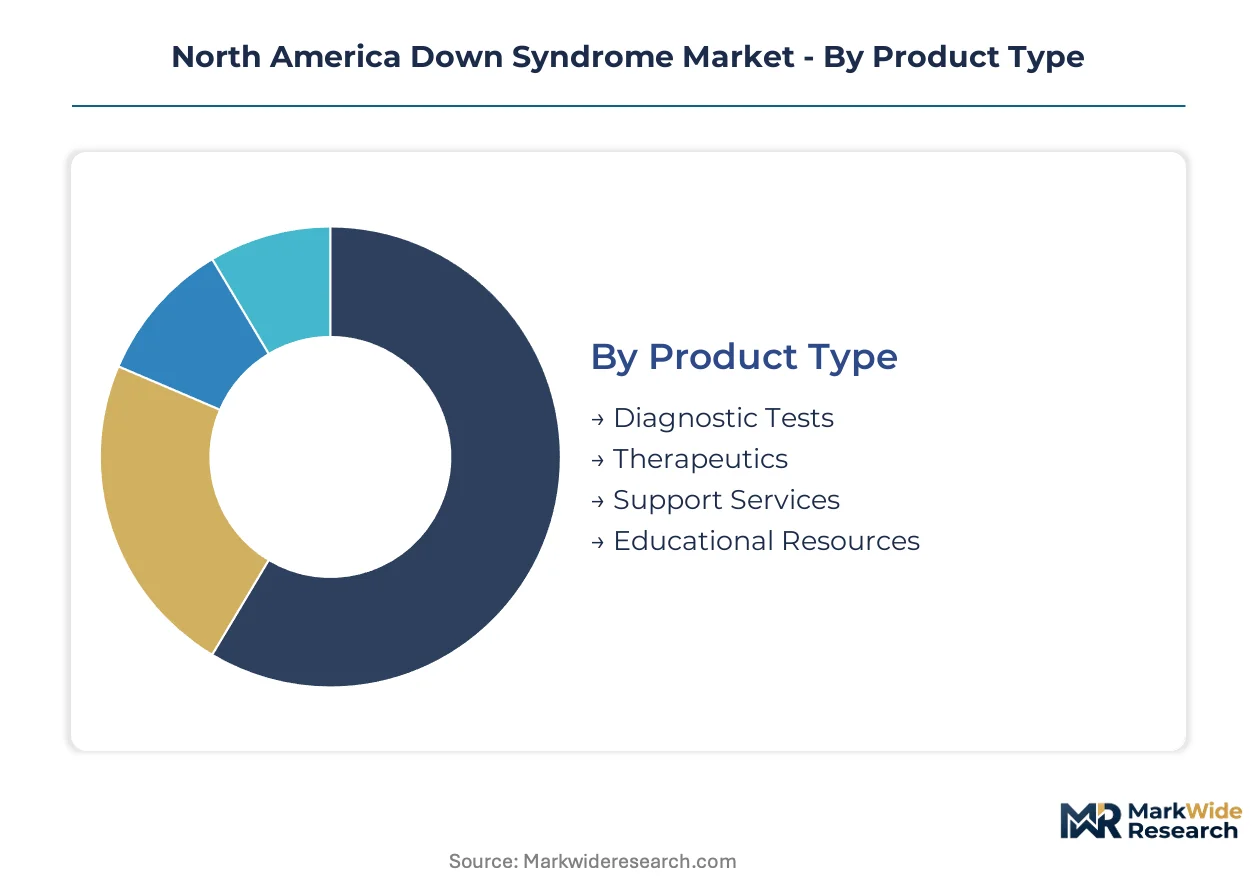
Down syndrome care pathways fragment across distinct reimbursement silos and regulatory jurisdictions, forcing vendors to architect separate commercial strategies for diagnostic, therapeutic, and service-oriented segments. Understanding these structural divides reveals where capital allocation and partnership priorities should concentrate.
Product Type:
FDA premarket authorization requirements separate diagnostic tests from therapeutics, while support services and educational resources fall outside FDA jurisdiction entirely, creating divergent compliance burdens across segments.
- Diagnostic Tests:Non-invasive prenatal testing (NIPT) platforms and confirmatory karyotype analysis dominate revenue concentration. Demand clusters in California's maternal-fetal medicine networks and Massachusetts' academic medical centers, where earlier detection protocols compress intervention windows and elevate reimbursement for high-risk pregnancy management.
- Therapeutics:Enzyme replacement therapies and emerging gene-modifying candidates target metabolic and cognitive phenotypes. Massachusetts' clinical research hub anchors neurodevelopmental trial recruitment, though viral vector manufacturing constraints in the United States bottleneck supply expansion for disease-modifying programs.
- Support Services:Care coordination and family navigation programs operate under state Medicaid variability, with uneven coverage determination processes across provincial boundaries limiting standardization.
- Educational Resources:Early-intervention curricula and developmental toolkits distribute through state-level Part C programs and nonprofit networks, with procurement authority fragmented across 50 distinct administrative structures.
Leading the category by volume: Diagnostic Tests. Growing fastest: Therapeutics.
End User:
Procurement authority concentrates differently across institutional buyers, with hospitals commanding capital equipment budgets while nonprofits navigate restricted grant funding cycles.
- Hospitals:Tertiary centers integrate NIPT into standard obstetric workflows and host specialized Down syndrome clinics for complex cardiac and endocrine comorbidities. California biomedical corridor facilities capture disproportionate patient volume through vertically integrated prenatal-to-pediatric care continuums.
- Clinics:Community-based maternal-fetal medicine practices and developmental pediatric clinics manage longitudinal follow-up. Texas and Illinois mid-sized reference labs are adopting cloud-based variant interpretation platforms to modularize analytical workflows and reduce capital intensity.
- Educational Institutions:Early-intervention providers and special education programs procure assistive technology and adapted curricula through state education agency allocations.
- Nonprofit Organizations:National and regional advocacy groups coordinate family support services, with funding stability tied to philanthropic cycles and federal grant renewal schedules.
Hospitals capture the dominant procurement share. Clinics are expanding most quickly as point-of-care testing decentralizes.
Care Setting:
Reimbursement design favors institutional over home-based delivery, though value-based payment pilots are beginning to shift financial incentives toward longitudinal care coordination.
- In-Home Care:Private-duty nursing and early-intervention therapy services delivered in residential settings. Demand concentrates where state Medicaid programs maintain generous home and community-based services waivers, creating geographic patchiness in access.
- Outpatient Care:Specialized Down syndrome clinics and multidisciplinary developmental centers anchor routine management. Boston-Cambridge's concentration of academic medical centers offers dedicated patient recruitment infrastructure for rare-disease neurodevelopmental trials.
- Institutional Care:Residential group homes and intermediate care facilities for individuals with intellectual disabilities operate under state licensure variability.
- Rehabilitation Facilities:Speech, occupational, and physical therapy centers address motor and communication delays through intensive intervention protocols.
Outpatient Care commands the largest patient volume. In-Home Care is gaining share fastest as CMS Innovation Center demonstrations test pediatric complex care coordination models.
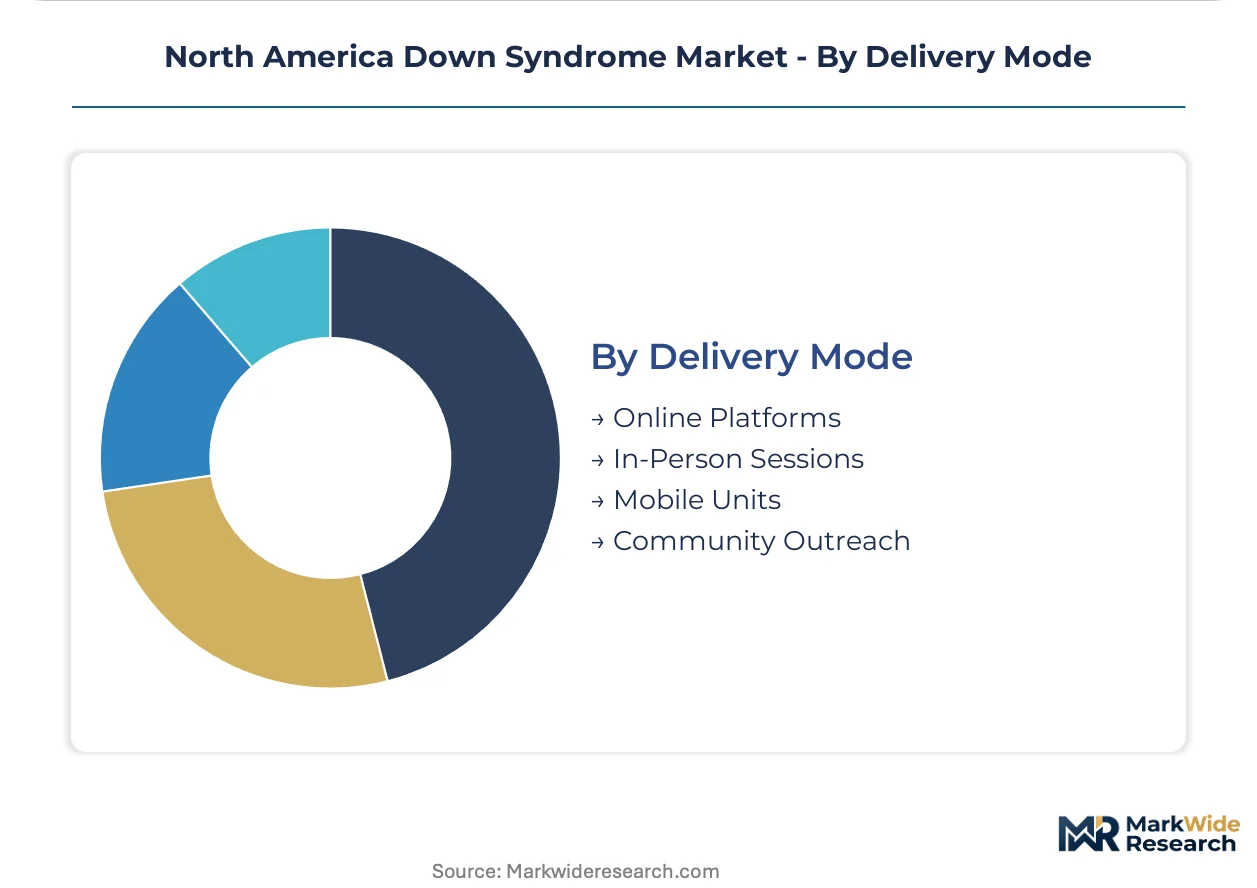
Delivery Mode:
Technology infrastructure investments are modularizing service delivery, separating content provision from in-person clinical encounters across urban and rural markets.
- Online Platforms:Telehealth genetic counseling and remote developmental monitoring expand reach beyond metropolitan catchment areas. HIPAA-mandated data infrastructure investments have streamlined secure exchange between maternal-fetal medicine specialists and pediatric coordinators.
- In-Person Sessions:Traditional clinic-based consultations retain dominance for initial diagnosis and complex case management. Metropolitan California health systems are restructuring workflows to incorporate consumer-initiated screening results into standardized risk counseling protocols.
- Mobile Units:Deployable screening and outreach vehicles extend diagnostic access to underserved rural and frontier regions with limited specialist density.
- Community Outreach:Faith-based and culturally adapted education programs target disparities in prenatal screening uptake among specific demographic cohorts.
In-Person Sessions still anchor the majority of encounters. Online Platforms are climbing the fastest as subscription-based genetic counseling models pilot annual membership structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic test production concentrates in California and Massachusetts manufacturing corridors, while clinical demand spreads across state Medicaid networks with uneven reimbursement density. Therapeutic development clusters near FDA regulatory infrastructure and academic medical center recruitment pools.
United States
California's biomedical corridor hosts concentrated NIPT manufacturing capacity and cell therapy production facilities around San Diego and San Francisco. FDA's evolving guidance framework for cell and gene therapies compresses development timelines for neurodevelopmental candidates. Massachusetts' clinical research hub anchors specialized patient recruitment infrastructure for rare-disease trials through Boston-Cambridge academic medical centers.
California
Metropolitan health systems in Los Angeles and San Francisco restructure maternal-fetal medicine workflows to incorporate consumer-initiated screening results into standardized risk counseling protocols. State-level Medicaid expansion dynamics determine patient out-of-pocket exposure for longitudinal developmental follow-up services. Venture deployment into cell therapy manufacturing facilities accelerates translational research from academic centers into regulated clinical trials.
Massachusetts
Greater Boston's concentration of contract research organizations offers dedicated infrastructure for pediatric neurodevelopmental endpoint validation studies. HIPAA mandates shape secure data exchange between laboratories and clinicians across integrated delivery networks. Harvard-affiliated hospitals and MIT-linked biotech clusters drive early-stage therapeutic candidate development through preclinical biomarker engagement protocols.
Texas
Mid-sized reference laboratories in Houston and Dallas adopt cloud-based variant interpretation platforms to modularize analytical workflows and reduce capital intensity. State Medicaid variability generates reimbursement uncertainty for early-intervention program enrollment across county-level administrative structures. Private-duty nursing demand concentrates where home and community-based services waivers maintain generous coverage parameters.
Canada
Provincial newborn screening programs operate under variability in developmental follow-up service coverage, creating uneven access landscapes across territorial boundaries. Health Canada oversight governs therapeutic approval pathways distinct from FDA timelines. Ontario and Quebec health systems pilot subscription-based genetic counseling models that bundle prenatal risk assessment into predictable per-patient revenue streams.
North America Down Syndrome Market Competitive Landscape
Top-tier vendors anchor sequencing infrastructure and enzyme therapy platforms, while mid-tier reference laboratories compete on turnaround time and regional coverage density. The vendor base stratifies across three archetypes: integrated diagnostic-therapeutic conglomerates, specialized genetic testing laboratories, and emerging cell therapy developers. Competitive moves concentrate on strategic partnerships for patient recruitment infrastructure and technology licensing for automated variant interpretation.
Among sequencing and diagnostic specialists, Illumina, Inc. and Natera, Inc. occupy positions within the platform-technology tier that supplies infrastructure to downstream testing providers. BioMarin exemplifies the rare-disease therapeutic archetype with established enzyme replacement expertise. These three entities represent distinct competitive vectors: hardware infrastructure, laboratory-developed test commercialization, and disease-modifying therapeutic development respectively.
| Leading Market Players |
|---|
| BioMarin |
| Illumina, Inc. |
| Myriad Genetics, Inc. |
| Natera, Inc. |
| Thermo Fisher Scientific Inc. |
| Annovis Bio, Inc. |
| Aphios Corporation |
| Karyopharm |
| PerkinElmer |
| Others |
Value Network & Pricing Analysis
Cloud-based variant interpretation platforms are modularizing cytogenetics workflows across mid-sized reference laboratories, simultaneously compressing capital requirements for market entry and fragmenting pricing power away from integrated diagnostic conglomerates toward specialized bioinformatics providers.
Pricing Analysis
Margin tightening in NIPT services reflects reimbursement compression from CMS and commercial payers alongside rising cloud infrastructure costs. Three-tier pricing structure across premium, standard, and economy levels segments by turnaround time and genetic counselor access depth. Cost-down pressure on confirmatory karyotyping accelerates because automated fetal fraction quantification reduces cytogeneticist labor intensity. State Medicaid programs demonstrate highest price sensitivity, while California's vertically integrated health systems maintain lowest sensitivity due to captive patient volume.
Supply Chain Analysis
Buy American provisions in federal health procurement are reshaping sourcing decisions for sequencing reagents and viral vector production inputs. Manufacturing concentrates in the United States, particularly California's San Diego corridor and Massachusetts' Boston-Cambridge cluster, with secondary capacity in Texas. Supply rests on CRISPR enzymes, fluorescence-activated cell sorting media, and synthetic oligonucleotide libraries. Single-source vulnerability in viral vector cleanroom capacity creates bottleneck risk for gene therapy candidates. Distribution runs through specialized cold-chain logistics providers serving hospital laboratories and fertility clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America's Down syndrome market is consolidating around integrated diagnostic-therapeutic platforms, with FDA's compressed gene therapy timelines and state Medicaid reimbursement variability forcing subscale reference laboratories toward acquisition or exit.
For Market Incumbents: Anticipate margin compression in standalone NIPT services as cloud-based bioinformatics platforms democratize variant interpretation capabilities. Defend position through backward integration into cell therapy manufacturing capacity in California's biomedical corridor, securing captive supply for disease-modifying candidates. Prioritize CLIA laboratory director certification pipelines to constrain regional competitor expansion velocity. For New Entrants and Emerging Players: Rural maternal-fetal medicine practices underserved by genetic counseling infrastructure represent the most penetrable entry point. Subscription-based annual membership models bundling prenatal screening with postnatal navigation bypass established hospital procurement committees. Direct-to-consumer genetic testing platform partnerships offer lower customer acquisition costs than traditional clinician detailing channels. For Investors and Strategic Acquirers: Re-rating potential sits with rare-disease therapeutic developers possessing natural history study infrastructure and FDA breakthrough therapy designation given the agency's 2023 neurodegenerative disease guidance clarity. Long-term viability hinges on demonstrated biomarker engagement in translatable animal models ahead of IND submission. Watch for CMS Innovation Center pediatric complex care coordination demonstration expansions as reimbursement inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Therapy Designation | Accelerates neurodevelopmental candidate review timelines under the agency's evolving gene therapy framework. |
| CLIA High-Complexity Laboratory Certification | Creates personnel credential barriers protecting incumbent NIPT providers from regional reference lab competition. |
| Cloud-Based Variant Interpretation Licensing | Enables Texas and Illinois mid-sized labs to modularize analytical workflows without capital-intensive bioinformatics infrastructure. |
| Natural History Study Infrastructure | Supports longitudinal control data collection required under FDA's 2023 preclinical study design expectations. |
| State Medicaid HCBS Waiver Navigation | Determines geographic patchiness in private-duty nursing and early-intervention therapy service reimbursement. |
Research Methodology
Multi-period observation of NIPT reimbursement rates, gene therapy IND submission volumes, and state Medicaid expansion dynamics anchored the trend analysis, supplemented by interviews with maternal-fetal medicine specialists, laboratory directors, regulatory affairs leads at therapeutic developers, and state early-intervention program administrators. Secondary validation drew from FDA guidance documents, ClinicalTrials.gov neurodevelopmental study registrations, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up patient volume modeling and top-down healthcare expenditure triangulation converged on segment-level estimates.
Segment-weighting across product type, end user, care setting, and delivery mode dimensions structured the analytical framework, with therapeutic pipeline stage-gate probabilities and diagnostic test adoption curves informing trajectory assumptions across the projection horizon. CAGRs derived from fitted growth curves applied to baseline expenditure estimates, incorporating viral vector manufacturing capacity constraints and genetic counselor workforce expansion rates as industry-specific forecast inputs.
Revisions become necessary when FDA gene therapy guidance undergoes substantial revision, CMS implements nationwide pediatric complex care coordination reimbursement, or state Medicaid programs harmonize developmental follow-up coverage standards. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Middle East and Africa Down Syndrome Market
Rare Diseases
Rare Neurological Disease Treatment Market
Rare Diseases
Alzheimer Disease Market
Rare Diseases
Global Rare Hemophilia Factors Market
Rare Diseases
Hemophagocytic Lymphohistiocytosis Market
Rare Diseases
Global Guillain-Barre Syndrome Market
Rare Diseases
Prader-Willi Syndrome (PWS) Market
Rare Diseases
Achondrogenesis Market
Rare Diseases
Leigh Syndrome Treatment Market
Rare Diseases
Edward’s Syndrome Treatment Market
Rare Diseases
Andersen-Tawil Syndrome Market
Rare Diseases
Chronic Granulomatous Disease (CGD) Management Market
Rare Diseases
Creutzfeldt-Jakob Disease (CJD) Market
Rare Diseases
Batten Disease Market
Rare Diseases
Glanzmann Thrombasthenia Market
Rare Diseases
Global Tyrosine Hydroxylase Deficiency Market