
 Disposable Acupuncture Needle Market | 2026-2036
Disposable Acupuncture Needle Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Acupuncture Needle Market Insights
Pain management clinics is expanding their adoption of acupuncture protocols as insurers broaden reimbursement for non-pharmacological interventions. SEIRIN Corporation dominates Japanese manufacturing with precision-drawn needle production. Suzhou Hualun Medical Appliance anchors Chinese supply through scale-oriented sterile packaging operations. DongBang Medical Co., Ltd. differentiates via Korean-origin stainless steel sourcing and specialized coating formulations.
A disposable acupuncture needle is a single-use sterile filament, typically manufactured from 304 or 316 stainless steel with diameters ranging from 28G to 34G, designed for percutaneous insertion at specific anatomical points to modulate neurological and circulatory responses. The needle gauge dimension shows 32G and 34G filaments gaining preference in cosmetic and pediatric applications where patient comfort thresholds are lowest. Stainless steel product types sustain the largest volume position, though coated variants command premium positioning through silicone lubrication that reduces insertion resistance. Individual blister packaging controls the clinical channel where sterility assurance and traceability requirements are most stringent.
China's NMPA enforces GB standards for sterile medical device manufacturing, while Japan's PMDA and METI coordinate on JIS-compliant needle specifications that govern export eligibility. The EU MDR and REACH frameworks constrain European market entry through biocompatibility testing and substance restriction protocols. Stakeholders must monitor how divergent sterility validation requirements across FDA, PMDA, and NMPA jurisdictions reshape regional manufacturing footprints and certificate maintenance costs.
Market Dynamics
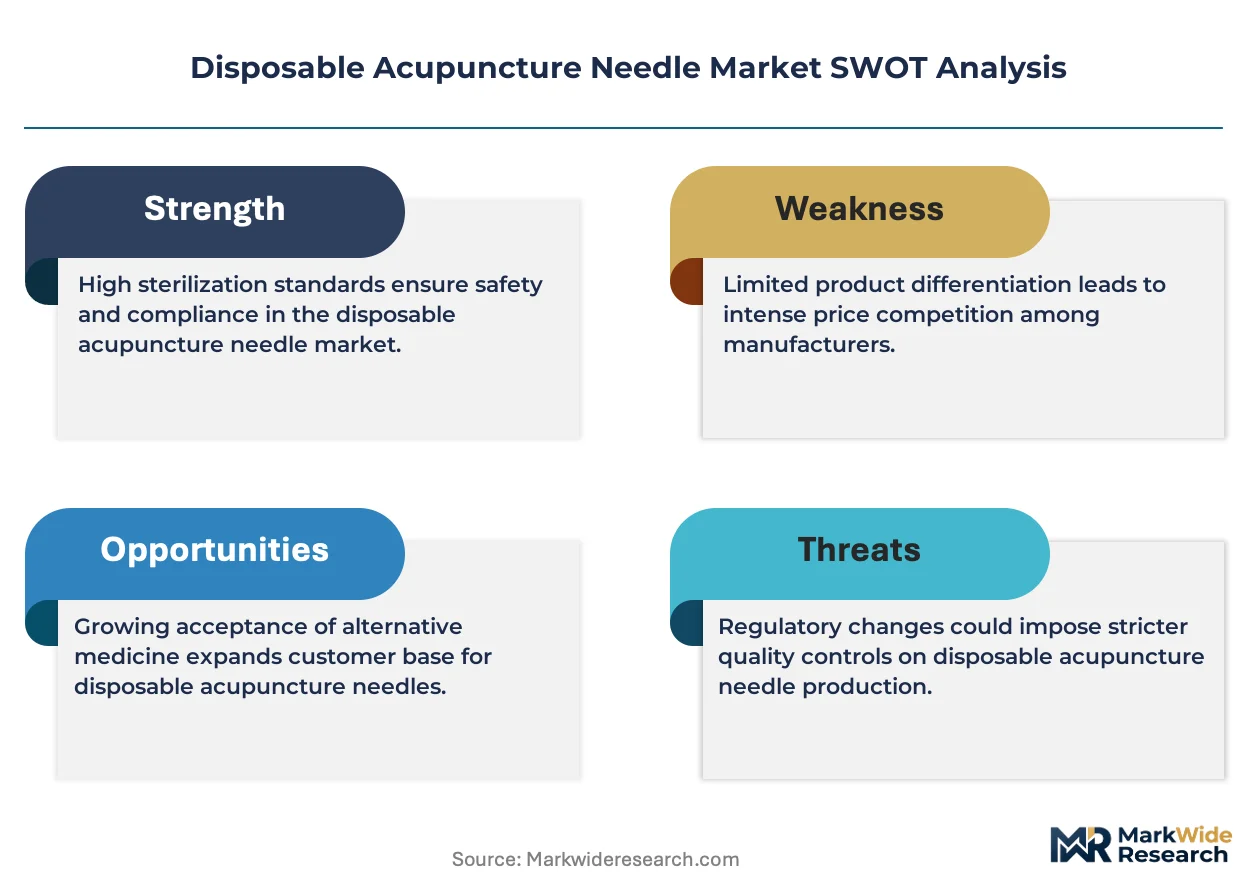
China's NMPA sterile needle standard revisions are compressing domestic manufacturer margins while accelerating consolidation toward ISO 13485-certified producers capable of 316L stainless steel sourcing.
Growth Catalysts
- Opioid prescription restrictions:US pain management clinics are expanding acupuncture service lines as insurers broaden CPT code reimbursement for non-pharmacological interventions.
- National health insurance integration:South Korea's Ministry of Health and Welfare extended acupuncture coverage under the National Health Insurance Service, deepening patient access across tertiary hospitals.
- Coated needle technology:Silicone-lubricated filaments reduce insertion resistance, commanding premium positioning in cosmetic dermatology and pediatric applications where comfort thresholds are lowest.
Market Restraints
- 316L stainless steel price volatility:Korean and Japanese mill sourcing concentrates in Pohang and Kitakyushu, exposing manufacturers to nickel alloy cost swings.
- Supply concentration risk:Sterile packaging film production clusters in Zhejiang province, creating single-geography dependency for blister barrier materials.
- REACH substance restrictions:EU MDR biocompatibility testing and ECHA substance limitations constrain European market entry timelines for Asian exporters.
Strategic Opportunities
- Veterinary acupuncture expansion:Equine sports medicine and companion animal rehabilitation represent underpenetrated end-uses with limited specialized needle suppliers.
- Telemedicine-guided home use:Licensed practitioner remote supervision protocols could unlock direct-to-consumer channels in jurisdictions permitting supervised self-administration.
- Japan's METI green innovation fund:Government incentives for sustainable manufacturing processes support biodegradable packaging material development and energy-efficient sterilization retrofits.
Industry Challenges
- ISO 13485 auditor scarcity:Certification body capacity constraints in East Asia extend quality management system audit wait times, delaying market entry for new entrants.
- Legacy ERP integration:UDHI-compliant traceability systems require substantial middleware investment for manufacturers running on-premise MRP platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Acupuncture Needle Market |
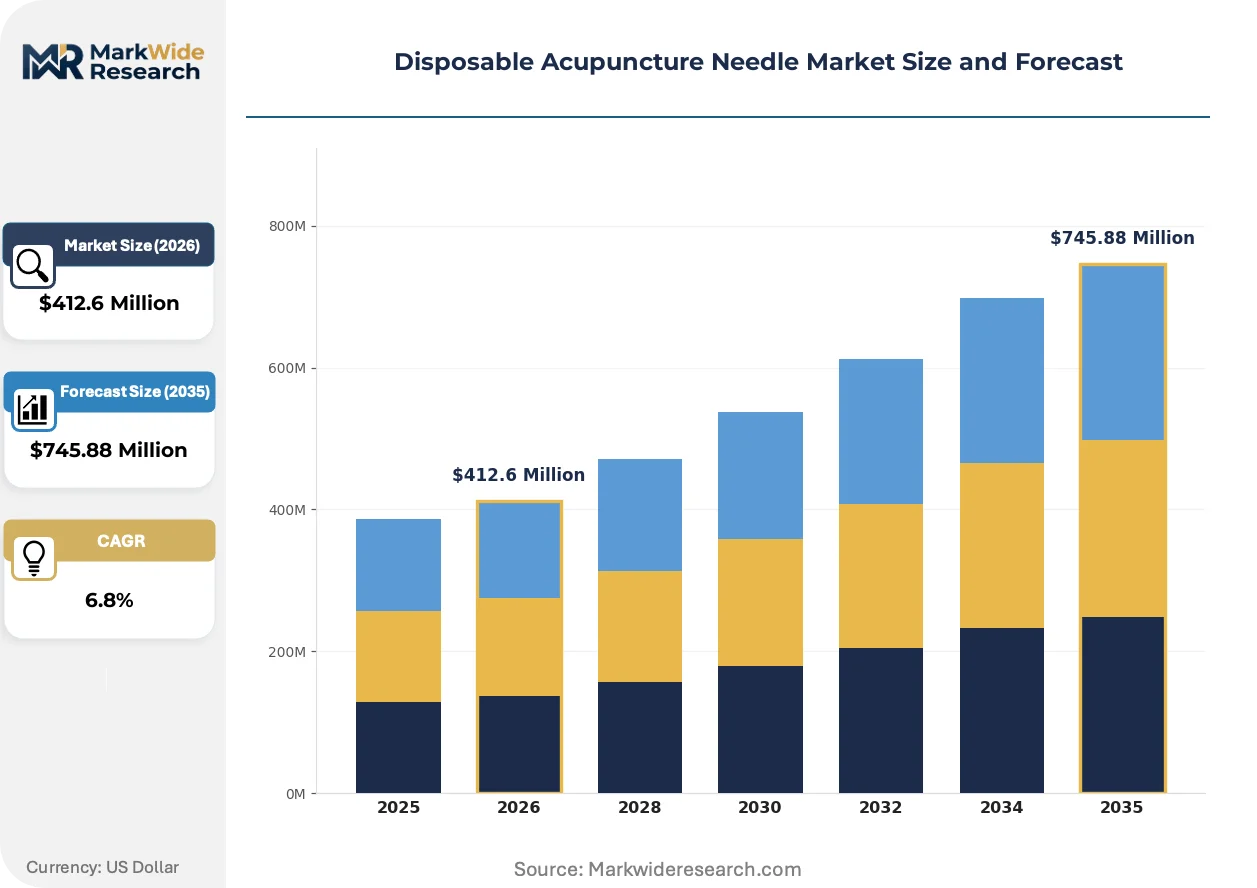
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stainless Steel, Coated, Bunched, Hand-Guide End User: Clinics, Practitioners, Home Use, Hospitals Packaging Type: Sterile Packs, Bulk Packs, Individual Blisters, Boxes Needle Gauge: 28G, 30G, 32G, 34G |
| Companies Covered | SEIRIN Corporation, 3B Scientific GmbH, Suzhou Hualun Medical Appliance, Boen Healthcare Co., Ltd., Suzhou Zhongjing Life & Science Technology Co., Ltd., DongBang Medical Co., Ltd., Wuxi Jiajian Medical Instruments Co., Ltd., AcuMedic Ltd., Changchun AIKANG Medical Devices Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Acupuncture Needle Market Trends and Innovations
Disposable acupuncture needle production is bifurcating between commodity stainless steel volume plays and precision-coated specialty filaments, with regulatory compliance costs now determining competitive viability more than manufacturing scale alone.
Polymer-coated needles with bioabsorbable lubricant layers are expanding into cosmetic dermatology and pain management clinics seeking reduced tissue trauma protocols. Seoul-based aesthetic chains and Tokyo university hospitals are adopting 34G silicone-coated filaments for facial rejuvenation and pediatric applications. This technology is expanding into premium pricing tiers previously occupied by Japanese precision-drawn products, compressing margin differentiation between regional supply bases.
EU MDR biocompatibility testing requirements and REACH substance restriction protocols are extending European market entry timelines for Asian manufacturers. The European Commission's 2021 Medical Device Regulation mandates ISO 10993 cytotoxicity and sensitization documentation previously absent from CE marking pathways. Small-batch sterile needle exporters in Jiangsu and Guangdong provinces are responding by establishing EU authorized representative offices and contracting Notified Body testing ahead of 2027 certificate renewal deadlines.
Hospital procurement departments are consolidating supplier rosters around vendors offering integrated sterile packaging and needle disposal container bundles. German university hospitals and Dutch pain management networks are replacing transactional needle purchases with multi-year framework agreements covering consumables and sharps waste management. This consolidation is most visible in Northern Europe, where sustainability scoring now weights procurement decisions alongside unit cost metrics.
Disposable Acupuncture Needle Market Segmentation
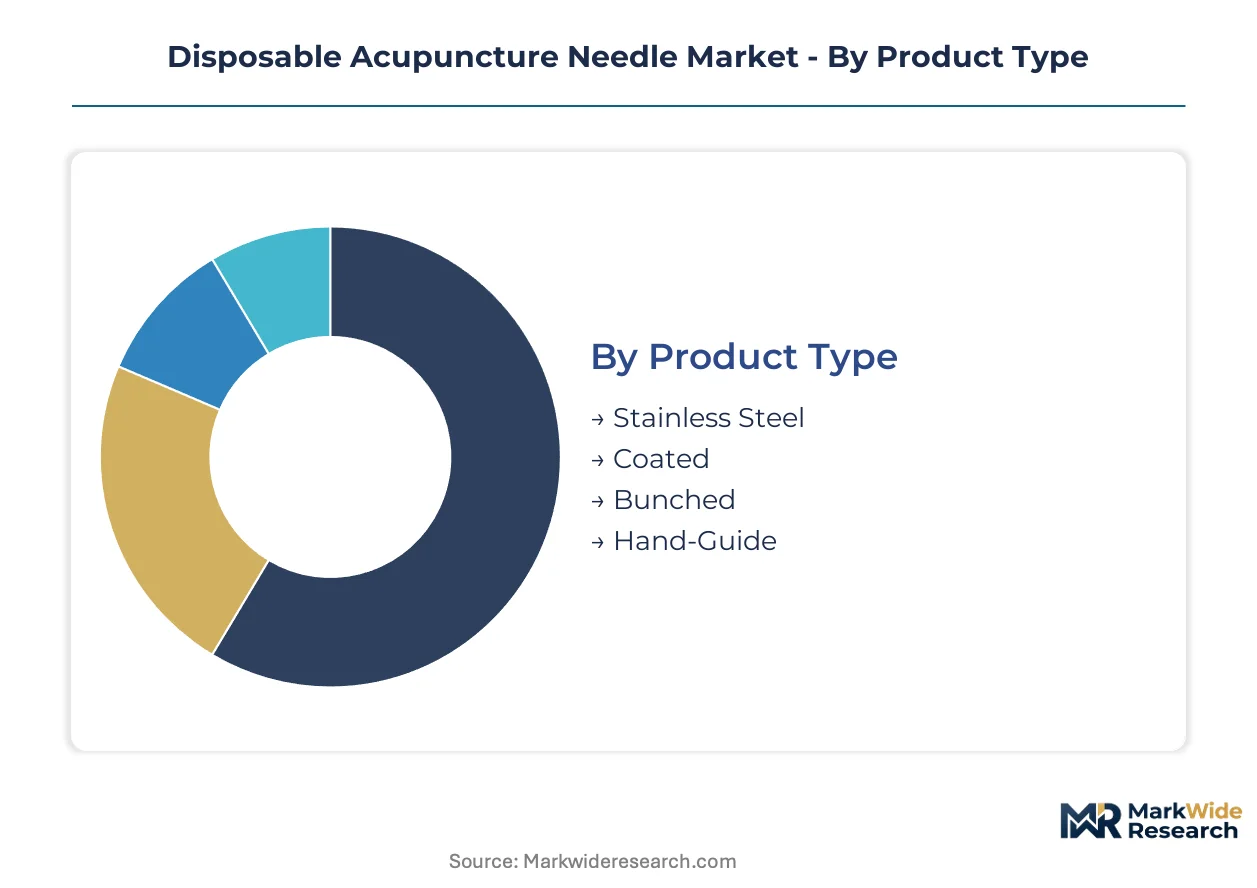
Disposable acupuncture needle manufacturing bifurcates sharply between commodity volume production and precision specialty filaments, with regulatory compliance costs now outweighing economies of scale as the primary competitive determinant. Supply concentration in East Asian stainless steel mills and Zhejiang packaging clusters forces segment-specific sourcing strategies.
Product Type:
Supply concentration in Korean and Japanese steel mills dictates material grade availability across product tiers, compressing margin structures for undifferentiated manufacturers.
- Stainless Steel:304 and 316L grades dominate hospital procurement through ISO 13485-certified production lines. China's NMPA standard revisions are accelerating consolidation toward mills capable of medical-grade certification, displacing commodity 304 suppliers in Jiangsu province.
- Coated:Silicone-lubricated filaments command premium positioning in Seoul aesthetic chains and Tokyo university hospitals where insertion resistance reduction justifies unit cost multiples. METI green innovation incentives support biodegradable lubricant layer development.
- Bunched:Multi-needle arrays serve high-throughput pain management clinics seeking procedural efficiency.
- Hand-Guide:Traditional insertion aids retain niche demand in practitioner training institutions.
Stainless steel absorbs the bulk of installed capacity; coated variants are expanding most quickly.
End User:
Customer type determines sterility assurance requirements and traceability system investments, with hospital procurement demanding UDHI-compliant serialization that excludes smaller manufacturers.
- Clinics:Pain management networks in the US and Germany are consolidating supplier rosters around vendors offering integrated sharps disposal bundles. CPT code reimbursement expansion for non-pharmacological interventions is deepening volume commitments.
- Practitioners:Individual licensed acupuncturists purchase through distributor channels with less stringent serialization requirements.
- Home Use:Telemedicine-guided self-administration protocols remain jurisdictionally constrained, limiting addressable demand to supervised regulatory environments.
- Hospitals:Tertiary institutions in South Korea's National Health Insurance Service network require 316L sourcing documentation and sterile packaging film traceability.
Clinics absorb the bulk of installed capacity; hospital procurement is climbing the fastest.
Packaging Type:
Barrier material supply clusters in Zhejiang province create single-geography dependency that shapes regional manufacturing footprints and certificate maintenance costs.
- Sterile Packs:Ethylene oxide sterilization validation protocols serve EU MDR and FDA jurisdictions with divergent biocompatibility testing requirements.
- Bulk Packs:Volume-oriented configurations serve training institutions and veterinary applications with reduced sterility assurance thresholds.
- Individual Blisters:German university hospitals and Dutch pain management networks mandate this format for sharps waste stream integration. Sustainability scoring now weights procurement decisions alongside unit cost metrics.
- Boxes:Retail-oriented configurations serve direct-to-consumer channels where permitted.
Individual blisters absorb the bulk of installed capacity; sterile packs are gaining share fastest.
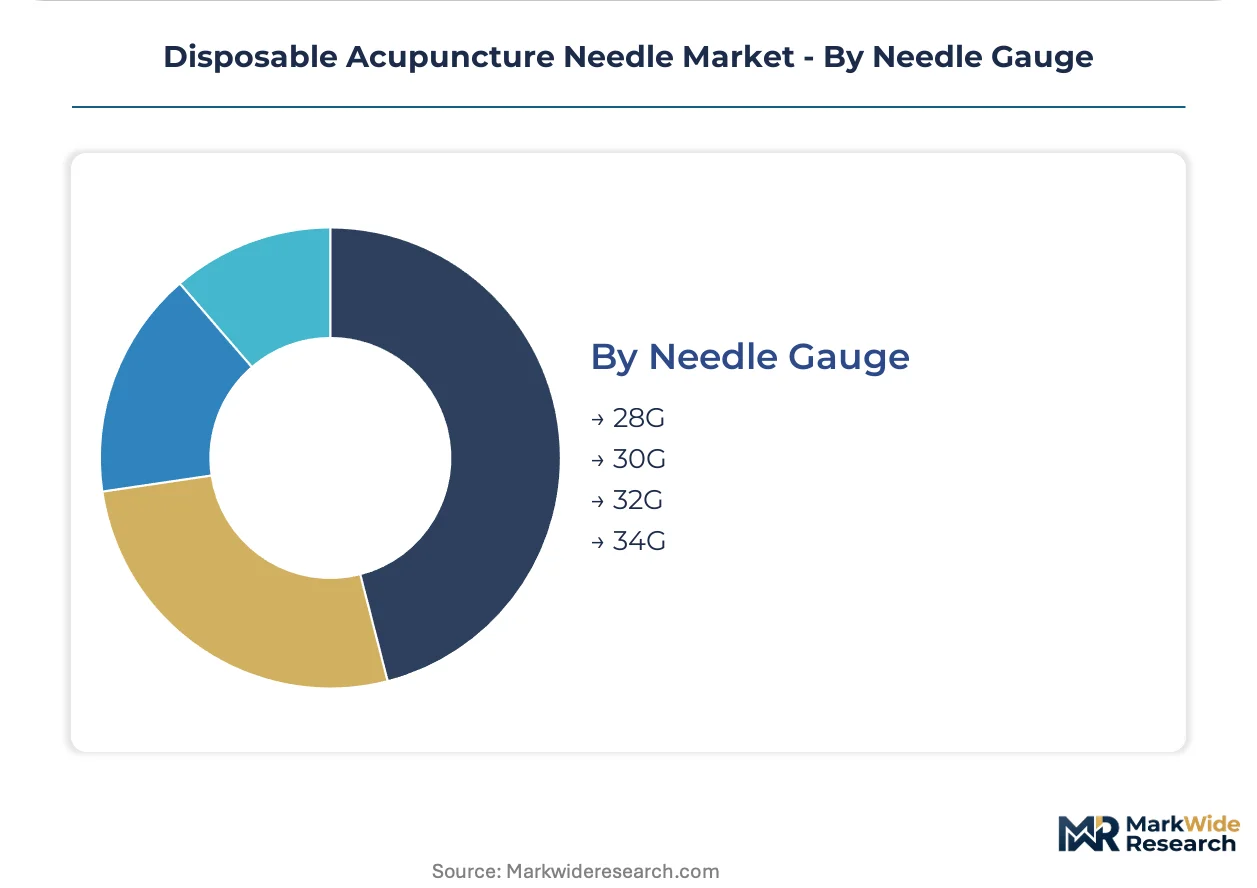
Needle Gauge:
Filament diameter selection concentrates demand in cosmetic and pediatric applications where patient comfort thresholds drive specification preferences.
- 32G:Facial rejuvenation protocols in Seoul aesthetic chains and Tokyo dermatology clinics favor this diameter for reduced tissue trauma. Silicone coating compatibility is highest at this gauge.
- 34G:Pediatric applications and cosmetic dermatology command premium positioning through pain threshold minimization. Japanese precision-drawn production dominates this specification tier.
- 28G:Traditional pain management applications retain volume demand through established insertion techniques.
- 30G:General clinical practice serves as the default specification for mixed-use procurement.
30G absorbs the bulk of installed capacity; 34G is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate sterile needle manufacturing through NMPA-certified production parks in Suzhou and Wuxi. South Korea's free economic zones in Busan and Incheon attract medical device exporters through tariff exemptions and accelerated MFDS approval pathways.
China
Pain management clinics in Beijing and Shanghai drive domestic absorption of 316L-grade filaments. NMPA's 2024 GB standard revisions mandate medical-grade stainless steel sourcing documentation. Suzhou's medical device industrial park hosts concentrated sterile packaging operations serving both domestic hospitals and EU-bound exports.
Japan
Tokyo university hospitals and Osaka cosmetic dermatology chains specify 34G precision-drawn needles for pediatric and facial rejuvenation protocols. METI's green innovation fund subsidizes energy-efficient sterilization retrofits in Kitakyushu steel processing zones. PMDA-JIS coordinated specifications govern export eligibility to European and North American jurisdictions.
South Korea
Seoul's aesthetic clinic networks command premium positioning for silicone-coated 32G filaments. The Ministry of Health and Welfare extended National Health Insurance Service coverage for acupuncture in tertiary hospitals during 2023. Pohang's POSCO steel complex anchors medical-grade stainless supply for domestic needle manufacturers.
Germany
Dutch-German pain management networks in North Rhine-Westphalia consolidate procurement around integrated sharps disposal bundles. EU MDR biocompatibility testing and REACH substance restrictions extend market entry timelines for Asian exporters. Freiburg university hospitals mandate individual blister packaging with sustainability scoring weighted alongside unit cost metrics.
United States
California and New York pain management clinics expand acupuncture service lines as insurers broaden CPT code reimbursement for non-pharmacological interventions. FDA 510(k) pathways for sterile needles require ISO 10993 cytotoxicity documentation. Minnesota's medical device corridor hosts distributors managing import logistics from East Asian manufacturing clusters.
Disposable Acupuncture Needle Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with precision-drawn Japanese producers commanding premium tiers while Chinese scale-oriented fabricators anchor volume positions. The vendor base organizes around three archetypes: ISO 13485-certified precision specialists, NMPA-registered domestic suppliers, and export-oriented contract manufacturers serving European distributors. Consolidation accelerates through strategic partnerships between packaging film producers and needle fabricators, alongside backward integration into medical-grade stainless steel sourcing.
Among East Asian fabricators, SEIRIN Corporation, Suzhou Hualun Medical Appliance, and DongBang Medical Co., Ltd. occupy distinct positioning archetypes. SEIRIN exemplifies the precision-drawn specialist tier with Japanese-origin production credentials. Suzhou Hualun represents scale-oriented sterile packaging integration within China's Yangtze River Delta manufacturing corridor. DongBang Medical anchors Korean-origin supply chains through specialized material sourcing positions. These three entities collectively illustrate how geographic concentration in East Asian steel mills and sterile barrier film production shapes competitive differentiation across regulatory jurisdictions.
| Leading Market Players |
|---|
| SEIRIN Corporation |
| 3B Scientific GmbH |
| Suzhou Hualun Medical Appliance |
| Boen Healthcare Co., Ltd. |
| Suzhou Zhongjing Life & Science Technology Co., Ltd. |
| DongBang Medical Co., Ltd. |
| Wuxi Jiajian Medical Instruments Co., Ltd. |
| AcuMedic Ltd. |
| Changchun AIKANG Medical Devices Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between ISO 13485-certified precision manufacturers and commodity NMPA-registered suppliers manifests in pricing spreads exceeding three-to-one for identical gauge specifications, with supply chain configurations tracking this bifurcation through captive 316L sourcing versus spot-market 304 procurement. Japanese and Korean mills command premium positioning through medical-grade documentation that European hospital procurement mandates, while Chinese fabricators absorb cost compression through Zhejiang packaging cluster integration.
Pricing Analysis
Short lead-time premiums for 316L-grade filaments with full traceability documentation command substantial markups over spot inventory carrying commodity 304 certifications. Three-tier pricing structure across precision-drawn Japanese specialists, ISO-certified Korean producers, and scale-oriented Chinese fabricators reflects certification ladder positioning. Cost compression in the commodity tier is intensifying because NMPA standard revisions force mill-grade upgrades without corresponding reimbursement expansion. Price-sensitive independent practitioners in distributor channels drive volume, while tertiary hospital procurement committees exhibit minimal elasticity for documented 316L sourcing.
Supply Chain Analysis
Freight cost differentials between air-cargo sterile filament shipments and sea-container bulk packaging determine competitive viability for EU-bound exports versus domestic Chinese absorption. Supply concentration in Chinese Yangtze River Delta parks, Korean Busan free economic zones, and Japanese Kitakyushu steel corridors creates geographic clustering around regulatory jurisdiction requirements. Raw material dependencies rest on Pohang and Kitakyushu 316L mill output, Zhejiang ethylene oxide sterilization film production, and silicone lubricant chemical feedstocks. Single-geography vulnerability in sterile barrier film manufacturing exposes manufacturers to regional logistics disruption. Distribution runs through Minnesota medical device corridor distributors for North American hospital networks and direct GPO contracts for German university hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 13485 auditor scarcity across East Asia props pricing power for certified incumbents, constraining new entrant capacity additions regardless of steel mill availability.
For Market Incumbents: Hedge against Korean and Japanese mill supply concentration by securing long-term 316L offtake agreements with alternative certified steel sources in Taiwan or India. Defend margin position through backward integration into captive sterile packaging film production, reducing Zhejiang cluster dependency. Prioritize METI green innovation fund qualification for energy-efficient sterilization retrofits that differentiate bids in sustainability-scored European procurement. For New Entrants and Emerging Players: Direct-to-practitioner e-commerce channels with telemedicine supervision protocols represent the most penetrable route for circumventing hospital procurement consolidation. Target veterinary acupuncture segments in equine sports medicine and companion animal rehabilitation where specialized needle suppliers remain scarce. Pursue white-label manufacturing partnerships with European distributors seeking EU MDR-compliant supply alternatives to established Asian exporters. For Investors and Strategic Acquirers: Re-rating potential sits with precision-drawn specialists possessing PMDA-JIS export credentials given EU MDR timeline compression for Asian commodity suppliers. Long-term viability favors manufacturers with demonstrated 316L sourcing documentation, sterile packaging integration, and multi-jurisdiction regulatory maintenance capabilities. Monitor MFDS approval pathway acceleration in Korean free economic zones as inflection signal for regional competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Auditor scarcity in East Asia extends quality system audit wait times, delaying market entry. |
| 316L Stainless Steel Sourcing Integration | NMPA GB standard revisions displace commodity 304 suppliers lacking medical-grade mill documentation. |
| Biodegradable Packaging Development | METI green innovation subsidies support sustainable sterile barrier materials for EU procurement scoring. |
| Veterinary Acupuncture Product Line | Equine sports medicine and companion animal rehabilitation segments show limited specialized supplier penetration. |
| EU Authorized Representative Establishment | MDR biocompatibility testing mandates force Asian exporters to contract Notified Body validation ahead of deadlines. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital purchasing committee members, GPO contracts managers, biomedical engineers, and sterile needle distributors. NMPA GB standard documentation, FDA 510(k) submission databases, EU MDR Notified Body certificates, and Korean MFDS approval registries provided regulatory pathway validation. Bottom-up volume estimates from mill-grade production data triangulated against top-down procedure volume projections from national health insurance reimbursement statistics.
Granularity-level modeling segmented the market by product type, end user, packaging format, and needle gauge, with regulatory jurisdiction overlays capturing divergent sterility validation requirements. CAGRs derived from procedure volume growth trajectories, reimbursement expansion timelines, and material cost trend assumptions across the projection horizon. Forecast inputs incorporated CPT code reimbursement policy shifts, stainless steel nickel alloy price volatility patterns, and packaging film supply concentration metrics.
The model holds under stable regulatory enforcement intensity and continued national health insurance integration for acupuncture services; deviation in sterilization validation requirement harmonization or raw material export restriction implementation would shift competitive positioning and volume trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Medicine
Cold Laser Therapy Market
Alternative Medicine
Bio Magnetic Ear Stickers Market
Alternative Medicine
Vacuum Cupping Market
Alternative Medicine
US Aromatherapy Market
Alternative Medicine
Traditional Chinese Herbal Medicine Market
Alternative Medicine
Allergy Immunotherapy Market
Alternative Medicine
Orthomolecular Medicine Market
Alternative Medicine
Fire Cupping Market
Alternative Medicine
Aromatherapy Market
Alternative Medicine
Ozone Therapy Units Market
Alternative Medicine
Traditional Chinese Medicine Market
Alternative Medicine
Global Acupuncture Market
Alternative Medicine
Botanicals & Acupuncture Market
Alternative Medicine
Electrotherapy Market
Alternative Medicine
Global OTC Herbal and Traditional Medicine Market
Alternative Medicine
Acupuncture Lasers Market