
 Global OTC Herbal and Traditional Medicine Market | 2026-2036
Global OTC Herbal and Traditional Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Global OTC Herbal and Traditional Medicine Market Foresight
India's Ayurvedic manufacturing corridor is reshaping raw material sourcing for standardized extracts. TSUMURA & CO anchors Japanese kampo production through physician-dispensed channels. Dabur India leverages backward integration into herb cultivation across Rajasthan and Madhya Pradesh. Tong Ren Tang dominates time-honored Beijing formulation retail through hospital-adjacent flagship stores.
OTC herbal and traditional medicine comprises plant-derived, mineral, or animal-origin preparations manufactured through decoction, extraction, or granulation processes to deliver standardized phytochemical doses for self-administered therapeutic use. The category spans multi-ingredient traditional systems and single-herb supplements, with stability testing and marker compound verification ensuring batch-to-batch consistency. Herbal Supplements and Traditional Remedies occupy the largest value pools due to entrenched cultural usage patterns, while Phytopharmaceuticals capture premium pricing through prescription-adjacent positioning. Online Retailers and E-commerce channels represent the fastest-expanding distribution vectors as direct-to-consumer brands bypass conventional pharmacy gatekeepers.
FDA dietary supplement GMPs, EMA herbal monographs, and China's NMPA traditional medicine registration framework collectively determine market access complexity and label claim permissibility. REACH and F-Gas Regulation in Europe additionally constrain solvent-based extraction chemistries, pushing manufacturers toward supercritical CO2 and aqueous methods. Stakeholders must monitor evolving pharmacovigilance obligations as regulators demand post-market safety data for historically exempt traditional preparations.
Market Dynamics
Pharmacovigilance obligations for historically exempt traditional preparations are forcing manufacturers to rebuild quality systems around batch traceability and adverse event reporting infrastructure.
Growth Catalysts
- Aging self-medication patterns:Germany and Japan exhibit pharmacy uptake acceleration as elderly cohorts bypass physician visits for chronic condition management using kampo and phytopharmaceutical formulations.
- EMA herbal monographs:Simplified registration pathways under the EU Traditional Herbal Medicines Directive reduce time-to-market for standardized multi-ingredient preparations.
- Supercritical CO2 extraction:REACH and F-Gas Regulation constraints on solvent-based methods are accelerating adoption of aqueous and supercritical extraction technologies across European manufacturing.
Market Restraints
- Raw material concentration:India's Ayurvedic manufacturing corridor dominates standardized extract sourcing, creating single-geography dependency for global formulators.
- Marker compound verification costs:Stability testing and phytochemical standardization require capital-intensive HPLC and mass spectrometry infrastructure.
- Prescription-adjacent positioning friction:Phytopharmaceuticals face reimbursement complexity when straddling OTC and prescription categories under national health systems.
Strategic Opportunities
- Direct-to-consumer e-commerce:Online Retailers and E-commerce channels enable brand bypass of conventional pharmacy gatekeepers, capturing margin compression from disintermediation.
- Hospital-adjacent retail formats:Flagship stores near medical facilities in Beijing and Tokyo capture physician-referred patient traffic for time-honored formulations.
- Backward integration into cultivation:Captive herb farming in Rajasthan and Madhya Pradesh secures supply chain control over high-value botanical inputs.
Industry Challenges
- Post-market surveillance infrastructure:FDA dietary supplement GMPs and China's NMPA framework now demand systematic adverse event collection, requiring investment in pharmacovigilance databases.
- Extraction chemistry reconfiguration:Transitioning from solvent-based to aqueous and supercritical methods disrupts established process validation protocols and equipment amortization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global OTC Herbal and Traditional Medicine Market |
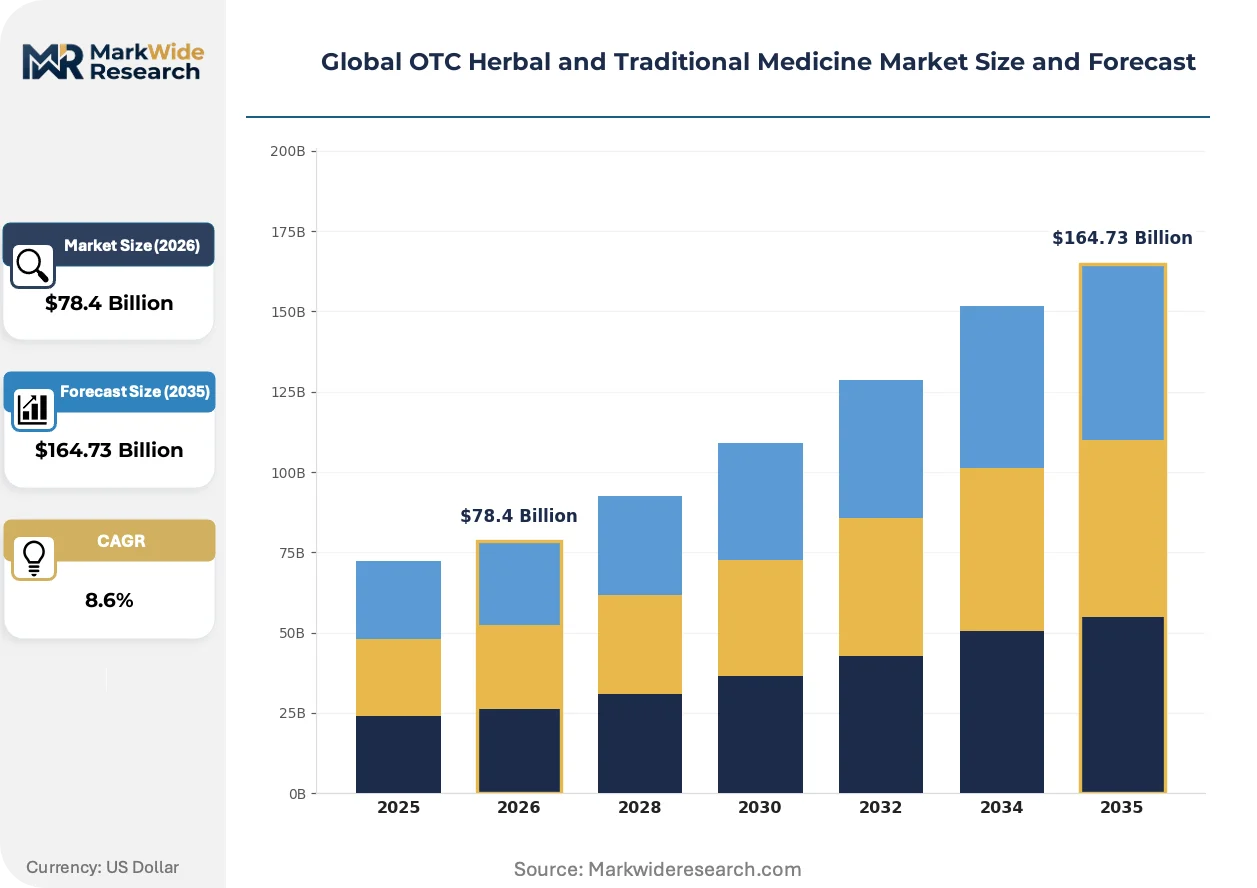
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $164.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Supplements, Traditional Remedies, Nutraceuticals, Phytopharmaceuticals, Homeopathic Products Application: Digestive Health, Respiratory Relief, Skin Care, Immune Support, Stress Management, Women's Wellness End User: Pharmacies, Wellness Centers, Health Food Stores, Online Retailers, Alternative Medicine Clinics Distribution Channel: Direct Sales, E-commerce, Supermarkets, Specialty Stores, Health Practitioner Offices |
| Companies Covered | TSUMURA & CO, Tong Ren Tang, Dabur India, Blackmores Limited, Weleda, Dr. Willmar Schwabe, Herbalife Nutrition, Amway Corporation, The Himalayan Drug Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global OTC Herbal and Traditional Medicine Market Shifts & Advancements
Digital supply chain verification and extraction technology substitution are compressing traditional manufacturing timelines while regulatory frameworks tighten around historical exemptions.
Blockchain-enabled provenance tracking is virtualizing batch documentation for botanical raw materials. German and Japanese importers now mandate chain-of-custody verification for Ayurvedic and kampo ingredients. This technology is virtualizing quality assurance labor while compressing audit preparation cycles from months to days.
China's NMPA traditional medicine registration framework is tightening label claim permissibility for historically unregulated preparations. Manufacturers must now submit pharmacological evidence for indications previously accepted under customary use doctrines. Domestic formulators in Beijing and Shanghai are responding by consolidating multi-product portfolios to amortize registration costs.
Physician-dispensed channels are fragmenting as direct-to-consumer brands capture patient education and loyalty through subscription models. Japanese kampo prescribers face margin compression from online retailers offering identical granule formulations. This channel rotation is most visible in Tokyo and Osaka metropolitan corridors where digital-native demographics dominate chronic condition self-management.
Global OTC Herbal and Traditional Medicine Market Segmentation
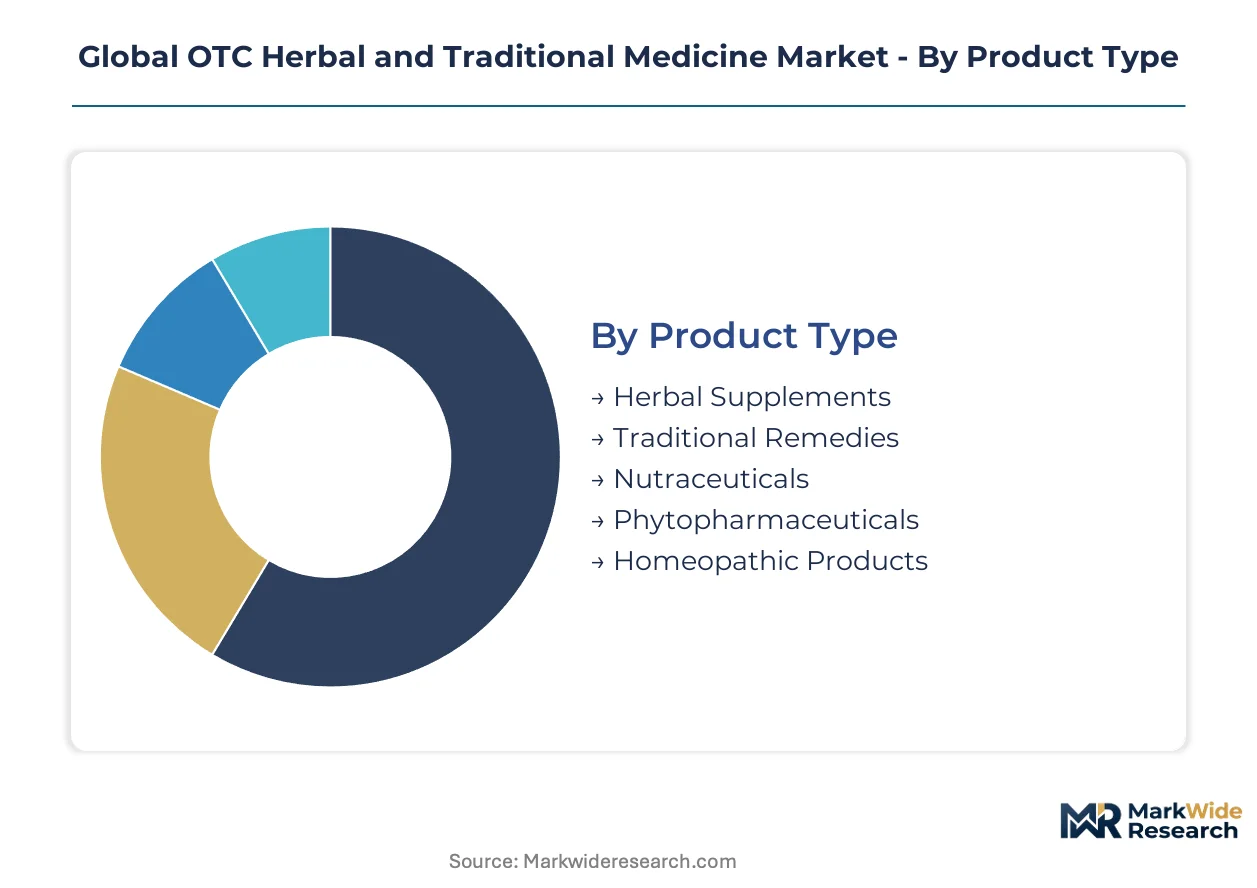
Segmentation in the OTC herbal and traditional medicine market determines formulation complexity, regulatory pathway selection, and channel margin structures. Product type classification governs whether preparations follow dietary supplement or quasi-pharmaceutical compliance frameworks. Distribution channel segmentation increasingly dictates whether brands capture direct consumer relationships or cede margin to pharmacy intermediaries.
Product Type:
After-sales intensity varies sharply across product types, with phytopharmaceuticals requiring pharmacovigilance infrastructure and homeopathic products demanding practitioner education support.
- Herbal Supplements:Single-herb or multi-ingredient botanical preparations standardized to marker compound concentrations, delivered in capsule, tablet, or liquid formats. Demand clusters in Germany and Japan where aging consumers self-manage chronic conditions through pharmacy-purchased formulations. EMA herbal monographs and FDA dietary supplement GMPs govern quality verification, with batch-to-batch consistency enforced through HPLC testing protocols.
- Traditional Remedies:Multi-component preparations rooted in established medical systems including Ayurveda, kampo, and traditional Chinese medicine, manufactured through decoction or granulation processes. East Asian markets exhibit concentrated uptake, with Japanese kampo granules and Chinese classical formulations capturing physician-referred patient traffic in Tokyo and Beijing hospital-adjacent retail. Cultural familiarity drives repeat purchase behavior without clinical consultation.
- Nutraceuticals:Bioactive-enriched functional foods bridging nutritional and therapeutic positioning.
- Phytopharmaceuticals:Prescription-adjacent botanical drugs requiring pharmacological evidence submissions under tightened NMPA and EMA frameworks.
- Homeopathic Products:Highly diluted preparations distributed through practitioner channels with embedded consultation services.
By volume, herbal supplements lead. By growth pace, phytopharmaceuticals are expanding most quickly as regulatory convergence creates premium positioning opportunities.
Application:
Application segmentation maps directly to consumer self-identification pathways, with digestive health and immune support commanding the highest purchase frequency.
- Digestive Health:Probiotic-herb combinations and bitters formulations targeting dyspepsia, irritable bowel patterns, and microbiome modulation. German pharmacy channels exhibit sustained demand for standardized artichoke, milk thistle, and gentian preparations as elderly cohorts bypass physician visits for functional gastrointestinal management.
- Immune Support:Echinacea, astragalus, and medicinal mushroom formulations positioned for seasonal prophylaxis and recovery acceleration. Chinese domestic manufacturers concentrate production in Beijing and Shanghai corridors, exporting standardized extracts to European and North American formulators facing raw material sourcing constraints.
- Respiratory Relief:Expectorant and bronchodilator herbal preparations for cough and congestion management.
- Skin Care:Topical botanicals and nutricosmetics targeting dermatological inflammation and aging.
- Stress Management:Adaptogenic herb formulations for cortisol modulation and sleep architecture support.
- Women's Wellness:Phytoestrogen and cycle-regulating preparations for menopausal and menstrual symptom management.
Digestive health generates the highest absolute volume. Immune support demonstrates the steepest expansion trajectory as post-pandemic prevention behavior persists.
End User:
End user segmentation reveals channel power dynamics, with online retailers disintermediating traditional pharmacy gatekeepers fastest.
- Online Retailers:Direct-to-consumer platforms enabling subscription-based chronic condition management and bypass of conventional pharmacy margin extraction. Japanese kampo granule formulations and Ayurvedic supplements flow through these channels to digital-native demographics in Tokyo and Osaka metropolitan corridors, capturing patient education and loyalty previously held by physician dispensaries.
- Pharmacies:Brick-and-mortar dispensaries with trained staff consultation, dominant in Germany and Japan where regulatory frameworks privilege pharmacy distribution for quasi-pharmaceutical preparations. EMA herbal monograph compliance and national reimbursement complexity create barrier structures favoring established pharmacy networks.
- Wellness Centers:Integrated health facilities combining diagnostic services with botanical therapeutics.
- Health Food Stores:Specialty retail with educated staff and curated premium positioning.
- Alternative Medicine Clinics:Practitioner-directed dispensing of traditional system preparations.
Pharmacies retain volume leadership. Online retailers are gaining share fastest as direct-to-consumer brands compress traditional channel economics.
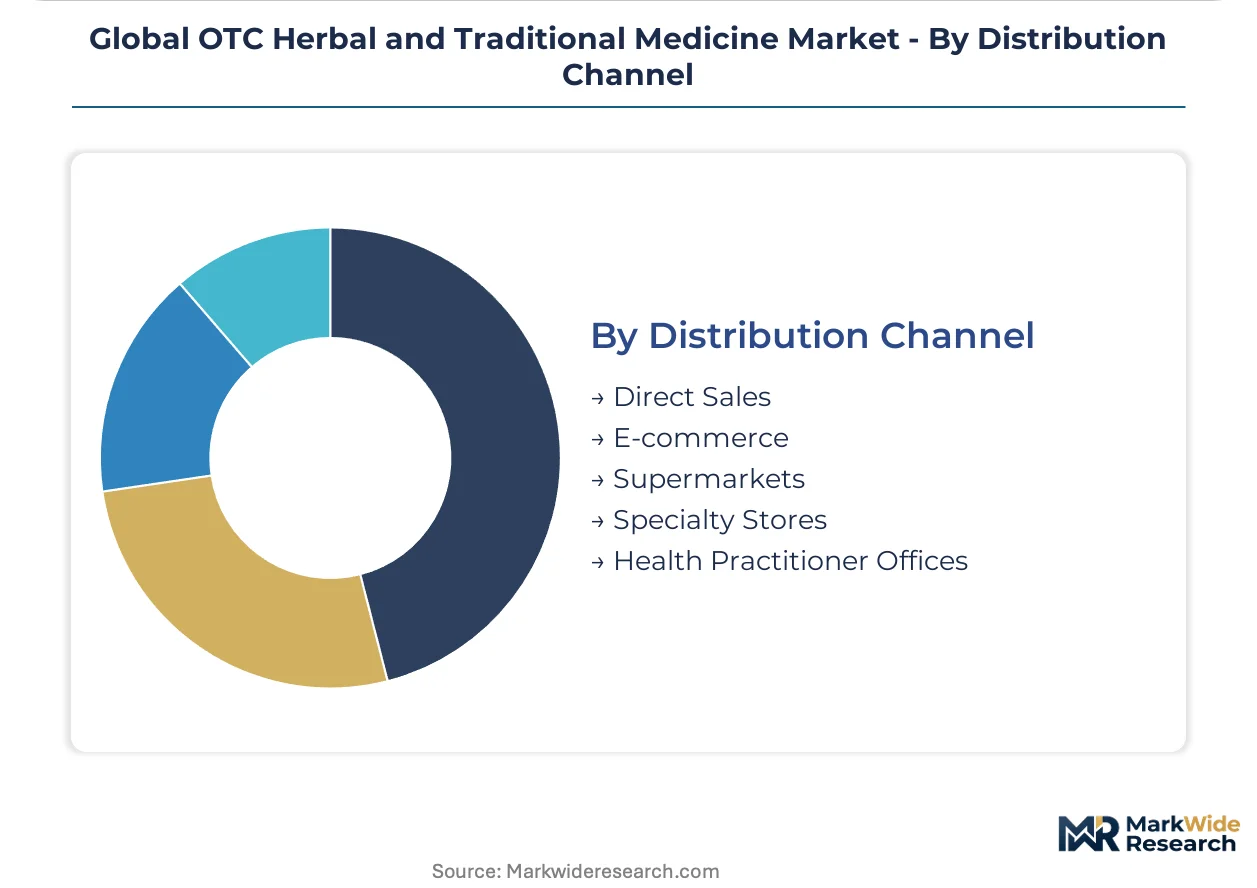
Distribution Channel:
Channel segmentation determines margin capture and regulatory exposure, with e-commerce platforms facing evolving pharmacovigilance obligations for historically exempt preparations.
- E-commerce:Digital platforms with algorithmic personalization and subscription logistics infrastructure. REACH and F-Gas Regulation compliance documentation travels with products into European markets, while China's NMPA registration requirements tighten for cross-border sales of traditional preparations previously accepted under customary use doctrines.
- Direct Sales:Network marketing and practitioner-dispensed channels with embedded education and compliance support.
- Supermarkets:Mass retail with limited staff expertise and price-competitive positioning for commoditized supplements.
- Specialty Stores:Curated retail with category expertise and premium assortment depth.
- Health Practitioner Offices:Physician and alternative provider dispensing with diagnostic integration.
E-commerce leads by volume velocity. Direct sales channels show the most rapid structural adaptation as practitioner networks digitize patient management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Ayurvedic manufacturing corridor dominates standardized extract sourcing for global formulators, while Germany and Japan anchor pharmacy-dispensed consumption. Regulatory fragmentation across FDA, EMA, and NMPA jurisdictions shapes divergent market access pathways.
India
Dabur India's backward integration into herb cultivation across Rajasthan and Madhya Pradesh secures captive supply chains for high-value botanical inputs. CDSCO's tightened traditional medicine registration framework now demands pharmacological evidence submissions previously accepted under customary use doctrines. Manufacturing clusters in Gujarat and Karnataka concentrate decoction and granulation capacity for export markets.
Germany
Aging cohorts bypass physician visits for chronic condition management using phytopharmaceutical formulations from pharmacy channels. EMA herbal monographs streamline registration pathways under the EU Traditional Herbal Medicines Directive, reducing time-to-market for standardized multi-ingredient preparations. Baden-Württemberg and Bavaria host extraction facilities transitioning from solvent-based to supercritical CO2 methods under REACH constraints.
Japan
TSUMURA & CO anchors kampo production through physician-dispensed channels, though digital-native demographics in Tokyo and Osaka increasingly self-medicate via online retailers. PMDA oversight maintains stringent quality verification for granule formulations, with METI promoting standardization of multi-ingredient classical preparations. The Kanto corridor concentrates formulation R&D adjacent to clinical research hospitals.
China
Tong Ren Tang dominates time-honored Beijing formulation retail through hospital-adjacent flagship stores capturing physician-referred patient traffic. NMPA's tightening label claim permissibility forces domestic formulators to consolidate multi-product portfolios and amortize registration costs. The Yangtze River Delta and Pearl River Delta clusters concentrate extraction capacity for export-grade standardized extracts.
United States
FDA dietary supplement GMPs govern quality verification for botanical preparations, with pharmacovigilance obligations now demanding systematic adverse event collection infrastructure. Direct-to-consumer brands bypass conventional pharmacy gatekeepers through algorithmic personalization and subscription logistics. California and New York metro areas anchor digital-native brand headquarters and e-commerce fulfillment networks.
Global OTC Herbal and Traditional Medicine Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The market exhibits tiered consolidation around vertically integrated Ayurvedic manufacturers, Japanese kampo houses with physician channel lock-in, and direct-to-consumer digital brands disintermediating traditional pharmacy networks. Three archetypes dominate: heritage traditional medicine houses with cultivation-to-retail control, pharmaceutical-adjacent botanical drug developers, and algorithmic direct-to-consumer formulators. Competitive moves center on backward integration into herb farming and extraction chemistry reconfiguration toward aqueous and supercritical methods.
Within the heritage traditional medicine tier, TSUMURA & CO and Tong Ren Tang exemplify physician-channel anchoring through granule formulation standardization, while Dabur India represents captive supply chain control via Rajasthan and Madhya Pradesh cultivation estates. These three occupy positions that blend cultural brand equity with regulatory compliance infrastructure across FDA, EMA, and NMPA jurisdictions.
| Leading Market Players |
|---|
| TSUMURA & CO |
| Tong Ren Tang |
| Dabur India |
| Blackmores Limited |
| Weleda |
| Dr. Willmar Schwabe |
| Herbalife Nutrition |
| Amway Corporation |
| The Himalayan Drug Company |
| Others |
Supply & Pricing Matrix
Gujarat's Ayurvedic extraction clusters concentrate decoction capacity for global formulators, compressing procurement timelines while amplifying buyer leverage over raw material premiums. This geographic concentration feeds directly into tiered pricing structures downstream, where EMA herbal monograph compliance and FDA dietary supplement GMP certification separate premium phytopharmaceutical positioning from commoditized single-herb supplements.
Pricing Analysis
EMA herbal monographs and FDA dietary supplement GMPs dictate the pricing tier structure across the Global OTC Herbal and Traditional Medicine Market. Three-tier pricing stratifies across premium phytopharmaceuticals with pharmacovigilance infrastructure, standard multi-ingredient traditional remedies with regional registration, and economy single-herb supplements with basic stability testing. Price differentiation hinges on certification grade and marker compound verification depth. Cost compression in standard tiers intensifies as Indian and Chinese manufacturers expand aqueous extraction capacity. Digital-native demographics in Tokyo and Osaka metropolitan corridors exhibit lowest price sensitivity for subscription-based kampo formulations, while mass-market supplement buyers in German supermarket channels drive hardest bargain hunting.
Supply Chain Analysis
Botanical raw material sourcing draws from India's Rajasthan and Madhya Pradesh cultivation estates, China's Yangtze River Delta extraction clusters, and Japan's Hokkaido medicinal plant cooperatives. Critical inputs span standardized artichoke and milk thistle extracts, kampo granule base materials, and supercritical CO2 processing equipment. Single-source vulnerability concentrates in India's Ayurvedic manufacturing corridor, where captive herb farming by integrated players limits spot market liquidity. Distribution runs through hospital-adjacent flagship stores in Beijing and Tokyo, pharmacy networks in Germany, and direct-to-consumer e-commerce platforms with algorithmic personalization infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern patient acquisition as direct-to-consumer brands capture chronic condition management relationships through subscription logistics, displacing physician-dispensed channel loyalty that anchored Japanese kampo and Chinese traditional medicine for decades. Interoperability between blockchain-enabled provenance verification and e-commerce personalization engines creates new ecosystem control points.
For Market Incumbents: Pre-empt channel fragmentation by consolidating physician network digitization before direct-to-consumer brands capture patient education infrastructure. TSUMURA & CO and Tong Ren Tang must accelerate backward integration into captive herb cultivation to defend margin position against spot market volatility. Investment in supercritical CO2 extraction capacity under REACH and F-Gas Regulation constraints secures regulatory compliance as a competitive moat.
For New Entrants and Emerging Players: Mid-market Ayurvedic supplements in North American e-commerce represent the most penetrable entry point, bypassing pharmacy gatekeeper economics that entrench European and East Asian incumbents. Subscription-based chronic condition management for digestive health and immune support captures recurring revenue without clinical consultation overhead. Go-to-market execution should anchor in algorithmic personalization platforms with pharmacovigilance database integration.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory compliance infrastructure play because pharmacovigilance obligations for historically exempt traditional preparations force capital-intensive quality system rebuilds across the industry. Acquisition targets should profile vertically integrated manufacturers with captive cultivation estates and multi-jurisdiction registration portfolios. The signal to watch is NMPA enforcement intensity against cross-border e-commerce sellers previously operating under customary use doctrines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Dabur India's Rajasthan estates secure supply chain control over high-value botanical inputs for standardized extract production. |
| Supercritical CO2 Extraction Transition | REACH and F-Gas Regulation constraints accelerate solvent-free chemistry adoption across European manufacturing facilities. |
| Direct-to-Consumer E-commerce Launch | Subscription logistics bypass pharmacy margin extraction while capturing patient loyalty through algorithmic personalization. |
| Pharmacovigilance Infrastructure Buildout | FDA dietary supplement GMPs and NMPA frameworks now demand systematic adverse event collection databases. |
| Blockchain Provenance Verification | German and Japanese importers mandate chain-of-custody documentation compressing audit preparation cycles from months to days. |
Research Methodology
The analysis maps herbal supplements, traditional remedies, phytopharmaceuticals, and homeopathic products, each validated through regulatory affairs directors at EMA-notified bodies, CDSCO registration consultants, PMDA compliance officers, and procurement managers at German pharmacy chains. Primary interviews with formulation R&D heads and extraction technology suppliers combined with secondary validation against FDA Warning Letters, EMA herbal monograph databases, NMPA registration filings, and CDSCO traditional medicine approval records. Bottom-up volume modeling across product types and top-down macroeconomic reconciliation ensured triangulation integrity.
Assumptions held fixed include regulatory enforcement intensity across FDA, EMA, and NMPA jurisdictions, raw material availability from Indian and Chinese cultivation clusters, and pharmacy channel share retention in Germany and Japan. Variables stress-tested encompass REACH extraction chemistry transition timelines, cross-border e-commerce regulatory tightening, and physician-dispensed channel fragmentation rates. Segmentation dimensions modeled span product type complexity, application indication, end-user channel power, and geographic regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for structural inflection points in channel economics and compliance cost amortization patterns.
Stress conditions across pharmacovigilance infrastructure investment requirements, supercritical CO2 equipment lead times, and NMPA label claim evidentiary thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with acknowledged sensitivity to regulatory enforcement acceleration and raw material sourcing disruption. Cross-checking against customs trade data for standardized extract flows and hospital procurement database trends for physician-dispensed formulations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Medicine
Global Complementary and Alternative Medicines Market
Alternative Medicine
US Aromatherapy Market
Alternative Medicine
Orthomolecular Medicine Market
Alternative Medicine
Natural Cold, Cough, and Sore Throat Remedies Market
Alternative Medicine
Complementary and Alternative Medicine for Anti Aging and Longevity Market
Alternative Medicine
Global Homeopathic Product Market
Alternative Medicine
US Chiropractic Market
Alternative Medicine
Traditional Chinese Medicine Market
Alternative Medicine
Flower Essences Market
Alternative Medicine
Biopuncture Treatment Market
Alternative Medicine
Vacuum Cupping Market
Alternative Medicine
Homeopathy Products Market
Alternative Medicine
Ozone Therapy Units Market
Alternative Medicine
Global Acupuncture Market
Alternative Medicine
Cold Laser Therapy Market
Alternative Medicine
Fire Cupping Market