
 Traditional Chinese Medicine Market | 2026-2036
Traditional Chinese Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Traditional Chinese Medicine Market Outlook
The gap between premium authenticated materia medica and commodity-grade herbal substitutes is recalibrating procurement standards across the supply chain. Beijing Tong Ren Tang leverages its imperial pharmacy heritage and vertically controlled cultivation bases to sustain price premiums on endangered species replacements. Yunnan Baiyao Group anchors its position through proprietary trauma formulations that dominate hospital formulary slots in southwestern China. Tianjin Zhongxin Pharmaceutical competes via modernized extraction facilities that supply standardized active fractions to European phytomedicine distributors.
Traditional Chinese Medicine encompasses botanical preparations, mineral compounds, and physical intervention modalities governed by syndrome differentiation principles and documented in classical pharmacopeias such as the Shennong Bencao Jing. Manufacturing integrates decoction concentration, ethanol extraction, and granule spray-drying to achieve batch-to-batch marker compound consistency for clinical deployment. Herbal Remedies command the dominant value share, though margin pools increasingly shift toward Acupuncture Devices as reimbursement codes expand in Western European integrative clinics. Pain Management applications outpace other therapeutic indications, driven by opioid-sparing protocols in perioperative and chronic musculoskeletal settings. Distribution through Specialty Stores retains higher per-unit economics than Online Retail, where price transparency erodes branded premium positioning.
China's NMPA enforces Good Agricultural Practice for Chinese Crude Drugs and Pharmacopoeia of the People's Republic of China monograph standards that dictate market access for domestic producers. The WHO Traditional Medicine Strategy and ISO/TC 249 technical specifications on acupuncture needle manufacturing create parallel compliance layers for export-oriented manufacturers. Stakeholders must monitor how FDA botanical drug guidance evolution and EMA herbal medicinal product registration requirements reshape competitive viability for standardized versus whole-herb formulations in Western markets.
Market Dynamics
China's NMPA streamlining of botanical drug registration is compressing approval timelines for standardized herbal formulations, forcing raw material suppliers to upgrade traceability systems or lose hospital formulary access.
Growth Catalysts
- Germany's Statutory Health Insurance Expansion:Chronic disease management programs now reimburse select herbal formulations, validating TCM protocols within Europe's largest healthcare market.
- ISO/TC 249 Technical Specifications:Harmonized acupuncture needle manufacturing standards are unlocking bulk procurement contracts from Western European integrative clinic chains.
- Opioid-Sparing Perioperative Protocols:Anesthesiology departments in tertiary hospitals are embedding acupuncture into multimodal pain management pathways.
Market Restraints
- Authenticated Materia Medica Scarcity:Premium-grade herbal substitutes command 3-4x commodity pricing, squeezing margin structures for mid-tier manufacturers.
- EMA Herbal Medicinal Product Registration Complexity:Whole-herb formulations face protracted safety documentation requirements that standardized extracts bypass.
- Synthetic Analgesic Substitution:Reformulated NSAIDs and neuropathic pain agents compete directly for musculoskeletal indication market access.
Strategic Opportunities
- EMA Simplified Registration Pathways:Well-established traditional use provisions create faster market entry for documented classical formulations.
- Telemedicine-Integrated Herbal Consultation:Digital TCM diagnostic platforms are opening direct-to-patient channels beyond physical clinic footprints.
- Metabolomics-Guided Extraction:Converging phytochemical profiling with AI-driven batch optimization is enabling personalized granule formulation at scale.
Industry Challenges
- Classical Formulation Authentication Expertise:Shortage of practitioners trained in syndrome differentiation limits clinical trial design quality for regulatory submissions.
- Dual Carbon Compliance Costs:Decoction concentration and ethanol extraction facilities face MEE emissions retrofit requirements that strain capex budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traditional Chinese Medicine Market |
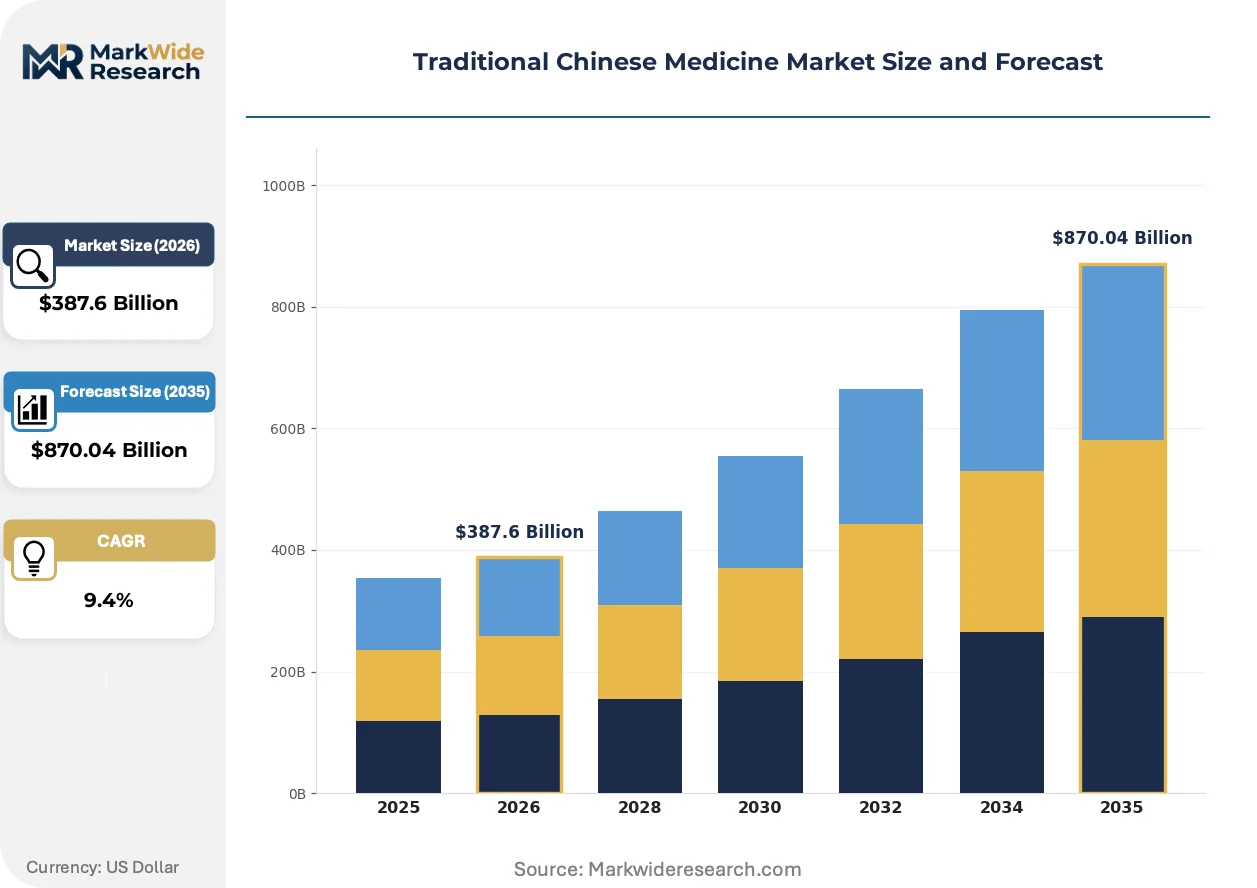
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $870.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Remedies, Acupuncture Devices, Cupping Therapy, Moxibustion Products Application: Pain Management, Digestive Wellness, Stress Relief, Immune Support Distribution Channel: Online Retail, Specialty Stores, Health Food Outlets, Pharmacies Customer Type: Individuals, Healthcare Professionals, Wellness Centers, Fitness Enthusiasts |
| Companies Covered | China Resources Pharmaceutical Group, Tianjin Zhongxin Pharmaceutical, Beijing Tong Ren Tang, Guangyuyuan, Shandong Buchang Pharmaceuticals, Yunnan Baiyao Group, Tasly Pharmaceutical, Harbin Pharmaceutical Group, Shanghai Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traditional Chinese Medicine Market Strategic Shifts
Digital phytochemical fingerprinting and blockchain-backed provenance systems are rewriting how botanical integrity gets verified before formulation, collapsing traditional quality assurance timelines.
Chromatography-linked metabolomic profiling is electrifying batch consistency verification for granule manufacturers. Tier-one hospital pharmacies in Shanghai and Guangzhou now mandate full-spectrum marker compound certificates. This technology is compressing supplier qualification cycles from months to weeks.
WHO Traditional Medicine Strategy implementation is reshaping national regulatory frameworks across Southeast Asian health ministries. Domestic manufacturers must align with both NMPA Pharmacopoeia standards and export destination monographs. European phytomedicine distributors are responding by demanding dual-certified active fractions.
Hospital procurement departments are consolidating herbal supplier rosters around vertically integrated cultivators with captive GAP-certified growing bases. Specialty retail channels retain patient trust through practitioner-staffed consultation counters. Japan's Kampo medicine reimbursement system offers a template for outcome-based herbal prescribing that Western European insurers are piloting.
Traditional Chinese Medicine Market Segmentation
Segmentation in Traditional Chinese Medicine reflects divergent clinical validation levels and procurement authority structures. Buyers range from hospital formulary committees with pharmacoeconomic mandates to self-directed consumers seeking wellness augmentation.
Product Type:
Procurement authority distinguishes institutional buyers seeking pharmacopoeia-grade consistency from retail consumers prioritizing convenience formats.
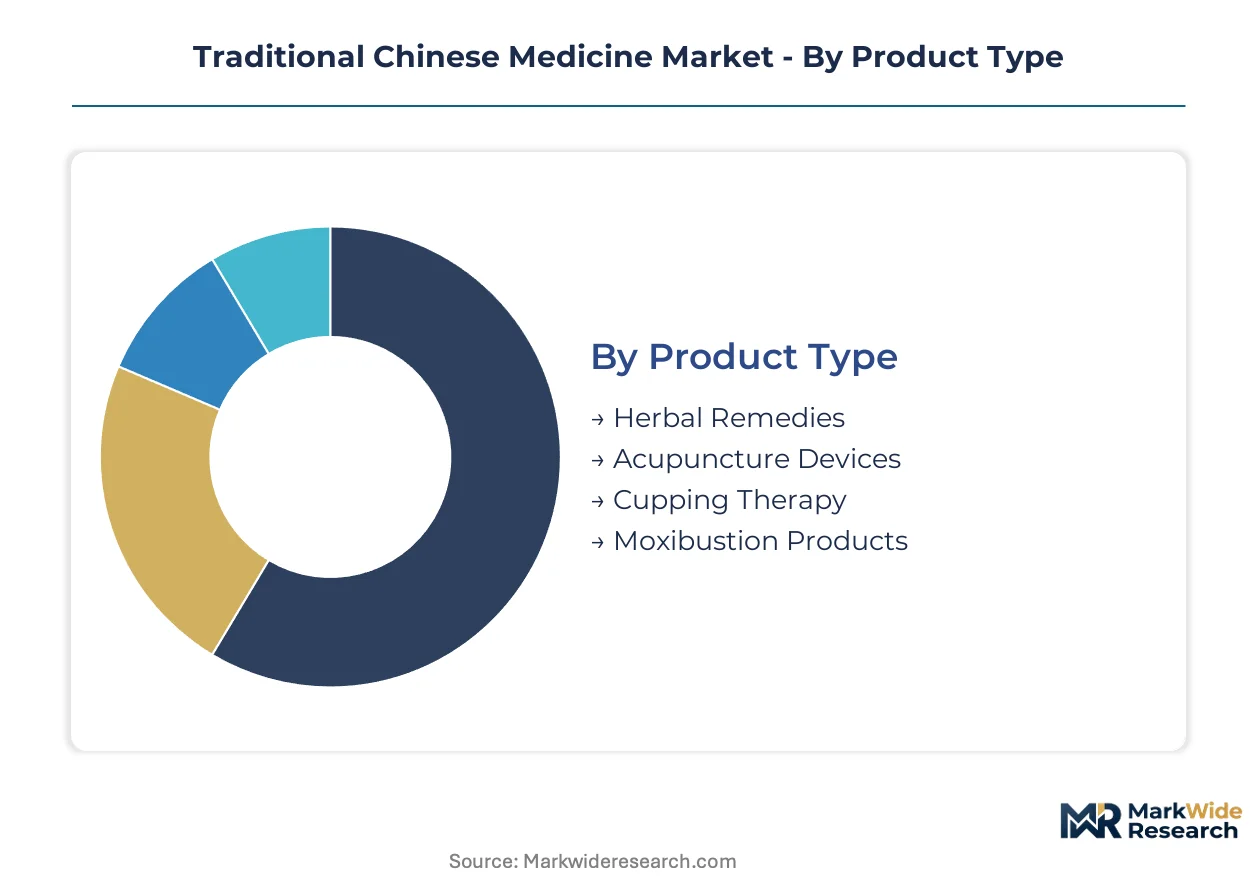
- Herbal Remedies:Decoctions, granules, and patent medicines standardized to Pharmacopoeia of the People's Republic of China monographs. Hospital pharmacies in Shanghai and Guangzhou now mandate full-spectrum marker compound certificates from suppliers, compressing qualification cycles from months to weeks.
- Acupuncture Devices:ISO/TC 249-compliant needles, electroacupuncture stimulators, and laser acupuncture systems. Western European integrative clinic chains are unlocking bulk procurement contracts as harmonized manufacturing standards reduce liability exposure.
- Cupping Therapy:Silicone, glass, and vacuum pump systems for myofascial decompression. Sports medicine departments in Germany's rehabilitation hospitals are embedding cupping into perioperative recovery protocols.
- Moxibustion Products:Mugwort rolls, smokeless sticks, and infrared moxa devices. Japanese Kampo practitioners favor indirect moxibustion for chronic fatigue syndromes, sustaining import demand for premium-grade mugwort from China's Henan province.
Volume sits with Herbal Remedies; growth tilts toward Acupuncture Devices.
Application:
Reimbursement coding density varies sharply across therapeutic indications, concentrating procurement volume where clinical evidence meets payer mandates.
- Pain Management:Acupuncture and herbal formulations for musculoskeletal, neuropathic, and perioperative pain. Germany's statutory health insurance expansion for chronic disease management programs validates TCM protocols within Europe's largest healthcare market.
- Stress Relief:Adaptogenic herbal stacks and auricular acupuncture for anxiety disorders. Corporate wellness programs in South Korea's chaebol conglomerates are subsidizing workplace acupuncture clinics as productivity interventions.
- Digestive Wellness:Prokinetic herbal combinations and abdominal acupuncture for functional disorders. China's NMPA streamlined botanical drug registration accelerates domestic innovation in gastroenterology indications.
- Immune Support:Tonic formulations and moxibustion protocols for recurrent infection prevention. Post-pandemic demand concentrates in East Asian metropolitan corridors where integrative hospital departments combine classical formulas with conventional oncology protocols.
Pain Management commands the dominant value share; Stress Relief is climbing the fastest as employer-sponsored wellness budgets expand.
Distribution Channel:
Price transparency and consultation depth trade off differently across channel formats, fragmenting brand premium capture.
- Specialty Stores:Practitioner-staffed consultation counters with diagnostic equipment and custom granule compounding. Beijing Tong Ren Tang leverages its imperial pharmacy heritage to sustain price premiums through vertically controlled cultivation bases.
- Online Retail:Direct-to-consumer platforms with algorithmic TCM diagnostic questionnaires. Price transparency erodes branded premium positioning, compressing margin structures for mid-tier manufacturers.
- Pharmacies:OTC herbal products and device resale with pharmacist counseling. European phytomedicine distributors demand dual-certified active fractions meeting both NMPA Pharmacopoeia and EMA herbal medicinal product standards.
- Health Food Outlets:General wellness positioning with limited clinical claims. Yunnan Baiyao Group anchors shelf presence through proprietary trauma formulations that dominate hospital formulary slots in southwestern China.
Specialty Stores retain higher per-unit economics; Online Retail is gaining share fastest as telemedicine-integrated herbal consultation platforms mature.
Customer Type:
Technical sophistication and batch consistency requirements scale with clinical liability exposure.
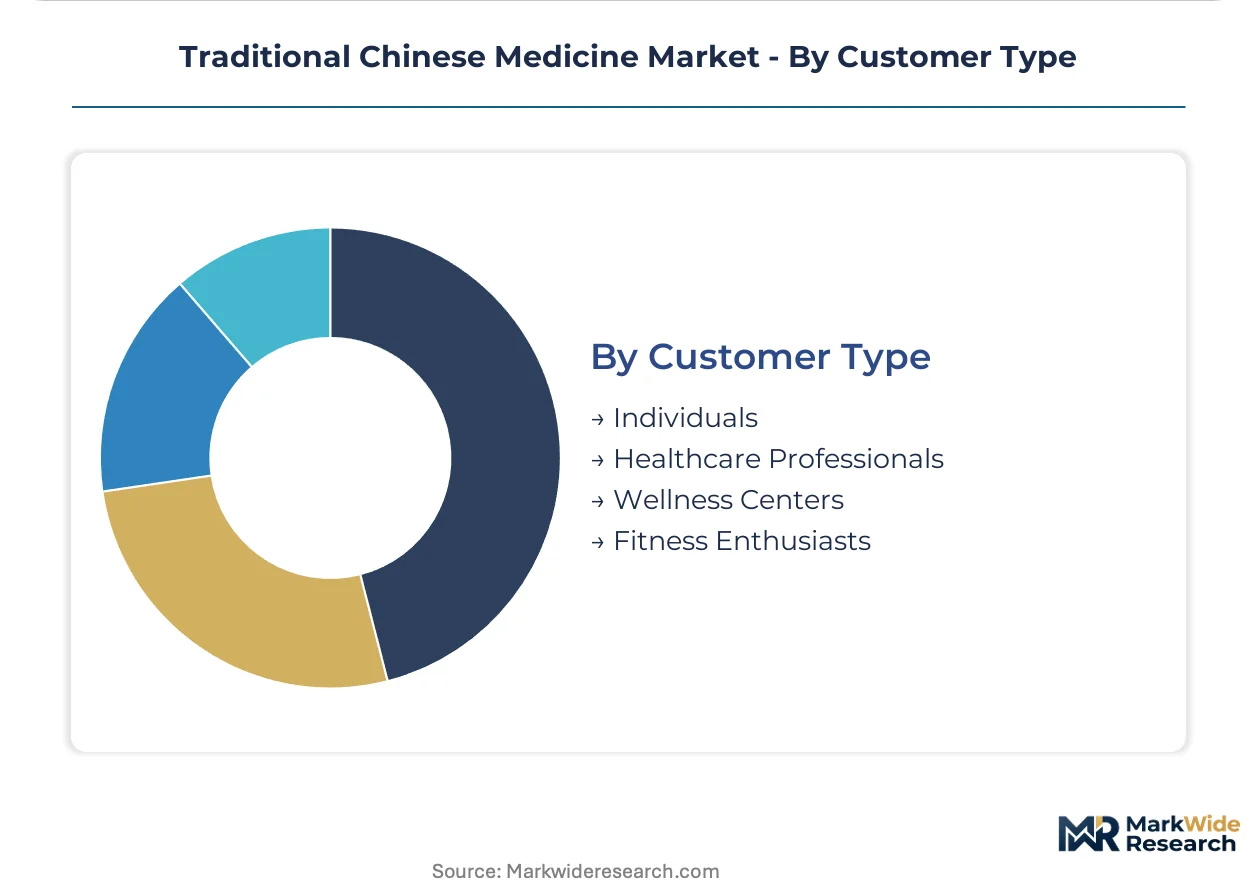
- Healthcare Professionals:Licensed acupuncturists and integrative physicians requiring GMP-certified supplies with full traceability documentation. Tianjin Zhongxin Pharmaceutical competes via modernized extraction facilities supplying standardized active fractions to European phytomedicine distributors.
- Wellness Centers:Spa and retreat operators seeking experiential differentiation through authentic TCM modalities. Procurement prioritizes aesthetic packaging and simplified training protocols over pharmacological precision.
- Individuals:Self-directed consumers purchasing for home use based on online research and peer recommendation. Digital TCM diagnostic platforms are opening direct-to-patient channels beyond physical clinic footprints.
- Fitness Enthusiasts:Athletes and recreational exercisers adopting cupping and acupuncture for recovery optimization. Sports medicine adoption in Germany's rehabilitation hospitals validates clinical credibility for this segment.
Healthcare Professionals anchor procurement volume; Individuals are expanding most quickly as smartphone-based syndrome differentiation tools proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors procurement volume for authenticated materia medica, with tertiary hospital pharmacies mandating full-spectrum marker compound certificates that compress supplier qualification cycles from months to weeks.
China
East Asian metropolitan corridors concentrate demand where integrative hospital departments combine acupuncture with conventional oncology protocols. NMPA streamlining of botanical drug registration accelerates domestic innovation while enforcing Good Agricultural Practice for Chinese Crude Drugs. Beijing-Tianjin-Hebei and the Yangtze River Delta host vertically integrated cultivators with captive GAP-certified growing bases supplying hospital procurement departments.
Germany
Chronic disease management programs reimburse select herbal formulations under statutory health insurance, validating TCM protocols within Europe's largest healthcare market. EMA herbal medicinal product registration requirements reshape competitive viability for standardized versus whole-herb formulations. Sports medicine departments in rehabilitation hospitals embed cupping into perioperative recovery protocols, anchoring clinical credibility.
Japan
Kampo medicine reimbursement system offers a template for outcome-based herbal prescribing that Western European insurers pilot. PMDA oversight of traditional use provisions creates faster market entry for documented classical formulations. Kansai region practitioners favor indirect moxibustion for chronic fatigue syndromes, sustaining import demand for premium-grade mugwort from Henan province.
South Korea
Corporate wellness programs in chaebol conglomerates subsidize workplace acupuncture clinics as productivity interventions. MFDS alignment with WHO Traditional Medicine Strategy reshapes national regulatory frameworks for domestic manufacturers. Seoul Capital Area digital TCM diagnostic platforms open direct-to-patient channels beyond physical clinic footprints.
United States
Anesthesiology departments in tertiary hospitals embed acupuncture into multimodal pain management pathways as opioid-sparing protocols expand. FDA botanical drug guidance evolution determines competitive viability for export-oriented manufacturers. Pacific Northwest integrative clinic chains unlock bulk procurement contracts as harmonized ISO/TC 249 standards reduce liability exposure.
Traditional Chinese Medicine Market Competitive Environment
Premium-margin players sit above commodity-margin players across authentication-grade materia medica sourcing, with imperial pharmacy heritage and vertically controlled cultivation bases sustaining price premiums on endangered species replacements. The vendor base stratifies into three tiers: heritage-brand incumbents with captive supply chains, modernized extraction specialists supplying standardized active fractions to European distributors, and regional granule manufacturers competing on price. Strategic moves concentrate on backward integration into GAP-certified growing bases and technology licensing for metabolomics-guided extraction systems.
Among heritage-brand incumbents, Beijing Tong Ren Tang occupies a position exemplifying imperial pharmacy lineage and vertically controlled cultivation. Yunnan Baiyao Group anchors the proprietary formulation tier through trauma-focused hospital formulary presence. Tianjin Zhongxin Pharmaceutical sits within the modernized extraction specialist archetype, supplying standardized active fractions. These three represent distinct competitive vectors: heritage authentication, proprietary clinical positioning, and technical standardization for export markets.
| Leading Market Players |
|---|
| China Resources Pharmaceutical Group |
| Tianjin Zhongxin Pharmaceutical |
| Beijing Tong Ren Tang |
| Guangyuyuan |
| Shandong Buchang Pharmaceuticals |
| Yunnan Baiyao Group |
| Tasly Pharmaceutical |
| Harbin Pharmaceutical Group |
| Shanghai Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Authenticated materia medica scarcity propagates through three distinct pricing tiers, with GAP-certified cultivation bases in Henan and Yunnan provinces commanding premiums that commodity-grade substitutes cannot match downstream. Hospital procurement departments in Shanghai and Guangzhou now mandate full-spectrum marker compound certificates, compressing supplier qualification cycles and collapsing traditional quality assurance timelines into weeks rather than months.
Pricing Analysis
Outcome-based prescribing anchors value capture in Japan's Kampo reimbursement system, where documented clinical efficacy sustains price premiums unavailable to unverified formulations. Three-tier pricing structure across pharmacopoeia-grade, GAP-certified, and commodity-grade levels separates Beijing Tong Ren Tang's heritage authentication from mid-tier granule manufacturers competing on volume. Cost compression in the commodity tier intensifies as online retail price transparency erodes branded positioning. Self-directed consumers purchasing through direct-to-consumer platforms exhibit highest price sensitivity, while hospital formulary committees prioritize batch consistency over unit cost.
Supply Chain Analysis
Dual-sourcing requirements now dominate procurement protocols as hospital pharmacies mandate redundant supplier qualification for critical herbal inputs. Geographic concentration centers on China, Japan, and Germany, with Henan province's mugwort cultivation and Yunnan's proprietary trauma formulations anchoring upstream supply. Raw material dependencies include endangered species replacements, ethanol extraction solvents, and ISO/TC 249-compliant acupuncture needle alloys. Single-source vulnerability persists for imperial pharmacy heritage brands with captive cultivation bases. Distribution runs through vertically integrated cultivators supplying hospital procurement departments, specialty retail channels with practitioner-staffed counters, and telemedicine-integrated platforms opening direct-to-patient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Authenticated materia medica scarcity props pricing across all tiers, with GAP-certified cultivation capacity acting as the binding constraint that heritage-brand incumbents exploit to sustain margin structures.
For Market Incumbents: Extend backward integration into captive GAP-certified growing bases in Henan and Yunnan provinces before mid-tier competitors secure land access. Invest in metabolomics-guided extraction systems to defend against standardized active fraction suppliers penetrating European phytomedicine distribution. Certification investment in dual NMPA-EMA compliance creates switching costs that lock hospital formulary slots against emerging domestic rivals. For New Entrants and Emerging Players: Begin with telemedicine-integrated herbal consultation platforms targeting self-directed consumers in South Korea's Seoul Capital Area, where smartphone-based syndrome differentiation tools proliferate fastest. Corporate wellness programs in chaebol conglomerates represent the most penetrable buyer segment, with employer-sponsored acupuncture clinics subsidized as productivity interventions. Digital diagnostic platforms bypass physical clinic footprint requirements that incumbents have spent decades building. For Investors and Strategic Acquirers: NMPA streamlining of botanical drug registration timelines is the leading indicator that domestic innovation capacity is accelerating beyond heritage-brand control. Five-to-ten year viability favors modernized extraction specialists supplying standardized active fractions to European distributors over regional granule manufacturers competing on price. Watch for EMA simplified registration pathway announcements for well-established traditional use provisions as the signal that export-oriented acquisition targets are de-risking.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into GAP-Certified Cultivation | Henan and Yunnan land access locks supply of authenticated materia medica for hospital formulary retention. |
| Metabolomics-Guided Extraction System Licensing | AI-driven batch optimization enables personalized granule formulation at scale for European phytomedicine distributors. |
| Dual NMPA-EMA Certification Investment | Parallel compliance layers unlock bulk procurement contracts from Western European integrative clinic chains. |
| Telemedicine-Integrated Herbal Consultation Launch | Digital diagnostic platforms open direct-to-patient channels beyond physical clinic footprints in Seoul Capital Area. |
| Blockchain-Backed Provenance System Deployment | Digital phytochemical fingerprinting collapses supplier qualification cycles from months to weeks for Shanghai hospital pharmacies. |
Study Parameters
Regulatory filings from NMPA, EMA, and PMDA, pharmacopeia monograph databases, and WHO Traditional Medicine Strategy implementation documents formed the secondary backbone of this analysis. Primary interviews with hospital procurement managers, licensed acupuncturists, integrative physicians, GMP-certified supplier quality directors, and European phytomedicine distributors combined with secondary validation through bottom-up and top-down triangulation. Customs records for mugwort and endangered species replacement materials supplemented trade flow analysis across export corridors.
Bottom-up modeling aggregated segment-level demand from product type, application, distribution channel, and customer type dimensions, while top-down validation cross-checked against national health expenditure patterns and reimbursement code expansion trajectories. CAGRs were derived from regression analysis of historical adoption curves and policy inflection points across the projection horizon. Forecast inputs included ISO/TC 249 standard implementation timelines, EMA herbal medicinal product registration queue data, and NMPA botanical drug approval velocity metrics.
Regulatory guidance evolution, authenticated materia medica harvest volatility, and reimbursement code expansion delays are the dominant revision risks to the outlook. Deviation in NMPA streamlining implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Medicine
Orthomolecular Medicine Market
Alternative Medicine
Ozone Therapy Units Market
Alternative Medicine
Disposable Acupuncture Needle Market
Alternative Medicine
Homeopathic Medicine Market
Alternative Medicine
Homeopathy Products Market
Alternative Medicine
Aromatherapy Market
Alternative Medicine
Natural Cold, Cough, and Sore Throat Remedies Market
Alternative Medicine
Global OTC Herbal and Traditional Medicine Market
Alternative Medicine
Acupuncture Lasers Market
Alternative Medicine
Biopuncture Treatment Market
Alternative Medicine
Global Acupuncture Market
Alternative Medicine
US Chiropractic Market
Alternative Medicine
Botanicals & Acupuncture Market
Alternative Medicine
Europe Complementary and Alternative Medicine Market
Alternative Medicine
Traditional Chinese Herbal Medicine Market
Alternative Medicine
Vacuum Cupping Market