
 Fire Cupping Market | 2026-2036
Fire Cupping Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Cupping Market Insights
Buyer concentration is realigning as wellness centers and sports medicine clinics consolidate purchasing power while home-use channels fragment across e-commerce platforms. Kangzhu leverages its manufacturing scale to supply bulk orders to hospital-affiliated rehabilitation centers. Hwato sustains brand recognition among traditional Chinese medicine practitioners through specialized glass cupping sets. BeiJing GuoYiYan Medical Technology and Medical Instrument CO.,LTD anchors its position with regulatory-compliant product lines targeting clinical certification requirements.
Fire cupping employs heated glass, silicone, bamboo, or plastic vessels applied to skin to create localized suction for therapeutic blood flow modulation, with glass vessels requiring flame-based deoxygenation to generate negative pressure between 0.03 and 0.06 MPa. Dry cupping dominates clinical volume due to standardized protocols and lower infection risk, while wet cupping retains specialized demand in traditional medicine settings where practitioners maintain bloodletting licensure. Silicone cups capture expanding home-use share because of portability and self-application safety, whereas glass sets command premium positioning in certified therapeutic environments where thermal durability and visibility of skin response matter.
China's NMPA and SAMR enforce GB standards for traditional medical device materials and sterilization, while EU MDR and CE marking govern clinical cupping equipment marketed as therapeutic devices in France, Germany, and Italy. FDA oversight in the United States classifies cupping sets as Class I medical devices when labeled for pain relief, creating divergent compliance pathways that manufacturers must navigate. Stakeholders should monitor evolving medical device reclassification movements in major jurisdictions that could shift cupping products from wellness accessories to regulated therapeutic instruments with attendant quality system requirements.
Market Dynamics
Medical device reclassification movements across major jurisdictions are compressing compliance timelines for cupping manufacturers, forcing simultaneous adaptation to divergent quality system requirements in China, the European Union, and the United States.
Growth Catalysts
- EU MDR clinical device pathways:Wellness centers in France and Germany are expanding therapeutic cupping menus under CE marking requirements, creating procurement pull for certified glass cupping sets.
- Home-use portability demand:Silicone cupping sets are capturing self-application segments through e-commerce channels, driven by consumer preference for lightweight, flame-free operation.
- NMPA quality standard enforcement:China's tightened GB standards for traditional medical devices are elevating product quality baselines, filtering substandard suppliers from hospital procurement pools.
Market Restraints
- Borosilicate glass supply concentration:Thermal-grade glass vessel production clusters in specific Chinese manufacturing zones, creating input vulnerability for premium cupping set producers.
- FDA Class I device friction:Pain relief labeling triggers medical device classification in the United States, imposing quality system burdens that deter wellness-oriented market entrants.
- Negative pressure calibration limits:Silicone cups face technical constraints achieving the 0.03-0.06 MPa suction range consistently without flame-based deoxygenation, restricting clinical equivalence claims.
Strategic Opportunities
- Sports medicine clinic verticals:Rehabilitation centers affiliated with professional athletic organizations are establishing dedicated cupping therapy protocols, creating institutional demand for standardized glass sets.
- Integrated TCM-physiotherapy models:Convergence of traditional Chinese medicine certification with Western physical therapy licensure is opening hybrid practice settings in Germany and Italy.
- Direct-to-clinic distribution platforms:Specialized procurement portals are disintermediating traditional medical supply distributors for certified therapeutic cupping equipment.
Industry Challenges
- Cross-jurisdictional compliance talent:Manufacturers face acute scarcity of regulatory affairs specialists capable of navigating simultaneous NMPA, FDA, and EU MDR submission pathways.
- Sterilization validation timelines:Autoclave-compatible silicone formulations require extended biocompatibility testing cycles that delay product launches in clinical-certified segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Cupping Market |
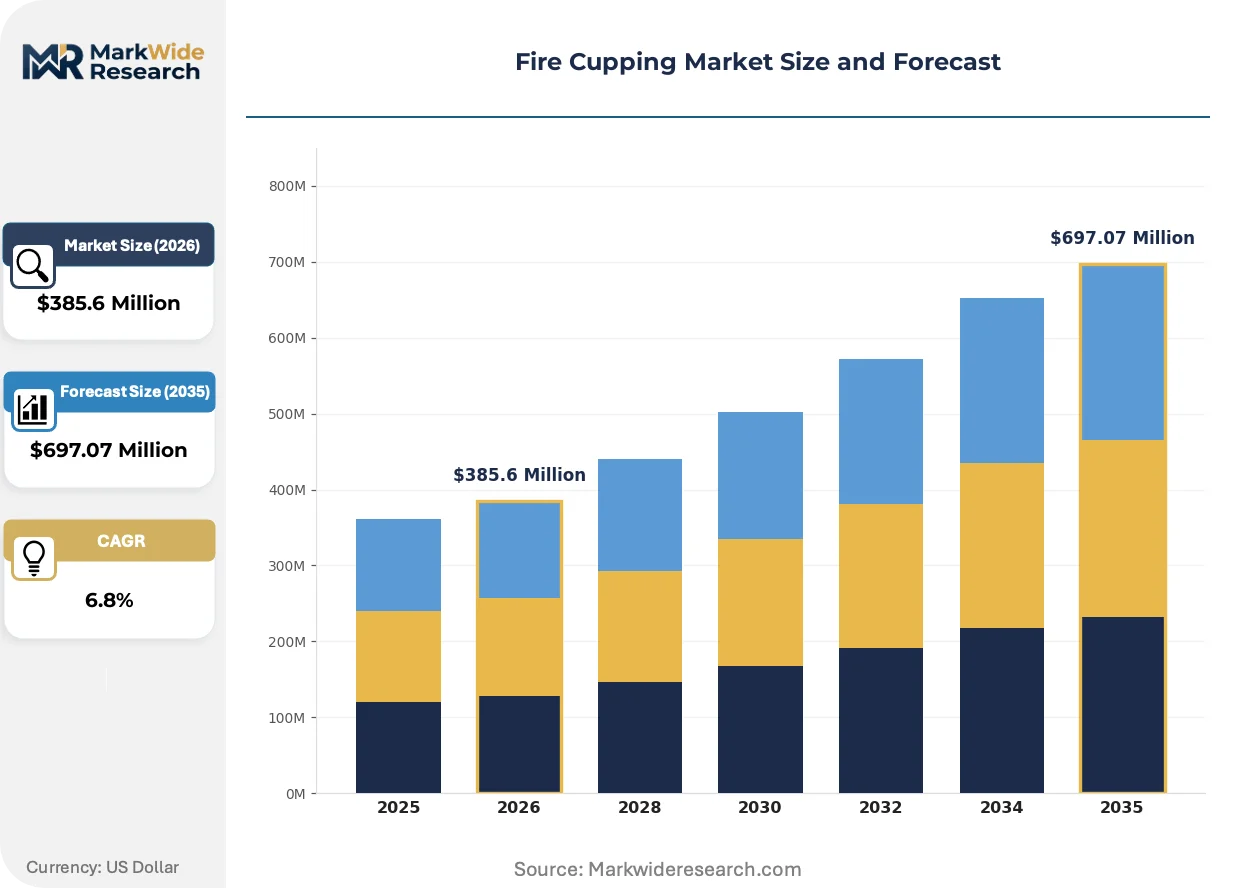
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technique: Wet Cupping, Dry Cupping, Flash Cupping, Moving Cupping Application: Pain Relief, Muscle Relaxation, Detoxification, Rehabilitation Material: Glass, Silicone, Bamboo, Plastic End User: Clinics, Wellness Centers, Sport Teams, Home Users |
| Companies Covered | Kangzhu, Hwato, BeiJing GuoYiYan Medical Technology and Medical Instrument CO.,LTD, Mengshibaguan, FOLEE, Huamingkangtaiu, YiFang, OuMaiAShi, Cofoe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Cupping Market Trends and Innovations
Active reshaping in fire cupping centers on material science substitution, regulatory framework convergence pressures, and the fragmentation of procurement authority between institutional buyers and direct-to-consumer channels.
Silicone cupping technology is expanding into flame-free therapeutic applications through vacuum pump integration and flexible rim designs that conform to body contours. Sports medicine clinics and physical therapy practices are adopting these sets at accelerating rates for patient self-management protocols. This material transition is expanding into home-use segments previously dominated by glass sets, compressing the addressable market for traditional flame-based equipment.
EU MDR medical device classification is tightening clinical claims verification for cupping equipment marketed with therapeutic indications. Manufacturers must now maintain technical documentation and post-market surveillance systems comparable to Class IIa devices regardless of actual risk classification. French and German wellness center chains are responding by segregating procurement streams between certified medical-grade glass sets and unregulated wellness accessories.
Buyer concentration in hospital-affiliated rehabilitation centers is fragmenting traditional distributor relationships as these institutions develop direct sourcing capabilities for certified therapeutic equipment. E-commerce platforms are simultaneously capturing dispersed home-use demand through specialized traditional medicine marketplaces. This bifurcation is most visible in China, where NMPA-registered products flow through clinic procurement channels while unregistered silicone sets dominate consumer platforms.
Fire Cupping Market Segmentation
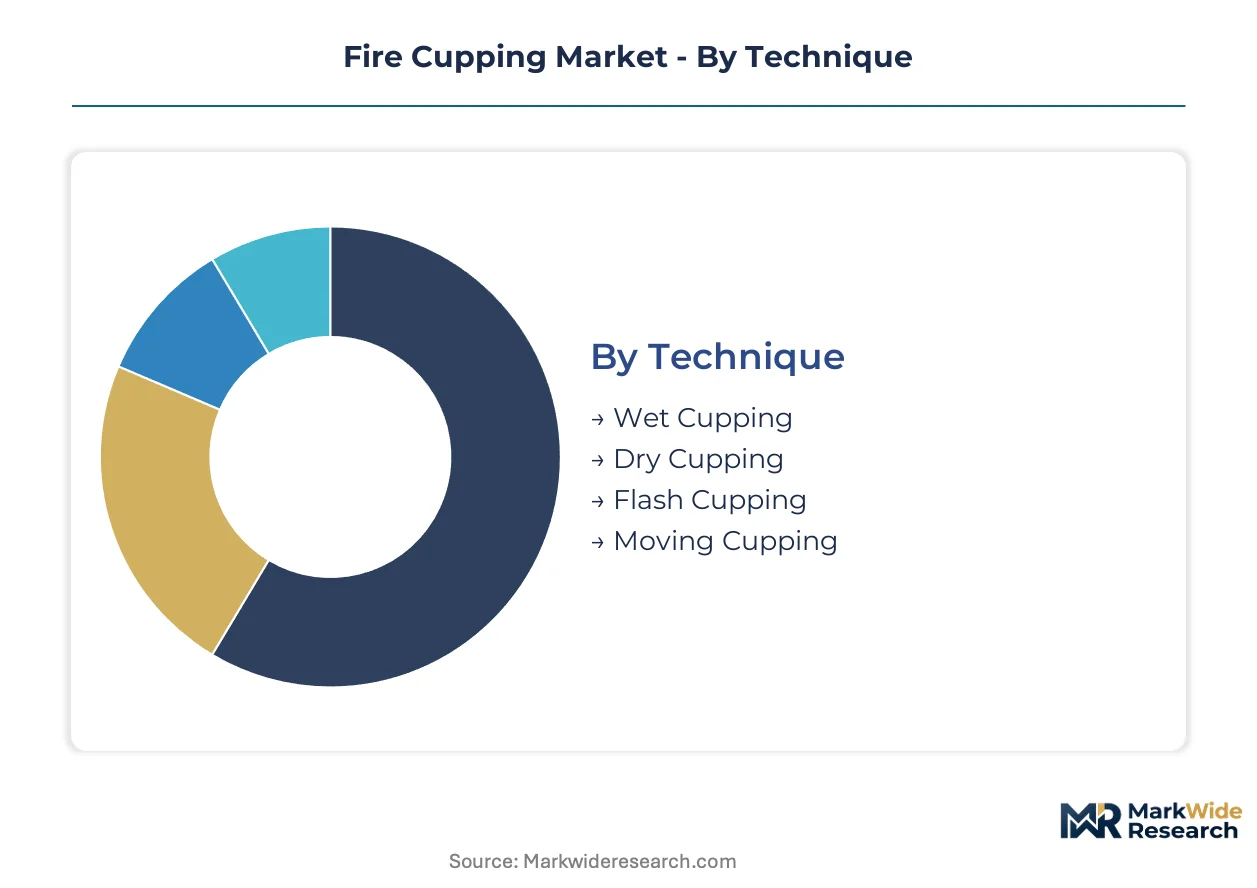
Fire cupping segmentation reveals divergent compliance and procurement pathways across therapeutic settings. Material choices determine regulatory classification, while technique selection dictates practitioner licensure requirements and reimbursement eligibility.
Technique:
Dry cupping operates as the standalone foundation across clinical protocols, whereas wet cupping demands embedded integration with bloodletting licensure frameworks.
- Wet Cupping:Practitioners perform controlled incisions before suction application, requiring specialized bloodletting certification in jurisdictions like Germany and Saudi Arabia. Demand clusters in traditional medicine institutes where practitioners maintain dual TCM-Western licensure, constrained by sterilization validation burdens that extend procurement cycles.
- Dry Cupping:Flame or vacuum-generated suction without skin penetration dominates hospital-affiliated rehabilitation centers. France's wellness center chains standardize on this technique for CE-marked equipment procurement, bypassing the invasive procedure regulations that complicate wet cupping compliance.
- Flash Cupping:Rapid application-release cycles suit sports medicine timing constraints.
- Moving Cupping:Sliding suction technique requires oil mediums and trained technique certification.
Volume placements concentrate in Dry Cupping; the faster expansion belongs to Flash Cupping.
Application:
Cost tier stratification separates institutional reimbursement-eligible indications from self-pay wellness categories.
- Pain Relief:FDA Class I medical device classification triggers when manufacturers label for this indication, imposing quality system requirements that filter out wellness-oriented suppliers. Germany's statutory health insurers increasingly require CE-marked equipment documentation for physiotherapy reimbursement claims.
- Rehabilitation:Post-surgical and injury recovery protocols in hospital-affiliated centers drive procurement of autoclave-compatible glass sets. China's NMPA-registered products flow through these channels under tightened GB sterilization standards that elevated quality baselines.
- Muscle Relaxation:Wellness center positioning avoids medical device classification in most jurisdictions.
- Detoxification:Traditional medicine framing limits institutional penetration outside TCM-certified settings.
Reimbursement eligibility favors Pain Relief; steepest expansion trajectory sits with Rehabilitation.
Material:
Supply concentration in borosilicate glass manufacturing zones shapes regional cost structures and availability.
- Glass:Thermal-grade borosilicate vessels withstand flame deoxygenation and autoclave sterilization cycles. Production clusters in specific Chinese manufacturing zones create input vulnerability for premium set producers serving EU MDR-certified clinical markets.
- Silicone:Flexible, flame-free operation captures home-use and self-application segments through e-commerce channels. Technical constraints in achieving consistent 0.03-0.06 MPa suction without thermal deoxygenation restrict clinical equivalence claims in certified therapeutic settings.
- Bamboo:Traditional aesthetic positioning serves wellness tourism and spa environments.
- Plastic:Lowest-cost entry point for disposable single-use applications in mass-market segments.
Certified procurement concentrates in Glass; consumer channels are displacing toward Silicone.
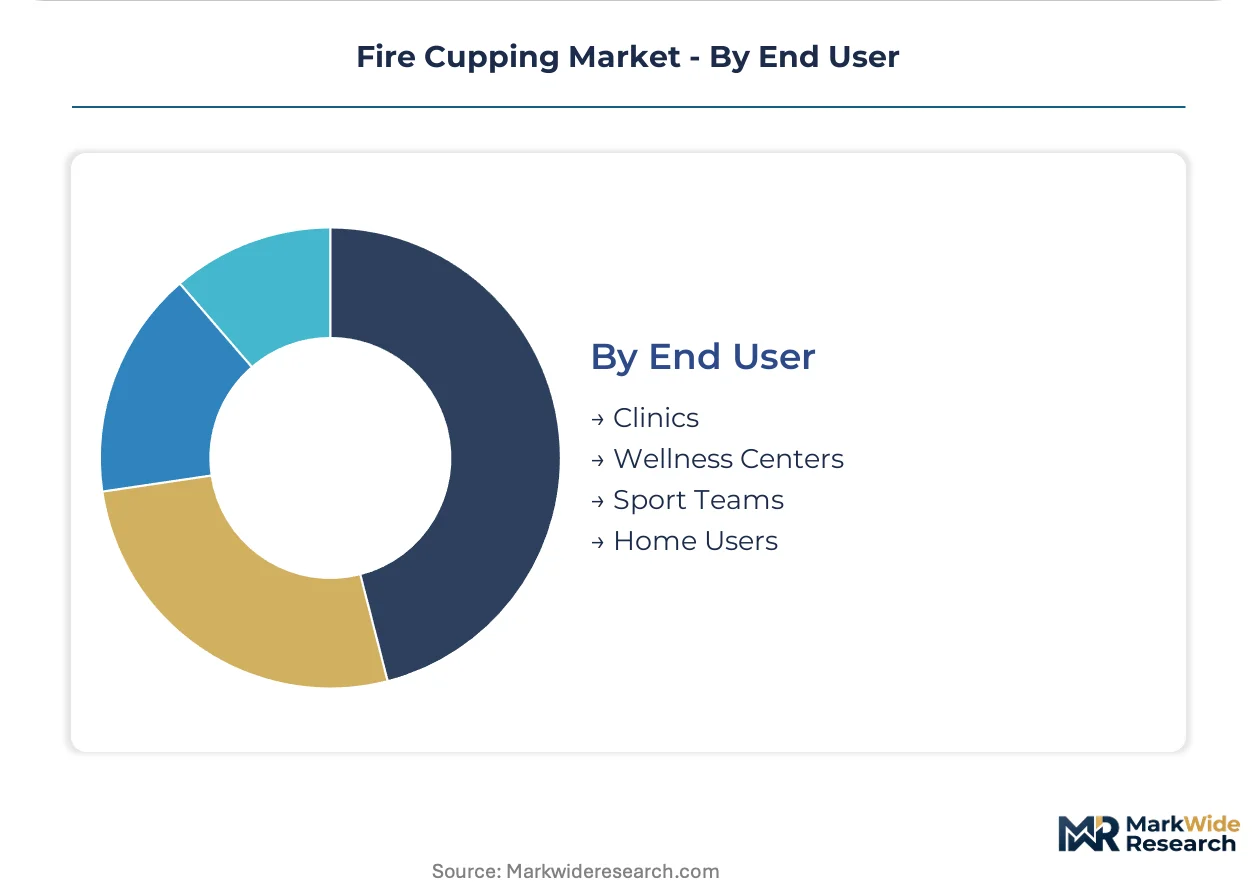
End User:
Customer type fragmentation splits between institutional procurement consolidation and dispersed direct-to-consumer acquisition.
- Clinics:Hospital-affiliated rehabilitation centers are developing direct sourcing capabilities for NMPA-registered and CE-marked equipment, bypassing traditional medical supply distributors. China's tightened GB standards filter substandard suppliers from these procurement pools.
- Home Users:E-commerce platforms capture dispersed demand through specialized traditional medicine marketplaces, with silicone sets dominating consumer channels due to portability and self-application safety. This segment operates largely outside medical device regulatory frameworks.
- Wellness Centers:EU MDR compliance requirements in France and Germany drive segregation between certified medical-grade and unregulated wellness accessories.
- Sport Teams:Professional athletic organizations establish dedicated cupping therapy protocols with standardized equipment requirements.
Procurement authority is concentrating in Clinics; Home Users are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for fire cupping equipment concentrates in clinical procurement channels across Germany, China, and France, where regulatory classification as medical devices shapes distributor relationships and compliance investments.
China
Hospital-affiliated rehabilitation centers in Beijing and Shanghai drive NMPA-registered glass cupping set procurement under tightened GB sterilization standards. SAMR enforcement has elevated quality baselines, filtering substandard suppliers from clinical channels while silicone sets dominate consumer e-commerce platforms operating outside medical device frameworks.
Germany
Statutory health insurers increasingly require CE-marked equipment documentation for physiotherapy reimbursement claims, compressing procurement timelines for wellness center chains. KBA oversight of medical device distribution ensures traceability requirements for autoclave-compatible glass sets supplied to Bavaria and North Rhine-Westphalia rehabilitation networks.
France
ANSM guidance on traditional medicine device classification drives segregation between certified medical-grade and unregulated wellness accessories in Paris and Lyon wellness center chains. CE marking requirements under EU MDR have expanded technical documentation burdens for cupping equipment marketed with therapeutic indications.
United States
FDA Class I medical device classification triggers when manufacturers label cupping sets for pain relief, imposing quality system requirements that filter wellness-oriented suppliers from clinical channels. Sports medicine clinics in California and Texas establish dedicated cupping therapy protocols with standardized equipment requirements for professional athletic organizations.
Italy
Convergence of traditional Chinese medicine certification with Western physical therapy licensure opens hybrid practice settings in Lombardy and Emilia-Romagna. EU MDR compliance requirements drive procurement of CE-marked glass sets through direct-sourcing capabilities developed by hospital-affiliated rehabilitation centers.
Fire Cupping Market Competitive Landscape
Chinese producers anchor the manufacturing tier; European specialists hold certification-driven distribution positions. The vendor base splits between scale-oriented fabricators serving bulk hospital procurement and niche players maintaining traditional medicine practitioner relationships. Two strategic archetypes dominate: regulatory compliance specialists navigating simultaneous NMPA and EU MDR pathways, and e-commerce-optimized suppliers capturing dispersed home-use demand. Competitive moves center on backward integration into borosilicate glass supply and direct-to-clinic distribution platform development.
Among Chinese medical device manufacturers, Kangzhu, Hwato, and BeiJing GuoYiYan Medical Technology and Medical Instrument CO.,LTD occupy positions spanning scale production and regulatory compliance specialization. Kangzhu exemplifies the bulk supply archetype serving hospital-affiliated rehabilitation centers. Hwato represents brand recognition maintenance among traditional Chinese medicine practitioners. BeiJing GuoYiYan anchors the regulatory-compliant product line segment targeting clinical certification requirements across multiple jurisdictions.
| Leading Market Players |
|---|
| Kangzhu |
| Hwato |
| BeiJing GuoYiYan Medical Technology and Medical Instrument CO.,LTD |
| Mengshibaguan |
| FOLEE |
| Huamingkangtaiu |
| YiFang |
| OuMaiAShi |
| Cofoe |
| Others |
Pricing and Supply Chain Analysis
Skilled borosilicate glassblowers concentrated in Hebei and Shandong provinces command wage premiums that compress margins on economy-tier cupping sets while inflating spreads to premium CE-marked clinical grades. Labor-cost differentials between these artisan clusters and automated silicone molding operations in Guangdong directly determine three-tier pricing stratification across hospital procurement, wellness center, and home-use channels.
Pricing Analysis
Volume placements cluster in economy-grade silicone sets sold through e-commerce platforms, while margin capture concentrates in premium glass cupping systems bearing NMPA registration and CE marking. Price differentiation hinges on certification tier—EU MDR technical documentation and FDA Class I quality systems—and thermal-grade borosilicate sourcing that withstands autoclave cycles. Cost compression in silicone home-use segments is intensifying because vacuum pump integration eliminates flame-based labor, though margins are tightening for undifferentiated commodity sets. Hospital-affiliated rehabilitation centers exhibit lowest price sensitivity given reimbursement eligibility requirements, whereas direct-to-consumer buyers prioritize portability over clinical-grade validation.
Supply Chain Analysis
Dual-sourcing requirements mandated by EU MDR-registered wellness center chains in France and Germany compel manufacturers to qualify secondary borosilicate suppliers beyond Hebei province. Geographic supply concentration centers on China for thermal-grade glass vessel fabrication, South Korea for medical-grade silicone formulations, and Germany for precision vacuum pump components. Raw material dependencies encompass borosilicate glass tubing, platinum-cured silicone elastomers, and surgical-grade stainless steel rims. Single-source vulnerability persists in artisan glassblowing clusters where generational skill transfer lags mechanization. Distribution runs through specialized medical supply distributors for clinical-certified equipment, while direct-to-consumer channels disintermediate traditional wholesale tiers for home-use silicone sets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fire cupping market sits in a material-transition phase as flame-free silicone vacuum systems displace traditional glass-and-fire protocols across sports medicine and home-use segments. This substitution wave compresses addressable demand for borosilicate-dependent equipment while elevating compliance burdens for clinical-grade glass manufacturers.
For Market Incumbents: Extend certification moats by accelerating EU MDR technical documentation and FDA 510(k) pathway investments before reclassification movements tighten quality system requirements. Backward integration into captive borosilicate supply from Hebei manufacturing clusters defends margin position against silicone substitution threats. Channel control through direct-to-clinic distribution platforms bypasses distributor consolidation in German and French rehabilitation networks.
For New Entrants and Emerging Players: E-commerce marketplace specialization offers the lowest-friction entry vector for flame-free silicone cupping sets targeting self-application demand outside medical device frameworks. Home-use segments in North America and Western Europe present the most penetrable white space given FDA Class I friction that deters wellness-oriented incumbents from pain relief labeling. A go-to-market angle anchored on physical therapy influencer partnerships and athlete testimonial content bypasses clinical procurement gatekeepers.
For Investors and Strategic Acquirers: Re-rating potential sits with regulatory compliance specialists given simultaneous NMPA and EU MDR pathway execution as the catalyst for premium valuation multiples. Long-term viability across a five-to-ten-year horizon favors manufacturers with validated autoclave-compatible silicone formulations and technical documentation systems portable across jurisdictions. The signal to watch is medical device reclassification movement in the United States that would shift cupping products from wellness accessories to regulated therapeutic instruments.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR CE Marking Pathway | Technical documentation systems unlock wellness center procurement in France and Germany under ANSM and KBA oversight. |
| Backward Integration into Borosilicate Supply | Captive glass sourcing from Hebei clusters insulates margin compression from artisan wage inflation and supply concentration risk. |
| Direct-to-Clinic Distribution Platform | Bypassing traditional medical supply distributors captures procurement authority concentrating in hospital-affiliated rehabilitation centers. |
| Autoclave-Compatible Silicone Formulation | Biocompatibility validation extends addressable market from home-use into clinical-certified segments requiring sterilization cycles. |
| Reimbursement Strategy Development | Statutory health insurer documentation in Germany's KBA framework enables physiotherapy claim eligibility for CE-marked equipment. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this fire cupping market analysis. Primary interviews with traditional Chinese medicine practitioners, hospital purchasing committee members, biomedical engineers specializing in rehabilitation equipment, and regulatory affairs specialists at medical device manufacturers combined with secondary validation from NMPA registration databases, EU MDR technical documentation repositories, FDA 510(k) filings, and hospital procurement contract disclosures. Bottom-up unit economics modeling and top-down category sizing triangulated volume and value estimates across the analysis window.
Segment-level granularity modeled material type at the vessel-grade tier, technique at the licensure-requirement level, application at the reimbursement-eligibility threshold, and end user at the procurement-authority concentration point. CAGRs derived from fitted growth curves applied to base-year observations, cross-referenced against clinician adoption surveys and wellness center expansion plans. Industry-specific forecast inputs encompassed autoclave sterilization standard adoption timelines and EU MDR transition completion rates among incumbent manufacturers.
The model holds under stable regulatory classification frameworks; deviation in FDA medical device reclassification or NMPA GB standard tightening would shift volume trajectories between clinical and home-use channels. Forecasts reflect assumptions regarding silicone substitution rates and certification investment capacity among mid-tier manufacturers. A model refresh is warranted upon material change in EU MDR enforcement intensity or statutory health insurer reimbursement policy in target European markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Medicine
Electrotherapy Market
Alternative Medicine
Homeopathic Medicine Market
Alternative Medicine
Natural Cold, Cough, and Sore Throat Remedies Market
Alternative Medicine
Disposable Acupuncture Needle Market
Alternative Medicine
Europe Complementary and Alternative Medicine Market
Alternative Medicine
Ozone Therapy Units Market
Alternative Medicine
Cold Laser Therapy Market
Alternative Medicine
Global Acupuncture Market
Alternative Medicine
Flower Essences Market
Alternative Medicine
Vacuum Cupping Market
Alternative Medicine
Aromatherapy Market
Alternative Medicine
Global OTC Herbal and Traditional Medicine Market
Alternative Medicine
Global Homeopathic Product Market
Alternative Medicine
Orthomolecular Medicine Market
Alternative Medicine
Homeopathy Products Market
Alternative Medicine
Biopuncture Treatment Market