
 Vacuum Cupping Market | 2026-2036
Vacuum Cupping Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Cupping Market Insights
Asset-light leasing models for electric cupping devices is fragmenting competitive dynamics across the Vacuum Cupping Market, enabling smaller clinics to access premium equipment without capital outlay. Mainspring Medical leverages direct-to-practitioner subscription programs to sustain recurring revenue streams in North American physiotherapy chains. Ig Medicare Pvt Ltd anchors its position through backward integration into medical-grade silicone production, controlling raw material quality for its cupping portfolio. Firma Medical differentiates via specialized glass cupping sets designed for TCM practitioners across European wellness centers.
Vacuum cupping employs negative pressure suction applied to skin and underlying tissue through rigid or flexible vessels, with modern electric systems generating controlled vacuum levels between 0.02 and 0.08 MPa for therapeutic decompression. The primary commercial purpose spans pain modulation, localized blood flow enhancement, and myofascial release across clinical and consumer settings. Silicone cups capture expanding share in home-use channels due to pliability and self-application safety, while electric cupping devices concentrate margin pools in professional sports medicine installations. Glass cups retain dominance within traditional Chinese medicine clinics where thermal compatibility and sterilization durability outweigh portability concerns.
The FDA regulates electric cupping devices as Class II medical instruments requiring 510(k) premarket notification, shaping product development timelines and market entry barriers for powered systems. China's NMPA enforces GB standards for medical device materials contact with human tissue, directly influencing silicone and rubber sourcing specifications for domestic manufacturers. ISO 13485 certification has become a baseline qualification for contract manufacturers serving European and North American therapeutic device distributors. Stakeholders must monitor evolving classification boundaries between wellness accessories and regulated medical devices as jurisdictions reassess claims language for pain management applications.
Market Dynamics
Electric cupping systems are displacing manual glass and silicone sets across professional physiotherapy chains, driven by sports medicine protocols demanding precise vacuum pressure control and reproducible treatment parameters.
Growth Catalysts
- Class II Medical Device Pathway:FDA 510(k) clearance requirements for powered therapeutic systems are legitimizing electric cupping in institutional procurement channels, expanding reimbursement eligibility for clinical applications.
- Sports Medicine Integration:Professional athletic training centers in the United States and Germany are embedding electric cupping into post-event muscle recovery protocols, creating standardized demand for programmable vacuum systems.
- Silicone Material Advances:Medical-grade platinum-cured silicone formulations meeting ISO 10993 biocompatibility standards are enabling self-application safety in consumer channels, broadening addressable user bases beyond clinical settings.
Market Restraints
- Medical-Grade Silicone Supply Concentration:Raw material sourcing for platinum-cured silicone concentrates among specialty chemical producers in Germany and Japan, exposing manufacturers to input cost volatility and allocation constraints.
- Regulatory Classification Friction:Jurisdictional ambiguity between wellness accessory and regulated medical device categories in the European Union creates compliance uncertainty, delaying product launches and marketing claims.
- Manual Cupping Substitution Persistence:Traditional glass and silicone sets retain cost advantages in home-use and TCM clinic segments, limiting price elasticity for premium electric systems in price-sensitive channels.
Strategic Opportunities
- Subscription-Based Equipment Access:Asset-light leasing models for electric cupping devices enable smaller physiotherapy clinics to deploy premium equipment without capital expenditure, expanding vendor addressable markets.
- TCM-Modern Physiotherapy Convergence:Integration of traditional Chinese medicine protocols with evidence-based sports science in China creates demand for hybrid cupping systems combining thermal compatibility with digital pressure monitoring.
- ISO 13485 Certification Arbitrage:Contract manufacturers achieving quality management system certification capture margin premiums serving North American and European therapeutic device distributors seeking compliant sourcing.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Development of precision vacuum control systems requires specialized expertise in pneumatic sensor integration and embedded firmware, constraining product innovation cycles.
- 510(k) Clearance Timeline Compression:FDA premarket notification processes for novel electric cupping devices extend development-to-revenue intervals, straining working capital for emerging manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Cupping Market |
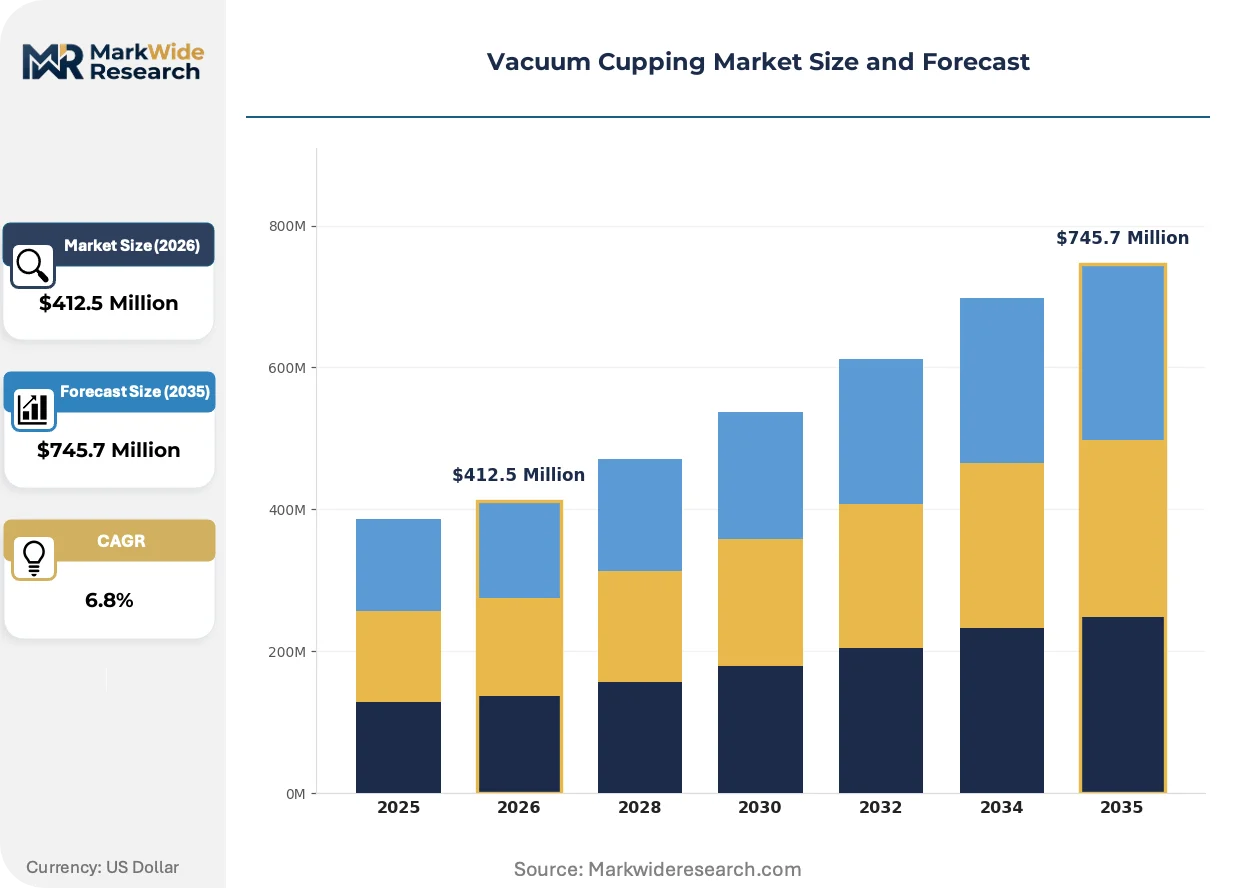
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Suction Cups, Silicone Cups, Glass Cups, Electric Cupping Devices End User: Clinics, Hospitals, Sports Facilities, Home Users Application: Pain Management, Muscle Recovery, Skin Rejuvenation, Stress Relief Material: Plastic, Glass, Silicone, Rubber |
| Companies Covered | Acupressure Health Mart, Ig Medicare Pvt Ltd, Physiotherapy Health Mart, Acupressure Health Care System, Sandeep Enterprises, Unysen Health, Mainspring Medical, Firma Medical, Encore Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Cupping Market Trends and Innovations
Digital pressure sensing and programmable treatment protocols are redefining therapeutic precision standards, while regulatory frameworks struggle to keep pace with converging wellness and medical device classifications.
Smart electric cupping systems incorporating real-time pressure feedback and Bluetooth connectivity are migrating from high-performance athletic facilities to outpatient rehabilitation centers, compressing the technology diffusion cycle from elite to mainstream clinical adoption. These systems enable treatment documentation for insurance reimbursement, fundamentally altering value capture mechanisms in professional channels.
China's NMPA enforcement of GB standards for medical device materials contact with human tissue is reshaping silicone and rubber sourcing specifications for domestic manufacturers, forcing supply chain requalification and raw material traceability investments. Domestic producers serving export markets must maintain dual compliance frameworks, elevating operational complexity and certification costs.
Direct-to-practitioner subscription programs are fragmenting traditional distributor relationships in North American physiotherapy chains, unbundling equipment procurement from maintenance and software update services. This channel innovation concentrates in metropolitan clinical networks seeking operational flexibility without capital commitment, compressing legacy equipment financing margins.
Vacuum Cupping Market Segmentation
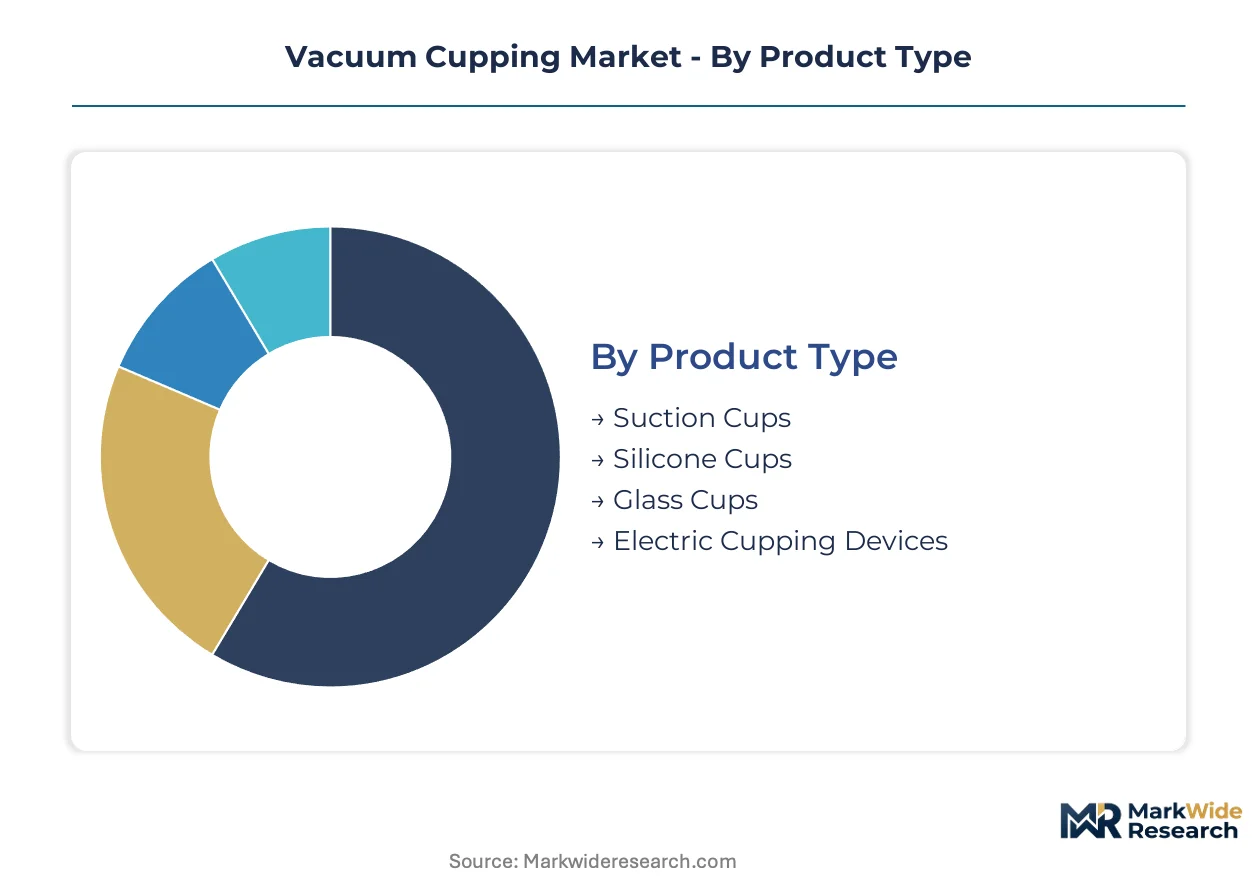
Vacuum cupping equipment fragments across distinct technical tiers, each serving divergent clinical sophistication levels and regulatory exposure. Material specifications and pressure generation mechanisms determine reimbursement eligibility, institutional procurement pathways, and end-user safety protocols.
Product Type:
The use-case spectrum spans from traditional manual sets requiring practitioner skill to digitally controlled systems enabling protocol standardization across clinical networks.
- Electric Cupping Devices:Programmable vacuum systems generate negative pressure between 0.02 and 0.08 MPa through pneumatic pumps with embedded pressure sensors. Sports facilities in Germany and the United States are embedding these into post-event recovery protocols, driving demand for FDA 510(k) cleared systems with treatment documentation capabilities.
- Silicone Cups:Medical-grade platinum-cured formulations offer pliability for self-application and conform to body contours without thermal conditioning. Home-use channels in China and North America are absorbing expanding volumes as ISO 10993 biocompatibility certifications reduce liability exposure for direct-to-consumer distribution.
- Glass Cups:Borosilicate construction withstands repeated sterilization cycles and thermal compatibility with fire-based traditional Chinese medicine techniques. TCM clinics retain preference for glass despite portability limitations.
- Suction Cups:Manual pump-activated rigid vessels dominate entry-level clinical procurement and portable field kits for athletic training staff.
The dominant share belongs to Electric Cupping Devices in professional channels, while Silicone Cups is closing the gap fastest through consumer self-care expansion.
End User:
Procurement sophistication varies sharply across institutional hierarchies, with reimbursement codes and capital budgeting cycles filtering equipment categories.
- Sports Facilities:Professional athletic training centers demand programmable systems with reproducible treatment parameters for muscle recovery protocols. NBA and Bundesliga franchise medical departments are standardizing electric cupping specifications, creating reference customer effects for vendor sales cycles.
- Clinics:Outpatient physiotherapy chains balance equipment utilization rates against lease payment structures. Mainspring Medical's subscription programs are penetrating metropolitan clinical networks seeking operational flexibility.
- Home Users:Self-application safety requirements favor silicone and rubber materials over glass or powered systems. E-commerce channels in China and the United States are capturing this segment through direct-to-consumer medical-grade silicone sets.
- Hospitals:Inpatient rehabilitation departments face stringent biomedical engineering review processes for powered therapeutic devices, slowing electric system adoption relative to outpatient settings.
Sports Facilities command premium pricing tiers, whereas Home Users is expanding addressable volume most steeply through e-commerce penetration.
Application:
Clinical evidence requirements and insurance reimbursement eligibility fragment demand across therapeutic indication categories.
- Muscle Recovery:Post-exertion myofascial decompression protocols in professional athletics are driving electric system specifications with pressure logging for training staff documentation.
- Pain Management:Chronic musculoskeletal conditions attract reimbursement scrutiny, favoring FDA-cleared electric devices with clinical trial backing over manual alternatives in institutional procurement.
- Skin Rejuvenation:Cosmetic wellness applications operate outside medical device regulatory frameworks in most jurisdictions, enabling broader marketing claims but limiting clinical channel access.
- Stress Relief:General wellness positioning avoids regulatory classification friction but sacrifices insurance eligibility and clinical credibility.
Muscle Recovery anchors professional segment revenue, while Pain Management is gaining institutional traction fastest through reimbursement pathway development.
Material:
Supply concentration and biocompatibility certification costs stratify manufacturing economics across material categories.
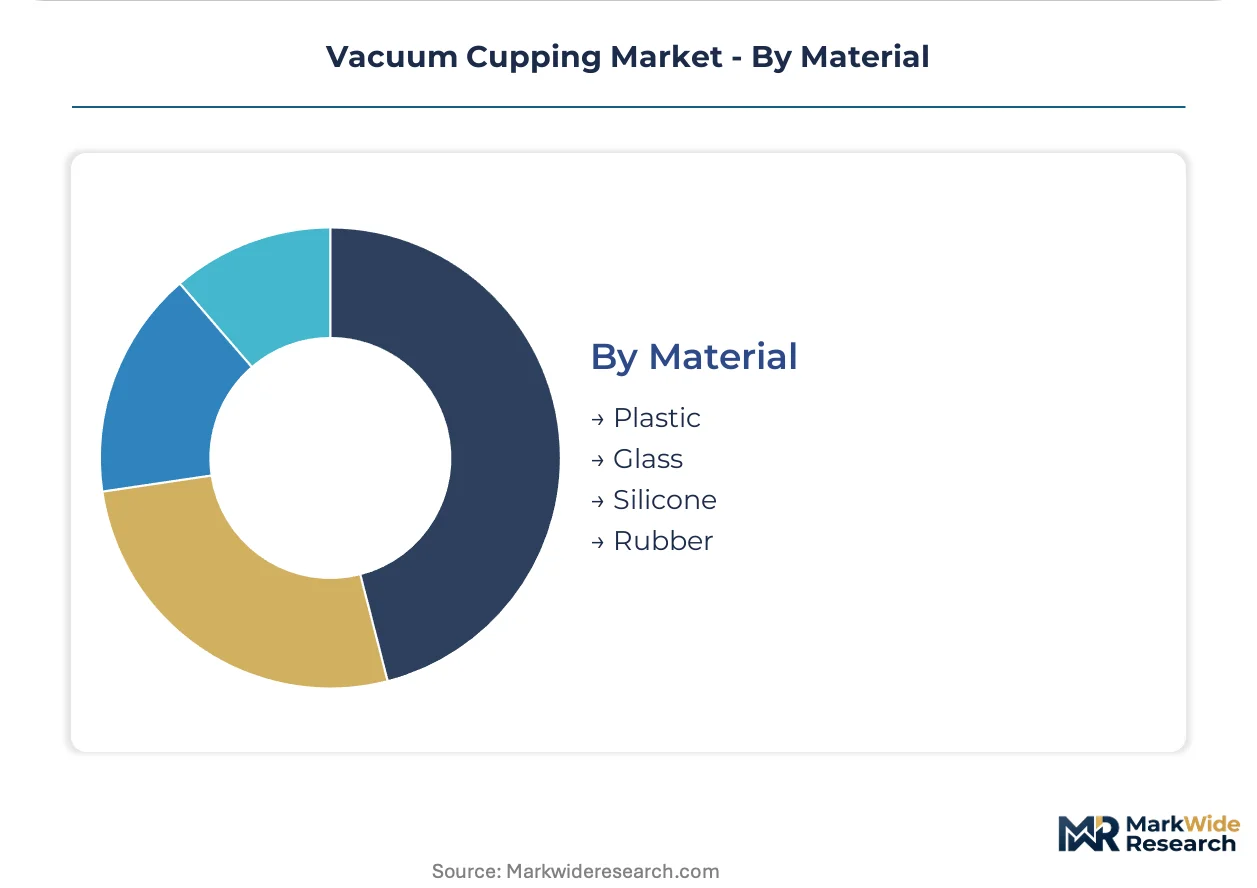
- Silicone:Platinum-cured medical-grade formulations from German and Japanese specialty chemical producers command price premiums but enable ISO 10993 compliance for skin contact devices. Ig Medicare's backward integration into silicone production captures margin and quality control advantages.
- Glass:Borosilicate sourcing concentrates among established laboratory glassware manufacturers with thermal shock resistance specifications. European wellness centers favor Firma Medical's specialized sets for TCM practitioner training programs.
- Plastic:Polypropylene and polycarbonate variants serve disposable single-use protocols and cost-sensitive consumer channels with limited durability requirements.
- Rubber:Natural and synthetic elastomer formulations retain niche presence in traditional manual pump systems and entry-level consumer sets.
Silicone dominates value capture in regulated channels, though Glass retains irreplaceable positioning within TCM institutional procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional athletic training centers and traditional Chinese medicine clinics concentrate equipment procurement across distinct geographic clusters, with regulatory frameworks fragmenting market access pathways.
United States
NBA and Bundesliga franchise medical departments standardize electric cupping specifications for post-event muscle recovery protocols. FDA 510(k) clearance requirements for powered therapeutic systems shape institutional procurement eligibility and reimbursement pathways. Dallas-Fort Worth and Los Angeles metropolitan clinical networks drive subscription-based equipment access models.
Germany
Bundesliga sports medicine facilities anchor European demand for programmable vacuum systems with reproducible treatment parameters. REACH and CE marking under the EU MDR govern silicone and rubber materials contact with human tissue. Baden-Württemberg industrial clusters concentrate specialty chemical production for platinum-cured medical-grade silicone formulations.
China
TCM clinics and modern physiotherapy convergence create specialized distribution channels for glass and silicone cupping sets. NMPA enforcement of GB standards for medical device materials forces supply chain requalification and raw material traceability investments. Yangtze River Delta manufacturing hubs dominate medical-grade silicone processing for domestic and export markets.
Japan
Meti and PMDA oversight of therapeutic device classifications creates compliance thresholds for electric cupping market entry. Aging population demand for home-use rehabilitation equipment expands silicone cup adoption through e-commerce channels. Osaka-Kobe industrial corridors concentrate precision pneumatic component manufacturing for medical device applications.
United Kingdom
London and Southeast England wellness centers integrate TCM protocols with evidence-based sports science, driving hybrid cupping system demand. MHRA classification boundaries between wellness accessories and regulated medical devices create marketing claims uncertainty. Midlands manufacturing bases supply borosilicate glassware for European TCM practitioner training programs.
Vacuum Cupping Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented competitive tiers, with no single entity commanding decisive market share. Electric device manufacturers, silicone fabricators, and traditional glassware suppliers occupy distinct margin pools with limited direct overlap. Strategic archetypes separate subscription-based equipment lessors, backward-integrated material producers, and TCM-specialized set designers. Competitive moves concentrate on ISO 13485 certification arbitrage and direct-to-practitioner channel unbundling.
Among India-based fabricators, Ig Medicare Pvt Ltd anchors the backward-integrated material producer archetype through in-house silicone production. Mainspring Medical exemplifies the subscription-model equipment lessor targeting North American physiotherapy chains. Firma Medical occupies a position within the TCM-specialized set designer tier serving European wellness centers.
| Leading Market Players |
|---|
| Acupressure Health Mart |
| Ig Medicare Pvt Ltd |
| Physiotherapy Health Mart |
| Acupressure Health Care System |
| Sandeep Enterprises |
| Unysen Health |
| Mainspring Medical |
| Firma Medical |
| Encore Medical |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta silicone processing hubs dictate downstream pricing leverage for medical-grade cupping materials, with platinum-cured formulation capacity constraints transmitting directly into electric device manufacturer margin compression. FDA 510(k) clearance costs and ISO 13485 certification investments stratify procurement tiers, concentrating pricing power among backward-integrated producers.
Pricing Analysis
Cost-plus contracts indexed to German and Japanese specialty chemical producer pricing dominate raw material procurement for medical-grade silicone. Three-tier pricing structure across FDA-cleared premium systems, CE-marked professional equipment, and unregulated consumer silicone sets reflects certification-grade differentiation. Pricing pressure stems from platinum-cured silicone allocation constraints and hospital capital budget tightening. Home-use channels exhibit highest price sensitivity, while Bundesliga and NBA franchise medical departments absorb premium electric system costs without volume negotiation.
Supply Chain Analysis
Export control regimes on precision pneumatic sensors and embedded pressure transducers constrain component flows from Japanese and German industrial corridors into electric cupping device assembly. Manufacturing gravity centers on China for silicone processing, Germany for specialty chemical formulation, and Japan for sensor integration. Supply chains draw from platinum-cured silicone, borosilicate glassware, and pneumatic pump components. Single-source vulnerability concentrates in medical-grade silicone feedstock from Baden-Württemberg and Osaka-Kobe clusters. Distribution runs through direct-to-practitioner subscription programs and TCM-specialized wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market's defensive moat rests on regulatory entrenchment: FDA 510(k) clearance timelines and ISO 13485 certification requirements create switching costs that institutional buyers cannot circumvent without operational disruption.
For Market Incumbents: Entrench position through captive silicone production capacity in Yangtze River Delta hubs, mirroring Ig Medicare's backward integration model. Pursue 510(k) clearance portfolio expansion for programmable pressure protocols before emerging pneumatic sensor suppliers achieve FDA quality system recognition. Threat of manual cupping substitution in price-sensitive TCM clinics demands premium electric system feature differentiation. For New Entrants and Emerging Players: Mid-market physiotherapy chains in China's second-tier cities represent the most penetrable entry point, combining TCM practitioner density with nascent electric device adoption. Subscription-based equipment access models for metropolitan clinical networks bypass capital expenditure barriers that favor incumbents. Go-to-market execution should anchor on ISO 13485-certified contract manufacturing partnerships rather than in-house quality system development. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device parents with underoptimized cupping portfolios lacking dedicated regulatory affairs infrastructure. Long-term viability hinges on reimbursement pathway development for pain management applications. Signal to watch: CMS Medicare coverage determination for electric cupping in outpatient rehabilitation settings.| Strategic Initiative | Industry Significance |
|---|---|
| 510(k) Clearance Pathway Investment | FDA premarket notification accelerates institutional procurement eligibility for powered therapeutic systems. |
| Backward Integration into Silicone Production | In-house medical-grade formulation captures margin and insulates against German-Japanese supplier allocation constraints. |
| Direct-to-Practitioner Subscription Launch | Asset-light leasing models penetrate metropolitan physiotherapy chains without capital expenditure friction. |
| ISO 13485 Certification Arbitrage | Quality management system credentials unlock contract manufacturing premiums from North American distributors. |
| TCM-Modern Physiotherapy Hybrid System Development | Thermal-compatible glass construction with digital pressure monitoring bridges traditional and evidence-based protocols. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, NMPA registration databases, hospital procurement contracts, and ISO certification registries. Interviews with biomedical engineers, physiotherapy clinic operators, TCM practitioners, GPO contracts managers, and specialty chemical procurement leads inform demand-side validation. Secondary sources include customs trade data for silicone and glassware imports, SEC filings for diversified medical device parents, and CMS reimbursement code databases. Bottom-up equipment shipment modeling triangulates against top-down addressable market sizing.
Forecast inputs incorporate electric device penetration rates across sports medicine facilities, silicone cup adoption curves in home-use channels, and regulatory classification boundary shifts between wellness accessories and medical devices. Segmentation dimensions span product type, end user, application, material, and regional regulatory cluster. CAGRs derive from installed base growth, replacement cycles, and price trajectory assumptions. Industry-specific inputs include 510(k) clearance pipeline velocity and platinum-cured silicone supply expansion timelines.
Practitioners should monitor FDA classification guidance revisions, NMPA GB standards enforcement intensity, and CMS coverage determination timelines for early signals of forecast deviation. Material shifts in electric cupping reimbursement eligibility or medical-grade silicone supply concentration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Medicine
Disposable Acupuncture Needle Market
Alternative Medicine
Traditional Chinese Herbal Medicine Market
Alternative Medicine
Homeopathic Medicine Market
Alternative Medicine
Europe Complementary and Alternative Medicine Market
Alternative Medicine
Fire Cupping Market
Alternative Medicine
Global OTC Herbal and Traditional Medicine Market
Alternative Medicine
US Aromatherapy Market
Alternative Medicine
Global Acupuncture Market
Alternative Medicine
Traditional Chinese Medicine Market
Alternative Medicine
Global Complementary and Alternative Medicines Market
Alternative Medicine
Flower Essences Market
Alternative Medicine
Electrotherapy Market
Alternative Medicine
Global Homeopathic Product Market
Alternative Medicine
Acupuncture Lasers Market
Alternative Medicine
Homeopathy Products Market
Alternative Medicine
Cold Laser Therapy Market