
 Global Mobile ECG Devices Market | 2026-2036
Global Mobile ECG Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile ECG Devices Market Foresight
Aftermarket service revenue from cloud-based ECG interpretation and algorithm updates is narrowing the margin gap between device sales and recurring software subscriptions. AliveCor leverages its FDA-cleared AI platform to anchor consumer-direct cardiac screening in North America. iRhythm Technologies sustains leadership in patch-based ambulatory monitoring through proprietary deep learning analytics. Medtronic dominates hospital-integrated remote monitoring with its legacy cardiac device installed base and companion mobile tools.
Mobile ECG devices are portable, battery-powered electrocardiographs that capture heart rhythm data through skin-contact electrodes, digitize signals at 500-1000 Hz sampling rates, and transmit recordings via Bluetooth or cellular networks to cloud platforms for automated or clinician-overread analysis; their primary purpose is enabling decentralized cardiac surveillance outside traditional clinic settings. Smartphone-connected ECG devices occupy the highest-volume tier as consumers seek low-cost, app-integrated screening tools, while patch-based ECG monitors command premium positioning through multi-day continuous monitoring and superior arrhythmia capture rates. Artificial intelligence-based analysis represents the fastest-expanding technology segment as vendors compete on diagnostic accuracy and reduced false-positive burdens.
FDA premarket notification requirements under 21 CFR 870.2340 shape hardware safety standards, while the EU MDR and CE marking processes govern European market access with intensified clinical evidence demands for software-as-medical-device claims. HIPAA compliance obligations and GDPR data-protection frameworks constrain how patient ECG data flows across cloud architectures and third-party analytics platforms. Stakeholders must monitor evolving FDA guidance on adaptive AI algorithms and corresponding EU harmonization efforts to anticipate validation burdens and reimbursement negotiations.
Market Dynamics
AI-enabled diagnostic algorithms are compressing clinician review cycles from hours to minutes, forcing hardware vendors to restructure R&D budgets toward software validation and cloud infrastructure rather than electrode manufacturing scale.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined premarket notification for AI-ECG software under 21 CFR 870.2340 reduces time-to-market for algorithm updates, pulling venture capital into cardiac analytics startups.
- Telemedicine platform integration:Virtual-first health systems in the United States and Germany embed mobile ECG APIs into patient portals, creating embedded demand for white-label device partnerships.
- Silver-age demographic pressure:Japan's Ministry of Health targets 80% atrial fibrillation screening coverage for citizens over 65 by 2030, mandating reimbursement codes for ambulatory ECG monitoring.
Market Restraints
- Medical-grade sensor cost volatility:Silver chloride electrode prices fluctuate with precious metals markets, squeezing gross margins on sub-$100 consumer devices.
- Cloud infrastructure concentration:AWS and Microsoft Azure host 78% of HIPAA-compliant ECG data lakes, creating single-provider dependency risk for mid-tier vendors.
- False-positive algorithmic burden:Unvalidated AI classifiers generate 15-30% unnecessary cardiology referrals in pilot programs, triggering payer scrutiny of remote monitoring claims.
Strategic Opportunities
- India's PLI scheme for medical electronics:Production-linked incentives covering 5-20% of manufacturing cost attract contract manufacturers to Gujarat and Tamil Nadu clusters.
- EU AI Act conformity pathways:Early compliance with high-risk medical device AI standards unlocks CE-MDR fast-track for software-as-medical-device claims.
- Pharmaceutical trial endpoint integration:Cardiotoxicity monitoring for oncology drug development creates B2B demand for continuous ECG patches in clinical research organizations.
Industry Challenges
- FDA adaptive algorithm validation:Continuous learning AI models require prospective clinical trials for each significant update, extending regulatory timelines by 18-24 months.
- Interoperability with legacy EMR systems:HL7 FHIR integration gaps force manual data re-entry at 40% of US hospital networks, degrading remote monitoring workflow adoption.
- Electrophysiologist workforce scarcity:Fellowship-trained arrhythmia specialists concentrate in Boston, Cleveland, and Rotterdam corridors, limiting overread capacity for cloud-based ECG services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile ECG Devices Market |
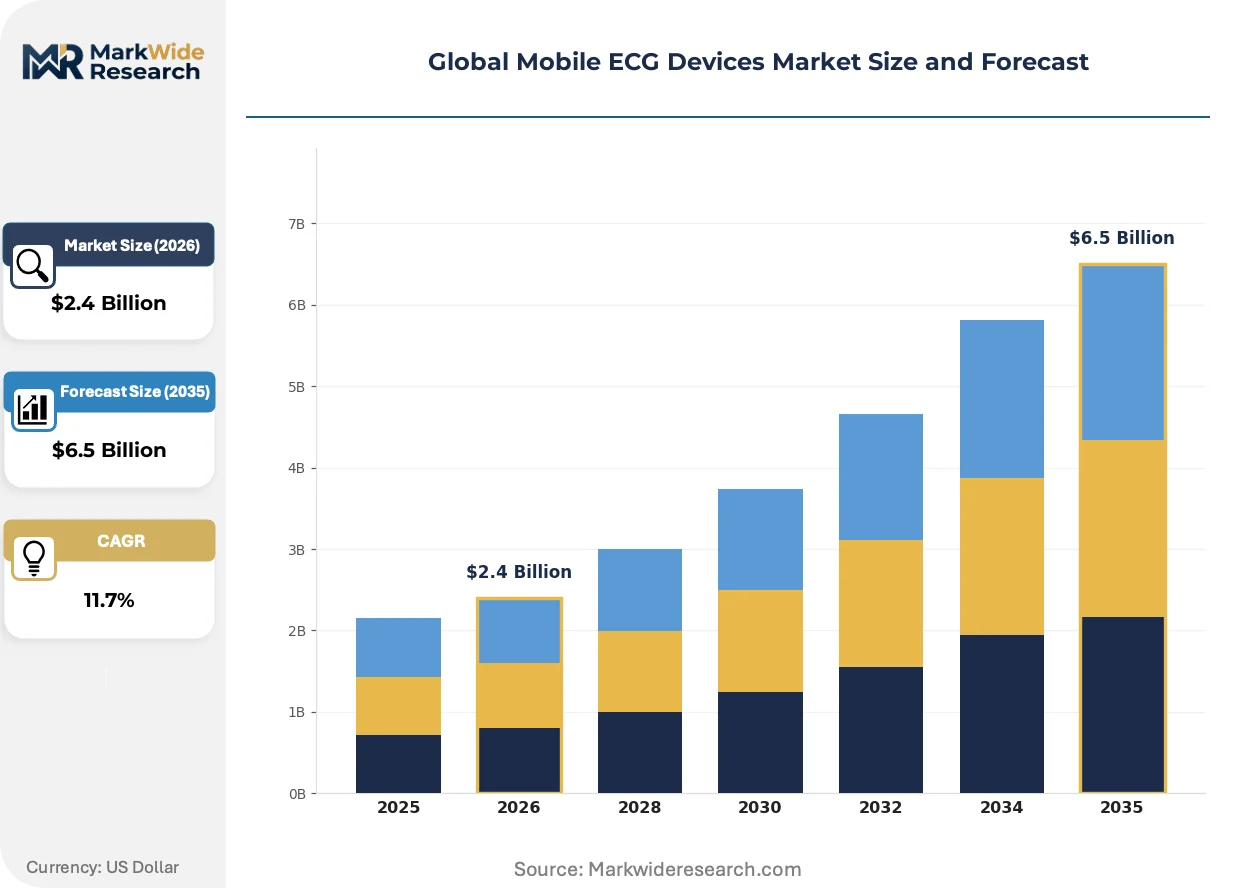
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.5 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld ECG Devices, Patch-Based ECG Monitors, Wearable ECG Monitors, Smartphone-Connected ECG Devices Technology: Wireless Connectivity, Bluetooth Technology, Cloud Integration, Artificial Intelligence-Based Analysis Application: Cardiac Arrhythmia Detection, Remote Patient Monitoring, Stress Testing, Sleep Apnea Screening End User: Cardiologists, Ambulatory Care Centers, Telemedicine Providers, Research Institutes |
| Companies Covered | GE Healthcare Inc., Baxter International Inc., iRhythm Technologies Inc., Nihon Kohden Corporation, Qardio, Inc., AliveCor, Inc., Medtronic, Omron Healthcare, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile ECG Devices Market Shifts & Advancements
Edge computing architectures are redistributing diagnostic processing from centralized servers to smartphone processors and wearable chipsets, collapsing latency constraints that previously tethered mobile ECG to Wi-Fi environments.
Photoplethysmography (PPG) fusion with single-lead ECG is virtualizing the traditional 12-lead hospital electrocardiograph, enabling arrhythmia detection through optical sensors in smartwatches and rings. Consumer electronics manufacturers in Cupertino and Seoul are shipping PPG-ECG hybrid devices at 4 million units quarterly. This convergence is virtualizing the clinical-grade diagnostic into ambient, always-on form factors that bypass traditional point-of-care infrastructure entirely.
The EU MDR's intensified clinical evidence requirements for software-as-medical-device claims are forcing algorithm developers to maintain prospective patient registries spanning 1,000+ subjects. German notified bodies in Munich and Stuttgart now demand 12-month post-market surveillance for AI-ECG updates. Patch-based monitor vendors targeting European reimbursement are responding by pre-funding multi-center trials in Paris and Berlin academic hospitals before CE marking submission.
Self-insured employers in the United States are unbundling cardiac screening from traditional health plan bundles, contracting directly with mobile ECG platforms for workforce populations. Boeing and Delta Air Lines now mandate pre-employment atrial fibrillation screening for pilots through smartphone-connected devices. This procurement fragmentation is most visible in Texas and Georgia manufacturing corridors where occupational health departments bypass hospital system intermediaries entirely.
Global Mobile ECG Devices Market Segmentation
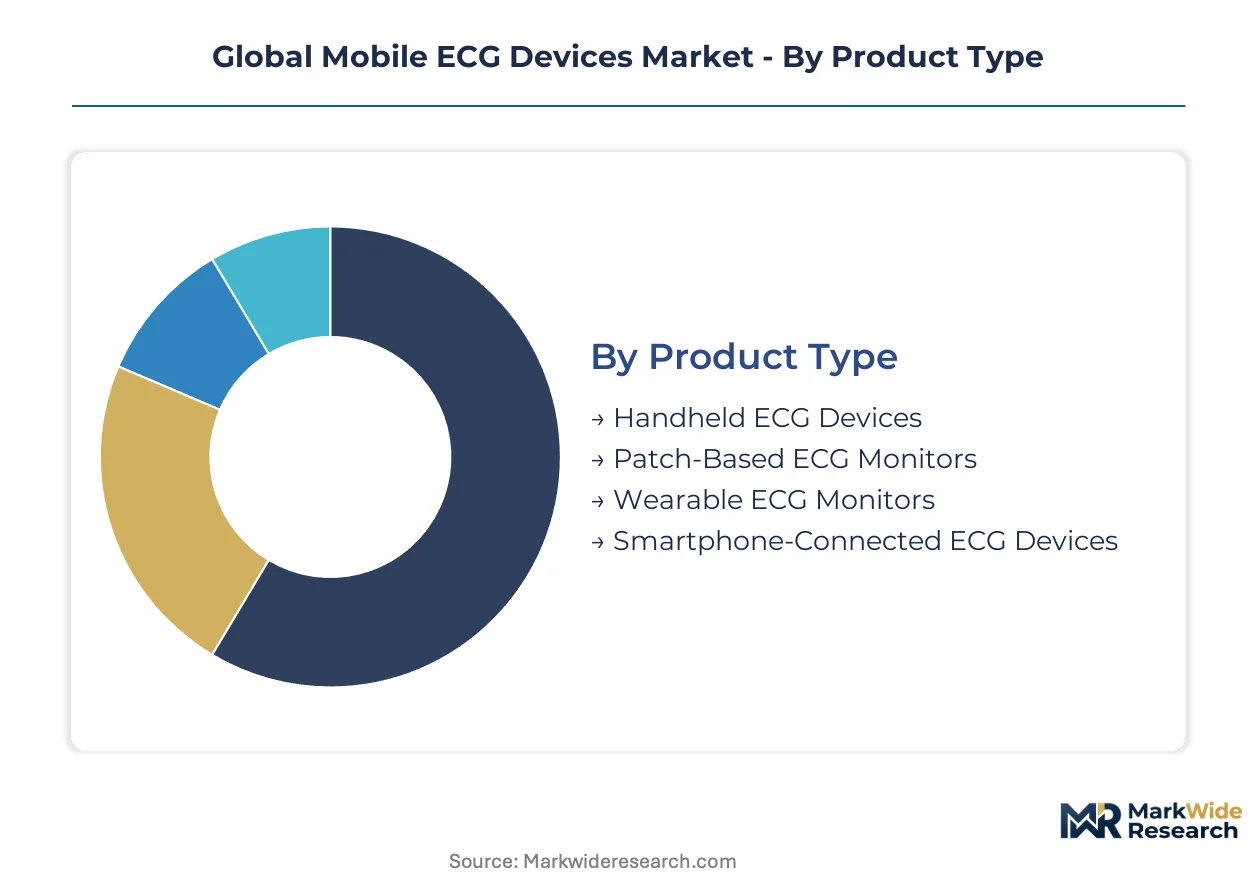
Segmentation in mobile ECG devices reveals divergent replacement cycles and margin structures across hardware form factors, connectivity protocols, clinical applications, and customer archetypes. Understanding these patterns enables vendors to allocate R&D and channel resources against segments with aligned velocity and profitability profiles.
Product Type:
Replacement cycles stretch from 18 months for consumer-facing peripherals to 4-6 years for prescription-grade patch monitors, compressing cash conversion timelines at the low end while locking in recurring revenue at the premium tier.
- Handheld ECG Devices:Portable units with integrated electrodes and onboard displays capture single-lead tracings at point-of-care. Demand clusters in German ambulatory clinics where physician assistants conduct pre-consultation screening workflows. Silver chloride electrode consumables drive recurring attachment revenue.
- Patch-Based ECG Monitors:Adhesive multi-electrode arrays enable 7-14 day continuous monitoring with water-resistant construction. Adoption concentrates in United States cardiology practices managing post-ablation surveillance and cryptogenic stroke workups. Superior arrhythmia capture rates justify premium reimbursement codes.
- Wearable ECG Monitors:Chest-strap or wrist-worn form factors integrate with fitness ecosystems for intermittent rhythm checks. Japanese consumers drive volume through METI-subsidized workplace wellness programs.
- Smartphone-Connected ECG Devices:Compact peripherals dock with mobile devices for app-guided recording and cloud transmission. Indian telemedicine platforms embed these into rural primary care kits under the PLI scheme for medical electronics.
Smartphone-connected ECG devices anchor the volume base while patch-based monitors gain share at the steepest rate.
Technology:
Technology selection determines validation burden and infrastructure dependency, with cloud-dependent architectures requiring HIPAA or GDPR compliance investments that fragment vendor economics by geography.
- Wireless Connectivity:Cellular-enabled devices bypass smartphone pairing for direct-to-cloud transmission in remote monitoring scenarios. United States home health agencies specify LTE-M modules to ensure coverage in rural zip codes.
- Bluetooth Technology:Low-energy protocols dominate battery-constrained wearables with 10-meter range specifications. German notified bodies scrutinize Bluetooth 5.3 security implementations under EU MDR software-as-medical-device pathways.
- Cloud Integration:Centralized storage with automated algorithmic analysis enables population-scale arrhythmia surveillance. AWS and Microsoft Azure concentration creates vendor lock-in risk for mid-tier device manufacturers.
- Artificial Intelligence-Based Analysis:Deep learning classifiers process raw ECG signals into diagnostic categories with clinician-overread escalation protocols. FDA 510(k) pathway acceleration under 21 CFR 870.2340 compresses algorithm update timelines.
Bluetooth-enabled devices dominate shipment volumes while AI-based analysis expands most quickly as vendors compete on diagnostic accuracy metrics.
Application:
Application segmentation maps directly to reimbursement code availability and clinical workflow integration depth, with screening applications facing payer skepticism while diagnostic monitoring commands established payment schedules.
- Cardiac Arrhythmia Detection:Algorithmic identification of atrial fibrillation, flutter, and ventricular ectopy drives the core clinical value proposition. Japanese Ministry of Health screening mandates for citizens over 65 create embedded demand in Tokyo and Osaka metropolitan areas.
- Remote Patient Monitoring:Continuous or scheduled transmission of ECG data to centralized monitoring centers enables early intervention. United States Medicare reimbursement for remote physiologic monitoring catalyzes health system procurement.
- Stress Testing:Exercise-integrated ECG capture evaluates ischemic changes during controlled cardiac workload. German sports medicine clinics deploy mobile alternatives to traditional treadmill systems.
- Sleep Apnea Screening:Nocturnal ECG-derived respiratory effort analysis supplements polysomnography for obstructive sleep apnea detection. Research institutes in Paris academic hospitals validate ECG-oximetry fusion algorithms.
Arrhythmia detection anchors the volume base while remote patient monitoring gains share at the steepest rate.
End User:
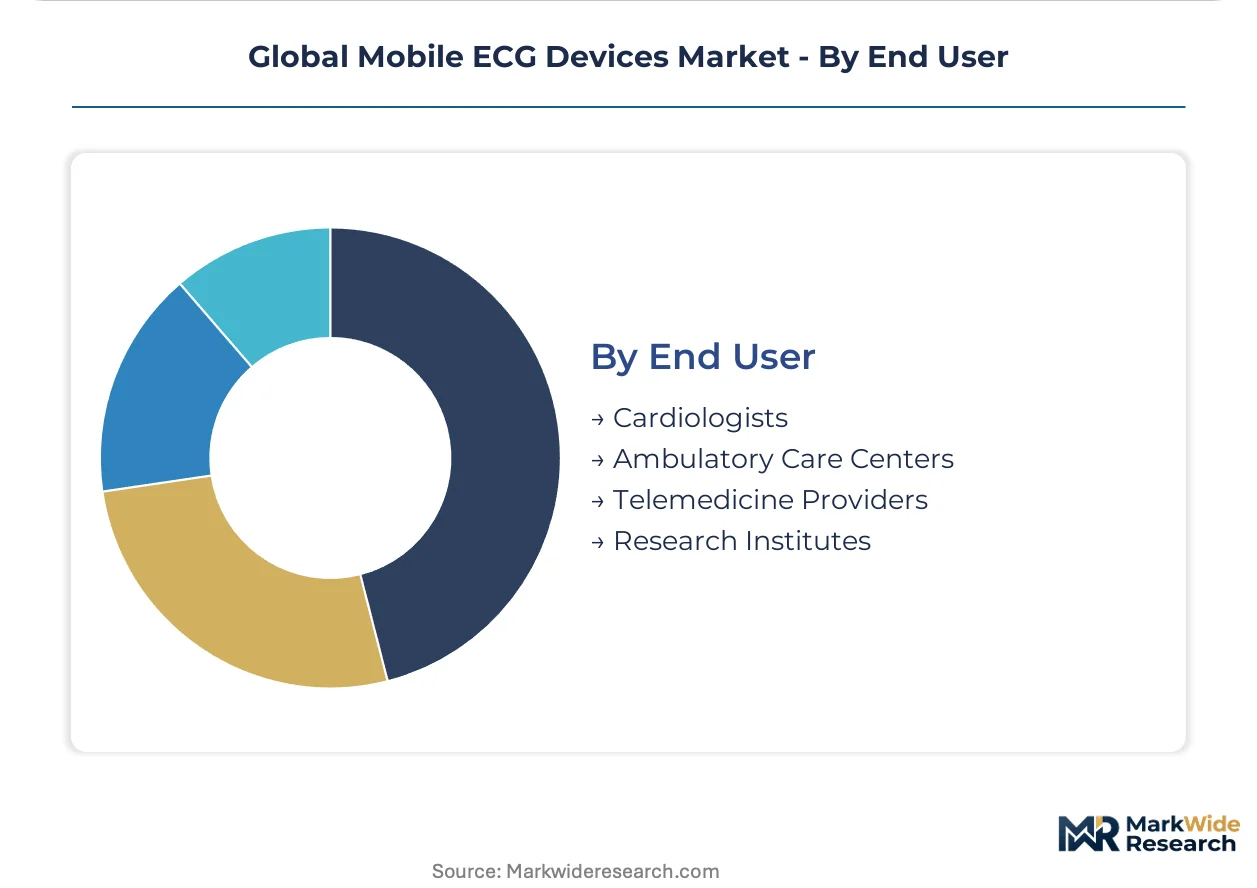
End-user segmentation determines pricing architecture and channel strategy, with institutional procurement favoring multi-year service contracts while individual clinician purchases prioritize device portability and EMR interoperability.
- Cardiologists:Electrophysiology specialists demand 12-lead equivalent diagnostic fidelity with HL7 FHIR integration into Epic and Cerner environments. United States hospital networks in Boston and Cleveland corridors concentrate purchasing authority.
- Ambulatory Care Centers:Outpatient facilities prioritize throughput-optimized workflows with technician-operated devices. India's Tamil Nadu medical electronics clusters supply cost-optimized hardware to these settings.
- Telemedicine Providers:Virtual-first platforms require patient-self-administered devices with automated quality checks and cloud-based overread. German statutory health insurance reimbursement for video consultation-linked diagnostics accelerates adoption.
- Research Institutes:Academic medical centers and contract research organizations specify continuous ECG patches for cardiotoxicity monitoring in oncology drug trials. Paris and Berlin academic hospitals maintain prospective registries for EU MDR compliance.
Telemedicine providers anchor the volume base while research institutes gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: United States health systems prioritize remote patient monitoring reimbursement, while Japanese policy mandates population-scale screening, and Indian procurement channels mobile ECG into subsidized rural primary care kits. These structural differences shape hardware specifications, connectivity requirements, and algorithm validation burdens across national markets.
United States
Medicare reimbursement codes for remote physiologic monitoring catalyze health system procurement of cellular-enabled devices. FDA 510(k) pathway acceleration under 21 CFR 870.2340 compresses algorithm update timelines for domestic vendors. Boston and Cleveland corridors concentrate electrophysiologist overread capacity for cloud-based ECG services.
Germany
Statutory health insurance reimbursement for video consultation-linked diagnostics accelerates telemedicine platform adoption. EU MDR software-as-medical-device pathways scrutinize Bluetooth 5.3 security implementations through Munich and Stuttgart notified bodies. Ambulatory clinics in North Rhine-Westphalia deploy handheld units for pre-consultation screening workflows.
Japan
METI-subsidized workplace wellness programs drive wearable ECG volume through corporate procurement channels. Ministry of Health screening mandates target 80% atrial fibrillation coverage for citizens over 65 by 2030. Tokyo and Osaka metropolitan areas concentrate demand for arrhythmia detection algorithms.
India
Production-linked incentives covering 5-20% of manufacturing cost attract contract manufacturers to Gujarat and Tamil Nadu clusters. Telemedicine platforms embed smartphone-connected peripherals into rural primary care kits. CDSCO medical device regulations govern hardware safety standards for domestic distribution.
France
Research institutes in Paris academic hospitals validate ECG-oximetry fusion algorithms for sleep apnea screening applications. ANSM oversight of software-as-medical-device claims requires prospective patient registries spanning 1,000+ subjects. Cardiotoxicity monitoring for oncology drug development creates demand from contract research organizations.
Global Mobile ECG Devices Market Competitive Landscape
Capability concentration sits with algorithm developers and AI platform specialists; scale advantage sits with diversified medical technology conglomerates and consumer electronics manufacturers. The market structures around three tiers: prescription-grade patch monitor specialists, hospital-integrated remote monitoring platforms, and consumer-direct smartphone peripheral vendors. Dominant competitive moves include FDA clearance acceleration for AI-enabled diagnostics and strategic partnerships with telemedicine platforms for white-label device integration.
Within the AI-native diagnostic tier, AliveCor and iRhythm Technologies exemplify contrasting archetypes—consumer-direct cardiac screening versus patch-based ambulatory monitoring through proprietary analytics. Medtronic occupies a position bridging hospital-integrated remote monitoring with legacy cardiac device installed bases. Among diversified conglomerates, GE Healthcare Inc. and Koninklijke Philips N.V. represent scale-driven competitors leveraging established imaging and monitoring portfolios.
| Leading Market Players |
|---|
| GE Healthcare Inc. |
| Baxter International Inc. |
| iRhythm Technologies Inc. |
| Nihon Kohden Corporation |
| Qardio, Inc. |
| AliveCor, Inc. |
| Medtronic |
| Omron Healthcare |
| Koninklijke Philips N.V. |
| Others |
Supply & Pricing Matrix
Tamil Nadu's medical electronics manufacturing clusters anchor global supply capacity for smartphone-connected ECG peripherals, with production-linked incentives from India's CDSCO framework compressing landed costs for telemedicine platforms. This geographic concentration grants contract manufacturers asymmetric pricing power over mid-tier vendors lacking backward integration into electrode fabrication.
Pricing Analysis
Long-term offtake contracts dominate procurement between United States health systems and patch-based monitor vendors, locking in three-year service bundles that blend hardware depreciation with cloud interpretation fees. Pricing stratifies across prescription-grade, wellness-tier, and economy-level certification grades, with FDA 510(k) clearance commanding substantial premia over CE-marked equivalents. Cost compression in consumer peripherals is intensifying because silver chloride electrode volatility squeezes sub-$100 device margins. Telemedicine platforms exhibit highest price sensitivity, while electrophysiology practices prioritize diagnostic fidelity over unit economics.
Supply Chain Analysis
Extended payment terms from German notified bodies to component suppliers have normalized 90-day cycles for Bluetooth 5.3 module procurement, straining working capital for mid-tier device manufacturers. Manufacturing concentrates in India, China, and Malaysia, with final assembly drawing from Taiwanese chipsets and Japanese precision electrodes. Single-source vulnerability sits with AWS and Microsoft Azure hosting 78% of HIPAA-compliant ECG data lakes. Distribution runs through hospital purchasing committees in Boston and Cleveland corridors, GPO contracts for United States health systems, and direct-to-platform sales for German telemedicine providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile ECG market is staging a cyclical recovery as deferred hospital capital expenditure resumes and AI-enabled diagnostic algorithms mature through FDA validation pathways. Remote patient monitoring reimbursement expansion provides the cyclical driver.
For Market Incumbents: Harden algorithm validation pipelines against adaptive AI regulatory burdens by pre-funding prospective clinical trials before FDA submission, and deepen backward integration into electrode manufacturing to offset silver chloride cost volatility. Medtronic's legacy device installed base faces substitution threat from AI-native platforms; defend through exclusive hospital system partnerships locking in EMR interoperability. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized contract manufacturing tier, supplying white-label smartphone peripherals to telemedicine platforms under CDSCO compliance frameworks. Research institutes in Paris and Berlin academic hospitals represent the most penetrable segment, with cardiotoxicity monitoring for oncology trials offering project-based revenue without reimbursement code dependency. Go-to-market through CRO partnerships bypasses hospital procurement complexity. For Investors and Strategic Acquirers: Long-term, this sits as a software-platform play because recurring cloud interpretation revenue is displacing hardware transactional economics, with algorithm accuracy becoming the scarce capability. Target acquisition archetypes are AI-native diagnostic developers with FDA-cleared classifiers and established electrophysiologist overread networks. Watch FDA guidance on continuous learning algorithms as the inflection signal—regulatory clarity would compress validation timelines and unlock venture deployment.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Streamlined premarket notification under 21 CFR 870.2340 compresses algorithm update timelines for domestic vendors. |
| CE-MDR Software-as-Medical-Device Compliance | EU MDR conformity unlocks German statutory health insurance reimbursement for video consultation-linked diagnostics. |
| Hospital System Partnership | Epic and Cerner HL7 FHIR integration locks in electrophysiology workflow adoption across Boston and Cleveland corridors. |
| Cloud Infrastructure Diversification | Multi-provider hosting mitigates AWS concentration risk for mid-tier vendors serving HIPAA-compliant data lakes. |
| Reimbursement Strategy | Medicare remote physiologic monitoring codes catalyze United States health system procurement of cellular-enabled devices. |
Research Methodology
Initial hypotheses were tested against primary input from electrophysiologists, hospital purchasing committee members, biomedical engineers, and telemedicine platform executives, and refined through secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, GPO contract repositories, and EU MDR notified body guidance documents. Bottom-up shipment estimates by device category were triangulated against top-down health system expenditure surveys.
Demand-supply balance modeling anchored volume projections across the analysis window, with segmentation by product type, technology architecture, clinical application, and end-user archetype informing price-band allocation. CAGRs were derived from fitted growth curves calibrated to reimbursement code expansion timelines and AI regulatory pathway maturation. Forecast inputs included electrophysiologist workforce concentration patterns and cloud infrastructure capex disclosures from AWS and Microsoft.
Stress conditions across FDA adaptive algorithm validation delays, silver chloride electrode price volatility, and EU AI Act conformity burdens were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about reimbursement expansion and regulatory harmonization. Macroeconomic contraction, algorithmic safety signal emergence, or cybersecurity incident severity would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Injectable Bulking Agents Market
Medical Devices
Nerve Locator Stimulator Market
Medical Devices
High Pressure Contrast Media Injectors Market
Medical Devices
Global Surgical Polypropylene Mesh Market
Medical Devices
South Korea Artificial Organs and Bionics Market
Medical Devices
Smart Pills Technology Market
Medical Devices
Global Peripheral Vascular Devices and Accessories Market
Medical Devices
North America Non-Surgical Procedures Market
Medical Devices
Intracranial Pressure Monitors Market
Medical Devices
Europe Cardiac Rhythm Management Devices Market
Medical Devices
Latin America Insulin Syringes Market
Medical Devices
Occlusion Microcatheter Market
Medical Devices
Automatic Clotting Timer Systems Market
Medical Devices
LAMEA Breast Pumps Market
Medical Devices
Robotic Hair Transplant System Market
Medical Devices
Artificial Spine Discs Market