
 Botanicals & Acupuncture Market | 2026-2036
Botanicals & Acupuncture Market Size, Share, and Industry Trends Forecast 2026-2036
Botanicals & Acupuncture Market Insights
Aftermarket service revenue from acupuncture continuing education and practitioner certification programs is tilting toward larger platform operators. Gaia Herbs leverages organic cultivation standards to sustain premium positioning in liquid extracts. Banyan Botanicals anchors its supply chain through Ayurvedic sourcing partnerships in India. Modern Acupuncture competes by standardizing clinic formats for scalable replication.
Botanicals and acupuncture encompass plant-derived therapeutic preparations and needle-based stimulation techniques used to modulate physiological function. Herbal supplements typically contain standardized extracts with defined marker compound concentrations, while acupuncture needles range from 0.12 mm to 0.35 mm diameter depending on body site and technique. Pain relief applications dominate clinical utilization, though stress management protocols are expanding fastest in wellness center settings. Capsule formulations command higher margins than dried herbs due to convenience and dosing precision.
EFSA evaluates health claims for botanical ingredients in Europe, while China's NMPA governs traditional medicine manufacturing under pharmacopeial standards. FDA oversight of dietary supplements in the United States operates under DSHEA enforcement discretion, creating variable market access requirements. Stakeholders must monitor evolving pharmacovigilance obligations and adapt quality systems before compliance deadlines tighten.
Market Dynamics
The Botanicals & Acupuncture Market is being reshaped by EFSA's tightening pharmacovigilance requirements for botanical health claims, which forces manufacturers to invest in clinical substantiation before market entry rather than retrofitting compliance post-launch.
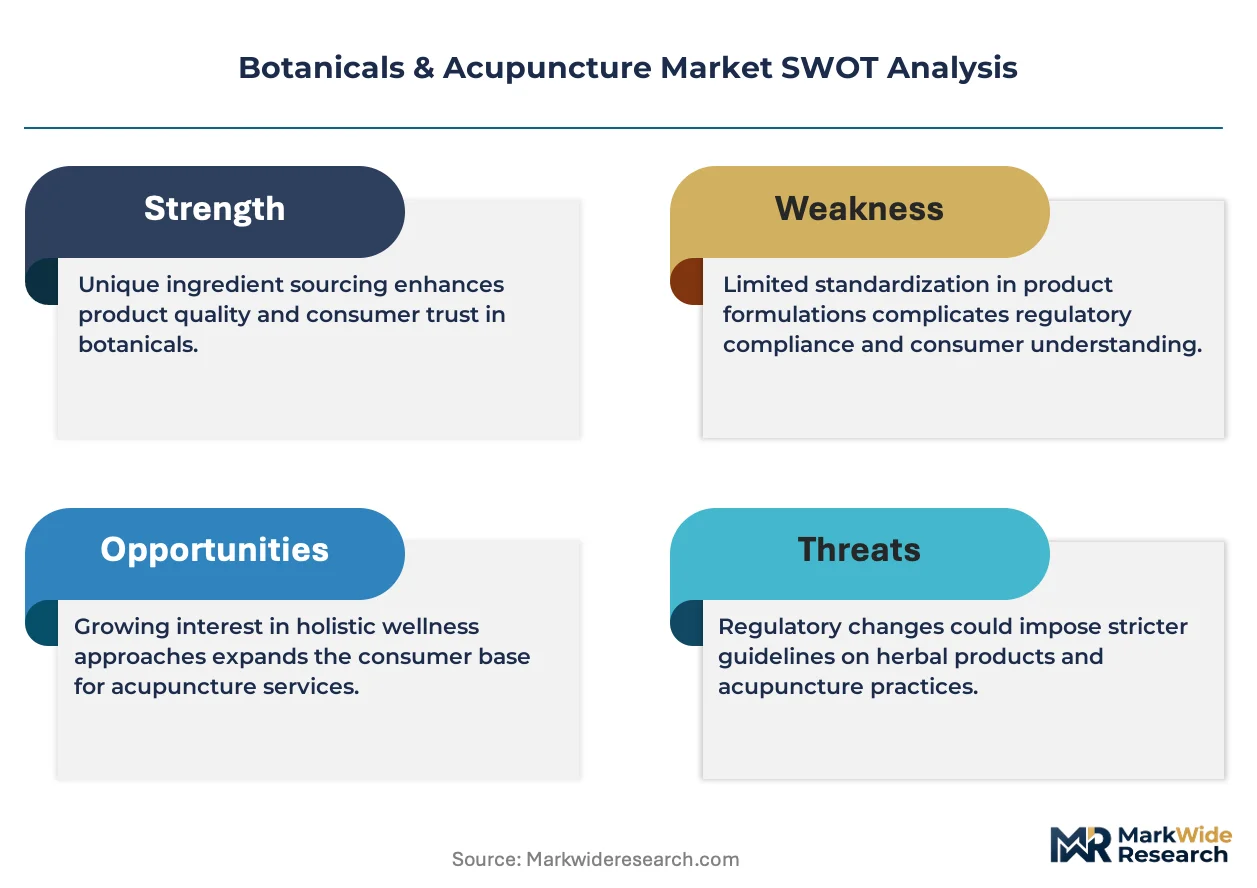
Growth Catalysts
- EFSA Guidance on Botanical Safety:Wellness centers across Germany are expanding herbal therapy programs under this framework, creating standardized demand for certified botanical preparations.
- Pain Management Protocols:Hospital systems in the United States are integrating acupuncture into perioperative care pathways, driving institutional procurement of sterile needle supplies.
- Ayurvedic Sourcing Corridors:India's traditional medicine manufacturing clusters are scaling extraction capacity to serve international capsule formulation demand.
Market Restraints
- Wild-Harvested Ingredient Volatility:Climate-sensitive botanicals like Rhodiola rosea face supply interruptions from Altai mountain regions, compressing raw material availability.
- FDA Enforcement Discretion:DSHEA's variable interpretation creates inconsistent market access timelines for novel botanical ingredients entering US distribution.
- Synthetic Analgesic Substitution:Pharmaceutical pain management innovations threaten acupuncture's clinical reimbursement positioning in institutional settings.
Strategic Opportunities
- Stress Management Wellness Centers:China's tier-two cities outside Beijing-Shanghai-Guangzhou show underpenetrated demand for traditional medicine protocols.
- Dual Carbon Goals:China's MEE incentives favor organic cultivation methods, creating regulatory tailwinds for certified sustainable botanical operations.
- Telehealth Integration:Remote practitioner consultation platforms are emerging as distribution channels for personalized herbal protocol recommendations.
Industry Challenges
- Practitioner Certification Bottlenecks:Multi-year training requirements for licensed acupuncturists constrain clinic expansion velocity in regulated markets.
- Pharmacopeial Harmonization Delays:Divergent marker compound standards between China's NMPA and USP create reformulation costs for multi-territory products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Botanicals & Acupuncture Market |
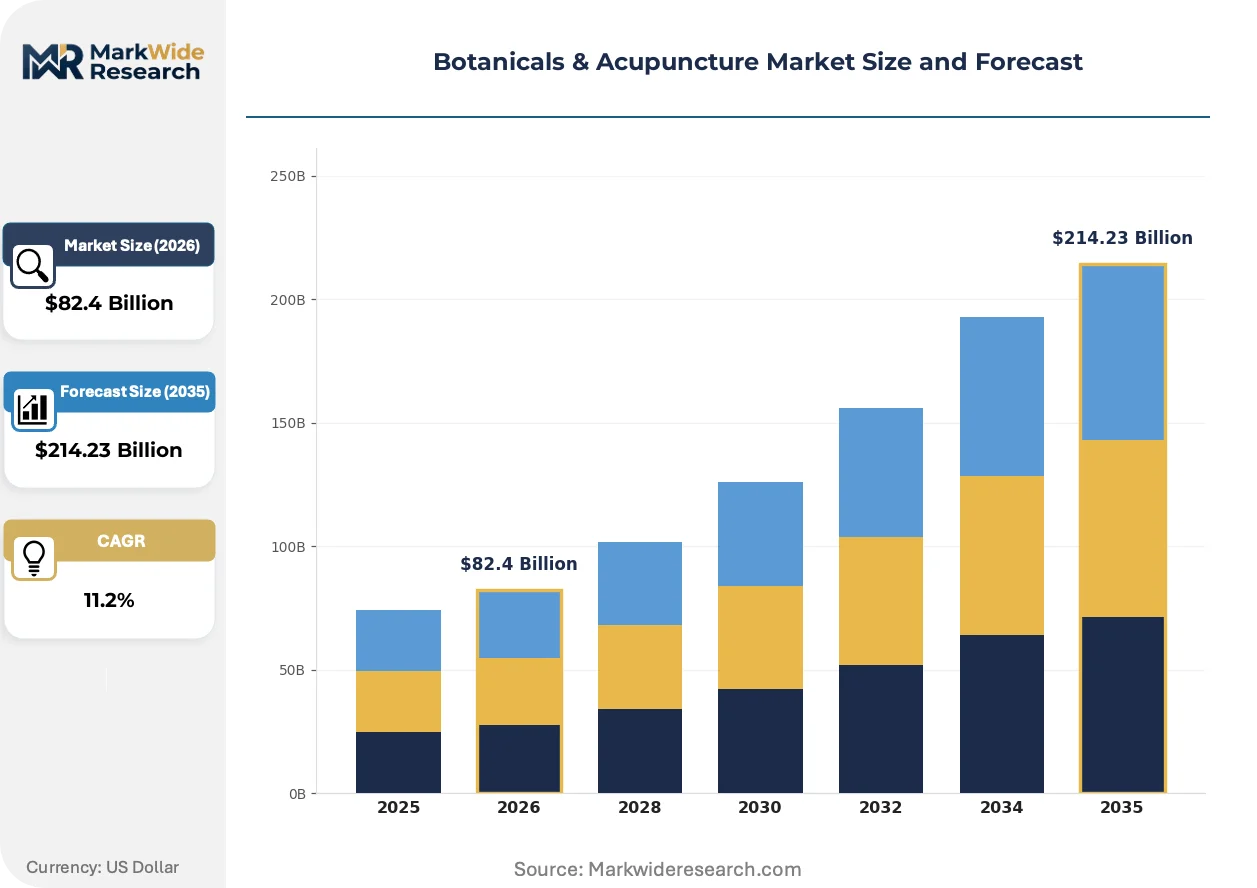
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $214.23 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Supplements, Essential Oils, Acupuncture Needles, Homeopathic Remedies End User: Clinics, Wellness Centers, Home Users, Practitioners Application: Pain Relief, Stress Management, Digestive Disorders, Sleep Improvement Form: Liquid Extracts, Dried Herbs, Capsules, Powders |
| Companies Covered | Modern Acupuncture, ARC Acupuncture & Physical Therapy, Ayush Ayurveda, Herb Pharm, Pure Encapsulations, NatureKue, Inc., Gaia Herbs, Banyan Botanicals, Sheng Chang Pharmaceutical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Botanicals & Acupuncture Market Trends and Innovations
Digital diagnostic platforms are penetrating traditional medicine practice management, compressing consultation documentation time while generating structured outcome data that satisfies emerging payer requirements for reimbursement justification.
Needle electro-acupuncture devices with embedded biofeedback sensors are digitizing treatment parameter recording. Pain management clinics in South Korea are deploying these systems at scale. The technology is digitizing outcome measurement standards that previously relied on subjective patient reporting.
EFSA's 2024 updated guidance on botanical health claim substantiation is mandating randomized trial evidence for immune-support positioning. European herbal supplement manufacturers are restructuring R&D budgets toward clinical validation. Capsule and liquid extract categories face the steepest compliance cost escalation.
Corporate wellness procurement is consolidating vendor relationships under single-platform contracts. Large employers in Germany are replacing fragmented local practitioner networks with standardized national service agreements. This concentration is most visible in Munich and Hamburg metropolitan area headquarters operations.
Botanicals & Acupuncture Market Segmentation
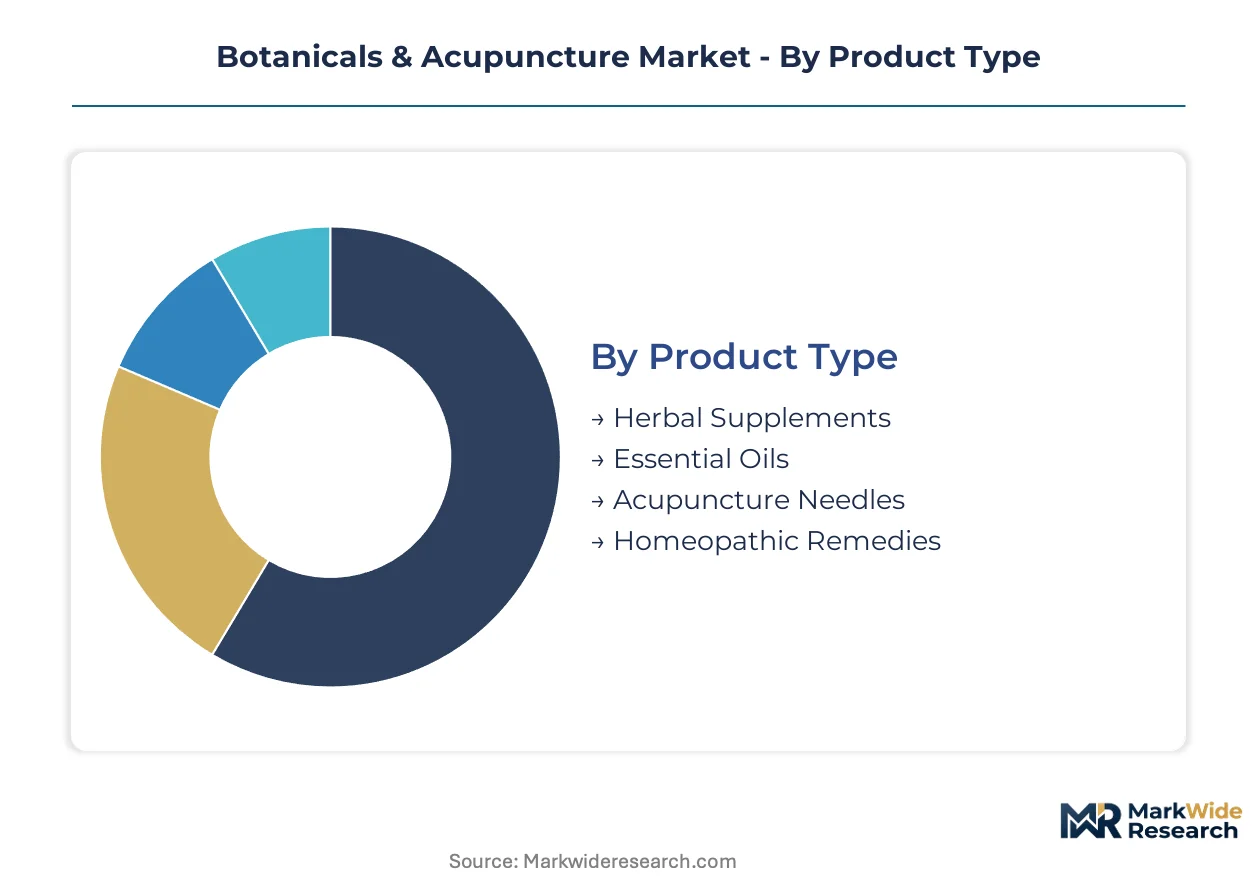
Segmentation in botanicals and acupuncture reveals how therapeutic intent, delivery format, and care setting intersect to shape procurement patterns. Each dimension carries distinct margin profiles and regulatory exposure that determine competitive positioning.
Product Type:
Herbal supplements and acupuncture needles anchor opposite ends of the therapeutic spectrum, spanning consumable botanicals to single-use clinical instruments.
- Herbal Supplements:Standardized extracts with defined marker compound concentrations dominate institutional procurement. EFSA's tightened pharmacovigilance requirements in Europe are forcing manufacturers to front-load clinical substantiation costs before market entry.
- Essential Oils:Volatile aromatic compounds extracted through steam distillation or cold pressing serve aromatherapy protocols in wellness center settings. Germany's expanding herbal therapy programs under EFSA guidance are standardizing quality specifications for therapeutic-grade oils.
- Acupuncture Needles:Sterile stainless steel instruments ranging from 0.12 mm to 0.35 mm diameter. US hospital systems integrating acupuncture into perioperative care are driving bulk procurement of sterile needle supplies.
- Homeopathic Remedies:Highly diluted preparations following Hahnemann principles. Regulatory scrutiny from FDA under DSHEA enforcement discretion creates variable market access timelines.
The dominant share belongs to Herbal Supplements, while Acupuncture Needles is closing the gap fastest as institutional reimbursement pathways mature.
End User:
Customer type determines pricing power and protocol standardization requirements across the value chain.
- Clinics:Licensed practitioner facilities delivering diagnosis and treatment. Multi-year certification requirements for acupuncturists constrain expansion velocity in regulated markets like the United States and Germany.
- Wellness Centers:Prevention-focused establishments integrating traditional medicine protocols. China's tier-two cities outside Beijing-Shanghai-Guangzhou show underpenetrated demand for these services.
- Home Users:Self-directed consumers purchasing over-the-counter preparations. Capsule formulations command preference over dried herbs due to convenience and dosing precision.
- Practitioners:Individual licensed professionals sourcing supplies for private practice. Corporate wellness procurement in Germany is consolidating fragmented local networks under standardized national agreements.
Clinics capture the largest revenue pool, though Wellness Centers are expanding most quickly as employer-sponsored preventive care budgets grow.
Application:
Therapeutic indication shapes clinical evidence requirements and reimbursement eligibility.
- Pain Relief:The most established clinical application with institutional acceptance. Hospital systems in the United States are embedding acupuncture into perioperative pathways.
- Stress Management:Fastest-expanding protocol category in wellness center settings. Digital diagnostic platforms are compressing consultation documentation time while generating structured outcome data.
- Digestive Disorders:Traditional medicine applications with growing Western adoption. Ayurvedic sourcing corridors in India are scaling extraction capacity to serve international capsule formulation demand.
- Sleep Improvement:Emerging indication driven by consumer wellness trends. EFSA's updated guidance on botanical health claims is mandating randomized trial evidence for positioning in this category.
Pain Relief maintains volume leadership, yet Stress Management is gaining share fastest as workplace wellness programs expand.
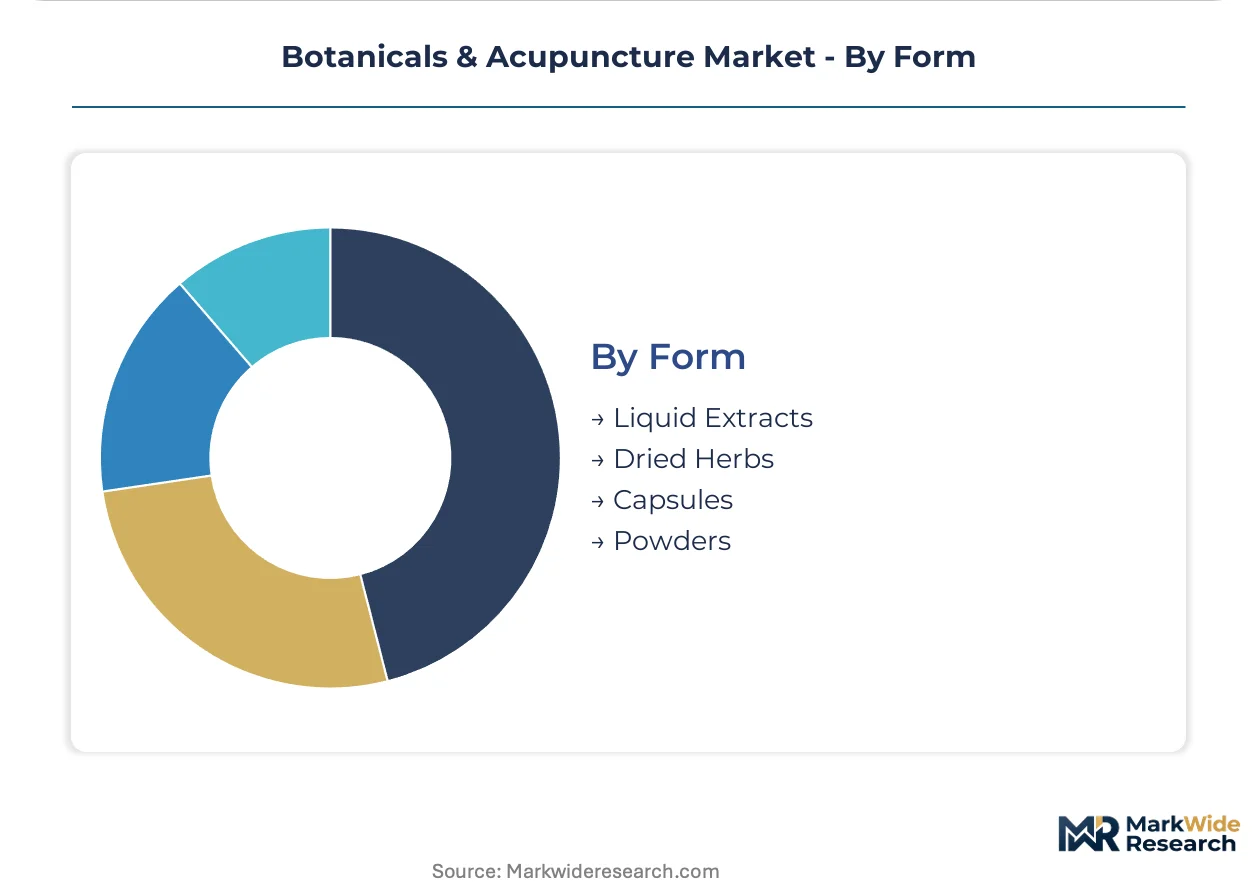
Form:
Delivery format directly influences margin structure and supply chain configuration.
- Liquid Extracts:Concentrated botanical preparations in alcohol or glycerin bases. Gaia Herbs leverages organic cultivation standards to sustain premium positioning in this category.
- Dried Herbs:Raw botanical material requiring preparation before use. Wild-harvested ingredient volatility from climate-sensitive sources like Altai mountain Rhodiola rosea compresses availability.
- Capsules:Encapsulated powders or extracts enabling precise dosing. Higher margins than dried herbs reflect convenience premium and manufacturing complexity.
- Powders:Milled botanical material for flexible dosing and compounding. China's MEE incentives under dual carbon goals favor organic cultivation methods for certified sustainable operations.
Capsules hold the leading position by value, while Liquid Extracts are climbing fastest on premium wellness positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes botanicals through institutional wellness programs while China deploys acupuncture through hospital-integrated traditional medicine corridors. The United States splits demand between clinical reimbursement pathways and direct-to-consumer supplement channels. India's Ayurvedic manufacturing clusters supply international capsule formulation demand.
United States
Hospital systems embed acupuncture into perioperative care pathways, driving institutional procurement of sterile needle supplies. FDA oversight under DSHEA enforcement discretion creates variable market access timelines for novel botanical ingredients. Pain management clinics in metropolitan health systems anchor the clinical segment.
Germany
Wellness centers expand herbal therapy programs under EFSA guidance on botanical safety claims. The country's national pharmaceutical regulator evaluates health claims with tightening pharmacovigilance requirements. Munich and Hamburg metropolitan headquarters operations consolidate corporate wellness vendor relationships under standardized national agreements.
China
Traditional medicine corridors spanning Beijing, Shanghai, and Guangzhou concentrate demand for acupuncture services and herbal preparations. NMPA governs manufacturing under pharmacopeial standards while MEE incentives under dual carbon goals favor organic cultivation methods. Tier-two cities outside the primary corridor show underpenetrated demand for traditional medicine protocols.
India
Ayurvedic sourcing partnerships anchor supply chains for international capsule formulation demand. The country's national pharmaceutical regulator oversees traditional medicine manufacturing standards. Traditional medicine manufacturing clusters scale extraction capacity to serve export markets.
South Korea
Pain management clinics deploy needle electro-acupuncture devices with embedded biofeedback sensors at scale. MFDS regulates medical device and pharmaceutical product categories. Seoul metropolitan area health technology adoption centers digitize outcome measurement standards.
Botanicals & Acupuncture Market Competitive Landscape
Capability concentration sits with heritage botanical specialists; scale advantage sits with platform operators standardizing clinic formats. The market structures around three tiers: organic cultivation specialists, Ayurvedic sourcing integrators, and clinic format standardizers. Consolidation pressures favor operators with captive supply chains or certified practitioner networks. Dominant competitive moves include backward integration into cultivation assets and technology licensing for diagnostic platforms.
Within the heritage botanical tier, Gaia Herbs and Banyan Botanicals exemplify supply chain anchoring strategies. Gaia Herbs occupies a position tied to organic cultivation standards, while Banyan Botanicals represents Ayurvedic sourcing partnership models. Modern Acupuncture sits within the platform standardization archetype. These three illustrate how competitive positioning diverges between supply-side control and demand-side format replication.
| Leading Market Players |
|---|
| Modern Acupuncture |
| ARC Acupuncture & Physical Therapy |
| Ayush Ayurveda |
| Herb Pharm |
| Pure Encapsulations |
| NatureKue, Inc. |
| Gaia Herbs |
| Banyan Botanicals |
| Sheng Chang Pharmaceutical Company |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in India's Ayurvedic extraction clusters is forcing international buyers to accept extended lead times and prepayment terms, compressing working capital cycles while elevating premium-tier pricing power for certified organic suppliers.
Pricing Analysis
Long-term offtake contracts dominate procurement between large wellness chains and certified cultivation operations, while spot markets handle wild-harvested specialty botanicals. Three-tier pricing structure across premium, standard, and economy levels reflects organic certification status, pharmacopeial compliance grade, and volume commitment scale. Price differentiation stems from EFSA substantiation costs and Altai mountain supply interruptions. Pricing pressure intensifies in capsule formulations as clinical validation expenses escalate. Home users demonstrate highest price sensitivity; institutional hospital procurement shows lowest sensitivity due to reimbursement pathway security.
Supply Chain Analysis
Extended payment terms from German wellness center chains are squeezing mid-tier Indian extractors, accelerating supply-chain finance facility adoption among Ayurvedic processors. Geographic concentration centers on India for extraction, China for cultivated raw material, and Germany for finished formulation. Raw material dependencies include Rhodiola rosea root, ashwagandha biomass, and stainless steel needle stock. Single-source vulnerability from Altai wild-harvesting regions threatens continuity. Distribution runs through practitioner networks, direct-to-consumer platforms, and hospital procurement systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Licensed practitioner scarcity constrains clinic expansion velocity, creating acquisition premiums for certified networks and forcing platform operators to internalize training capacity.
For Market Incumbents: Insulate market position by securing captive cultivation contracts in India's organic-certified corridors before MEE dual carbon incentives attract competing buyers. Acquire distressed extraction assets in Uttar Pradesh and Kerala to consolidate Ayurvedic supply control. EFSA pharmacovigilance tightening threatens non-compliant product lines; front-load clinical substantiation budgets for immune-support positioning. For New Entrants and Emerging Players: Tier-two Chinese cities outside the Beijing-Shanghai-Guangzhou corridor represent the most penetrable entry point for standardized wellness center formats. Telehealth-integrated herbal consultation platforms targeting employer-sponsored stress management programs offer lower capital intensity than physical clinic buildout. Partner with existing TCM hospitals for practitioner credential transfer rather than building training infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across clinical validation-dependent capsule formulations as EFSA mandates randomized trial evidence. Target acquisition archetypes include distressed European herbal supplement manufacturers with existing pharmacopeial dossiers and underutilized extraction capacity. Monitor FDA DSHEA enforcement discretion patterns as signal for US market access timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation Assets | Captures organic certification premiums and insulates against Altai supply volatility. |
| Clinical Trial Advancement for EFSA Claims | Enables immune-support positioning in European markets ahead of compliance deadlines. |
| Practitioner Network Acquisition | Accelerates clinic expansion velocity where multi-year licensing constraints bottleneck growth. |
| Telehealth Platform Integration | Compresses consultation documentation time while generating structured reimbursement data. |
| Long-term Supply Agreement with Hospital Systems | Secures sterile needle procurement volumes as US perioperative acupuncture adoption expands. |
Research Methodology
The analysis maps herbal supplements, acupuncture instruments, essential oils, and homeopathic preparations, each validated through licensed acupuncturists, wellness center procurement directors, Ayurvedic extraction facility managers, and hospital purchasing committee members. Primary interview data triangulates against NMPA pharmacopeial filings, EFSA health claim registers, USP monograph databases, and customs trade records for botanical raw material flows. Bottom-up practitioner network sizing reconciles with top-down wellness center revenue aggregation.
Assumptions held fixed include EFSA enforcement trajectory, NMPA manufacturing standard continuity, and DSHEA interpretation stability, while variables included dual carbon goal implementation pace and telehealth reimbursement policy evolution. Segmentation dimensions encompassed product type, end-user category, therapeutic application, and delivery form. CAGRs derive from volume-demand elasticity modeling against practitioner supply constraints. Forecast inputs incorporated climate-sensitive botanical yield projections and institutional acupuncture adoption curves.
Practitioners should monitor EFSA substantiation deadline adjustments, Altai region harvest yield reports, and FDA warning letter patterns for early signals of forecast revision necessity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Medicine
US Chiropractic Market
Alternative Medicine
Homeopathic Medicine Market
Alternative Medicine
Global OTC Herbal and Traditional Medicine Market
Alternative Medicine
Global Complementary and Alternative Medicines Market
Alternative Medicine
Complementary and Alternative Medicine for Anti Aging and Longevity Market
Alternative Medicine
Disposable Acupuncture Needle Market
Alternative Medicine
Natural Cold, Cough, and Sore Throat Remedies Market
Alternative Medicine
Ozone Therapy Units Market
Alternative Medicine
Global Acupuncture Market
Alternative Medicine
US Aromatherapy Market
Alternative Medicine
Acupuncture Lasers Market
Alternative Medicine
Aromatherapy Market
Alternative Medicine
Orthomolecular Medicine Market
Alternative Medicine
Bio Magnetic Ear Stickers Market
Alternative Medicine
Biopuncture Treatment Market
Alternative Medicine
Global Homeopathic Product Market